
 Magnetite Nanoparticles Market | 2026-2036
Magnetite Nanoparticles Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetite Nanoparticles Market Intelligence
Surface functionalization chemistry is tilting toward silane and polymer grafting protocols that enable targeted drug delivery and magnetic separation workflows. Fortis Life Sciences leverages its bioconjugation expertise to anchor premium positioning in diagnostic applications. Nanografi Nano Technology sustains competitive intensity through specialized synthesis routes for narrow particle-size distributions. Strem Chemicals Inc. dominates catalog distribution channels for research-grade materials across North American academic markets.
Magnetite nanoparticles consist of iron oxide (Fe3O4) crystallites typically ranging from 1 to 100 nanometers in diameter, synthesized through coprecipitation, thermal decomposition, or hydrothermal methods to achieve superparamagnetic behavior at room temperature. These particles serve primarily as contrast agents in magnetic resonance imaging, magnetic carriers in hyperthermia cancer therapy, and separable catalyst supports in industrial processes. The biomedical application segment leads current value generation, driven by diagnostic imaging and cell-sorting protocols, while energy storage represents the fastest-expanding structural pocket as battery developers test magnetite anode formulations. Coatings and surface-modified variants command the deepest margin pools due to technical complexity and regulatory qualification barriers.
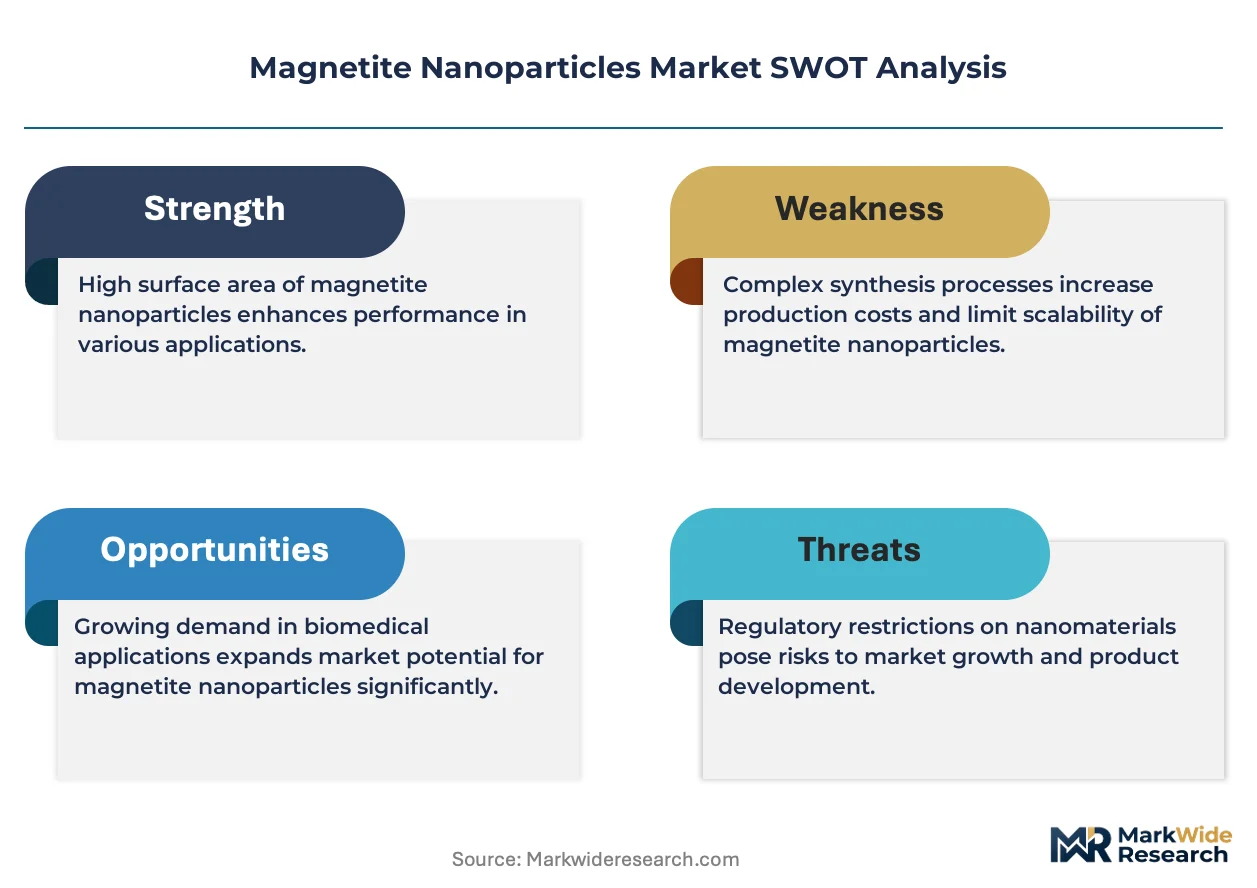
EMA's nanomaterial-specific guidance under the Medical Device Regulation and FDA's evolving nanotechnology regulatory framework jointly elevate documentation burdens for clinical-grade suppliers. REACH registration requirements for iron oxide nanoparticles in the European Union further constrain market access for uncertified producers. Stakeholders must monitor how EPA's TSCA Section 8(a) reporting rules for nanoscale materials reshape supply chain transparency obligations in the United States. The decisive variable ahead lies in which manufacturers secure pharmacopeial-grade certification before reimbursement pathways for nano-enabled therapeutics crystallize.
Market Dynamics
Surface functionalization protocols are compressing product qualification timelines while EMA's Medical Device Regulation and FDA's nanotechnology framework jointly escalate documentation burdens for clinical-grade suppliers.
Growth Catalysts
- Biomedical diagnostics expansion:MRI contrast agent demand from oncology screening programs drives volume absorption in hospital networks across Germany and the United States.
- REACH compliance pathways:ECHA registration requirements for iron oxide nanoparticles filter out uncertified competitors, concentrating market access among qualified producers.
- Hyperthermia therapy protocols:Magnetic fluid hyperthermia for solid tumors is gaining clinical traction in European university hospitals, anchoring therapeutic application growth.
Market Restraints
- Iron precursor cost volatility:Ferrous chloride and ferric nitrate feedstock prices fluctuate with steel industry cycles, squeezing coprecipitation route margins.
- Technical agglomeration limits:Magnetic dipole interactions cause irreversible particle clustering above critical concentrations, constraining formulation stability in high-loading drug delivery systems.
- Substitution by ferrite alternatives:Cobalt-doped and manganese ferrite nanoparticles offer superior magnetic susceptibility for specific frequency ranges in magnetic separation equipment.
Strategic Opportunities
- Battery anode formulations:Magnetite's theoretical capacity of 925 mAh/g positions it as a silicon-complementary active material for next-generation lithium-ion architectures.
- India's PLI scheme for specialty chemicals:Production-linked incentives for advanced materials manufacturing attract greenfield synthesis capacity to Gujarat and Maharashtra chemical corridors.
- ISO/TS 19337 harmonization:Emerging international standards for nanoparticle characterization enable cross-border qualification equivalency, reducing redundant testing costs.
Industry Challenges
- Pharmacopeial certification timelines:USP-NF and Ph.Eur. monograph compliance for injectable-grade magnetite requires 18-24 month stability studies, delaying commercial launch.
- Bioconjugation skill scarcity:Silane chemistry expertise and antibody-anchoring protocols remain concentrated among contract research organizations, limiting in-house formulation capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetite Nanoparticles Market |
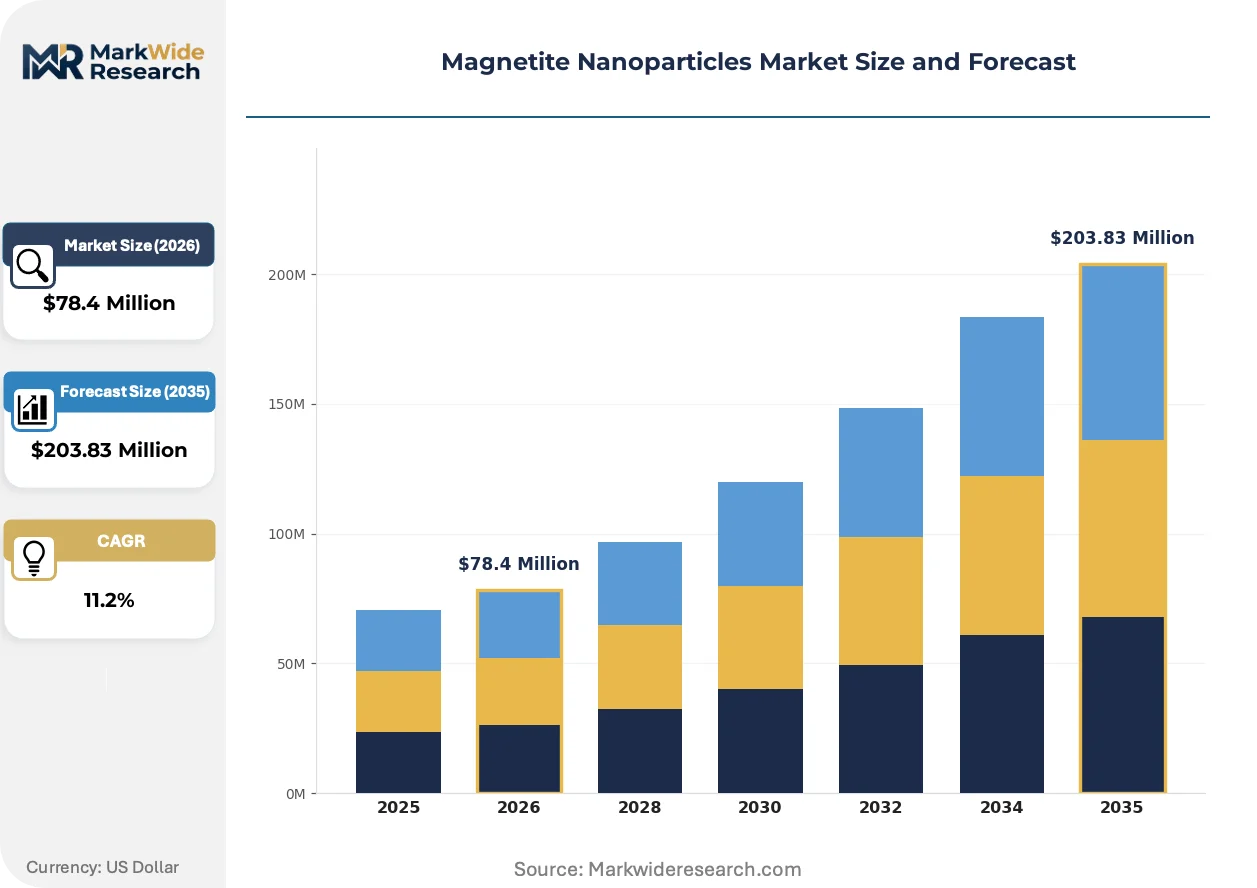
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $203.83 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanocrystals, Microparticles, Coatings, Composites Application: Biomedical, Electronics, Environmental, Energy Storage End User: Pharmaceuticals, Electronics Manufacturers, Research Institutions, Environmental Agencies Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Fortis Life Sciences, SkySpring Nanomaterials Inc., American Elements, Nanografi Nano Technology, US Research Nanomaterials Inc., Cytodiagnostics Inc., Nanoshel LLC, Strem Chemicals Inc., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetite Nanoparticles Market Strategic Shifts & Innovations
Digital process control and automated synthesis platforms are compressing batch-to-batch variability while regulatory data integrity requirements reshape manufacturing documentation architectures.
Continuous flow microreactor synthesis is digitizing quality assurance protocols by embedding inline DLS and TEM monitoring, enabling real-time particle size distribution correction. Pharmaceutical contract manufacturers in Switzerland and Massachusetts are adopting these systems to meet FDA's process analytical technology guidance. The technology is digitizing batch release decisions, collapsing traditional 72-hour QC hold periods into automated disposition workflows.
EMA's 2024 nanomaterial-specific guidance under the Medical Device Regulation mandates particle size distribution reporting across the full production batch, not just representative samples. This elevates analytical equipment requirements for notified body submissions. Diagnostic reagent suppliers in Germany and the Netherlands are restructuring quality management systems to accommodate batch-level nanoparticle tracking databases.
Academic procurement is consolidating around preferred supplier agreements with integrated characterization services, displacing catalog-based spot purchasing. Research institutions in California and Bavaria now demand certificates of analysis with electron microscopy micrographs for every lot. This behavioral shift concentrates volume among vendors with captive analytical laboratories, fragmenting the long-tail of undifferentiated material suppliers.
Magnetite Nanoparticles Market Segmentation
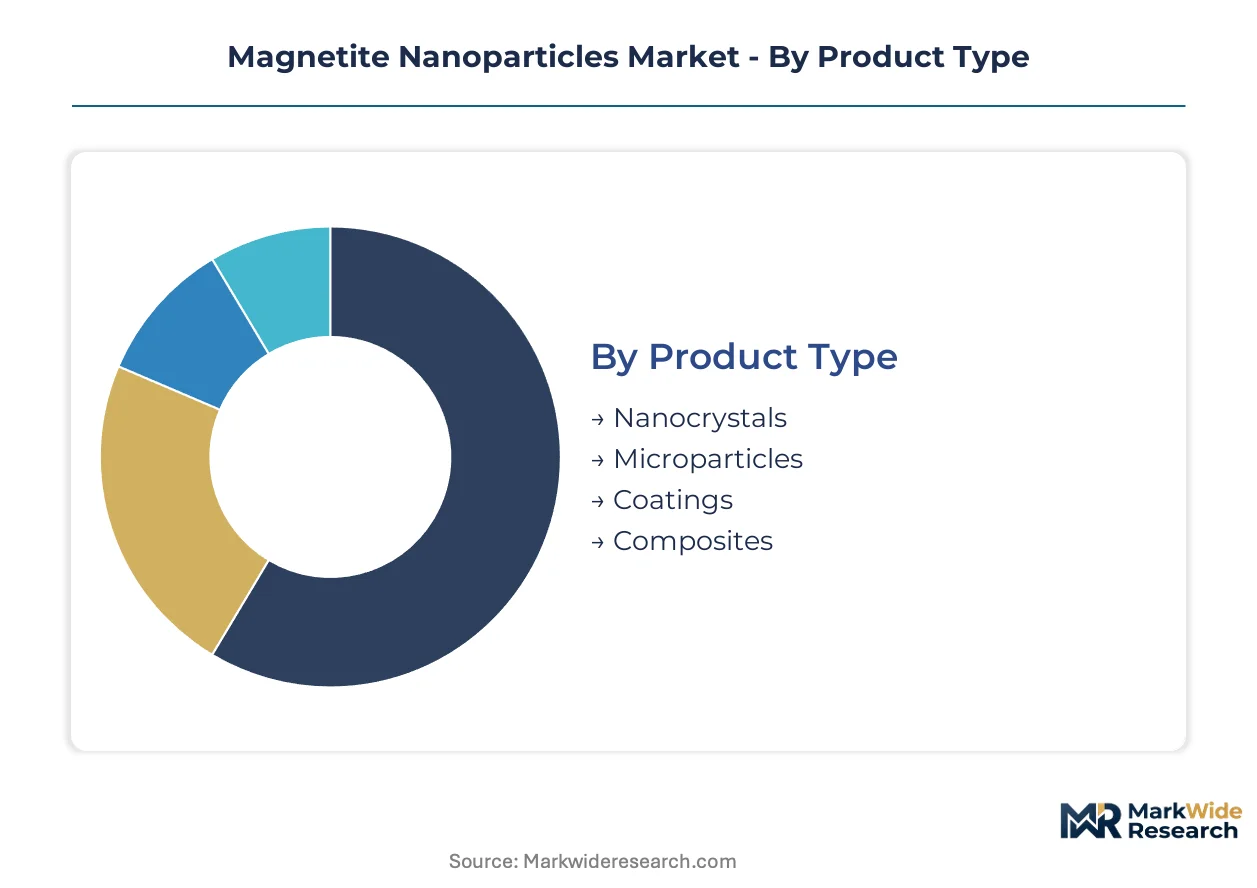
Segmentation in magnetite nanoparticles reveals how surface chemistry sophistication and regulatory qualification tiers partition value capture across supplier tiers. Product type and application dimensions expose the steepest margin gradients between commodity iron oxide powders and pharmacopeial-grade functionalized materials.
Product Type:
The use-case spectrum spans from unmodified nanocrystals for industrial catalysis to polymer-encapsulated composites for intravenous therapeutics, with surface architecture determining price multiples across the hierarchy.
- Coatings:Silane-grafted and dextran-coated variants enable bioconjugation for MRI contrast agents and magnetic separation protocols. Demand concentrates in Swiss and Massachusetts pharmaceutical contract manufacturing facilities where FDA process analytical technology compliance is mandatory.
- Nanocrystals:Unfunctionalized Fe3O4 crystallites ranging 10-50 nm serve catalysis and magnetic recording media applications. German precision chemical clusters around Düsseldorf absorb volume for industrial separations equipment.
- Microparticles:Aggregated nanocrystal clusters above 1 μm diameter serve magnetic separation and waste remediation workflows.
- Composites:Polymer-embedded or silica-shell architectures for drug delivery and hyperthermia therapy platforms.
The dominant share belongs to Coatings, while Composites are closing the gap fastest.
Application:
Cost tiers separate diagnostic-grade formulations commanding pharmacopeial certification premiums from industrial-grade materials sold on iron content specifications alone.
- Biomedical:MRI contrast enhancement, magnetic fluid hyperthermia, and cell-sorting protocols drive pharmacopeial-grade demand. European university hospitals in Germany and the Netherlands anchor therapeutic adoption under EMA Medical Device Regulation pathways.
- Energy Storage:Magnetite anode formulations for lithium-ion batteries exploit theoretical capacity advantages. Battery developers in California and South Korea test silicon-composite architectures.
- Electronics:Magnetic recording media and spintronic device fabrication.
- Environmental:Heavy metal remediation and wastewater treatment deployments.
Biomedical captures the deepest margin pool, with Energy Storage expanding most quickly.
End User:
Customer type determines procurement rigor, from research spot-buying with minimal documentation to pharmaceutical master service agreements requiring 18-24 month stability studies.
- Pharmaceuticals:Injectable-grade magnetite for oncology therapeutics and diagnostic reagents demands USP-NF and Ph.Eur. monograph compliance. CDSCO registration requirements in India filter supplier access for multinational drug developers.
- Research Institutions:Academic procurement consolidates around preferred supplier agreements with integrated electron microscopy characterization services.
- Electronics Manufacturers:Magnetic tape and sensor producers purchasing on magnetic susceptibility specifications.
- Environmental Agencies:Remediation contractors deploying unmodified particles for groundwater treatment.
Pharmaceuticals dominate procurement value, while Research Institutions are gaining share fastest through analytical-service bundling.
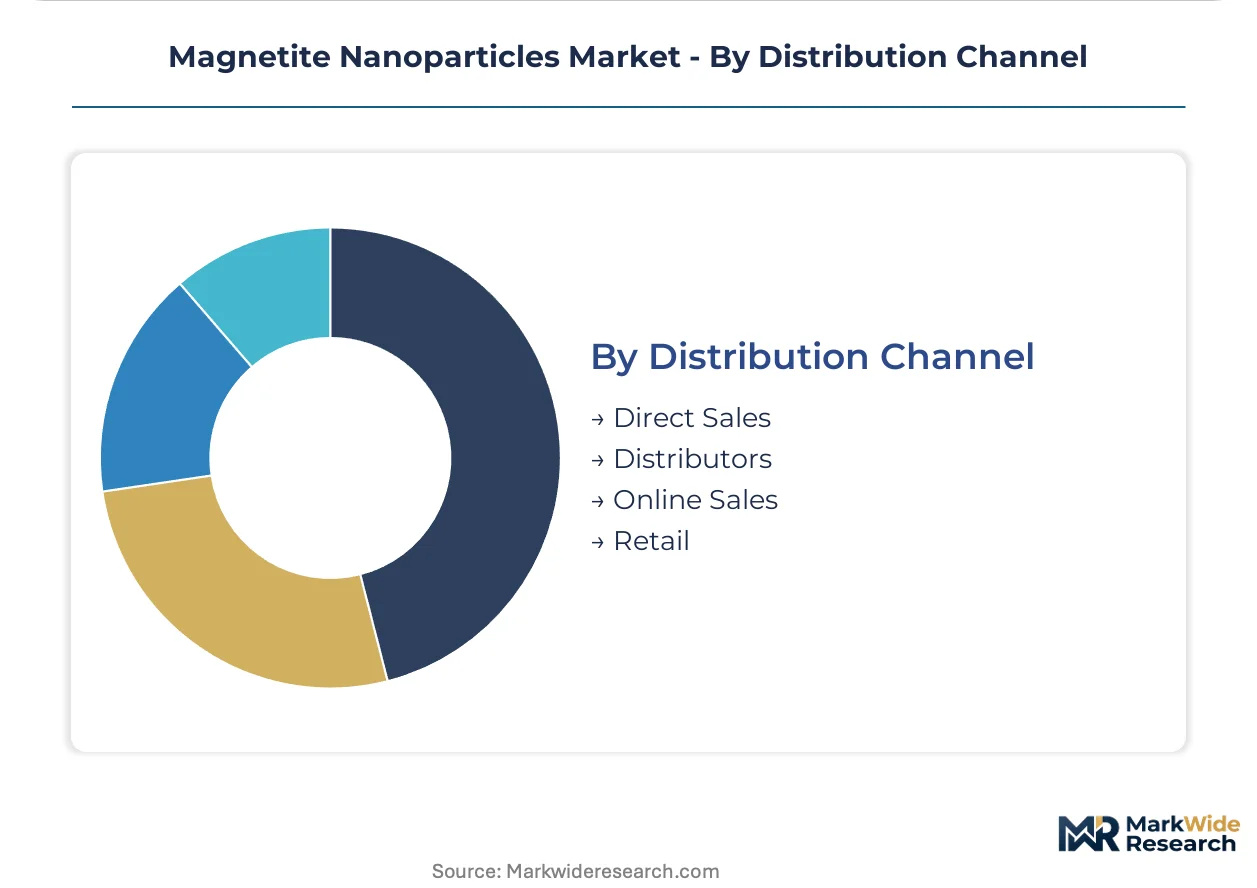
Distribution Channel:
Supply concentration favors direct relationships for clinical-grade volumes, with distributor networks handling industrial spot demand.
- Direct Sales:Pharmaceutical and battery developers negotiate multi-year supply agreements with dedicated quality management systems. Swissmedic-registered manufacturers in Basel maintain direct technical service teams for European diagnostic reagent producers.
- Distributors:Catalog distributors like Strem Chemicals dominate North American academic spot purchasing with 72-hour fulfillment.
- Online Sales:Research-grade material portals serving small-volume academic procurement.
- Retail:Minimal presence; limited to educational demonstration kits.
Direct Sales holds the dominant position, though Distributors are closing the gap fastest through analytical-service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision chemical exporters supply diagnostic-grade magnetite to Swiss pharmaceutical contract manufacturers and Massachusetts-based biotech developers, anchoring transatlantic trade flows in clinical-grade nanomaterials.
United States
FDA's nanotechnology regulatory framework and process analytical technology guidance drive qualification protocols for MRI contrast agents. Massachusetts pharmaceutical contract manufacturers adopt continuous flow microreactor systems to meet documentation requirements. Greater Boston anchors therapeutic application development for magnetic fluid hyperthermia protocols.
Germany
EMA's Medical Device Regulation mandates batch-level particle size distribution tracking for diagnostic reagents. REACH registration requirements for iron oxide nanoparticles filter supplier access to the European market. The Düsseldorf-Leverkusen precision chemical cluster concentrates synthesis capacity for hospital network supply.
Switzerland
Swissmedic registration requirements elevate quality management systems for injectable-grade magnetite used in oncology therapeutics. The country's pharmaceutical contract manufacturing sector absorbs volume from German chemical exporters. Basel maintains direct technical service teams for European diagnostic reagent producers.
India
CDSCO registration requirements for multinational drug developers filter supplier access for clinical-grade materials. The PLI scheme for specialty chemicals attracts greenfield synthesis capacity to Gujarat and Maharashtra chemical corridors. Mumbai-Pune pharmaceutical developers test magnetite anode formulations for battery applications.
South Korea
MFDS oversight of nanomaterial-containing medical devices shapes documentation pathways for diagnostic-grade suppliers. Battery developers in Seoul test silicon-composite magnetite architectures for next-generation lithium-ion systems. The Gyeonggi-Seoul corridor concentrates electronics manufacturing demand for magnetic recording media.
Magnetite Nanoparticles Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Catalog distributors dominate North American academic spot purchasing while direct-sales relationships capture pharmaceutical contract manufacturing volumes. Three archetypes define positioning: research-grade material suppliers with captive analytical laboratories, clinical-grade manufacturers with pharmacopeial certification, and battery-focused developers with anode formulation expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers secure pharmacopeial-grade certification ahead of reimbursement pathway crystallization.
Among research-grade material specialists, Strem Chemicals Inc. and SkySpring Nanomaterials Inc. occupy positions within the catalog distribution channel serving academic procurement consolidation. Fortis Life Sciences exemplifies the clinical-grade tier where bioconjugation expertise anchors premium positioning in diagnostic applications. These three companies represent distinct strategic vectors: scale-driven catalog fulfillment, specialized synthesis for narrow particle-size distributions, and integrated analytical-service bundling for preferred supplier agreements.
| Leading Market Players |
|---|
| Fortis Life Sciences |
| SkySpring Nanomaterials Inc. |
| American Elements |
| Nanografi Nano Technology |
| US Research Nanomaterials Inc. |
| Cytodiagnostics Inc. |
| Nanoshel LLC |
| Strem Chemicals Inc. |
| Merck KGaA |
| Others |
Cost & Logistics Intelligence
German precision chemical clusters around Düsseldorf and Leverkusen concentrate synthesis capacity for pharmacopeial-grade magnetite, anchoring margin pools downstream in Swiss pharmaceutical contract manufacturing and Massachusetts-based diagnostic reagent producers. Iron precursor cost volatility from steel industry cycles compresses coprecipitation route margins, while surface functionalization complexity sustains premium capture for silane-grafted and dextran-coated variants.
Pricing Analysis
Technology-generation pricing gaps separate unfunctionalized nanocrystals for industrial catalysis from polymer-encapsulated composites for intravenous therapeutics. Three-tier pricing structure across pharmacopeial-grade, research-grade, and industrial-grade levels reflects certification burden and analytical documentation depth. Price differentiation rests on USP-NF monograph compliance and batch-level electron microscopy characterization. Cost compression in research-grade tiers intensifies as academic procurement consolidates around preferred supplier agreements with integrated analytical services. Environmental agencies deploying unmodified particles for groundwater remediation exhibit highest price sensitivity; pharmaceutical contract manufacturers negotiating multi-year supply agreements for injectable-grade magnetite exhibit lowest.
Supply Chain Analysis
Tariff exposure between Germany and Switzerland dominates supply chain risk for clinical-grade magnetite moving from Düsseldorf-Leverkusen synthesis facilities to Basel pharmaceutical contract manufacturers. Geographic supply concentration centers on Germany, Switzerland, and the United States for pharmacopeial-grade materials, with India emerging through PLI scheme incentives in Gujarat and Maharashtra. Raw material dependencies draw from ferrous chloride, ferric nitrate, and specialized silane coupling agents. Single-source vulnerability characterizes bioconjugation expertise concentration among contract research organizations. Distribution runs through direct sales relationships for clinical-grade volumes, with catalog distributors handling North American academic spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetite nanoparticles represent an early-cycle expansion story as magnetic fluid hyperthermia protocols gain clinical traction in European university hospitals and battery developers test silicon-composite anode architectures.
For Market Incumbents: Harden pharmacopeial-grade certification moats through accelerated USP-NF and Ph.Eur. monograph compliance investments ahead of reimbursement pathway crystallization. Fortify backward integration into specialized silane chemistry capabilities to reduce dependency on scarce contract research organization expertise. Cobalt-doped ferrite substitution threats in magnetic separation equipment demand continuous R&D in superparamagnetic behavior optimization. For New Entrants and Emerging Players: Pursue battery anode formulation white space where magnetite's theoretical capacity advantages attract silicon-complementary development programs in California and South Korea. India's PLI scheme for specialty chemicals offers the most penetrable geography for greenfield synthesis capacity. Anchor go-to-market strategy through analytical-service bundling that mirrors academic procurement consolidation trends in California and Bavaria. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous flow microreactor synthesis platforms as pharmaceutical contract manufacturers adopt automated quality assurance protocols. Long-term viability over the next decade favors clinical-grade manufacturers with pharmacopeial certification and captive bioconjugation capabilities. Acquisition target archetype: mid-tier synthesis specialists with narrow particle-size distribution expertise and pending regulatory submissions. Watch FDA process analytical technology guidance enforcement intensity as inflection indicator for documentation burden escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial Certification Investment | USP-NF monograph compliance anchors premium positioning in oncology therapeutic supply chains. |
| Continuous Flow Microreactor Adoption | Inline DLS and TEM monitoring collapses batch release timelines for FDA process analytical technology compliance. |
| Bioconjugation Capability Buildout | Silane chemistry expertise in-house reduces dependency on scarce contract research organization capacity. |
| Battery Anode Formulation Partnership | South Korean and California battery developers test silicon-composite magnetite architectures for next-generation lithium-ion systems. |
| Greenfield Synthesis in India | PLI scheme incentives in Gujarat and Maharashtra attract specialty chemicals manufacturing capacity. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EMA guidance documents, FDA nanotechnology framework publications, REACH registration databases, and trade flow records for iron oxide nanoparticles. Primary interviews engaged synthesis chemists at precision chemical manufacturers, regulatory affairs leads at diagnostic reagent producers, procurement managers at pharmaceutical contract manufacturers, and biomedical engineers at European university hospitals. Secondary validation drew from SEC filings of listed chemical suppliers, ECHA registration dossiers, Swissmedic device approvals, and CDSCO registration records. Bottom-up volume estimates from application-specific absorption rates triangulate against top-down market sizing from supplier revenue analysis.
Forecast inputs include segmentation across product type, application, end user, and distribution channel dimensions throughout the projection horizon. Modeled variables span pharmacopeial-grade versus research-grade versus industrial-grade tier penetration, MRI contrast agent absorption in hospital networks, magnetic fluid hyperthermia protocol adoption curves, and battery anode formulation testing volumes. CAGRs derive from regression analysis of historical pricing and volume trajectories, adjusted for regulatory qualification timeline compression and feedstock cost volatility assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by battery-focused developers or accelerated pharmacopeial certification by Indian suppliers would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Flux Field Directional Material Market
Magnetic Materials
Europe Copper Magnetic Wire Market
Magnetic Materials
Magnetic Material Magnetization and Testing Equipment Market
Magnetic Materials
Magnet Buffer Market
Magnetic Materials
Copper Magnet Wire Market
Magnetic Materials
High Performance Permanent Magnet Market
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
Rare Earth Magnet Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Reduced Iron Powder Market
Magnetic Materials
Global Permanent Magnet Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
North America Ferrite Magnet Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Ferromanganese Market
Magnetic Materials
Ferrite Magnet Market