
 Amorphous Soft Magnetic Materials Market | 2026-2036
Amorphous Soft Magnetic Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Amorphous Soft Magnetic Materials Market Intelligence
The European Union's Green Deal, with its focus on energy efficiency in electronics, is restructuring demand for advanced magnetic materials. Hitachi Metals, Ltd. leverages its extensive research and development in nanocrystalline alloys to serve high-frequency applications. VACUUMSCHMELZE GmbH specializes in high-performance components for the renewable energy and automotive sectors. Meanwhile, Qingdao Yunlu Advanced Materials Technology Co., Ltd. anchors its position through large-scale production capacity for metallic glass.
Amorphous soft magnetic materials are metallic alloys lacking a long-range crystalline structure, typically produced via rapid solidification processes like melt spinning. This unique atomic arrangement results in superior magnetic properties, such as low coercivity and high permeability, minimizing energy loss in electrical devices. Transformers and inductors represent the largest application segments due to the material's efficiency benefits. Within end-user industries, the consumer electronics and renewable energy sectors are showing significant growth, driven by inverter and power supply component needs.
Global regulations like the EU's RoHS directive restrict hazardous substances, influencing material composition. Concurrently, China's GB standards for energy efficiency and international ISO 9001 quality management systems govern product performance and market access. Stakeholders must navigate the trade-off between the higher initial cost of amorphous materials and the long-term total cost of ownership benefits from improved energy efficiency.
Market Dynamics
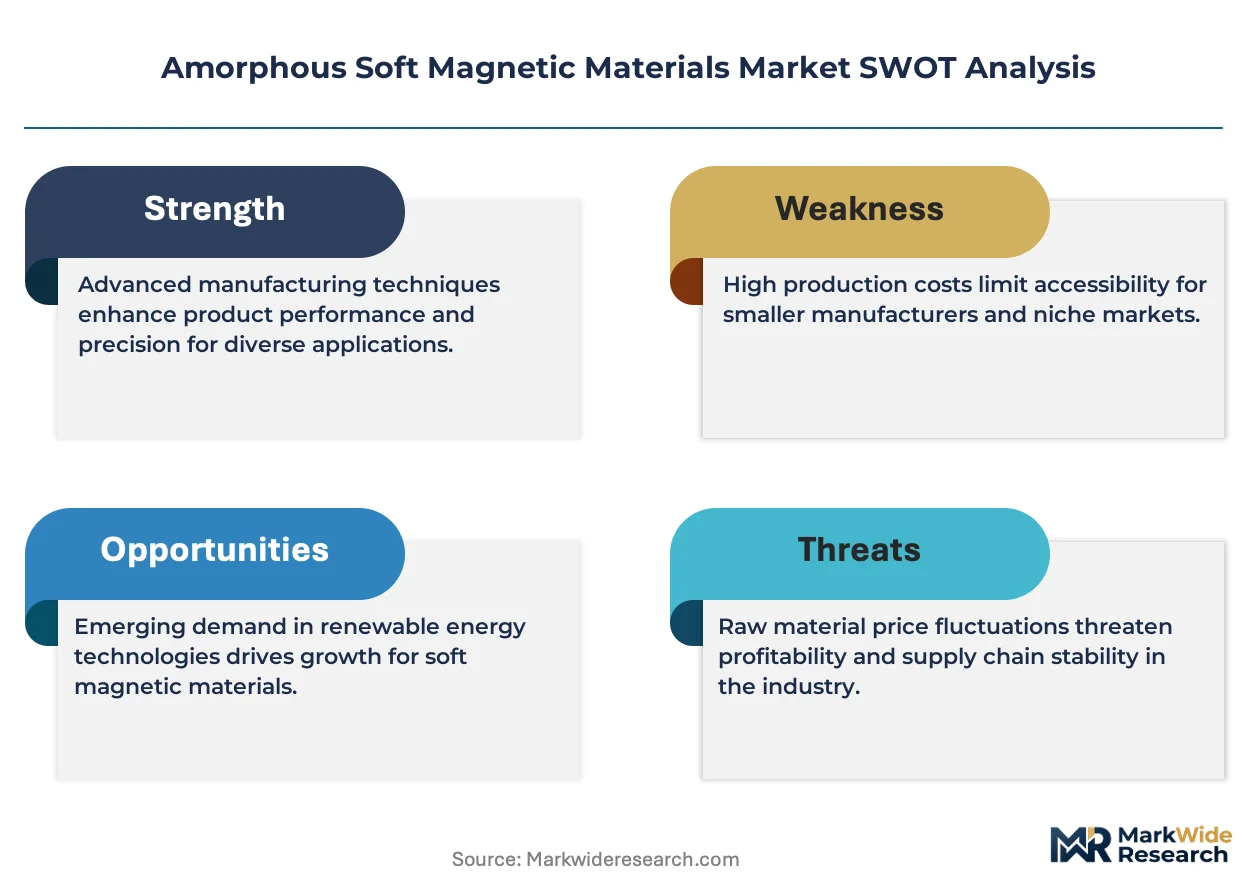
The market's central dynamic is the tension between accelerating energy efficiency mandates, such as the EU Green Deal, and a highly concentrated supply chain for raw amorphous ribbons. This structure forces downstream component manufacturers to balance long-term performance gains against supply dependency risks.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal and China's GB standards for electronics and transformers enforce stringent energy efficiency levels, compelling the substitution of traditional silicon steel with higher-performance amorphous and nanocrystalline materials.
- Renewable Energy Expansion:Demand from the solar and wind energy sectors for high-efficiency inverters and grid-tied transformers provides a primary growth engine, as these materials minimize power conversion losses.
- Electric Vehicle Production:The rapid scale-up of electric vehicle manufacturing, particularly in China, drives significant volume for amorphous materials used in onboard chargers, DC-DC converters, and high-frequency motors.
Market Restraints
- Higher Initial Cost:The upfront cost of amorphous soft magnetic materials is significantly higher than that of conventional grain-oriented electrical steel, posing a barrier for cost-sensitive applications despite long-term ownership benefits.
- Manufacturing Brittleness:The inherent brittleness of amorphous metallic glass ribbons complicates the winding and assembly process for magnetic cores, requiring specialized equipment and handling techniques that increase production costs.
- Supply Chain Concentration:Production of high-quality amorphous alloy ribbons is concentrated among a few key global suppliers, creating potential bottlenecks and price volatility for component manufacturers reliant on these inputs.
Strategic Opportunities
- High-Frequency Power Electronics:The development of materials optimized for high-frequency applications opens new opportunities in 5G telecommunication base stations, advanced data center power supplies, and server infrastructure.
- Wide-Bandgap Semiconductor Synergy:Combining amorphous magnetic components with silicon carbide (SiC) and gallium nitride (GaN) semiconductors enables the creation of ultra-compact, high-efficiency power conversion systems.
- Indian Grid Modernization:India's national initiatives to upgrade its electrical grid and promote electric mobility present a significant, underpenetrated market for energy-efficient distribution transformers and automotive components.
Industry Challenges
- Capital-Intensive Production:Establishing manufacturing capabilities for amorphous materials requires substantial capital investment in rapid solidification technology, such as melt spinning, and high-temperature annealing furnaces.
- Performance Standardization Gaps:A lack of universally accepted testing and performance standards for different grades of amorphous and nanocrystalline materials creates design challenges for engineers and complicates procurement.
- Specialized Talent Scarcity:The industry faces a shortage of materials scientists and process engineers with deep expertise in rapid solidification physics, magnetic annealing, and high-frequency material characterization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amorphous Soft Magnetic Materials Market |
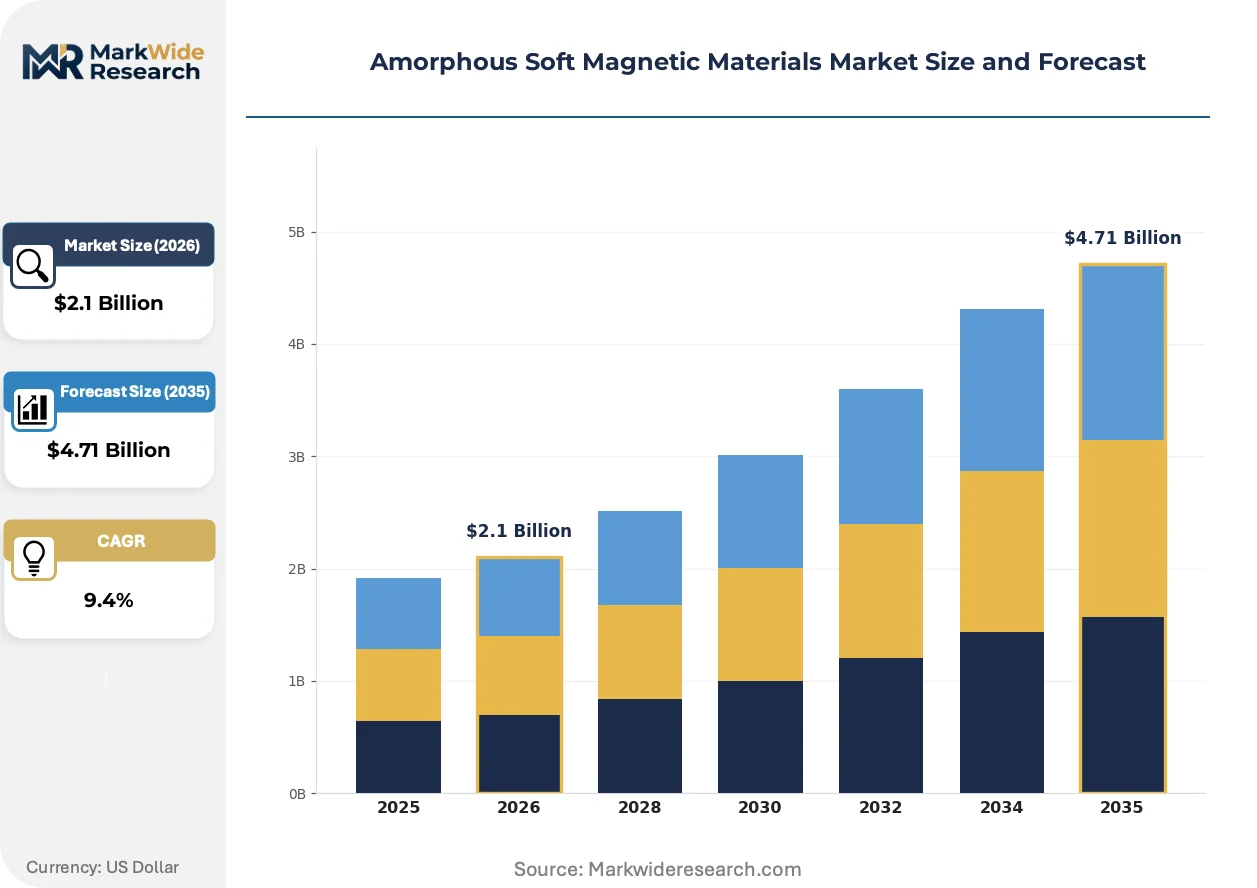
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic Glass, Nanocrystalline Alloys, Composite Materials, Powdered Metals Application: Transformers, Inductors, Electric Motors, Magnetic Sensors End User Industry: Consumer Electronics, Renewable Energy, Telecommunications, Aerospace Manufacturing Process: Rapid Solidification, Melt Spinning, Vacuum Casting, Thermomechanical Treatment |
| Companies Covered | Qingdao Yunlu Advanced Materials Technology Co., Ltd., Hitachi Metals, Ltd., Proterial, Ltd, TDK Corporation, Daido Steel Co., Ltd., Advanced Technology & Materials Co., Ltd., Henan Zhongyue Amorphous New Materials Co., Ltd., DMEGC Magnetics Co., Ltd., VACUUMSCHMELZE GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amorphous Soft Magnetic Materials Market Strategic Shifts & Innovations
The push toward higher power density and miniaturization is a dominant theme, compelling material innovation. This evolution is driven by the simultaneous demands of advanced electronics for smaller form factors and regulatory pressures for greater energy efficiency in power conversion.
Nanocrystalline alloys, produced by annealing amorphous precursors, provide superior magnetic permeability and low losses at very high frequencies. Automotive and renewable energy sectors are adopting these materials for compact electric vehicle chargers and solar microinverters. This shift toward advanced material science is decentralizing design innovation from the system integrator to the specialized magnetic component manufacturer.
China's GB standards governing the energy efficiency of electric motors and power transformers are becoming progressively more stringent. These regulations create a non-negotiable performance floor, forcing manufacturers to adopt amorphous alloys over traditional electrical steel to comply with minimum efficiency requirements. The distribution transformer and industrial motor segments are most affected, accelerating material qualification cycles within China's domestic supply chain.
A significant behavioral change is the move from sourcing standard off-the-shelf magnetic cores to engaging in collaborative, application-specific component design. This co-development model is displacing transactional purchasing in high-value segments where performance optimization is critical. The trend is most visible in the aerospace and medical device industries, where unique operating parameters and form factors demand fully customized magnetic solutions.
Amorphous Soft Magnetic Materials Market Segmentation
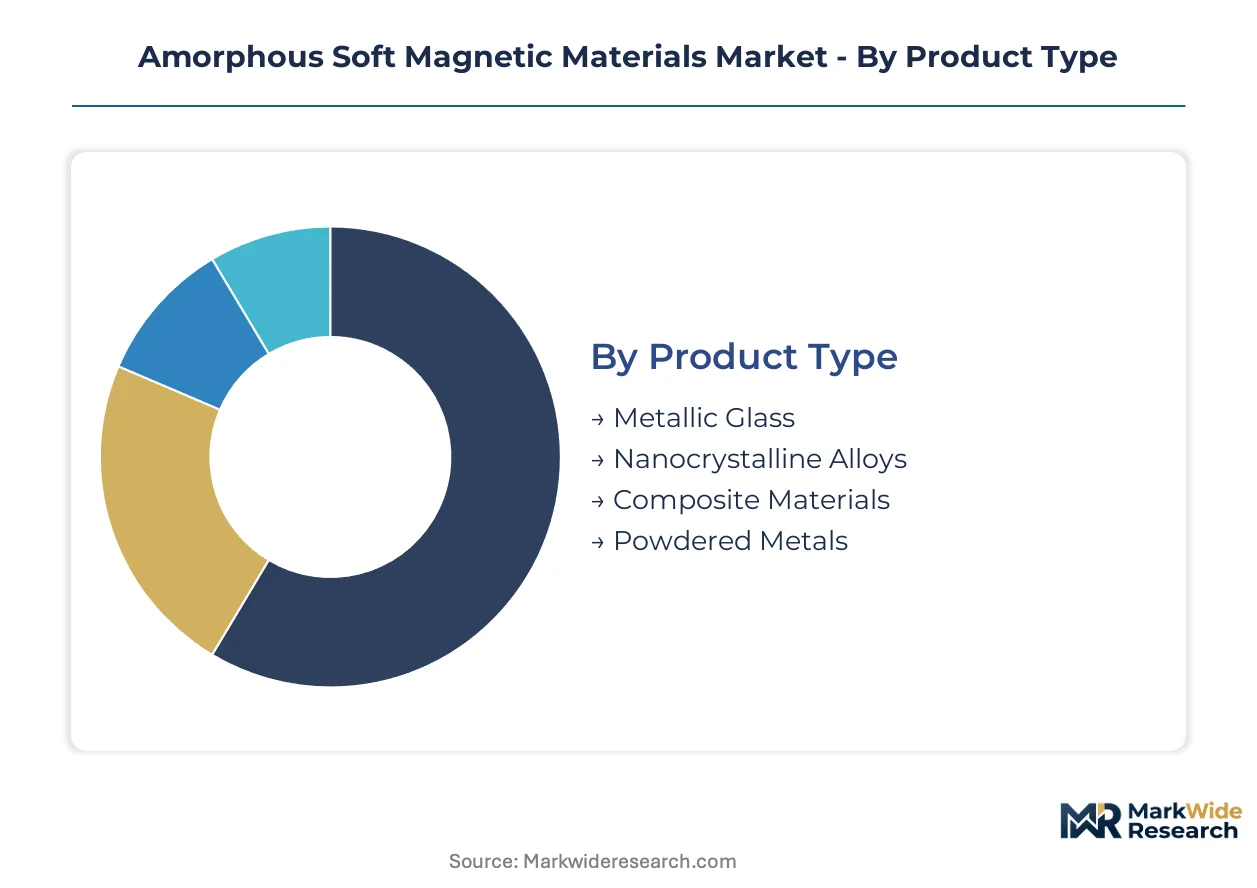
Understanding the segmentation of the amorphous soft magnetic materials market reveals how diverse performance requirements drive material and application choices. Each segment addresses specific technical needs, ranging from high-frequency operation to large-scale energy conversion, influencing material development and market penetration.
Product Type:
Buyers in this category differentiate based on the specific magnetic properties and performance characteristics required for their end applications.
- Nanocrystalline Alloys:These materials are formed by annealing amorphous precursors, resulting in a fine grain structure that offers superior magnetic permeability and extremely low losses at very high frequencies. Demand concentrates in advanced power electronics for electric vehicles and renewable energy microinverters, where efficiency at high switching speeds is critical.
- Metallic Glass:Produced via rapid solidification, metallic glass features a non-crystalline atomic structure, providing excellent soft magnetic properties like high permeability and low core losses. This material finds extensive use in high-efficiency distribution transformers in China and power supplies, where its energy-saving capabilities are valued despite higher initial costs.
- Composite Materials:These combine amorphous or nanocrystalline powders with binders, allowing for tailored magnetic properties and complex geometries.
- Powdered Metals:Often used for inductor cores, powdered metals offer design flexibility and good performance in specific frequency ranges.
Metallic Glass leads volumes today; Nanocrystalline Alloys is gaining share fastest.
Application:
The functional purpose within electrical systems determines material selection, with efficiency and power density being primary considerations.
- Transformers:Amorphous materials significantly reduce core losses in power transformers and distribution transformers, enhancing energy efficiency and reducing operational costs. The EU Green Deal and China's GB standards compel their adoption in grid infrastructure and industrial power systems, minimizing energy waste.
- Inductors:Essential for energy storage and filtering in power conversion circuits, amorphous and nanocrystalline inductors enable higher switching frequencies and smaller component sizes. This drives their use in compact power supplies and inverter designs for consumer electronics and solar systems, where space is at a premium.
- Electric Motors:These materials improve motor efficiency by reducing eddy current losses in high-speed and high-frequency motor designs.
- Magnetic Sensors:Amorphous alloys provide high sensitivity and linearity for various sensing applications, including automotive and industrial controls.
Transformers represent the largest volume, while Inductors show robust expansion.
End User Industry:
End-user industries prioritize different performance metrics and regulatory compliance, shaping material demand.
- Renewable Energy:This sector demands high-efficiency magnetic components for solar inverters, wind turbine generators, and grid-tied systems to minimize power conversion losses. The global push for clean energy and stringent efficiency targets, such as those in Europe, accelerate the adoption of advanced amorphous materials in this segment.
- Consumer Electronics:Miniaturization, higher power density, and improved energy efficiency are critical for devices like laptops, smartphones, and domestic appliances. Amorphous materials are integrated into power adapters, chargers, and power management units, reducing heat generation and extending battery life.
- Telecommunications:High-frequency power supplies and filtering components in 5G base stations and data centers benefit from the low-loss properties of these materials.
- Aerospace:Lightweight and high-performance magnetic components are crucial for avionics and power systems in aircraft, where reliability is paramount.
Renewable Energy is a significant growth driver, with Consumer Electronics maintaining consistent demand.
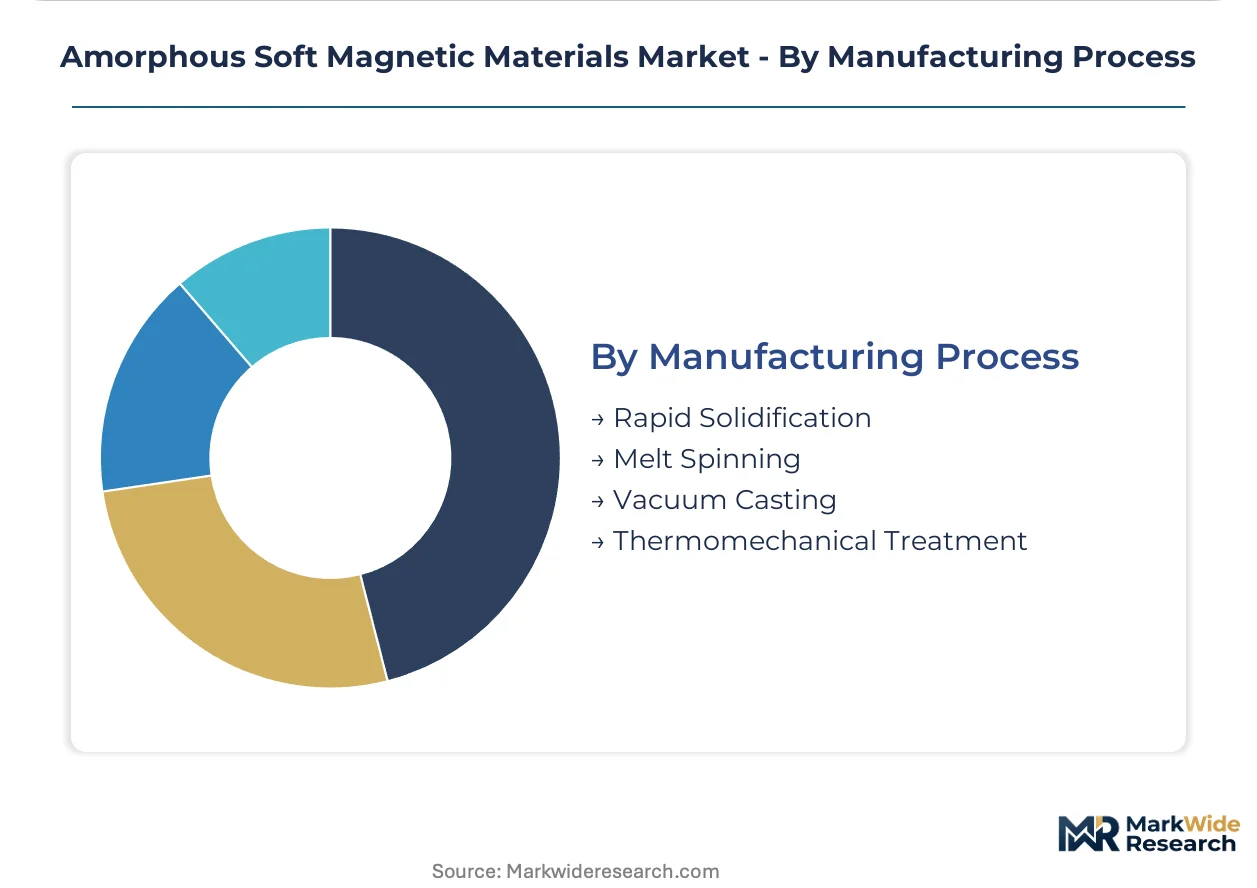
Manufacturing Process:
The chosen manufacturing process dictates the material's form factor, magnetic properties, and production cost structure.
- Melt Spinning:This rapid solidification technique produces thin, continuous ribbons of amorphous metal by rapidly cooling molten alloy on a rotating wheel. It is the primary method for large-scale production of amorphous ribbons used in transformer cores, offering high throughput and consistent quality.
- Rapid Solidification:This broad category encompasses various techniques that quickly cool molten alloys to prevent crystallization, including melt spinning and atomization. It is fundamental to creating the unique non-crystalline structure of amorphous metals, enabling their superior magnetic properties.
- Vacuum Casting:Used for producing bulk metallic glasses or specific geometries, this process involves casting molten metal in a vacuum environment.
- Thermomechanical Treatment:This involves controlled heating and mechanical deformation to optimize the magnetic properties of amorphous and nanocrystalline materials.
Melt Spinning remains the dominant method, while Rapid Solidification encompasses diverse emerging techniques.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A specialized workforce in materials science and advanced manufacturing anchors the global amorphous soft magnetic materials market. These technical capabilities drive innovation and production across key regions, influencing the adoption of high-performance alloys in critical sectors.
China
Demand for high-efficiency transformers and electric vehicle components drives material consumption in China. The nation's GB standards for energy efficiency in power transformers compel manufacturers to integrate amorphous alloys. Industrial clusters in the Yangtze River Delta and Pearl River Delta lead production and application development for metallic glass.
Germany
Germany's strong automotive and industrial electronics sectors generate significant demand for nanocrystalline alloys. The EU Green Deal initiatives push for greater energy efficiency in power conversion systems. Research institutions in cities like Dresden and Aachen collaborate with manufacturers on advanced magnetic material development.
United States
The renewable energy sector and data center infrastructure are primary demand drivers in the United States. Federal tax incentives for energy-efficient technologies support the adoption of advanced magnetic components. Silicon Valley and other tech hubs concentrate R&D efforts for high-frequency power electronics applications.
India
India's national grid modernization programs and electric mobility targets create a substantial market for distribution transformers and EV chargers. The Bureau of Indian Standards (BIS) promotes energy efficiency in electrical equipment. Industrial zones in Maharashtra and Gujarat are emerging as manufacturing centers for amorphous core components.
Japan
Japan's expertise in advanced materials and precision manufacturing fuels demand for high-performance magnetic alloys. METI (Ministry of Economy, Trade and Industry) supports research into next-generation power electronics. Companies in the Kanto region, particularly around Tokyo, innovate in nanocrystalline alloy production and application.
Amorphous Soft Magnetic Materials Market Key Industry Players
Capital-heavy producers of amorphous ribbons compete with asset-light designers of magnetic components. The market exhibits a tiered structure, with a few large-scale material suppliers providing raw input to numerous specialized component fabricators. Strategic archetypes include integrated material-to-component manufacturers, specialized alloy producers, and application-specific component designers. Dominant competitive moves involve capacity expansion for raw materials and strategic partnerships for application development.
Among the established market leaders, Hitachi Metals, Ltd. (now Proterial, Ltd.) and VACUUMSCHMELZE GmbH represent European and Japanese expertise in high-performance alloys. These companies focus on advanced nanocrystalline materials for demanding applications in automotive and renewable energy. Qingdao Yunlu Advanced Materials Technology Co., Ltd. anchors the Chinese market with its large-scale production capacity for metallic glass, primarily serving the high-volume transformer segment.
| Leading Market Players |
|---|
| Qingdao Yunlu Advanced Materials Technology Co., Ltd. |
| Hitachi Metals, Ltd. |
| Proterial, Ltd |
| TDK Corporation |
| Daido Steel Co., Ltd. |
| Advanced Technology & Materials Co., Ltd. |
| Henan Zhongyue Amorphous New Materials Co., Ltd. |
| DMEGC Magnetics Co., Ltd. |
| VACUUMSCHMELZE GmbH |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's stringent energy efficiency targets gate qualified amorphous material supply, influencing both premium-tier pricing and market access. This mandate drives demand for advanced materials while simultaneously raising the entry bar for suppliers and component manufacturers.
Pricing Analysis
Bundled solutions for magnetic components often command a premium, contrasting with transactional pricing for standard amorphous ribbons. Price differentiation stems from material performance grades, such as nanocrystalline alloys, and the level of application-specific customization. Pricing softness reflects the higher initial cost of amorphous materials compared to traditional electrical steel, particularly in cost-sensitive distribution transformer segments. Consumer electronics manufacturers exhibit lower price sensitivity due to the value placed on miniaturization and power density.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns manage the flow of amorphous ribbons from key production hubs to component fabricators. Supply concentration remains high in China, Japan, and Germany for specialized amorphous and nanocrystalline alloys. Raw material dependencies include high-purity alloying elements and specialized melt-spun ribbons. Single-source vulnerability for advanced alloy ribbons represents a significant structural risk for downstream manufacturers. Distribution primarily runs through direct sales channels to large-scale component assemblers and specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The amorphous soft magnetic materials market is a late-cycle quality story, driven by the shift towards nanocrystalline alloys for high-frequency power electronics.
For Market Incumbents: Cement market leadership by expanding nanocrystalline alloy production capacity in Europe, countering the threat from commodity metallic glass suppliers. Invest in advanced materials R&D for high-frequency applications, leveraging patent portfolios against emerging competitors. Vertical integration into downstream component fabrication can secure demand and capture additional value.
For New Entrants and Emerging Players: China's GB standards for energy efficiency in power transformers open a window for specialized component fabricators. Target the Indian grid modernization initiatives with localized, cost-effective amorphous core solutions, using direct sales channels to distribution transformer manufacturers. Focus on application-specific solutions for solar microinverters in underserved regional markets.
For Investors and Strategic Acquirers: Roll-up economics work for specialized component manufacturers because of the fragmented application landscape and demand for customized solutions. Focus on acquiring firms with unique expertise in high-frequency magnetic core winding or advanced material processing capabilities. Watch for regulatory shifts favoring domestic production as a key inflection indicator for regional investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Hitachi Metals expands nanocrystalline production to meet growing electric vehicle demand in Europe. |
| R&D Investment | VACUUMSCHMELZE invests in materials optimized for SiC/GaN power conversion systems. |
| Strategic Partnerships | Qingdao Yunlu forms alliances for advanced amorphous core integration in renewable energy projects. |
| Geographic Market Entry | Advanced Technology & Materials Co., Ltd. targets India's distribution transformer market with localized products. |
| Product Portfolio Diversification | TDK Corporation develops composite materials for high-frequency inductor applications in 5G infrastructure. |
Research Approach
Multiple input streams — industry whitepapers, company financial reports, and regulatory filings — were reconciled through a rigorous data collection process. Primary interviews with materials scientists, power electronics engineers, and procurement managers provided qualitative insights. Secondary validation from academic research and trade association reports confirmed market trends, employing both bottom-up and top-down triangulation.
The analytical framework reconciled diverse data streams to project market trajectories over the projection horizon. Segmentation dimensions modeled included product type, application, end-user industry, and manufacturing process, alongside the regional regulatory landscape. Compound annual growth rates were derived from historical trends and expert consensus, with electric vehicle production volumes serving as a key forecast input.
Revisions become necessary when significant policy changes, material science breakthroughs, or global economic shifts materialize. Forecasts reflect documented assumptions regarding technological adoption and market dynamics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Magnet Buffer Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Magnet Market
Magnetic Materials
High Performance Magnet Market
Magnetic Materials
North America Magnet Market
Magnetic Materials
Global Electrical Steel Sheet Market
Magnetic Materials
Flux Field Directional Material Market
Magnetic Materials
High Performance Permanent Magnet Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Global Non-Oriented Electrical Steel Market
Magnetic Materials
Global Soft Magnetic Materials Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
Magnetic Filter Market
Magnetic Materials
Global Soft Magnetic Alloys Market
Magnetic Materials
Neodymium-Iron-Boron Magnet Market