
 Sintered Magnet Market | 2026-2036
Sintered Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
Sintered Magnet Market Analytics
Buyer concentration among electric vehicle original equipment manufacturers is hardening procurement terms for sintered rare-earth magnets. JL MAG Rare-Earth anchors Chinese supply chains through integrated mining-to-magnet production. Shin-Etsu Chemical leverages decades of grain-boundary diffusion expertise to sustain premium positioning in Japanese automotive programs. VACUUMSCHMELZE dominates European aerospace and medical imaging segments with specialized cobalt-samarium formulations.
Sintered magnets are polycrystalline permanent magnets produced by compacting alloy powders and densifying them at temperatures below melting point, typically achieving remanence values exceeding 1.4 T for neodymium-iron-boron grades. Neodymium segments command the dominant revenue share due to unmatched energy density in traction motor applications. Cold pressing technology leads volume production for automotive end users while 3D printing emerges as a growth vector for complex sensor geometries with reduced rare-earth content. Die casting occupies niche positions in consumer electronics where dimensional precision at micro-scale determines performance.
China's MIIT enforces GB standards on rare-earth magnet performance and export quotas that directly constrain non-Chinese motor manufacturers. Japan's METI coordinates strategic stockpiling policies and domestic recycling investments to offset supply vulnerability. REACH and RoHS frameworks in Europe restrict heavy-metal content in magnet coatings, elevating compliance costs for exporters. Stakeholders must monitor substitution timelines for cerium-reduced formulations and assess captive mine investments before supply agreements expire.
Market Dynamics
Automotive electrification is compressing development cycles for traction motor magnets while China's export licensing regime forces motor manufacturers to reconfigure supply security frameworks. Dual carbon mandates in Beijing and strategic stockpiling in Tokyo are accelerating regional supply chain fragmentation.
Growth Catalysts
- Automotive traction motor procurement:Electric vehicle powertrain programs are pulling neodymium-iron-boron grades into high-volume qualification pipelines. Tier-1 motor suppliers are locking multi-year offtake agreements.
- Japan METI strategic stockpiling:Tokyo's coordinated recycling investments and national reserve policies are reducing import dependency ratios. Domestic magnet-to-magnet recovery facilities are scaling operational capacity.
- Grain-boundary diffusion processes:Advanced heat-treatment protocols are reducing dysprosium and terbium loading requirements. Japanese process licensors are expanding technology transfer programs to Korean motor assembly hubs.
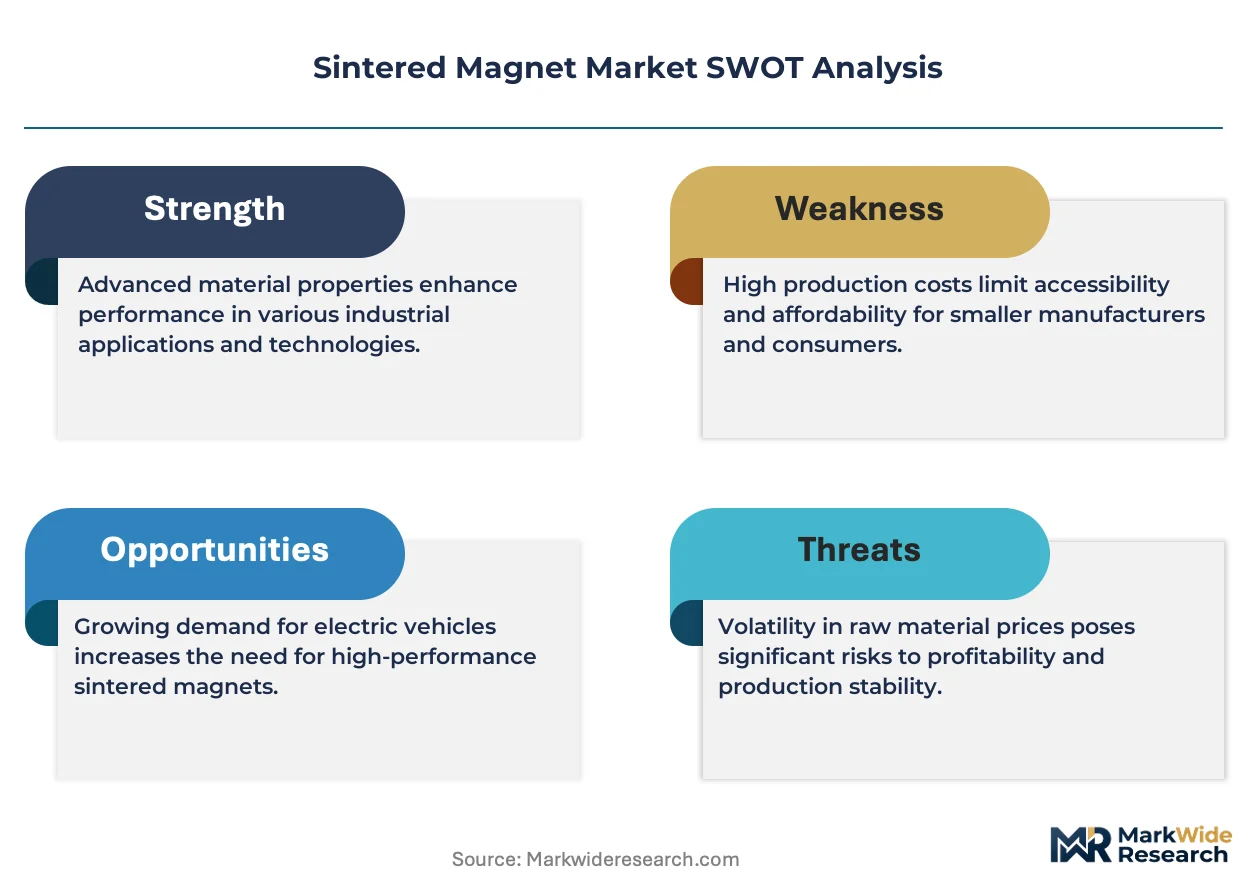
Market Restraints
- Rare-earth oxide price volatility:Neodymium and praseodymium concentrate quotations swing with Chinese spot market liquidity. Non-Chinese magnet fabricators face margin compression during supply tightness.
- Concentrated upstream mining:Bastnäsite and monazite extraction concentrates in Chinese and Burmese jurisdictions. Western motor OEMs confront single-source vulnerability for separated rare-earth oxides.
- Heavy-metal coating restrictions:REACH and RoHS frameworks in Europe constrain nickel-copper-nickel plating chemistries. Exporters must qualify alternative barrier coatings for automotive qualification.
Strategic Opportunities
- India automotive manufacturing:PLI scheme incentives for electric two-wheelers and passenger vehicles are creating localized magnet demand. Domestic motor assembly investments require sintered rare-earth supply partnerships.
- Additive manufacturing for sensor geometries:3D printing of complex magnetic architectures enables reduced rare-earth content in position sensing applications. Medical imaging equipment builders are piloting topology-optimized designs.
- Cerium-substituted formulations:Low-cost cerium additions to neodymium-iron-boron matrices are penetrating cost-sensitive auxiliary motor segments. Material scientists are pushing substitution ratios toward commercial thresholds.
Industry Challenges
- Magnet technician scarcity:Powder metallurgy specialists with hydrogen decrepitation and pressing expertise command premium compensation. Training pipelines lag demand from expanding Korean and Vietnamese fabrication facilities.
- Automotive qualification timelines:PPAP documentation and thermal cycling validation for traction motors extend months beyond industrial magnet approvals. Tier-1 suppliers face working capital strain during pre-production phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sintered Magnet Market |
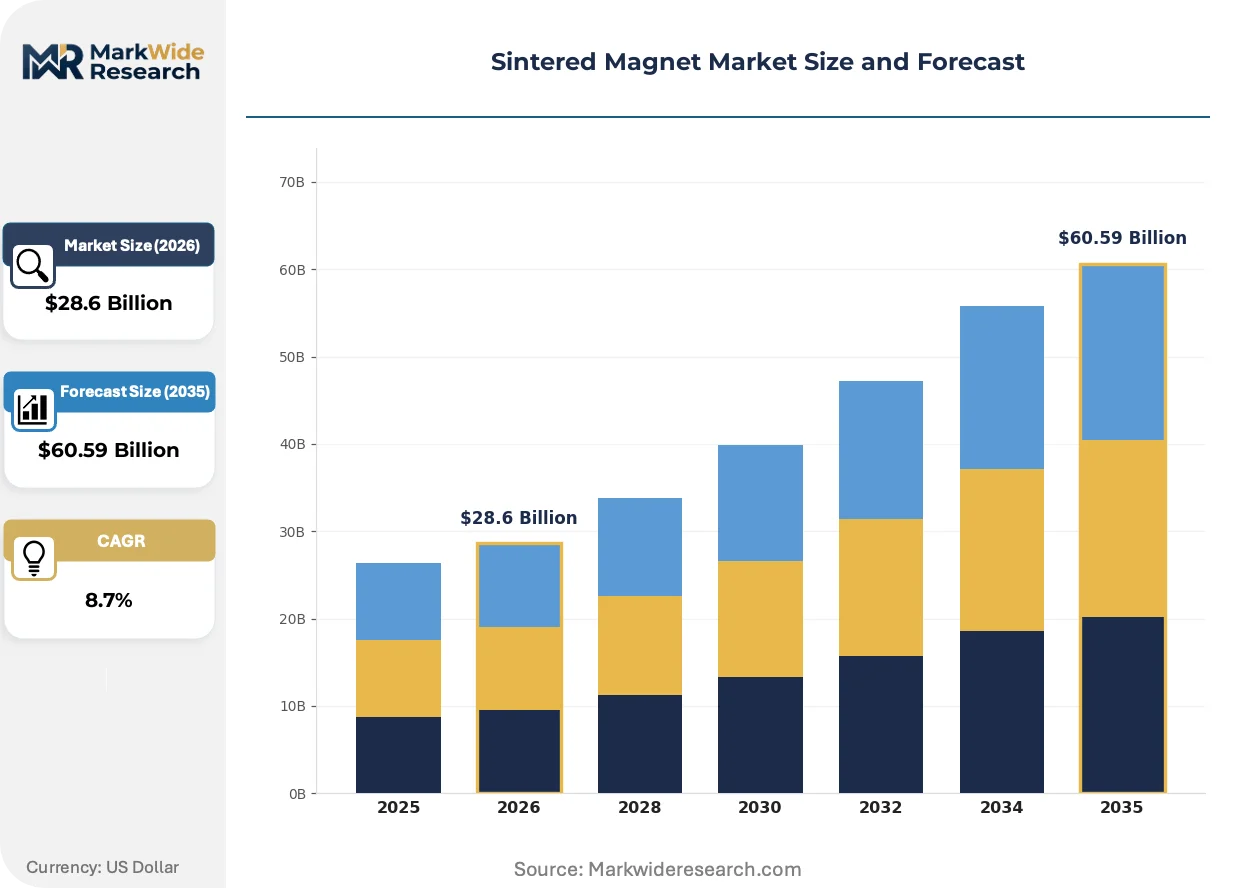
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neodymium, Samarium Cobalt, Ferrite, Alnico Application: Electric Motors, Generators, Sensors, Magnetic Resonance Imaging End User: Automotive, Consumer Electronics, Industrial Equipment, Renewable Energy Technology: 3D Printing, Cold Pressing, Die Casting, Injection Molding |
| Companies Covered | JL MAG Rare-Earth, Sanhuan, Shin-Etsu Chemical, VACUUMSCHMELZE, Arnold Magnetic Technologies, TDK Corporation, Yunsheng, Innuovo Magnetics, Proterial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sintered Magnet Market Evolving Landscape
Magnet fabrication is pivoting toward process intensification and rare-earth efficiency as energy density requirements harden and supply security concerns mount. Technical trajectories favor reduced heavy-rare-earth dependence and novel forming methods.
Hot isostatic pressing is integrating near-net-shape capabilities into automotive magnet production workflows. European aerospace tier suppliers are adopting HIP-consolidated cobalt-samarium geometries for turbine actuator applications. The technology is integrating complex internal cooling channel architectures that cold pressing cannot replicate, compressing machining waste streams.
China's MIIT is tightening GB standard enforcement on magnet performance consistency and traceability documentation. Export license applicants must now certify rare-earth origin and carbon intensity metrics. European motor manufacturers are responding by accelerating qualification of recycled-content magnets from Japanese urban mining operations.
Long-term service agreements are displacing spot procurement in wind turbine generator programs. Vestas and Siemens Gamesa are bundling magnet replacement schedules into 20-year O&M contracts. The shift concentrates buyer power among OEM service divisions and compresses spot market liquidity for high-grade neodymium segments.
Sintered Magnet Market Segmentation
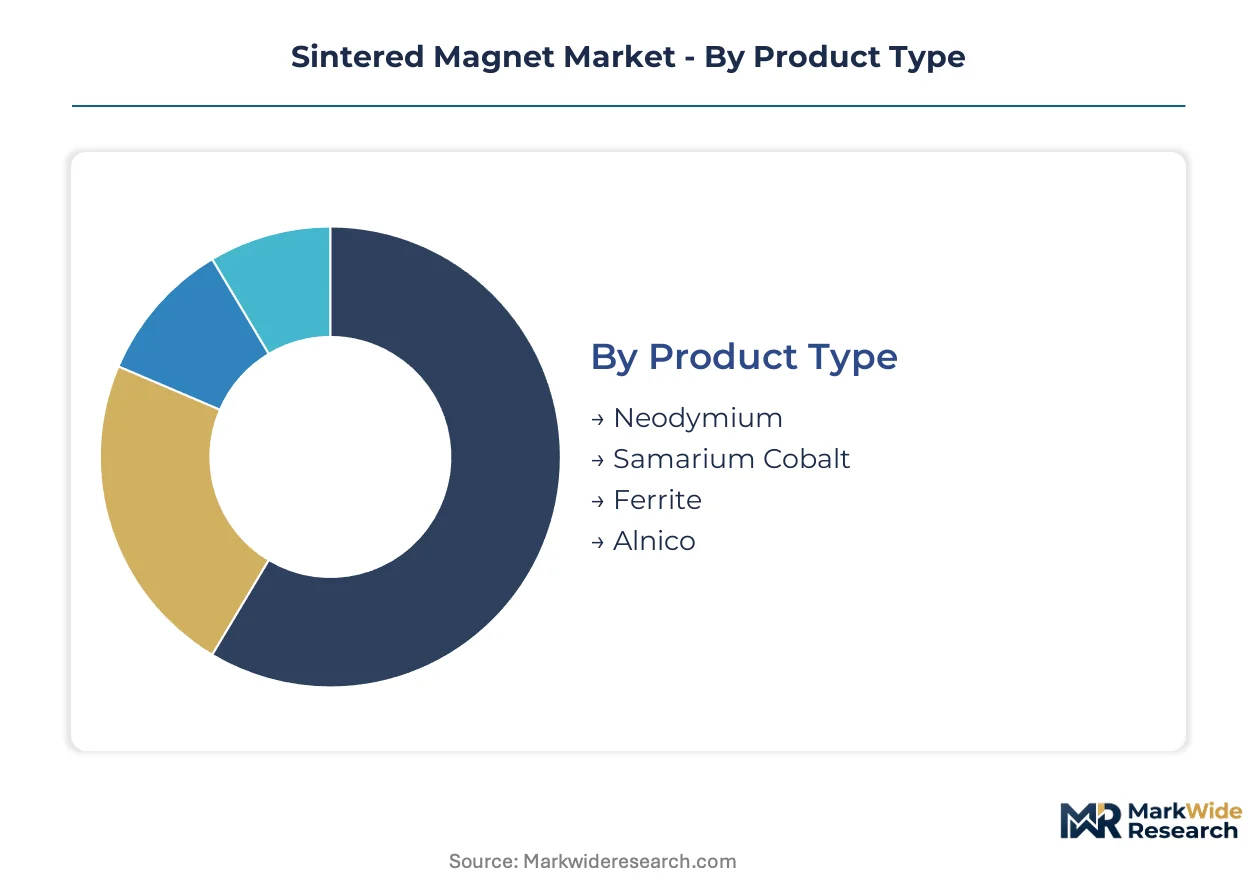
Sintered magnet procurement patterns diverge sharply across material grades, fabrication methods, and end-use specifications. Motor manufacturers prioritize energy density and thermal stability thresholds that vary by application, creating distinct qualification pipelines for each segment combination.
Product Type:
Material composition determines magnetic performance ceilings and rare-earth loading requirements.
- Neodymium:Neodymium-iron-boron alloys achieve remanence exceeding 1.4 T through controlled grain orientation during sintering. Automotive traction motor programs in Japan and South Korea specify this grade exclusively for permanent magnet synchronous machines operating above 150°C.
- Samarium Cobalt:SmCo formulations retain magnetic properties at temperatures exceeding 300°C with superior corrosion resistance. Aerospace actuator suppliers in France and Germany specify these grades for turbine applications where thermal cycling tolerance outweighs cost premiums.
- Ferrite:Strontium and barium hexaferrite variants serve cost-sensitive auxiliary motors in Indian electric two-wheelers.
- Alnico:Aluminum-nickel-cobalt castings persist in legacy instrumentation and high-temperature sensor housings.
Mature deployment sits with Neodymium. Newer deployment is concentrated in Samarium Cobalt for extreme environment applications.
Application:
Functional requirements dictate magnet geometry complexity and coating specifications.
- Electric Motors:Traction motor architectures require arc-segment or bread-loaf geometries with diametral magnetization patterns. Chinese and German OEMs are qualifying grain-boundary-diffused segments with reduced dysprosium content for passenger vehicle platforms.
- Generators:Direct-drive wind turbine generators specify large-block neodymium magnets with corrosion-resistant barrier coatings. Vestas and Siemens Gamesa service contracts are bundling magnet replacement schedules into long-term O&M agreements.
- Sensors:Position sensing applications favor multipole ring magnets with tight dimensional tolerances for automotive camshaft and crankshaft encoding.
- Magnetic Resonance Imaging:Superconducting magnet systems in medical imaging equipment require specialized sintered shim magnets for field homogeneity correction.
Volume concentration rests with Electric Motors. Technical differentiation is expanding fastest in Magnetic Resonance Imaging.
End User:
Customer procurement power and qualification timelines segment the demand base.
- Automotive:Tier-1 motor suppliers enforce PPAP documentation and thermal cycling validation protocols extending months beyond industrial approvals. Working capital requirements strain fabricators during pre-production phases.
- Consumer Electronics:Smartphone and wearable device assemblers specify micro-scale magnets with nickel-copper-nickel plating compliant with REACH heavy-metal restrictions.
- Industrial Equipment:Factory automation and robotics OEMs prioritize delivery reliability over specification extremes, accepting broader performance tolerances.
- Renewable Energy:Wind turbine generator procurement is shifting toward 20-year service agreements that bundle magnet replacement schedules, compressing spot market liquidity.
Procurement leverage concentrates in Automotive. Contract duration is extending most rapidly in Renewable Energy.
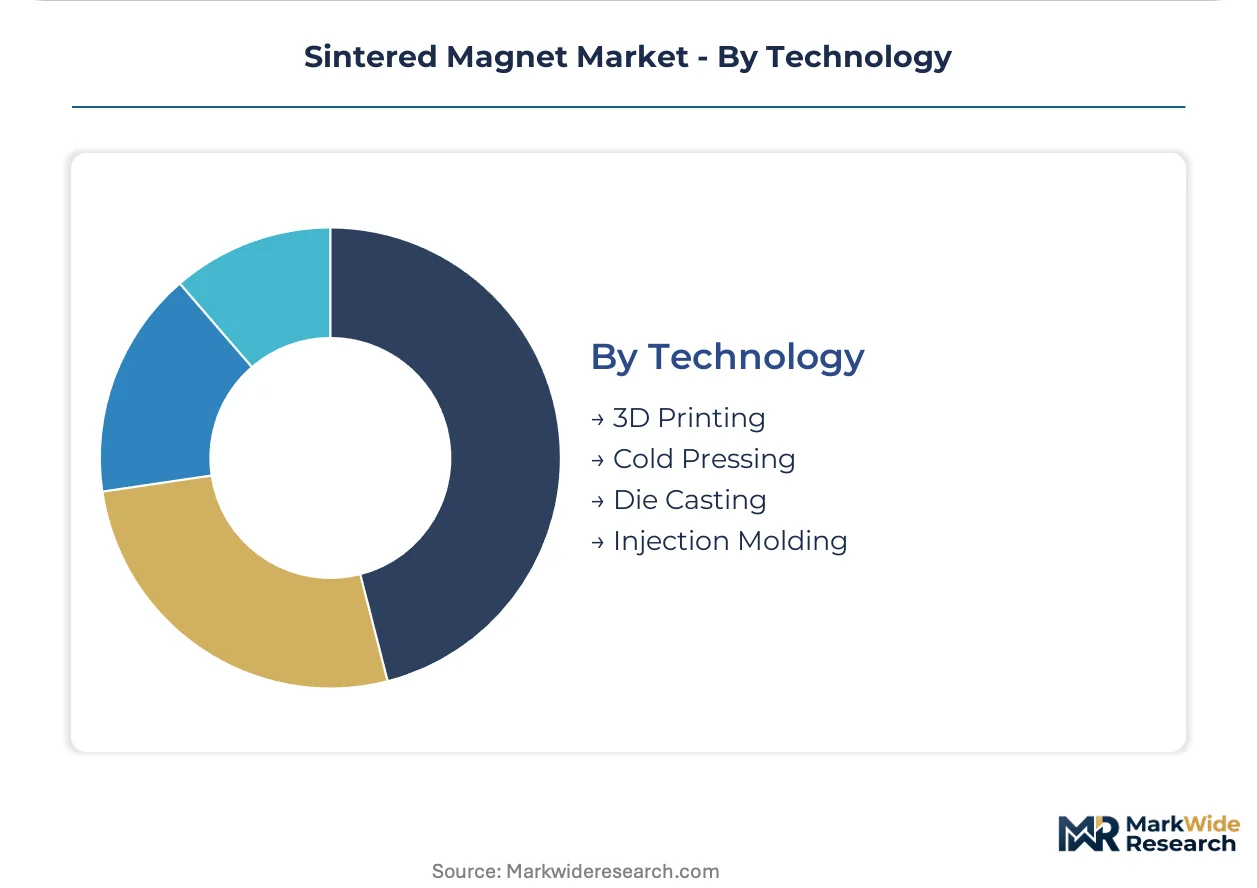
Technology:
Forming method selection balances geometric complexity against rare-earth efficiency and production scale.
- Cold Pressing:Uniaxial and isostatic pressing of aligned powder compacts dominates high-volume automotive production. Japanese fabricators license grain-boundary diffusion protocols to Korean motor assembly hubs to enhance coercivity without heavy-rare-earth loading.
- 3D Printing:Binder jetting and laser powder bed fusion enable topology-optimized sensor geometries with reduced rare-earth content. Medical imaging equipment builders in Switzerland are piloting complex internal channel architectures impossible with conventional pressing.
- Die Casting:Semi-solid metal injection suits consumer electronics micro-magnets requiring dimensional precision below 50 micrometers.
- Injection Molding:Polymer-bonded magnet compounds serve low-cost ferrite applications in appliance motors and automotive auxiliaries.
Scale leadership belongs to Cold Pressing. Process innovation is advancing most quickly in 3D Printing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Magnet procurement concentrates in East Asian manufacturing corridors where automotive electrification programs and wind turbine assembly hubs generate concentrated demand. Chinese export licensing and Japanese strategic stockpiling are fragmenting supply security frameworks across motor manufacturing networks. Regulatory divergence between Beijing's dual carbon mandates and European REACH restrictions is forcing fabricators to maintain parallel qualification pipelines.
China
Domestic EV powertrain programs and wind turbine generator contracts absorb the majority of neodymium-iron-boron output. MIIT enforces GB standards on magnet performance consistency and rare-earth origin traceability for export license applicants. JL MAG Rare-Earth anchors integrated mining-to-magnet production in Jiangxi province, supplying traction motor segments to domestic automotive OEMs.
Japan
Permanent magnet synchronous machines for hybrid and battery electric vehicles drive procurement from Tokyo and Nagoya motor assembly hubs. METI coordinates strategic stockpiling policies and domestic recycling investments through designated urban mining facilities. Shin-Etsu Chemical leverages grain-boundary diffusion expertise from Chiba prefecture operations to sustain premium positioning in automotive qualification programs.
Germany
Traction motor development for European passenger vehicle platforms and aerospace actuator specifications generate specialized cobalt-samarium demand. REACH and RoHS frameworks restrict heavy-metal coating chemistries, elevating compliance costs for nickel-copper-nickel plating alternatives. VACUUMSCHMELZE dominates aerospace and medical imaging segments from Hanau facilities with customized SmCo formulations.
South Korea
Hyundai-Kia electric vehicle platforms and domestic battery manufacturing pull rare-earth magnets into Gyeonggi-do and Ulsan industrial corridors. Technology transfer agreements with Japanese process licensors are scaling grain-boundary diffusion capabilities locally. Korean motor assembly hubs are qualifying reduced-dysprosium segments for next-generation traction applications.
United States
Defense aerospace programs and medical imaging equipment sustain demand for high-coercivity grades despite limited domestic fabrication capacity. NHTSA fuel economy standards and IRA clean vehicle incentives are accelerating EV motor manufacturing investments. Arnold Magnetic Technologies maintains specialty magnet production for aerospace and industrial sensor applications from Rochester, New York operations.
Sintered Magnet Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue additive manufacturing and cerium-substituted formulations. The fabricator base concentrates around three strategic archetypes: integrated Chinese rare-earth miners with captive magnet production, Japanese process licensors with grain-boundary diffusion expertise, and European specialists in high-temperature cobalt-samarium grades. Dominant competitive moves include technology licensing partnerships for reduced heavy-rare-earth processing and backward integration into rare-earth separation capacity.
Among Chinese integrated producers, JL MAG Rare-Eth and Sanhuan exemplify the mining-to-magnet archetype with upstream control over concentrate supply. Japanese fabricators Shin-Etsu Chemical and TDK Corporation occupy positions within the premium process-licensing tier, while European specialist VACUUMSCHMELZE anchors the high-temperature aerospace segment from German operations.
| Leading Market Players |
|---|
| JL MAG Rare-Earth |
| Sanhuan |
| Shin-Etsu Chemical |
| VACUUMSCHMELZE |
| Arnold Magnetic Technologies |
| TDK Corporation |
| Yunsheng |
| Innuovo Magnetics |
| Proterial |
| Others |
Value Network & Pricing Analysis
Powder metallurgy specialists with hydrogen decrepitation expertise cluster in Japan's Chiba prefecture and Korea's Gyeonggi-do corridor, creating labor-cost differentials that widen pricing spreads between premium grain-boundary-diffused segments and standard cold-pressed grades. Automotive OEM procurement teams exploit this tiered labor geography to source qualified magnets at divergent cost bases.
Pricing Analysis
High-volume automotive contracts trade at thin margins while aerospace and medical imaging segments sustain premium markups. Pricing stratifies across automotive qualification tiers, grain-boundary diffusion certification levels, and volume scale commitments. Cost compression in standard neodymium grades intensifies as Chinese integrated producers expand cold-pressing capacity. Tier-1 motor suppliers exhibit acute price sensitivity; medical imaging OEMs prioritize thermal stability over unit cost.
Supply Chain Analysis
Rare-earth oxide supply rests on Chinese bastnäsite mining in Jiangxi and Burmese monazite extraction, with separated neodymium and dysprosium outputs feeding Japanese and Korean fabrication hubs. Magnet powder production draws from hydrogen decrepitation processing and jet milling operations concentrated in East Asian manufacturing corridors. Single-source vulnerability for heavy-rare-earth elements creates structural risk for non-Chinese motor manufacturers. Distribution runs through long-term offtake agreements rather than spot procurement, particularly for automotive traction motor programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream rare-earth separation capacity and downstream magnet fabrication expertise determine competitive survival. Players are pursuing captive mine investments to offset Chinese export licensing exposure.
For Market Incumbents:Lock in multi-year offtake agreements with Korean and Japanese automotive OEMs before qualification windows close. Secure backward integration into rare-earth separation capacity to mitigate MIIT export license volatility. Defend against cerium-substituted formulations by accelerating grain-boundary diffusion licensing to Southeast Asian fabrication hubs.
For New Entrants and Emerging Players:Tier-2 motor suppliers in India's PLI scheme corridors represent the most penetrable channel partner type for reduced-dysprosium segment qualification. Target electric two-wheeler manufacturers in Tamil Nadu and Gujarat seeking localized magnet partnerships. Pursue additive manufacturing pilot programs with Swiss medical imaging equipment builders as a technology differentiation angle.
For Investors and Strategic Acquirers:Re-rating potential sits with urban mining operators given Tokyo's METI recycling investment acceleration and tightening rare-earth origin traceability requirements. Long-term viability favors magnet-to-magnet recovery facilities with established Japanese offtake relationships. Watch Japanese strategic stockpile release schedules as an inflection indicator for spot market liquidity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Separation | Captive oxide supply insulates VACUUMSCHMELZE and European fabricators from Chinese export licensing volatility. |
| Grain-Boundary Diffusion Licensing Expansion | Shin-Etsu Chemical's technology transfer to Korean hubs reduces heavy-rare-earth loading across Hyundai-Kia platforms. |
| Urban Mining Facility Scale-Up | Japanese magnet-to-magnet recovery operations under METI coordination offset import dependency for automotive programs. |
| Cerium-Substituted Formulation Development | Low-cost auxiliary motor segments in Indian electric two-wheelers absorb experimental neodymium-iron-boron-cerium matrices. |
| Additive Manufacturing Qualification | Swiss medical imaging builders pilot topology-optimized sensor geometries with reduced rare-earth content via binder jetting. |
Research Methodology
Trade statistics from Chinese customs authorities, Japanese METI mineral resource reports, and Korean MOTIE industrial production indices formed the secondary backbone. Primary interviews with powder metallurgy plant managers, Tier-1 motor supplier procurement leads, rare-earth trading desk operators, and automotive platform engineers validated supply chain configurations. Bottom-up magnet fabrication capacity estimates triangulated against top-down automotive traction motor demand projections.
Bottom-up modeling segmented the market by material grade, forming technology, and end-use qualification tier across the analysis window. Forecasts incorporated rare-earth oxide price elasticity, automotive electrification penetration curves, and regulatory timeline assumptions including REACH coating restrictions and MIIT traceability mandates. CAGRs derived from volume-weighted segment growth rates applied to baseline procurement data.
Caveats apply where Chinese export license issuance rates or Japanese strategic stockpile release volumes could materially shift the outlook. Rare-earth oxide price volatility, automotive platform cancellation decisions, and substitution breakthroughs in cerium-reduced formulations represent additional revision triggers. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Asia-Pacific Magnet Wire Market
Magnetic Materials
Magnet Wire Market
Magnetic Materials
North America Ferrite Magnet Market
Magnetic Materials
Magnetic Carbon Nanofoam Market
Magnetic Materials
Global Non-Oriented Electrical Steel Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Ferrite Magnet Market
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
Europe Copper Magnetic Wire Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
High Performance Magnet Market
Magnetic Materials
Magnet Market
Magnetic Materials
Magnetic Materials Market
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
Neodymium-Iron-Boron Magnet Market
Magnetic Materials
Neodymium [Nd-Fe-B] Magnet Market