
 Magnetostrictive Materials Market | 2026-2036
Magnetostrictive Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetostrictive Materials Market Analytics
Modular actuator assemblies is recalibrating buyer choice in the magnetostrictive materials sector. VACUUMSCHMELZE GmbH & Co. KG leverages its vacuum induction melting expertise to dominate high-purity Terfenol-D supply. TdVib LLC anchors its position through specialized energy harvesting configurations. Dexter Magnetic Technologies, Inc. differentiates via precision magnetic assemblies for aerospace telemetry.
Magnetostrictive materials exhibit dimensional change under magnetic field exposure, with Terfenol-D achieving strains exceeding 1500 ppm at room temperature for precision transduction. These alloys convert magnetic energy to mechanical force in sonar projectors, fuel injectors, and vibration damping systems. Terfenol-D commands the largest product share due to its giant magnetostrictive coefficient, while Galfenol gains traction in harsh-environment sensors where mechanical durability outweighs peak strain performance. Thin-film technology represents the fastest-growing fabrication route as microscale actuators penetrate telecommunications switching.
EPA oversees rare earth processing emissions in the United States, while REACH governs chemical registration and substitution protocols across Europe. Japan's METI coordinates domestic rare earth stockpiling to secure magnetostrictive supply chains against export volatility. Stakeholders must monitor regulatory thresholds for dysprosium and terbium content, as these critical elements face intensifying supply scrutiny.
Market Dynamics
Thin-film fabrication routes are compressing minimum viable batch sizes and enabling microscale actuator penetration into telecommunications switching, fundamentally altering the economics of precision transduction component supply.
Growth Catalysts
- Naval Sonar Modernization:Terfenol-D alloys power next-generation precision sonar projectors for undersea surveillance. Defense procurement cycles in Germany and Japan sustain alloy demand.
- EPA Rare Earth Processing Standards:Tightening emission thresholds for dysprosium and terbium refining accelerate investment in closed-loop material recovery systems.
- Energy Harvesting Architectures:Galfenol-based vibration scavengers capture mechanical waste energy in heavy industrial equipment. Manufacturing facilities in the United States deploy these for auxiliary power generation.
Market Restraints
- Critical Element Concentration:Dysprosium and terbium supply concentrates in Chinese refining complexes. Export quota volatility exposes downstream magnetostrictive processors to input disruption.
- Alloy Brittleness Constraints:Terfenol-D's mechanical fragility limits strain cycling durability. Applications requiring millions of operational cycles favor piezoelectric alternatives.
- REACH Substitution Pressures:ECHA scrutiny of heavy rare earth content drives formulators toward lower-strain Galfenol variants with reduced terbium dependency.
Strategic Opportunities
- Telecommunications Micro-Actuators:Thin-film Terfenol-D deposition enables optical switch arrays. NTT and Deutsche Telekom infrastructure upgrades create specification pull.
- IRA Clean Energy Manufacturing Credits:Domestic content bonuses for rare earth processing incentivize US-based Terfenol-D vacuum melting capacity expansion.
- Aerospace Telemetry Miniaturization:Magnetostrictive strain sensors replace bulkier inductive pickups in flight data acquisition. Boeing and Airbus supplier qualification programs open certification pathways.
Industry Challenges
- Vacuum Metallurgy Talent Scarcity:High-purity Terfenol-D production requires rare expertise in induction melting atmosphere control. Workforce development lags capacity expansion timelines.
- Multi-Physics Simulation Complexity:Coupled magneto-mechanical-thermal modeling demands specialized finite-element capabilities. Design houses struggle to predict fatigue life accurately.
- Dual-Use Export Classification:Sonar-grade alloys fall under US ITAR and EU dual-use regulations. Licensing delays extend customer qualification cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetostrictive Materials Market |
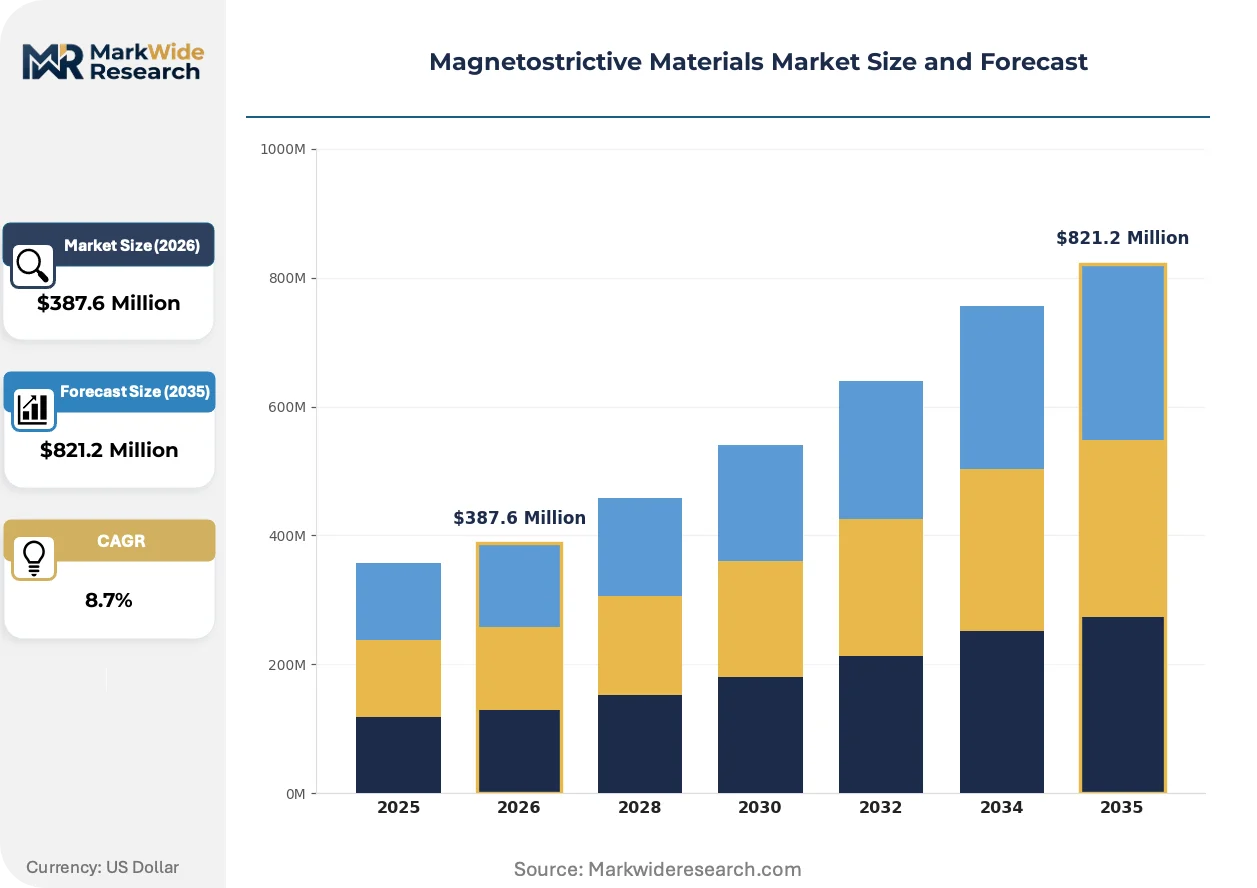
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terfenol-D, Galfenol, Nickel, Cobalt Application: Sensors, Actuators, Energy Harvesting, Sonar End User: Aerospace, Automotive, Industrial Automation, Telecommunications Technology: Nano-Composite, Thin-Film, Bulk, Coatings |
| Companies Covered | Dexter Magnetic Technologies, Inc., VACUUMSCHMELZE GmbH & Co. KG, Etrema Products, Inc., Grirem Advanced Materials Co., Ltd., Hitachi Metals, Ltd., TdVib LLC, Gansu Tianxing Rare Earth Functional Materials Co., Ltd., Metglas, Inc., TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetostrictive Materials Market Evolving Landscape
Additive manufacturing of magnetostrictive composites is dissolving traditional powder metallurgy constraints. Laser powder bed fusion enables topology-optimized actuator geometries previously impossible to machine from monolithic billets.
Terfenol-D thin-film sputtering is automating wafer-scale production of microactuator arrays for fiber optic switching. Lumentum and Coherent have qualified 8-inch deposition lines. This automation is collapsing per-unit costs for telecom infrastructure and enabling MEMS-scale integration previously reserved for piezoelectric alternatives.
Japan's METI rare earth stockpiling mandate is restructuring procurement security protocols. Strategic reserve requirements compel domestic manufacturers to maintain 60-day Terfenol-D inventory buffers. Japanese actuator assemblers are diversifying alloy sourcing toward Australian and US refined feedstock to satisfy origin verification requirements.
Specification-driven vendor consolidation is compressing qualified supplier lists across aerospace and defense procurement. Tier-1 integrators now mandate AS9100D certification and ITAR registration for magnetostrictive component vendors. German sensor houses are responding by acquiring captive vacuum melting capability rather than relying on merchant alloy supply.
Magnetostrictive Materials Market Segmentation
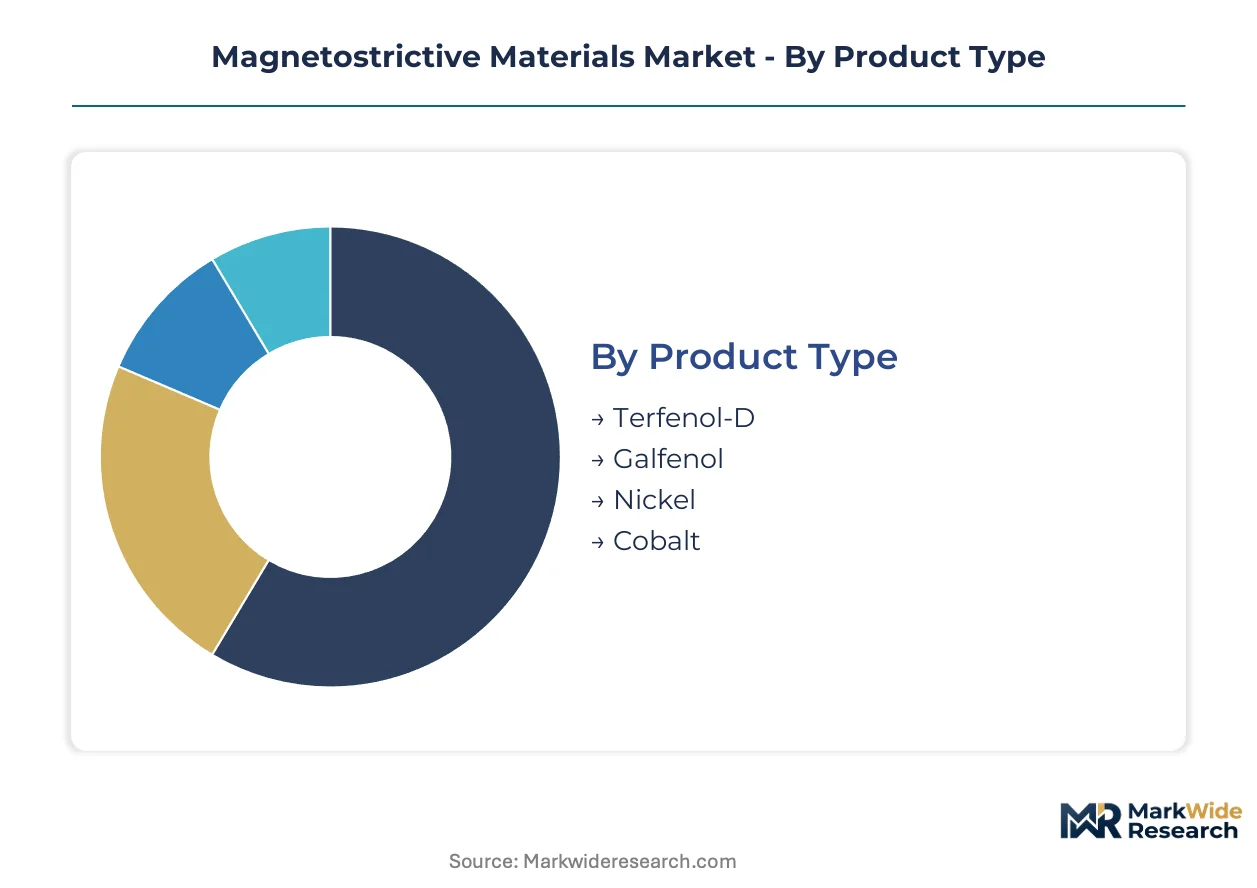
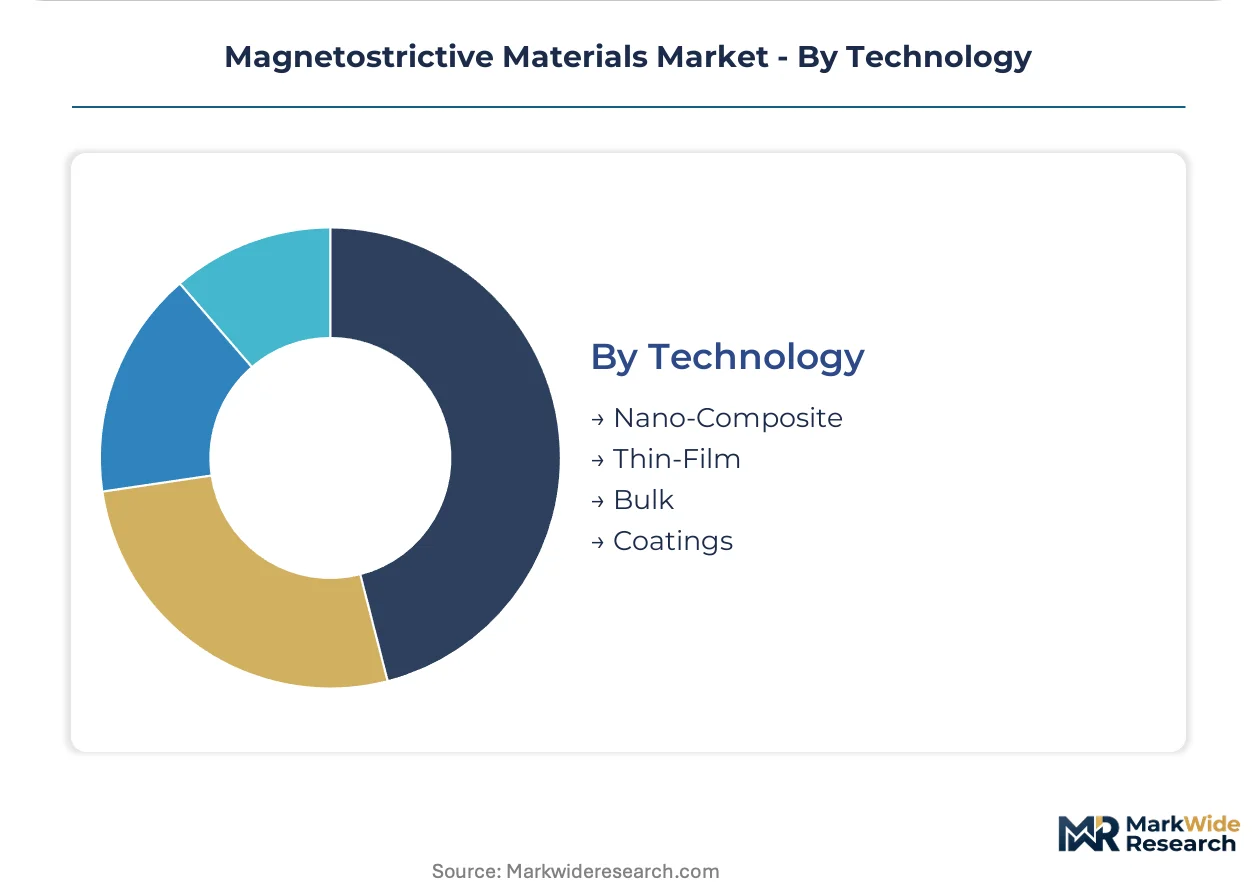
Magnetostrictive materials fragment across alloy chemistry, integration depth, and fabrication scale. Each segmentation axis carries distinct margin profiles and technical qualification barriers that reshape procurement patterns across defense, industrial, and telecommunications verticals.
Product Type:
Standalone alloy ingots supply discrete actuator manufacturers, while pre-machined geometries embed directly into OEM subsystems.
- Terfenol-D:This terbium-dysprosium-iron alloy achieves magnetostrictive strains exceeding 1500 ppm at room temperature. Naval procurement in Germany and Japan anchors demand for sonar-grade billets, though supply security concerns intensify due to heavy rare earth dependency.
- Galfenol:Iron-gallium alloys trade peak strain for mechanical durability and machinability. Industrial vibration sensors in United States manufacturing plants favor this chemistry where fatigue resistance outweighs maximum displacement specifications.
- Nickel:Conventional magnetostrictive element for legacy sensor architectures requiring moderate strain response.
- Cobalt:High-temperature stability drives niche adoption in aerospace telemetry applications.
Volume placements concentrate in Terfenol-D; the faster expansion belongs to Galfenol.
Application:
Cost tiers separate precision defense systems from commodity industrial monitoring equipment.
- Sensors:Strain gauges and torque transducers convert mechanical deformation into electrical signals via magnetostrictive ribbons. Automotive drivetrain monitoring in Germany and flight data acquisition for Boeing and Airbus supplier networks drive specification diversity.
- Actuators:Precision positioning systems exploit giant magnetostriction for microscale displacement control. Telecommunications optical switches at NTT and Deutsche Telekom infrastructure upgrades pull thin-film deposition capacity.
- Energy Harvesting:Vibration scavengers capture waste mechanical energy in heavy industrial equipment.
- Sonar:Underwater acoustic projectors remain the highest-specification application with ITAR-controlled supply chains.
Defense procurement dominates absolute value; telecommunications micro-actuators are climbing the fastest.
End User:
Customer maturity separates specification-driven aerospace qualification from price-sensitive automotive tier-2 supply.
- Aerospace:Flight-qualified magnetostrictive sensors replace inductive pickups in telemetry systems. AS9100D certification and ITAR registration requirements compress qualified vendor lists to vacuum melting specialists with documented traceability.
- Automotive:Fuel injection and valve timing actuators exploit rapid response characteristics. Tier-1 suppliers in Germany and Japan specify alloy purity thresholds that eliminate merchant feedstock variability.
- Industrial Automation:Position feedback and vibration monitoring systems deploy across manufacturing facilities.
- Telecommunications:Fiber optic switching arrays demand wafer-scale thin-film uniformity.
Procurement scale peaks in Industrial Automation; specification premiums concentrate in Aerospace.
Technology:
Fabrication scale determines minimum viable batch economics and integration flexibility.
- Thin-Film:Sputter deposition onto 8-inch wafers enables MEMS-scale actuator arrays. Lumentum and Coherent qualification programs collapse per-unit costs for optical switching infrastructure previously reserved for piezoelectric alternatives.
- Bulk:Vacuum induction melting produces monolithic billets for high-force actuators. VACUUMSCHMELZE GmbH & Co. KG dominates this route through atmosphere control expertise that ensures terbium and dysprosium homogeneity.
- Nano-Composite:Embedded particle architectures improve mechanical durability in cycling-intensive applications.
- Coatings:Surface deposition protects substrates while retaining magnetostrictive response.
Installed capacity concentrates in Bulk; capacity expansion is steepest in Thin-Film.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in vacuum metallurgy clusters across Germany, Japan, and the United States, while consumption pulls toward precision manufacturing hubs in these same markets. Rare earth refining bottlenecks in China create supply security tensions that reshape procurement patterns. Defense procurement cycles and telecommunications infrastructure upgrades drive divergent demand profiles by geography.
United States
Naval sonar modernization programs and aerospace telemetry miniaturization anchor demand for Terfenol-D alloys. EPA rare earth processing emission standards tighten refining thresholds, accelerating closed-loop material recovery investments. Manufacturing facilities in Ohio and Pennsylvania deploy Galfenol-based vibration scavengers for auxiliary power generation in heavy industrial settings.
Germany
Automotive drivetrain monitoring and precision sensor architectures consume magnetostrictive ribbons for torque transducers. REACH chemical registration protocols govern dysprosium and terbium substitution thresholds, pressuring formulators toward lower-strain variants. The Ruhr industrial corridor and Bavarian precision engineering clusters anchor vacuum induction melting capacity for high-purity alloy supply.
Japan
Telecommunications infrastructure upgrades at NTT and specialized energy harvesting configurations drive specification diversity in actuator procurement. METI coordinates domestic rare earth stockpiling mandates requiring 60-day Terfenol-D inventory buffers. The Nagoya-Chubu manufacturing belt concentrates thin-film sputtering capacity for MEMS-scale microactuator production.
China
Rare earth refining concentration creates upstream supply leverage over global magnetostrictive feedstock flows. Export quota volatility for dysprosium and terbium exposes downstream processors to input disruption risks. Gansu and Inner Mongolia host primary rare earth separation complexes that supply alloy manufacturers in Japan and Germany.
South Korea
Semiconductor equipment and display manufacturing automation generate demand for precision positioning actuators. The country's national industrial technology regulator coordinates domestic rare earth alloy processing investments to reduce import dependency. The Seoul Capital Area concentrates actuator assembly operations serving telecommunications and industrial automation OEMs.
Magnetostrictive Materials Market Competitive Landscape
The competitive structure tilts toward vacuum metallurgy specialists with atmosphere control expertise. Three to five dominant players control high-purity Terfenol-D supply through proprietary induction melting protocols, while mid-tier fabricators compete on Galfenol machining and thin-film deposition services. Strategic archetypes separate vacuum melting purists, thin-film sputtering specialists, and integrated actuator assemblers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with German and Japanese players acquiring captive alloy supply to secure qualification pathways.
Among vacuum metallurgy specialists, VACUUMSCHMELZE GmbH & Co. KG exemplifies the high-purity alloy archetype through its German GmbH structure, while TdVib LLC occupies a position within the specialized energy harvesting tier. Dexter Magnetic Technologies, Inc. represents the precision magnetic assembly segment serving aerospace telemetry applications. These three anchors illustrate how geographic clustering in Germany and the United States aligns with defense and telecommunications demand verticals.
| Leading Market Players |
|---|
| Dexter Magnetic Technologies, Inc. |
| VACUUMSCHMELZE GmbH & Co. KG |
| Etrema Products, Inc. |
| Grirem Advanced Materials Co., Ltd. |
| Hitachi Metals, Ltd. |
| TdVib LLC |
| Gansu Tianxing Rare Earth Functional Materials Co., Ltd. |
| Metglas, Inc. |
| TDK Corporation |
| Others |
Value Network & Pricing Analysis
AS9100D certification mandates from Boeing and Airbus supplier networks are compressing qualified vendor lists and forcing alloy processors to absorb qualification costs that propagate through contract pricing structures. This specification-driven consolidation rewards vacuum melting specialists with documented traceability while marginalizing merchant feedstock suppliers.
Pricing Analysis
Margin tightening in sonar-grade Terfenol-D reflects dysprosium and terbium price volatility from Chinese export quota fluctuations. Three-tier pricing structure across ITAR-registered defense tier, AS9100D aerospace tier, and industrial commercial tier differentiates by certification burden and traceability documentation. Cost compression accelerates in telecommunications thin-film segments as Lumentum and Coherent volume commitments extract scale discounts. Industrial automation buyers exhibit highest price sensitivity; defense procurement shows lowest, prioritizing supply security over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from Japanese METI stockpiling mandates and German defense procurement protocols compel alloy assemblers to qualify Australian and US refined feedstock alongside traditional Chinese supply. Rare earth separation concentrates in Gansu and Inner Mongolia, with vacuum induction melting clustered in Germany, Japan, and Ohio. Raw material supply draws from dysprosium, terbium, and high-purity iron inputs. Single-source vulnerability in heavy rare earth refining exposes downstream processors to quota disruption. Distribution runs through qualified actuator OEMs and defense prime contractors with ITAR-controlled logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetostrictive supply chains are consolidating around captive vacuum melting capacity as German and Japanese players race to secure upstream alloy supply against export volatility. This vertical-integration imperative stems from METI stockpiling mandates and REACH substitution pressures that reward in-house purification control.
For Market Incumbents: Deepen atmosphere control expertise in vacuum induction melting to defend AS9100D and ITAR-registered positions against emerging thin-film sputtering specialists. Acquire Australian or US rare earth refining partnerships to satisfy origin verification requirements from Japanese defense procurement. Prioritize workforce development programs addressing vacuum metallurgy talent scarcity before capacity expansion timelines stall. For New Entrants and Emerging Players: Capture telecommunications micro-actuator white space through 8-inch wafer-scale Terfenol-D deposition partnerships with Coherent or Lumentum qualification programs. Target Galfenol-based industrial vibration sensors in Ohio and Pennsylvania manufacturing facilities where mechanical durability specifications lower rare earth dependency barriers. Pursue joint development agreements with Tier 2 automotive suppliers seeking fuel injection actuator alternatives to piezoelectric ceramics. For Investors and Strategic Acquirers: The window for entry favors vacuum metallurgy specialists with documented terbium homogeneity protocols and existing defense prime contractor relationships. Long-term viability hinges on rare earth processing capacity in jurisdictions outside Chinese export control. Watch METI rare earth stockpile release schedules as inflection indicator for feedstock price pressure and Japanese actuator assembler sourcing diversification urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Vacuum Melting Acquisition | German sensor houses secure terbium homogeneity control against REACH substitution pressures. |
| Thin-Film Sputtering Capacity Expansion | Telecommunications infrastructure upgrades at NTT and Deutsche Telekom pull wafer-scale deposition investment. |
| Rare Earth Refining Partnership | Australian and US feedstock diversification satisfies Japanese METI origin verification mandates. |
| AS9100D Certification Investment | Aerospace telemetry miniaturization programs at Boeing and Airbus compress qualified supplier lists. |
| Energy Harvesting Configuration Development | Ohio and Pennsylvania industrial facilities deploy Galfenol vibration scavengers for auxiliary power generation. |
Research Methodology
Trade statistics from customs databases, SEC filings from vacuum metallurgy specialists, and ECHA REACH registration records formed the secondary backbone for supply chain mapping and regulatory threshold identification. Primary interviews with vacuum induction melting plant managers, defense procurement officers at German and Japanese primes, telecommunications actuator specification engineers, and rare earth trading desk analysts combined with secondary validation. Bottom-up and top-down triangulation cross-checked alloy production volumes against end-use demand signals from sonar modernization programs and automotive fuel injection deployments.
Bottom-up modeling aggregated discrete actuator demand across naval defense, aerospace telemetry, telecommunications switching, and industrial automation verticals. Segmentation dimensions included alloy chemistry tier, fabrication scale, integration depth, and regional regulatory cluster. CAGRs derived from weighted average growth contributions across these segments. Forecast inputs incorporated EPA rare earth processing emission standard timelines and METI stockpiling mandate compliance schedules.
The model holds under stable Chinese export quota enforcement and sustained defense procurement cycles; deviation in rare earth trade policy or telecommunications infrastructure capital expenditure would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
Carbonyl Iron Powder Market
Magnetic Materials
Sintered Magnet Market
Magnetic Materials
Magnet Wire Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
Cobalt Oxide Market
Magnetic Materials
Neodymium-Iron-Boron Magnet Market
Magnetic Materials
Global Electrical Steel Sheet Market
Magnetic Materials
Rare Earth Magnet Market
Magnetic Materials
North America Samarium Cobalt Magnets Market
Magnetic Materials
Copper Magnet Wire Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
Ferroboron Market
Magnetic Materials
Japan Neodymium Iron Boron Magnet Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Reduced Iron Powder Market