
 Global Neodymium Magnet Market | 2026-2036
Global Neodymium Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neodymium Magnet Market Foresight
The EU Green Deal is expanding compliance requirements across rare-earth supply chains, forcing magnet producers to document carbon intensity from mine to finished component. Shin-Etsu Chemical Co. Ltd. leverages captive rare-earth separation capacity to sustain pricing power in bonded magnet grades. TDK Corporation anchors its position through R&D intensity in thin-film deposition techniques for miniaturized electronics applications. Proterial Ltd. competes by dominating hot-deformed magnet output for traction motor architectures.
Neodymium magnets are Nd-Fe-B alloys engineered through powder metallurgy or rapid solidification, typically achieving maximum energy products of 30-52 MGOe depending on grade and processing route. These magnets convert electrical to mechanical energy with minimal loss, serving as the core torque generator in brushless permanent-magnet motors. Sintered magnets occupy the dominant share of value owing to their superior magnetic performance in wind turbine generators and EV drivetrains, while bonded magnets capture specialized demand in precision electronics where complex geometries outweigh peak flux density requirements. Injection molded magnets represent a faster-growing technology segment as robotics providers demand net-shape components with tight dimensional tolerances.
The EPA enforces hazardous substance reporting under TSCA for rare-earth processing facilities operating on US soil, while REACH governs chemical registration and restriction across European magnet import channels. China's MEE administers emission caps and wastewater standards for Nd-Fe-B sintering operations in Inner Mongolia and Jiangxi provinces. Stakeholders must monitor divergence between EU carbon border adjustment mechanisms and domestic content requirements in North American incentive frameworks when siting downstream magnet fabrication capacity.
Market Dynamics
Automotive electrification mandates are compressing magnet procurement timelines as OEMs lock in multi-year sintered magnet supply agreements to secure Nd-Fe-B volumes for traction motor platforms.
Growth Catalysts
- EU Green Deal carbon border adjustments:Magnet fabricators serving European EV manufacturers must document embedded emissions, creating certified supply premiums for low-carbon sintered grades.
- Wind turbine generator scaling:Offshore wind projects above 15MW capacity require high-coercivity magnet architectures, pulling specialized Nd-Fe-B formulations into nacelle assembly lines.
- Robotics actuator miniaturization:Cobot manufacturers in Shenzhen and Nagoya are specifying thin-walled bonded magnet geometries for joint motor integration.
Market Restraints
- Rare-earth oxide price volatility:Neodymium and dysprosium oxide spot markets swing 40-60% annually, compressing magnet fabricator margins on fixed-price automotive contracts.
- Chinese separation concentration:Over 85% of global rare-earth oxide refining occurs in Jiangxi and Inner Mongolia provinces, exposing downstream magnet producers to single-source supply risk.
- Heavy rare-earth substitution limits:Dysprosium and terbium remain irreplaceable for high-temperature motor applications above 150°C, blocking cost-down pathways.
Strategic Opportunities
- India automotive localization:PLI scheme incentives for EV component manufacturing are attracting magnet alloy powder producers to Gujarat and Tamil Nadu industrial corridors.
- Magnet-to-motor recycling loops:Hydrogen decrepitation recovery processes can reclaim 95% of rare-earth content from end-of-life wind turbine generators.
- Thin-film deposition convergence:Sputtered Nd-Fe-B coatings on silicon substrates are enabling on-chip magnetic MEMS for medical imaging equipment.
Industry Challenges
- Metallurgical talent scarcity:Powder metallurgy specialists with Nd-Fe-B sintering expertise are concentrated in aging workforces across Tianjin and Aichi prefecture facilities.
- REACH registration timelines:European importers face 18-24 month delays for novel magnet alloy compositions under ECHA substance evaluation protocols.
- Hot-deformed process scale-up:Anisotropic nanocrystalline magnet production requires proprietary rapid-solidification equipment with limited second-source availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neodymium Magnet Market |
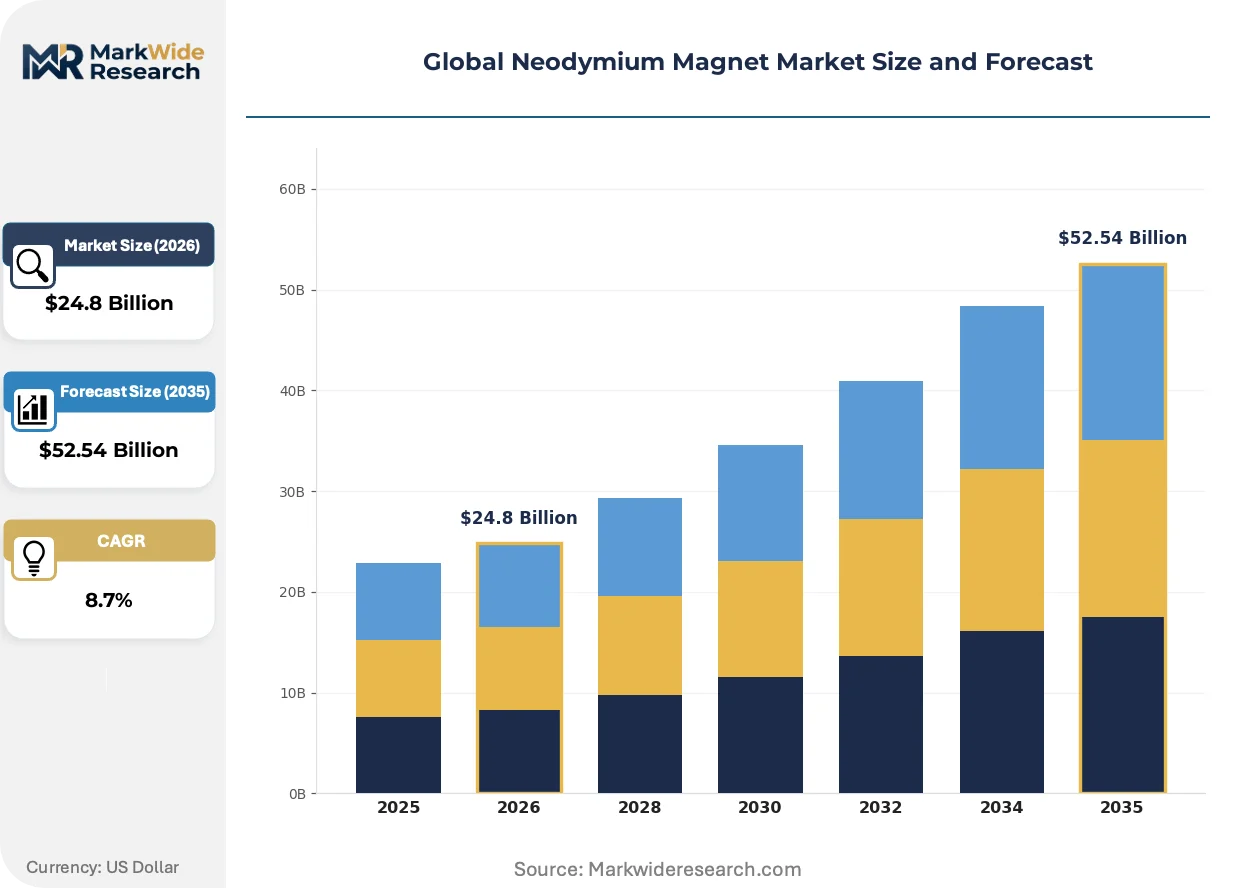
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $52.54 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
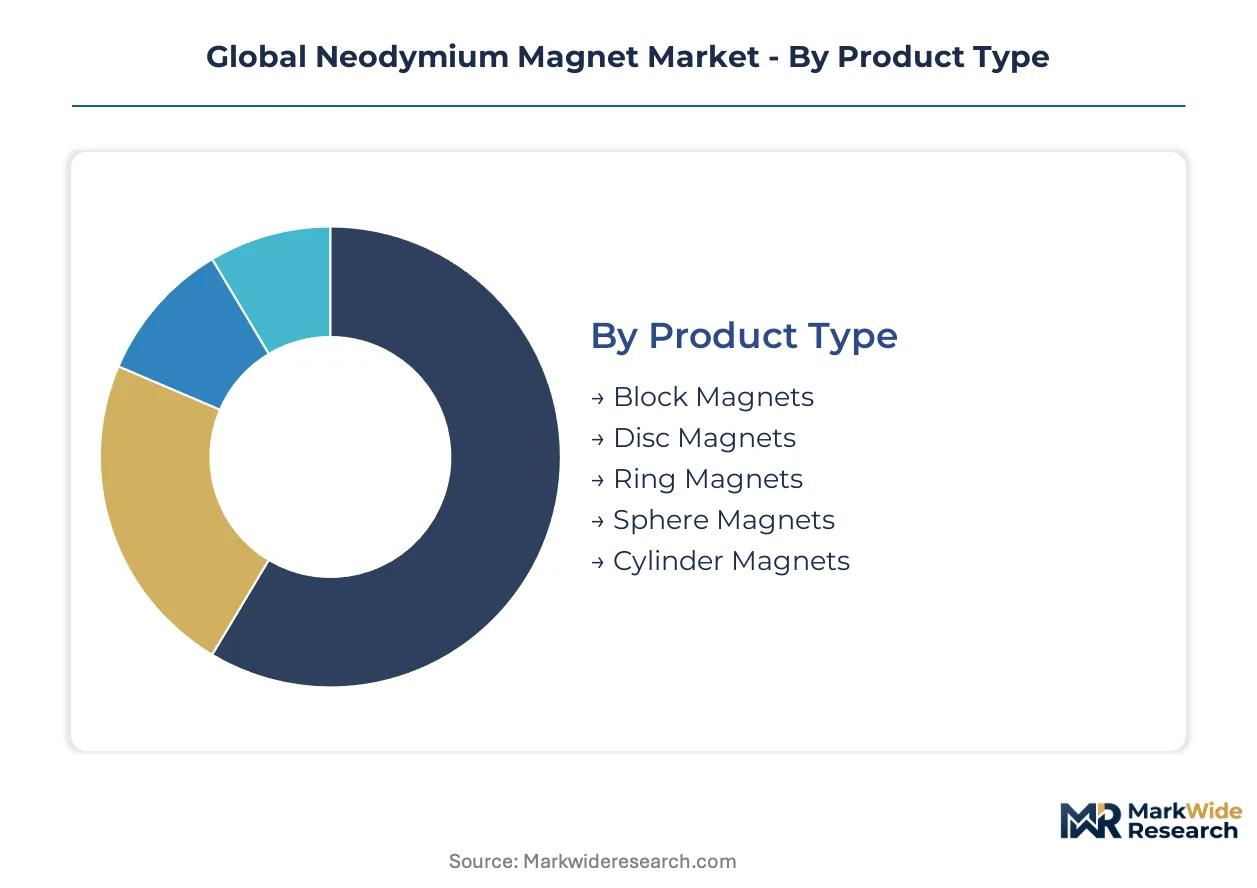
| Segmentation | Product Type: Block Magnets, Disc Magnets, Ring Magnets, Sphere Magnets, Cylinder Magnets Technology: Sintered Magnets, Bonded Magnets, Hot-Deformed Magnets, Injection Molded Magnets, Melt-Spun Magnets Application: Consumer Electronics, Renewable Energy Systems, Industrial Automation, Audio Equipment, Magnetic Resonance Imaging End User: Electronics Manufacturers, Wind Turbine Producers, Robotics Providers, Healthcare Device Makers, Automotive Suppliers |
| Companies Covered | Shin-Etsu Chemical Co. Ltd., TDK Corporation, Proterial Ltd., Hitachi Metals Ltd., JL MAG Rare-Earth Co. Ltd., Vacuumschmelze GmbH & Co. KG, Ningbo Yunsheng Co. Ltd., Earth-Panda Advance Magnetic Material Co. Ltd., Hangzhou Permanent Magnet Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neodymium Magnet Market Shifts & Advancements
Magnet manufacturing is bifurcating between high-volume sintered output for automotive traction and precision bonded geometries for robotics, with processing technology diverging accordingly.
Additive manufacturing of net-shape Nd-Fe-B components is unifying complex magnetic circuit designs with structural integration. Medical device manufacturers in Switzerland and Massachusetts are piloting laser powder bed fusion for patient-specific motor assemblies. This technology is unifying previously separate magnet fabrication and component machining steps, collapsing lead times from twelve weeks to under ten days for prototype volumes.
China's MEE emission caps on rare-earth roasting operations are forcing sintering facilities in Ganzhou and Baotou to install acid-recovery scrubbers or face production halts. Compliance costs are pushing small-scale magnet fabricators toward consolidation with state-owned rare-earth groups. High-energy-product grades for aerospace applications face the steepest cost pass-throughs as environmental levies concentrate in heavy rare-earth processing streams.
Automotive tier-one suppliers are consolidating magnet procurement under direct OEM relationships, bypassing traditional distributor channels. Bosch and Nidec are establishing captive magnet specification teams in Stuttgart and Kyoto to qualify suppliers against internal coercivity and temperature coefficient protocols. This concentration is most visible in German and Japanese EV supply chains, where single-source magnet agreements now span five-to-seven year horizons with price reopener clauses tied to oxide index movements.
Global Neodymium Magnet Market Segmentation
Neodymium magnet procurement decisions hinge on magnetic flux density requirements, thermal operating envelopes, and geometric complexity. Buyers across automotive, renewable energy, and electronics verticals prioritize different performance trade-offs, fragmenting supplier specialization. Understanding these segment boundaries clarifies where pricing power concentrates and where commoditization pressures dominate.
Product Type:
Geometry selection follows torque density targets and assembly integration constraints, with automotive drivetrain engineers specifying ring configurations for rotor mounting while electronics designers favor thin discs for miniaturized actuators.
- Block Magnets:Rectangular prismatic forms with uniform magnetization axes serve linear motor architectures and magnetic separation equipment. Wind turbine nacelle manufacturers in Denmark and Germany specify large-format blocks for direct-drive generator topologies, though supply lead times stretch to sixteen weeks for Nd-Fe-B grades above 48 MGOe.
- Disc Magnets:Axially magnetized cylinders with high diameter-to-thickness ratios optimize surface field strength in sensor applications and speaker assemblies. Shenzhen-based acoustic component suppliers consume precision-ground discs for earbud motor miniaturization, with dimensional tolerances tightening to ±0.02mm for premium audio tiers.
- Ring Magnets:Hollow cylindrical geometries enable rotor-shaft integration in brushless DC motors. Robotics servo manufacturers in Nagoya specify segmented ring arrays for cobot joint actuation.
- Sphere Magnets:Isotropic magnetization in spherical form factors supports educational demonstrations and specialized magnetic bearings. Niche demand concentrates in scientific instrument calibration.
- Cylinder Magnets:Solid rod configurations provide deep magnetic penetration for holding applications and magnetic couplings. Industrial automation suppliers in Michigan specify corrosion-coated cylinders for food processing equipment.
Volume sits with disc geometries; growth tilts toward ring configurations.
Technology:
Processing route selection separates high-performance traction applications from cost-sensitive precision electronics, with sintering dominating where energy product exceeds 45 MGOe and bonding capturing complex net-shape requirements.
- Sintered Magnets:Powder metallurgy compaction followed by liquid-phase sintering achieves maximum energy products of 48-52 MGOe in N52 and N55 grades. Automotive tier-one suppliers in Stuttgart lock in multi-year offtake agreements for high-coercivity sintered volumes, with dysprosium content adjusted for 180°C continuous operation in EV drivetrains.
- Bonded Magnets:Nd-Fe-B powder embedded in polymer matrices enables injection molding and compression forming of complex geometries. Medical device manufacturers in Switzerland specify bonded grades for surgical motor housings where magnetic circuit integration with structural plastic components reduces assembly step count.
- Hot-Deformed Magnets:Rapid solidification and die-upsetting produce anisotropic nanocrystalline microstructures with isotropic precursor flexibility. Traction motor designers in Toyota City evaluate hot-deformed grades for reduced heavy rare-earth dependence.
- Injection Molded Magnets:Thermoplastic bonding with polyamide or PPS carriers permits net-shape fabrication with tight dimensional tolerances. Robotics providers in Shenzhen specify thin-walled injection molded rotors for collaborative robot joint motors.
- Melt-Spun Magnets:Rapid quenching of molten alloy produces amorphous or nanocrystalline ribbon for bonded magnet feedstock. Specialty magnet powder suppliers in Tianjin control melt-spun flake morphology for consistent compression molding performance.
Revenue concentrates in sintered processing; expansion accelerates most quickly in injection molded formats.
Application:
End-use prioritization shifts magnetic specification emphasis, with renewable energy demanding thermal stability and medical imaging requiring field uniformity.
- Consumer Electronics:Miniaturized motors, speakers, and vibration mechanisms in smartphones, laptops, and wearables. Precision magnetization patterns enable haptic feedback systems in Seoul-designed flagship devices.
- Renewable Energy Systems:Direct-drive and geared wind turbine generators above 5MW capacity. Offshore projects in the North Sea specify corrosion-resistant coatings for 25-year service life.
- Industrial Automation:Servo motors, linear actuators, and magnetic couplings for factory equipment. German machine tool builders source high-coercivity grades for spindle motor reliability.
- Audio Equipment:High-fidelity speaker drivers and professional sound reinforcement systems. Japanese audio specialists in Tokyo specify low-distortion magnetization for studio monitor accuracy.
- Magnetic Resonance Imaging:Gradient coil assemblies and shim magnets for diagnostic imaging systems. Siemens Healthineers in Erlangen qualify specialized grades for 3T and 7T scanner field homogeneity.
Procurement volume centers on consumer electronics; steepest expansion trajectory belongs to renewable energy systems.
End User:
Buyer concentration and technical sophistication vary sharply, with automotive suppliers driving standardization while healthcare device makers impose qualification burdens.
- Electronics Manufacturers:Contract assemblers and OEMs in Guangdong and Taoyuan sourcing magnets for motor, sensor, and acoustic integration. Apple and Samsung supply chains enforce conflict-mineral documentation and carbon intensity disclosure.
- Wind Turbine Producers:Vestas, Siemens Gamesa, and Goldwind specifying generator magnet architectures. Direct-drive designs in 15MW offshore platforms consume 2-3 tonnes Nd-Fe-B per nacelle.
- Robotics Providers:Collaborative and industrial robot builders in Aichi and Bavaria. KUKA and FANUC specify compact motor magnet arrays for six-axis arm density.
- Healthcare Device Makers:MRI system integrators and surgical equipment specialists. FDA and EMA device regulations impose biocompatibility and traceability requirements on magnet supply chains.
- Automotive Suppliers:Tier-one motor and drivetrain specialists including Bosch, Nidec, and Valeo. Magnet procurement teams in Stuttgart and Kyoto negotiate oxide-index-linked pricing with five-to-seven year horizons.
Contract value concentrates with automotive suppliers; qualification intensity peaks among healthcare device makers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates rare-earth oxide refining and sintered magnet fabrication, while Germany, Japan, and the United States concentrate downstream demand in automotive and renewable energy applications. India's emerging EV supply chain is attracting alloy powder investment, creating new procurement alternatives outside East Asian manufacturing clusters.
China
Automotive electrification mandates and wind turbine generator scaling drive magnet consumption across domestic OEM supply chains. The Ministry of Ecology and Environment enforces emission caps on roasting operations in Jiangxi and Inner Mongolia provinces. Ganzhou and Baotou industrial corridors host concentrated sintering capacity where acid-recovery scrubber installations are forcing small fabricators toward state-owned group consolidation.
Germany
Direct-drive wind turbine nacelle assembly and EV traction motor platforms anchor magnet procurement volumes for Vestas and automotive tier-one suppliers. REACH registration protocols under ECHA impose 18-24 month delays for novel alloy compositions entering European import channels. Stuttgart-based procurement teams at Bosch and Nidec negotiate oxide-index-linked supply agreements spanning five-to-seven year horizons.
Japan
Robotics actuator miniaturization and medical imaging equipment manufacturing specify precision magnet geometries for FANUC and Siemens Healthineers supply chains. METI industrial standards govern rare-earth material traceability in high-coercivity grades. Nagoya and Aichi prefecture facilities concentrate hot-deformed magnet expertise amid aging powder metallurgy workforces.
United States
Defense aerospace applications and medical device motor assemblies sustain demand for high-energy-product grades above 48 MGOe. The EPA enforces TSCA hazardous substance reporting for rare-earth processing facilities operating domestically. Michigan industrial automation suppliers specify corrosion-coated cylinder magnets for food processing equipment integration.
India
PLI scheme incentives for EV component manufacturing are attracting magnet alloy powder producers to Gujarat and Tamil Nadu corridors. The Bureau of Indian Standards develops domestic certification protocols for Nd-Fe-B grades used in traction motor architectures. Chennai and Ahmedabad industrial zones are emerging as alternative fabrication locations to East Asian supply concentration.
Global Neodymium Magnet Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with captive rare-earth separation capacity. Sintered magnet fabrication concentrates among East Asian and European specialists with multi-decade powder metallurgy expertise, while bonded magnet production fragments across precision electronics component suppliers. Three archetypes dominate: integrated rare-earth-to-magnet producers, specialized sintering fabricators, and precision bonding specialists. Capacity expansion and backward integration into oxide refining represent the primary competitive moves as procurement timelines compress.
Among Japanese chemical conglomerates, Shin-Etsu Chemical Co. Ltd. and TDK Corporation exemplify integrated production models spanning rare-earth separation through finished magnet grades. Proterial Ltd. occupies a position within the specialized sintering tier, representing fabricators with concentrated expertise in high-temperature motor applications. These three companies anchor the premium-grade supply segment where dysprosium-adjusted formulations for EV drivetrains command pricing premiums tied to oxide index movements.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co. Ltd. |
| TDK Corporation |
| Proterial Ltd. |
| Hitachi Metals Ltd. |
| JL MAG Rare-Earth Co. Ltd. |
| Vacuumschmelze GmbH & Co. KG |
| Ningbo Yunsheng Co. Ltd. |
| Earth-Panda Advance Magnetic Material Co. Ltd. |
| Hangzhou Permanent Magnet Group Ltd. |
| Others |
Supply & Pricing Matrix
Powder metallurgy specialists concentrated in Tianjin and Aichi prefecture facilities create labor-cost differentials that widen pricing-tier spreads between premium sintered grades and commodity bonded magnet outputs.
Pricing Analysis
Margin tightening in standard-grade sintered volumes reflects oxide-index-linked contract structures that pass neodymium and dysprosium spot volatility directly to automotive tier-one suppliers. Pricing stratifies across premium, standard, and economy tiers based on heavy rare-earth content and temperature coefficient certification. Cost-down pressure on bonded magnet grades accelerates because robotics providers in Shenzhen specify thin-walled geometries with tight dimensional tolerances. Automotive suppliers demonstrate highest price sensitivity due to multi-year offtake agreements with fixed-base pricing, while medical device makers accept premiums for traceability and biocompatibility documentation.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare-earth oxide refining concentrated in Jiangxi and Inner Mongolia provinces, where over 85% of global separation capacity feeds downstream magnet fabrication. The supply chain draws from neodymium-dysprosium-terbium oxide feedstocks, polymer bonding agents, and rapid-solidification equipment with limited second-source availability. Tariff exposure runs through European import channels governed by REACH registration protocols and emerging carbon border adjustment mechanisms. Distribution runs through direct OEM procurement relationships that bypass traditional distributor channels, with Stuttgart and Kyoto-based specification teams consolidating supplier qualification under captive protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained story where rare-earth oxide refining bottlenecks prop pricing power for integrated producers with captive separation capacity.
For Market Incumbents: Anticipate consolidation pressure from state-owned rare-earth groups in China absorbing small-scale fabricators facing MEE emission compliance costs. Defensive moves require backward integration into oxide refining or capacity expansion in India PLI corridors to diversify geographic exposure. Certification investment in EU carbon intensity documentation represents a critical lever for premium-grade positioning. For New Entrants and Emerging Players: Launch via injection molded magnet specialization targeting collaborative robot joint motor applications in Shenzhen and Nagoya industrial clusters. White-space opportunities concentrate in thin-film deposition for medical imaging MEMS and hydrogen decrepitation recycling loops for end-of-life wind turbine generators. Go-to-market positioning should emphasize net-shape fabrication capabilities that collapse lead times for prototype volumes. For Investors and Strategic Acquirers: Re-rating potential sits with hot-deformed magnet specialists given traction motor architecture shifts toward reduced heavy rare-earth dependence. Long-term viability over a 5-10 year window favors fabricators with proprietary rapid-solidification equipment and established automotive qualification protocols. The signal to watch is ECHA substance evaluation timeline compression for novel alloy compositions entering European channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oxide Refining | Captive rare-earth separation capacity insulates Shin-Etsu and TDK from Jiangxi supply disruptions. |
| India PLI Corridor Capacity Buildout | Gujarat and Tamil Nadu fabrication zones reduce single-source dependence on East Asian clusters. |
| Hydrogen Decrepitation Recycling Scale-Up | 95% rare-earth recovery from wind turbine generators addresses EU Green Deal circularity mandates. |
| Thin-Film Deposition R&D Partnership | Sputtered Nd-Fe-B coatings on silicon substrates enable Siemens Healthineers MRI MEMS applications. |
| Automotive Direct Procurement Consolidation | Bosch and Nidec captive specification teams in Stuttgart bypass traditional distributor markups. |
Research Methodology
Document review covered trade customs data, SEC filings from magnet-intensive OEMs, and MEE emission compliance records, complemented by interviews with powder metallurgy plant managers, automotive tier-one procurement leads, wind turbine nacelle engineers, and robotics actuator designers. Secondary sources included IEA renewable energy deployment databases, ECHA substance evaluation protocols, and vehicle production statistics from IHS Markit. Bottom-up segment sizing and top-down macroeconomic cross-checks ensured triangulation integrity across volume and value estimates.
Historical capacity utilization patterns were cross-referenced against expert panel inputs from rare-earth separation specialists and sintering fabricators. Segmentation modeling spanned product geometry, processing technology, end-use application, and regional production hub characteristics across the projection horizon. CAGRs were derived from demand elasticity coefficients tied to EV drivetrain penetration curves and offshore wind turbine generator scaling trajectories.
The model assumes a particular technology adoption path; alternative pathways for hot-deformed nanocrystalline magnet production would alter the outlook if rapid-solidification equipment achieves broader second-source availability. Forecasts reflect assumptions regarding Chinese environmental enforcement continuity, EU carbon border implementation timelines, and automotive electrification mandate stringency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
High Purity Carbonyl Iron Powder (CIP) Market
Magnetic Materials
High Performance Permanent Magnet Market
Magnetic Materials
North America Magnet Market
Magnetic Materials
Global Permanent Magnet Market
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
Carbonyl Iron Powder Market
Magnetic Materials
Ferrite Magnet Market
Magnetic Materials
North America Ferrite Magnet Market
Magnetic Materials
Global Bonded Magnet Market
Magnetic Materials
Europe Copper Magnetic Wire Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Global Soft Magnetic Materials Market