
 Magnet Market | 2026-2036
Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
Magnet Market Intelligence
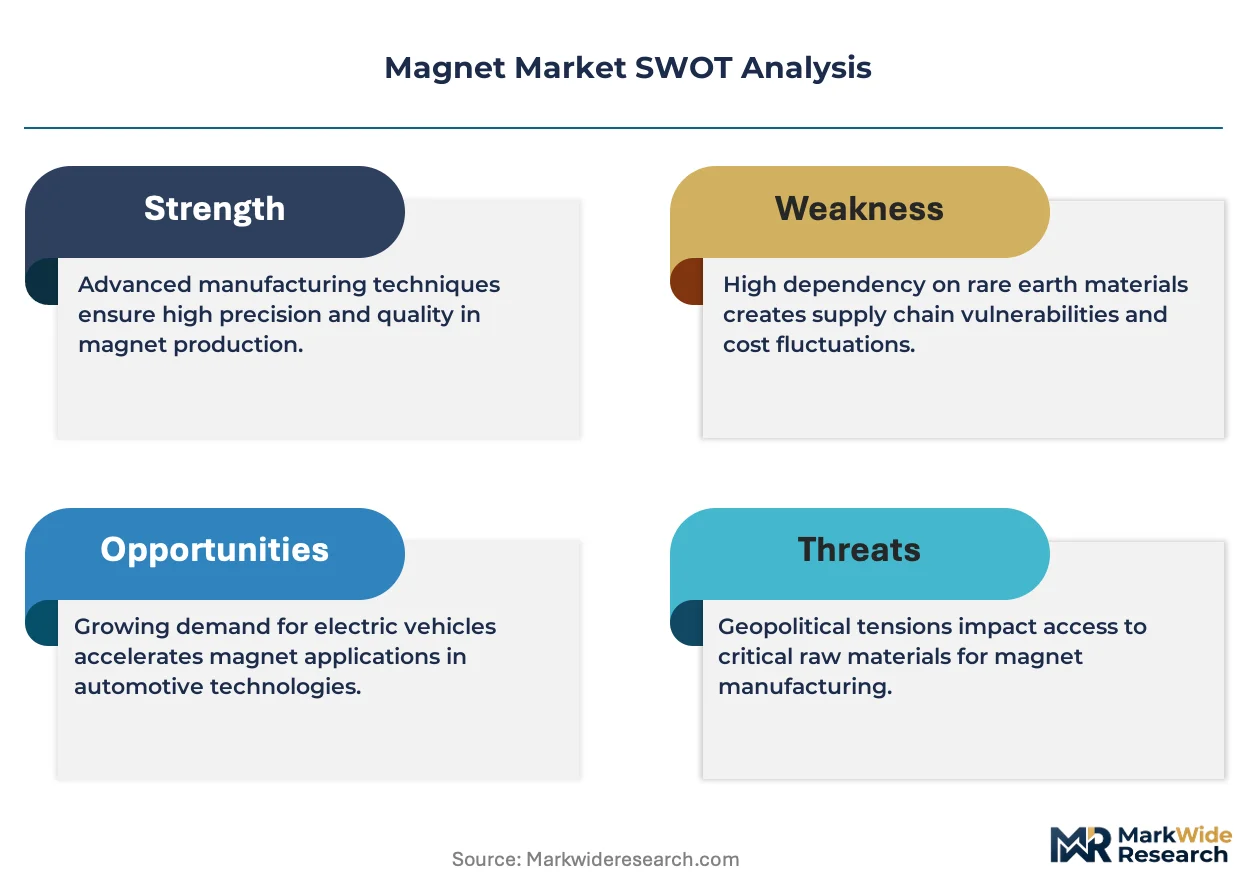
EU REACH compliance is shifting the cost-of-entry calculus for magnet producers serving European automotive and industrial clients. Shin-Etsu Chemical Co., Ltd. leverages integrated rare-earth refining and magnet alloy production to sustain margin control across the value chain. TDK Corporation anchors its position through deep specialization in high-performance ferrite and neodymium formulations for precision electronics. Ningbo Yunsheng Co., Ltd. competes on manufacturing scale, operating some of the largest sintered NdFeB capacities outside Japan.
A magnet is a material or assembly that generates a persistent magnetic field through aligned magnetic domains, with neodymium-iron-boron (NdFeB) alloys delivering energy products exceeding 50 MGOe for torque-dense motor applications. Permanent magnets dominate value capture in the product type dimension, while electromagnets retain structural importance in adjustable-field industrial machinery and MRI systems. The automotive components application is expanding fastest as traction motors electrify, though magnetic resonance imaging sustains premium pricing for ultra-high-field configurations. Block and ring form factors command specialized tooling premiums in aerospace and energy-sector procurement.
The US EPA and NHTSA shape magnet demand through emissions rules that expand electric drivetrain penetration, while China's MIIT enforces GB standards on rare-earth processing efficiency and environmental discharge. Japan's METI coordinates supply security through stockpiling policies and recycling technology mandates for dysprosium and terbium. Stakeholders must monitor regulatory divergence between EU substance restrictions and US mineral security initiatives when siting refining and magnet fabrication assets.
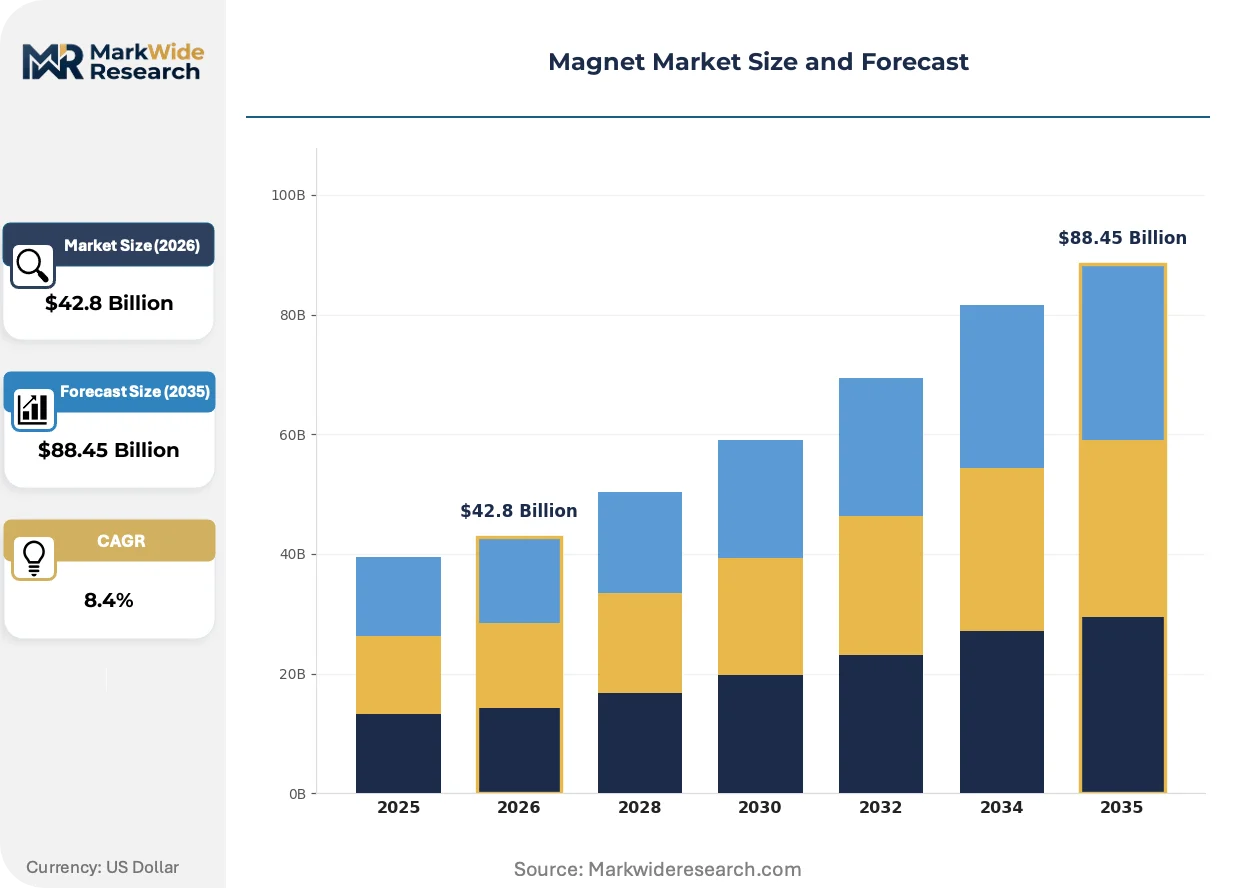
Market Dynamics
Electric vehicle powertrain electrification is concentrating procurement of rare-earth permanent magnets into long-term offtake contracts, while China's dual carbon goals and the EU F-Gas Regulation simultaneously tighten extraction standards and reshape supply geography.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is accelerating magnet demand in compressor motors for heat pumps and refrigeration systems across European HVAC retrofit cycles.
- NdFeB torque density:Traction motor designs for electric vehicles now specify energy products exceeding 50 MGOe, locking in permanent magnet architectures for drivetrain efficiency targets.
- China's rare-earth dominance:Concentrated sintering and fabrication capacity in Ningbo and Baotou clusters enables rapid scale-up for automotive procurement volumes.
Market Restraints
- Dysprosium supply concentration:Heavy rare-earth separation capacity concentrates in southern China, creating single-source dependency for high-temperature magnet grades.
- EU REACH compliance costs:Substance registration and downstream user obligations add fixed cost layers for European automotive and industrial magnet suppliers.
- Ferrite substitution in low-performance motors:Strontium ferrite formulations displace NdFeB in cost-sensitive appliance and fan applications below 5 kW.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives for electric vehicle manufacturing are creating localized magnet assembly demand outside established East Asian supply chains.
- Magnet-to-stator integration:Direct bonding and overmolding technologies enable module-level supplier capture in next-generation axial-flux motor designs.
- Japan's METI recycling mandates:Dysprosium and terbium recovery targets from end-of-life electronics are opening secondary material certification pathways.
Industry Challenges
- Magnet alloy metallurgy expertise:Sintering process control for grain boundary diffusion requires specialized technicians scarce outside Japanese and Chinese engineering bases.
- Multi-jurisdiction certification timelines:Simultaneous NHTSA, ECE, and GB standard compliance for automotive magnets extends qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnet Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $88.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Magnets, Electromagnets, Temporary Magnets, Neodymium Magnets Application: Industrial Machinery, Automotive Components, Consumer Electronics, Magnetic Resonance Imaging Form Factor: Disc, Rod, Block, Ring End User: Aerospace, Healthcare, Construction, Electronics |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., TDK Corporation, Proterial, Ltd., Arnold Magnetic Technologies, Hitachi Metals, Ltd., Ningbo Yunsheng Co., Ltd., Electron Energy Corporation, Adams Magnetic Products, Yantai Dongxing Magnetic Materials Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnet Market Strategic Shifts & Innovations
Grain boundary diffusion engineering and halide-reduced sintering processes are reshaping magnet performance-cost tradeoffs, while regulatory substance restrictions and buyer consolidation are restructuring how value is captured across the supply chain.
Heavy rare-earth reduction through grain boundary diffusion is converging with automotive OEM cost targets. Toyota and Hyundai procurement specifications now accept cerium-substituted NdFeB formulations for traction motors below 150°C operating temperatures. This convergence is compressing dysprosium intensity per kilowatt of motor output by 30-40% in mid-performance drivetrain tiers.
The EU F-Gas Regulation's 2030 phase-down targets are forcing compressor redesigns in commercial refrigeration and heat pump systems. Magnet suppliers serving European HVAC OEMs must now certify fluorinated gas-free manufacturing processes and document rare-earth provenance through ECHA-registered supply chains. German and Italian appliance manufacturers are consolidating supplier panels to three qualified magnet sources per motor platform.
Automotive OEMs are compressing magnet qualification cycles through pre-competitive consortium testing. BMW, Volkswagen, and Stellantis now pool accelerated aging and demagnetization test data through the German Automotive Industry Association, reducing duplicate certification costs. This pooled validation model is most advanced in Stuttgart and Munich engineering centers, where shared test protocols cut per-program qualification spend by half.
Magnet Market Segmentation
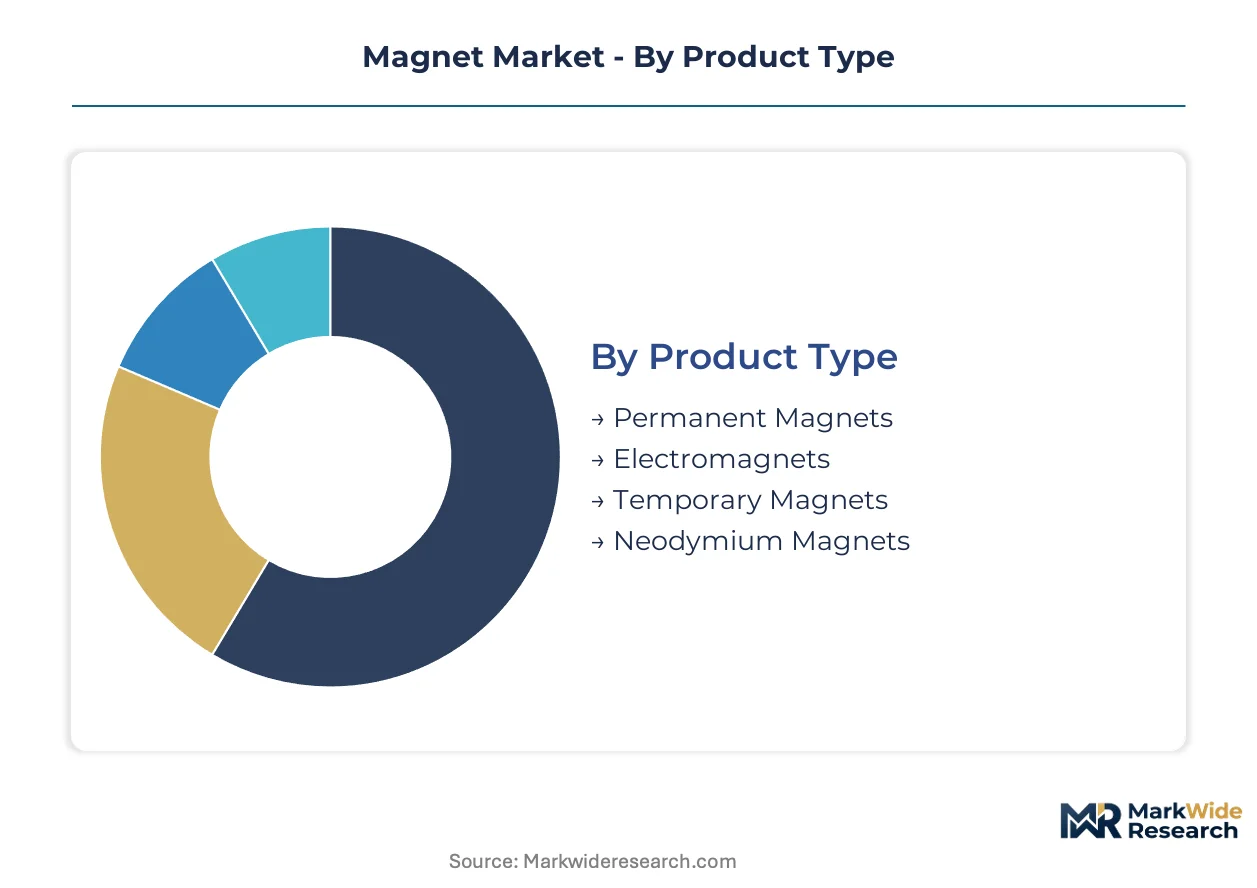
Magnet procurement patterns diverge sharply between standalone component sales and embedded system supply, with qualification requirements and margin structures varying by integration depth. Understanding these segment boundaries enables suppliers to align metallurgy investments with specific customer technical roadmaps.
Product Type:
Permanent magnet architectures dominate embedded motor applications where field stability is essential, while electromagnets retain structural importance in adjustable-field systems requiring real-time flux control.
- Permanent Magnets:NdFeB and ferrite formulations deliver persistent magnetic fields without continuous energy input, locking in traction motor designs for electric vehicle powertrains where efficiency targets exceed 50 MGOe energy products. Automotive OEMs in Germany and Japan now specify grain-boundary-diffused grades to reduce dysprosium intensity by 30-40% in mid-performance drivetrains.
- Electromagnets:Copper-wound coils with soft iron cores generate adjustable magnetic fields through controlled current input, sustaining demand in MRI systems and industrial lifting equipment where field modulation is required. Siemens Healthineers and GE Healthcare procurement specifications prioritize superconducting electromagnet stability for ultra-high-field imaging configurations above 7 Tesla.
- Temporary Magnets:Soft magnetic materials exhibit magnetization only under external field exposure, serving sensor calibration fixtures and educational apparatus where reversible polarity is functionally necessary.
- Neodymium Magnets:Sintered NdFeB alloys represent the highest energy-product commercially available, concentrating in precision robotics and aerospace actuators where torque density constraints are most severe.
Volume placements concentrate in Permanent Magnets; the faster expansion belongs to Neodymium Magnets as traction motor specifications tighten.
Application:
Cost tier segmentation separates capital-intensive industrial installations from high-volume consumer electronics procurement, with automotive qualification cycles imposing the steepest technical barriers.
- Industrial Machinery:Conveyor systems, magnetic separators, and servo motors deploy ferrite and NdFeB assemblies in factory automation environments. German machinery OEMs now mandate ECHA-registered supply chains for rare-earth provenance documentation under EU F-Gas Regulation compliance timelines.
- Automotive Components:Traction motors, power steering systems, and sensor packages specify NdFeB grades with heavy rare-earth stabilization for 150°C+ operating temperatures. China's MIIT enforces GB standards on magnet recycling efficiency that reshape supplier qualification for export-bound production.
- Consumer Electronics:Miniature NdFeB discs and blocks enable smartphone haptic feedback, laptop hinge positioning, and audio driver assemblies where spatial constraints dominate design tradeoffs.
- Magnetic Resonance Imaging:Superconducting electromagnets and permanent magnet configurations for low-field portable systems command premium pricing through FDA and CE MDR certification requirements.
Cost pressure is most severe in Consumer Electronics; margin capture is strongest in Magnetic Resonance Imaging.
Form Factor:
Geographic manufacturing concentration shapes tooling investment recovery, with specialized sintering dies for non-standard geometries concentrating in Chinese and Japanese production clusters.
- Disc:Axially magnetized cylinders serve rotary encoder applications and speaker assemblies where uniform radial field distribution is required. Ningbo fabrication clusters produce disc geometries at scale for appliance motor suppliers serving European HVAC retrofit markets.
- Rod:Elongated cylindrical magnets align magnetic domains along the longitudinal axis, deploying in linear actuator designs for factory automation and medical infusion pumps.
- Block:Rectangular prisms with through-hole or counterbore features enable mechanical fastening in wind turbine generators and magnetic clamping systems. Specialized wire-EDM finishing adds 15-20% cost premium for aerospace surface flatness specifications.
- Ring:Radially or diametrically magnetized annular geometries concentrate flux in motor air gaps, serving direct-drive torque motors and magnetic bearings where rotational symmetry is critical.
Block geometries dominate wind energy procurement; Ring form factors are climbing fastest in axial-flux motor architectures.
End User:
Customer type segmentation separates specification-intensive regulated industries from price-sensitive construction and general electronics markets, with certification burden varying by end-use safety criticality.
- Aerospace:AS9100-certified NdFeB and SmCo magnets deploy in flight control actuators, fuel valve positioning, and sensor packages where demagnetization resistance at altitude temperature extremes is mandatory. Boeing and Airbus supplier qualification extends 24-36 months for new magnet alloy sources.
- Healthcare:ISO 13485-compliant magnet assemblies serve implantable devices, diagnostic imaging, and laboratory automation where biocompatibility and field precision are regulated. FDA 510(k) pathways for MRI magnet subsystems require documented thermal cycling test data.
- Construction:Ferrite block magnets and magnetic lifting assemblies deploy in temporary fastening and debris separation applications where cost minimization dominates supplier selection.
- Electronics:Miniature NdFeB and bonded magnet formulations enable data storage, acoustic transduction, and MEMS positioning in consumer and industrial device manufacturing.
Construction absorbs the highest magnet tonnage; Healthcare sustains the steepest value-per-kilogram realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates over four-fifths of rare-earth magnet fabrication capacity, while automotive electrification and HVAC efficiency mandates are redrawing procurement geography across Germany, Japan, the United States, and India.
China
MIIT enforces GB standards on rare-earth processing efficiency and environmental discharge, tightening extraction protocols in Inner Mongolia and Jiangxi mining districts. Ningbo and Baotou clusters house the world's densest sintered NdFeB production bases, supplying automotive OEMs with heavy rare-earth-stabilized grades for 150°C traction motor operation.
Germany
ECHA-registered supply chains are now mandatory under EU F-Gas Regulation compliance timelines for compressor motor redesigns. Stuttgart and Munich engineering centers host pooled validation consortia where BMW, Volkswagen, and Stellantis share accelerated aging test data, cutting per-program qualification spend.
Japan
METI coordinates dysprosium and terbium stockpiling policies alongside recycling technology mandates for end-of-life electronics. Chubu and Kansai industrial corridors retain specialized grain boundary diffusion expertise scarce outside East Asian engineering bases.
United States
EPA and NHTSA emissions rules expand electric drivetrain penetration, concentrating magnet demand in Michigan and California automotive engineering hubs. The Department of Defense is accelerating domestic rare-earth separation facility permitting to reduce import dependency for defense-grade SmCo magnets.
India
PLI scheme production-linked incentives for electric vehicle manufacturing are creating localized magnet assembly demand outside established East Asian supply chains. Tamil Nadu and Gujarat automotive corridors are attracting module-level suppliers for axial-flux motor integration projects.
Magnet Market Key Industry Players
Japanese producers anchor the premium alloy tier; Chinese fabricators hold scale-driven cost positions. The vendor base splits between integrated rare-earth refiners and specialized magnet alloy manufacturers, with strategic differentiation running through metallurgical process control and qualification speed. Two dominant competitive moves are emerging: backward integration into rare-earth separation capacity and pre-competitive consortium testing to compress automotive certification cycles.
Among Japanese specialists, Shin-Etsu Chemical Co., Ltd. and TDK Corporation exemplify the integrated refining-to-magnet production archetype that sustains margin control across value chain stages. Ningbo Yunsheng Co., Ltd. occupies a position within the scale-driven Chinese fabrication tier, operating sintering capacities that serve high-volume automotive procurement. These three anchors illustrate how geographic concentration in rare-earth mining and processing shapes competitive positioning without requiring identical strategic postures.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| TDK Corporation |
| Proterial, Ltd. |
| Arnold Magnetic Technologies |
| Hitachi Metals, Ltd. |
| Ningbo Yunsheng Co., Ltd. |
| Electron Energy Corporation |
| Adams Magnetic Products |
| Yantai Dongxing Magnetic Materials Inc. |
| Others |
Cost & Logistics Intelligence
Grain boundary diffusion engineering is compressing heavy rare-earth intensity per kilowatt while simultaneously concentrating metallurgical expertise in Ningbo and Baotou production clusters, tightening the link between process innovation and geographic cost advantages. This technical shift rewards integrated refiners with captive dysprosium access while squeezing margin buffers for alloy purchasers locked into spot-heavy rare-earth markets.
Pricing Analysis
Volume placements in standard-grade ferrite and cerium-substituted NdFeB run on thin margins, while grain-boundary-diffused heavy rare-earth grades for 150°C automotive traction motors capture premium realizations. Three-tier pricing structure across aerospace-certified, automotive-qualified, and industrial-economy grades separates AS9100-certified SmCo assemblies from ECHA-registered NdFeB and unregistered ferrite blocks. Pricing pressure stems from Toyota and Hyundai procurement specifications now accepting cerium-substituted formulations for mid-performance drivetrains. Consumer electronics miniature disc magnets exhibit the steepest price sensitivity; MRI superconducting electromagnets show the least.
Supply Chain Analysis
Dual-sourcing requirements from BMW, Volkswagen, and Stellantis now mandate qualified magnet suppliers per motor platform, forcing HVAC and automotive OEMs to maintain redundant ECHA-registered supply chains. Raw material extraction concentrates in China's Inner Mongolia and Jiangxi mining districts, with heavy rare-earth separation capacity tethered to southern Chinese processing infrastructure. Neodymium, praseodymium, and dysprosium draw from concentrated geological deposits and politically exposed refining corridors. Single-source vulnerability in heavy rare-earth separation creates chokepoint exposure for high-temperature magnet grades. Distribution runs through Tier 1 motor assembly plants in Germany, Japan, and Michigan automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnet market consolidation is accelerating as EU REACH compliance costs and automotive qualification timelines force sub-scale alloy producers toward exit or acquisition. Dysprosium supply concentration and pooled OEM validation consortia are raising barriers that weaker metallurgical players cannot cross.
For Market Incumbents: Deepen backward integration into rare-earth separation capacity or captive heavy rare-earth offtake agreements to defend margin control against spot price volatility in southern Chinese processing corridors. Expand grain boundary diffusion engineering capabilities in Chubu and Kansai technical centers to maintain differentiation from scale-driven Chinese fabricators. Prioritize AS9100 and ISO 13485 certification maintenance for aerospace and healthcare revenue stability. For New Entrants and Emerging Players: Halide-reduced sintering process expertise offers entry leverage into European HVAC compressor motor redesigns driven by EU F-Gas Regulation phase-down timelines. India's Tamil Nadu and Gujarat automotive corridors present the most penetrable white-space for module-level axial-flux magnet-to-stator integration projects. Pursue direct bonding and overmolding technology partnerships with PLI-scheme-qualified electric vehicle assemblers to bypass established NdFeB sintering scale disadvantages. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated Japanese chemical conglomerates and Chinese state-affiliated rare-earth groups seeking metallurgical talent outside their home engineering bases. Target acquisition archetypes are mid-cap specialists with grain boundary diffusion process control and existing ECHA-registered supply chains. Watch Japan's METI recycling mandate enforcement intensity as the signal for secondary dysprosium and terbium material viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Separation | Captive dysprosium access insulates margin from Chinese heavy rare-earth spot volatility. |
| Grain Boundary Diffusion Process Scale-Up | Toyota procurement specifications reward cerium-substituted NdFeB with 30-40% heavy rare-earth reduction. |
| ECHA-Registered Supply Chain Certification | Mandatory documentation for EU F-Gas Regulation compliance in German and Italian HVAC compressor motors. |
| Magnet-to-Stator Integration Module Development | Axial-flux motor designs enable supplier capture beyond standalone component sales. |
| End-of-Life Magnet Recycling Technology Deployment | METI mandates create secondary material certification pathways for dysprosium and terbium recovery. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with rare-earth refinery operations managers, automotive Tier 1 procurement directors, HVAC OEM sourcing leads, and magnet alloy R&D directors. Bottom-up and top-down triangulation validated volume estimates against MIIT production statistics, ECHA registration databases, and Japan Rare Earths Association stockpile disclosures.
Segmentation granularity modeled permanent versus electromagnet architectures, NdFeB versus ferrite versus SmCo alloy grades, automotive traction motor versus HVAC compressor versus MRI imaging applications, and block versus ring versus disc form factors across the projection horizon. CAGRs derived from weighted average of historical production growth, OEM electrification platform announcements, and regulatory mandate phase-in schedules. Forecast inputs included electric vehicle powertrain penetration curves and heat pump installation retrofit cycles.
Several conditions sit outside the modeled scope, including unannounced national rare-earth export restrictions, breakthrough non-rare-earth magnet formulations, and abrupt automotive OEM platform cancellations. Forecasts reflect documented assumptions about sustained Chinese processing dominance and stable heavy rare-earth geological availability. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement intensity or Japan's METI recycling mandate implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Neodymium-Iron-Boron Magnet Market
Magnetic Materials
Reduced Iron Powder Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
Global Electrical Steel Sheet Market
Magnetic Materials
Flux Field Directional Material Market
Magnetic Materials
Europe Ferrite Magnet Market
Magnetic Materials
Magnet Buffer Market
Magnetic Materials
North America Magnet Wire Market
Magnetic Materials
Global Non-Oriented Electrical Steel Market
Magnetic Materials
North America Ferrite Magnet Market
Magnetic Materials
Magnetic Material Magnetization and Testing Equipment Market
Magnetic Materials
Japan Neodymium Iron Boron Magnet Market
Magnetic Materials
Magnet Wire Market
Magnetic Materials
Europe Copper Magnetic Wire Market