
 Global Boron Market | 2026-2036
Global Boron Market Size, Share, and Industry Trends Forecast 2026-2036
Global Boron Market Foresight
Advanced ceramics buyers are redrawing procurement priorities as semiconductor thermal management needs intensify. Rio Tinto leverages its integrated mine-to-refinery footprint in California to sustain long-term supply contracts with aerospace alloy producers. Eti Maden anchors global raw material flows through its dominance of Turkey's Bigadiç and Kestelek deposits. 5E Advanced Materials competes in the high-purity boron segment through its Fort Cady development in the United States.
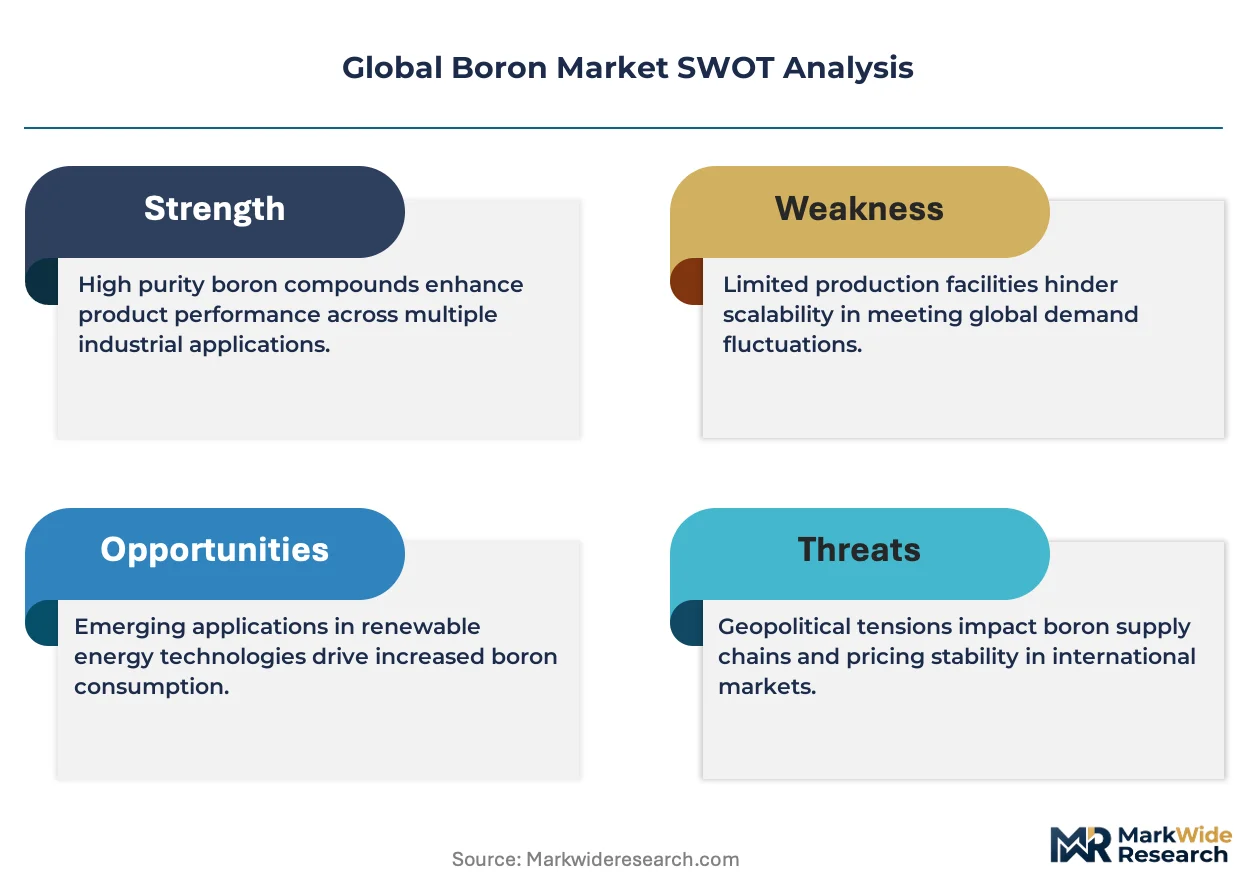
Boron is a metalloid element, atomic number 5, extracted primarily as sodium tetraborate decahydrate from evaporite deposits and processed into derivatives with purity grades ranging from technical to semiconductor-grade. Its primary industrial purpose centers on glass formulation, agricultural micronutrient delivery, and neutron absorption in nuclear shielding applications. Boron carbide and boron nitride command premium positioning within the product type matrix due to their extreme hardness and thermal conductivity profiles in defense and electronics end uses. Glass manufacturing retains the largest volume share among applications, though flame retardants and energy storage segments are expanding fastest as building codes tighten and lithium-boron battery chemistries advance.
The EPA governs boron discharge limits under the Clean Water Act, while REACH mandates registration and hazard communication for boron compounds imported into Europe. China's SAMR enforces GB standards on borax and boric acid purity for domestic industrial consumption, directly shaping export eligibility for non-compliant producers. Turkey's mining ministry regulates royalty structures and export licensing for state-controlled borate extraction. Stakeholders must monitor evolving classification of boron compounds under the EU CLP regulation and corresponding downstream notification obligations.
Market Dynamics
Turkey's state-controlled borate extraction monopoly at Eti Maden concentrates global raw material flows, forcing downstream processors to negotiate long-term offtake agreements or develop alternative deposit access in the United States and South America.
Growth Catalysts
- Semiconductor thermal management:Advanced ceramics manufacturers are expanding boron nitride procurement for heat-dissipation substrates in high-performance computing chips.
- REACH compliance deadlines:ECHA registration requirements for boron compounds are accelerating purity upgrades across European supply chains, filtering out substandard producers.
- Lithium-boron battery chemistry:Solid-state electrolyte research is pulling high-purity boron into next-generation energy storage formulations.
Market Restraints
- Reserve concentration risk:Over 70% of economically viable borate deposits sit within Turkey's Bigadiç and Kestelek basins, creating single-source vulnerability.
- Energy input volatility:Boron carbide synthesis requires sustained high-temperature electric arc furnaces, exposing margins to power cost swings.
- Flame retardant substitution:Phosphorus-based intumescent coatings are capturing share in polymer applications where borates previously dominated.
Strategic Opportunities
- United States domestic sourcing:California's Fort Cady and Argentina's Salta-Jujuy provinces offer undeveloped colemanite reserves for supply chain diversification.
- Nuclear shielding expansion:Small modular reactor deployments are renewing demand for boron-10 isotope neutron absorption materials.
- EU Green Deal industrial policy:Carbon border adjustment mechanisms favor low-carbon boron refining routes, rewarding process innovators.
Industry Challenges
- Semiconductor-grade purification:Achieving 99.9999% purity for electronics applications demands capital-intensive ion exchange and crystallization infrastructure.
- REACH downstream notification:CLP classification updates for reproductive toxicity are triggering complex supply chain communication obligations across EU importers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Boron Market |
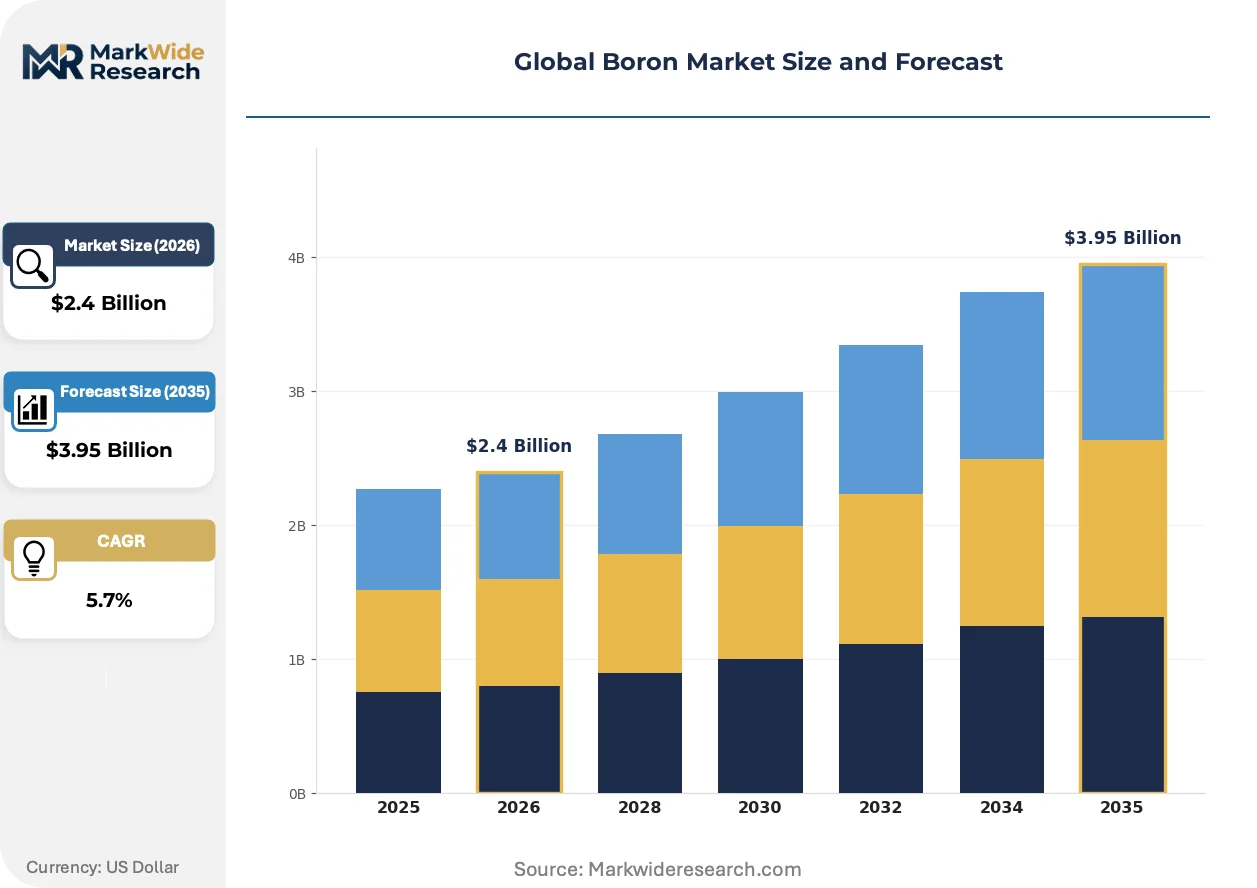
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.95 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boric Acid, Borax, Boron Carbide, Boron Nitride, Boron Oxide, Others Application: Glass Manufacturing, Agriculture, Detergents, Ceramics, Flame Retardants, Fertilizers End User Industry: Electronic Components, Construction Materials, Agriculture Equipment, Chemical Manufacturing, Energy Storage, Aerospace Form: Powder, Granules, Liquid, Crystals, Pellets |
| Companies Covered | Eti Maden, Rio Tinto, 3M, SB Boron Corporation, Quiborax, Searles Valley Minerals, Minera Santa Rita, Inkabor, 5E Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Boron Market Shifts & Advancements
Process intensification and purity segmentation are redrawing competitive boundaries across the boron value chain. Suppliers are racing to qualify for semiconductor and nuclear grades while defending volume positions in glass and agriculture.
High-purity boron carbide synthesis via plasma-enhanced chemical vapor deposition is displacing traditional electric arc furnace methods for defense armor and abrasive applications. Aerospace contractors in the United States are qualifying these materials for next-generation ballistic protection systems. The shift is compressing margins for conventional powder producers unable to fund plasma reactor capex.
ECHA's 2023 update to REACH guidance on boron compound hazard classification is forcing reformulation across European detergent and cosmetic applications. Downstream formulators are substituting sodium perborate alternatives or investing in exposure mitigation studies. The glass and ceramics sectors face lower compliance burdens, redirecting trade flows toward industrial rather than consumer chemical grades.
Integrated mine-to-chemical processors are capturing long-term contracts by guaranteeing certified purity tiers rather than spot-trading commodity borax. Nuclear utilities and semiconductor foundries are consolidating supplier panels to three qualified sources per geography. This concentration is most visible in Japan, where METI's critical materials stockpiling policy incentivizes dual-sourcing from Turkey and domestic refined inventories.
Global Boron Market Segmentation
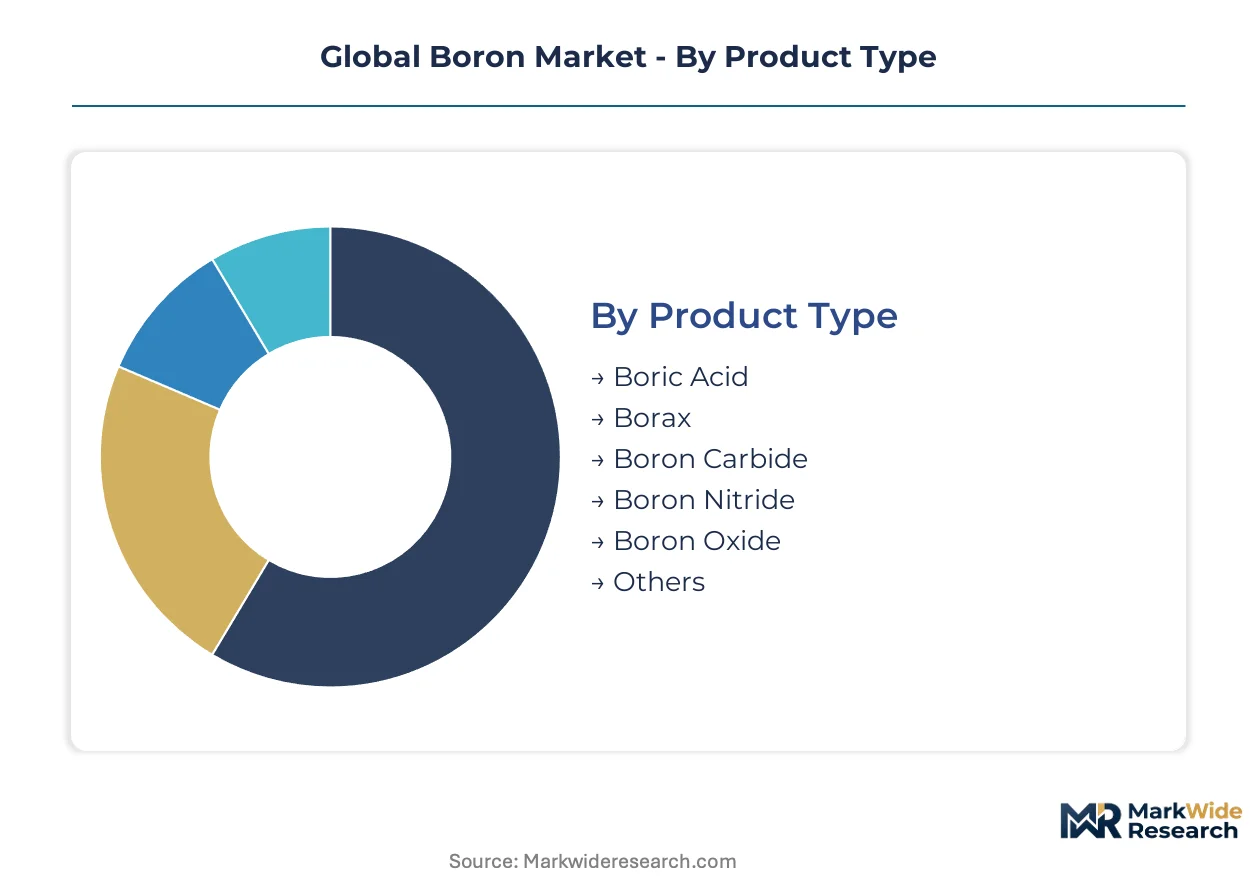
Boron derivatives span radically different purity grades and price tiers, from commodity agricultural inputs to semiconductor-grade ceramics. Understanding where substitution pressures and supply bottlenecks concentrate within each dimension shapes procurement strategy and investment timing.
Product Type:
Boric acid and borax face intensifying substitution from phosphorus-based alternatives in consumer applications, while advanced ceramic grades remain insulated by performance requirements.
- Boric Acid:Technical-grade crystals serve glass fluxing and agricultural micronutrient delivery. Demand concentrates in Turkey's domestic processing clusters and California's Central Valley fertilizer distribution networks, constrained by REACH-driven reformulation in European consumer products.
- Borax:Sodium tetraborate decahydrate extracted from evaporite deposits supplies detergent builders and metallurgical fluxes. Procurement is shifting toward long-term offtake contracts with Eti Maden as spot market liquidity thins.
- Boron Carbide:Extreme hardness ceramic for ballistic armor and abrasive applications.
- Boron Nitride:Hexagonal crystal structure delivers thermal conductivity for semiconductor heat-dissipation substrates.
- Boron Oxide:Glass formulation additive and borosilicate precursor.
- Others:Specialty borates including perborates and organoboron compounds.
Borax retains volume leadership; boron nitride holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity volume applications from premium specialty segments where technical specifications command 10-20x price multiples.
- Glass Manufacturing:Borosilicate and fiberglass formulations consume the largest raw material volumes. Float glass producers in Turkey, China, and the United States anchor demand, though energy cost volatility is compressing margins at energy-intensive melting operations.
- Agriculture:Soil micronutrient correction and boron-deficient crop management. Latin American soybean cultivation and Southeast Asian palm oil plantations are pulling granular borate formulations.
- Detergents:Sodium perborate bleaching agents face ECHA classification pressure.
- Ceramics:Advanced structural components for aerospace thermal protection.
- Flame Retardants:Zinc borate and boric acid formulations for polymer fire safety.
- Fertilizers:Compound NPK blends with trace boron enrichment.
Glass manufacturing dominates absolute tonnage; ceramics and flame retardants are climbing the fastest.
End User Industry:
Customer type fragmentation splits the market between price-sensitive commodity buyers and specification-locked critical materials purchasers with dual-sourcing mandates.
- Electronic Components:Semiconductor foundries and thermal interface material suppliers require 99.9999% purity boron nitride. Japan's METI stockpiling policy and TSMC's Arizona expansion are concentrating procurement from qualified Turkish and domestic US sources.
- Construction Materials:Fiberglass insulation and structural composites. North American housing starts and China's property sector stimulus cycles drive volume volatility.
- Agriculture Equipment:Fertilizer spreader compatibility and precision application systems.
- Chemical Manufacturing:Intermediate inputs for pharmaceutical and agrochemical synthesis.
- Energy Storage:Solid-state lithium-boron electrolyte research programs.
- Aerospace:Thermal protection systems and neutron shielding for propulsion.
Construction materials absorb the highest volumes; energy storage and electronic components are expanding most quickly.
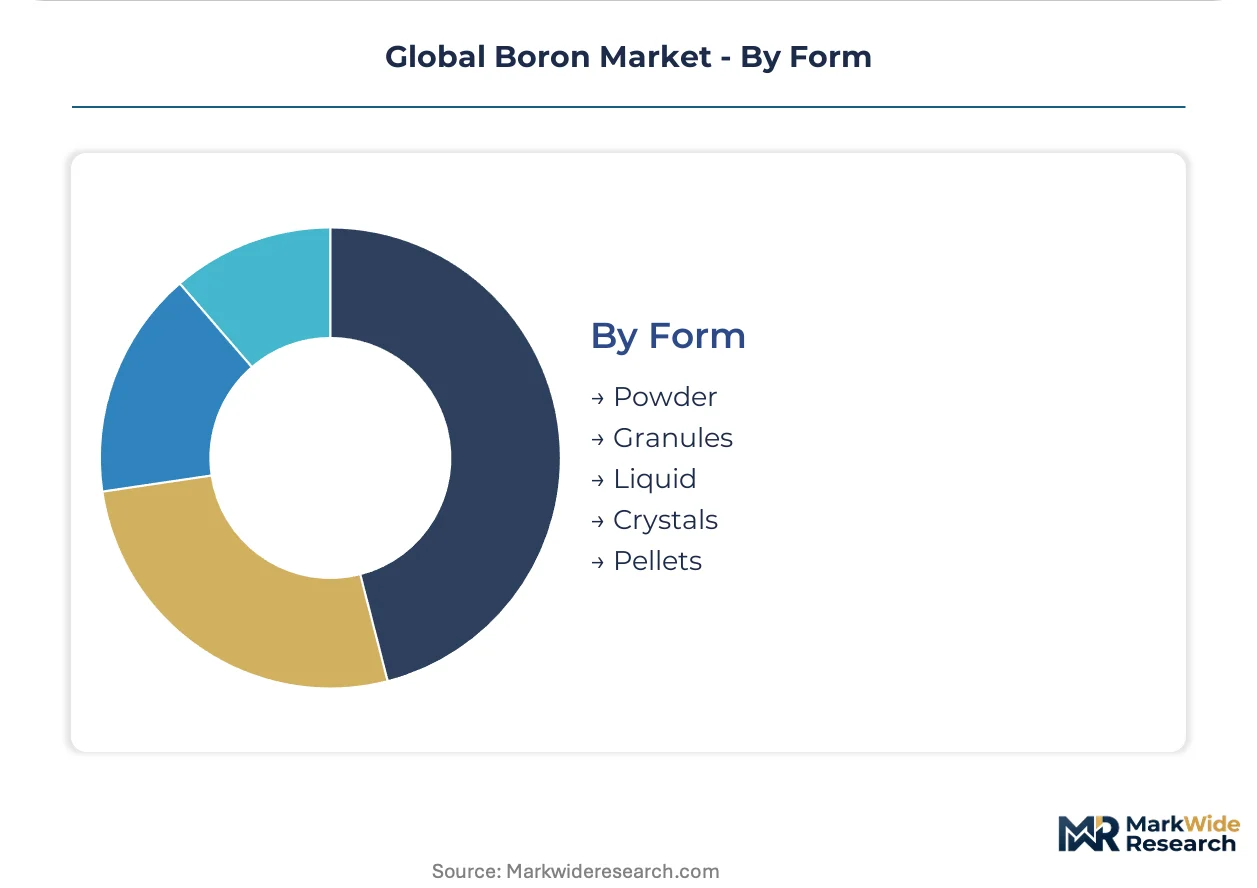
Form:
Supply chain configuration favors powder and granule formats for bulk industrial handling, while crystal and pellet forms capture premium positioning in precision dosing applications.
- Powder:Fine-ground borax and boric acid for glass batch mixing and agricultural spray solutions. Dust exposure regulations under OSHA and China's MEE are increasing packaging and handling costs.
- Granules:Controlled-release fertilizer formulations and metallurgical fluxes. Brazilian soybean belt and Australian wheat belt distributors prefer this format for aerial application compatibility.
- Liquid:Soluble borate solutions for detergent and wood treatment.
- Crystals:High-purity semiconductor-grade boron carbide and nitride.
- Pellets:Compressed borax for slow-dissolution industrial processes.
Powder retains volume leadership; crystals hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bandırma port complex on Turkey's Sea of Marmara underwrites the country's dominance in global borate logistics, handling bulk exports from the Bigadiç and Kestelek mining basins to processors across three continents.
Turkey
State-controlled extraction at Eti Maden supplies over 70% of global refined borate flows. The Turkish mining ministry regulates royalty structures and export licensing, constraining spot market liquidity. Industrial clusters around Bandırma and Eskişehir concentrate downstream boric acid and borax refining operations for European and Asian glass manufacturers.
United States
Semiconductor foundries in Arizona and Texas are pulling high-purity boron nitride for thermal management substrates. The EPA governs boron discharge limits under the Clean Water Act, tightening effluent standards for California refiners. The Fort Cady colemanite deposit in San Bernardino County anchors domestic sourcing initiatives by integrated chemical processors.
China
Float glass producers in Shandong and Hebei provinces consume massive borax volumes for borosilicate formulations. SAMR enforces GB standards on borax and boric acid purity, filtering export eligibility for non-compliant producers. The Yangtze River Delta hosts specialty borate refineries serving domestic electronics and ceramics supply chains.
Germany
Advanced ceramics manufacturers in Bavaria and North Rhine-Westphalia procure boron carbide for aerospace thermal protection systems. ECHA's REACH registration requirements and CLP classification updates for reproductive toxicity are accelerating purity upgrades across European supply chains. The Rhine-Ruhr industrial corridor concentrates detergent and glass chemical processing demand.
Japan
TSMC's Kumamoto expansion and domestic semiconductor foundries are consolidating qualified boron nitride supplier panels. METI's critical materials stockpiling policy incentivizes dual-sourcing from Turkish and domestic refined inventories. The Kanto region around Tokyo hosts precision ceramics fabricators serving neutron absorption and thermal interface material applications.
Global Boron Market Competitive Landscape
Concentration sits with state-affiliated mining enterprises and integrated mine-to-chemical processors. Eti Maden's control of Turkish reserves creates a supply-side bottleneck that downstream refiners must navigate through long-term offtake negotiations or alternative deposit development. Three archetypes dominate: state mining monopolies with captive reserves, integrated chemical processors with refining expertise, and specialty materials developers targeting semiconductor and nuclear grades. Competitive moves center on backward integration into undeveloped deposits and purity-tier certification for critical materials qualification.
Among state-controlled mining enterprises, Eti Maden exemplifies the reserve-dominant archetype. Rio Tinto occupies a position within the integrated processor tier, leveraging California-based mine-to-refinery infrastructure. 5E Advanced Materials represents the specialty developer segment, targeting high-purity boron production from domestic United States deposits for electronics and energy storage applications.
| Leading Market Players |
|---|
| Eti Maden |
| Rio Tinto |
| 3M |
| SB Boron Corporation |
| Quiborax |
| Searles Valley Minerals |
| Minera Santa Rita |
| Inkabor |
| 5E Advanced Materials |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day inventory cycles at European glass manufacturers concentrate procurement leverage around Eti Maden's quarterly contract windows, amplifying Turkey's pricing power over technical-grade borax while semiconductor buyers absorb premiums for certified high-purity streams.
Pricing Analysis
Three-tier pricing structure across semiconductor-grade, technical-grade, and agricultural-grade levels separates specification-locked buyers from commodity purchasers. Price differentiation hinges on ion-exchange purification certification and volume-scale commitments in long-term offtake agreements. Pricing pressure stems from phosphorus-based flame retardant substitution in polymer applications, compressing margins for standard boric acid. Agricultural distributors exhibit highest price sensitivity, while nuclear utilities and semiconductor foundries accept steep premiums for dual-sourced qualified supply.
Supply Chain Analysis
Turkey and the United States anchor global borate extraction, with Turkey's Bigadiç basin feeding Eti Maden's integrated refining complexes and California's Fort Cady deposit supporting domestic sourcing initiatives. Downstream processing draws from colemanite ore, sulfuric acid, and high-temperature electric arc furnace capacity as critical inputs. Single-source vulnerability concentrates in Turkey's state-controlled reserve monopoly, exposing processors to export licensing disruptions. Distribution runs through bulk maritime terminals at Bandırma, with containerized specialty grades feeding precision ceramics fabricators in Japan and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored in semiconductor capital expenditure cycles, as thermal management substrate demand rebounds from foundry buildouts in Arizona and Kumamoto.
For Market Incumbents: Fortify long-term offtake positions with Eti Maden through volume-commitment structures that preempt spot market exposure. Invest in ion-exchange crystallization infrastructure to capture semiconductor-grade certification premiums before REACH purity mandates harden. Defend against Argentine colemanite developers by securing exclusive logistics slots at Bandırma. For New Entrants and Emerging Players: Anchor in the United States domestic sourcing gap, where Fort Cady and Salta-Jujuy deposits offer alternative reserve access outside Turkish state control. Target lithium-boron solid-state electrolyte research programs as the most penetrable white-space segment. Pursue qualification partnerships with Arizona semiconductor foundries seeking dual-source redundancy. For Investors and Strategic Acquirers: Long-term, this sits as a critical materials scarcity play because reserve concentration outside Turkey remains underdeveloped and purity-tier certification creates durable moats. Acquisition targets should display integrated mine-to-chemical processing capability or established semiconductor-grade qualification. Watch for ECHA CLP classification enforcement intensity as the signal for downstream reformulation demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Undeveloped Reserves | Secures colemanite supply outside Turkey's state monopoly, reducing single-source vulnerability. |
| Semiconductor-Grade Certification Investment | Unlocks 10-20x pricing multiples from TSMC and Intel thermal management substrate contracts. |
| Long-term Supply Agreement with Nuclear Utilities | Captures boron-10 isotope demand from small modular reactor deployments. |
| Green Manufacturing Transition | Qualifies for EU carbon border adjustment preferences in boron carbide synthesis. |
| Joint Venture with Advanced Ceramics Developers | Accelerates plasma-enhanced CVD qualification for defense armor applications. |
Research Methodology
A standing panel of boron refinery operations managers, glass manufacturer procurement directors, semiconductor foundry materials engineers, and agricultural distributor category buyers provided ongoing calibration against trade flow data, ECHA registration filings, Turkish mining ministry export statistics, and SEC chemical processor disclosures. Bottom-up volume estimates from end-use consumption patterns were triangulated with top-down reserve capacity assessments.
Consistency checks validated projections against customs import records, industrial glass production indices, and nuclear utility fuel procurement databases across the analysis window. Segmentation modeling incorporated grade tier, end-use industry, regional production hub, and purity certification status as dimensions. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines, with semiconductor thermal management and lithium-boron battery chemistry as primary demand-side inputs.
Underlying assumptions cover sustained REACH enforcement intensity, Turkish export licensing stability, and electric arc furnace energy cost trajectories, with deviation risk concentrated in phosphorus substitution acceleration and small modular reactor deployment delays. Recalibration cycles align with material shifts in ECHA classification updates and semiconductor foundry construction announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Flake Graphite Market
Metals & Minerals
Mineral Screening Market
Metals & Minerals
Silver Mining Market
Metals & Minerals
Silver Salt Market
Metals & Minerals
Dolomite Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
Compacted Graphite Iron Market
Metals & Minerals
Garnet Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
Prefab Iron Market
Metals & Minerals
Steel Powder Market
Metals & Minerals
Hot Briquetted Iron (HBI) Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Gregoryite Market
Metals & Minerals
Global Mining Metals Market