
 Samarium Cobalt Magnets Market | 2026-2036
Samarium Cobalt Magnets Market Size, Share, and Industry Trends Forecast 2026-2036
Samarium Cobalt Magnets Market Intelligence
High-temperature specification grades is rotating toward center stage as defense and aerospace procurement tightens material certification requirements. Arnold Magnetic Technologies leverages in-house sintering capabilities to sustain qualification pipelines for military-grade supply chains. Electron Energy Corporation anchors North American production of precision-machined arc segments for satellite gyroscope assemblies. Hangzhou Permanent Magnet Group Ltd. dominates bulk orders of standard-grade blocks for industrial automation OEMs across East Asia.
Samarium cobalt magnets are rare earth permanent magnets composed of samarium and cobalt with exceptional thermal stability, maintaining magnetic performance at temperatures exceeding 300°C through powder metallurgy sintering processes. These magnets serve critical functions in aerospace actuators, defense guidance systems, and high-performance electric motors where operating environments exceed neodymium tolerance thresholds. The application dimension shows aerospace and defense commanding premium pricing due to material traceability requirements, while automotive traction motors represent the fastest-growing consumption vector as EV thermal management architectures evolve. Product type segmentation reveals custom shapes capturing disproportionate margin pools due to engineering-intensive specification work, though disc and ring configurations sustain volume leadership in sensor and encoder markets.
US Department of Defense DFARS sourcing rules and ITAR compliance frameworks restrict qualified supplier pools for strategic magnet grades, elevating barriers for non-domestic manufacturers. China's MIIT rare earth export license system and GB standards for permanent magnet classification shape international supply availability and quality benchmarking protocols. REACH and RoHS frameworks in Europe constrain cobalt content reporting thresholds for industrial equipment placed on EU markets. Stakeholders must monitor evolving critical minerals stockpile policies across multiple jurisdictions to anticipate procurement priority shifts and qualification timeline extensions.
Market Dynamics
Thermal management requirements in electric propulsion systems are forcing aerospace and automotive engineers toward magnet materials that sustain performance beyond neodymium failure thresholds. DFARS compliance rules and China's rare earth export licensing system have bifurcated qualified supplier pools into domestic-military and international-commercial tracks.
Growth Catalysts
- Defense procurement mandates:US Department of Defense DFARS sourcing rules require domestic provenance for strategic magnet grades used in missile guidance and satellite systems, creating captive demand for qualified North American sintering capacity.
- Dual carbon policy enforcement:China's MIIT rare earth processing regulations tighten environmental compliance for smelting operations, accelerating consolidation among domestic producers and elevating pricing power for certified clean supply.
- Precision motor efficiency standards:Japan's METI mandates for industrial servo applications are displacing ferrite magnets with rare earth alternatives in factory automation equipment.
Market Restraints
- Cobalt price volatility:Raw material input costs fluctuate with battery industry demand cycles, compressing margin predictability for magnet fabricators locked into long-term aerospace supply contracts.
- Supply concentration risk:Rare earth oxide separation capacity concentrates in Chinese processing corridors, exposing non-domestic magnet manufacturers to export license delays and quota fluctuations.
- Neodymium substitution ceiling:High-temperature grades above 300°C operating thresholds remain technically unreachable by NdFeB alternatives, but cost-sensitive applications below 200°C increasingly default to the cheaper rare earth system.
Strategic Opportunities
- Underpenetrated geothermal energy sector:Downhole drilling motors and turbine generators in volcanic zones require magnets that survive 250°C+ environments where neodymium irreversibly demagnetizes.
- EU critical minerals stockpiling:The European Raw Materials Alliance is financing magnet recycling and alternative sourcing initiatives that could qualify new non-Chinese feedstock streams for automotive OEMs.
- Additive manufacturing convergence:Binder jet printing of pre-alloyed SmCo powders is emerging as a route to complex net-shape geometries without diamond grinding waste, attracting prototyping contracts from satellite component suppliers.
Industry Challenges
- Metallurgical talent scarcity:Powder metallurgy sintering expertise for rare earth magnets concentrates among retiring specialists in Japan and the United States, constraining capacity expansion timelines for new production lines.
- ITAR certification latency:Security clearance requirements for military-grade magnet traceability extend qualification cycles to 18-24 months, freezing supplier switches even when technical performance gaps emerge.
- Legacy equipment integration:Retrofitting SmCo magnets into existing ferrite-based motor architectures requires complete stator redesigns, creating engineering friction for industrial automation OEMs with installed base commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Samarium Cobalt Magnets Market |
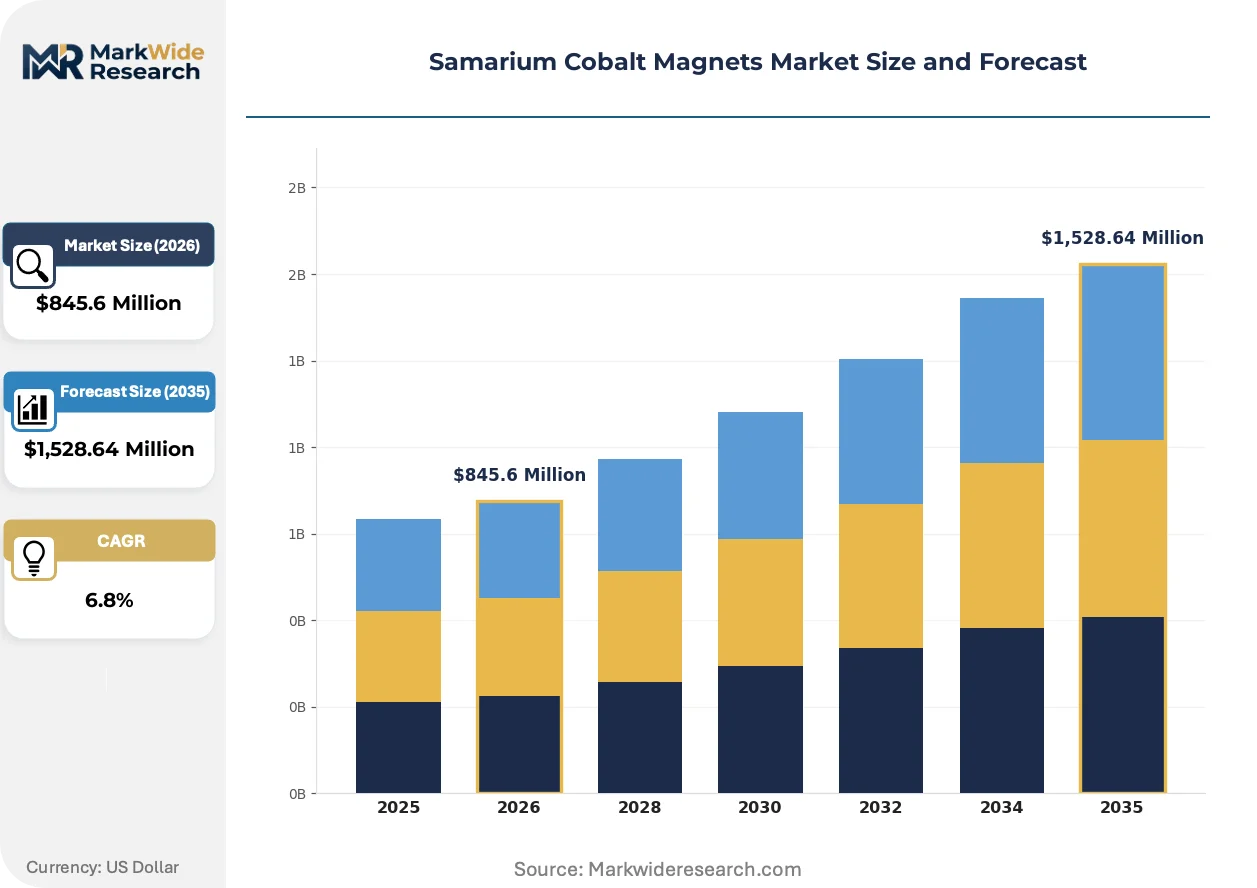
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,528.64 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc, Ring, Block, Custom Shapes Application: Automotive, Aerospace, Consumer Electronics, Industrial Motors End User: Manufacturers, Wholesalers, Retailers, OEMs Size: Small, Medium, Large, Extra Large |
| Companies Covered | NingBo NingGang Permanent Magnetic Materials Co., Ltd., Ningbo Ketian Magnet Co., Ltd., Arnold Magnetic Technologies, Hangzhou Permanent Magnet Group Ltd., China Magnets Source Materials Limited, Electron Energy Corporation, ADAMS Magnetic Products Co., Bunting Magnetics Co., Integrated Magnetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Samarium Cobalt Magnets Market Strategic Shifts & Innovations
Magnet manufacturing is pivoting toward additive and near-net-shape processes that reduce rare earth waste while thermal specification thresholds climb across electrified transportation sectors. Regulatory frameworks are hardening around supply chain provenance and embodied carbon accounting.
Hot isostatic pressing of pre-alloyed SmCo powders is decomposing traditional sintering workflows by enabling full-density consolidation without grain boundary contamination. Satellite gyroscope manufacturers in the United States and Japan are qualifying HIP-processed arc segments for precision momentum wheels. The technology is decomposing machining waste ratios from 40% to under 15% in complex geometries.
REACH and RoHS frameworks in Europe are tightening cobalt content reporting thresholds for industrial equipment placed on EU markets, forcing magnet fabricators to implement batch-level chemical traceability systems. The European Chemicals Agency is expanding substance of very high concern candidate lists to include certain rare earth processing byproducts. Automotive tier-one suppliers serving Stuttgart and Munich manufacturing clusters are responding by demanding full lifecycle analysis documentation from magnet vendors.
Long-term offtake contracting is displacing spot market purchasing for aerospace-grade material, as turbine manufacturers seek price stability across multi-year propulsion development programs. Tier-one suppliers are locking in five-year supply agreements directly with sintering houses, bypassing traditional distributor networks. The shift is most visible in United States defense procurement, where prime contractors consolidate qualified supplier lists to reduce audit burden.
Samarium Cobalt Magnets Market Segmentation
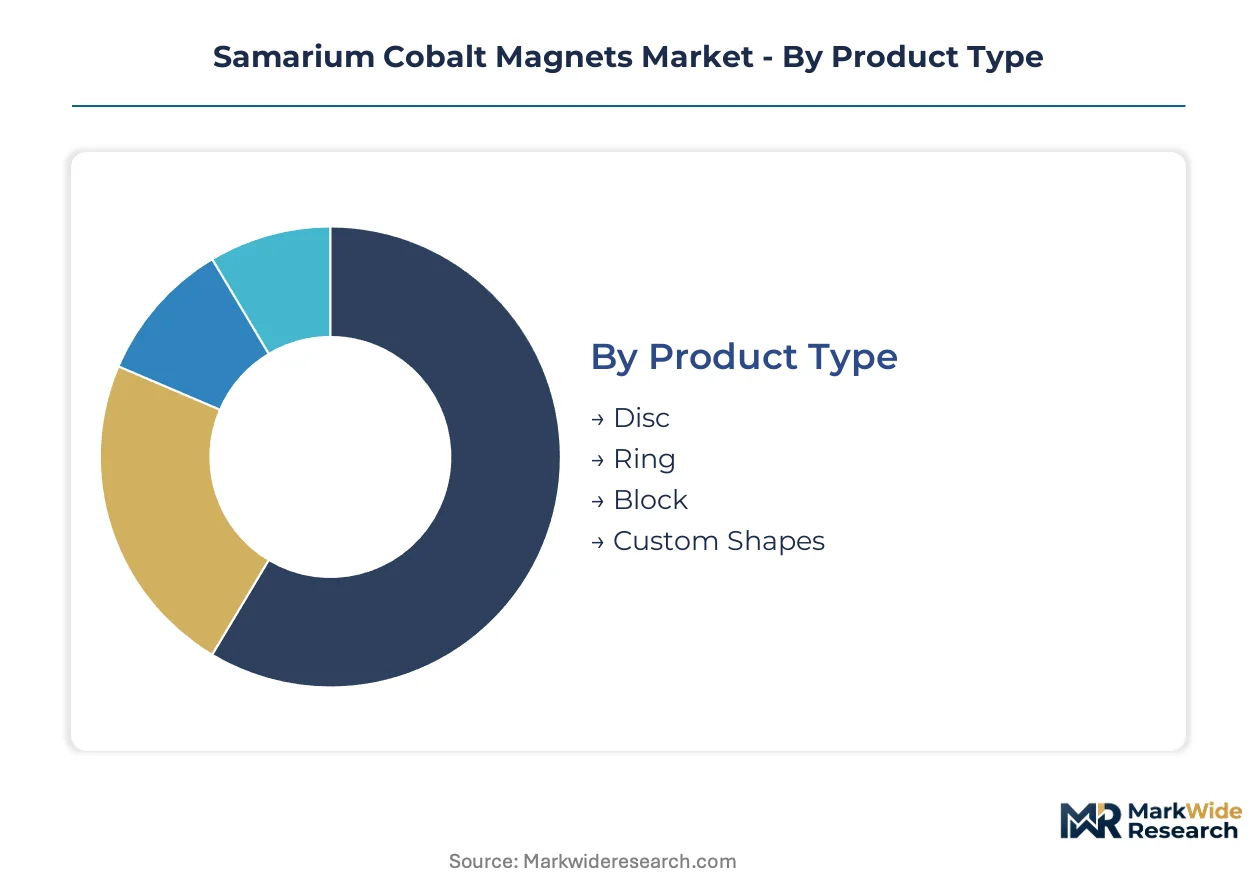
Samarium cobalt magnets fragment across four distinct dimensions that shape procurement patterns and margin structures. Product geometry and thermal specification requirements determine channel routing, while end-use application intensity dictates pricing tiers and qualification complexity.
Product Type:
Disc and ring configurations flow through high-volume distributor networks serving sensor and encoder markets, while custom geometries bypass traditional channels for direct mill-to-OEM contracting.
- Disc:Cylindrical geometries with axial magnetization dominate rotary encoder and position sensor applications. Demand concentrates in Japan's precision motor sector where METI efficiency mandates displace ferrite alternatives in factory automation feedback systems.
- Custom Shapes:Engineered arc segments, tapered blocks, and asymmetric profiles require powder metallurgy sintering followed by precision diamond grinding. Aerospace turbine manufacturers in the United States procure these through DFARS-qualified domestic sintering houses for next-generation propulsion actuator assemblies.
- Ring:Radially magnetized annular configurations serve torque motor and magnetic bearing applications.
- Block:Rectangular prisms with through-thickness magnetization anchor industrial automation OEM procurement across East Asia.
Block magnets dominate installed base volume. Custom shapes are where expansion concentrates.
Application:
Cost tier stratification separates defense-aerospace premiums from automotive volume plays, with thermal threshold requirements determining material grade selection.
- Aerospace:Satellite gyroscope momentum wheels and turbine actuator systems demand SmCo grades exceeding 300°C thermal stability. US Department of Defense procurement mandates domestic provenance, creating captive demand pools for ITAR-certified sintering capacity.
- Automotive:Traction motors in electric vehicles require magnets surviving 180-250°C winding temperatures where neodymium faces irreversible demagnetization risk. European automotive tier-one suppliers serving Stuttgart and Munich clusters now demand full lifecycle analysis documentation under tightening REACH frameworks.
- Industrial Motors:Servo and stepper motor applications in factory automation equipment.
- Consumer Electronics:Miniature acoustic transducers and vibration motors in portable devices.
Industrial motors anchor current volume consumption. Automotive applications are climbing the fastest.
End User:
Customer type determines contract structure, with OEMs locking in multi-year offtake agreements while wholesalers absorb spot market price volatility.
- OEMs:Original equipment manufacturers in aerospace and automotive sectors negotiate direct sintering house relationships, bypassing distributor markups. Long-term contracting is displacing spot purchasing as turbine manufacturers seek price stability across multi-year propulsion development programs.
- Manufacturers:Magnet fabricators and motor assemblers purchase raw magnet stock for value-added machining and magnetization.
- Wholesalers:Distributor networks serve maintenance-repair-operations demand and small-batch industrial procurement.
- Retailers:Specialty component vendors serve hobbyist, research, and prototyping markets.
Manufacturers control upstream volume aggregation. OEMs are where margin expansion concentrates.
Size:
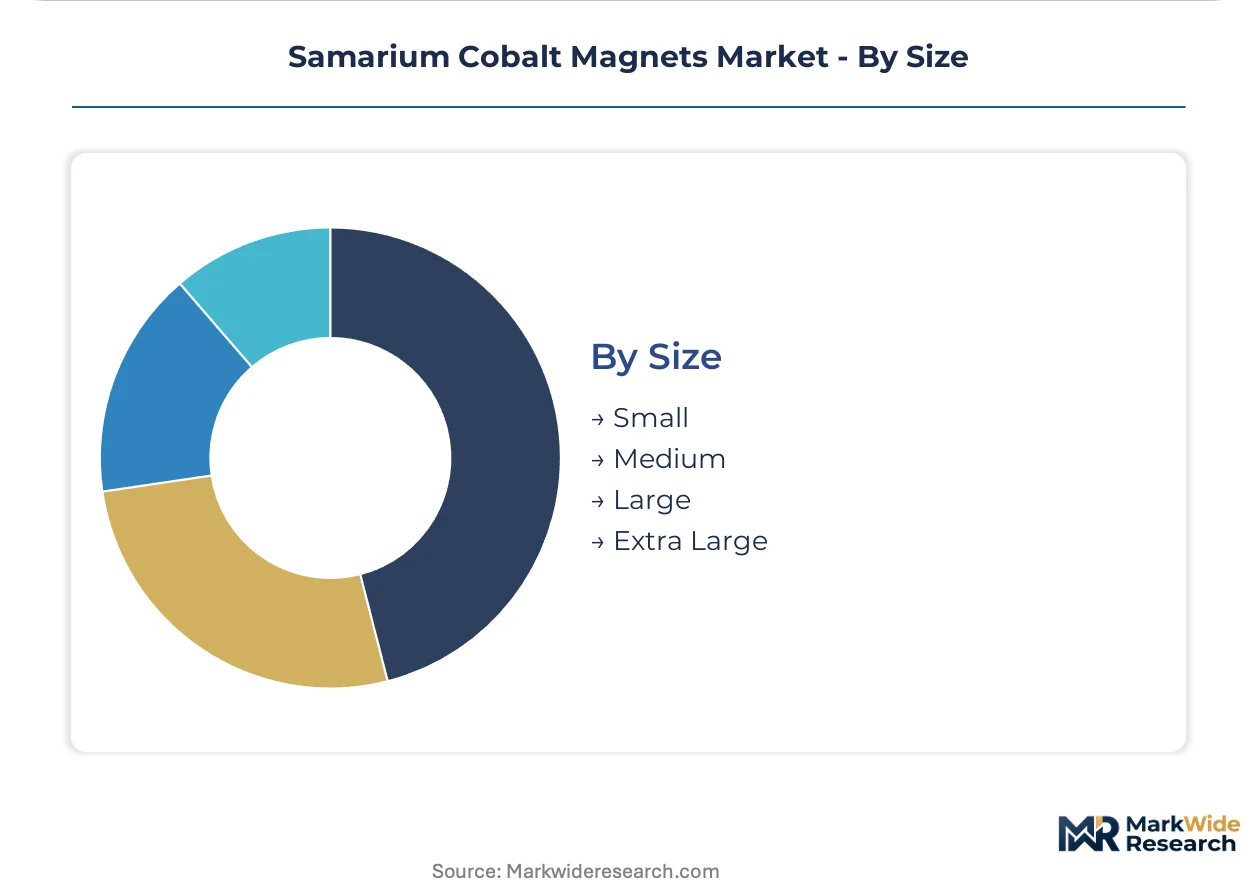
Scale determines processing methodology, with small geometries enabling additive manufacturing experimentation while extra-large blocks require conventional press-and-sinter infrastructure.
- Small:Sub-10mm dimensions enable net-shape binder jet printing of pre-alloyed SmCo powders, reducing diamond grinding waste ratios. Satellite component suppliers in the United States and Japan are qualifying additively manufactured prototypes for precision momentum wheel applications.
- Large:High-energy product blocks exceeding 50mm in any dimension serve wind turbine pitch control motors and heavy industrial servo systems.
- Medium:Mid-range geometries balance magnetic energy density with manufacturing yield.
- Extra Large:Specialized configurations for research accelerators and magnetic separation equipment.
Medium sizes dominate production throughput. Small geometries are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese rare earth processors dominate upstream oxide separation, exporting refined samarium-cobalt feedstock to Japanese precision motor manufacturers and US defense contractors under divergent regulatory frameworks.
United States
DFARS sourcing rules mandate domestic provenance for strategic magnet grades in missile guidance and satellite systems. The US Department of Defense ITAR compliance framework restricts qualified supplier pools, elevating barriers for non-domestic manufacturers. Aerospace turbine manufacturers in California and satellite component suppliers in Colorado are expanding procurement of high-temperature grade SmCo magnets for next-generation propulsion systems.
China
Dual carbon goals and MIIT rare earth processing regulations tighten environmental compliance for smelting operations, accelerating consolidation among domestic producers. The country's export license system shapes international supply availability and quality benchmarking protocols. Processing corridors in Jiangxi and Inner Mongolia concentrate rare earth oxide separation capacity, exposing non-domestic magnet manufacturers to quota fluctuations.
Japan
METI efficiency mandates for industrial servo applications displace ferrite magnets with rare earth alternatives in factory automation equipment. Precision motor manufacturers in Nagoya and Osaka clusters drive demand concentration for disc and ring configurations in rotary encoder markets. JIS standards for permanent magnet classification establish quality protocols that regional suppliers must meet.
Germany
Automotive tier-one suppliers serving Stuttgart and Munich manufacturing clusters demand full lifecycle analysis documentation under tightening REACH frameworks. The European Raw Materials Alliance finances magnet recycling initiatives that could qualify new non-Chinese feedstock streams for automotive OEMs. Industrial automation OEM procurement concentrates on standard-grade blocks for servo motor retrofit programs.
South Korea
Electric vehicle traction motor development programs require magnets surviving 180-250°C winding temperatures where neodymium faces irreversible demagnetization risk. MFDS and national industrial policy support domestic magnet fabricator capacity expansion for automotive supply chains. Seoul Capital Area and Busan-Ulsan clusters anchor precision machining capabilities for custom arc segments.
Samarium Cobalt Magnets Market Key Industry Players
Listed leaders compete with private specialists across certification tiers, with public companies commanding capital access for capacity expansion while private fabricators retain agility in custom engineering. The supplier base stratifies into three tiers: DFARS-qualified domestic sintering houses serving defense primes, high-volume East Asian block producers supplying industrial automation, and precision specialists machining complex geometries for satellite applications. Dominant competitive moves include long-term offtake contracting that bypasses distributor networks and additive manufacturing qualification for near-net-shape prototyping.
Within the defense-qualified tier, Arnold Magnetic Technologies and Electron Energy Corporation exemplify North American sintering specialists positioned for ITAR-restricted procurement pipelines. Among East Asian volume producers, Hangzhou Permanent Magnet Group Ltd. and NingBo NingGang Permanent Magnetic Materials Co., Ltd. occupy positions serving industrial automation OEM procurement across factory automation corridors. These fabricators represent contrasting archetypes: precision-machined arc segment suppliers versus bulk block producers standardizing on rectangular prism geometries.
| Leading Market Players |
|---|
| NingBo NingGang Permanent Magnetic Materials Co., Ltd. |
| Ningbo Ketian Magnet Co., Ltd. |
| Arnold Magnetic Technologies |
| Hangzhou Permanent Magnet Group Ltd. |
| China Magnets Source Materials Limited |
| Electron Energy Corporation |
| ADAMS Magnetic Products Co. |
| Bunting Magnetics Co. |
| Integrated Magnetics |
| Others |
Cost & Logistics Intelligence
Eighteen-to-twenty-four month ITAR certification cycles for military-grade magnet traceability compress supplier switching flexibility and amplify pricing power for qualified domestic sintering houses serving US defense primes. Aerospace turbine manufacturers absorb premium pricing for DFARS-compliant material while industrial automation OEMs in East Asia negotiate volume discounts on standard-grade blocks from bulk producers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that displaces spot market purchasing for aerospace-grade material. Price differentiation hinges on DFARS certification tier and thermal specification grade, with defense-aerospace premiums widening against automotive volume plays. Cost compression in standard-grade blocks is intensifying because Chinese rare earth export license delays create feedstock scarcity for non-domestic fabricators. Automotive tier-one suppliers exhibit highest price sensitivity due to neodymium substitution ceilings below 200°C, while satellite gyroscope assemblers show least sensitivity given irreplaceable high-temperature performance requirements.
Supply Chain Analysis
Forty-to-fifty percent diamond grinding waste ratios in conventional sintering workflows drive inventory intensity for custom arc segment producers serving precision momentum wheel applications. Rare earth oxide separation capacity concentrates in China, Japan, and the United States, with samarium-cobalt feedstock drawing from Jiangxi processing corridors and domestic military-grade sintering houses. Raw material dependencies rest on cobalt metal, rare earth oxides, and pre-alloyed powders. Single-source vulnerability in Chinese export licensing creates supply chain risk. Distribution runs through direct mill-to-OEM contracting for custom geometries and high-volume distributor networks for disc and ring configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among aerospace primes consolidating qualified supplier lists to reduce audit burden, shifting negotiation leverage toward volume-committed OEMs and away from fragmented distributor networks.
For Market Incumbents: Fortify DFARS-qualified sintering capacity through in-house powder metallurgy expertise retention as retiring specialists in Japan and the United States constrain expansion timelines. Deepen backward integration into rare earth oxide separation to reduce exposure to Chinese export license delays. Prioritize additive manufacturing qualification for near-net-shape prototyping to capture satellite component supplier contracts with waste-reduction requirements.
For New Entrants and Emerging Players: ITAR certification fast-tracks for military-grade supply chains offer entry pathways into captive defense demand pools insulated from price competition. Geothermal energy downhole drilling motors represent the most penetrable white-space target, requiring magnets surviving 250°C+ environments where neodymium irreversibly demagnetizes. Pursue prototyping partnerships with volcanic zone turbine generator developers as the go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized sintering assets and dormant military-grade certification pipelines. Long-term viability hinges on positioning for critical minerals stockpile policy shifts across multiple jurisdictions. Monitor European Raw Materials Alliance financing announcements as the inflection indicator for non-Chinese feedstock stream qualification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| ITAR Certification Investment | Opens captive defense procurement pipelines restricted to qualified domestic sintering capacity under DFARS rules. |
| Backward Integration into Oxide Separation | Reduces quota exposure from Chinese rare earth export licensing system and secures feedstock traceability. |
| Additive Manufacturing Qualification | Captures satellite gyroscope contracts demanding HIP-processed arc segments with sub-15% machining waste ratios. |
| Long-term Offtake Contracting | Locks in price stability for aerospace primes across multi-year propulsion development programs. |
| Geothermal Sector Partnership | Positions for underpenetrated volcanic zone turbine generator demand requiring 250°C+ thermal stability. |
Research Approach
A spread of perspectives from powder metallurgy sintering specialists, aerospace procurement officers, rare earth oxide traders, and automotive tier-one supplier engineers converged on the working assumptions. Primary interviews combined with secondary validation from SEC filings of magnet fabricators, US Department of Defense procurement databases, Japan METI industrial efficiency reports, and Chinese MIIT rare earth processing regulations. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Product geometry, thermal specification grade, end-use application intensity, and customer contract structure served as the segmentation dimensions modeled. CAGRs derived from growth driver elasticity analysis against base-year consumption patterns. Forecast inputs included defense procurement mandate enforcement timelines, EV thermal management architecture evolution rates, and REACH cobalt content reporting threshold adjustments.
Decision-makers should treat outputs as directional under assumptions of sustained DFARS compliance enforcement and Chinese dual carbon policy continuity; material deviation in either would warrant model refresh. Forecasts reflect these assumptions without claiming predictive certainty. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Magnet Market
Magnetic Materials
Sintered Magnet Market
Magnetic Materials
High Performance Magnet Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
Neodymium [Nd-Fe-B] Magnet Market
Magnetic Materials
Carbonyl Iron Powder Market
Magnetic Materials
Ferroboron Market
Magnetic Materials
High Purity Carbonyl Iron Powder (CIP) Market
Magnetic Materials
Magnetic Material Magnetization and Testing Equipment Market
Magnetic Materials
Magnet Wire Market
Magnetic Materials
Global Non-Oriented Electrical Steel Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Ferromanganese Market
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
North America Magnet Market