
 Global Soft Magnetic Alloys Market | 2026-2036
Global Soft Magnetic Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Global Soft Magnetic Alloys Market Foresight
Capital-intensity divergence between integrated melt-to-lamination producers and specialty alloy developers is rotating competitive advantage toward firms controlling vacuum induction melting and precision rolling infrastructure. VACUUMSCHMELZE GmbH & Co. KG leverages its ultra-pure melting capability to dominate premium iron-cobalt and iron-nickel grades for aerospace and medical applications. Hitachi Metals, Ltd. anchors regional supply through integrated silicon steel production serving transformer and motor manufacturers across East Asia. JFE Steel Corporation competes on thermal-process scale, sustaining cost leadership in oriented silicon steel for grid infrastructure.
Soft magnetic alloys are metallic materials engineered for high magnetic permeability and low coercivity, typically containing controlled silicon, nickel, or cobalt additions processed through precision rolling and annealing cycles to optimize grain orientation and minimize core loss in alternating magnetic fields. Their primary commercial purpose centers on efficient energy conversion and signal transmission in electromagnetic devices ranging from distribution transformers to high-frequency power electronics. Silicon steel retains the largest volume share across transformer and industrial motor applications, reflecting mature infrastructure replacement cycles and established supply chains. Amorphous metals represent the fastest-expanding product category, driven by distribution transformer efficiency mandates that reward their superior core-loss performance over conventional crystalline grades. Iron-nickel alloys command concentrated margin pools in precision instrumentation and defense applications where permeability stability under temperature variation justifies material premiums.
The US Department of Energy enforces transformer efficiency standards through NHTSA-aligned appliance regulations, while the EU Green Deal and F-Gas Regulation accelerate core material upgrades across European grid infrastructure. China's MIIT implements GB standards for motor efficiency tiers that directly specify allowable core loss thresholds, channeling demand toward higher-grade silicon steel and amorphous alternatives. Japan's METI maintains JIS standards that exceed baseline IEC requirements, sustaining domestic premium for advanced alloy formulations. Stakeholders must monitor evolving efficiency tier definitions across these regulatory frameworks to align R&D portfolios with compliance thresholds that will determine market access and procurement qualification.
Market Dynamics
Transformer efficiency mandates across major economies are compressing demand timelines for advanced core materials, forcing alloy producers to accelerate qualification cycles for amorphous metal and high-grade silicon steel alternatives ahead of scheduled grid modernization waves.
Growth Catalysts
- EU Green Deal efficiency tiers:Distribution transformer standards under the F-Gas Regulation are mandating core-loss reductions that favor amorphous metal adoption over conventional crystalline grades in European grid infrastructure.
- Electric vehicle traction motors:Automakers are specifying thinner-gauge silicon steel laminations with optimized grain orientation to maximize power density in high-speed motor designs.
- China's dual carbon framework:MIIT efficiency classifications for industrial motors are channeling procurement toward premium alloy grades that meet GB standard core-loss thresholds.
Market Restraints
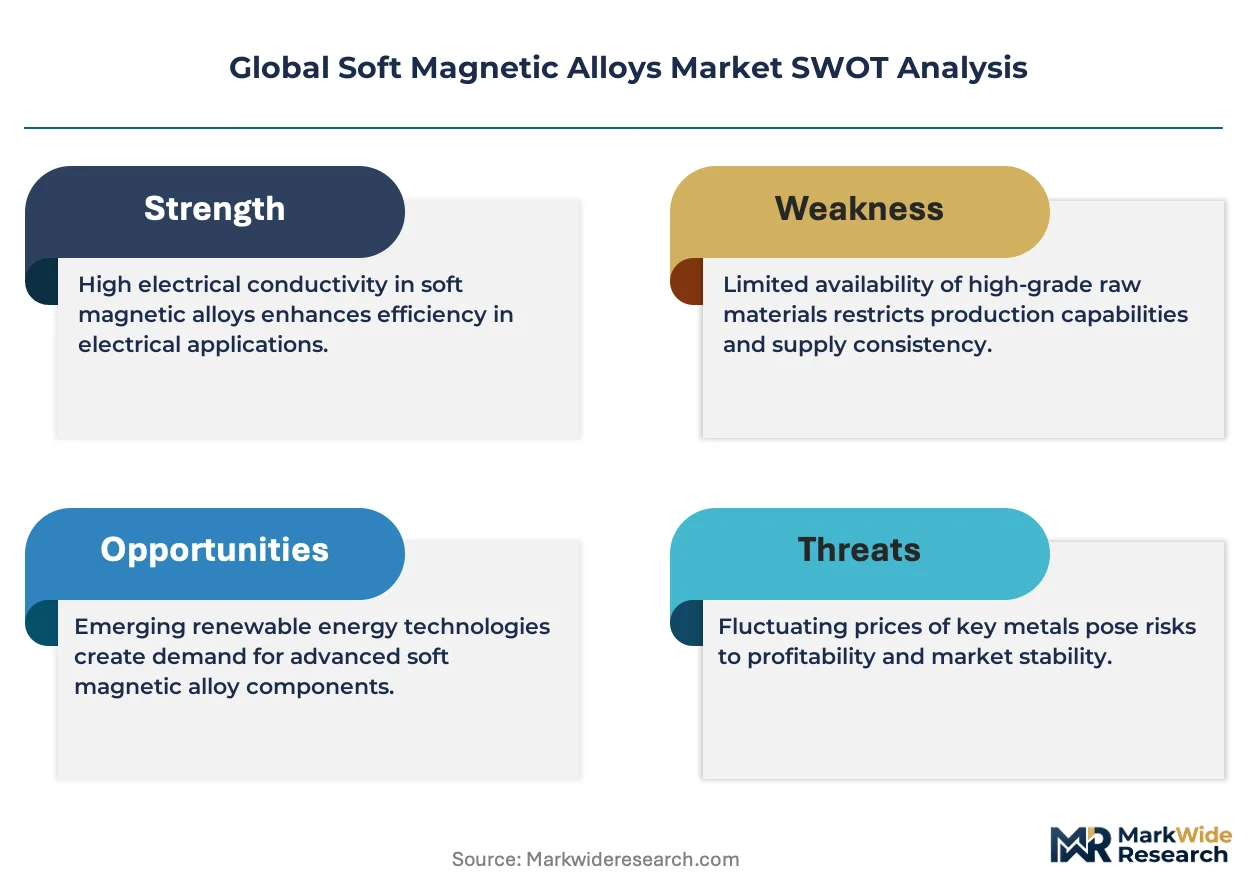
- Raw material concentration:High-purity cobalt and nickel supply chains concentrate in southern African mining operations and Russian refining capacity, exposing alloy producers to geopolitical input volatility.
- Amorphous metal processing limits:Rapid solidification casting equipment operates at narrower throughput windows than conventional rolling mills, constraining volume scalability for distribution transformer demand surges.
- Transformer replacement inertia:Utility asset managers face capital allocation conflicts between efficiency upgrades and grid resilience investments, slowing core material refresh cycles despite regulatory deadlines.
Strategic Opportunities
- India motor efficiency expansion:BIS implementation of IE4 and IE5 motor standards creates procurement pull for high-permeability iron-nickel alloys in precision industrial applications where local supply remains underdeveloped.
- Power electronics miniaturization:Convergence of wide-bandgap semiconductors with high-frequency magnetic cores is opening design space for nanocrystalline ribbon in EV onboard chargers and renewable inverters.
- Direct utility procurement platforms:Grid operators in Japan and South Korea are establishing qualified supplier registries that bypass traditional distributor networks for transformer core material sourcing.
Industry Challenges
- Vacuum induction melting expertise scarcity:Ultra-pure alloy production requires operators with specialized metallurgical training that outpaces vocational pipeline output in established manufacturing regions.
- Multi-jurisdiction certification stacking:Core material suppliers must simultaneously satisfy JIS, IEC, and GB testing protocols to maintain qualification across Japanese, European, and Chinese transformer OEM supply bases.
- Legacy lamination equipment retrofit costs:Conventional rolling mills require substantial capital redeployment to achieve thickness tolerances demanded by next-generation motor designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Soft Magnetic Alloys Market |
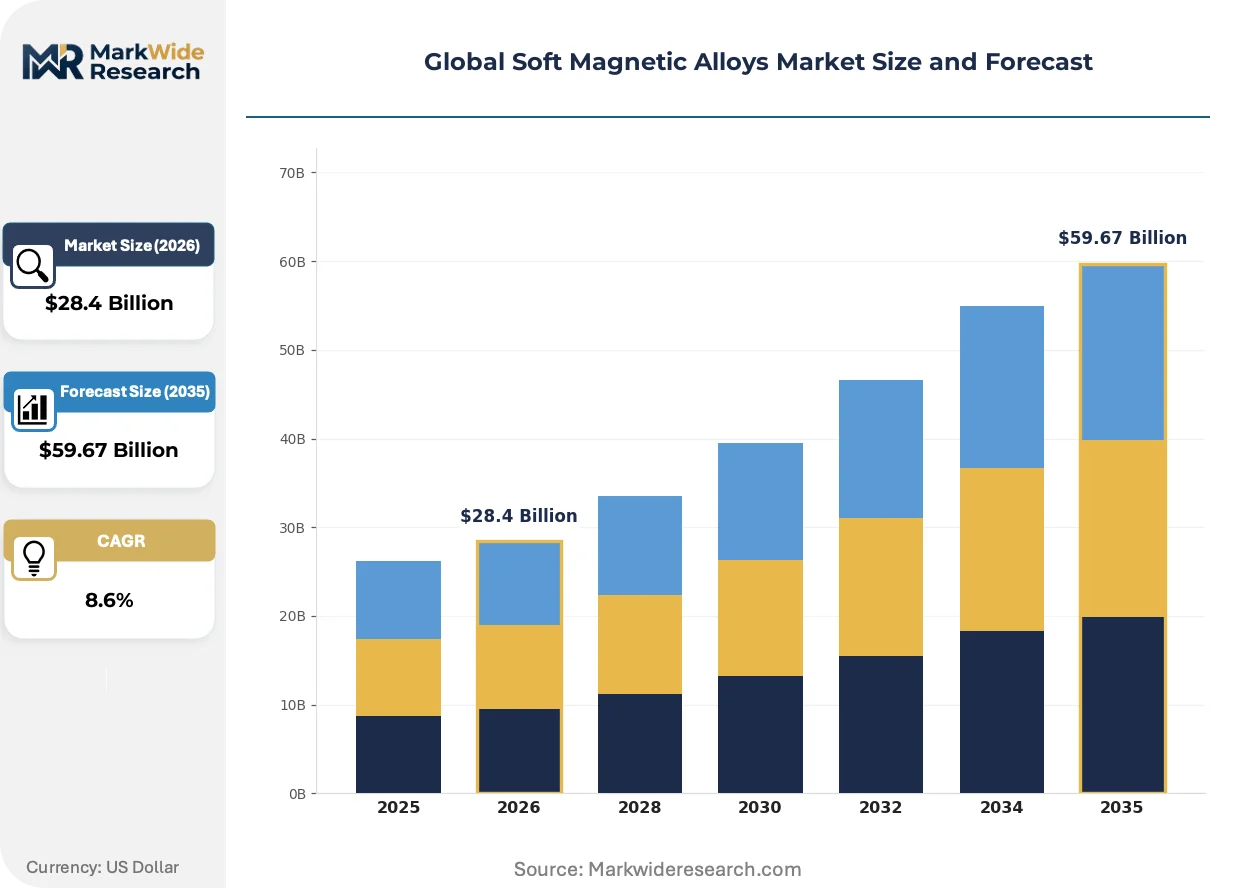
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $59.67 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Steel, Iron-Cobalt Alloys, Iron-Nickel Alloys, Amorphous Metals, Ferrites Application: Electric Motors, Transformers, Inductors, Magnetic Sensors, Power Generation End User Industry: Consumer Electronics, Renewable Energy, Defense Equipment, Telecommunications, Rail Transport Manufacturing Process: Casting, Powder Metallurgy, Rolling, Annealing, Sintering |
| Companies Covered | Hitachi Metals, Ltd., VACUUMSCHMELZE GmbH & Co. KG, JFE Steel Corporation, Toshiba Materials Co., Ltd., Daido Steel Co., Ltd., PROTERIAL, Ltd., Advanced Technology & Materials Co., Ltd., ArcelorMittal S.A., TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Soft Magnetic Alloys Market Shifts & Advancements
Material science advances and regulatory compression are splitting the market into efficiency-optimized premium grades and cost-driven standard offerings, with processing technology rather than raw material chemistry becoming the primary differentiation vector.
Amorphous metal ribbon production is bifurcating the transformer core market between ultra-low-loss distribution applications and conventional grain-oriented silicon steel dominance in power transformers. Japanese and South Korean utilities are qualifying amorphous cores for urban substation deployments where load density justifies material premiums. This technology is compressing the viable performance window for mid-grade silicon steel, forcing producers to choose between premium amorphous qualification or standard-grade cost leadership.
China's MIIT has tightened GB motor efficiency classifications that explicitly reference core-loss testing methodologies, eliminating loopholes that previously allowed marginal material grades to qualify for higher tier labels. Domestic motor manufacturers are redesigning stator geometries to accommodate thinner laminations that compensate for alloy cost premiums through copper savings. The industrial motor segment faces the steepest compliance trajectory, with foundries and metal processors representing the largest addressable volume for upgraded core materials.
Long-term supply agreements are displacing spot-market purchasing for high-grade silicon steel among tier-one transformer OEMs seeking volume certainty amid raw material volatility. Japanese trading houses are consolidating procurement for regional grid operators into consolidated material pools that reduce qualification overhead. This concentration is most visible in East Asian manufacturing clusters, where integrated steel-alloy-lamination supply chains enable just-in-time core production for transformer assembly lines.
Global Soft Magnetic Alloys Market Segmentation
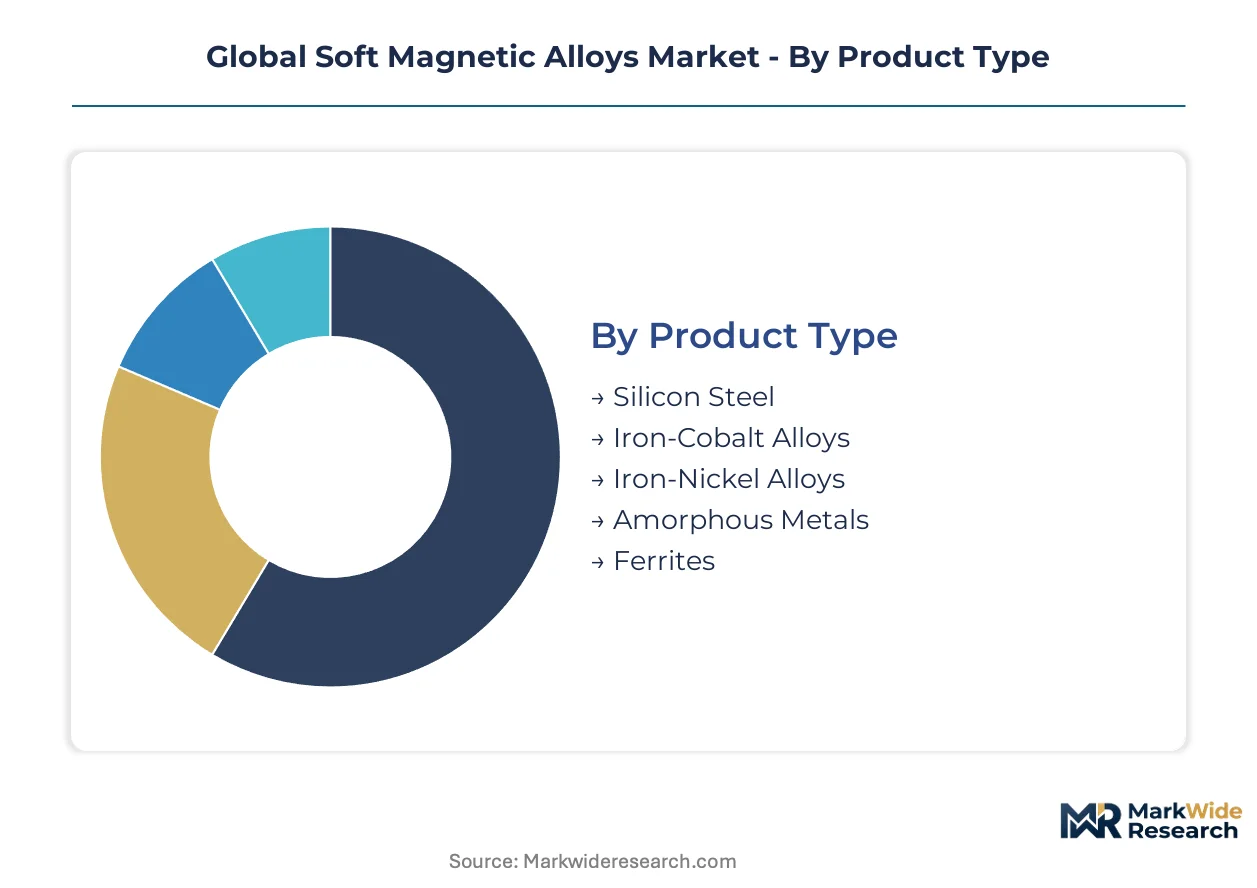
Soft magnetic alloys serve fundamentally different performance requirements across energy conversion, signal processing, and electromagnetic shielding applications. Segmentation reveals where material substitution pressures are most acute and where proprietary processing capabilities defend margin pools.
Product Type:
Amorphous metals pose the most direct substitution threat to conventional crystalline grades, particularly in distribution transformer cores where efficiency mandates reward their superior core-loss performance.
- Silicon Steel:Crystalline iron-silicon alloys processed through precision rolling and grain orientation control dominate transformer and industrial motor laminations. Demand concentrates in China's power grid expansion and India's distribution infrastructure, where GB and BIS efficiency standards channel procurement toward higher-grade oriented variants.
- Amorphous Metals:Rapidly solidified non-crystalline ribbons manufactured through melt-spinning achieve core losses one-third those of conventional silicon steel. Japanese utilities under METI efficiency guidelines are qualifying amorphous cores for urban substation deployments where load density justifies material premiums.
- Iron-Nickel Alloys:High-permeability permalloy grades serve precision instrumentation and aerospace applications requiring magnetic stability across temperature extremes.
- Iron-Cobalt Alloys:Ultra-high saturation induction grades command concentrated margins in defense and medical imaging where power density constraints dominate design.
- Ferrites:Ceramic magnetic oxides occupy high-frequency power electronics and EMI suppression below 1 MHz where metallic alloys exhibit excessive eddy current losses.
Silicon steel retains volume leadership; amorphous metals hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity-grade motor laminations from premium transformer cores where efficiency certification drives material selection.
- Transformers:Distribution and power transformer cores represent the largest addressable volume, with EU F-Gas Regulation and China's dual carbon framework mandating core-loss reductions that favor advanced alloy grades.
- Electric Motors:Traction motor laminations in EV powertrains specify thinner-gauge silicon steel with optimized grain orientation to maximize power density at rotational speeds exceeding 15,000 RPM.
- Inductors:Power conditioning and filtering applications in renewable inverters drive demand for nanocrystalline ribbon compatible with wide-bandgap semiconductor switching frequencies.
- Magnetic Sensors:Position and current sensing applications in automotive and industrial automation require iron-nickel alloys with stable permeability across operating temperature ranges.
- Power Generation:Generator cores in wind turbines and conventional plants utilize grain-oriented silicon steel with specific loss characteristics matched to grid frequency requirements.
Transformers dominate procurement volume; electric motors are climbing the fastest as EV production scales.
End User Industry:
Geographic concentration of manufacturing capacity creates divergent demand profiles across East Asian electronics clusters and European renewable energy infrastructure.
- Renewable Energy:Wind turbine generators and solar inverter inductors require high-efficiency core materials that minimize conversion losses across variable load conditions. Procurement concentrates in Denmark, Germany, and China's coastal manufacturing provinces.
- Consumer Electronics:Miniaturized power adapters and wireless charging coils specify thin-gauge amorphous ribbon and ferrite cores where frequency performance outweighs material cost.
- Rail Transport:Traction motor and auxiliary transformer applications in high-speed rail networks specify certified laminations meeting stringent fire safety and electromagnetic compatibility standards.
- Defense Equipment:Stealth applications and precision guidance systems utilize iron-cobalt and iron-nickel alloys with tailored magnetic signatures and radiation hardness.
- Telecommunications:Base station power supplies and data center UPS systems drive demand for amorphous metal distribution transformers in Japan and South Korea.
Renewable energy commands the largest project-based volumes; consumer electronics exhibits the most rapid design cycle turnover.
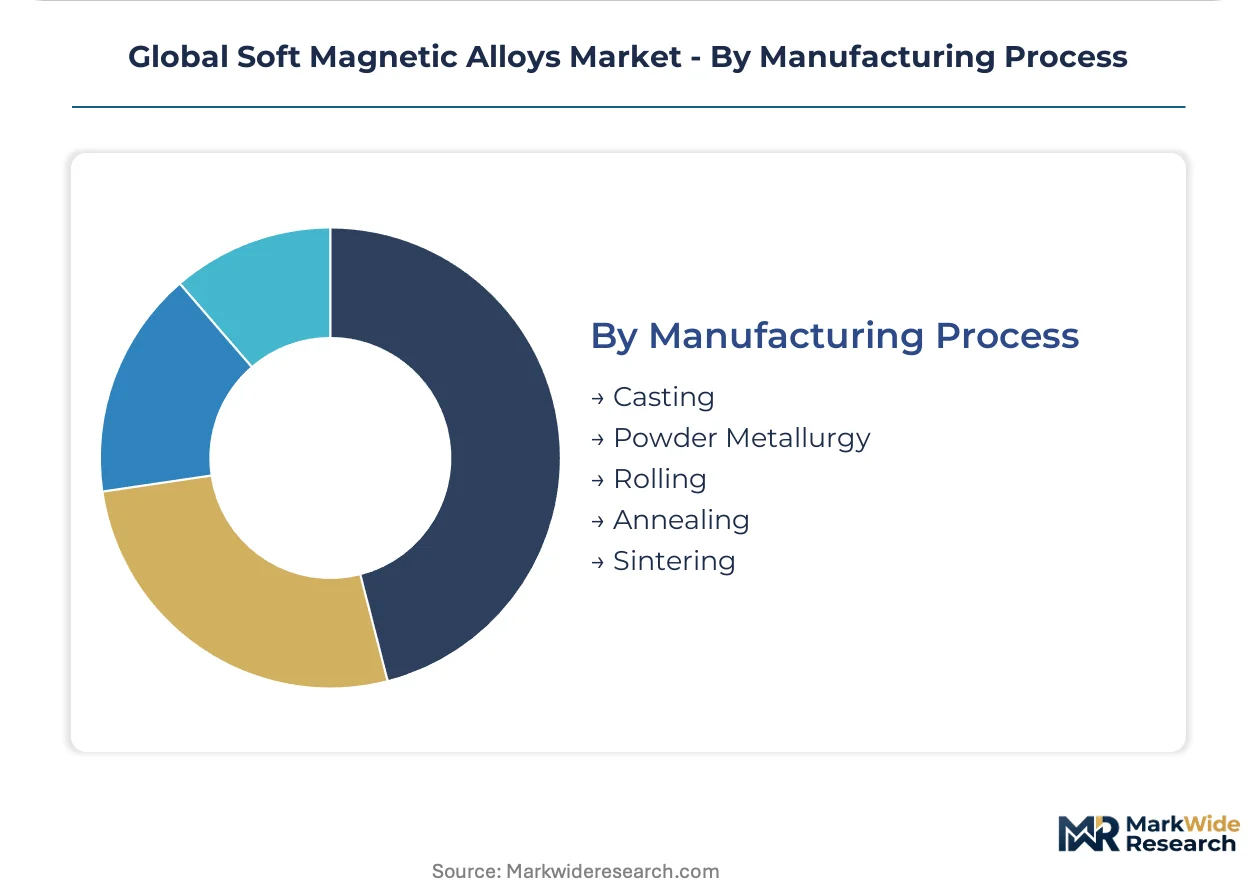
Manufacturing Process:
Supply concentration in vacuum induction melting and precision rolling infrastructure determines which producers can qualify for premium efficiency tiers.
- Rolling:Tandem cold rolling mills with automated gauge control produce silicon steel laminations to thickness tolerances below 0.2 mm for high-speed motor applications. JFE Steel and Hitachi Metals anchor regional supply through integrated melt-to-lamination production in Japan.
- Annealing:Continuous annealing lines with controlled atmosphere and magnetic field alignment optimize grain orientation and reduce residual stress in transformer-grade silicon steel.
- Casting:Conventional ingot casting serves lower-efficiency motor grades where cost minimization outweighs core-loss performance.
- Powder Metallurgy:Compaction and sintering of alloy powders enables complex net-shape magnetic cores for inductor applications where machining would degrade magnetic properties.
- Sintering:Ferrite production relies on ceramic sintering processes distinct from metallic alloy processing, with supply chains concentrated in Chinese and Japanese ceramic manufacturers.
Rolling dominates metallic alloy throughput; annealing capacity represents the critical bottleneck for premium grade qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and South Korea exhibit the lowest price elasticity, prioritizing efficiency certification over material cost, while Indian and Southeast Asian procurement remains highly sensitive to unit economics. This demand-elasticity contrast shapes regional supply strategies.
China
Grid modernization and EV motor expansion drive procurement of high-grade silicon steel and amorphous ribbon. MIIT's GB motor efficiency standards mandate specific core-loss thresholds that disqualify marginal alloy grades. Yangtze River Delta manufacturing clusters around Shanghai host integrated melt-to-lamination facilities supplying transformer OEMs.
Japan
Urban substation densification and telecommunications infrastructure sustain premium demand for ultra-low-loss core materials. METI's JIS standards exceed baseline IEC requirements, creating a protected domestic market for advanced alloy formulations. Kansai region producers concentrate precision rolling capacity for thin-gauge motor laminations.
Germany
Wind turbine generator manufacturing and distribution transformer replacement cycles anchor European demand. EU Green Deal F-Gas Regulation mandates core-loss reductions that accelerate amorphous metal qualification. Industrial clusters in North Rhine-Westphalia coordinate material procurement through consolidated supplier pools.
United States
Data center power infrastructure and EV traction motor supply chains represent the fastest-expanding demand segments. DOE transformer efficiency standards through NHTSA-aligned regulations enforce appliance-grade core material specifications. Southeast manufacturing corridors are attracting lamination capacity to serve regional transformer assembly.
India
Industrial motor efficiency upgrades and renewable inverter deployment create procurement pull for high-permeability alloys. BIS implementation of IE4 and IE5 motor standards channels demand toward certified core materials. Gujarat and Maharashtra industrial zones face supply gaps in locally qualified silicon steel production.
Global Soft Magnetic Alloys Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Integrated steel-alloy producers dominate volume segments through thermal-process scale, while specialty alloy developers capture premium tiers through vacuum melting expertise. Three archetypes define the field: melt-to-lamination integrators, precision alloy specialists, and diversified materials conglomerates. Capacity expansion and strategic partnerships represent the dominant competitive moves, with firms securing long-term supply agreements to lock in raw material access.
Within the specialty alloy tier, VACUUMSCHMELZE GmbH & Co. KG exemplifies ultra-pure melting capability, while Hitachi Metals, Ltd. and JFE Steel Corporation occupy positions as integrated regional suppliers. These three anchors illustrate how geographic concentration in East Asian manufacturing clusters reinforces supply chain proximity advantages. Archetype differentiation rests on processing infrastructure rather than raw material access alone.
| Leading Market Players |
|---|
| Hitachi Metals, Ltd. |
| VACUUMSCHMELZE GmbH & Co. KG |
| JFE Steel Corporation |
| Toshiba Materials Co., Ltd. |
| Daido Steel Co., Ltd. |
| PROTERIAL, Ltd. |
| Advanced Technology & Materials Co., Ltd. |
| ArcelorMittal S.A. |
| TDK Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Japanese transformer OEMs and integrated steel producers lock in both cobalt-nickel alloy access and price visibility through the EU Green Deal compliance window. These contracts insulate premium-grade purchasers from spot volatility in southern African mining output while compressing margins for uncommitted spot buyers.
Pricing Analysis
After-sales service contracts covering lamination qualification and core-loss certification drive lifetime value for amorphous metal suppliers. Three-tier pricing structure across premium amorphous ribbon, high-grade oriented silicon steel, and standard motor laminations reflects GB standard efficiency tier alignment. Pricing pressure stems from rapid solidification equipment throughput constraints that limit volume scalability against distribution transformer demand surges. Indian industrial motor manufacturers exhibit highest price sensitivity, while Japanese utilities under METI guidelines prioritize core-loss performance over unit cost.
Supply Chain Analysis
China and Japan anchor global silicon steel melting and precision rolling capacity, with South Korea consolidating amorphous metal ribbon production for telecommunications infrastructure. High-purity cobalt from southern African mining operations and nickel from Russian refining capacity feed vacuum induction melting lines. Single-source vulnerability in rapid solidification casting equipment creates qualification bottlenecks for amorphous metal expansion. Distribution runs through integrated melt-to-lamination facilities in East Asian manufacturing clusters, bypassing traditional distributor networks for qualified transformer core material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Soft Magnetic Alloys Market sits in early-cycle expansion as EV traction motor specifications proliferate thinner-gauge lamination requirements across multiple OEM platforms. Amorphous metal qualification waves in European and East Asian grid infrastructure extend the addressable premium-grade envelope.
For Market Incumbents: Fortify vacuum induction melting capacity in the Yangtze River Delta to capture MIIT GB standard compliance demand from domestic motor manufacturers. Deepen backward integration into high-purity cobalt offtake from southern African mining operations to hedge against geopolitical input volatility threatening iron-cobalt alloy margins.
For New Entrants and Emerging Players: Differentiate on nanocrystalline ribbon formulations for wide-bandgap semiconductor power electronics in EV onboard chargers and renewable inverters. Target India's Gujarat and Maharashtra industrial zones where BIS IE4 and IE5 motor standards create procurement pull for certified core materials amid local supply gaps. Pursue direct utility procurement platform qualification in Japan and South Korea to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward specialty alloy developers with captive vacuum induction melting infrastructure and established JIS-IEC-GB certification stacking capabilities. Long-term viability rests on processing technology differentiation rather than raw material chemistry alone. Watch for amorphous metal volume scalability breakthroughs in rapid solidification casting as the inflection signal for premium-grade market share shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Precision Rolling | JFE Steel and Hitachi Metals anchor regional supply through integrated melt-to-lamination production in Japan. |
| Backward Integration into Cobalt Supply | VACUUMSCHMELZE secures high-purity melting feedstock from southern African mining operations for aerospace grades. |
| Amorphous Metal Qualification Partnerships | Japanese utilities under METI guidelines validate ultra-low-loss cores for urban substation densification deployments. |
| Long-term Supply Agreement with EV OEMs | Tier-one motor manufacturers lock in thinner-gauge silicon steel laminations through multi-year offtake contracts. |
| Joint Venture for Rapid Solidification Scale-up | Equipment constraints in melt-spinning lines limit volume scalability against EU F-Gas Regulation demand surges. |
Research Methodology
A standing panel of transformer OEM procurement directors, vacuum induction melting operators, motor design engineers, and utility grid planning officers provided ongoing calibration against secondary validation. Primary interviews combined with customs trade data, MIIT GB standard filings, SEC 10-K disclosures from listed steel producers, and METI JIS certification databases enabled bottom-up and top-down triangulation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, application, end-use industry, and manufacturing process segmentation dimensions. CAGRs were derived from modeled adoption curves for amorphous metal substitution in distribution transformers and EV traction motor lamination specifications. Industry-specific inputs included GB standard efficiency tier implementation timelines and rapid solidification equipment capacity utilization rates.
Material uncertainties — cobalt-nickel supply disruption, amorphous metal processing scale limitations, and multi-jurisdiction certification protocol divergence — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory compliance deadline adherence and OEM platform standardization trajectories. Recalibration cycles align with material shifts in MIIT motor efficiency classifications and EU F-Gas Regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Ferroboron Market
Magnetic Materials
Magnetostrictive Materials Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
Magnet Wire Market
Magnetic Materials
Global Iron Powder Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
North America Magnet Market
Magnetic Materials
Carbonyl Iron Powder Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Neodymium-Iron-Boron Magnet Market
Magnetic Materials
Magnet Buffer Market
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
High Performance Permanent Magnet Market