
 North America Ferrite Magnet Market | 2026-2036
North America Ferrite Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ferrite Magnet Market Intelligence
Buyer concentration across the North American automotive tier-one supply base is broadening as EV platforms diversify beyond traditional Detroit sourcing pools. Dura Magnetics leverages its proximity to Midwest motor manufacturers to sustain just-in-time delivery contracts. Arnold Magnetic Technologies anchors its position through specialized ferrite formulations for high-temperature sensor applications. Electron Energy Corporation competes via rare-earth alternatives that redirect some ferrite demand toward bonded hybrid solutions.
North America ferrite magnets are ceramic compounds composed primarily of iron oxide (Fe₂O₃) combined with strontium or barium carbonate, sintered at temperatures exceeding 1,200°C to achieve coercivity values typically ranging from 150 to 300 kA/m and operating temperatures up to 250°C; these properties make them indispensable for cost-sensitive electromechanical applications requiring moderate magnetic energy products. Ferrite blocks dominate volume shipments across motor components due to their geometric flexibility in stator and rotor assemblies, while ferrite rings command premium positioning within transformer applications where toroidal flux paths reduce eddy current losses. The sensors application segment exhibits the fastest structural expansion as ADAS architectures multiply magnetic sensing nodes per vehicle platform.
NHTSA motor-vehicle safety standards and EPA hazardous substance restrictions shape material selection and recycling obligations throughout the ferrite supply chain, while USMCA origin requirements influence cross-border component sourcing between US, Mexican, and Canadian assembly plants. OSHA workplace exposure limits for ceramic particulates during sintering operations add compliance costs that favor larger-scale producers with captive environmental controls. Stakeholders must monitor how NHTSA's evolving electrification safety protocols and EPA per- and polyfluoroalkyl substance screening programs will recast ferrite magnet qualification criteria across the North American supplier base.
Market Dynamics
EPA emissions rules and NHTSA efficiency mandates are compressing qualification timelines for ferrite magnet suppliers serving electrified powertrain programs, while the geographic concentration of EV motor manufacturing in the US Great Lakes corridor is reshaping procurement proximity requirements.
Growth Catalysts
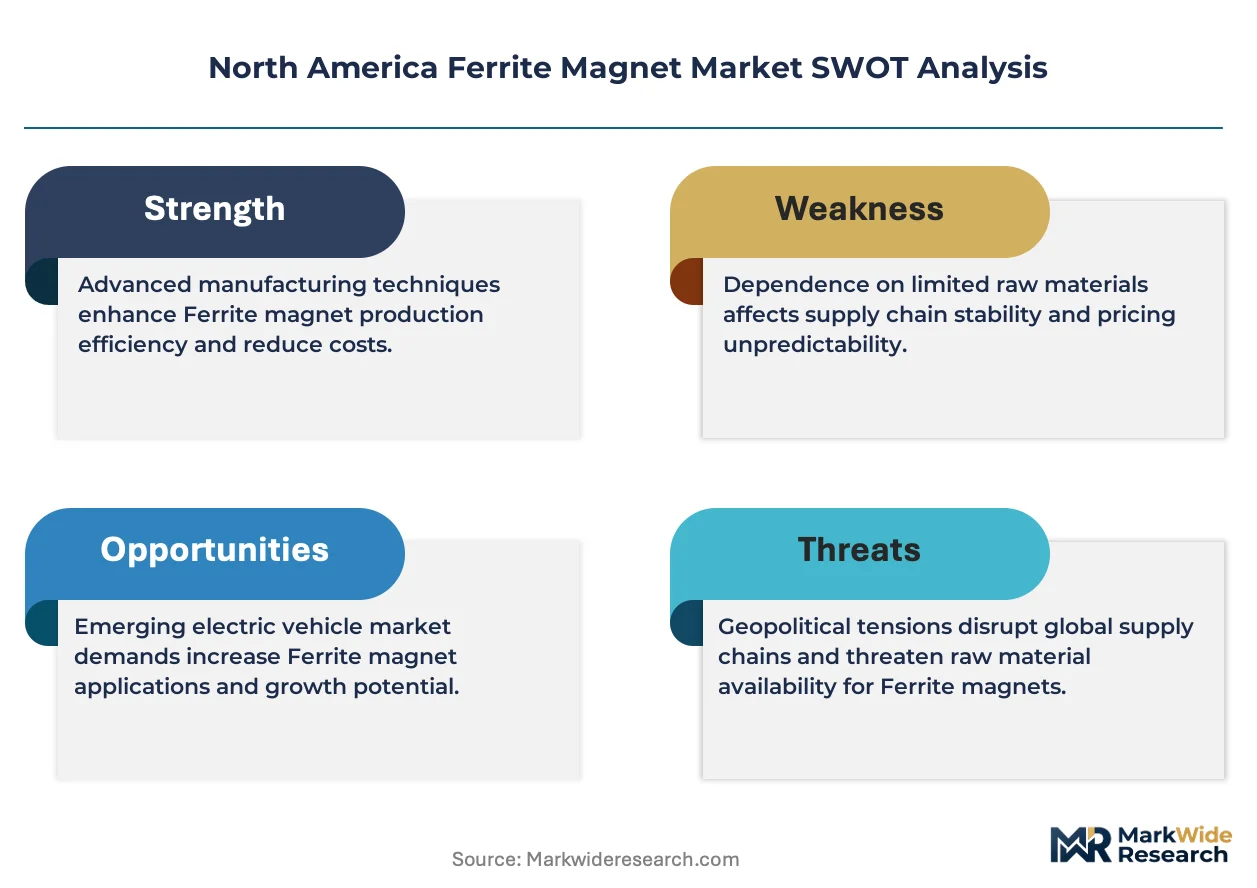
- USMCA origin compliance:North American assembly plants are qualifying regional ferrite sources to satisfy content requirements for cross-border motor component shipments.
- NHTSA electrification safety protocols:Updated federal motor-vehicle standards are mandating redundant magnetic sensing architectures that expand ferrite node counts per platform.
- Iron oxide feedstock proximity:Domestic ore processing and powder metallurgy capabilities in the Midwest are shortening supply chains for sintered ceramic magnet producers.
Market Restraints
- Strontium carbonate import dependence:North American ferrite producers rely on concentrated overseas suppliers for critical carbonate precursors, exposing margin structures to freight and tariff volatility.
- Bonded rare-earth hybrid substitution:Electron Energy Corporation and competitors are redirecting some sensor and actuator demand toward neodymium-iron-boron alternatives with superior energy density.
- OSHA ceramic particulate limits:Workplace exposure regulations during sintering operations impose fixed compliance costs that disadvantage smaller-scale producers lacking captive environmental controls.
Strategic Opportunities
- Canadian critical minerals processing:Saskatchewan and Ontario deposits offer upstream integration potential for ferrite precursor supply security under USMCA frameworks.
- ADAS magnetic sensing proliferation:Advanced driver-assistance systems are multiplying wheel-speed, position, and current-sensing nodes per vehicle platform.
- EPA per- and polyfluoroalkyl substance screening:Emerging federal chemical restrictions are creating qualification windows for ferrite formulations that eliminate fluorinated process additives.
Industry Challenges
- Sintering furnace operator certification:OSHA-mandated training programs for high-temperature ceramic processing are constraining available technical labor pools in Midwest manufacturing zones.
- Multi-site environmental compliance:Producers operating across US state lines face fragmented air-quality permitting timelines that delay capacity expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ferrite Magnet Market |
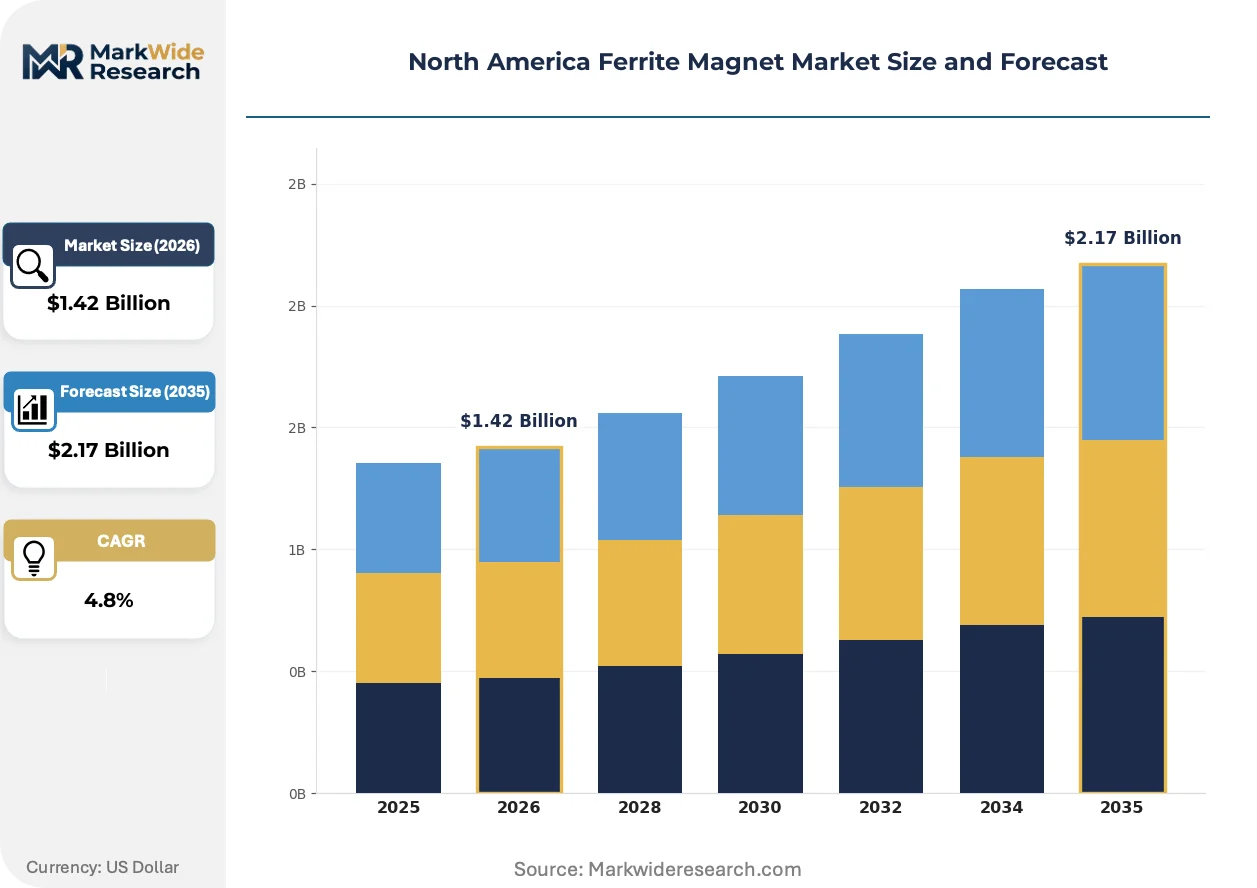
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferrite Rods, Ferrite Blocks, Ferrite Discs, Ferrite Rings End User: Electronics, Automotive, Industrial, Aerospace Application: Motor Components, Sensors, Magnetic Assemblies, Transformers Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | Dura Magnetics, Electron Energy Corporation, Arnold Magnetic Technologies, Honeywell International, Stanford Magnets, Integrated Magnetics, Master Magnetics, MainRich Magnets, Dexter Magnetic Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ferrite Magnet Market Strategic Shifts & Innovations
Magnet manufacturing processes are fragmenting across distributed production nodes as proximity-to-customer imperatives override historical centralization economics in the automotive supply base.
Isotropic ferrite powder injection molding is decentralizing motor component sourcing by enabling tier-two suppliers to produce complex stator geometries without capital-intensive press-and-sinter infrastructure. Tier-one EV motor manufacturers are qualifying these distributed sources for non-critical auxiliary applications. The technology is compressing minimum efficient scale thresholds and opening supplier entry points outside traditional magnet manufacturing clusters.
NHTSA's evolving electrification safety protocols are mandating redundant magnetic isolation barriers in high-voltage powertrain architectures. The regulatory pressure is forcing ferrite suppliers to develop temperature-graded formulations that maintain coercivity above 200°C. Sensor module producers serving Detroit-based OEMs are accelerating qualification cycles for these enhanced ceramic grades.
Buyers are consolidating magnetic component procurement under platform-level contracts that bundle ferrite rings, blocks, and arc segments into single-source agreements. Tier-one motor manufacturers are displacing fragmented spot purchasing with multi-year supply commitments indexed to EV production schedules. The behavioral shift is most visible in the Great Lakes manufacturing corridor where Dura Magnetics and Arnold Magnetic Technologies compete for integrated platform awards.
North America Ferrite Magnet Market Segmentation
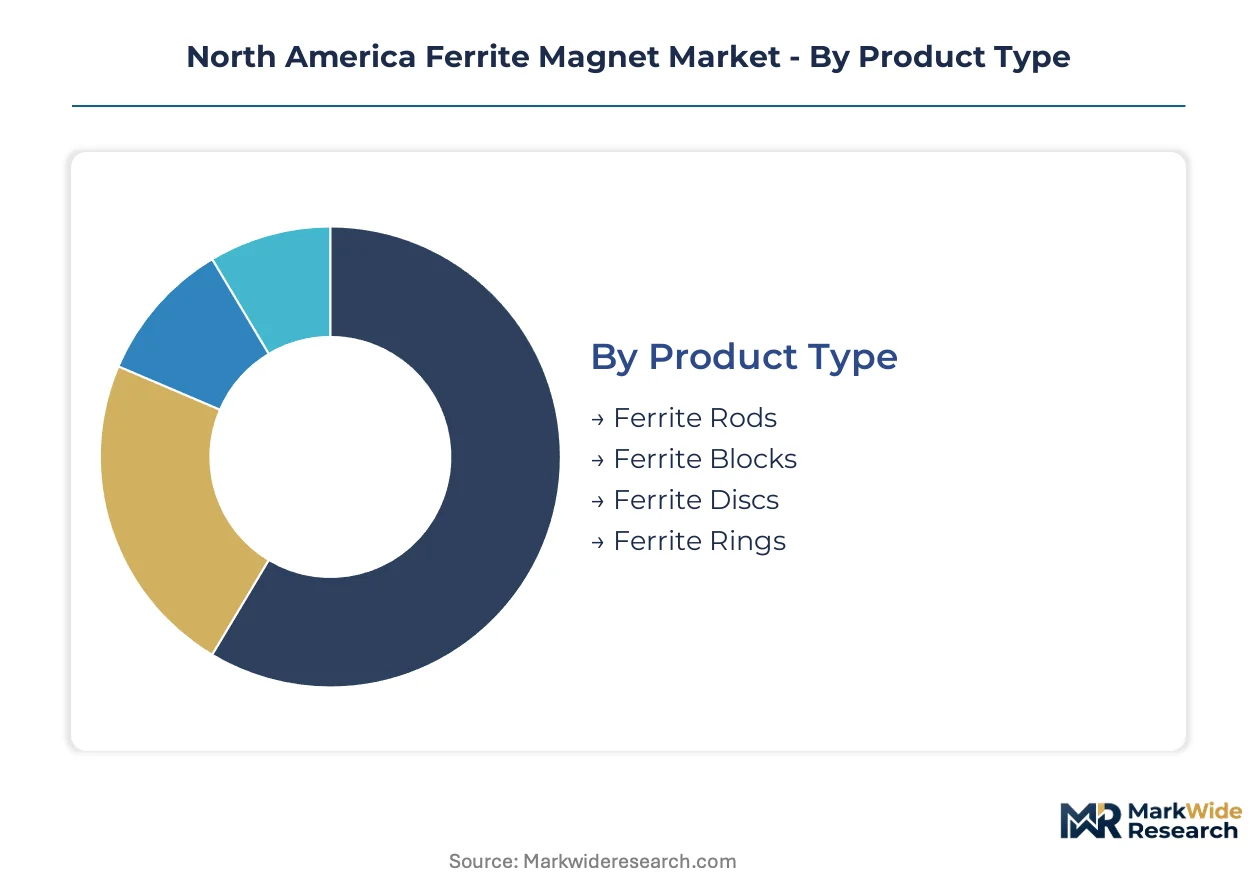
North American ferrite magnet procurement patterns diverge sharply across product geometry, end-use thermal requirements, and application-specific flux density thresholds. Buyers prioritize dimensional precision in motor assemblies, corrosion resistance in automotive underhood environments, and cost-per-magnetic-energy-unit in high-volume consumer electronics.
Product Type:
Geometric complexity in the buyer's motor assembly process determines which ferrite form factor commands procurement priority.
- Ferrite Blocks:Rectangular ceramic slabs with anisotropic grain alignment deliver magnetic energy products of 30-36 kJ/m³. Detroit-area EV motor manufacturers specify these for stator core assemblies where modular stacking reduces eddy current losses. The Great Lakes manufacturing corridor concentrates demand for high-volume block shipments.
- Ferrite Rings:Toroidal geometries with radial magnetization patterns minimize flux leakage in transformer cores and inductive chokes. Ontario-based power electronics suppliers source these for grid-tied inverter applications where toroidal winding efficiency outweighs unit cost premiums.
- Ferrite Rods:Cylindrical forms serve antenna cores and inductor applications across consumer electronics manufacturing clusters in Mexico's Baja California region.
- Ferrite Discs:Flat circular magnets support speaker assemblies and magnetic clamping fixtures throughout Midwest industrial automation supply chains.
Ferrite blocks lead on scale; ferrite rings lead on momentum.
End User:
Thermal operating envelopes and regulatory compliance burdens segment end-user procurement specifications across distinct certification tiers.
- Automotive:Underhood applications demand ferrite grades rated to 250°C with coercivity stability against thermal demagnetization. NHTSA electrification safety protocols mandate redundant magnetic isolation barriers in high-voltage architectures, expanding node counts per EV platform.
- Electronics:Consumer device manufacturers prioritize isotropic ferrite powders for cost-sensitive inductor and filter applications where moderate permeability suffices.
- Industrial:Factory automation systems specify arc-segment ferrites for servo motor rotors requiring precise angular positioning repeatability.
- Aerospace:Defense contractors source specialized ferrite formulations meeting MIL-STD-981 outgassing requirements for satellite attitude control systems.
Automotive commands procurement volume; aerospace commands specification premiums.
Application:
Flux path efficiency requirements and assembly automation compatibility shape application-level sourcing decisions.
- Sensors:Wheel-speed, position, and current-sensing nodes in ADAS architectures multiply magnetic component counts per vehicle platform. These applications demand tight dimensional tolerances and temperature-stable magnetic properties.
- Motor Components:Stator and rotor assemblies consume the largest ferrite volumes, with procurement consolidating under platform-level contracts indexed to EV production schedules.
- Transformers:Power conversion equipment relies on low-core-loss ferrite grades for switching frequencies above 100 kHz in renewable energy inverters.
- Magnetic Assemblies:Custom bonded ferrite configurations serve holding and lifting applications across material handling equipment manufacturers.
Motor components anchor volume demand; sensors demonstrate the steepest expansion trajectory.
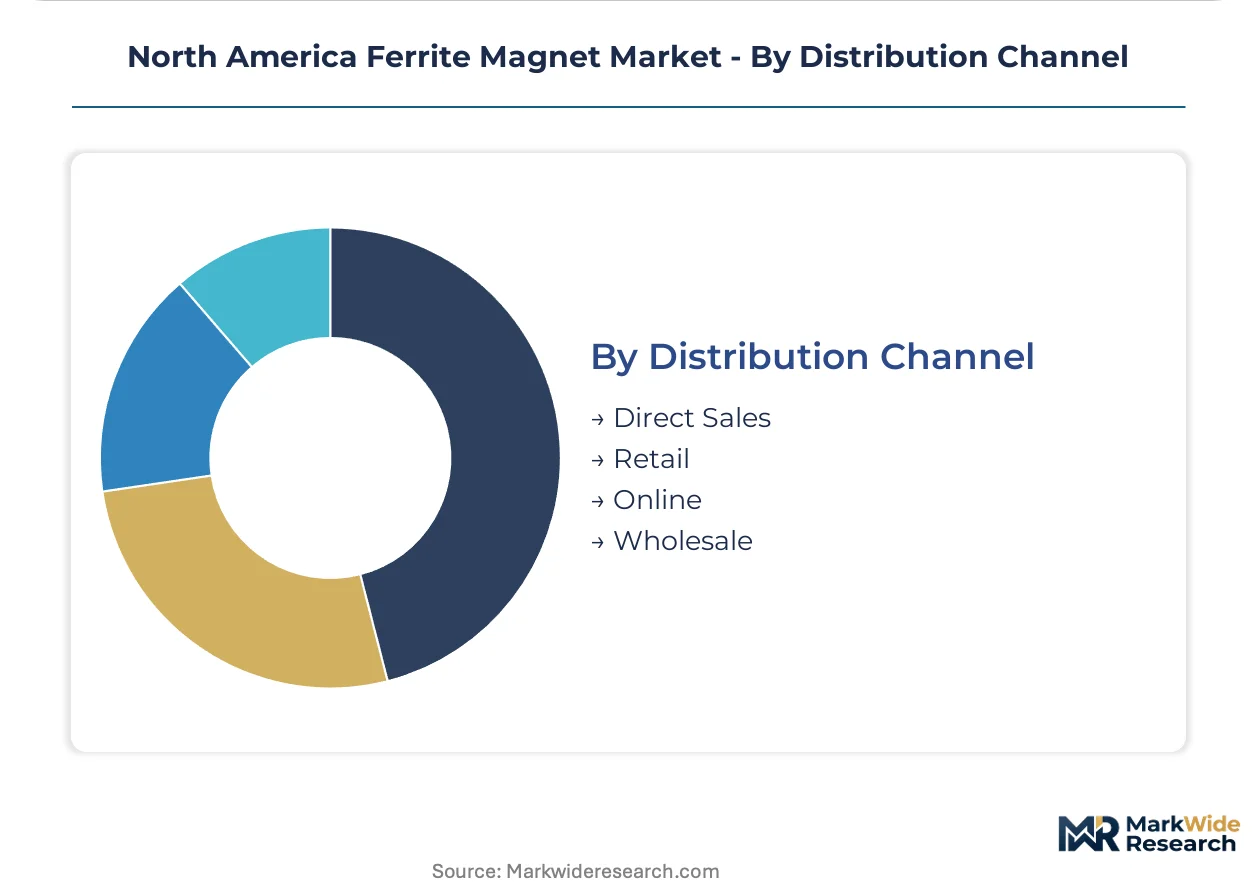
Distribution Channel:
Order size predictability and technical support requirements determine channel selection across buyer segments.
- Direct Sales:Tier-one automotive suppliers negotiate multi-year supply agreements with captive technical service support for qualification and failure analysis.
- Wholesale:Industrial distributors stock standard ferrite geometries for maintenance-repair-operations procurement across fragmented manufacturing customers.
- Online:E-commerce platforms serve prototype builders and small-batch electronics manufacturers requiring rapid sample turnaround.
- Retail:Limited specialty magnet retail presence targets educational and hobbyist segments with pre-packaged assortments.
Direct sales dominates contract value; wholesale captures transaction frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's critical minerals processing ambitions contrast with Mexico's electronics assembly export orientation, while the United States concentrates EV motor manufacturing and regulatory standard-setting. Each national market operates under distinct supply chain configurations and policy frameworks.
United States
EPA emissions rules and NHTSA efficiency mandates compress qualification timelines for ferrite suppliers serving electrified powertrain programs. The USMCA origin requirements incentivize regional sourcing for cross-border motor component shipments. The Great Lakes manufacturing corridor anchors EV motor production, with Detroit-area OEMs consolidating procurement under platform-level contracts.
Canada
Saskatchewan and Ontario deposits offer upstream integration potential for ferrite precursor supply security under USMCA frameworks. Health Canada and Environment and Climate Change Canada administer chemical screening programs that parallel EPA substance restrictions. Ontario-based power electronics suppliers concentrate demand for toroidal ferrite rings in grid-tied inverter applications.
Mexico
Baja California electronics manufacturing clusters source cylindrical ferrite rods for antenna cores and inductor applications across consumer device supply chains. The Secretariat of Economy implements industrial policy supporting maquiladora operations that feed North American automotive and electronics value chains. Mexico City Metro and Nuevo León host expanding automotive component operations qualifying regional ferrite sources for USMCA compliance.
North America Ferrite Magnet Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the North American ferrite magnet supply base. The market structure exhibits moderate consolidation, with tier-one automotive suppliers commanding multi-year supply agreements while smaller fabricators serve maintenance-repair-operations channels. Strategic archetypes include proximity-based just-in-time suppliers, formulation specialists for high-temperature applications, and rare-earth hybrid competitors redirecting select demand. Dominant competitive moves center on geographic expansion toward the Great Lakes corridor and portfolio diversification into bonded ferrite configurations.
Among Midwest-based specialists, Dura Magnetics and Arnold Magnetic Technologies occupy positions within the automotive supply tier, while Electron Energy Corporation exemplifies the rare-earth alternative archetype competing for sensor and actuator applications. These named entities anchor distinct competitive vectors without exhaustively representing the full supplier base.
| Leading Market Players |
|---|
| Dura Magnetics |
| Electron Energy Corporation |
| Arnold Magnetic Technologies |
| Honeywell International |
| Stanford Magnets |
| Integrated Magnetics |
| Master Magnetics |
| MainRich Magnets |
| Dexter Magnetic Technologies |
| Others |
Cost & Logistics Intelligence
Tier-one EV motor manufacturers in the Great Lakes corridor concentrate procurement under multi-year platform contracts, anchoring North American ferrite magnet pricing to automotive production schedules rather than spot commodity dynamics. This buyer concentration compresses margin structures for suppliers lacking captive precursor processing or USMCA-qualifying origin status.
Pricing Analysis
Capacity additions in the US Midwest are reshaping price floors for sintered ferrite blocks as Dura Magnetics and Arnold Magnetic Technologies expand press-and-sinter infrastructure near Detroit OEM assembly plants. Contract-based long-term offtake dominates, with price differentiation resting on thermal grade certification and proximity-to-plant delivery guarantees. Cost compression in standard-grade blocks is intensifying because tier-two suppliers are qualifying isotropic powder injection molding for auxiliary motor applications. Small-batch electronics manufacturers exhibit highest price sensitivity, while aerospace defense contractors absorb premiums for MIL-STD-981 qualified formulations.
Supply Chain Analysis
Dual-sourcing requirements from NHTSA-qualified automotive suppliers mandate ferrite producers maintain redundant precursor streams and geographically distributed pressing capacity. Geographic supply concentration centers on the United States for finished magnet fabrication, Canada for strontium carbonate precursor potential, and China for refined iron oxide feedstock. Raw material dependencies include strontium carbonate, barium carbonate, and high-purity iron oxide powders. Tariff exposure on Chinese-origin oxide imports creates margin volatility for non-integrated producers. Distribution runs through direct sales channels for tier-one automotive contracts and wholesale distributors for maintenance-repair-operations procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in North American ferrite magnets rests on upstream integration into Canadian critical minerals processing and premium-tier qualification for NHTSA electrification safety protocols. Cost-down drivers include isotropic powder injection molding adoption and USMCA origin compliance reducing tariff exposure.
For Market Incumbents: Deploy backward integration into Saskatchewan strontium carbonate deposits to secure precursor supply and qualify for USMCA content requirements. Incumbent suppliers must accelerate high-temperature formulation R&D as NHTSA mandates redundant magnetic isolation barriers above 200°C operating thresholds. Arnold Magnetic Technologies and Dura Magnetics should consolidate platform-level contract awards before tier-two powder injection molders achieve full automotive qualification. For New Entrants and Emerging Players: Enter via isotropic ferrite powder injection molding for non-critical auxiliary motor applications where capital barriers to press-and-sentry infrastructure exclude established competitors. The most penetrable white-space sits in distributed production nodes serving tier-two automotive suppliers outside traditional Great Lakes magnet manufacturing clusters. A precision-focused go-to-market angle targeting wheel-speed sensor modules for ADAS architectures bypasses direct competition with block-volume incumbents. For Investors and Strategic Acquirers: Tier-one automotive suppliers are the most active acquirer in this space, seeking captive magnet supply for EV platform security. Long-term viability favors producers with dual capability across sintered anisotropic blocks and bonded isotropic configurations. Acquisition target archetypes include Canadian critical minerals processors with strontium carbonate reserves and powder metallurgy specialists with automotive qualification pathways. The signal to watch is NHTSA publication of final electrification safety protocol thermal specifications, which will trigger accelerated qualification cycles for 250°C-rated formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Canadian Critical Minerals | Saskatchewan strontium deposits reduce import dependence and secure USMCA origin compliance for automotive contracts. |
| High-Temperature Formulation Development | NHTSA electrification protocols mandate 200°C-plus coercivity stability, creating premium tier qualification windows. |
| Isotropic Powder Injection Molding Scale-Up | Distributed production nodes compress minimum efficient scale and open tier-two supplier entry points. |
| Platform-Level Contract Consolidation | Multi-year supply agreements indexed to EV production schedules displace fragmented spot purchasing. |
| Dual-Source Precursor Qualification | Redundant strontium carbonate streams mitigate tariff exposure and satisfy automotive supplier audit requirements. |
Research Approach
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market triangulated against secondary validation. Primary interviews engaged tier-one automotive supplier procurement directors, EV platform engineers, ferrite plant operations managers, and powder metallurgy technical directors. Secondary sources included USMCA trade flow databases, EPA hazardous substance screening filings, NHTSA motor-vehicle safety standard dockets, and SEC 10-K disclosures from diversified magnet producers. Bottom-up volume modeling across product geometries and end-use segments was reconciled with top-down market sizing from automotive production forecasts and electronics import data.
Rate-of-change decomposition isolated volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end-user thermal requirements, application flux density thresholds, and distribution channel structure. CAGRs were derived from regression analysis against EV production schedules and ADAS sensor penetration curves. Industry-specific forecast inputs incorporated NHTSA regulatory timeline assumptions and USMCA origin compliance thresholds for cross-border motor component shipments.
Inputs from EPA, NHTSA, and USMCA administrative records were available through the study window; gaps in real-time strontium carbonate spot pricing and confidential automotive supplier contract terms introduce uncertainty bands around margin structure projections. Deviation in NHTSA electrification safety protocol implementation timing or Canadian critical minerals processing investment commitments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Ferroboron Market
Magnetic Materials
North America Samarium Cobalt Magnets Market
Magnetic Materials
North America Magnet Wire Market
Magnetic Materials
Nanocrystalline Soft Magnetic Material Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
Ferrite Magnet Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
Carbonyl Iron Powder Market
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Neodymium [Nd-Fe-B] Magnet Market
Magnetic Materials
Neodymium-Iron-Boron Magnet Market
Magnetic Materials
Plastic Bonded Magnet Market