
 Europe Ferrite Magnet Market | 2026-2036
Europe Ferrite Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ferrite Magnet Market Intelligence
The gap between sintered and bonded ferrite manufacturing cost is narrowing as European producers automate pressing and calcination lines. VACUUMSCHMELZE leverages its precision magnet expertise to dominate high-tolerance segments for automotive sensors. Rheinmagnet sustains competitive positioning through backward integration into oxide powder preparation. Goudsmit Magnetics specializes in magnetic assembly integration, extending value capture beyond raw magnet supply.
Europe ferrite magnets are ceramic compounds of iron oxide combined with barium or strontium carbonate, sintered at temperatures exceeding 1,200°C to achieve coercivity values of 150-300 kA/m and maximum energy products of 10-40 kJ/m³, serving primarily as cost-efficient permanent magnets in motors, speakers, and magnetic separators. Hard ferrite occupies the mature volume base across automotive components and industrial motors, where specifications standardize and price competition intensifies. Soft ferrite segments in consumer electronics power supplies retain stronger margin pools due to frequency performance requirements and tighter ferrite core tolerances. Bonded ferrite formulations in magnetic assemblies represent the fastest-growing structural category, driven by geometric flexibility in injection-molded sensor housings and rotor designs.
REACH compliance through ECHA governs chemical substance registration for strontium and barium precursors, while RoHS directives restrict hazardous substance content in electronics applications, collectively elevating material traceability costs for non-compliant imports. The EU Green Deal carbon border adjustments are reshaping sourcing economics, favoring European calcination and sintering operations with verified emissions profiles. Stakeholders must monitor evolving CSRD disclosure requirements and embedded carbon accounting rules to maintain contract eligibility with tier-one automotive and industrial OEMs.
Market Dynamics
EU Green Deal carbon border adjustments are compressing import economics for Asian calcined ferrite powders, forcing European motor manufacturers toward regional sintering operations with auditable emissions profiles.
Growth Catalysts
- F-Gas Regulation phase-down:Refrigeration motor manufacturers in Germany and France are substituting rare-earth permanent magnets with ferrite alternatives to eliminate synthetic refrigerant dependencies in compressor designs.
- Strontium ferrite powder automation:European producers deploying robotic pressing lines are narrowing the cost gap against bonded ferrite imports from Southeast Asia.
- Electric power steering penetration:German tier-one automotive suppliers are expanding ferrite magnet procurement for torque sensor modules and brushless DC motor assemblies.
Market Restraints
- Strontium carbonate price volatility:Supply concentration in Chinese carbonate refining creates input cost instability for European oxide preparation facilities.
- Energy-intensive sintering economics:Natural gas and electricity tariffs in Italy and Spain are elevating calcination costs versus Asian competitors with coal-fired kiln operations.
- Performance ceiling in high-torque motors:Ferrite maximum energy products of 10-40 kJ/m³ cap substitution potential in traction motor applications above 50 kW.
Strategic Opportunities
- CSRD disclosure mandates:Embedded carbon accounting rules are creating contract eligibility advantages for European magnet producers with verified Scope 3 emissions data.
- Injection-molded bonded ferrite:Geometric flexibility in sensor housings and custom rotor designs is opening white space in medical device and robotics actuator segments.
- Poland and Czech Republic industrial motor clusters:Underpenetrated assembly operations in Central Europe offer expansion targets for magnetic assembly integrators.
Industry Challenges
- REACH substance registration timelines:ECHA documentation requirements for barium and strontium precursor variants are extending new material qualification cycles by 12-18 months.
- Precision grinding skill scarcity:Tolerance requirements below 50 microns for automotive sensor magnets face workforce pipeline constraints in European machining trades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ferrite Magnet Market |
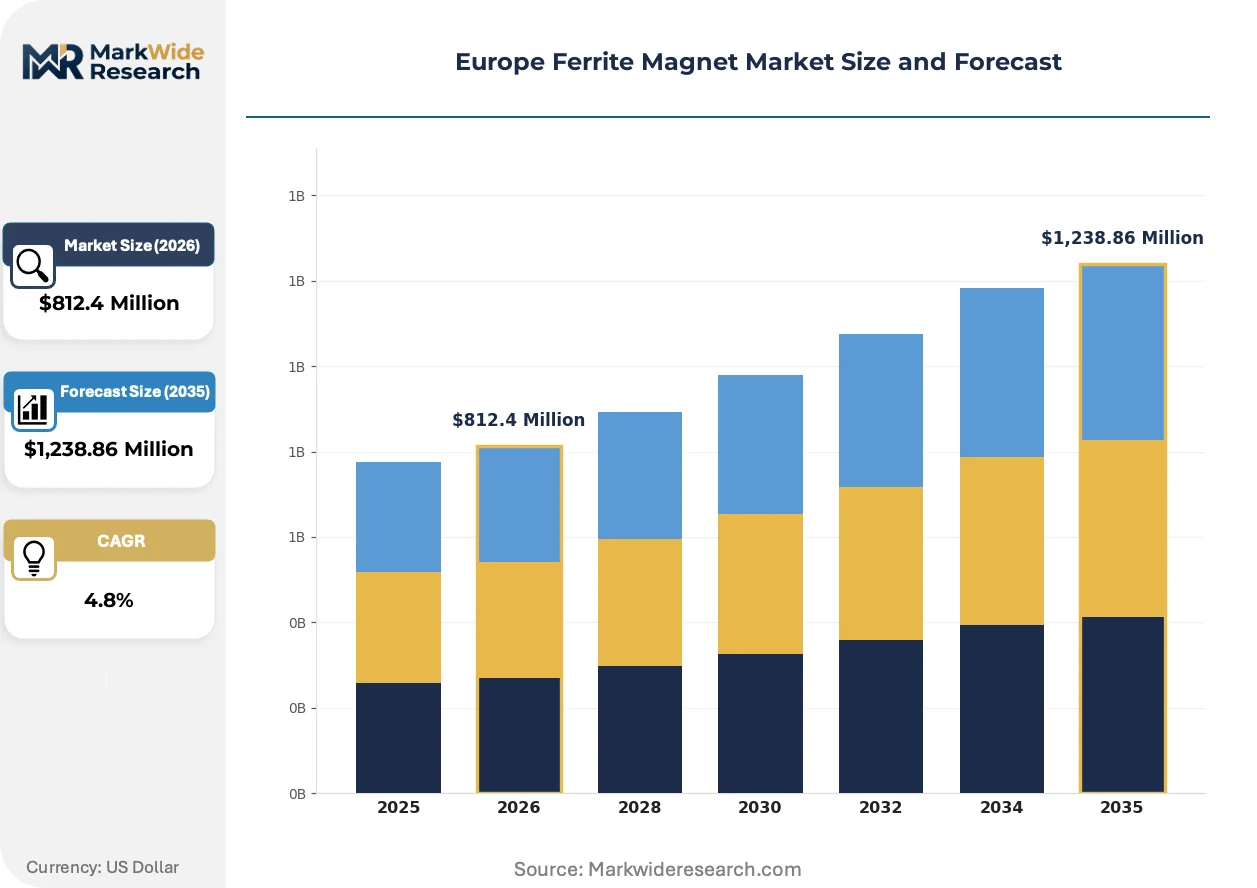
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,238.86 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Ferrite, Soft Ferrite, Bonded Ferrite, Composite Ferrite Application: Automotive Components, Industrial Motors, Consumer Electronics, Magnetic Assemblies End User: Manufacturers, Distributors, Retailers, Repair Services Distribution Channel: Online Sales, Direct Sales, Wholesale, Storefront |
| Companies Covered | VACUUMSCHMELZE, Magnosphere, Rheinmagnet, MainRich Magnets, Eclipse Magnetics, Newland Magnetics Europe, Calamit, TDK Corporation, Goudsmit Magnetics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ferrite Magnet Market Strategic Shifts & Innovations
Process instrumentation and quality control systems are undergoing fundamental restructuring as European ferrite producers compete on dimensional consistency rather than commodity volume.
Multi-axis CNC grinding with in-line laser measurement is digitizing tolerance verification for automotive sensor-grade ferrite rings. Bosch and Continental procurement teams are mandating 100% dimensional traceability for EPS motor magnets. Real-time feedback loops are compressing rejection rates and enabling zero-defect supply contracts that were previously uneconomical at ferrite price points.
EU F-Gas Regulation amendments are accelerating magnet material substitutions in hermetic compressor motors for commercial refrigeration. The 2024 phase-down quotas for hydrofluorocarbons are forcing equipment OEMs to redesign motor efficiency around ferrite-based solutions that tolerate wider thermal envelopes. Italian refrigeration manufacturers are leading this transition, with test protocols now standardizing ferrite performance validation at elevated ambient temperatures.
Automotive tier-one suppliers are consolidating magnet procurement through approved vendor lists with embedded carbon disclosure requirements. Long-term agreements now specify Scope 3 emissions thresholds for sintered ferrite, displacing spot-market purchasing for power steering and sensor applications. German OEMs are enforcing these clauses most aggressively, with qualification penalties for suppliers lacking EPD-verified production data.
Europe Ferrite Magnet Market Segmentation
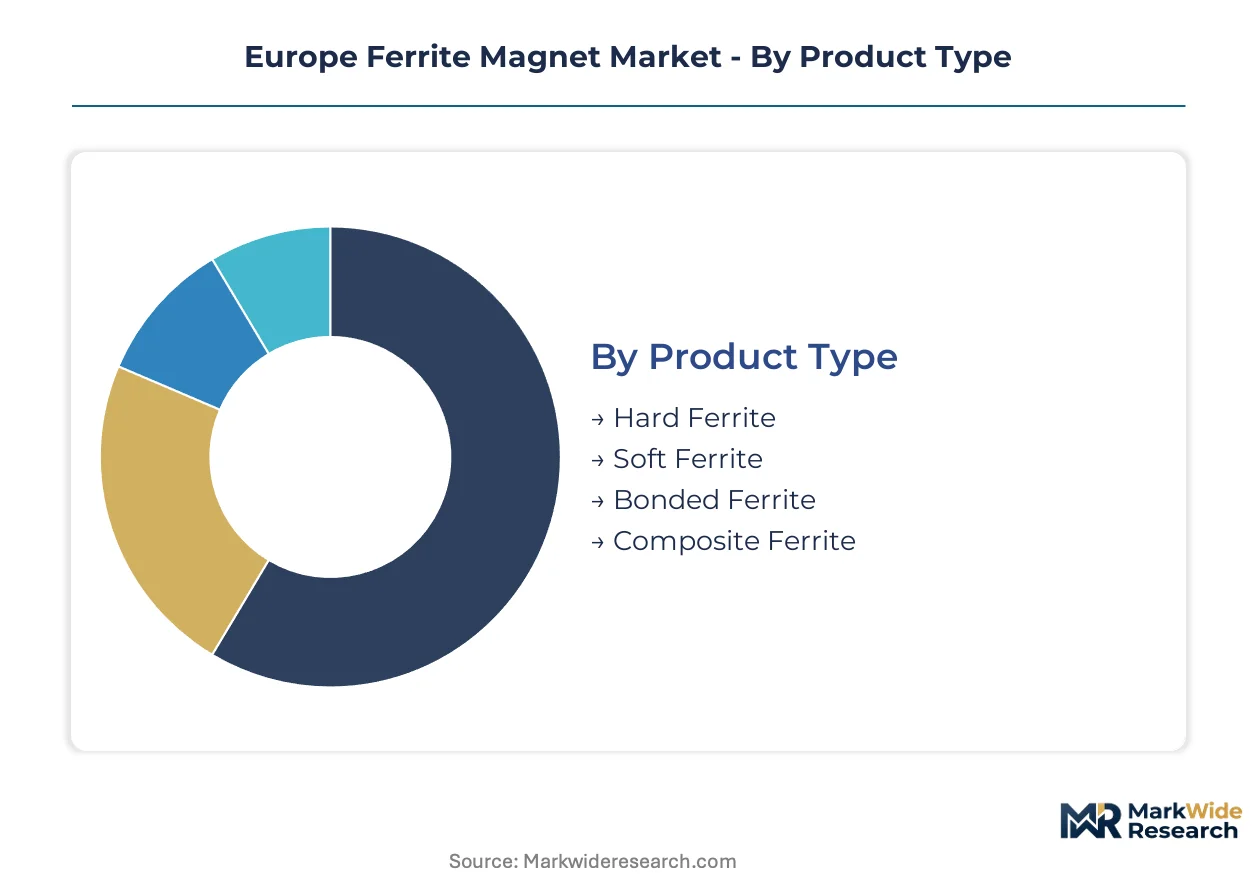
Segmentation reveals how ferrite magnet value pools split across material grades, application engineering requirements, and procurement channel economics. Each dimension carries distinct margin structures and regulatory exposure profiles that reshape supplier positioning.
Product Type:
Cost tier differentiation separates commodity volume from precision-grade premium positioning across European production bases.
- Hard Ferrite:Ceramic compounds of iron oxide with barium or strontium carbonate, sintered above 1,200°C to achieve coercivity of 150-300 kA/m. German automotive suppliers anchor procurement for electric power steering modules, though energy-intensive calcination faces margin pressure from Italian and Spanish natural gas tariffs.
- Soft Ferrite:Manganese-zinc and nickel-zinc formulations optimized for high-frequency magnetic flux with minimal hysteresis loss. Consumer electronics power supplies in France and the Netherlands concentrate demand, where RoHS compliance and ferrite core tolerance specifications sustain stronger margin pools than commodity hard ferrite.
- Bonded Ferrite:Polymer-bonded powder formulations enabling injection-molded geometries for sensor housings and custom rotors.
- Composite Ferrite:Hybrid material systems combining ferrite with elastomer or thermoplastic matrices for vibration-damping applications.
Hard ferrite commands the established base. The steepest expansion runs through bonded ferrite.
Application:
Application segmentation tracks how EU Green Deal carbon accounting and F-Gas Regulation phase-downs redirect magnet procurement across end-use sectors.
- Automotive Components:Torque sensor modules, brushless DC motor assemblies, and electric power steering systems requiring dimensional tolerances below 50 microns. Bosch and Continental procurement teams in Germany mandate 100% dimensional traceability, compressing rejection rates through multi-axis CNC grinding with in-line laser measurement.
- Industrial Motors:Standardized specifications and price competition dominate hermetic compressor motors for commercial refrigeration, where Italian manufacturers lead ferrite substitution to eliminate synthetic refrigerant dependencies under F-Gas phase-down quotas.
- Consumer Electronics:Power supply inductors and transformers in frequency-sensitive applications.
- Magnetic Assemblies:Integrated magnetic systems for separation, sensing, and holding applications.
Industrial motors anchor volume throughput. Automotive components deliver the sharpest margin expansion.
End User:
Customer type segmentation exposes how CSRD disclosure mandates and Scope 3 emissions thresholds reshape contract eligibility across procurement hierarchies.
- Manufacturers:Tier-one automotive and industrial OEMs consolidating magnet procurement through approved vendor lists with embedded carbon disclosure requirements. German OEMs enforce EPD-verified production data most aggressively, displacing spot-market purchasing with long-term agreements specifying emissions thresholds.
- Distributors:Intermediary stocking points serving fragmented industrial motor repair and replacement demand.
- Retailers:Small-volume outlets for consumer electronics accessories and hobbyist applications.
- Repair Services:Aftermarket maintenance providers sourcing replacement magnets for motor refurbishment.
Manufacturers dominate contract value. Distributors capture the broadest geographic reach.
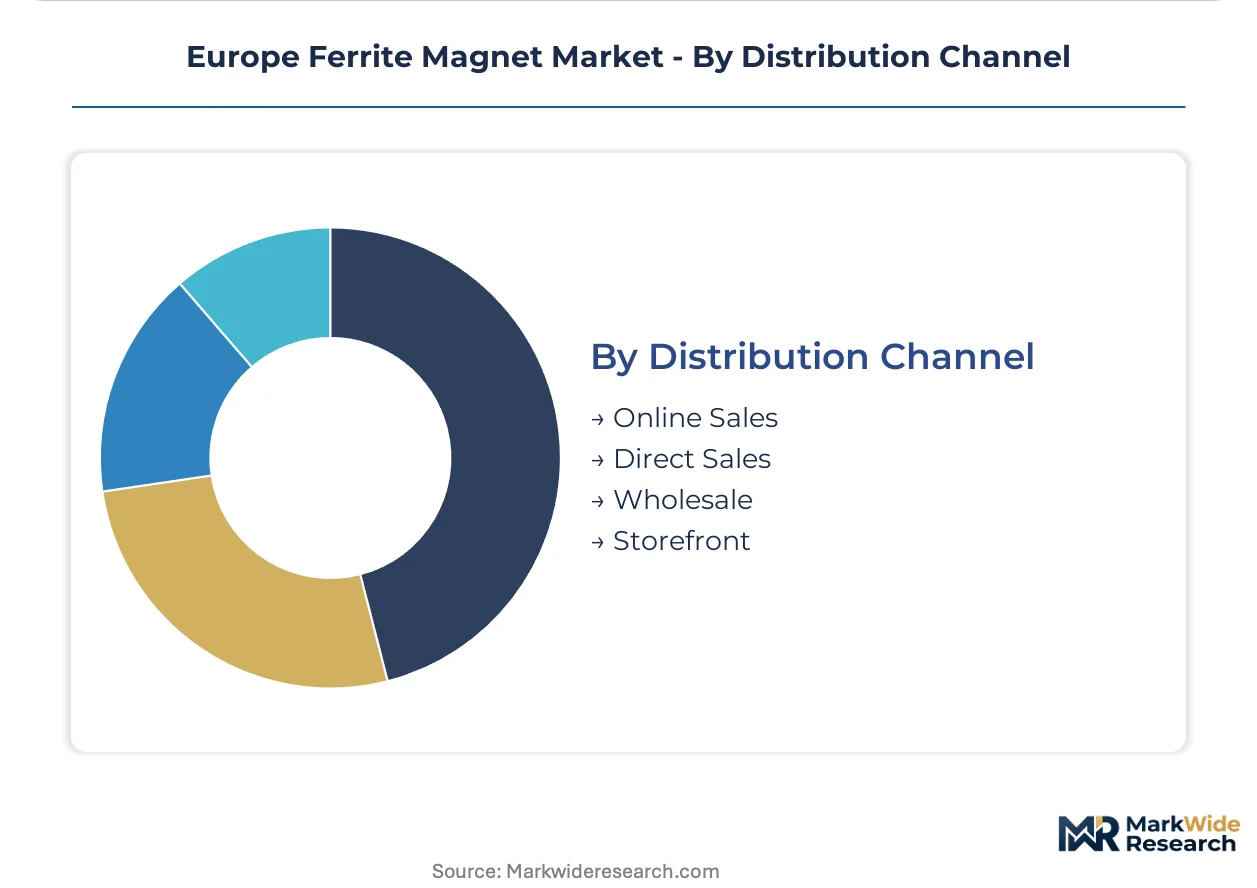
Distribution Channel:
Channel economics reflect how REACH substance registration timelines and material traceability costs filter through procurement system architectures.
- Direct Sales:Long-term supply agreements between European calcination operators and automotive tier-ones, favored by EU Green Deal carbon border adjustments that compress import economics for Asian calcined powders. Auditable emissions profiles and verified Scope 3 data secure contract eligibility.
- Wholesale:Bulk intermediation for standardized hard ferrite grades serving industrial motor clusters in Poland and the Czech Republic.
- Online Sales:E-commerce platforms for specification-grade bonded ferrite in low-volume prototyping and medical device development.
- Storefront:Physical distribution points for immediate-need replacement inventory.
Direct sales lock the highest-value relationships. Online channels are climbing fastest in specification-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive tier-ones concentrate the highest-value procurement contracts, while Italian and Polish industrial motor clusters absorb standardized volume. French consumer electronics manufacturers and Dutch magnetic assembly integrators complete the buyer landscape.
Germany
Bosch and Continental procurement teams drive ferrite magnet demand for electric power steering modules and torque sensors. The EU Green Deal carbon border adjustments favor domestic calcination operations with auditable emissions profiles. Stuttgart and Munich anchor automotive sensor-grade magnet consumption, where multi-axis CNC grinding with in-line laser measurement compresses rejection rates.
Italy
Commercial refrigeration manufacturers substitute ferrite magnets for rare-earth alternatives under F-Gas Regulation phase-down quotas. REACH substance registration timelines through ECHA extend new material qualification cycles for barium and strontium precursors. Northern industrial motor clusters around Milan and Turin lead test protocol standardization for elevated ambient temperature performance.
France
Consumer electronics power supply manufacturers concentrate demand for manganese-zinc and nickel-zinc soft ferrite cores. RoHS directives restrict hazardous substance content, elevating material traceability costs for non-compliant imports. The Paris-Saclay electronics corridor sustains stronger margin pools through frequency performance requirements and tighter ferrite core tolerances.
Poland
Underpenetrated industrial motor assembly operations offer expansion targets for magnetic assembly integrators seeking Central European proximity. CSRD disclosure mandates reshape contract eligibility, favoring suppliers with verified Scope 3 emissions data. The Silesian and Łódź manufacturing belts attract wholesale distribution channels for standardized hard ferrite grades.
Netherlands
Magnetic assembly integrators extend value capture beyond raw magnet supply through system-level design services. The Eindhoven high-tech ecosystem specializes in sensor housing integration for medical device and robotics actuator segments. Dutch operations leverage geometric flexibility in injection-molded bonded ferrite formulations to serve prototyping and low-volume specification-grade demand.
Europe Ferrite Magnet Market Key Industry Players
Channel-controlling players compete with product-specialist players across a moderately consolidated structure. German and Japanese-origin entities anchor high-tolerance automotive segments, while regional European fabricators capture industrial motor volume through backward integration into oxide powder preparation. Two strategic archetypes dominate: precision-grade specialists serving tier-one automotive qualification requirements, and cost-optimized volume producers supplying standardized motor applications. Competitive moves concentrate on geographic expansion toward Central European industrial clusters and portfolio diversification into bonded ferrite formulations for sensor integration.
Among Germany-based precision magnet specialists, VACUUMSCHMELZE and Rheinmagnet occupy positions at opposite ends of the integration spectrum. VACUUMSCHMELZE exemplifies the high-tolerance archetype for automotive sensor applications, while Rheinmagnet represents backward-integrated oxide preparation capabilities. Goudsmit Magnetics, with Dutch origins, anchors the magnetic assembly integration tier, extending value capture through system-level design rather than commodity magnet supply alone.
| Leading Market Players |
|---|
| VACUUMSCHMELZE |
| Magnosphere |
| Rheinmagnet |
| MainRich Magnets |
| Eclipse Magnetics |
| Newland Magnetics Europe |
| Calamit |
| TDK Corporation |
| Goudsmit Magnetics |
| Others |
Cost & Logistics Intelligence
Chinese strontium carbonate refining concentration anchors input cost instability for European oxide preparation facilities, compressing margin pools at the calcination tier while precision-grade automotive sensor magnets retain pricing power through dimensional traceability mandates.
Pricing Analysis
Cost-plus contracts with strontium carbonate indexation dominate procurement between European sintering operations and automotive tier-ones. Price differentiation rests on certification grade and volume scale, with EPD-verified production data commanding premiums from German OEMs. Cost compression in commodity hard ferrite is intensifying due to energy tariff disparities with Asian coal-fired kiln competitors. Industrial motor manufacturers exhibit highest price sensitivity, while automotive sensor-grade buyers prioritize zero-defect supply contracts over unit economics.
Supply Chain Analysis
Supply-chain finance facilities with extended payment terms have become standard between European magnetic assembly integrators and their distributor networks. Raw material sourcing draws from Chinese strontium carbonate refineries, Spanish and Italian natural gas-dependent calcination operations, and German precision grinding facilities. Single-source vulnerability in carbonate refining creates structural exposure to input cost spikes. Distribution runs through direct sales channels for automotive qualification programs and wholesale intermediation for standardized industrial motor clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic assembly integration services and carbon accounting verification represent faster-expanding revenue layers than raw magnet supply, creating service-attach opportunities for suppliers embedding EPD certification and sensor housing design into long-term contracts.
For Market Incumbents: Harden contract eligibility through captive oxide powder preparation and EPD-verified Scope 3 emissions data to defend against Asian calcined powder imports compressed by EU Green Deal carbon border adjustments. Expand multi-axis CNC grinding capacity in Stuttgart and Munich corridors to capture automotive sensor-grade demand with 100% dimensional traceability requirements. For New Entrants and Emerging Players: Central European industrial motor clusters in Poland and the Czech Republic represent the most penetrable entry point for wholesale distribution of standardized hard ferrite grades. Injection-molded bonded ferrite for medical device sensor housings offers specification-grade positioning with lower capital intensity than sintering operations. Partner with Dutch magnetic assembly integrators for system-level design capabilities that extend value capture beyond commodity supply. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision grinding specialists serving German automotive tier-ones. Long-term viability over a 5-10 year horizon hinges on carbon accounting infrastructure and geometric flexibility in bonded formulations. Watch for F-Gas Regulation phase-down acceleration as the inflection signal for refrigeration motor substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oxide Powder Preparation | Rheinmagnet's captive strontium ferrite production insulates margins from Chinese carbonate volatility. |
| EPD-Verified Carbon Accounting Infrastructure | German OEM procurement teams now mandate auditable Scope 3 emissions data for contract eligibility. |
| Multi-Axis CNC Grinding Capacity Expansion | Bosch and Continental require sub-50-micron tolerances with 100% dimensional traceability for EPS magnets. |
| Injection-Molded Bonded Ferrite Formulation Development | Goudsmit Magnetics leverages geometric flexibility to serve medical device and robotics prototyping demand. |
| Central European Distribution Network Buildout | Polish and Czech industrial motor clusters remain underpenetrated by magnetic assembly integrators. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interviews with automotive tier-one procurement managers, industrial motor plant engineers, magnetic assembly technical directors, and ECHA regulatory affairs specialists. Secondary validation drew from EU customs trade data, ECHA REACH registration databases, SEC filings of listed magnet producers, and Cefic chemical industry reports. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and end-user segments.
Calibration against historical production data and disclosed capacity expansions anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material grade tier, automotive versus industrial end-use, and direct versus wholesale channel economics. CAGRs were derived from regression analysis of disclosed revenue trajectories and capacity utilization trends. Key inputs encompassed natural gas tariff forecasts for Italian and Spanish calcination operations and F-Gas Regulation phase-down quota schedules.
Practitioners should monitor strontium carbonate price volatility and EU carbon border adjustment implementation timing for early signals of sourcing economics shifts. Forecasts reflect assumptions regarding automotive electrification penetration and refrigeration motor redesign timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
High Performance Magnet Market
Magnetic Materials
Global Electrical Steel Sheet Market
Magnetic Materials
North America Magnet Wire Market
Magnetic Materials
Magnet Buffer Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Global Soft Magnetic Alloys Market
Magnetic Materials
Europe Copper Magnetic Wire Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Magnet Market
Magnetic Materials
Global Iron Powder Market
Magnetic Materials
Reduced Iron Powder Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Magnetic Materials Market
Magnetic Materials
Flux Field Directional Material Market
Magnetic Materials
Ferrite Magnet Market