
 Global Non Grain-Oriented Electrical Steel Market | 2026-2036
Global Non Grain-Oriented Electrical Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non Grain-Oriented Electrical Steel Market Foresight
Direct mill-to-OEM supply agreements is narrowing the role of traditional steel distributors in non grain-oriented electrical steel procurement. ArcelorMittal leverages its European flat-rolled network to sustain captive supply relationships with major motor manufacturers. POSCO anchors high-volume coil production for Asian appliance and automotive electrification programs. Nippon Steel Corporation differentiates through ultra-thin gauge R&D leadership serving precision magnetic device applications.
Non grain-oriented electrical steel is a low-carbon silicon-alloyed ferromagnetic material, typically containing 0.5% to 3.5% silicon, manufactured through continuous cold rolling and continuous annealing to achieve isotropic magnetic properties in all planar directions. Its primary commercial purpose is to minimize hysteresis and eddy current losses in rotating electrical machines and static magnetic components where the magnetic flux direction varies during operation. Coated steel variants command premium positioning due to interlaminar insulation requirements in high-frequency inverter-fed motors, while cold rolled and annealed grades dominate volume throughput for standard-efficiency industrial motors. The renewable energy sector end-user category represents the fastest-growing demand pool as wind turbine generator OEMs specify higher silicon grades for improved partial-load efficiency.
The US Department of Energy appliance efficiency standards, China's GB standards administered by SAMR, and the EU Ecodesign framework collectively mandate tighter core loss thresholds that force steel mills to reformulate alloy chemistry and annealing profiles. Japan's METI enacts Top Runner standards that effectively block lower-efficiency electrical steel imports from non-compliant origins. Stakeholders must monitor divergence between regional efficiency test protocols and certification reciprocity agreements to avoid stranded inventory in cross-border supply chains.
Market Dynamics
Electric vehicle motor manufacturers are consolidating procurement around direct mill-to-OEM supply agreements, compressing traditional steel distributor margins while demanding tighter alloy chemistry tolerances from silicon-alloyed ferromagnetic suppliers.
Growth Catalysts
- EU F-Gas Regulation:The framework mandates tighter energy-efficiency standards for core materials in rotating electrical machines, forcing motor OEMs to specify higher silicon grades.
- Wind turbine generator demand:Renewable energy sector procurement of non grain-oriented electrical steel for improved partial-load efficiency is accelerating across East Asian manufacturing clusters.
- China's dual carbon goals:SAMR-administered GB standards are tightening core loss thresholds that require steel mills to reformulate annealing profiles for domestic appliance and automotive electrification programs.
Market Restraints
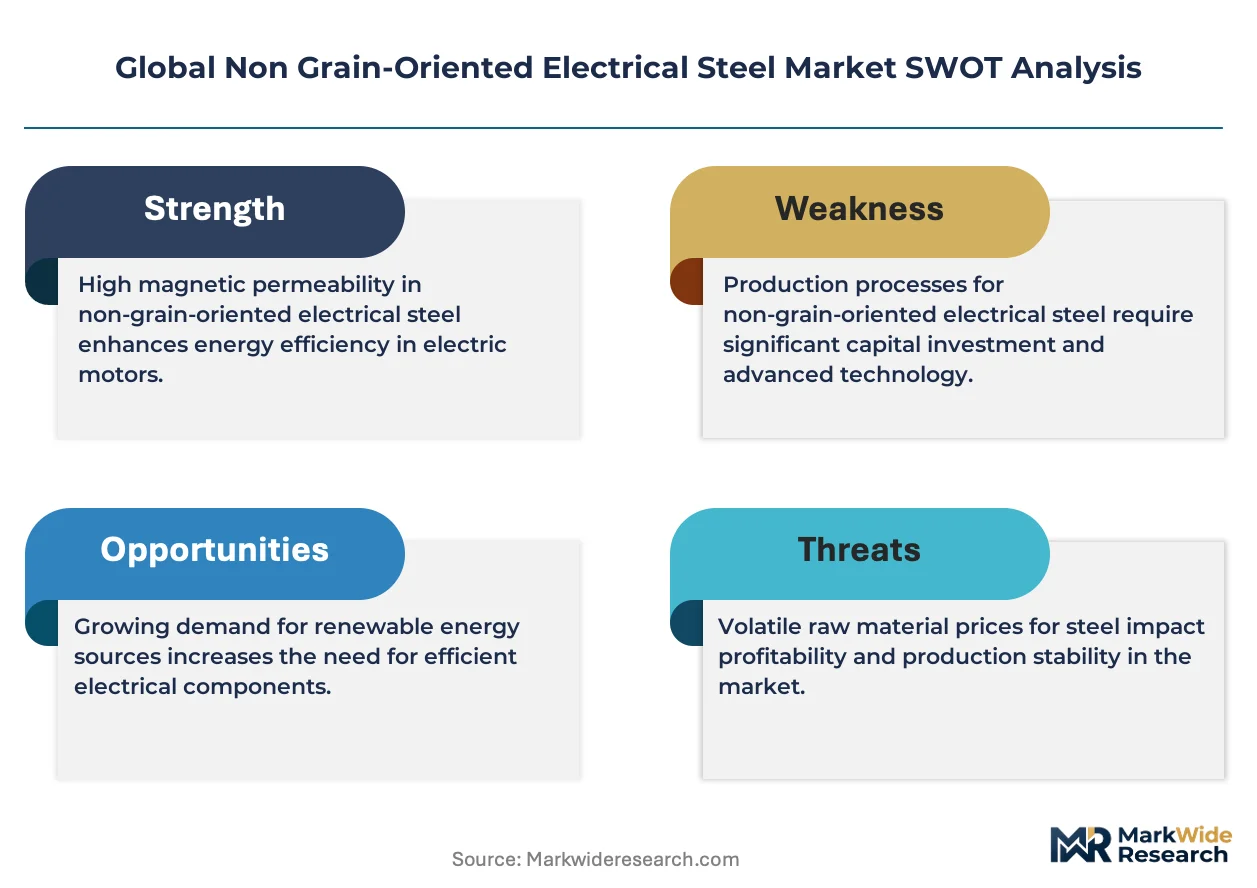
- Silicon input cost volatility:Ferrosilicon alloy pricing fluctuations compress mill margins on standard-efficiency grades where pass-through clauses remain weak.
- East Asian supply concentration:Coil production gravity around Shanghai and Busan exposes procurement chains to port congestion and regional logistics disruptions.
- Technical thickness floor:Ultra-thin gauge rolling below 0.20mm remains constrained by annealing line speed limitations and yield loss penalties.
Strategic Opportunities
- India appliance motor localization:BIS efficiency labeling expansion and PLI scheme incentives for domestic manufacturing create white space for high-silicon grade supply.
- High-frequency inverter-fed motors:Coated steel variants with interlaminar insulation properties command premium positioning in precision magnetic device applications.
- US IRA clean energy provisions:Domestic content bonuses for wind and solar components incentivize North American mill capacity expansion for generator-grade material.
Industry Challenges
- Metallurgical talent scarcity:Continuous annealing process engineers with magnetic property optimization expertise are concentrated among incumbent Asian mills.
- Reciprocity certification friction:Divergence between Japan's METI Top Runner test protocols and EU Ecodesign efficiency verification creates stranded inventory risk in cross-border supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non Grain-Oriented Electrical Steel Market |
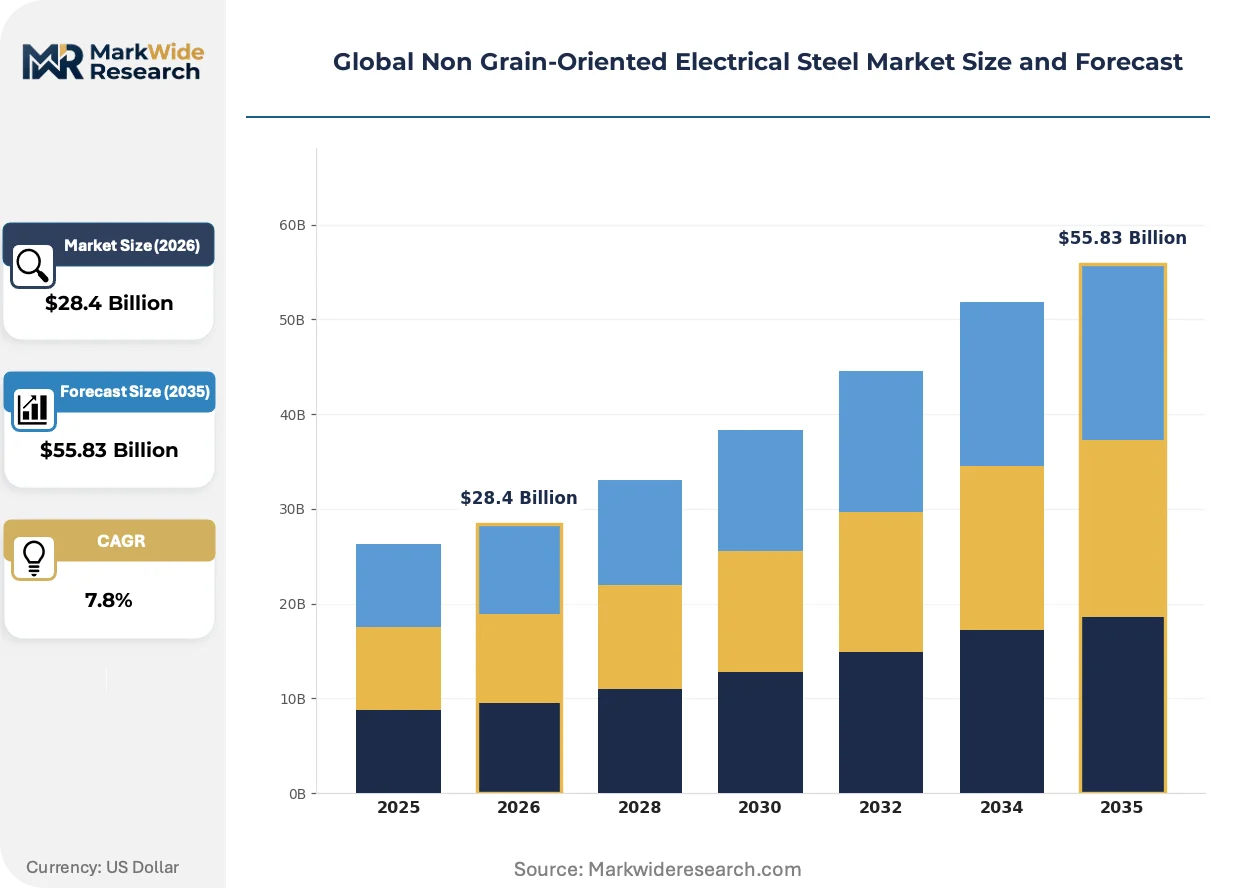
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $55.83 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Steel, Uncoated Steel, Cold Rolled, Annealed, Semi-processed Application: Transformers, Electric Motors, Generators, Inductors, Magnetic Devices End User Industry: Power Generation, Electrical Equipment Manufacturers, Appliance Producers, Renewable Energy Sector, Defense Equipment Form: Sheets, Strips, Coils, Laminations, Plates |
| Companies Covered | ArcelorMittal, Nippon Steel Corporation, POSCO, Baosteel Group Corporation, JFE Steel Corporation, Nucor Corporation, Thyssenkrupp, Tata Steel, NLMK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non Grain-Oriented Electrical Steel Market Shifts & Advancements
Digital twin modeling of magnetic core loss prediction is compressing product development cycles while enabling mills to simulate alloy chemistry variations before physical trial production.
Thin-gauge silicon steel with optimized grain texture is virtualizing traditional lamination stacking designs in high-speed traction motors. European and Asian EV powertrain engineers are adopting 0.20-0.27mm thickness ranges for inverter-fed applications above 10 kHz switching frequencies. This virtualization is collapsing the historical trade-off between core loss reduction and mechanical stiffness in rotor assemblies.
The EU F-Gas Regulation phase-down schedule is accelerating motor efficiency tier migrations ahead of mechanical replacement cycles. Industrial compressor and pump OEMs must now certify partial-load performance curves that were previously exempt from Ecodesign scrutiny. Cold-rolled and annealed grade suppliers in Germany and Italy are reconfiguring annealing line temperature profiles to meet the stricter 2027 thresholds.
Direct mill contracting is displacing spot-market purchasing for high-volume automotive electrification programs. Tier-1 motor manufacturers in South Korea and Japan are locking multi-year coil supply agreements with fixed alloy specifications. This concentration is most visible in Busan-area manufacturing clusters where captive supply relationships now govern procurement for appliance and EV traction motor laminations.
Global Non Grain-Oriented Electrical Steel Market Segmentation
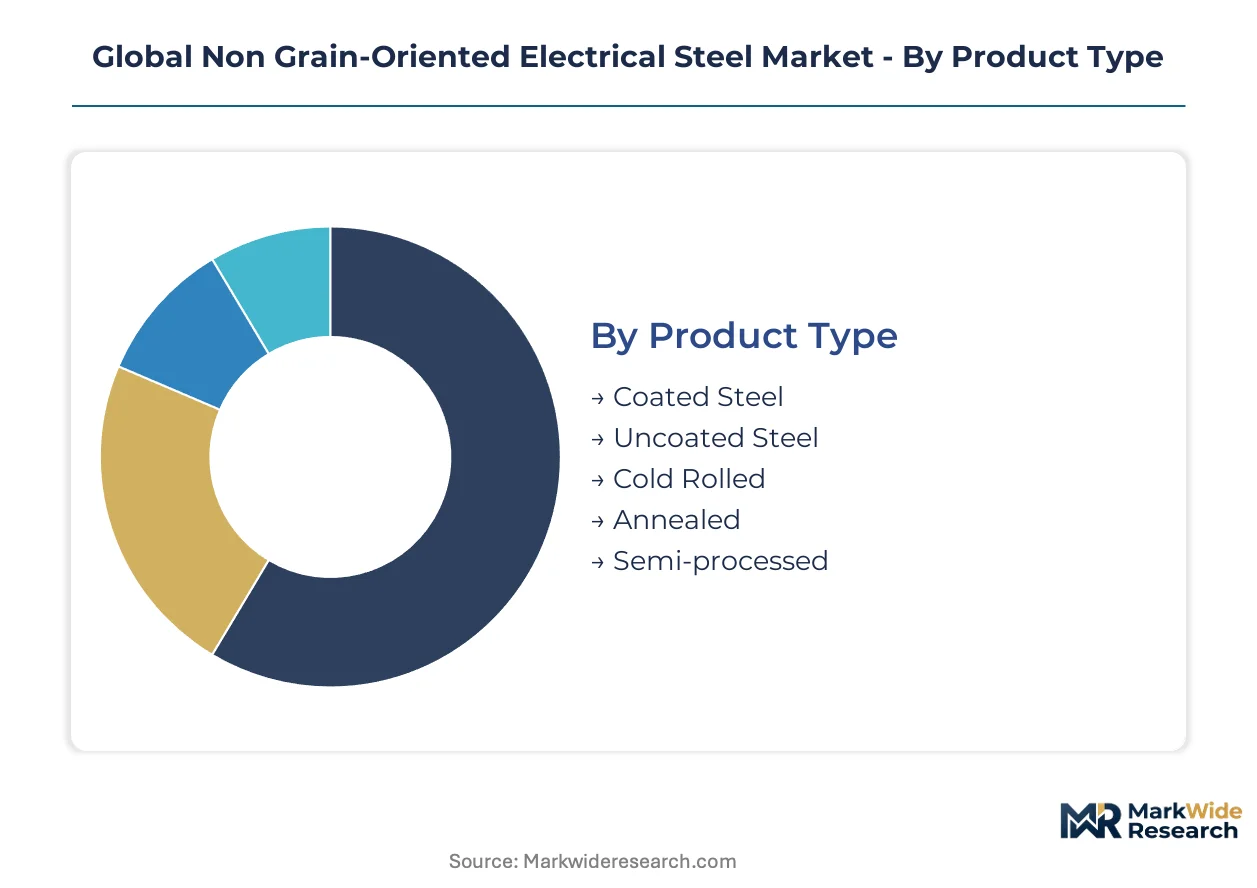
Segmentation in non grain-oriented electrical steel reveals how alloy chemistry, processing depth, and end-use thermal cycles dictate margin structures and inventory velocity. Mills optimize coil scheduling around the divergent lead times of appliance motor laminations versus wind turbine generator cores.
Product Type:
Cold rolled and annealed grades turn inventory fastest through appliance motor supply chains, while coated variants sit longer awaiting high-frequency inverter specifications.
- Coated Steel:Interlaminar insulation coatings of phosphate or organic resin enable eddy current suppression in inverter-fed motors above 10 kHz switching frequencies. Procurement concentrates with EV traction motor manufacturers in South Korea and Japan where METI efficiency tiers mandate core loss minimization.
- Uncoated Steel:Standard-efficiency industrial motors and legacy appliance stators consume uncoated laminations where cost sensitivity outweighs frequency-driven loss concerns. Chinese domestic appliance producers under SAMR-administered GB standards represent the dominant demand pool.
- Cold Rolled:Continuous tandem mill reduction to final gauge delivers isotropic magnetic properties for rotating machines.
- Annealed:Continuous annealing recrystallizes grain structure to optimize permeability and minimize hysteresis losses.
- Semi-processed:Material shipped in unannealed condition allows motor manufacturers to customize final magnetic properties through in-house heat treatment.
Annealed grades anchor the volume base while coated steel gains share at the steepest rate.
Application:
Cost tier separation runs deepest here: utility-scale transformers absorb premium silicon grades while commodity induction motors compete on ferrosilicon input pass-through.
- Electric Motors:Fractional-horsepower appliance motors and high-speed traction motors share laminations but diverge sharply on silicon content and gauge specifications. EV powertrain procurement in Germany and Japan drives ultra-thin gauge adoption.
- Generators:Wind turbine generators require higher silicon grades for partial-load efficiency optimization. OEMs in Denmark and Spain specify material for direct-drive and geared architectures under EU Ecodesign frameworks.
- Transformers:Distribution and power transformers utilize non grain-oriented steel in smaller ratings where core flux patterns remain non-directional.
- Inductors:Choke and filter applications in power electronics demand controlled permeability across frequency ranges.
- Magnetic Devices:Sensors, actuators, and specialty magnetic components exploit isotropic properties for complex flux geometries.
Electric motors command the largest tonnage position while generators expand most quickly on renewable energy buildout.
End User Industry:
Customer type fragmentation separates price-takers from specification-setters, with appliance producers driving volume and renewable developers dictating alloy innovation.
- Renewable Energy Sector:Wind turbine generator OEMs specify 2.0-3.5% silicon grades with tight core loss tolerances for 20-25 year operational life. Procurement clusters around Shanghai and Busan manufacturing hubs serving domestic and export markets.
- Appliance Producers:Compressor and pump motor manufacturers in India and Mexico source standard-efficiency grades under BIS and NOM efficiency labeling programs. Volume concentration enables direct mill contracting with fixed alloy specifications.
- Power Generation:Utility and independent power producers procure generator-grade material for gas turbine and hydroelectric applications.
- Electrical Equipment Manufacturers:Motor rewind shops and industrial drive suppliers purchase slit coils and laminations through distributor channels.
- Defense Equipment:Naval propulsion and aircraft electrical systems require certified material traceability and magnetic property documentation.
Appliance producers anchor the volume base while the renewable energy sector gains share at the steepest rate.
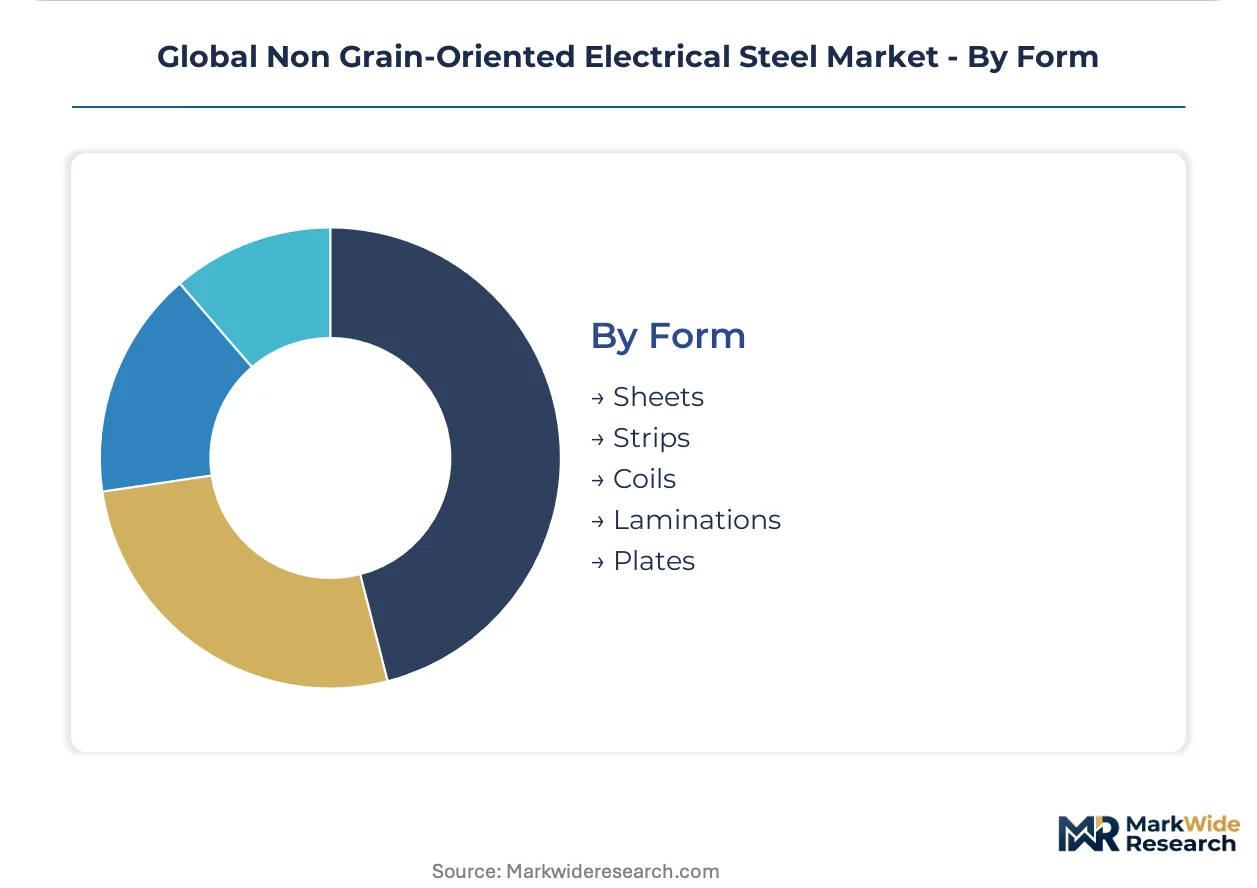
Form:
Supply concentration varies by physical form: coils concentrate at mill level while laminations fragment across stamping operations.
- Coils:Master coils up to 2,000mm width feed high-volume slitting and blanking operations at tier-1 motor manufacturers. Busan-area clusters consume captive supply relationships for automotive electrification programs.
- Laminations:Precision-stamped rotor and stator segments with interlocking notches and alignment holes ship directly to motor assembly lines. European motor OEMs source from integrated stamping operations in Germany and Italy.
- Sheets:Cut-to-length flat products serve low-volume transformer and specialty motor applications.
- Strips:Narrow slit coils feed high-speed progressive die stamping for small motor production.
- Plates:Thicker gauge plate products accommodate mechanical strength requirements in structural magnetic applications.
Coils anchor the volume base while laminations gain share at the steepest rate on motor manufacturer vertical integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in non grain-oriented electrical steel tilts toward East Asian mills serving export markets, while European and North American buyers absorb premium logistics costs for certified grades. Chinese producers leverage domestic silicon supply chains to undercut landed prices in Southeast Asia and Latin America. Japanese and South Korean mills command alloy chemistry premiums for ultra-thin gauge specifications demanded by EV traction motor programs.
China
Wind turbine generator OEMs and appliance motor manufacturers drive tonnage demand across the Yangtze River Delta manufacturing corridor. SAMR-administered GB standards tighten core loss thresholds for domestic electrification programs under the country's dual carbon goals. Shanghai-area steel clusters supply high-silicon grades to captive automotive electrification programs serving BYD and SAIC Motor.
Japan
Precision magnetic device applications and high-frequency inverter-fed motors anchor demand for ultra-thin gauge material below 0.27mm thickness. METI Top Runner standards block lower-efficiency electrical steel imports through mandatory certification reciprocity requirements. Kanto-region mills concentrate R&D leadership for grain texture optimization serving robotics and medical imaging equipment.
Germany
Industrial compressor and pump OEMs face accelerated efficiency tier migrations under the EU F-Gas Regulation phase-down schedule. Ecodesign framework mandates now cover partial-load performance curves previously exempt from scrutiny. North Rhine-Westphalia steel processing centers reconfigure annealing line temperature profiles to meet stricter 2027 thresholds for generator-grade material.
United States
Wind and solar component manufacturers access domestic content bonuses through IRA clean energy provisions incentivizing North American mill capacity expansion. Department of Energy appliance efficiency standards tighten core loss thresholds for motor laminations used in HVAC and refrigeration equipment. Midwest manufacturing clusters around Detroit and Chicago consolidate procurement for automotive electrification programs.
South Korea
EV traction motor manufacturers lock multi-year coil supply agreements with fixed alloy specifications through direct mill contracting. Busan-area manufacturing clusters govern procurement for appliance and automotive electrification laminations through captive supply relationships. Domestic mills anchor high-volume production for export markets across Southeast Asia and Australia.
Global Non Grain-Oriented Electrical Steel Market Competitive Landscape
Integrated steel conglomerates and specialized electrical steel producers split the market along capability and scale vectors. The vendor base concentrates among Asian integrated mills with captive silicon supply chains and European processors with Ecodesign certification expertise. Three archetypes dominate: full-range integrated producers, regional efficiency-grade specialists, and coating technology licensors. Competitive moves center on backward integration into ferrosilicon supply and multi-year direct contracting with automotive OEMs.
Within the integrated producer tier, ArcelorMittal and Nippon Steel Corporation exemplify divergent geographic positioning. ArcelorMittal occupies a position anchored in European flat-rolled network density, while Nippon Steel Corporation represents ultra-thin gauge R&D leadership. POSCO sits within the high-volume Asian supply archetype serving Busan-area manufacturing clusters. These three companies collectively illustrate how mill-to-OEM contracting is compressing traditional distributor roles across major electrification programs.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nippon Steel Corporation |
| POSCO |
| Baosteel Group Corporation |
| JFE Steel Corporation |
| Nucor Corporation |
| Thyssenkrupp |
| Tata Steel |
| NLMK |
| Others |
Supply & Pricing Matrix
Silicon input cost volatility determines both tiered pricing spreads and supply chain configuration across non grain-oriented electrical steel markets. Ferrosilicon alloy pricing fluctuations compress mill margins on standard-efficiency grades while forcing buyers toward longer-term contracting structures that reshape procurement geography.
Pricing Analysis
Configured-to-order pricing for ultra-thin gauge material commands spreads exceeding three standard deviations above commodity coil baselines. Three-tier pricing structure across premium, standard, and economy levels separates coated high-frequency grades from cold-rolled annealed stock and semi-processed material. Pricing pressure stems from ferrosilicon cost pass-through limitations in appliance motor contracts. Appliance producers under China's SAMR-administered GB standards exhibit highest price sensitivity, while EV traction motor manufacturers in South Korea absorb premium positioning for METI-compliant certification tiers.
Supply Chain Analysis
Busan-area manufacturing clusters and Shanghai steel processing centers concentrate contract-manufacturing capacity for high-volume automotive electrification programs. Coil production draws from Chinese domestic silicon supply chains, South Korean integrated mill networks, and Japanese precision rolling operations. Single-source vulnerability concentrates in annealing line engineering talent pools anchored among incumbent Asian mills. Distribution runs through direct mill-to-OEM agreements that displace traditional steel distributor channels for generator-grade and traction motor material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous annealing process engineers with magnetic property optimization expertise remain concentrated among a handful of incumbent mills, creating structural bottlenecks that constrain capacity expansion regardless of capital availability.
For Market Incumbents: Insulate core margin positions by locking multi-year direct contracting with EV traction motor manufacturers before alternative silicon steel formulations mature. Deepen backward integration into ferrosilicon supply through offtake agreements with Chinese alloy producers, neutralizing the input cost volatility that erodes standard-grade profitability. Prioritize certification reciprocity investment to prevent stranded inventory when Japan's METI Top Runner protocols diverge from EU Ecodesign verification standards. For New Entrants and Emerging Players: Mid-market appliance motor manufacturers in India represent the most penetrable entry point, with BIS efficiency labeling expansion and PLI scheme incentives creating procurement white space absent entrenched supplier relationships. Target coated steel variants for high-frequency inverter-fed motors above 10 kHz switching frequencies, where interlaminar insulation requirements sustain premium positioning against commodity uncoated grades. Pursue toll-processing arrangements with established annealing line operators to bypass metallurgical talent scarcity. For Investors and Strategic Acquirers: The EU F-Gas Regulation phase-down schedule reshapes the acquisition landscape by accelerating efficiency tier migrations that favor mills with Ecodesign certification expertise over volume-scale commodity producers. Five-to-ten-year viability hinges on positioning for generator-grade material demand from wind turbine OEMs specifying higher silicon grades for partial-load efficiency optimization. Monitor divergence between regional efficiency test protocols as the primary signal for stranded inventory risk and cross-border supply chain disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrosilicon Supply | Captive alloy sourcing neutralizes input cost volatility compressing standard-grade margins. |
| Multi-Year Direct Mill Contracting | Fixed alloy specifications lock procurement relationships with EV traction motor manufacturers. |
| Ultra-Thin Gauge R&D Investment | Grain texture optimization serves precision magnetic device applications in robotics and medical imaging. |
| Coating Technology Licensing | Interlaminar insulation capabilities access premium positioning in inverter-fed motors above 10 kHz. |
| Regional Certification Reciprocity Programs | Harmonized test protocols prevent stranded inventory when METI Top Runner diverges from EU Ecodesign. |
Research Methodology
A spread of perspectives from continuous annealing process engineers, EV motor procurement directors, wind turbine generator OEM specification teams, and steel distributor channel managers converged on the working assumptions governing alloy chemistry tolerance and efficiency tier migration timelines. Primary interview insights triangulated against customs trade data, SAMR GB standard filings, EU Ecodesign framework documentation, and SEC 10-K disclosures from integrated steel producers. Bottom-up coil shipment analysis and top-down end-use demand modeling validated segmentation splits across product type, application, and end-user industry dimensions.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning silicon content grade, processing depth, physical form, and regional regulatory cluster. CAGRs derived from rolling average replacement cycle analysis and electrification program procurement schedules. Forecast inputs incorporated ferrosilicon pricing trajectory assumptions and annealing line capacity expansion announcements from East Asian manufacturing clusters.
Practitioners should monitor divergence between Japan's METI Top Runner test protocols and EU Ecodesign efficiency verification for early signals of cross-border certification friction. Forecasts reflect documented assumptions regarding alloy chemistry tolerance tightening and renewable energy sector procurement acceleration. Quarterly review of SAMR-administered GB standard amendment schedules and IRA domestic content bonus implementation guidance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Copper Magnet Wire Market
Magnetic Materials
Ferrite Magnet Market
Magnetic Materials
Flux Field Directional Material Market
Magnetic Materials
Magnet Market
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
Reduced Iron Powder Market
Magnetic Materials
Sintered Soft Magnetic Material Market
Magnetic Materials
Neodymium [Nd-Fe-B] Magnet Market
Magnetic Materials
Global Non-Oriented Electrical Steel Market
Magnetic Materials
Superconducting Magnets Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
Magnetic Materials Market
Magnetic Materials
Cobalt Oxide Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Global Permanent Magnet Market