
 Light Diffusion Materials Market | 2026-2036
Light Diffusion Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Light Diffusion Materials Market Foresight
The capability gap between integrated resin producers and downstream converters is collapsing as proprietary compounding technology becomes table stakes. Mitsubishi Chemical Group leverages captive acrylic monomer supply to control formulation consistency across optical-grade diffusion sheets. Evonik Industries AG anchors its position through specialized methacrylate chemistry that sustains haze-performance ratios under thermal stress. Röhm GmbH competes on backward integration into methyl methacrylate, securing feedstock cost advantages for premium diffuser applications.
Light diffusion materials are engineered polymers or glass formulations containing micro-structured surfaces or embedded scattering particles that redistribute incident light across specified angular distributions, typically achieving haze values above 85 percent while maintaining minimum 40 percent total light transmittance. These materials serve primarily to eliminate hot spots, reduce glare, and achieve uniform luminance in solid-state lighting enclosures, display backlights, and vehicle forward lighting modules. Acrylic dominates volume in commercial lighting applications where cost-sensitive architects specify extruded diffuser panels for linear LED troffers, while polycarbonate captures margin pools in automotive lighting where thermal resilience and impact resistance justify premium positioning. Films represent the fastest-growing form factor as electronics manufacturers adopt roll-to-roll processed optical diffusion layers for slim display architectures.
The US Environmental Protection Agency regulates volatile organic compound emissions from solvent-based coating processes used in diffuser manufacturing, pushing producers toward waterborne or UV-cured alternatives. ECE Regulation 48 in Europe mandates precise beam pattern uniformity for vehicle headlamps, directly specifying optical diffuser performance thresholds that polycarbonate and acrylic grades must satisfy. China's GB standards for LED lighting safety, enforced by SAMR, require flame-retardant diffusion materials in public infrastructure installations. Stakeholders must monitor how evolving photobiological safety standards in multiple jurisdictions reshape material selection criteria for human-centric lighting applications.
Market Dynamics
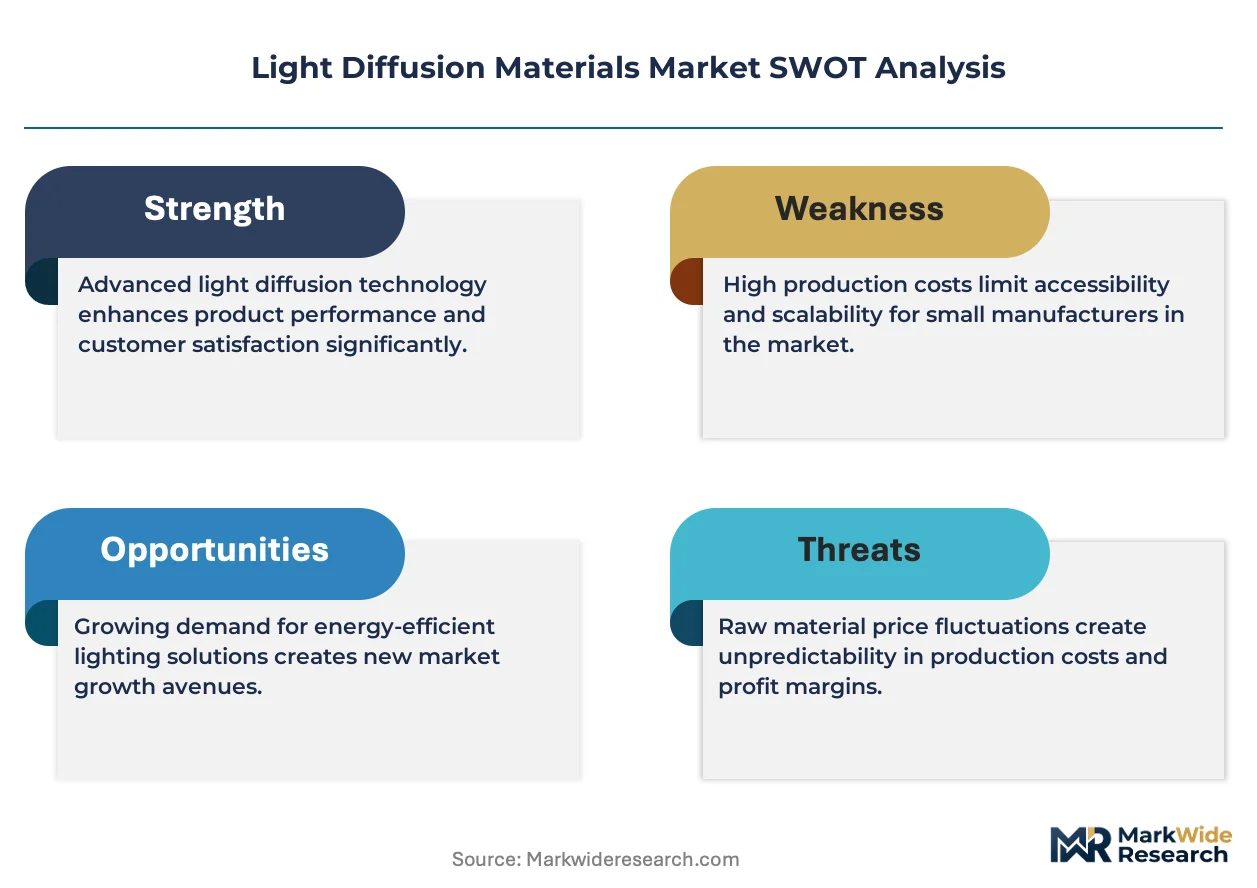
The collapse of capability gaps between integrated resin producers and downstream converters is compressing margin pools across the value chain, forcing specialty compounders to defend differentiation through proprietary optical formulations rather than feedstock access alone.
Growth Catalysts
- ECE Regulation 48 beam uniformity mandates:European vehicle headlamp standards require precise optical diffuser performance thresholds, pulling polycarbonate grades into premium automotive lighting modules.
- Guangdong province LED cluster concentration:Fixture manufacturers co-located with raw material suppliers achieve procurement cost advantages and rapid formulation iteration cycles.
- Roll-to-roll film processing adoption:Electronics manufacturers deploy continuous optical diffusion layers to enable thinner display architectures and reduce assembly steps.
Market Restraints
- Methyl methacrylate feedstock volatility:Acrylic diffuser pricing tracks monomer supply disruptions from crackers in the US Gulf Coast and Northeast Asia.
- Specialized compounding equipment scarcity:Twin-screw extruders capable of sub-micron particle dispersion face 18-month order backlogs from European machinery builders.
- Glass microsphere substitution threat:High-performance lighting applications in Japan increasingly specify borosilicate diffusers for extreme thermal cycling environments.
Strategic Opportunities
- India BIS LED safety standard implementation:Pending flame-retardant diffusion material mandates for public infrastructure create first-mover positioning for certified suppliers.
- Human-centric lighting photobiological compliance:Circadian rhythm-optimized fixtures require spectrally-tuned diffusers with melanopic ratio control.
- Automotive matrix beam convergence:Integration of pixelated LED sources with adaptive diffusion layers enables dynamic beam shaping without mechanical actuators.
Industry Challenges
- Optical metrology talent scarcity:Laboratories capable of haze and transmittance characterization to ECE tolerances face recruitment competition from semiconductor and pharmaceutical sectors.
- Multi-jurisdiction certification timelines:Simultaneous EPA VOC compliance, ECE photometric validation, and China GB flame testing extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Diffusion Materials Market |
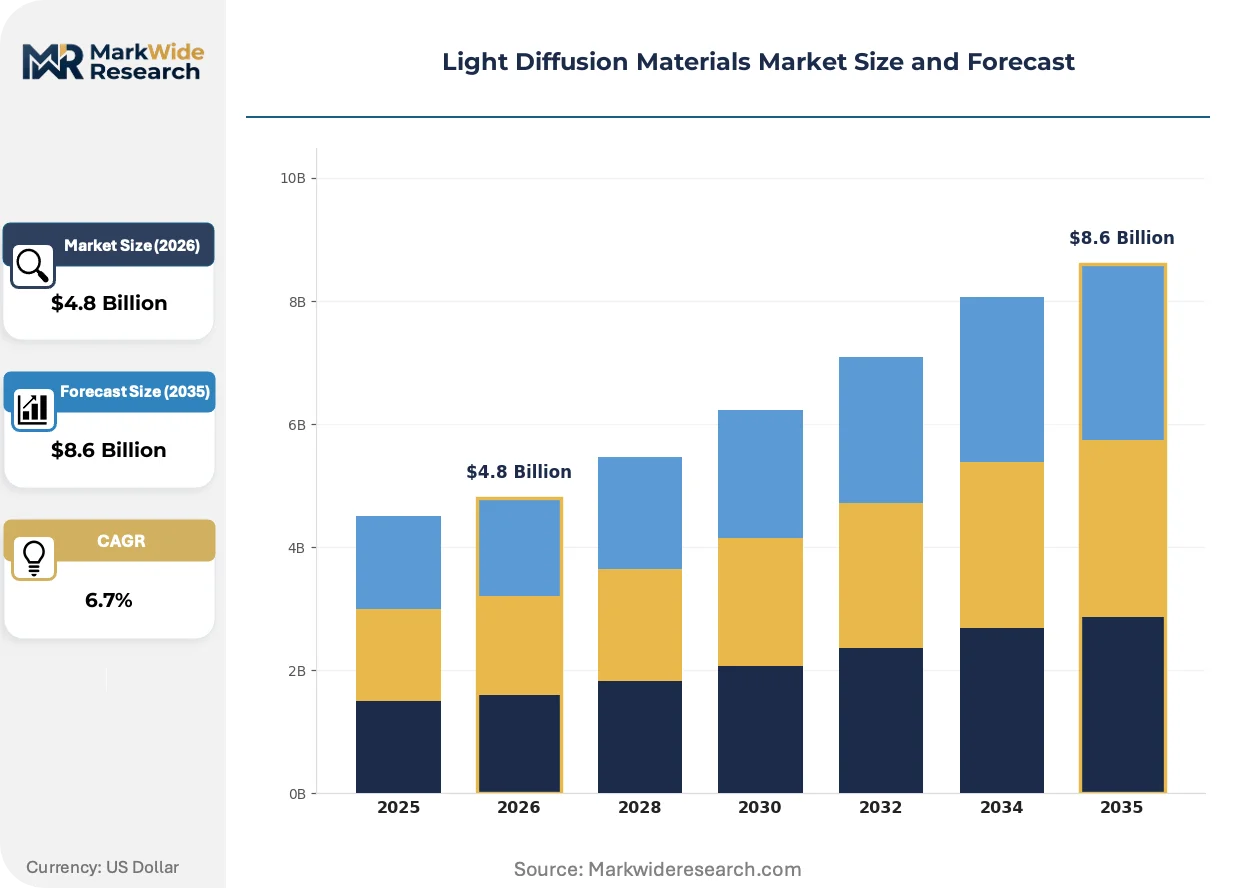
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polycarbonate, Glass, Silicone End User: Architects, Automotive Manufacturers, Lighting Designers, Electronics Application: Commercial Lighting, Automotive Lighting, Residential Lighting, Decorative Fixtures Form: Films, Panels, Sheets, Strips |
| Companies Covered | Mitsubishi Chemical Group Corporation, Röhm GmbH, 3M, Dow, Luminit LLC, SABIC, Toray Industries, Evonik Industries AG, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Diffusion Materials Market Shifts & Advancements
Formulation science and manufacturing process control are converging to enable functionally graded diffusion materials that vary optical properties across single components, eliminating multi-layer laminations in next-generation lighting enclosures.
Nano-structured surface embossing is displacing particle-loaded bulk diffusion in premium display applications. Korean panel manufacturers adopt UV-cured micro-lens arrays for edge-lit LCD backlights. This transition compresses material thickness requirements by 40 percent while maintaining luminance uniformity.
EPA enforcement of volatile organic compound limits from solvent coating processes tightens emission thresholds for diffuser manufacturing. Producers migrate toward waterborne dispersion or electron-beam curing technologies. Automotive suppliers in Michigan and South Carolina retrofit lines to maintain US market access.
Architectural lighting procurement now favors certified optical performance guarantees over brand-based supplier selection. Third-party photometric validation laboratories in Germany and the United States issue haze-transmittance certificates that substitute for traditional material specifications. Municipal buyers in California and New York mandate these certificates for public infrastructure tenders.
Light Diffusion Materials Market Segmentation
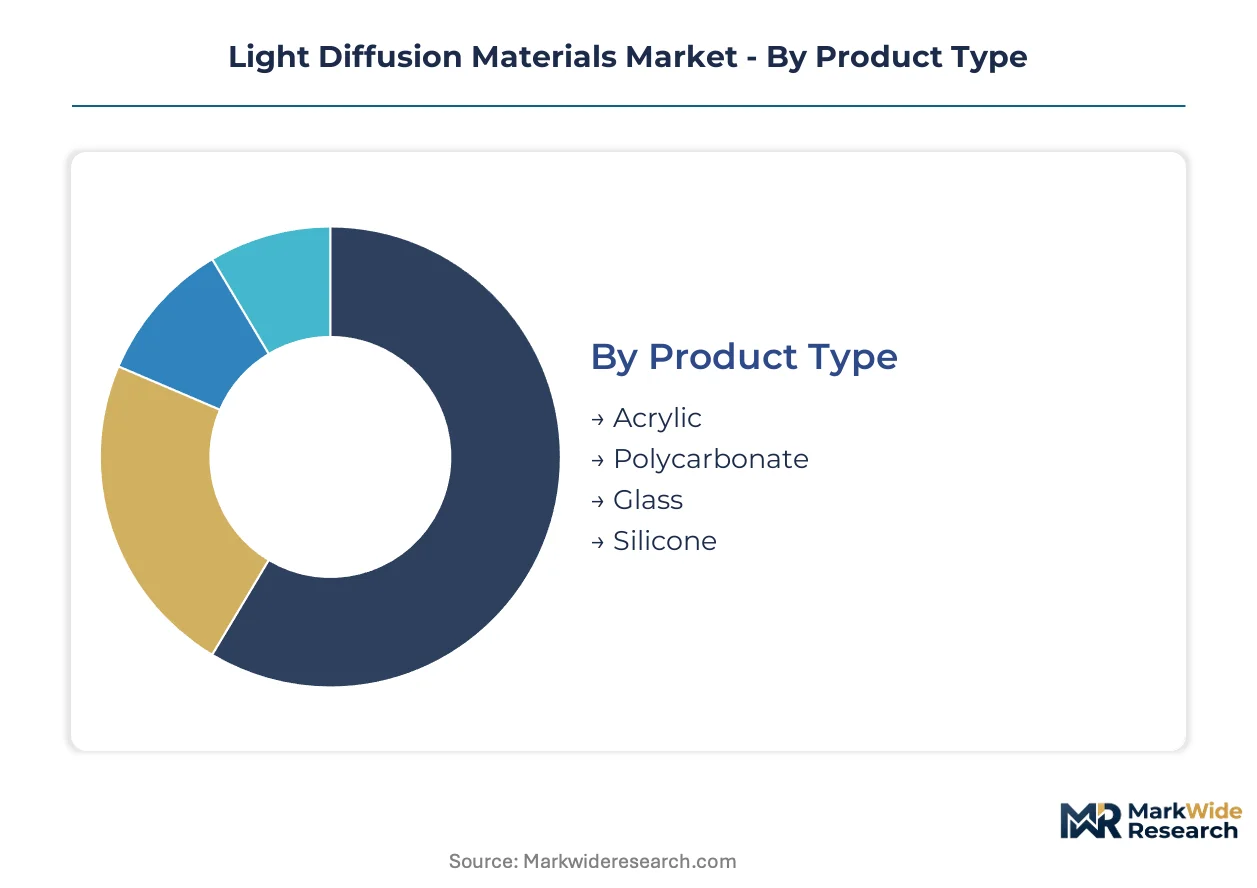
Segmentation in light diffusion materials determines formulation priorities, certification pathways, and margin capture. Acrylic and polycarbonate grades flow through entirely different channel structures—extruded sheet distributors versus automotive Tier-1 integrators—shaping how producers allocate technical service resources.
Product Type:
Channel mix varies sharply by resin chemistry: acrylic moves through architectural distributors and lighting fixture OEMs, polycarbonate through automotive Tier-1s, glass through specialty optical houses, and silicone through electronics contract manufacturers.
- Acrylic:Extruded or cast polymethyl methacrylate formulations achieve haze values above 85 percent through embedded organic scattering particles. Demand concentrates in China's Guangdong province, where LED fixture manufacturers specify cost-optimized diffuser panels for linear commercial troffers and the country's MIIT efficiency mandates accelerate fixture retrofits.
- Polycarbonate:Bisphenol-A derived thermoplastics withstand thermal loads above 120°C in automotive forward lighting modules. German automotive lighting designers under ECE Regulation 48 specify these grades for headlamp uniformity compliance, pulling material through specialized compounders with captive compounding lines.
- Glass:Borosilicate and soda-lime formulations with acid-etched or sandblasted surfaces serve high-temperature industrial applications.
- Silicone:Platinum-cured elastomeric diffusers enable flexible form factors in emerging human-centric lighting fixtures.
By volume, acrylic leads. By growth pace, polycarbonate is ahead.
End User:
Customer type determines specification authority and purchasing behavior: architects issue performance-based specifications, automotive manufacturers enforce material qualification protocols, lighting designers prioritize optical consistency, and electronics buyers emphasize thickness tolerance and roll-to-roll compatibility.
- Architects:Commercial building designers in California and New York municipalities now mandate third-party photometric validation certificates for public infrastructure tenders, shifting procurement from brand loyalty to certified performance metrics.
- Automotive Manufacturers:German OEMs and their Tier-1 lighting suppliers enforce ECE Regulation 48 beam uniformity standards through qualified material databases, locking in polycarbonate grades that survive thermal cycling and impact testing protocols.
- Lighting Designers:Specifiers of decorative and human-centric fixtures drive demand for spectrally-tuned diffusers with melanopic ratio control.
- Electronics:Display and device manufacturers in Korea adopt UV-cured micro-lens arrays processed via roll-to-roll methods, compressing material thickness requirements by 40 percent.
Architects and electronics buyers dominate volume procurement. Automotive manufacturers command the steepest expansion trajectory through matrix beam integration.
Application:
Application focus dictates thermal and mechanical requirements: commercial lighting prioritizes cost-efficient extrusion, automotive demands impact resistance, residential balances aesthetics with ease of installation, and decorative fixtures emphasize design flexibility.
- Commercial Lighting:Linear LED troffers, panel lights, and high-bay fixtures specify extruded acrylic diffuser panels where procurement cost dominates. China's SAMR enforces GB flame-retardant standards for public infrastructure, filtering supplier qualification.
- Automotive Lighting:Headlamp, taillamp, and interior modules require polycarbonate grades that maintain haze-performance ratios under thermal stress per ECE Regulation 48 mandates in Germany.
- Residential Lighting:Downlights, pendants, and surface-mounted fixtures balance optical performance with consumer price sensitivity.
- Decorative Fixtures:Custom luminaires for hospitality and retail prioritize aesthetic diffusion effects over standardized performance metrics.
Commercial lighting holds volume leadership. Automotive lighting climbs fastest on regulatory pull and technology convergence.
Form:
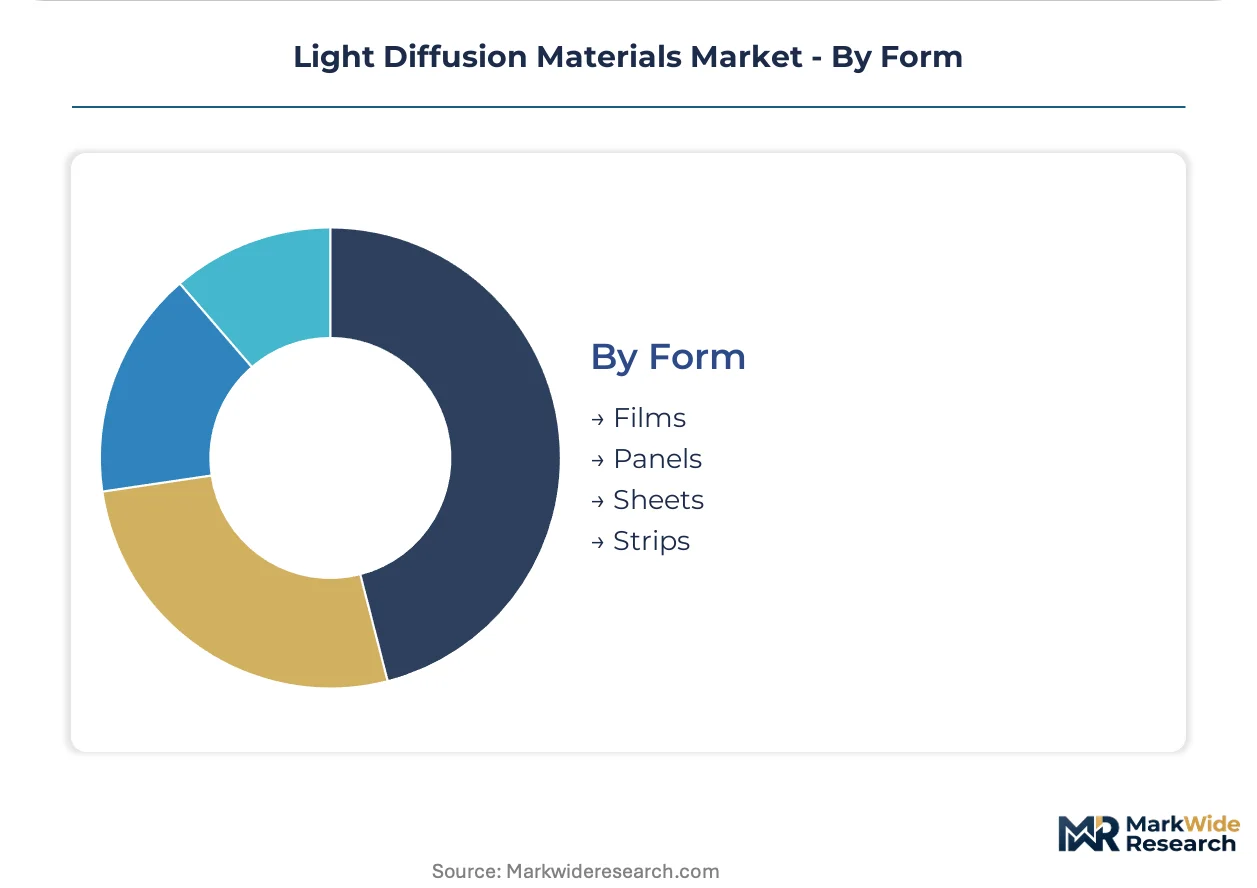
Physical form factor determines manufacturing investment and logistics economics: films enable electronics roll-to-roll processing, panels serve architectural scale, sheets bridge industrial and commercial uses, and strips address linear fixture specialization.
- Films:Roll-to-roll processed optical diffusion layers, including UV-cured micro-lens arrays, enable the thinnest display backlights and reduce assembly steps for Korean electronics manufacturers.
- Panels:Rigid extruded or cast sheets in standard architectural dimensions serve commercial troffer and panel light enclosures.
- Sheets:Intermediate thickness formats bridge industrial lighting and specialty signage applications.
- Strips:Narrow linear formats match LED tape and channel extrusion systems for cove and accent lighting.
Panels dominate current volume. Films expand most quickly on electronics adoption and display architecture thinning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's Guangdong province exhibit the highest price elasticity, squeezing margins on extruded acrylic panels, while German automotive lighting designers accept premium polycarbonate pricing to secure ECE Regulation 48 compliance. This demand-elasticity contrast shapes regional competitive positioning across the value chain.
China
LED fixture manufacturers cluster in Guangdong province near petrochemical feedstock terminals, achieving procurement cost advantages through rapid formulation iteration cycles. MIIT efficiency mandates accelerate fixture retrofits across commercial infrastructure. SAMR enforces GB flame-retardant standards for public installations, filtering supplier qualification to certified compounders.
Germany
Automotive lighting designers specify polycarbonate diffusers under ECE Regulation 48 beam uniformity mandates, pulling premium grades through specialized compounders with captive compounding lines. KBA enforces photometric validation protocols for headlamp homologation. Stuttgart and Munich host Tier-1 lighting integrators co-located with optical metrology laboratories.
United States
Automotive suppliers in Michigan and South Carolina retrofit manufacturing lines to maintain EPA VOC compliance for solvent-based coating processes. The agency tightens emission thresholds, pushing producers toward waterborne dispersion or electron-beam curing technologies. California and New York municipalities mandate third-party photometric validation certificates for public infrastructure tenders.
South Korea
Display manufacturers adopt UV-cured micro-lens arrays processed via roll-to-roll methods, compressing material thickness requirements by 40 percent. MFDS oversight of photobiological safety standards influences material selection for human-centric lighting applications. Seoul and Suwon host electronics contract manufacturers driving film form-factor adoption.
India
Pending BIS LED safety standard implementation creates first-mover positioning opportunities for flame-retardant diffusion material suppliers certified for public infrastructure. The CEA efficiency mandates accelerate commercial lighting retrofits in Maharashtra and Gujarat. Mumbai and Ahmedabad concentrate fixture assembly operations importing compounded resins.
Light Diffusion Materials Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into methyl methacrylate monomer supply distinguishing the upper tier from formulation-dependent compounders below. Three archetypes populate the structure: petrochemical majors with captive acrylic supply, specialized methacrylate chemists with thermal-stress expertise, and optical film processors with roll-to-roll capabilities. Dominant competitive moves include strategic partnerships for compounding technology access and geographic expansion through distributor network consolidation.
Among integrated resin producers, Mitsubishi Chemical Group Corporation and Röhm GmbH exemplify the upper-tier archetype through captive monomer positions, while Evonik Industries AG occupies a specialist position anchored in methacrylate chemistry expertise. These three entities represent distinct strategic postures within the competitive structure—feedstock control versus formulation differentiation versus thermal-performance specialization.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group Corporation |
| Röhm GmbH |
| 3M |
| Dow |
| Luminit LLC |
| SABIC |
| Toray Industries |
| Evonik Industries AG |
| Covestro AG |
| Others |
Supply & Pricing Matrix
ECE Regulation 48 beam uniformity mandates in Germany simultaneously gate supplier qualification and stratify price tiers, as automotive lighting designers pay premiums for polycarbonate grades that survive KBA photometric validation while Guangdong fixture manufacturers squeeze acrylic panel margins through cluster-proximity procurement.
Pricing Analysis
After-sales certification maintenance and technical service contracts drive lifetime value for compounders serving automotive Tier-1s. Three-tier pricing structure across optical-grade premium, industrial-standard, and construction-economy levels separates qualified suppliers from commodity converters. Cost compression in extruded acrylic panels is intensifying because Guangdong LED fixture manufacturers leverage co-location with petrochemical terminals for rapid formulation iteration. Electronics buyers in Korea exhibit lowest price sensitivity for UV-cured micro-lens arrays, while municipal procurement in India prioritizes certified flame-retardant grades over unit cost.
Supply Chain Analysis
Eighteen-month order backlogs for twin-screw extruders capable of sub-micron particle dispersion signal inventory stress at the specialized compounding tier. Supply concentrates in China, Germany, and South Korea, with Guangdong province hosting the densest LED fixture manufacturing cluster. Feedstock draws from methyl methacrylate crackers on the US Gulf Coast and Northeast Asia, plus bisphenol-A supply from integrated petrochemical complexes. Single-source vulnerability in optical metrology equipment creates qualification bottlenecks for new entrants. Distribution runs through automotive Tier-1 integrators for polycarbonate and architectural distributors for acrylic.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Matrix beam convergence in automotive lighting represents a high-growth disruption, as pixelated LED sources with adaptive diffusion layers eliminate mechanical actuators and reset material performance thresholds across the forecast horizon.
For Market Incumbents: Consolidate formulation expertise through captive compounding line investments in Stuttgart and Munich corridor, where KBA validation protocols lock in qualified supplier status. Deepen backward integration into methyl methacrylate monomer to defend margin position against feedstock volatility from US Gulf Coast crackers. Acquire optical metrology laboratories facing recruitment competition from semiconductor sectors to secure characterization capacity. For New Entrants and Emerging Players: BIS LED safety standard fast-track certification creates first-mover positioning in Maharashtra and Gujarat public infrastructure tenders before incumbent compounders achieve flame-retardant grade qualification. Target spectrally-tuned diffusers with melanopic ratio control for human-centric lighting fixtures, where specification authority sits with lighting designers rather than procurement departments. Partner with Korean electronics contract manufacturers for roll-to-roll film processing technology transfer. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed optical film processors lacking captive monomer supply, presenting consolidation targets for integrated resin producers seeking roll-to-roll capabilities. Five-to-ten year viability hinges on positioning within automotive matrix beam supply chains rather than architectural lighting commoditization. Watch for EPA enforcement tightening on solvent-based coating processes as signal for waterborne technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methyl Methacrylate | Captive monomer supply secures formulation consistency for Mitsubishi Chemical and Röhm against Gulf Coast feedstock disruptions. |
| Optical Metrology Laboratory Acquisition | Specialized haze-transmittance characterization capacity addresses talent scarcity from semiconductor sector competition. |
| Roll-to-Roll Film Processing Scale-Up | Continuous UV-cured micro-lens array production enables Korean display manufacturers to compress backlight thickness by 40 percent. |
| BIS Flame-Retardant Certification Investment | Pending Indian public infrastructure mandates create qualification moat before global compounders achieve certified grade production. |
| Waterborne Coating Line Retrofit | EPA VOC compliance maintains US market access for Michigan and South Carolina automotive supplier facilities. |
Research Methodology
The analysis maps acrylic extrusion, polycarbonate compounding, glass microsphere, and silicone elastomer sub-sectors, each validated through technical directors at automotive Tier-1 lighting suppliers, procurement leads at Guangdong LED fixture manufacturers, optical metrology laboratory managers, and architectural specification consultants. Primary interview findings triangulated against customs trade data for methyl methacrylate and bisphenol-A flows, SEC 10-K filings from integrated resin producers, MIIT efficiency mandate implementation records, and KBA homologation databases. Bottom-up volume builds from fixture installation data reconciled with top-down resin consumption estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models resin chemistry, physical form factor, end-use application, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from elasticity-adjusted demand curves incorporating ECE Regulation 48 compliance timelines, MIIT retrofit acceleration curves, and electronics film adoption rates. Forecast inputs include methyl methacrylate cracker operating rates and automotive LED pixel density trajectories.
Underlying assumptions cover sustained ECE beam uniformity enforcement, MIIT efficiency mandate continuity, and EPA VOC threshold tightening, with deviation risk concentrated in methyl methacrylate supply disruptions and glass microsphere substitution acceleration in extreme thermal cycling applications. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Global Cellulose Esters Market
Specialty Materials
Acrylic Fine Particle Market
Specialty Materials
Spermaceti Wax Market
Specialty Materials
Compostable Cotton Swab Market
Specialty Materials
Global Graphic Film Market
Specialty Materials
Niobium Pentoxide Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Melamine Foam Market
Specialty Materials
Cellulose Gel Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Fumed Silica Market
Specialty Materials
Conductive Carbon Black Market
Specialty Materials
Super Engineering Plastics Market
Specialty Materials
Global Ajinomoto Build-Up Film Substrate Market
Specialty Materials
Solar Control Films Market
Specialty Materials
Advanced Green Septa Market