
 Laser Sensitive Pigments Market | 2026-2036
Laser Sensitive Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Sensitive Pigments Market Foresight
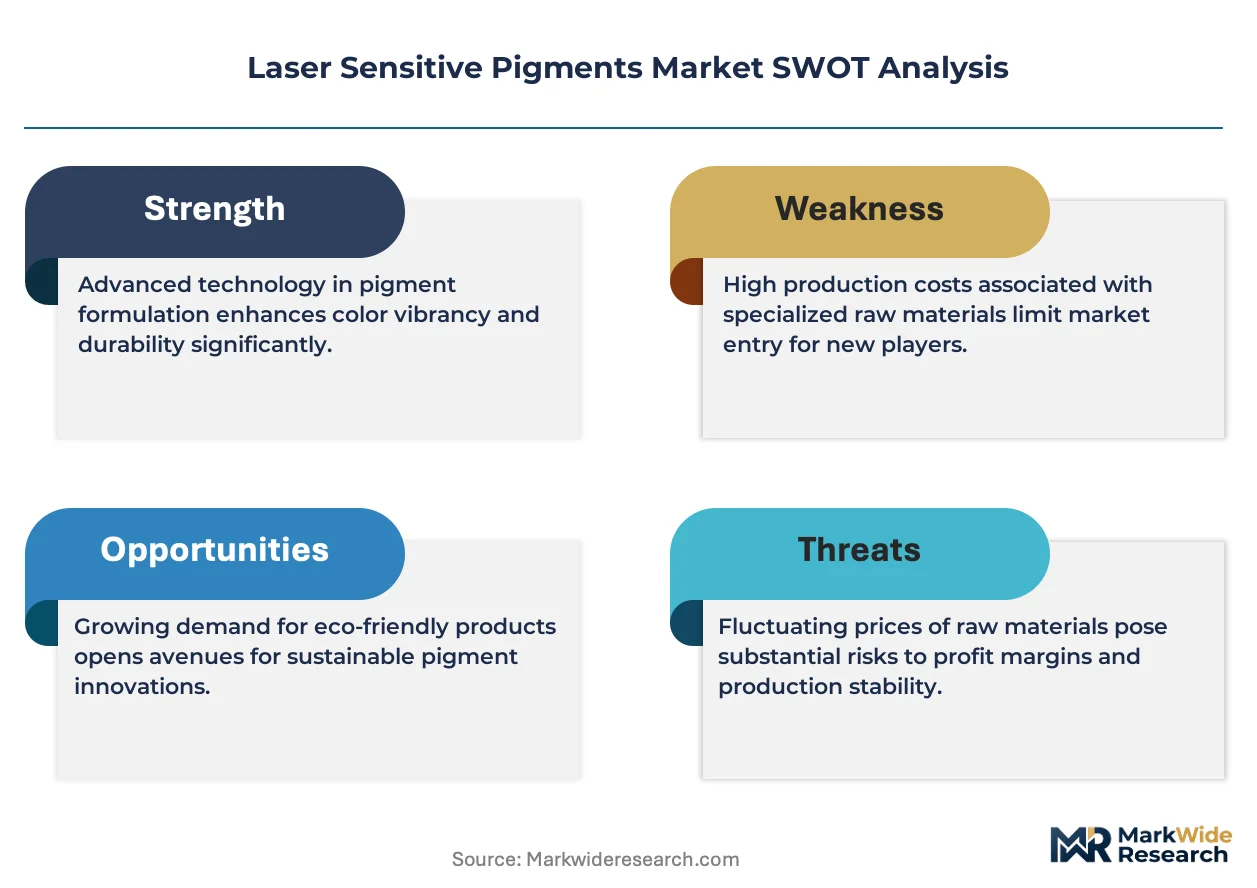
REACH is restructuring the cost-of-entry calculus for European pigment suppliers by mandating full substance registration and toxicity dossiers before market placement. Sun Chemical leverages its integrated pigment-manufacturing network to absorb compliance costs across multiple product lines. Clariant anchors its competitive position through specialized colorant R&D facilities in Switzerland that pre-validate formulations against evolving chemical safety thresholds. BASF dominates bulk intermediate supply for laser-reactive chemistries through its Ludwigshafen Verbund complex.
Laser sensitive pigments are specialized colorant systems engineered to undergo reversible or irreversible optical changes when exposed to specific laser wavelengths, typically incorporating photochromic, thermochromic, or fluorescent molecular structures with defined activation thresholds between 355 nm and 10,600 nm. These materials serve critical functions in anti-counterfeiting, product authentication, and interactive packaging where covert or overt visual verification is required. Photochromic pigments command premium positioning due to their reversible switching capability and extended cycle durability in security applications. Fluorescent pigments represent the fastest-expanding category as digital printing adoption in pharmaceutical serialization demands high-contrast, machine-readable optical signatures. Coatings applications concentrate margin pools through technical service intensity and custom color-matching protocols.
EPA oversight of heavy metal content in commercial pigments constrains formulation flexibility for US-market suppliers, while ECHA's SVHC candidate list drives continuous substitution of legacy chromophores across European supply chains. FDA color additive regulations for indirect food contact applications create additional qualification barriers for pigments used in packaging films and container coatings. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized formulation platforms or region-specific product lines deliver superior capital efficiency.
Market Dynamics
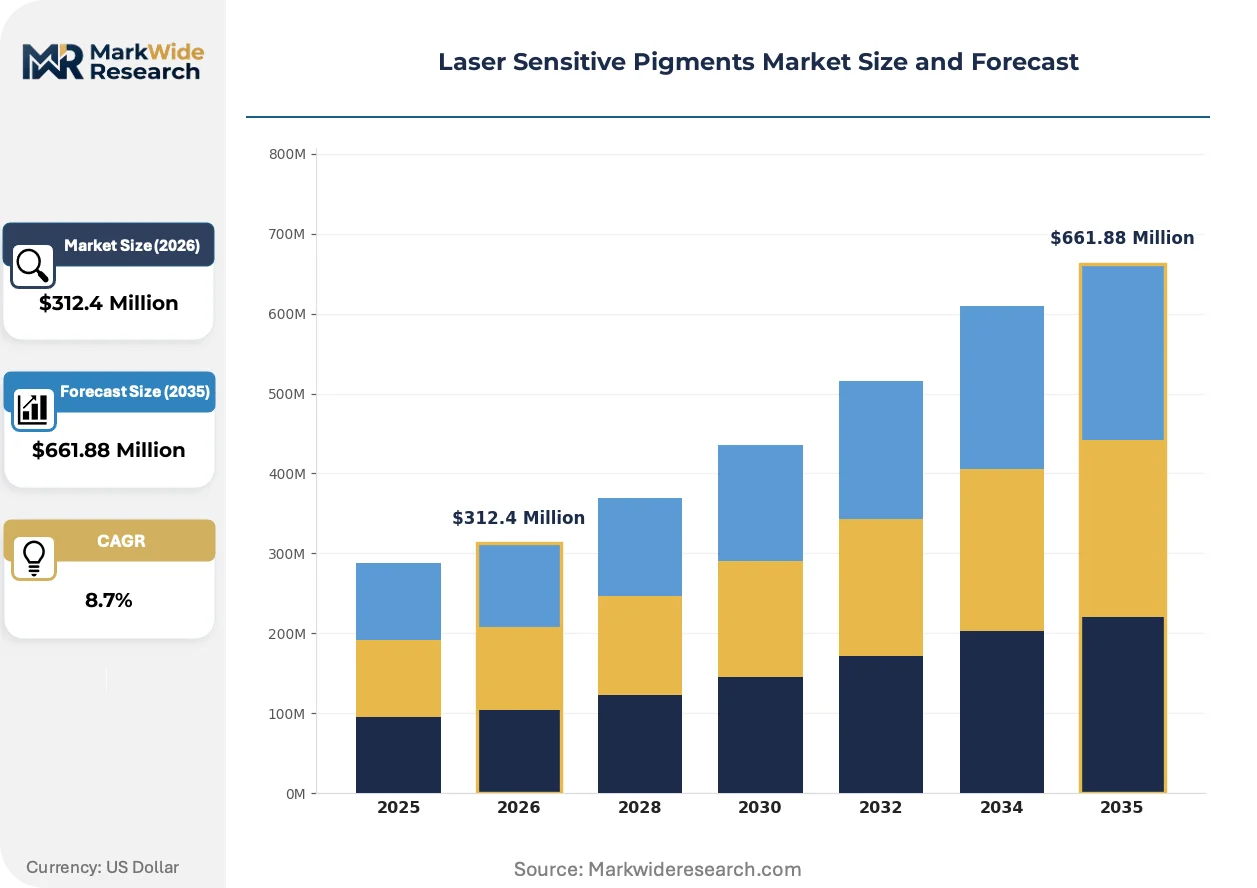
REACH compliance is restructuring raw material qualification requirements across European supply chains, forcing pigment manufacturers to absorb substantial registration costs or exit the market entirely. This regulatory pressure concentrates competitive advantage among integrated producers with dedicated toxicity testing infrastructure.
Growth Catalysts
- Pharmaceutical serialization mandates:Track-and-trace regulations in the US and EU require machine-readable optical signatures on packaging, pulling fluorescent pigments into high-volume security printing applications.
- Laser marking adoption in automotive:German OEMs around Stuttgart are specifying laser-sensitive coatings for component traceability, creating anchored demand for thermochromic formulations.
- ECHA SVHC substitution waves:Legacy chromophore bans are accelerating reformulation programs, opening procurement windows for compliant pigment suppliers with pre-validated dossiers.
Market Restraints
- Specialized intermediate concentration:Bulk supply of laser-reactive chemistries clusters at the Ludwigshafen Verbund complex, creating single-source vulnerability for downstream formulators.
- Heavy metal input volatility:EPA constraints on cadmium and lead content in commercial pigments limit color gamut flexibility and force costly alternative-seeking in red and yellow formulations.
- Photochromic durability ceiling:Reversible switching pigments face cycle-life limitations in high-UV exposure applications, constraining deployment in outdoor security markings.
Strategic Opportunities
- India's PLI scheme for packaging:Domestic pharmaceutical manufacturing incentives are building serialization infrastructure that will require imported authentication pigment systems.
- Digital printing convergence:Inkjet-compatible fluorescent nanoparticles enable on-demand serialization, merging security functions with variable-data packaging workflows.
- CSRD disclosure requirements:EU corporate sustainability reporting is elevating supply chain transparency as a procurement criterion, rewarding pigment suppliers with verified green chemistry credentials.
Industry Challenges
- Toxicology dossier compilation:REACH registration demands specialized regulatory affairs personnel that mid-tier pigment houses struggle to recruit and retain.
- FDA color additive qualification:Indirect food contact approvals for packaging films require 18-24 month timeline commitments that compress working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Sensitive Pigments Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Pigments, Photochromic Pigments, Fluorescent Pigments, Color Changing Pigments Application: Textiles, Coatings, Plastics, Inks End User: Textile Manufacturers, Paint Companies, Packaging Firms, Advertising Agencies Technology: Laser Marking, Digital Printing, Injection Molding, Screen Printing |
| Companies Covered | Sun Chemical, Clariant, BASF, Huntsman Corporation, Eckart, Ferro Corporation, Toyal, Kremer Pigments, DIC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Sensitive Pigments Market Shifts & Advancements
Formulation science is pivoting toward multi-modal authentication systems where laser-reactive pigments combine with other covert features. This convergence is compressing the addressable market for single-mechanism products while expanding premium tiers.
Nanostructured fluorescent pigments with defined excitation thresholds are absorbing share from conventional organic dye systems in pharmaceutical serialization. Serialization contractors in Germany and Switzerland are specifying these materials for their superior contrast ratios under UV-Vis scanners. The technology is absorbing margin from legacy fluorescent offerings by commanding 40-60% price premiums for equivalent volume coverage.
REACH Article 33 disclosure obligations are forcing downstream users to document SVHC content above 0.1% w/w in finished articles. Pigment suppliers must now maintain granular substance-level traceability from raw material through formulation. Coatings houses serving the Stuttgart industrial corridor are responding by consolidating supplier panels to reduce compliance audit burden.
Specification authority is migrating from procurement departments to quality assurance and regulatory affairs functions in pharmaceutical packaging. QA teams in Basel and Frankfurt are now mandating pre-submitted toxicity data packages before vendor qualification. This shift is elongating sales cycles but locking in multi-year supply agreements for qualified pigment sources.
Laser Sensitive Pigments Market Segmentation
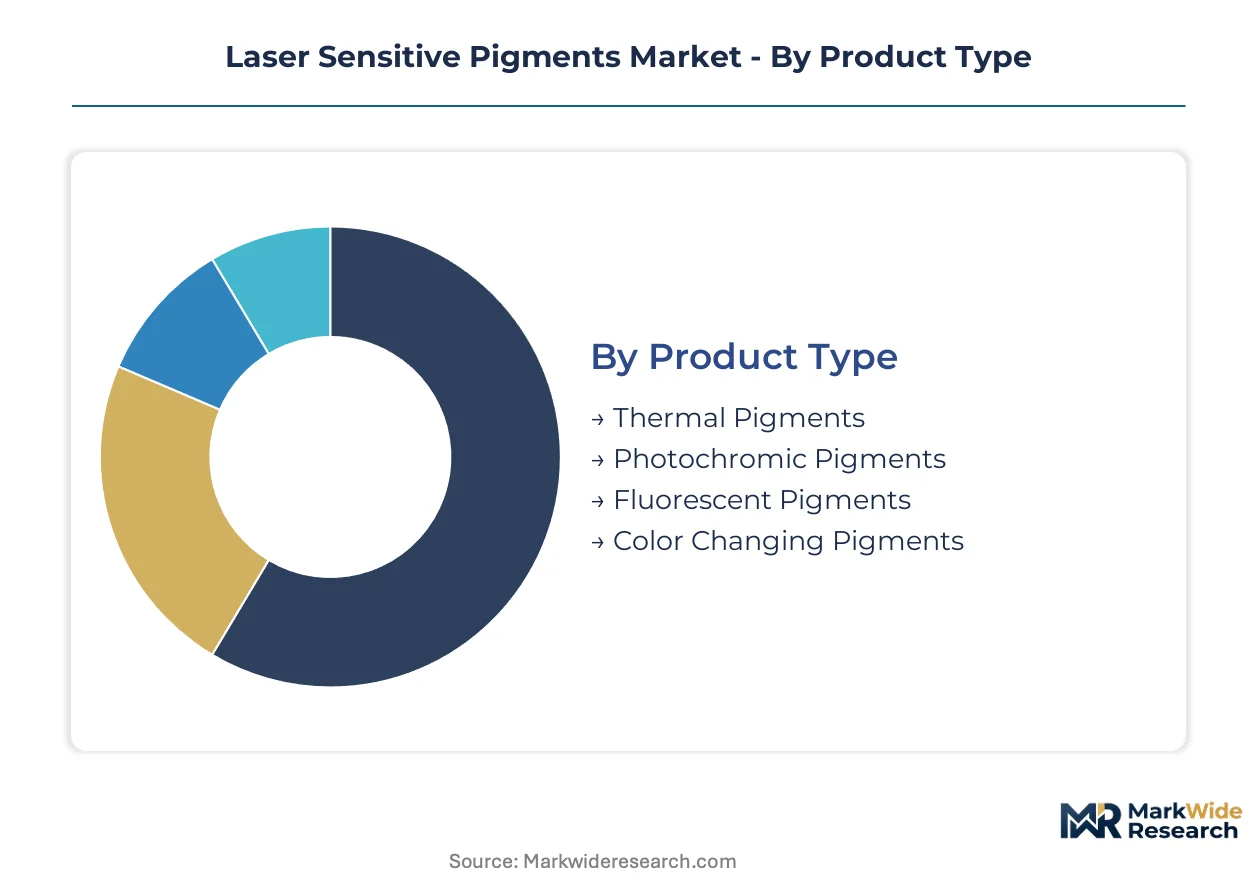
Laser sensitive pigments demand divergent certification pathways across product categories, with pharmaceutical-facing segments requiring FDA color additive qualification while industrial coatings navigate REACH dossier obligations. Segmentation strategy must align formulation investment with the specific regulatory burden each end-use imposes.
Product Type:
FDA color additive regulations and REACH SVHC thresholds create asymmetric compliance costs across pigment chemistries, with reversible photochromic systems facing extended toxicity testing timelines.
- Thermal Pigments:Thermochromic formulations undergo irreversible color change at defined laser energy thresholds, typically deployed in automotive component traceability. German OEMs around Stuttgart specify these materials for permanent marking of polymer underhood parts, with BASF's Ludwigshafen complex supplying bulk intermediates.
- Photochromic Pigments:Reversible optical switching enables repeated authentication cycles in security applications. Extended durability testing under ECHA guidelines delays European market entry, concentrating near-term revenue in US pharmaceutical packaging where FDA qualification pathways are established.
- Fluorescent Pigments:High-contrast emission under UV-Vis excitation dominates pharmaceutical serialization demand. Nanostructured variants with defined excitation thresholds command premium positioning in Swiss and German packaging corridors.
- Color Changing Pigments:Multi-wavelength responsive systems combine thermochromic and photochromic mechanisms for layered authentication. Niche deployment in high-value consumer goods packaging.
Leading the category by volume: Fluorescent Pigments. Growing fastest: Photochromic Pigments.
Application:
Application selection dictates margin structure, with coatings commanding technical service premiums and plastics requiring volume-scale intermediate supply.
- Textiles:Laser-reactive dyes for fabric marking face restricted color gamut due to EPA heavy metal constraints on cadmium-based reds. Apparel authentication demand concentrates in premium sportswear verticals.
- Coatings:Industrial finishes for automotive and aerospace specify laser-sensitive pigments for component traceability. Stuttgart's coatings corridor generates anchored demand through embedded technical service relationships and custom color-matching protocols.
- Plastics:Masterbatch integration of laser-reactive additives serves injection molding workflows. Polymer compatibility testing extends qualification cycles for each resin system.
- Inks:Security printing applications pull pigment systems into serialized pharmaceutical packaging. Digital printing convergence demands inkjet-compatible nanoparticle formulations with narrow particle size distribution.
Widest margin pool: Coatings. Steepest volume expansion: Inks.
End User:
Procurement authority migration from purchasing to quality assurance functions reshapes vendor selection criteria across end-user categories.
- Textile Manufacturers:Apparel producers specify laser-markable fabrics for brand protection, with authentication features integrated at fiber level. Compliance with restricted substance lists limits supplier panels.
- Paint Companies:Industrial coatings houses consolidate pigment suppliers to reduce REACH audit burden. Pre-submitted toxicity data packages now gate vendor qualification in Basel and Frankfurt procurement centers.
- Packaging Firms:Pharmaceutical serialization contractors drive fluorescent pigment specification for machine-readable optical signatures. QA teams mandate multi-year supply agreements post-qualification.
- Advertising Agencies:Interactive packaging and promotional materials deploy color-changing pigments for consumer engagement. Shorter product lifecycles tolerate higher per-unit pigment costs.
Longest sales cycles: Packaging Firms. Fastest procurement decisions: Advertising Agencies.
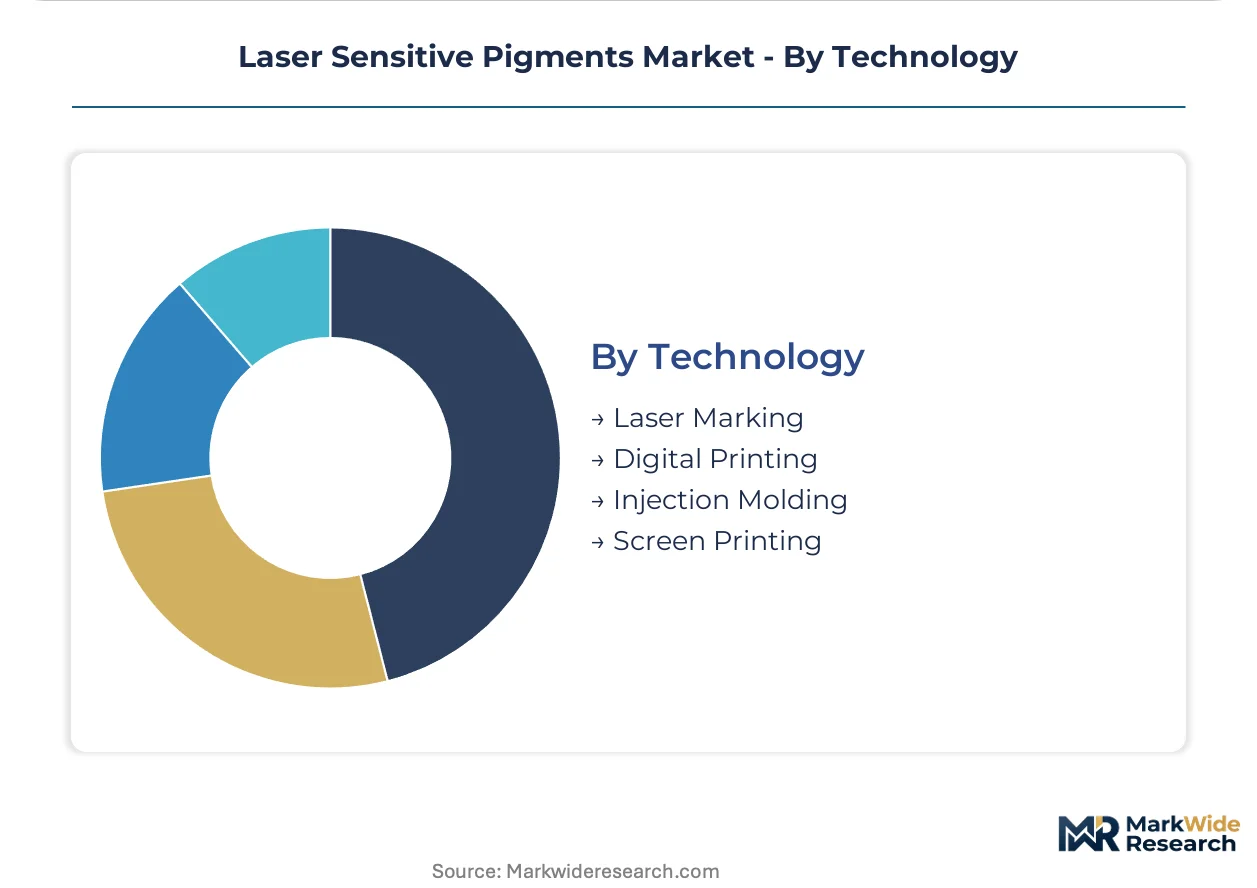
Technology:
Technology selection determines pigment formulation parameters, with laser marking imposing precise activation thresholds and digital printing demanding rheological compatibility.
- Laser Marking:Direct laser-material interaction requires pigments with defined absorption bands matched to source wavelength. YAG and fiber laser systems at 1064 nm dominate industrial marking installations.
- Digital Printing:Inkjet deposition of fluorescent nanoparticles enables on-demand serialization with variable data. Pigment surface chemistry must prevent nozzle clogging while maintaining optical contrast.
- Injection Molding:Thermal processing of laser-sensitive masterbatches requires heat-stable chromophores. Shear exposure during compounding risks premature activation of thermochromic systems.
- Screen Printing:Thick-film deposition of pigment pastes serves decorative and security applications. Viscosity tuning for mesh compatibility adds formulation complexity.
Highest technical barrier: Digital Printing. Most mature process integration: Laser Marking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical serialization mandates in Germany and the United States concentrate demand for fluorescent authentication pigments, while automotive laser-marking specifications in Stuttgart and Detroit anchor thermochromic consumption. REACH compliance costs and FDA qualification pathways reshape supplier access across major economies.
United States
Pharmaceutical track-and-trace regulations under the Drug Supply Chain Security Act pull fluorescent pigments into serialized packaging workflows. FDA color additive qualification for indirect food contact applications gates market entry for packaging film suppliers. The Northeast corridor houses serialization contractors specifying pre-validated pigment systems for high-volume drug distribution.
Germany
Automotive OEMs around Stuttgart specify laser-sensitive coatings for permanent component traceability on polymer underhood parts. ECHA's SVHC candidate list drives continuous substitution of legacy chromophores, opening procurement windows for compliant suppliers. The Ludwigshafen Verbund complex dominates bulk intermediate supply for laser-reactive chemistries serving downstream formulators.
Switzerland
Specialized colorant R&D facilities in Basel pre-validate formulations against evolving REACH chemical safety thresholds. Swissmedic pharmaceutical packaging standards mandate machine-readable optical signatures that absorb nanostructured fluorescent pigments. QA teams in Basel procurement centers now require pre-submitted toxicity data packages before vendor qualification.
India
The PLI scheme for domestic pharmaceutical manufacturing builds serialization infrastructure requiring imported authentication pigment systems. CDSCO track-and-trace alignment with global standards accelerates demand for compliant optical signatures. Maharashtra and Gujarat pharmaceutical clusters drive procurement of fluorescent masterbatches for packaging integration.
Japan
PMDA serialization requirements for pharmaceutical exports harmonize with EU and US standards, pulling compatible pigment systems into domestic packaging workflows. METI industrial standards for laser marking in automotive components specify defined activation thresholds. The Kanto region concentrates demand from precision electronics manufacturers deploying covert authentication features.
Laser Sensitive Pigments Market Competitive Landscape
German producers anchor one tier through integrated petrochemical networks; Swiss and Japanese specialists hold differentiated positions in high-purity colorant development. The market structures around three tiers: multinational chemical conglomerates with captive intermediate supply, mid-scale pigment houses with regulatory dossier capabilities, and niche specialists in security-grade formulations. Competitive moves concentrate on REACH dossier pre-validation and digital printing compatibility certification.
Within the multinational tier, Sun Chemical leverages integrated manufacturing networks to absorb compliance costs across multiple product lines. Clariant anchors its position through specialized R&D facilities that pre-validate formulations against evolving chemical safety thresholds. BASF occupies a dominant supply position for bulk laser-reactive intermediates through its Ludwigshafen complex. These three represent distinct archetypes: portfolio-scale compliance absorption, specialized validation services, and captive upstream chemical production.
| Leading Market Players |
|---|
| Sun Chemical |
| Clariant |
| BASF |
| Huntsman Corporation |
| Eckart |
| Ferro Corporation |
| Toyal |
| Kremer Pigments |
| DIC Corporation |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap pigment specialists in Germany and Switzerland maintain disciplined pricing through captive raw material positions and long-standing technical service relationships with coatings houses. Their ownership structure insulates margin pools from quarterly earnings pressure, allowing sustained investment in REACH dossier pre-validation that commodity traders cannot match.
Pricing Analysis
Short lead-time premiums of 15-25% apply to nanostructured fluorescent pigments for pharmaceutical serialization, while spot inventory of legacy thermochromic formulations trades at distressed levels. Three-tier pricing structure across premium, standard, and economy levels separates FDA-qualified colorants from REACH-compliant industrial grades and unregistered commodity alternatives. Cost compression in standard-grade photochromic pigments is intensifying because ECHA SVHC substitution has flooded the market with reformulated supply. Packaging firms in Basel and Frankfurt show least price sensitivity due to locked multi-year supply agreements, while advertising agencies purchasing interactive display pigments remain highly elastic.
Supply Chain Analysis
Dual-sourcing requirements from German automotive OEMs mandate qualified backup suppliers for laser-sensitive coatings, preventing single-source lock-in at the Ludwigshafen complex. Bulk intermediate production concentrates in Germany, Switzerland, and Japan, with nanostructured fluorescent feedstock drawing from specialized chemical synthesis in Basel and Kanto. Raw material dependencies span rare earth activators, photochromic spiropyran precursors, and thermally stable polymer carriers. Single-source vulnerability persists for YAG-laser-matched absorption chromophores synthesized exclusively at the Ludwigshafen Verbund. Distribution runs through authorized distributor networks serving coatings houses and masterbatch compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into laser-reactive intermediate synthesis to escape margin capture by the Ludwigshafen complex.
For Market Incumbents: Cement supply security through captive production of photochromic spiropyran intermediates or long-term offtake agreements with rare earth processors. ECHA's expanding SVHC candidate list threatens legacy chromophore portfolios, demanding accelerated reformulation programs. Capacity addition in Swiss R&D corridors preserves premium positioning against commodity encroachment. For New Entrants and Emerging Players: Inkjet-compatible fluorescent nanoparticles offer a technology-first wedge into pharmaceutical serialization workflows where incumbent pigment houses lack rheological formulation expertise. India's PLI-driven packaging infrastructure presents the most penetrable geography, with CDSCO track-and-trace alignment creating demand for imported authentication systems. Partner with digital printing OEMs for co-development certification. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale pigment houses with pre-submitted REACH dossiers and established technical service relationships in the Stuttgart coatings corridor. Long-term viability hinges on regulatory compliance infrastructure rather than scale economies. Watch ECHA SVHC publication timing as the inflection signal for substitution-driven procurement windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intermediates | Captive supply of laser-reactive chemistries reduces dependency on Ludwigshafen Verbund pricing power. |
| REACH Dossier Pre-Validation | Pre-submitted toxicity data packages accelerate vendor qualification with Basel and Frankfurt QA teams. |
| Digital Printing Compatibility Certification | Inkjet-compatible nanoparticle formulations merge security functions with variable-data pharmaceutical workflows. |
| Long-Term Supply Agreements | Multi-year contracts with serialization contractors lock in volume against spot market volatility. |
| Joint Venture in Indian Packaging Corridor | Domestic masterbatch production serves Maharashtra and Gujarat pharmaceutical clusters under PLI incentives. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with technical R&D directors at pigment houses, procurement leads at coatings OEMs, regulatory affairs specialists managing REACH compliance, and quality assurance managers at pharmaceutical packaging firms. ECHA SVHC candidate list updates, FDA color additive petitions, SEC 10-K disclosures from listed chemical producers, and Cefic sector reports provided validation benchmarks. Bottom-up volume estimates from application-level consumption patterns reconciled with top-down value projections across the analysis window.
Data-stream reconciliation across supply-side capacity assessments and demand-side procurement surveys shaped the analytical framework. Segmentation dimensions modeled include pigment chemistry type, end-use industry vertical, regulatory qualification tier, and regional production hub classification. CAGRs derived from weighted average of historical trajectory and forward-looking substitution elasticities, incorporating laser marking equipment installation rates and pharmaceutical serialization mandate implementation timelines as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including breakthrough photochromic durability technologies, abrupt ECHA SVHC list expansions, and trade policy disruptions affecting rare earth activator supply. Forecasts reflect documented assumptions about regulatory implementation pacing and downstream adoption curves. Deviation in ECHA SVHC substitution timelines or FDA qualification pathway delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Methylene Blue Market
Dyes and Pigments
Photoluminescent Paints Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
Pigment Dispersions Market
Dyes and Pigments
Global Paper Dyes Market
Dyes and Pigments
Global White Inorganic Pigments Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Pearl Pigment Market
Dyes and Pigments
Acrylic Colors Market
Dyes and Pigments
France Aluminium Pigments Market
Dyes and Pigments
Ponceau 4R Colors Market
Dyes and Pigments
Complex Inorganic Color Pigments Market
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
Carmine Market
Dyes and Pigments
Fluorescent Pigments Market
Dyes and Pigments
Inorganic Cosmetics Pigments Market