
 Dysprosium Acetate Market | 2026-2036
Dysprosium Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Dysprosium Acetate Market Insights
Buyer concentration among permanent magnet manufacturers is recalibrating procurement patterns across the dysprosium acetate value chain. Lynas Rare Earths Ltd leverages its Mount Weld deposit to sustain non-Chinese supply security for Western magnet producers. China Northern Rare Earth Group High-Tech Co Ltd anchors domestic acetate refining through integrated Bayan Obo operations. MP Materials Corporation competes by advancing Mountain Pass downstream processing toward separated heavy rare earth oxides.
Dysprosium acetate is the hydrated salt of dysprosium with the formula Dy(C₂H₃O₂)₃·nH₂O, typically synthesized via dissolution of dysprosium oxide or carbonate in acetic acid under controlled pH conditions, yielding a pinkish crystalline solid used primarily as a precursor for dysprosium-doped ceramics and magnetic alloys. High purity grades command premium positioning due to stringent semiconductor manufacturing specifications for thin-film deposition, while electronic grade volumes scale with magnet sector procurement. Semiconductor manufacturing applications concentrate margin pools where sputtering target purity requirements exceed four-nines thresholds, contrasting with industrial grade catalyst demand that dominates tonnage flows.
REACH registration requirements in Europe govern chemical safety documentation for acetate imports, while China's MIIT oversees rare earth separation quotas that directly constrain acetate feedstock availability. The US EPA tracks hazardous waste streams from acetate crystallization, influencing domestic production economics. Stakeholders must monitor regulatory divergence between export-controlled supply geographies and end-use certification regimes to align inventory positioning with compliance-validated demand channels.
Market Dynamics
China's MIIT rare earth separation quotas are constraining acetate feedstock flows, forcing permanent magnet manufacturers to diversify sourcing across non-Chinese processing corridors and recalibrate inventory positions against regulatory-validated supply channels.
Growth Catalysts
- Permanent magnet demand from wind turbine OEMs:Offshore wind installations require dysprosium-doped neodymium magnets for high-temperature corrosion resistance, pulling acetate volumes into magnet precursor supply chains.
- REACH registration compliance in Europe:ECHA chemical safety documentation mandates for acetate imports are validating qualified suppliers and creating preferential procurement pathways for registered refiners.
- Semiconductor thin-film deposition specifications:Four-nines purity grades for sputtering targets are commanding premium positioning as chip fabrication expands captive acetate refining for magnetic alloy precursors.
Market Restraints
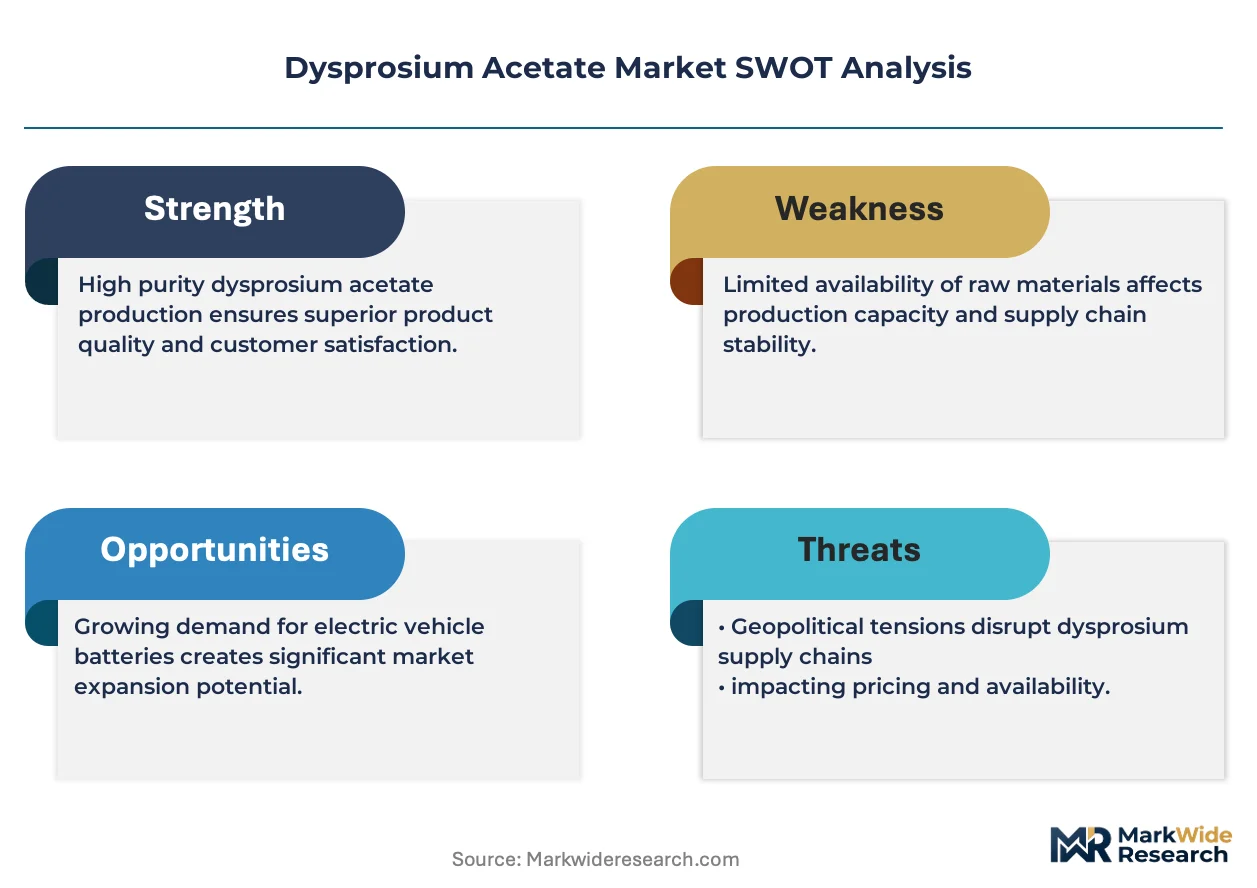
- Heavy rare earth oxide price volatility:Dysprosium oxide spot market swings transmit directly to acetate production economics, compressing margins for non-integrated refiners.
- Bayan Obo supply concentration:China's Northern Rare Earth Group controls dominant oxide feedstock volumes, creating single-source vulnerability for acetate processors outside integrated operations.
- Terbium substitution in high-temperature magnets:Magnet designers are partially substituting terbium for dysprosium in certain thermal stability applications, capping acetate demand elasticity.
Strategic Opportunities
- US downstream processing expansion:MP Materials Corporation's Mountain Pass separation facility is advancing toward heavy rare earth oxide output, creating non-Chinese acetate feedstock potential for Western magnet makers.
- Japan's magnet maker captive refining:TDK Corporation and Hitachi Metals are integrating acetate-to-magnet precursor production, opening tolling partnerships for qualified chemical processors.
- EU Green Deal critical raw materials autonomy targets:The European Commission's 2030 domestic processing mandates are incentivizing acetate refining investments within member state industrial corridors.
Industry Challenges
- Separations chemistry expertise scarcity:Solvent extraction and ion exchange specialists capable of heavy rare earth purification are concentrated at Chinese state-owned enterprises, constraining Western facility staffing.
- EPA hazardous waste compliance for crystallization effluent:US-based acetate producers face elevated environmental remediation costs from acetic acid recovery and rare earth-laden wastewater treatment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dysprosium Acetate Market |
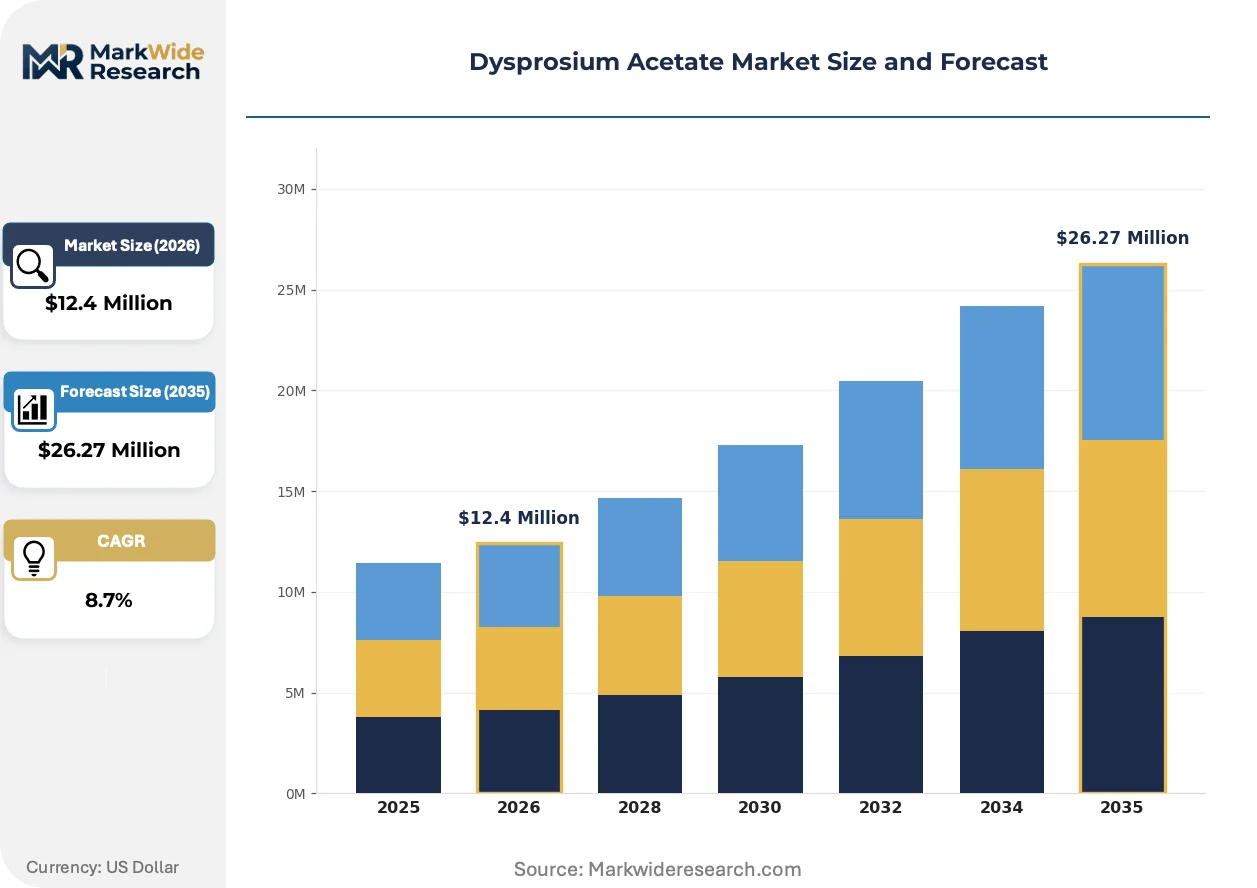
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $26.27 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Industrial Grade, Electronic Grade, Laboratory Grade Application: Catalysts, Research, Semiconductor Manufacturing, Additives End User: Healthcare, Electronics, Aerospace, Renewable Energy Packaging Type: Bulk Packaging, Glass Bottles, Sachets, Drums |
| Companies Covered | Lynas Rare Earths Ltd, China Northern Rare Earth Group High-Tech Co Ltd, MP Materials Corporation, Shenghe Resources Holding Co Ltd, Iluka Resources Limited, Arafura Resources Limited, Neo Performance Materials Inc, China Minmetals Rare Earth Co Ltd, Inner Mongolia Baotou Steel Rare-Earth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dysprosium Acetate Market Trends and Innovations
Acetate refining technology is bifurcating between semiconductor-grade purity achievements and industrial-scale cost optimization, with regulatory certification becoming the primary competitive differentiator across end-use verticals.
Continuous flow reactor synthesis is expanding into dysprosium acetate production, replacing batch crystallization with automated pH-controlled dissolution systems. Wind turbine magnet manufacturers are adopting flow-produced acetate for consistent dopant ratios in neodymium-iron-boron sintering. This process standardization is compressing qualification timelines for new suppliers entering renewable energy supply chains.
REACH authorization requirements are tightening chemical substance documentation for European acetate importers, mandating full supply chain disclosure from oxide mine to final salt. ECHA's 2024 updated guidance on rare earth compound classification is forcing non-EU refiners to establish EU-based only representative structures. Semiconductor equipment OEMs in Germany and the Netherlands are prioritizing REACH-registered acetate sources for sputtering target fabrication.
Magnet makers are consolidating acetate procurement through long-term offtake contracts with separation facilities, displacing spot market purchasing. Japanese automotive tier-1 suppliers are locking five-year supply agreements directly with Mount Weld and Mountain Pass downstream projects. This contract concentration is most visible in electric drive motor supply chains, where OEMs demand provenance-certified heavy rare earth documentation for ESG compliance reporting.
Dysprosium Acetate Market Segmentation
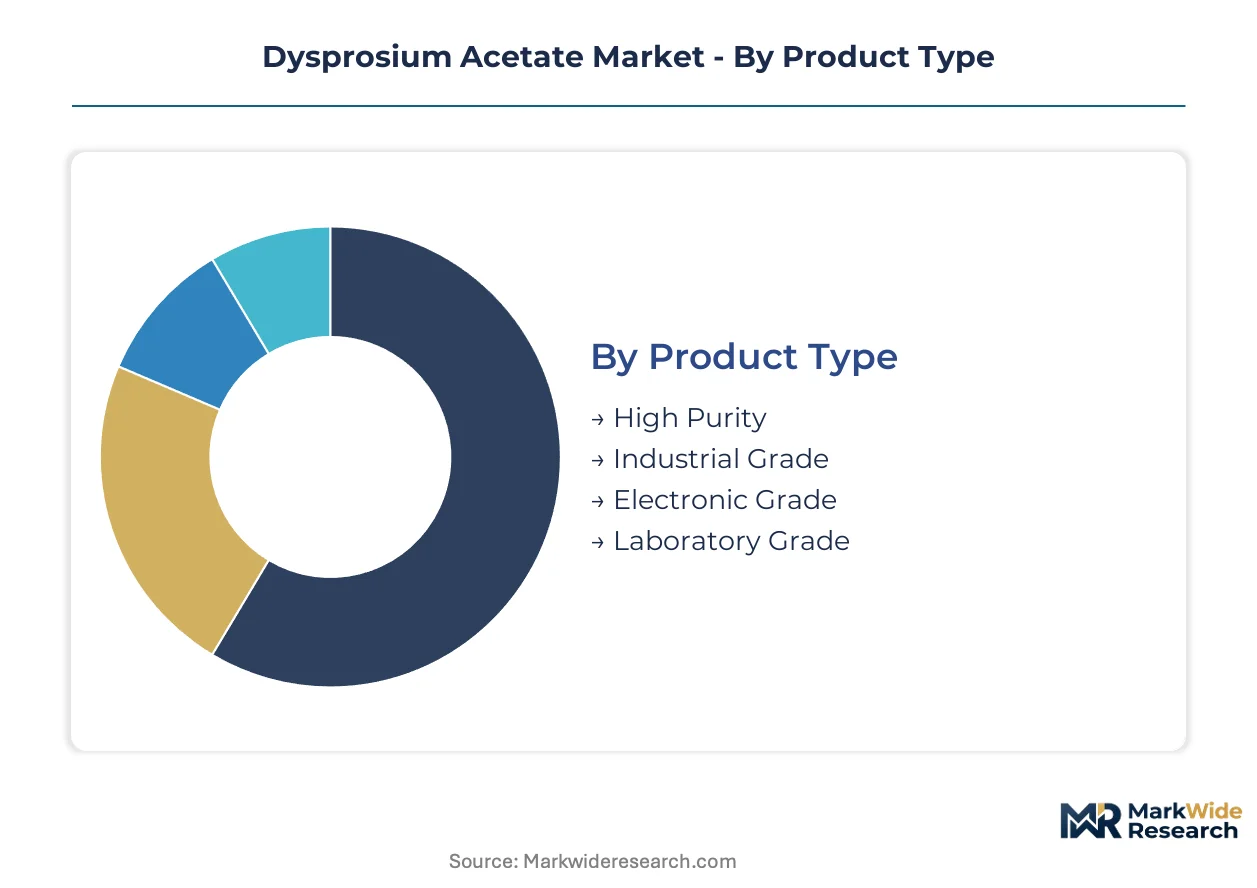
Dysprosium acetate procurement patterns diverge sharply across purity thresholds and end-use certification requirements. Segment boundaries harden where REACH registration, semiconductor specifications, and magnet sector dopant ratios create non-substitutable demand channels.
Product Type:
Integration depth varies from standalone chemical supply to embedded precursor systems, with purity grades determining downstream process compatibility.
- High Purity:Four-nines specification (99.99% Dy content) eliminates metallic impurities for sputtering target fabrication. Semiconductor OEMs in Germany and the Netherlands validate REACH-registered sources for thin-film deposition equipment, with ECHA substance documentation mandatory for import clearance.
- Electronic Grade:Three-nines purity balanced against volume scalability for neodymium-iron-boron magnet doping. Wind turbine OEMs in Denmark and Spain specify electronic grade acetate for high-temperature corrosion resistance in offshore generator assemblies.
- Industrial Grade:Standardized hydrate salt for ceramic pigment and glass additive manufacturing.
- Laboratory Grade:Small-batch crystalline supply for analytical reference standards and academic research protocols.
Volume placements concentrate in Electronic Grade; the faster expansion belongs to High Purity.
Application:
Cost tier stratification separates commodity catalyst demand from premium deposition chemistry, with certification overhead driving margin dispersion.
- Semiconductor Manufacturing:Sputtering target precursor requiring ion chromatography validation for alkali metal content below 10 ppm. Japanese equipment makers Hitachi High-Tech and TEL specify acetate provenance from non-Chinese separation corridors to satisfy supply chain audit requirements.
- Catalysts:Hydrated acetate deployed in organic synthesis and polymerization acceleration. Industrial chemical processors in India and Brazil source tonnage quantities through spot market channels, with price sensitivity overriding purity premiums.
- Research:Institutional procurement for materials science and rare earth coordination chemistry investigation.
- Additives:Ceramic and glass matrix incorporation for UV absorption and refractive index modification.
Margin pools concentrate in Semiconductor Manufacturing; Catalysts dominate absolute tonnage flows.
End User:
Customer type fragmentation maps to certification intensity, with automotive and medical device sectors imposing the most stringent documentation burdens.
- Renewable Energy:Permanent magnet manufacturers for direct-drive wind turbine generators. Vestas and Siemens Gamesa specify dysprosium doping ratios between 4-8% by weight for offshore installations exceeding 10 MW capacity.
- Electronics:Hard disk drive actuator magnets and smartphone vibration motor assemblies. South Korean component suppliers Samsung Electro-Mechanics and LG Innotek integrate acetate refining into captive magnet precursor operations.
- Healthcare:MRI contrast agent synthesis and medical laser crystal fabrication.
- Aerospace:Satellite attitude control momentum wheel magnets and avionics shielding applications.
Procurement concentration sits with Renewable Energy; Electronics shows the steepest expansion trajectory.
Packaging Type:
Supply chain configuration determines format selection, with bulk logistics favoring integrated processors and specialty packaging serving distributed laboratory networks.
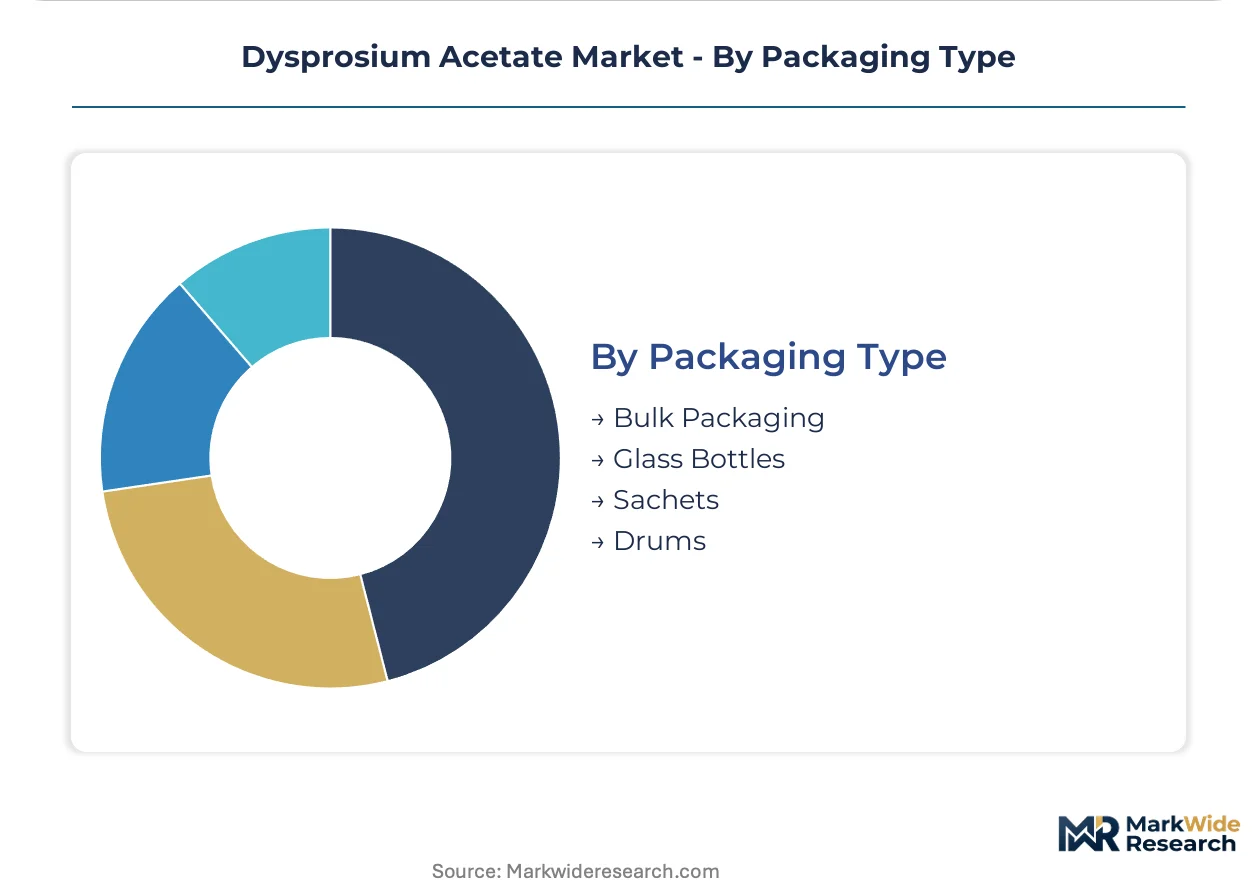
- Drums:Standard 200-liter steel containment for industrial-scale acetate hydrate shipments. Chinese refiners China Northern Rare Earth and Shenghe Resources deploy drum packaging for containerized export to European magnet makers.
- Bulk Packaging:Flexible intermediate bulk containers and silo truck delivery for continuous flow reactor feedstock. MP Materials Corporation's Mountain Pass downstream project targets bulk format for Western automotive supply chain integration.
- Glass Bottles:Amber borosilicate vials for semiconductor-grade moisture protection.
- Sachets:Polyethylene-aluminum laminate pouches for laboratory and research quantity distribution.
Shipment volumes concentrate in Drums; Bulk Packaging gains share fastest as Western separation capacity advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permanent magnet manufacturers cluster procurement in East Asian processing corridors, with Western separation projects advancing to diversify oxide feedstock access. Regulatory divergence between export-controlled supply geographies and end-use certification regimes shapes inventory positioning strategies.
China
Wind turbine OEMs and electric vehicle motor producers drive acetate demand through neodymium-iron-boron magnet supply chains. MIIT rare earth separation quotas directly constrain feedstock availability for acetate refiners. Bayan Obo operations in Inner Mongolia anchor integrated oxide-to-acetate production for domestic magnet makers.
Japan
TDK Corporation and Hitachi Metals expand captive acetate refining for automotive and electronics magnet precursors. METI critical mineral stockpiling programs incentivize supply chain resilience investments. Nagoya and Osaka industrial corridors concentrate magnet precursor manufacturing with integrated chemical processing.
United States
MP Materials Corporation advances Mountain Pass downstream separation toward heavy rare earth oxide output for Western acetate production. EPA hazardous waste tracking elevates environmental compliance costs for domestic crystallization operations. Texas and California host emerging magnet alloy fabrication facilities seeking non-Chinese acetate sources.
Germany
Siemens Gamesa and Vestas specify dysprosium-doped magnets for offshore wind installations exceeding 10 MW capacity. REACH registration requirements validate qualified acetate suppliers for semiconductor and renewable energy applications. Eindhoven-Dortmund industrial corridor concentrates thin-film deposition equipment manufacturing with stringent purity specifications.
Australia
Lynas Rare Earths Ltd leverages Mount Weld deposit to sustain non-Chinese supply security for Western magnet producers. Critical minerals processing incentives under national industrial policy support downstream separation investments. Kalgoorlie and Mount Weld processing sites anchor heavy rare earth oxide output for export acetate refining.
Dysprosium Acetate Market Competitive Landscape
Chinese producers anchor one tier through integrated Bayan Obo operations; Australian and North American specialists hold emerging positions through mine-to-magnet separation projects. Market structure bifurcates between state-backed integrated refiners and independent downstream processors seeking captive oxide access. Three archetypes dominate: integrated mining-refining conglomerates, independent chemical processors, and magnet-maker captive operations. Capacity expansion and strategic offtake contracting represent the dominant competitive moves as Western separation projects advance.
Among integrated rare earth conglomerates, China Northern Rare Earth Group High-Tech Co Ltd and Inner Mongolia Baotou Steel Rare-Earth occupy positions exemplifying state-backed vertical control over oxide-to-acetate production. Lynas Rare Earths Ltd represents the non-Chinese supply security archetype, anchoring Western magnet maker procurement diversification through Mount Weld feedstock. These three companies illustrate the geographic and structural segmentation defining competitive positioning in heavy rare earth acetate supply chains.
| Leading Market Players |
|---|
| Lynas Rare Earths Ltd |
| China Northern Rare Earth Group High-Tech Co Ltd |
| MP Materials Corporation |
| Shenghe Resources Holding Co Ltd |
| Iluka Resources Limited |
| Arafura Resources Limited |
| Neo Performance Materials Inc |
| China Minmetals Rare Earth Co Ltd |
| Inner Mongolia Baotou Steel Rare-Earth |
| Others |
Pricing and Supply Chain Analysis
Dysprosium oxide spot quotations cascade through acetate conversion economics, compressing margins for non-integrated refiners while amplifying pricing power for Bayan Obo-anchored producers. Contract-based long-term offtake agreements are displacing spot procurement as Japanese automotive tier-1 suppliers lock supply visibility for ESG-compliant magnet documentation.
Pricing Analysis
Volume placements concentrate in electronic grade acetate for wind turbine magnet doping, while high purity four-nines specifications command semiconductor-grade premiums. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered semiconductor sources from industrial catalyst grades, with certification overhead driving 40-60% spreads between tiers. Cost compression in standard-grade channels is intensifying because Chinese export quota adjustments constrain oxide feedstock availability. Catalyst processors in India and Brazil exhibit highest price sensitivity, prioritizing tonnage scale over purity thresholds.
Supply Chain Analysis
Dual-sourcing mandates from Vestas and Siemens Gamesa require permanent magnet manufacturers to qualify oxide suppliers across Chinese and non-Chinese separation corridors simultaneously. Geographic supply concentration centers on China, Australia, and the United States, with Mount Weld and Mountain Pass projects advancing Western feedstock alternatives. Raw material dependencies rest on dysprosium oxide concentrate, acetic acid reagent supply, and crystallization energy inputs. Single-source vulnerability persists around Bayan Obo heavy rare earth output. Distribution runs through drum-packaged containerized shipments for Asian magnet makers and bulk silo delivery for Western automotive integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dysprosium acetate market is a vertical-integration race where upstream oxide control and downstream magnet precursor access determine competitive survival. Players are pursuing captive separation capacity as the decisive lever.
For Market Incumbents: Deploy long-term offtake contracting to lock oxide feedstock before Western separation projects reach commercial output. China Northern Rare Earth Group and Lynas Rare Earths should deepen solvent extraction expertise pools to defend against terbium substitution threats in high-temperature magnet applications. Captive refining integration into automotive supply chains represents the priority defensive position.
For New Entrants and Emerging Players: Enter via tolling partnerships with Japanese magnet makers seeking qualified acetate processors outside Chinese supply chains. The most penetrable white-space sits in European REACH-registered refining for German and Dutch semiconductor equipment OEMs. A go-to-market angle emphasizing ESG-provenance documentation for renewable energy procurement committees opens contract pathways.
For Investors and Strategic Acquirers: Distressed-cycle entries favor solvent-extraction technology specialists in Australian and North American geographies where critical minerals policy incentives reduce capital recovery risk. Long-term viability over the next decade hinges on heavy rare earth separation chemistry capabilities rather than standalone acetate conversion assets. Watch MIIT quota announcement timing as the inflection signal for feedstock availability stress.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oxide Separation | MP Materials Corporation's Mountain Pass downstream project reduces Chinese feedstock dependency for Western magnet makers. |
| REACH Registration Investment | ECHA compliance documentation opens preferential procurement channels with German semiconductor equipment manufacturers. |
| Captive Acetate-to-Magnet Precursor Operations | TDK Corporation and Hitachi Metals integrate chemical processing to secure dopant ratio consistency for automotive motors. |
| Continuous Flow Reactor Deployment | Automated pH-controlled dissolution systems compress supplier qualification timelines for Vestas and Siemens Gamesa. |
| Long-term Supply Agreement Structuring | Five-year offtake contracts with Mount Weld and Mountain Pass projects displace spot market volatility for tier-1 automotive suppliers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this dysprosium acetate market assessment. Primary interviews with rare earth separation plant managers, permanent magnet procurement leads at wind turbine OEMs, acetate distribution channel partners, and semiconductor sputtering target technical directors combined with MIIT quota announcements, ECHA substance registrations, and SEC 10-K disclosures from listed rare earth companies. Bottom-up volume modeling across purity grades and applications triangulated against top-down oxide feedstock availability estimates.
Segment-level granularity modeled purity tiers, end-use verticals, packaging formats, and regional processing hub configurations across the projection horizon. CAGRs derived from weighted average of historical oxide-to-acetate conversion ratios and forward capacity expansion announcements. Forecast inputs incorporated wind turbine installation pipelines, electric vehicle motor content specifications, and semiconductor fabrication equipment capex trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT quota restriction scenarios or accelerated terbium substitution in magnet thermal stability applications. Deviation in Chinese export licensing timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
Oxygen Scavenger Masterbatch Market
Specialty Compounds
White Carbon Black Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Polypropylene Compounds Market
Specialty Compounds
Lauramidopropyl Betaine Market
Specialty Compounds
High Performance Foam Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
United States Caustic Potash Market
Specialty Compounds
Liquid Ammonium and Liquid Potassium Thiosulfate Market
Specialty Compounds
Organosulfur Compounds Market
Specialty Compounds
Methane Sulfonyl Chloride Market
Specialty Compounds
North America Lithium Compound Market
Specialty Compounds
Automated Compound Storage and Retrieval (ACSR) Market