
 Bahrain Paints and Coatings Market | 2026-2036
Bahrain Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Bahrain Paints and Coatings Market Outlook
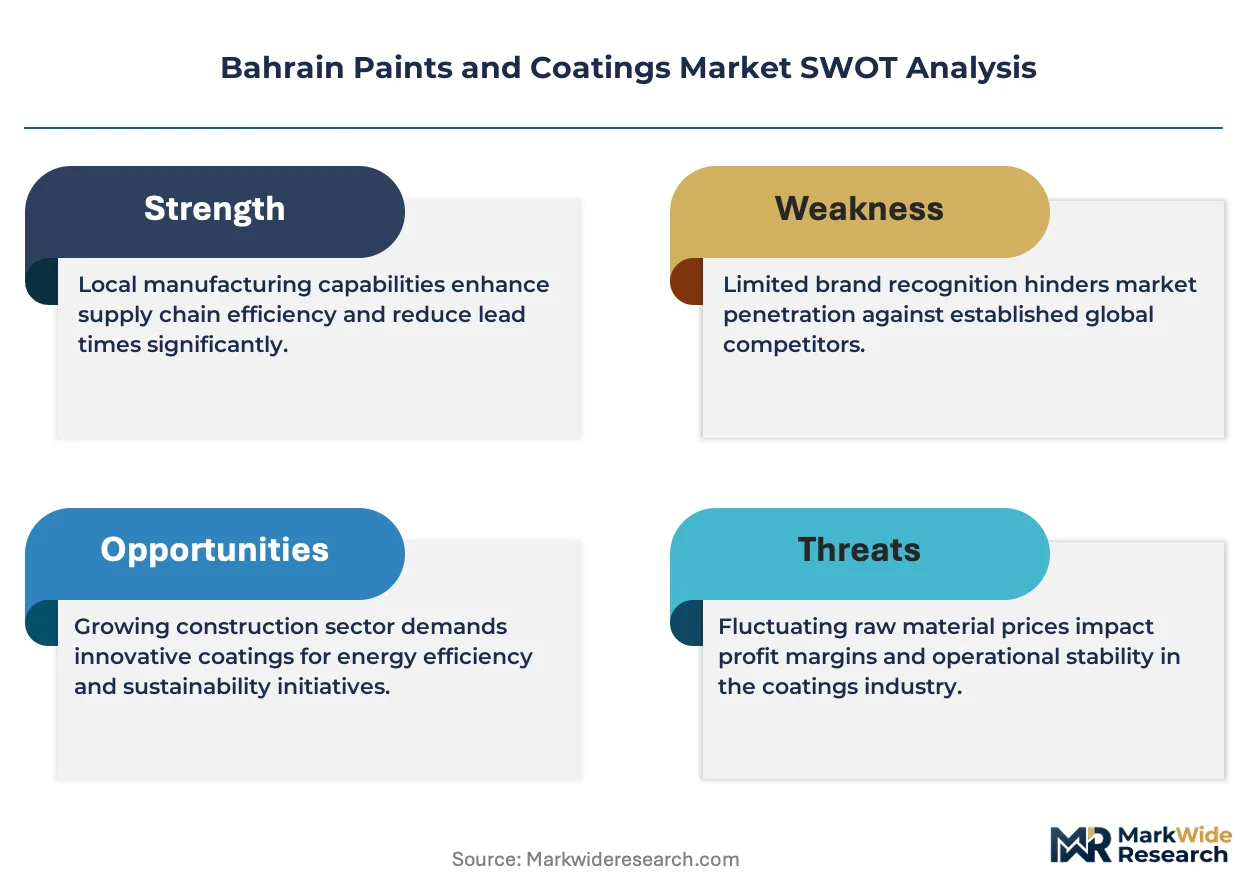
Specialty retail and direct-contractor supply in Bahrain is tilting toward consolidated distribution hubs near the Sitra industrial zone. Hempel leverages its marine coatings expertise to sustain project wins at the Khalifa Bin Salman Port expansion. Jotun anchors the decorative segment through dedicated color concept stores in Manama and Riffa. Legend Paints Company W L L competes on localized production and rapid custom tinting turnaround for mid-tier contractors.
Paints and coatings are liquid, powder, or curable film-forming materials composed of binders, pigments, solvents, and additives that cure to protective or decorative layers on substrates. Epoxy formulations achieve dry-film thicknesses of 200-500 microns and serve primarily to prevent corrosion on steel infrastructure in marine and industrial settings. Architectural coatings occupy the largest volume share due to continuous residential and commercial building activity across Bahrain's governorates. Industrial formulations, particularly polyurethane systems for the automotive and furniture sectors, represent the fastest-expanding margin pool as durability specifications tighten. Protective coatings command premium pricing in offshore and petrochemical applications where NORSOK and ISO 12944 compliance is mandatory.
Bahrain's national regulator for industrial standards enforces conformity with Gulf Standardization Organization (GSO) specifications for VOC content and lead-free formulations, while the Ministry of Works mandates environmental product declarations on large public tenders. These frameworks elevate compliance costs for imported alkyd systems while creating preferential market access for regional manufacturers with certified water-based portfolios. Stakeholders must monitor how upcoming amendments to the Bahrain Green Building Council rating tools redefine permissible coating chemistries across government-funded developments.
Market Dynamics
Bahrain's Ministry of Works is tightening VOC emission limits under the national green building code, forcing manufacturers to abandon solvent-borne alkyds for water-based acrylic systems. This regulatory compression is restructuring raw material sourcing and tinting infrastructure across the Northern Governorate.
Growth Catalysts
- Infrastructure Megaprojects:Waterfront developments and port expansions in the Northern Governorate are absorbing protective epoxy and polyurethane volumes for steel infrastructure.
- GSO VOC Standards:Gulf Standardization Organization specifications for low-emission formulations are accelerating certified water-based portfolio investments by regional manufacturers.
- Marine Coatings Demand:Khalifa Bin Salman Port expansion and offshore maintenance cycles are pulling specialized anti-corrosive systems.
Market Restraints
- Titanium Dioxide Volatility:Pigment cost swings compress margin stability for decorative coating producers serving mid-tier residential contractors.
- Import Dependency:Specialized epoxy hardeners and isocyanate curing agents concentrate supply from Saudi and UAE chemical hubs, exposing Bahraini formulators to cross-border logistics friction.
- Alkyd Transition Costs:Legacy solvent-borne inventory and application equipment depreciation create stranded asset risk for distributors.
Strategic Opportunities
- Southern Governorate Penetration:Underserved residential construction in Riffa and Isa Town offers decorative volume expansion for localized tinting operations.
- Digital Color Matching:Spectrophotometer-linked dispensing systems are enabling same-day custom formulation for contractor direct supply.
- Bahrain Green Building Council Amendments:Upcoming rating tool revisions will mandate environmental product declarations on government tenders, favoring certified domestic producers.
Industry Challenges
- Applicator Skill Shortage:Certified spray technicians for high-build epoxy and intumescent systems remain scarce, delaying project completion on industrial sites.
- Certification Timeline Compression:GSO conformity assessment and Ministry of Works approval cycles for new water-based formulations extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bahrain Paints and Coatings Market |
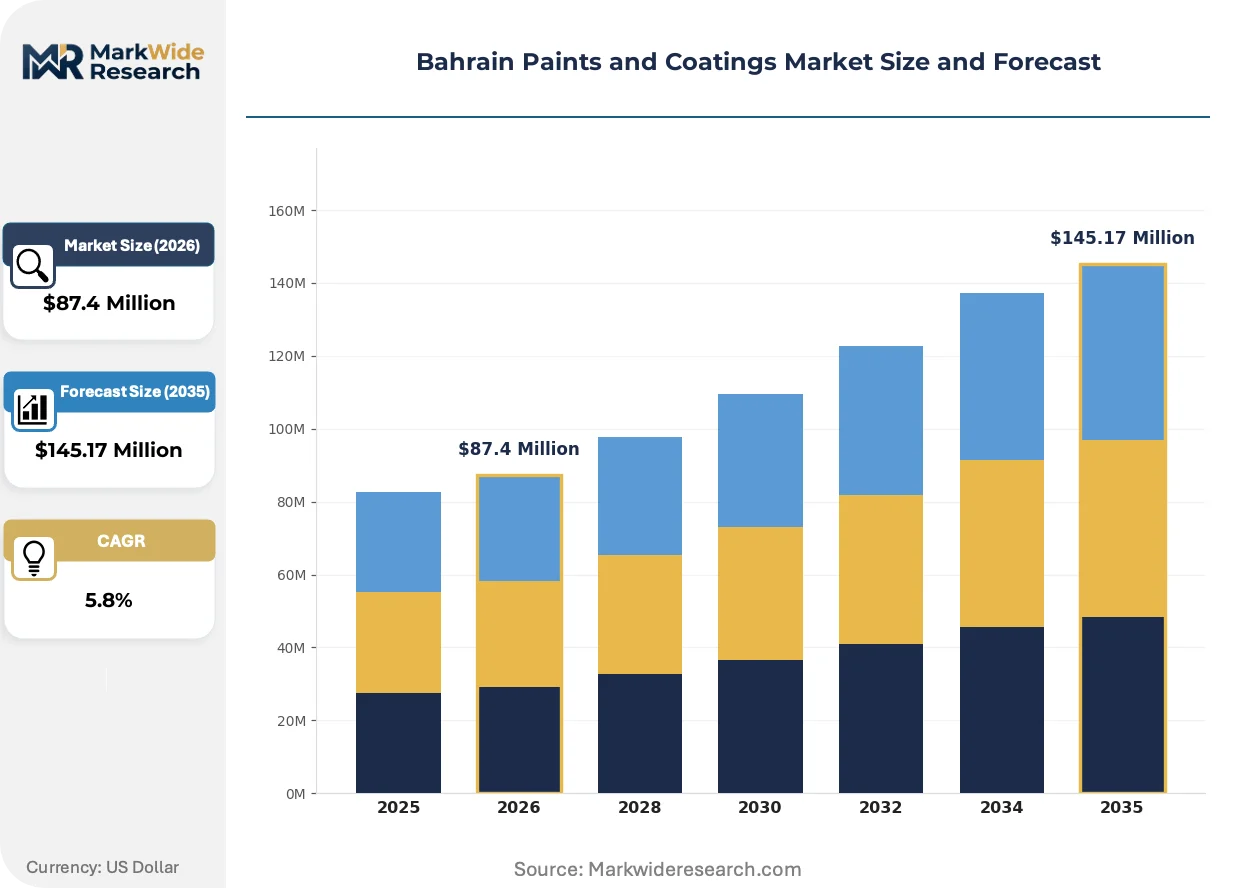
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $145.17 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural, Industrial, Protective, Decorative Formulation: Acrylic, Alkyd, Epoxy, Polyurethane Application Method: Brush, Roller, Spray, Dip End Use: Construction, Automotive, Marine, Furniture |
| Companies Covered | Hempel, The Sherwin-Williams Company, Jotun, Legend Paints Company W L L, Omega Paints & Chemical Industries, PPG Industries, Caparol, Akzo Nobel, Asian Paints Berger, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bahrain Paints and Coatings Market Strategic Shifts
Formulation chemistry and application infrastructure in Bahrain are converging around low-emission compliance and digital service integration. Manufacturers are rebuilding supply chains and customer interfaces simultaneously.
Spectrophotometer-linked tinting systems are digitizing color matching and order fulfillment for decorative coatings. Mid-tier contractors in Manama and Muharraq are adopting these platforms to compress specification-to-delivery cycles. The technology is digitizing inventory management and reducing working capital requirements for distributors.
Bahrain's Ministry of Works is mandating environmental product declarations on public tenders above defined value thresholds. This policy is elevating documentation costs for imported systems while creating preferential access for regional manufacturers with certified portfolios. Large infrastructure projects in the Northern Governorate are responding by pre-qualifying suppliers based on EPD availability.
Direct-contractor supply channels are displacing traditional distributor intermediation in the decorative segment. Project developers in waterfront zones are consolidating purchases through dedicated procurement platforms linked to manufacturer tinting hubs. This pattern is most visible in Manama, where consolidated distribution infrastructure near Sitra enables next-day delivery commitments.
Bahrain Paints and Coatings Market Segmentation
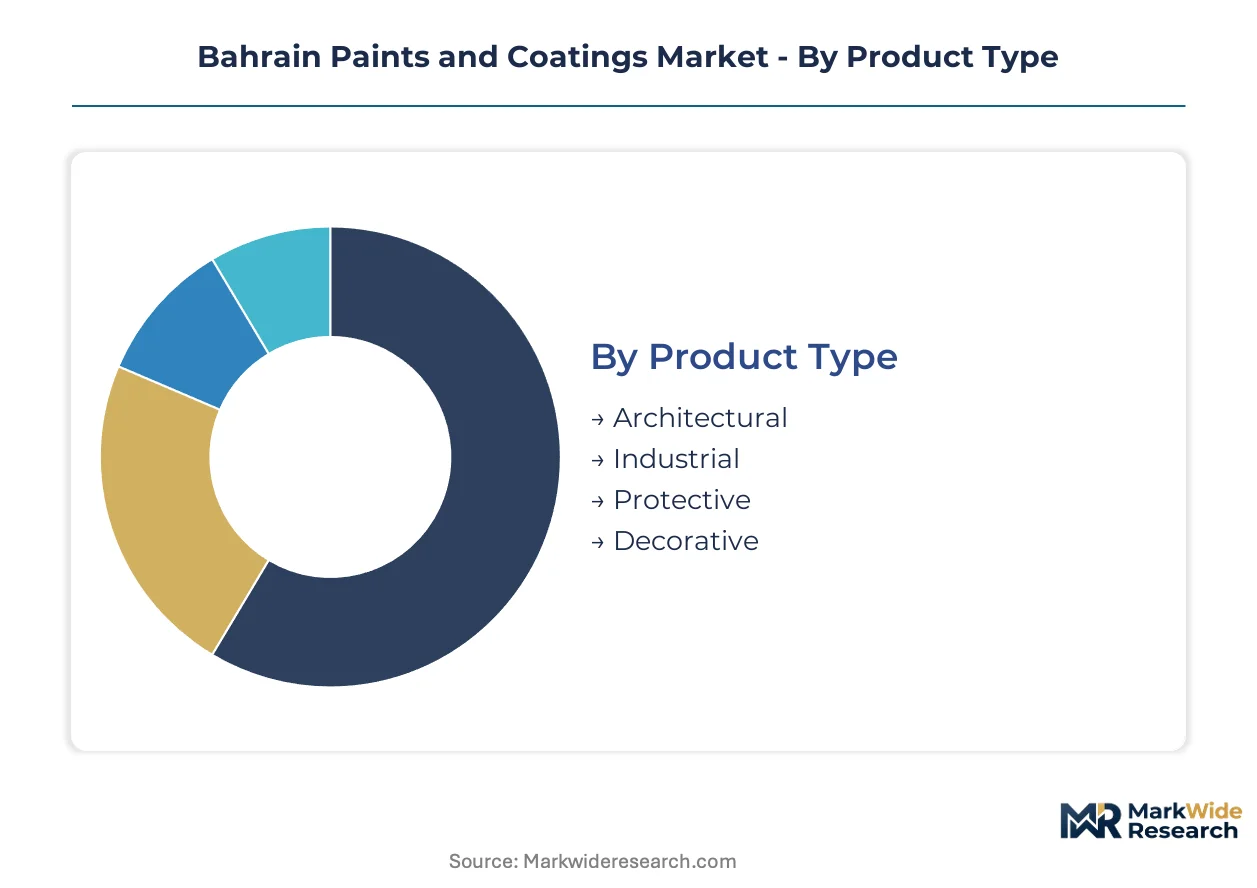
Segmentation in Bahrain's paints and coatings market reveals how formulation chemistry, application infrastructure, and end-use specifications create distinct margin pools. Each dimension carries different inventory velocities and certification burdens that reshape competitive positioning across the Northern Governorate and Sitra industrial corridor.
Product Type:
Architectural coatings turn inventory fastest through residential construction cycles, while protective systems sit longest on specification timelines tied to infrastructure procurement.
- Architectural:Water-based acrylic and emulsion systems formulated for interior and exterior building surfaces. Demand concentrates in Manama and Muharraq residential towers where the Ministry of Works mandates low-VOC compliance on public housing tenders.
- Industrial:High-performance coatings for manufacturing equipment and process infrastructure. Automotive assembly plants in the Sitra industrial zone and furniture factories in Riffa are absorbing polyurethane and epoxy formulations as durability specifications tighten.
- Protective:Heavy-duty systems engineered for corrosion resistance on steel substrates in marine and petrochemical environments.
- Decorative:Aesthetic finishes emphasizing color breadth and application ease for residential and commercial interiors.
Architectural dominates installed base. Industrial is where expansion concentrates.
Formulation:
Cost tiers separate commodity acrylics from premium polyurethanes, with compliance-grade water-based systems commanding margin premiums over legacy solvent chemistry.
- Acrylic:Water-dispersed polymers dominating decorative and architectural applications for rapid drying and low odor. Northern Governorate residential projects are specifying these systems to meet Bahrain Green Building Council emission thresholds.
- Alkyd:Oil-modified polyester resins traditionally favored for gloss retention and substrate penetration. Solvent-borne inventories face stranded asset risk as GSO VOC standards tighten, though low-odor variants retain niche demand in maintenance repainting.
- Epoxy:Two-component thermosetting systems achieving 200-500 micron dry-film thickness for chemical and abrasion resistance.
- Polyurethane:Aliphatic and aromatic isocyanate-cured films delivering UV stability and flexible durability.
Acrylic holds volume leadership. Polyurethane is climbing the fastest on specification upgrades.
Application Method:
Equipment intensity varies sharply, with spray systems requiring capital investment and certified technicians while brush and roller remain accessible to general labor pools.
- Brush:Manual application using bristle or synthetic filament tools for detailed work and touch-up. Riffa and Isa Town residential contractors favor brush methods for interior decorative finishes where masking precision matters.
- Roller:Nap-textured cylinders for rapid coverage of large planar surfaces. Mid-tier construction crews across Muharraq deploy roller systems to compress application timelines on apartment block interiors.
- Spray:Airless and conventional atomization equipment for high-build industrial and protective coatings.
- Dip:Immersion coating for small components and uniform film formation.
Roller commands the broadest contractor base. Spray is gaining share fastest on industrial project scale-up.
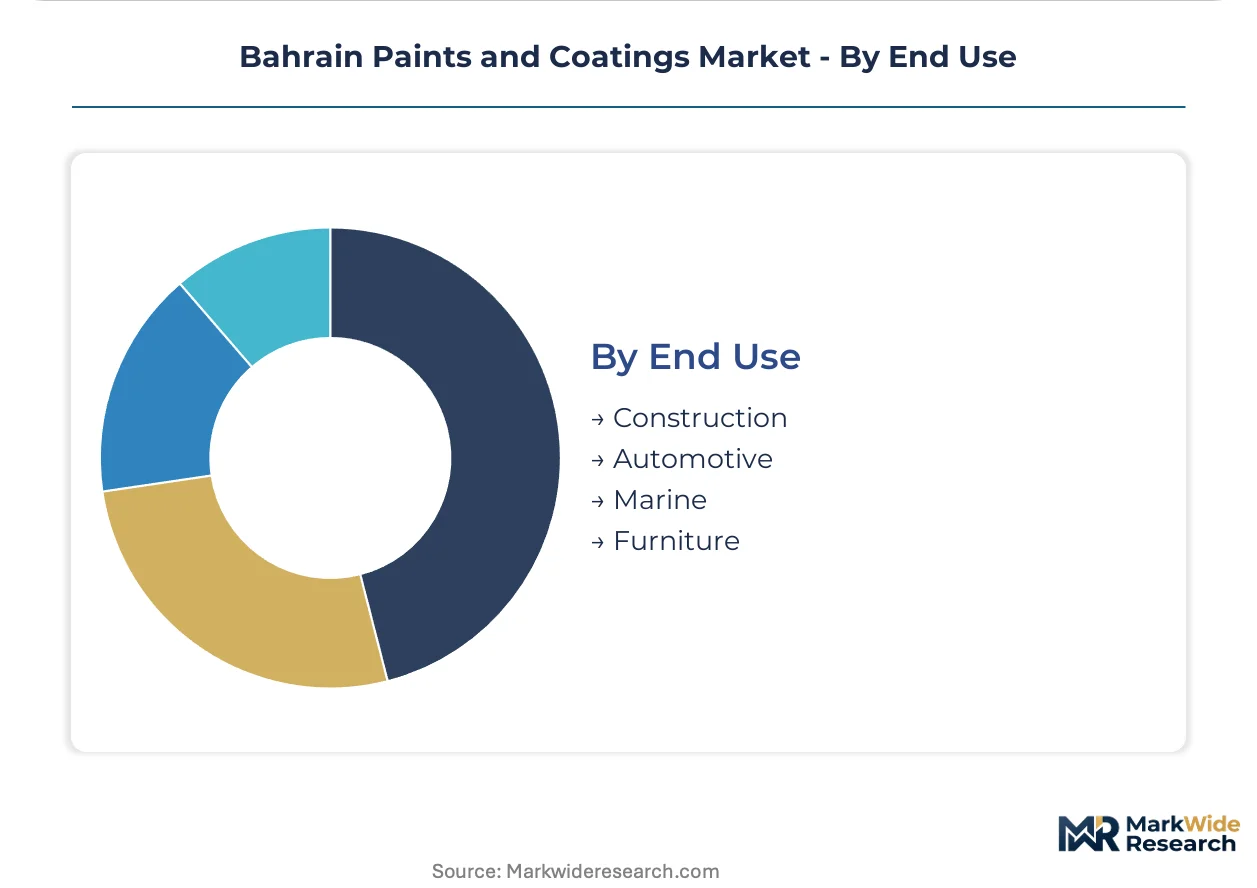
End Use:
Customer type separates project-driven construction demand from recurring maintenance cycles in marine and automotive sectors.
- Construction:New build and renovation activity across residential, commercial, and infrastructure verticals. Waterfront developments in the Northern Governorate are pulling protective epoxy volumes for steel reinforcement in high-salinity environments.
- Automotive:OEM finishing and refinish coatings for vehicle assembly and repair. Local assembly operations and premium detailing shops in Manama are specifying polyurethane clearcoats as durability expectations rise.
- Marine:Anti-corrosive and antifouling systems for vessels and port infrastructure.
- Furniture:Wood finishing and decorative coatings for cabinetry and interior fixtures.
Construction anchors volume demand. Marine is where specification value concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bahrain's Ministry of Works anchors regulatory pressure across the island's construction corridors. The national green building code and GSO VOC standards are compressing formulation choices while concentrating demand in the Northern Governorate.
Northern Governorate
Waterfront developments and port infrastructure at Khalifa Bin Salman Port are absorbing protective epoxy and polyurethane volumes for steel reinforcement. The Ministry of Works mandates environmental product declarations on public tenders above defined thresholds. Manama and Muharraq residential towers are specifying water-based acrylic systems to meet emission limits.
Southern Governorate
Residential construction in Riffa and Isa Town offers decorative volume expansion for localized tinting operations. The Bahrain Green Building Council rating tool revisions are elevating documentation requirements for imported systems. Mid-tier contractors in Sitra industrial zone proximity are consolidating procurement through direct-manufacturer platforms.
Central Governorate
Automotive assembly plants and furniture factories are pulling polyurethane formulations as durability specifications tighten. GSO conformity assessment cycles for new water-based products extend launch windows for formulators. The Sitra industrial corridor hosts consolidated distribution hubs enabling next-day delivery commitments to project sites.
Muharraq Governorate
Marine maintenance cycles and vessel repair yards are sustaining demand for anti-corrosive coating systems. The Ministry of Works enforces Gulf Standardization Organization specifications for VOC content and lead-free formulations. Color concept stores and digital spectrophotometer-linked tinting systems are compressing specification-to-delivery cycles for decorative finishes.
Bahrain Paints and Coatings Market Competitive Environment
Marine-specialist multinationals and regional decorative producers split the market across divergent specification timelines. The structure concentrates around port-proximate protective coatings and residential-tinted architectural systems. Three archetypes dominate: European marine coating specialists with project engineering capabilities, Nordic decorative brands with retail color infrastructure, and localized Bahraini formulators with rapid custom turnaround. Competitive moves center on direct-contractor supply channel expansion and water-based portfolio certification investments.
Within the marine-specialist tier, Hempel and Jotun occupy positions shaped by project engineering depth and color retail infrastructure respectively. Legend Paints Company W L L exemplifies the localized Bahraini formulator archetype with production proximity to mid-tier contractor demand. These three anchors illustrate how specification complexity, retail service intensity, and geographic responsiveness define competitive positioning under tightening VOC regulation.
| Leading Market Players |
|---|
| Hempel |
| The Sherwin-Williams Company |
| Jotun |
| Legend Paints Company W L L |
| Omega Paints & Chemical Industries |
| PPG Industries |
| Caparol |
| Akzo Nobel |
| Asian Paints Berger |
| Others |
Value Chain & Pricing Dynamics
Titanium dioxide volatility compresses margin stability across decorative coating tiers while simultaneously forcing supply chain restructuring toward Saudi and UAE chemical hubs for epoxy hardeners and isocyanate curing agents. This pigment cost instability widens pricing spreads between certified water-based systems and legacy solvent-borne inventories, with compliance-grade formulations commanding measurable premiums as GSO VOC standards tighten.
Pricing Analysis
The customization-premium spread separates rapid-tint architectural coatings from standard protective systems, with three-tier pricing structure across premium, standard, and economy levels anchoring competitive positioning. Price differentiation hinges on Bahrain Green Building Council certification grade and volume scale, with bulk procurement by Northern Governorate infrastructure developers securing favorable terms. Cost compression in mid-tier decorative segments intensifies because titanium dioxide swings erode producer margins. Residential contractors in Riffa and Isa Town exhibit highest price sensitivity, while offshore petrochemical operators prioritize NORSOK-compliant systems over cost.
Supply Chain Analysis
Tariff exposure between Saudi Arabia and Bahrain dominates raw material procurement risk for specialized epoxy hardeners and isocyanate curing agents. Geographic supply concentration centers on Saudi Arabia, UAE, and domestic Sitra industrial zone production for water-based acrylic binders. Raw material dependencies rest on titanium dioxide pigment, aliphatic isocyanates, and epoxy resin precursors. Single-source vulnerability characterizes high-performance curing agent supply. Distribution runs through consolidated hubs near Sitra enabling next-day delivery to Northern Governorate megaprojects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bahrain's Ministry of Works mandate for environmental product declarations on public tenders constitutes a regulatory inflection accelerating portfolio certification investments and restructuring competitive access.
For Market Incumbents: Build regulatory compliance moats through GSO-certified water-based portfolio expansion and captive tinting infrastructure in Sitra proximity. Backward integration into acrylic resin production reduces import dependency exposure. Certification investment ahead of Bahrain Green Building Council rating tool revisions secures preferred supplier status on government-funded developments. For New Entrants and Emerging Players: Establish a beachhead in Southern Governorate residential construction through spectrophotometer-linked custom tinting services for mid-tier contractors. Underserved decorative demand in Riffa and Isa Town offers penetrable volume expansion. Direct-contractor supply platforms bypass legacy distributor intermediation, compressing specification-to-delivery cycles against established players. For Investors and Strategic Acquirers: Bahrain Green Building Council amendments to rating tools reshape the acquisition landscape toward certified domestic producers with EPD documentation capabilities. Long-term viability centers on water-based formulation expertise and port-proximate protective coatings positioning. Acquisition target archetype: localized formulators with rapid custom turnaround and Ministry of Works pre-qualification. The signal to watch is GSO conformity assessment cycle compression for new product launches.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Portfolio Certification | GSO VOC compliance unlocks preferential access to Ministry of Works tenders. |
| Spectrophotometer-Linked Tinting Investment | Digital color matching compresses delivery cycles for Manama contractors. |
| Backward Integration into Acrylic Resins | Captive binder production reduces Saudi import dependency and margin volatility. |
| Southern Governorate Distribution Expansion | Localized Riffa and Isa Town presence captures underserved residential volume. |
| Environmental Product Declaration Pre-Positioning | EPD documentation ahead of Bahrain Green Building Council mandates secures competitive positioning. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, Ministry of Works tender documentation, and Gulf Standardization Organization regulatory filings. Primary interviews engaged plant managers at Sitra industrial zone facilities, procurement leads at Northern Governorate infrastructure developers, distribution channel partners serving Manama residential contractors, and technical R&D directors overseeing water-based formulation transitions. Bottom-up volume estimates from end-use consumption patterns triangulate against top-down production capacity assessments across the analysis window.
Forecast inputs include construction permit flows from the Ministry of Works, port infrastructure investment pipelines at Khalifa Bin Salman Port, and automotive assembly plant capacity plans in the Sitra corridor. Segmentation dimensions span formulation chemistry, application equipment intensity, and end-use specification grade. CAGRs derive from regression analysis against historical consumption patterns and projected infrastructure spend trajectories. Industry-specific inputs incorporate GSO regulatory amendment timelines and Bahrain Green Building Council rating tool revision schedules.
Sensitivities concentrate around titanium dioxide price volatility, cross-border logistics friction with Saudi chemical hubs, and certification timeline compression for new water-based launches. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Epoxy Paint Thinner Market
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
Middle East and Africa Paints and Coatings Market
Paints & Coatings
Automotive OEM Coatings Market
Paints & Coatings
Global Anti-Formaldehyde Paint Market
Paints & Coatings
South America Paints and Coatings Additives Market
Paints & Coatings
Europe Automotive Paints and Coatings Market
Paints & Coatings
Europe Architectural Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
Global Decorative Paints and Coatings Market
Paints & Coatings
Cellulose Paints Market
Paints & Coatings
Alkyd Coatings Market
Paints & Coatings
Acrylic Paints Market
Paints & Coatings
Floor Paints Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
Polyolefin Resin Paints Market