
 Magnetic Material Magnetization and Testing Equipment Market | 2026-2036
Magnetic Material Magnetization and Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Material Magnetization and Testing Equipment Market Insights
REACH compliance is decoupling European equipment procurement from legacy magnetizer architectures that rely on restricted coating chemistries. Bruker leverages its cryogen-free superconducting magnet platform to sustain leadership in high-field material characterization. Magnetic Analysis Corporation anchors North American aftermarket service through dense calibration center placement near automotive stamping clusters.
Magnetic material magnetization and testing equipment encompasses systems that apply controlled magnetic fields to align ferromagnetic domains and quantify hysteresis loops, coercivity, and remanence with resolutions reaching microtesla sensitivity; these instruments serve quality assurance and R&D functions across permanent magnet supply chains. Hysteresisgraph instruments dominate capital allocation due to their indispensability in neodymium-iron-boron grade verification, while SQUID magnetometer technology captures the fastest expansion as quantum sensing applications migrate from academic laboratories to commercial thin-film foundries. Nondestructive testing applications concentrate margin pools through recurring consumable and certification service attachments.
FDA device-quality regulations in the United States and CE marking requirements under the EU Machinery Directive shape product safety validation protocols for electromagnetic testing platforms deployed in medical and industrial environments. China's GB standards for rare earth processing equipment and Japan's JIS magnetization procedure specifications further fragment compliance burdens for multinational suppliers. Stakeholders must monitor how carbon-border adjustment mechanisms reshape magnet sourcing economics and whether domestic content thresholds in clean-energy procurement rules redirect equipment demand toward regional manufacturing bases.
Market Dynamics
Electric vehicle motor manufacturers are scaling precision magnetization systems to meet torque-density targets, while the EU's F-Gas Regulation pressures suppliers to eliminate fluorinated coolant use in cryogenic testing platforms.
Growth Catalysts
- Neodymium-iron-boron grade verification:Permanent magnet supply chains require hysteresisgraph instruments for quality assurance, pulling capital into metrology infrastructure near automotive stamping clusters.
- CE marking under EU Machinery Directive:Electromagnetic testing platforms deployed in industrial environments must validate product safety protocols, creating compliance-driven equipment refresh cycles.
- Quantum sensing migration:SQUID magnetometer technology is capturing expansion as applications migrate from academic laboratories to commercial thin-film foundries.
Market Restraints
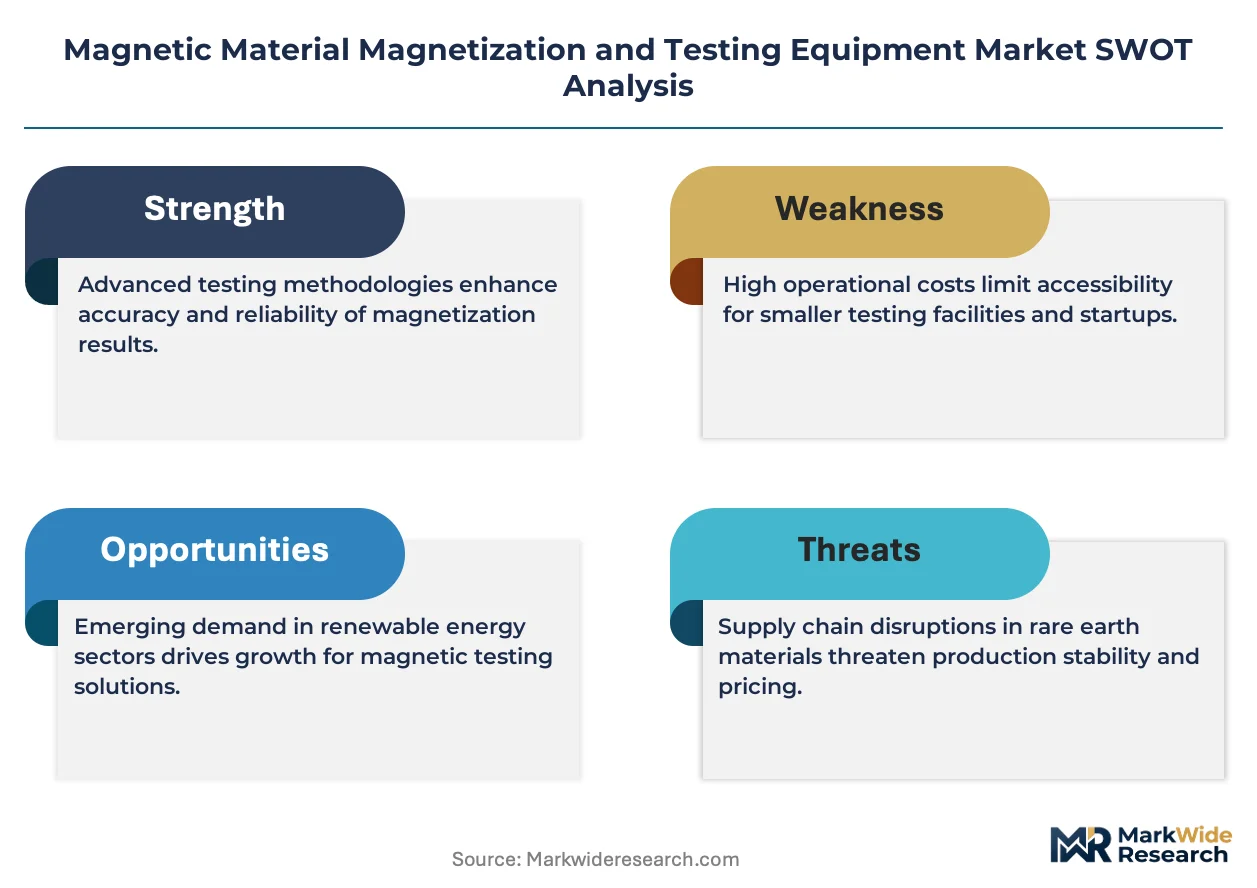
- Helium supply concentration:Cryogenic testing platforms depend on helium for superconducting magnet cooling, with sourcing concentrated in geopolitically sensitive extraction regions.
- REACH restricted coating chemistries:European equipment procurement is decoupling from legacy magnetizer architectures that rely on restricted substances, forcing premature asset retirement.
- High-field magnet capex intensity:Superconducting magnet platforms require substantial upfront investment, limiting adoption among mid-tier metrology service providers.
Strategic Opportunities
- India's PLI scheme for rare earth processing:Domestic content thresholds in clean-energy procurement rules are redirecting equipment demand toward regional manufacturing bases.
- Cryogen-free superconducting platforms:Elimination of liquid helium dependency is rewriting total cost of ownership calculations for high-field material characterization.
- Nondestructive testing service attachments:Recurring consumable and certification revenue pools concentrate margin capture through aftermarket relationships.
Industry Challenges
- SQUID magnetometer calibration expertise:Quantum sensing applications require specialized technicians capable of microtesla sensitivity verification, creating talent scarcity.
- Multi-jurisdiction compliance synchronization:China's GB standards, Japan's JIS specifications, and FDA device-quality regulations fragment validation protocols for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Material Magnetization and Testing Equipment Market |
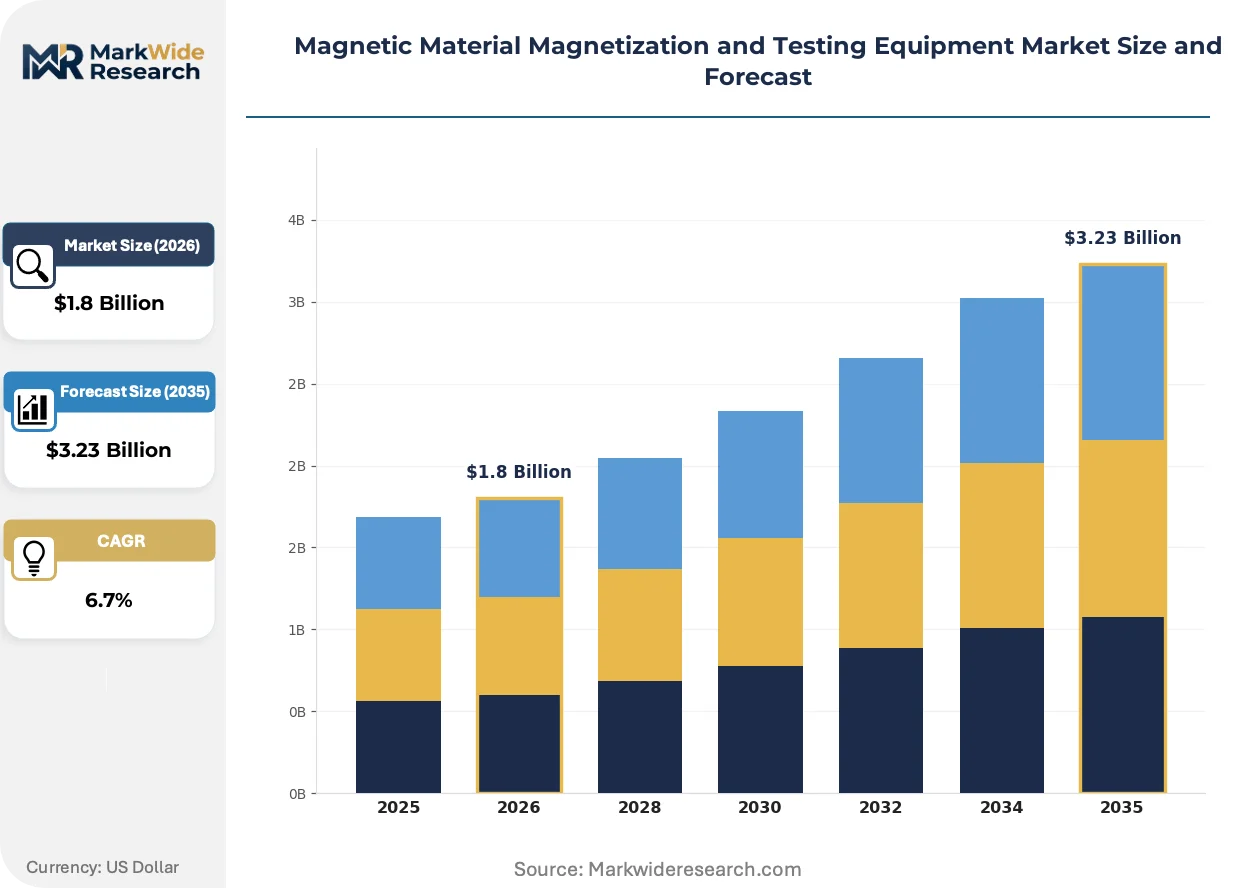
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetizers, Hysteresisgraph Instruments, Coercivity Testers, Demagnetizers, Fluxmeters Technology: Barkhausen Noise Analysis, Vibrating Sample Magnetometer, SQUID Magnetometer, Magneto-Optical Kerr Effect, Pulsed Field Method Application: Magnetic Storage Development, Nondestructive Testing, Electronic Component Inspection, Power Generation Equipment Evaluation, Material Characterization End User: Research Institutions, Manufacturing Facilities, Quality Control Laboratories, Automotive Component Producers, Aerospace Engineering Firms |
| Companies Covered | Bruker, Magnetic Shield Corporation, Magnaflux, Mistras Group, Magnetic Analysis Corporation, Karl Deutsch, Eriez Manufacturing, YXLON International, Olympus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Material Magnetization and Testing Equipment Market Trends and Innovations
Testing instrumentation is pivoting toward closed-cycle refrigeration and quantum-enhanced sensitivity as end-users demand higher throughput with reduced operational dependency on scarce cryogens.
Cryogen-free superconducting magnet technology is rewriting capital deployment patterns for high-field material characterization. Thin-film foundries are adopting these platforms at accelerated pace to eliminate helium supply vulnerability. The structural consequence is compressing maintenance intervals while expanding field accessibility for routine quality assurance.
REACH compliance is decoupling European equipment procurement from legacy magnetizer architectures. Industrial users must validate that coating chemistries meet restricted substance thresholds before deploying electromagnetic testing platforms. Neodymium-iron-boron grade verification workflows face the most acute retooling pressure as suppliers scramble to certify alternative deposition processes.
After-sales service unbundling is fragmenting traditional equipment vendor relationships. Automotive OEMs in Germany's industrial corridor now contract calibration and certification separately from hardware acquisition, favoring dense metrology service provider networks over manufacturer-direct support. This pattern concentrates margin pools with regional specialists capable of rapid turnaround on hysteresis loop validation.
Magnetic Material Magnetization and Testing Equipment Market Segmentation
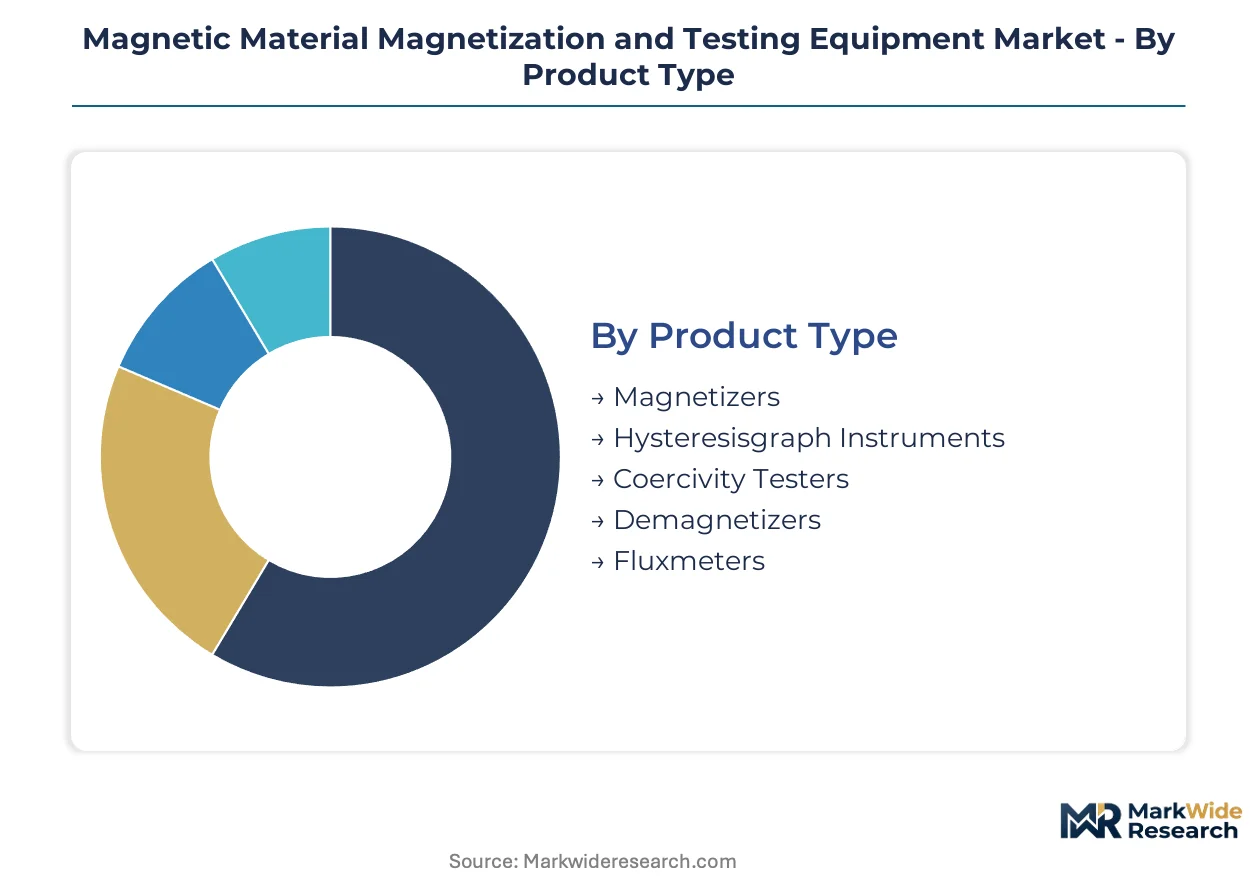
Segmentation in magnetic material testing equipment reveals how procurement priorities diverge between high-volume manufacturing quality assurance and precision R&D characterization. Equipment specifications, technology platforms, and service attachments vary sharply across end-use contexts, creating distinct margin pools and competitive dynamics.
Product Type:
Cost tier separates commodity magnetization hardware from analytical instrumentation requiring calibration infrastructure and specialized technician training.
- Hysteresisgraph Instruments:These systems quantify magnetic hysteresis loops, coercivity, and remanence with microtesla resolution for neodymium-iron-boron grade verification. Demand concentrates in Germany's industrial corridor around Stuttgart and Munich, where automotive OEMs co-locate with metrology service providers to meet torque-density targets for electric vehicle motors.
- SQUID Magnetometer:Quantum-interference devices achieve femtotesla sensitivity for thin-film magnetic characterization. Commercial thin-film foundries are adopting these platforms at accelerated pace as quantum sensing applications migrate from academic laboratories, though helium supply concentration in geopolitically sensitive regions constrains deployment scale.
- Magnetizers:Pulse and DC systems align ferromagnetic domains in production environments.
- Coercivity Testers:Dedicated instruments measure resistance to demagnetization for permanent magnet grading.
- Demagnetizers:AC and thermal systems reset magnetic domains for rework or recycling operations.
- Fluxmeters:Portable and benchtop units quantify magnetic flux density in quality control workflows.
Volume sits with hysteresisgraph instruments; growth tilts toward SQUID magnetometer platforms.
Technology:
Application maturity drives technology selection, with established methods serving high-throughput manufacturing and emerging techniques capturing R&D budgets.
- Vibrating Sample Magnetometer:Oscillating specimen systems measure magnetic moment across temperature and field ranges for routine material characterization. Manufacturing facilities in Japan deploy these platforms under JIS magnetization procedure specifications for electronic component inspection, with CE marking requirements under the EU Machinery Directive shaping validation protocols for exported equipment.
- SQUID Magnetometer:Superconducting quantum interference devices enable quantum-enhanced sensitivity for research-grade measurements. Cryogen-free superconducting magnet platforms are rewriting total cost of ownership calculations by eliminating liquid helium dependency, compressing maintenance intervals while expanding field accessibility.
- Barkhausen Noise Analysis:Nondestructive evaluation technique detects stress and microstructural defects in ferromagnetic materials.
- Magneto-Optical Kerr Effect:Surface-sensitive technique images magnetic domain structures in thin films.
- Pulsed Field Method:High-field transient measurements access extreme magnetic states inaccessible to static techniques.
Established volume belongs to vibrating sample magnetometry; steepest expansion trajectory attaches to SQUID platforms.
Application:
Customer workflow integration determines equipment specification, with inline testing demanding ruggedization and laboratory applications prioritizing sensitivity.
- Nondestructive Testing:Magnetic flux leakage and eddy current systems inspect pipelines, rails, and structural components without material destruction. Margin pools concentrate through recurring consumable and certification service attachments, with aftermarket relationships capturing value separate from hardware acquisition.
- Material Characterization:Comprehensive magnetic property measurement supports alloy development and quality certification. Research institutions in the United States validate protocols against FDA device-quality regulations when equipment serves medical imaging magnet development.
- Magnetic Storage Development:Thin-film head and media testing for hard disk and tape systems.
- Electronic Component Inspection:Verification of inductors, transformers, and sensor magnetic performance.
- Power Generation Equipment Evaluation:Testing of generator rotors, transformer cores, and grid infrastructure components.
Revenue concentration favors nondestructive testing; material characterization claims the fastest share gain.
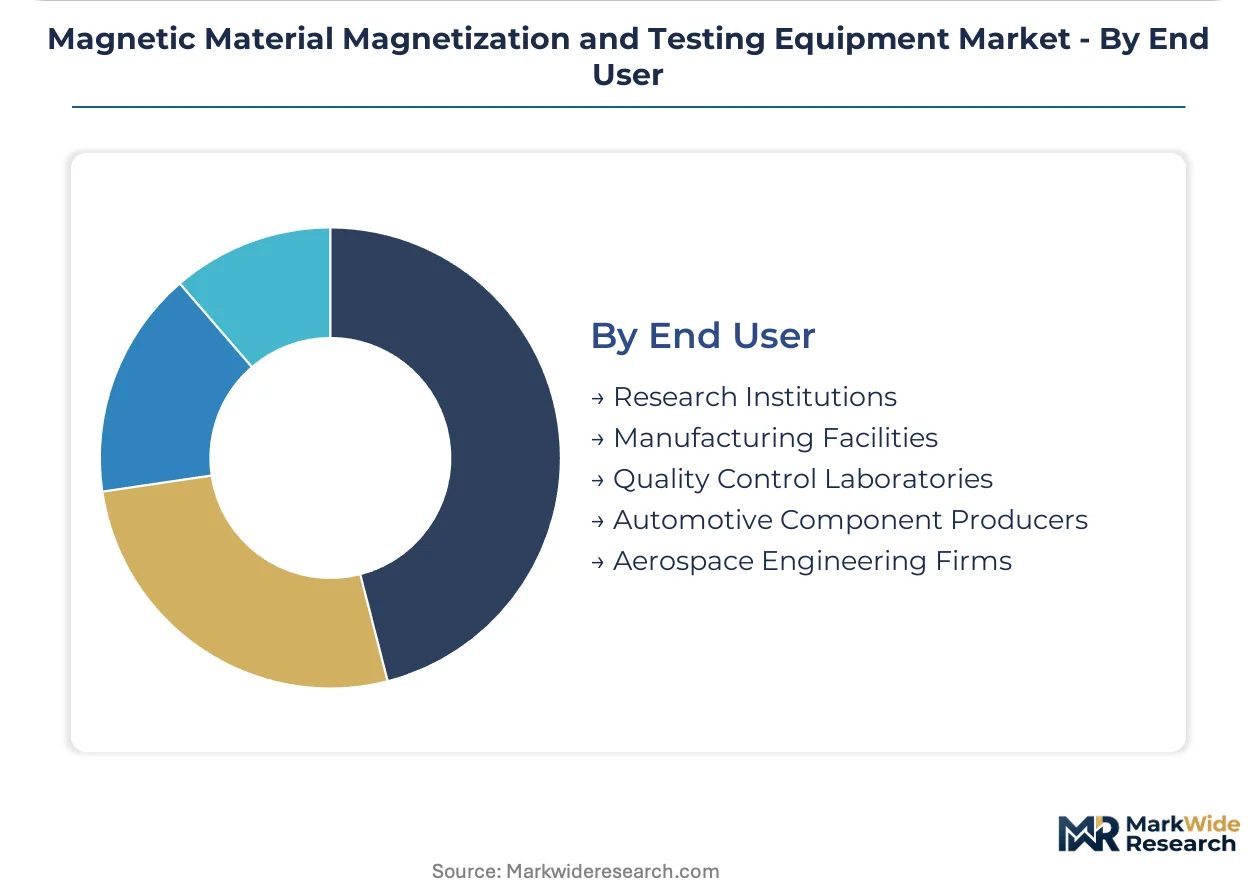
End User:
Procurement authority and technical capability separate institutional buyers with dedicated metrology staff from manufacturing operators seeking turnkey solutions.
- Automotive Component Producers:Electric vehicle motor manufacturers scale precision magnetization systems to meet torque-density targets, with dense calibration center placement near automotive stamping clusters anchoring aftermarket service relationships. India's PLI scheme for rare earth processing is redirecting equipment demand toward regional manufacturing bases as domestic content thresholds reshape procurement.
- Research Institutions:Universities and national laboratories drive adoption of frontier techniques requiring specialized expertise. SQUID magnetometer calibration capability scarcity creates talent bottlenecks, as quantum sensing applications require technicians capable of microtesla sensitivity verification.
- Manufacturing Facilities:High-volume production environments prioritize throughput and uptime.
- Quality Control Laboratories:Third-party validation services require versatile, certifiable equipment platforms.
- Aerospace Engineering Firms:Specialty applications in navigation, propulsion, and sensing systems.
Equipment volume flows to automotive component producers; research institutions command premium pricing for advanced platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's rare earth processing special economic zones concentrate magnetization equipment demand near Baotou and Ganzhou, where state-backed refineries integrate testing infrastructure with upstream extraction.
Germany
Automotive OEMs in Stuttgart and Munich co-locate with metrology service providers to meet torque-density targets for electric vehicle motors. The EU F-Gas Regulation pressures suppliers to eliminate fluorinated coolant use in cryogenic testing platforms. Baden-Württemberg's industrial corridor anchors precision magnetization system procurement.
United States
FDA device-quality regulations shape validation protocols for electromagnetic testing platforms serving medical imaging magnet development. Dense calibration center placement near automotive stamping clusters in Michigan and Ohio anchors aftermarket service relationships. The Inflation Reduction Act's domestic content thresholds redirect equipment demand toward regional manufacturing bases.
Japan
METI's JIS magnetization procedure specifications govern electronic component inspection workflows. Manufacturing facilities deploy vibrating sample magnetometer platforms under standardized protocols for quality assurance. The Kansai region around Osaka concentrates thin-film foundry adoption of quantum sensing equipment.
India
The PLI scheme for rare earth processing redirects equipment demand toward regional manufacturing bases as domestic content thresholds reshape procurement. Automotive component producers in Tamil Nadu and Maharashtra scale precision magnetization systems. BIS standards compliance creates validation protocol fragmentation for multinational suppliers.
Magnetic Material Magnetization and Testing Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: diversified analytical instrumentation conglomerates, specialized magnetic testing pure-plays, and regional fabrication specialists serving aftermarket service networks. Competitive moves concentrate on cryogen-free technology licensing and dense calibration center placement near automotive stamping clusters.
Within the diversified instrumentation tier, Bruker occupies a position exemplifying cryogen-free superconducting magnet platform leadership. Magnetic Analysis Corporation represents the specialized pure-play archetype anchoring North American aftermarket service relationships. Among European-focused metrology providers, Karl Deutsch sits within the regional fabrication specialist category serving industrial nondestructive testing applications.
| Leading Market Players |
|---|
| Bruker |
| Magnetic Shield Corporation |
| Magnaflux |
| Mistras Group |
| Magnetic Analysis Corporation |
| Karl Deutsch |
| Eriez Manufacturing |
| YXLON International |
| Olympus |
| Others |
Pricing and Supply Chain Analysis
SQUID magnetometer calibration expertise concentrated in Germany's Baden-Württemberg region widens pricing spreads between premium certified systems and economy-grade alternatives, as labor-cost differentials compound with helium supply vulnerability to stratify procurement tiers.
Pricing Analysis
Lead-time premiums for cryogen-free superconducting magnet platforms command substantial markups over spot-inventory legacy systems still dependent on liquid helium cooling. Three-tier pricing structure across premium, standard, and economy levels separates Bruker's cryogen-free platforms from mid-tier vibrating sample magnetometers and commodity pulse magnetizers. Cost compression in economy-grade hysteresisgraph instruments intensifies because Chinese manufacturers are scaling domestic production under GB standards compliance. Automotive OEMs in Stuttgart exhibit least price sensitivity due to torque-density certification requirements, while Indian rare earth processors under PLI scheme constraints face acute budget pressure.
Supply Chain Analysis
Single-source vulnerability sits with helium extraction concentrated in geopolitically sensitive regions including Qatar, Russia, and the United States. Superconducting wire manufacturing draws from Japan, China, and Germany, while precision sensor fabrication rests on South Korean and Taiwanese semiconductor foundries. Tariff exposure on rare earth magnet feedstocks from China threatens margin stability for European equipment assemblers. Distribution runs through authorized metrology service provider networks rather than direct manufacturer channels, concentrating aftermarket value capture with regional calibration specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from REACH compliance costs is forcing weaker players without cryogen-free platforms to exit or seek acquisition, compressing the vendor base toward diversified instrumentation conglomerates and specialized pure-plays with certified alternative chemistries.
For Market Incumbents: To counter helium supply concentration eroding customer confidence in legacy platforms, Bruker and Magnetic Analysis Corporation should accelerate cryogen-free technology licensing to mid-tier metrology providers while anchoring aftermarket relationships through dense calibration center placement near automotive stamping clusters in Michigan and Ohio. For New Entrants and Emerging Players: Digital-channel routes through cloud-based hysteresis loop validation services offer white-space penetration into Tier 2 automotive suppliers in India and Southeast Asia. India's PLI scheme for rare earth processing represents the most penetrable geography, with remote calibration subscriptions as the go-to-market angle bypassing capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: The window for entry favors cryogen-free platform specialists with existing CE marking pathways and established automotive OEM relationships. Long-term viability hinges on decoupling from helium-dependent architectures and securing REACH-compliant coating chemistry certifications. Watch for F-Gas Regulation enforcement intensity in Germany as the inflection indicator for accelerated legacy asset retirement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogen-Free Platform Development | Eliminates helium dependency for Bruker and compresses maintenance intervals for thin-film foundries. |
| Calibration Center Network Expansion | Magnetic Analysis Corporation anchors aftermarket value capture near Michigan automotive stamping clusters. |
| REACH-Compliant Coating Certification | Validates alternative deposition processes for neodymium-iron-boron grade verification workflows under ECHA restrictions. |
| PLI Scheme Localization Partnership | Redirects equipment demand toward Tamil Nadu and Maharashtra manufacturing bases under India's domestic content thresholds. |
| Quantum Sensing Talent Acquisition | Addresses SQUID magnetometer calibration expertise scarcity constraining commercial thin-film foundry adoption. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with metrology service provider technical directors, automotive OEM magnet procurement specialists, rare earth refinery operations managers, and cryogenic equipment maintenance heads. ECHA REACH restriction updates, FDA device-quality guidance documents, and Japan METI JIS specification releases provided regulatory validation. Bottom-up equipment shipment tracking and top-down rare earth processing capacity estimates were triangulated against hysteresisgraph and SQUID magnetometer installation records.
Product type, technology platform, application workflow, and end-user procurement authority were modeled at segment level across the analysis window. CAGRs derived from weighted average of equipment replacement cycles, automotive motor production forecasts, and thin-film foundry capacity expansion timelines. Quantum sensing migration velocity and F-Gas Regulation compliance deadlines served as industry-specific demand drivers in the projection framework.
Inputs from ECHA restriction databases and automotive OEM procurement disclosures were available through the study window; gaps in thin-film foundry confidential capacity plans introduce uncertainty bands around SQUID magnetometer adoption trajectories. Forecasts reflect assumptions on helium supply stability and PLI scheme disbursement pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
Europe Ferrite Magnet Market
Magnetic Materials
North America Magnet Wire Market
Magnetic Materials
Global Bonded Magnet Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Ferromanganese Market
Magnetic Materials
Sintered Magnet Market
Magnetic Materials
Ferrofluid Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
Global Iron Powder Market
Magnetic Materials
Superconducting Magnets Market
Magnetic Materials
Magnet Market
Magnetic Materials
Magnetic Filter Market
Magnetic Materials
North America Magnet Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
Global Permanent Magnet Market