
 Magnetic Carbon Nanofoam Market | 2026-2036
Magnetic Carbon Nanofoam Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Carbon Nanofoam Market Analysis
Graphene-based aerogels is shifting toward magnetic carbon nanofoam in high-performance shielding applications as thermal stability requirements tighten. SGL Group anchors European supply through its carbon fiber precursor integration. Nanoshel specializes in nanoparticle doping protocols that differentiate its foam magnetization profiles. BASF leverages polymer chemistry expertise to control binder formulations for structural nanofoam variants.
Magnetic carbon nanofoam constitutes a three-dimensional porous carbon architecture with embedded magnetic nanoparticles, typically exhibiting surface areas exceeding 500 square meters per gram and pore diameters tunable between 2 and 50 nanometers. Manufacturers produce these structures through chemical vapor deposition or hydrothermal synthesis to achieve simultaneous electrical conductivity and magnetic permeability for electromagnetic interference mitigation. Rigid nanofoam dominates current volume in aerospace bulkhead applications where compression strength governs specification, while flexible nanofoam captures widening demand in wearable biomedical sensors requiring conformal contact with tissue surfaces. Energy storage applications in supercapacitor electrodes represent the fastest-expanding segment as electrode thickness constraints favor ultra-lightweight current collectors.
EPA guidelines on volatile organic compound emissions during carbon precursor pyrolysis shape domestic manufacturing plant siting decisions. REACH registration requirements for nanoparticle additives govern EU market access and supplier qualification timelines. ISO 10993 biocompatibility standards constrain healthcare entry for any nanofoam designated for implantable device proximity. Stakeholders must weigh regulatory compliance investment against the technical performance premium these materials command in certification-sensitive end markets.
Market Dynamics
REACH compliance timelines in Europe and electromagnetic compatibility mandates in East Asia are compressing supplier qualification windows while aerospace OEMs consolidate qualified material sources.
Growth Catalysts
- REACH registration pathways:ECHA's streamlined nanoparticle dossier processes are accelerating EU market entry for compliant foam architectures. German carbon composite clusters around Munich and Dresden absorb expanding certified supply.
- Aerospace electromagnetic shielding:FAA airworthiness directives on avionics interference are hardening specification requirements for lightweight conductive materials in bulkhead applications.
- Supercapacitor electrode demand:Energy storage OEMs specify ultra-lightweight current collectors as electrode thickness constraints tighten in next-generation cells.
Market Restraints
- Pyrolysis input cost volatility:Carbon precursor feedstock prices fluctuate with petrochemical indices, squeezing batch economics for hydrothermal synthesis routes.
- Supplier concentration risk:Qualified magnetic nanoparticle doping protocols concentrate among specialty chemical houses in Germany and Japan, creating single-source vulnerabilities.
- Biocompatibility certification friction:ISO 10993 testing timelines for implantable-proximity nanofoams extend 18-24 months, gating healthcare revenue streams.
Strategic Opportunities
- Wearable biomedical sensors:Flexible nanofoam variants for conformal tissue contact remain underpenetrated in Japanese and South Korean device markets.
- EU Green Deal material mandates:Circular economy requirements for aerospace interiors are creating specification pull for recyclable carbon architectures.
- Graphene aerogel displacement:Thermal stability failures in legacy shielding materials are forcing specification switches toward magnetic carbon nanofoam in satellite electronics.
Industry Challenges
- Cross-functional talent scarcity:Manufacturers compete for chemists with simultaneous expertise in carbon pyrolysis and magnetic nanoparticle surface functionalization.
- Dual-certification complexity:Suppliers must synchronize REACH nanoparticle registrations with FAA material qualification timelines for aerospace tier-1 contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Carbon Nanofoam Market |
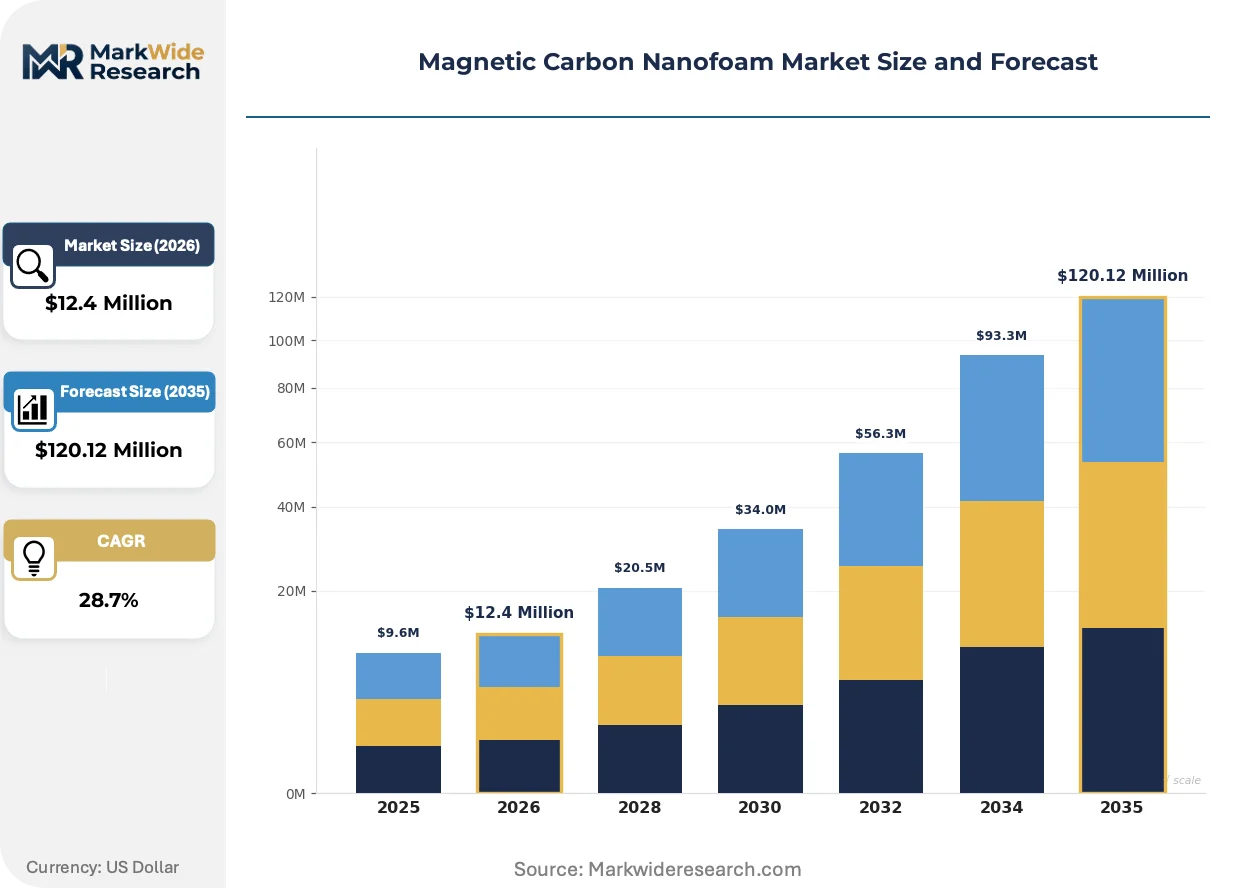
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $120.12 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Nanofoam, Rigid Nanofoam, Conductive Nanofoam, Insulative Nanofoam Application: Energy Storage, Biomedical Devices, Filtration Systems, Electromagnetic Shielding End User: Electronics, Healthcare, Aerospace, Automotive Technology: Chemical Vapor Deposition, Sol-Gel Process, Hydrothermal Synthesis, Mechanical Milling |
| Companies Covered | Zoltek Companies, Nanoshel, SGL Group, BASF, FutureCarbon GmbH, Cytec Solvay Group, Toho Tenax America, Graphenano, Hexcel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Carbon Nanofoam Market Emerging Trajectories
Specification standards are hardening across aerospace and medical verticals while synthesis methods converge toward scalable, lower-temperature routes. These pressures are reshaping R&D priorities and supplier capability investments.
Hydrothermal synthesis with in-situ magnetic nanoparticle embedding is absorbing development resources from chemical vapor deposition lines. Aerospace shielding contractors in Germany and Japan are qualifying these batches for satellite bus applications at compressed timelines. The process is absorbing market share from legacy graphene aerogel suppliers as thermal cycling requirements tighten.
REACH Annex XIV authorization requirements for cobalt-based magnetic dopants are forcing formulation pivots toward iron-nickel alternatives. ECHA's 2024 updated guidance on nanomaterial hazard classification is extending safety dossier preparation timelines. European medical device OEMs are responding by dual-qualifying US and Asia-Pacific suppliers to hedge authorization delays.
Certification-driven procurement is consolidating buyer power among tier-1 aerospace integrators with in-house electromagnetic testing labs. Smaller shielding subcontractors are losing direct material specification authority as OEMs centralize qualified supplier lists. The shift is most visible in Germany's carbon composite manufacturing corridor, where Munich-based system houses now dictate nanofoam architecture selection.
Magnetic Carbon Nanofoam Market Segmentation
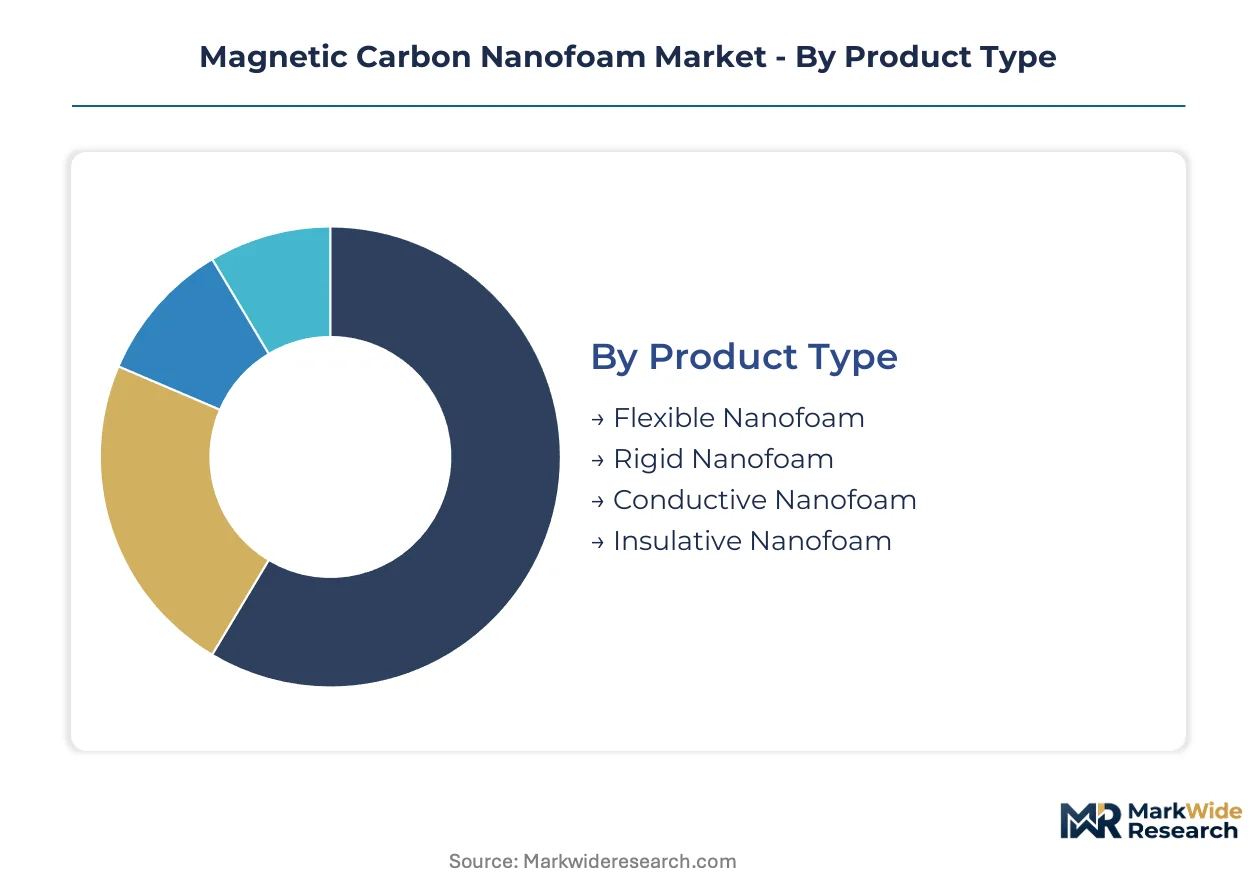
Magnetic carbon nanofoam exhibits divergent value profiles across structural variants and manufacturing routes. Specification requirements in aerospace bulkheads versus wearable biomedical sensors create distinct demand pools with incompatible performance thresholds.
Product Type:
Rigid nanofoam commands volume dominance in structural load-bearing applications, while flexible variants capture premium pricing in conformal device integration.
- Flexible Nanofoam:Compressible porous architecture with tunable pore diameters between 2 and 50 nanometers enables tissue-conformal contact. Japanese and South Korean wearable sensor manufacturers specify this variant for continuous biometric monitoring where skin adhesion governs device performance.
- Rigid Nanofoam:Three-dimensional carbon scaffold with embedded magnetic nanoparticles delivers compression strength exceeding 10 MPa for aerospace bulkhead installations. Munich-based system houses in Germany's carbon composite corridor specify rigid grades for satellite bus electromagnetic shielding where structural integrity intersects with interference mitigation.
- Conductive Nanofoam:Surface area exceeding 500 square meters per gram enables ultra-lightweight current collector applications in supercapacitor electrodes.
- Insulative Nanofoam:Reduced electrical conductivity profile targets thermal management applications where magnetic permeability must decouple from electron transport.
Today's leader: Rigid Nanofoam. Tomorrow's challenger: Flexible Nanofoam.
Application:
Energy storage electrode specifications favor ultra-lightweight architectures, while biomedical proximity triggers ISO 10993 certification bottlenecks that extend qualification timelines.
- Energy Storage:Supercapacitor OEMs specify nanofoam current collectors to resolve electrode thickness constraints in next-generation cells. The segment gains share fastest as energy density targets tighten across German and Japanese battery system integrators.
- Electromagnetic Shielding:FAA airworthiness directives on avionics interference harden specification requirements for lightweight conductive materials in aerospace bulkhead and satellite electronics applications.
- Biomedical Devices:Implantable-proximity nanofoams face 18-24 month ISO 10993 testing timelines that gate healthcare revenue streams.
- Filtration Systems:Magnetic nanoparticle embedding enables selective contaminant capture in industrial water treatment and air purification installations.
Electromagnetic Shielding anchors current procurement volume. Energy Storage climbs the fastest trajectory.
End User:
Aerospace tier-1 integrators centralize qualified supplier lists, while healthcare entry faces biocompatibility friction that compresses addressable market penetration.
- Aerospace:Tier-1 system houses with in-house electromagnetic testing labs now dictate nanofoam architecture selection, consolidating procurement authority away from smaller shielding subcontractors in Germany's manufacturing corridor.
- Healthcare:Wearable and implantable device proximity demands ISO 10993 compliance that extends supplier qualification beyond typical material certification windows.
- Electronics:Consumer and industrial device manufacturers specify nanofoam for electromagnetic compatibility in compact form factors.
- Automotive:Electric vehicle power electronics and autonomous sensor suites create emerging demand for lightweight shielding in battery enclosures and LiDAR housings.
Aerospace dominates qualified supplier relationships. Healthcare presents the steepest certification barrier.
Technology:
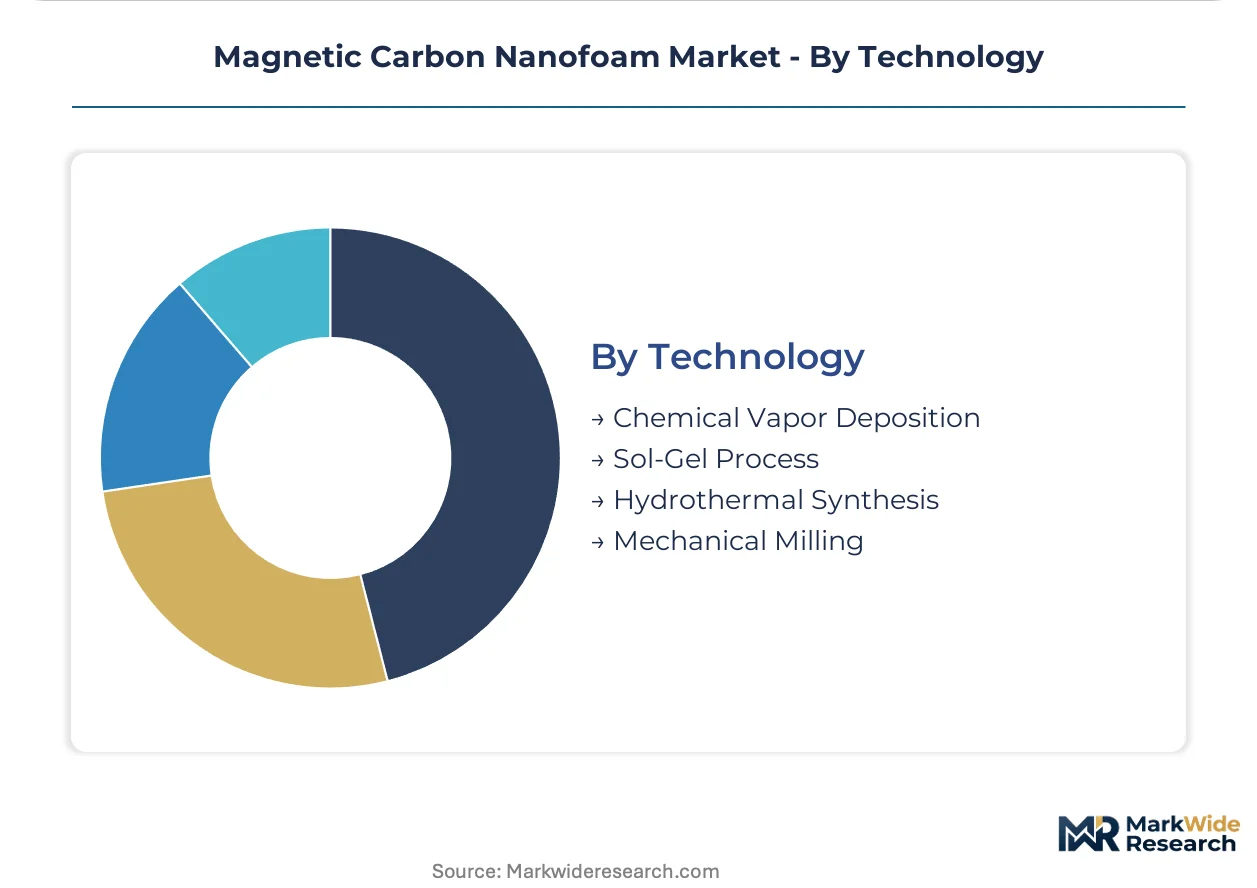
Hydrothermal synthesis with in-situ magnetic nanoparticle embedding absorbs development resources from legacy chemical vapor deposition lines as batch economics improve.
- Hydrothermal Synthesis:Lower-temperature aqueous processing enables cobalt-free iron-nickel magnetic dopant integration that satisfies REACH Annex XIV authorization constraints. German and Japanese aerospace contractors qualify these batches for satellite applications at compressed timelines.
- Chemical Vapor Deposition:High-temperature gas-phase carbon precursor decomposition delivers precise pore size control but faces volatile organic compound emission scrutiny under EPA guidelines that shape domestic manufacturing plant siting.
- Sol-Gel Process:Wet chemical route offers intermediate temperature processing with tunable magnetic nanoparticle distribution for filtration and sensing applications.
- Mechanical Milling:Solid-state processing reduces thermal exposure but introduces crystalline defect densities that compromise electrical conductivity in high-performance shielding grades.
Chemical Vapor Deposition retains specification authority. Hydrothermal Synthesis gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's carbon composite manufacturing corridor around Munich and Dresden anchors qualified supply chains for aerospace electromagnetic shielding specifications.
United States
FAA airworthiness directives on avionics interference harden demand for lightweight conductive materials in satellite electronics and commercial aviation. EPA guidelines on volatile organic compound emissions during carbon precursor pyrolysis shape domestic manufacturing plant siting decisions. Greater Boston and Pacific Northwest clusters host specialty chemical houses developing REACH-compliant iron-nickel magnetic dopant alternatives.
Germany
Munich-based system houses and Dresden-area research institutes absorb expanding certified supply for rigid nanofoam bulkhead applications. ECHA's streamlined nanoparticle dossier processes accelerate EU market entry for compliant foam architectures. Bavaria's carbon composite corridor concentrates qualified supplier relationships as tier-1 aerospace integrators centralize procurement authority.
Japan
METI-backed initiatives on next-generation energy storage drive supercapacitor electrode specifications favoring ultra-lightweight current collectors. JIS standards on electromagnetic compatibility constrain material qualification pathways for electronics OEMs. Kanto and Kansai industrial belts host magnetic nanoparticle doping specialists supplying satellite bus shielding contractors.
South Korea
MFDS biocompatibility frameworks and wearable sensor OEMs create demand for flexible nanofoam variants enabling conformal tissue contact. Domestic battery system integrators specify nanofoam current collectors as electrode thickness constraints tighten. Seoul Capital Area device manufacturers represent underpenetrated demand pools for continuous biometric monitoring applications.
China
MIIT electromagnetic compatibility mandates and dual carbon goals reshape material certification pathways for domestic aerospace and automotive electronics. GB standards on nanomaterial hazard classification extend safety dossier preparation timelines. Yangtze River Delta chemical processing hubs absorb development resources for lower-temperature hydrothermal synthesis routes.
Magnetic Carbon Nanofoam Market Vendor Landscape
Global majors compete with regional champions across qualified supplier access and certification velocity. The vendor base stratifies between carbon fiber precursor integrators, nanoparticle doping specialists, and polymer chemistry houses controlling binder formulations. Three archetypes dominate: vertically integrated material conglomerates, focused nanomaterial developers, and diversified chemical multinationals. Capacity expansion in German and Japanese manufacturing corridors and strategic partnerships bridging REACH compliance with FAA qualification timelines constitute the dominant competitive moves.
Among carbon fiber precursor specialists, Zoltek Companies and SGL Group exemplify the integrated-materials archetype with upstream control over pyrolysis feedstocks. Nanoshel occupies a position within the focused nanomaterial developer tier, representing nanoparticle doping protocol differentiation. BASF anchors the diversified chemical multinational segment, leveraging polymer chemistry expertise across structural nanofoam binder formulations. These three players collectively illustrate how competitive positioning concentrates around regulatory compliance capabilities and magnetic nanoparticle surface functionalization expertise.
| Leading Market Players |
|---|
| Zoltek Companies |
| Nanoshel |
| SGL Group |
| BASF |
| FutureCarbon GmbH |
| Cytec Solvay Group |
| Toho Tenax America |
| Graphenano |
| Hexcel Corporation |
| Others |
Supply Flow & Price Mechanics
Petrochemical index volatility for carbon precursor feedstocks cascades through hydrothermal synthesis batch economics into three-tier pricing stratification across premium certified, standard industrial, and economy prototype grades. REACH Annex XIV authorization costs for cobalt-based magnetic dopants compress margins in European supply tiers while accelerating iron-nickel formulation premiums.
Pricing Analysis
Input-cost pass-through from magnetic nanoparticle doping protocols and carbon fiber precursor pyrolysis drives contract-based long-term offtake structures with aerospace tier-1 integrators. Price differentiation centers on REACH registration tier and FAA material qualification status, with certified batches commanding substantial premiums over uncertified industrial grades. Pricing pressure stems from pyrolysis input cost volatility squeezing batch economics for mid-tier producers. Healthcare OEMs exhibit highest price sensitivity due to extended ISO 10993 testing timelines, while aerospace shielding contractors demonstrate lowest sensitivity given airworthiness directive compliance imperatives.
Supply Chain Analysis
REACH registration and FAA material qualification gating concentrates qualified supply among German carbon composite manufacturing clusters and Japanese magnetic nanoparticle doping specialists. The supply chain draws from carbon fiber precursor feedstocks, iron-nickel magnetic dopants, and specialized hydrothermal synthesis equipment. Single-source vulnerability pervades qualified magnetic nanoparticle doping protocols, with concentration among specialty chemical houses in Germany and Japan creating procurement risk. Distribution runs through direct qualified supplier relationships with tier-1 aerospace system houses, bypassing traditional chemical distribution channels for certified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory milestones into procurement consolidation, with ECHA's streamlined nanoparticle dossier processes and FAA airworthiness directives on avionics interference hardening specification requirements that reward certified supply.
For Market Incumbents: Anchor qualified supplier relationships through backward integration into magnetic nanoparticle surface functionalization capabilities, eliminating single-source dependencies that threaten tier-1 aerospace contracts. Expand hydrothermal synthesis capacity in Germany's carbon composite corridor to absorb compressed qualification timelines from satellite bus shielding contractors. Defend against graphene aerogel displacement by accelerating cobalt-free iron-nickel formulation certification ahead of REACH Annex XIV authorization deadlines.
For New Entrants and Emerging Players: Hydrothermal synthesis with in-situ magnetic nanoparticle embedding offers a technology-first wedge into flexible nanofoam variants for South Korean and Japanese wearable biomedical sensor markets, where conformal tissue contact specifications remain underpenetrated. Target Seoul Capital Area device manufacturers with ISO 10993 pre-certified flexible grades to bypass 18-24 month testing timelines that gate incumbent revenue streams. Pursue joint development agreements with battery system integrators seeking ultra-lightweight current collectors as electrode thickness constraints tighten.
For Investors and Strategic Acquirers: Asymmetric upside sits with focused nanomaterial developers possessing REACH-compliant iron-nickel doping protocols and established relationships with Munich-based aerospace system houses. Long-term viability over the projection horizon rests on regulatory compliance velocity rather than scale economics alone. Acquisition candidates should demonstrate synchronized REACH-FAA dual-certification capabilities. The signal to watch is tier-1 aerospace integrator consolidation of qualified supplier lists, which will accelerate procurement authority concentration and reward compliant mid-cap specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnetic Nanoparticle Production | Eliminates single-source vulnerability from German and Japanese specialty chemical houses. |
| REACH-FAA Dual-Certification Investment | Compresses supplier qualification windows for tier-1 aerospace electromagnetic shielding contracts. |
| Hydrothermal Synthesis Capacity Expansion | Captures share from chemical vapor deposition as batch economics improve for satellite applications. |
| Cobalt-Free Iron-Nickel Formulation Pivot | Preempts ECHA Annex XIV authorization constraints on legacy magnetic dopants. |
| Flexible Nanofoam Biocompatibility Pre-Certification | Bypasses ISO 10993 testing timelines gating healthcare revenue streams. |
Methodological Framework
Coverage spans Germany, Japan, the United States, and South Korea, with primary inputs from each market's carbon composite manufacturing clusters and regulatory authorities. The approach combines primary interviews with plant managers at hydrothermal synthesis facilities, procurement leads at aerospace tier-1 integrators, technical R&D directors at magnetic nanoparticle specialists, and regulatory affairs leads navigating ECHA dossier processes. Secondary validation draws from ECHA registration databases, FAA airworthiness directives, EPA emission guidelines, and SEC filings from carbon fiber precursor suppliers. Bottom-up volume modeling triangulates against top-down market sizing across product type, application, and technology segments.
Granularity-level modeling disaggregates the analysis window by rigid versus flexible nanofoam architectures, electromagnetic shielding versus energy storage versus biomedical device applications, and hydrothermal synthesis versus chemical vapor deposition technology routes. CAGRs derive from segment-level volume projections calibrated to aerospace OEM procurement timelines and supercapacitor electrode specification trajectories. Industry-specific forecast inputs include REACH registration pipeline data and FAA material qualification status tracking.
The model holds under stable petrochemical feedstock pricing and sustained ECHA-FAA regulatory trajectory; deviation in pyrolysis input cost volatility or nanoparticle hazard classification updates would shift volume projections. Forecasts reflect assumptions on certification velocity and tier-1 supplier consolidation patterns. A model refresh is warranted upon material change in REACH Annex XIV authorization timelines or FAA airworthiness directive scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Ferrite Magnet Market
Magnetic Materials
Superconducting Magnets Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Flux Field Directional Material Market
Magnetic Materials
North America Magnet Market
Magnetic Materials
Europe Ferrite Magnet Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
High Performance Permanent Magnet Market
Magnetic Materials
Global Permanent Magnet Market
Magnetic Materials
High Purity Carbonyl Iron Powder (CIP) Market
Magnetic Materials
Copper Magnet Wire Market
Magnetic Materials
Ferromanganese Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
Magnet Wire Market