
 Soft Ferrite Core Market | 2026-2036
Soft Ferrite Core Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Ferrite Core Market Outlook
EU RoHS and REACH compliance deadlines are shifting procurement criteria toward low-loss, high-permeability ferrite formulations across European automotive and industrial supply chains. TDK Corporation leverages integrated powder-to-core manufacturing to sustain cost leadership in MnZn grades. Ferroxcube International Holding B.V. anchors European supply through specialized power ferrite portfolios for renewable energy inverters. Hitachi Metals Ltd. competes on ultra-low core-loss materials for next-generation EV onboard chargers.
Soft ferrite cores are ceramic, iron-oxide-based magnetic materials sintered at temperatures exceeding 1,200°C to achieve controlled permeability and low coercivity for efficient electromagnetic energy conversion in alternating current circuits. MnZn ferrite dominates volume demand for power transformer and inductor applications below 2 MHz due to superior permeability and lower cost, while NiZn ferrite captures higher-frequency filter and choke segments where resistivity requirements exceed MnZn capabilities. Automotive end-use represents the fastest-expanding demand pool as electrified powertrains multiply magnetic component counts per vehicle.
Japan's METI enforces JIS standards on magnetic core efficiency that constrain import eligibility and shape domestic supplier qualification protocols. China's SAMR and MEE administer GB standards and dual carbon compliance rules that elevate energy-efficiency thresholds for ferrite materials used in industrial motor drives and grid infrastructure. The US EPA and FCC regulate electromagnetic interference limits that determine core specification minimums for telecommunications and consumer electronics equipment. Stakeholders must monitor evolving efficiency mandates across multiple jurisdictions to align R&D roadmaps with certification requirements before capacity commitments lock in.
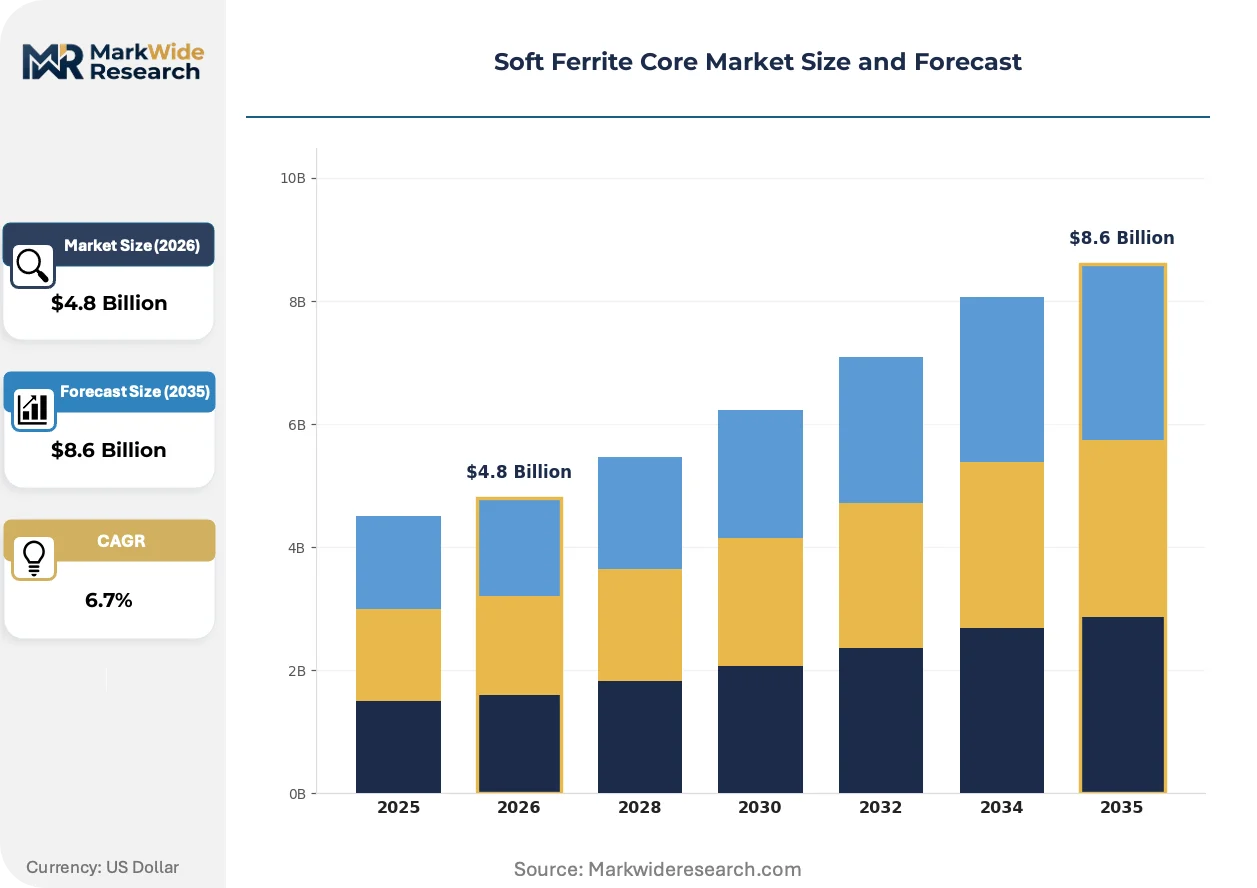
Market Dynamics
China's dual carbon mandates and GB standards on magnetic efficiency are forcing ferrite manufacturers to reformulate MnZn and NiZn compositions, compressing legacy material margins while rewarding suppliers with certified low-loss portfolios.
Growth Catalysts
- EV Powertrain Expansion:Electrified vehicle architectures multiply magnetic component counts per platform, with onboard chargers and DC-DC converters consuming high-permeability cores.
- Japan's JIS Standards:METI efficiency mandates constrain import eligibility and accelerate domestic supplier qualification for premium-grade ferrite materials.
- Renewable Energy Inverters:Solar and wind installations in East Asian manufacturing clusters drive procurement of specialized power ferrite for grid-tied conversion systems.
Market Restraints
- Raw Material Concentration:Iron oxide and rare earth precursor supply concentrates in Chinese mining and refining operations, exposing processors to input volatility.
- Technical Frequency Ceiling:MnZn ferrite permeability degrades above 2 MHz, ceding higher-frequency filter applications to NiZn alternatives with inferior cost economics.
- EU REACH Compliance Friction:RoHS substance restrictions and ECHA registration requirements extend certification timelines for European automotive supply qualification.
Strategic Opportunities
- India Industrial Motor Drives:BIS energy-efficiency labeling and CEA grid modernization programs create demand for imported ferrite cores in variable-frequency drive applications.
- WBG-Ferrite Hybrid Systems:Silicon carbide and gallium nitride power electronics convergence with optimized ferrite magnetics enables next-generation compact converter designs.
- Direct OEM Contracting:Tier-1 automotive suppliers are bypassing distributor channels to secure volume commitments with certified ferrite manufacturers.
Industry Challenges
- Sintering Process Expertise Gap:Temperature control and atmosphere management skills for 1,200°C+ ceramic firing remain scarce outside established East Asian production bases.
- Multi-Jurisdiction Certification Burden:Simultaneous compliance with JIS, GB, and IEC core-loss testing protocols strains R&D bandwidth and extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Ferrite Core Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MnZn Ferrite, NiZn Ferrite, CoFe Ferrite, Others Application: Power Transformers, Inductors, Chokes, Filters Manufacturing Stage: Raw Material Processing, Product Assembly, Testing, Packaging End User: Consumer Electronics, Automotive, Industrial Equipment, Telecommunications |
| Companies Covered | TDK Corporation, Hitachi Metals Ltd., Ferroxcube International Holding B.V., Murata Manufacturing Co., Ltd., DMEGC Magnetics Co., Ltd., Toshiba Materials Co., Ltd., VACUUMSCHMELZE GmbH & Co. KG, Acme Electronics Corporation, Taiyo Yuden Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Ferrite Core Market Strategic Shifts
Magnetic material science and power electronics architecture are converging to redefine performance benchmarks for energy conversion components across transportation and grid infrastructure.
Additive manufacturing of ferrite core geometries is overtaking conventional pressed-powder forming for prototype and low-volume production runs. EV power electronics engineering teams at European and Japanese OEMs are adopting topology-optimized core shapes within six-month design cycles. This fabrication shift is compressing time-to-market for custom inductor configurations while challenging traditional high-volume sintering economics.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant system electrification, indirectly tightening electromagnetic compatibility requirements for compressor motor drives. Industrial HVAC manufacturers must now specify ferrite cores with enhanced temperature stability to meet CE marking under revised efficiency directives. German and Italian motor drive suppliers are reformulating procurement specifications to prioritize cores validated under combined thermal and EMI stress protocols.
Consolidated supplier frameworks are displacing fragmented multi-source purchasing in automotive magnetic component procurement. Tier-1 power module manufacturers in South Korea and Japan are narrowing approved vendor lists to three certified ferrite suppliers per material grade. This concentration pattern is most pronounced in battery electric vehicle programs where traceability requirements from cell to chassis mandate single-source accountability for magnetic subsystems.
Soft Ferrite Core Market Segmentation
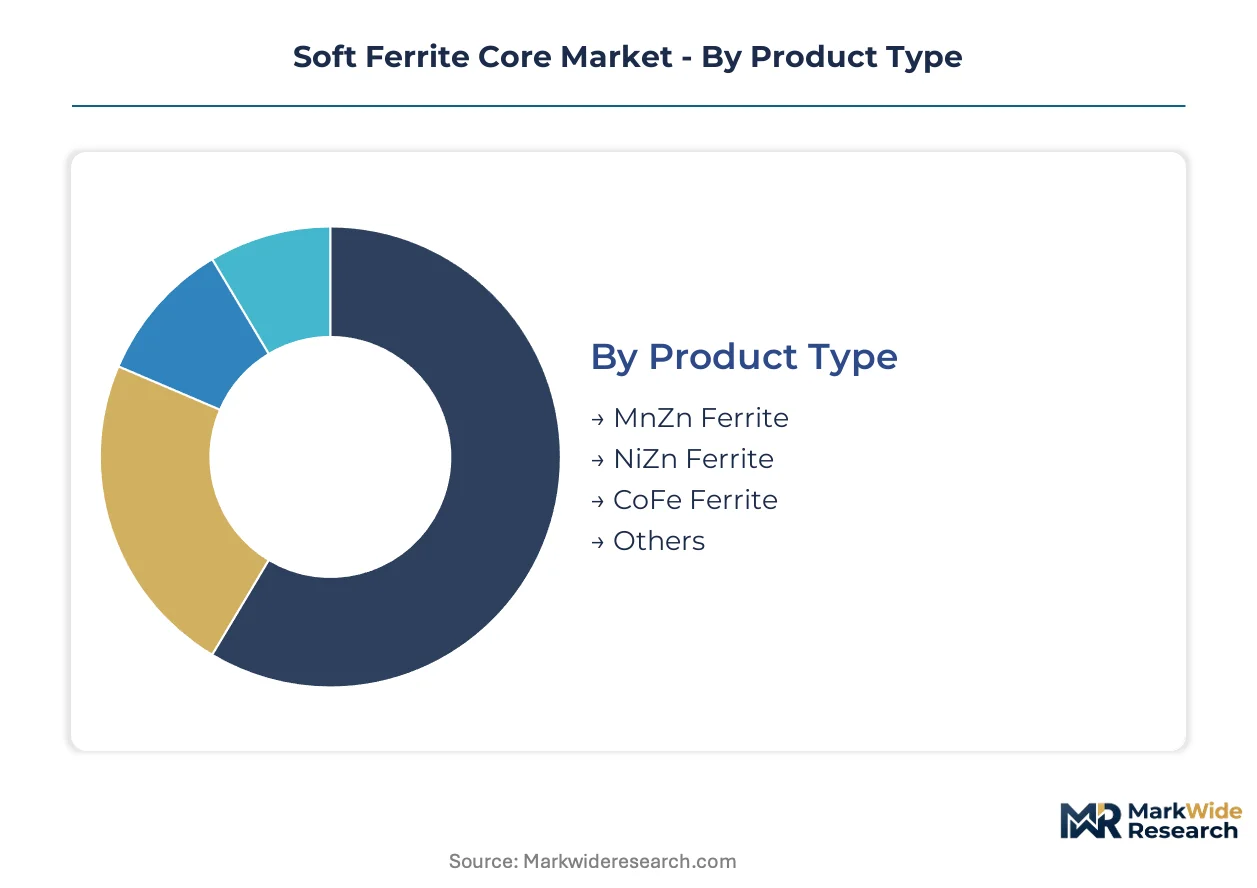
Soft ferrite core segmentation reveals distinct value capture patterns across material chemistry, integration depth, and end-use certification requirements. Procurement specifications diverge sharply between high-volume power conversion applications and precision-filtering segments where permeability tolerances command premium positioning.
Product Type:
Integration depth varies substantially across ferrite chemistries, with some grades dominating discrete component supply while others penetrate embedded module architectures.
- MnZn Ferrite:Manganese-zinc compositions deliver permeability exceeding 15,000 with core losses minimized below 2 MHz, making them indispensable for EV onboard chargers and industrial motor drives. Procurement from East Asian manufacturing clusters concentrates in high-volume power transformer applications where TDK Corporation and Ferroxcube International compete on certified low-loss portfolios under JIS and GB efficiency mandates.
- NiZn Ferrite:Nickel-zinc formulations achieve resistivity above 10^6 Ω·m, enabling stable performance in RF chokes and EMI suppression circuits where MnZn conductivity proves prohibitive. Demand from telecommunications infrastructure and 5G base station deployments in Japan and South Korea is accelerating qualification protocols for high-frequency filter applications above 2 MHz.
- CoFe Ferrite:Cobalt-ferrite variants serve specialized high-temperature sensor applications with Curie points exceeding 500°C.
- Others:Lithium and magnesium ferrite derivatives address niche microwave absorption and medical imaging coil requirements.
Volume placements concentrate in MnZn grades; the faster expansion belongs to NiZn formulations for next-generation wireless power and telecommunications filtering.
Application:
Cost tier stratification separates commodity power magnetics from precision-filtering components where specification tolerance tightens pricing bands.
- Power Transformers:Laminated core assemblies for grid-tied inverters and EV charging infrastructure require MnZn grades with temperature stability validated across -40°C to 150°C operating windows. Procurement from renewable energy developers in Germany and China is prioritizing cores certified under combined thermal cycling and IEC core-loss testing protocols.
- Inductors:Energy storage magnetics for DC-DC converters and power factor correction circuits demand gapped core geometries with controlled AL values. Automotive Tier-1 suppliers in South Korea are consolidating approved vendor lists to three certified ferrite manufacturers per material grade to satisfy traceability mandates from cell to chassis.
- Chokes:Common-mode and differential-mode suppression components for EMI compliance in industrial motor drives.
- Filters:High-frequency signal conditioning magnetics for telecommunications and RF equipment.
Margin capture is highest in inductor segments serving automotive electrification; steepest expansion trajectory is emerging in power transformers for solar and wind inverter installations.
Manufacturing Stage:
Supply concentration patterns differentiate captive raw material processing from outsourced assembly and testing operations across production networks.
- Raw Material Processing:Iron oxide precursor refining and powder synthesis operations concentrate in Chinese mining and chemical processing corridors, with SAMR-administered GB standards tightening purity specifications for battery-grade ferrite feedstocks. Hitachi Metals Ltd. maintains backward integration into powder production to secure cost leadership in ultra-low core-loss formulations.
- Product Assembly:Core winding, gapping, and coating operations distribute across Mexico, Vietnam, and Eastern European contract manufacturing zones to satisfy regional content requirements in automotive supply chains.
- Testing:Core-loss characterization and permeability validation under JIS, IEC, and customer-specific protocols.
- Packaging:Anti-corrosion and traceability labeling for semiconductor-grade cleanroom handling requirements.
Capability scarcity sits with 1,200°C+ sintering atmosphere control; assembly and testing stages face commoditization pressure from automation deployment.
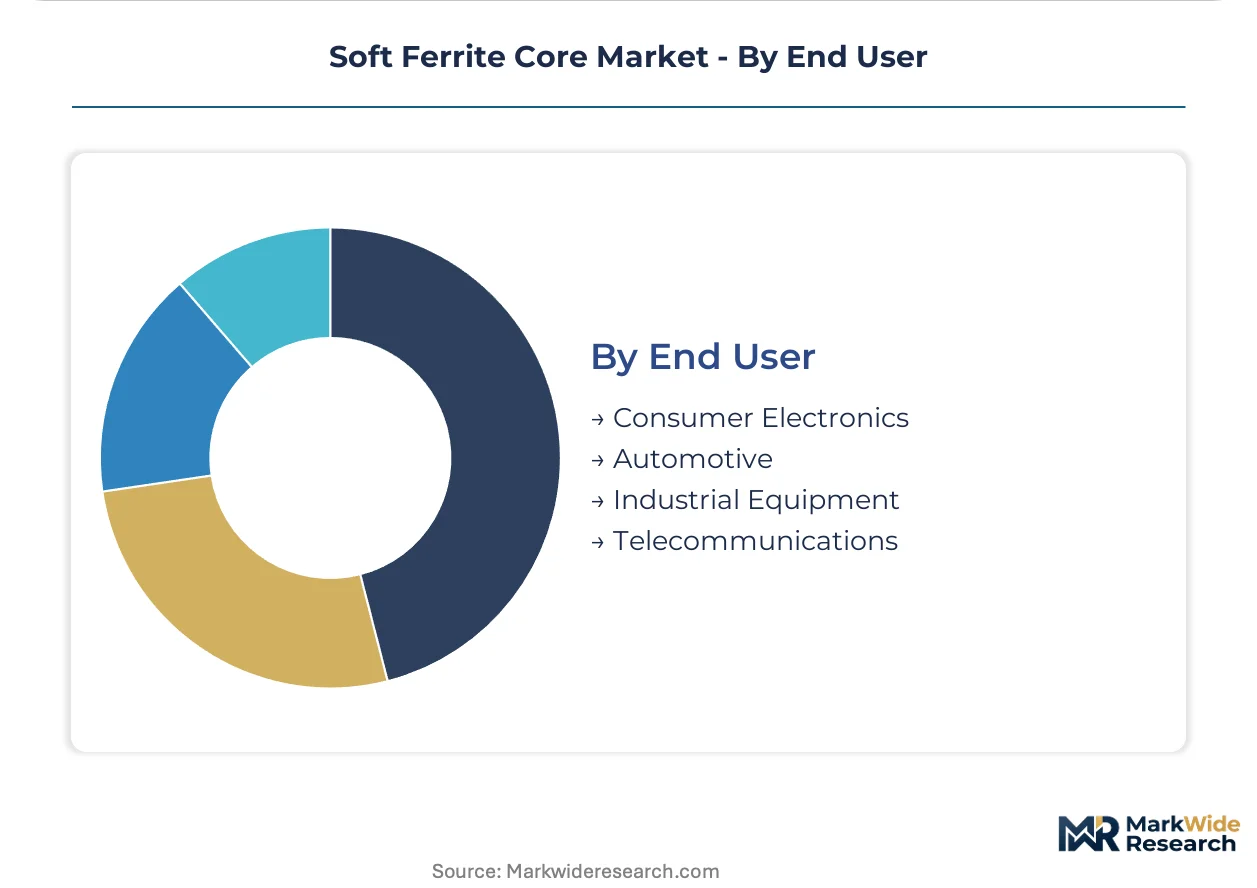
End User:
Customer type segmentation separates price-sensitive consumer electronics procurement from automotive qualification programs with multi-year validation cycles.
- Automotive:Electrified powertrain architectures multiply magnetic component counts per platform, with battery management systems and onboard chargers consuming high-permeability cores in volumes scaling with EV production ramps. European OEMs are bypassing distributor channels to secure direct volume commitments with certified ferrite manufacturers under REACH and RoHS compliance deadlines.
- Industrial Equipment:Variable-frequency drives and servo motor controllers for factory automation demand cores with enhanced temperature stability under EU F-Gas Regulation phase-down schedules accelerating refrigerant system electrification.
- Consumer Electronics:Smartphone and laptop adapter magnetics where cost minimization dominates specification trade-offs.
- Telecommunications:Base station power supplies and optical network equipment requiring EMI suppression under FCC and CE marking protocols.
Procurement volume concentrates in consumer electronics; certification premium and growth acceleration belong to automotive electrification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters dominate soft ferrite core production, while European and North American demand concentrates in automotive electrification and renewable energy conversion systems. Consumption patterns diverge sharply between high-volume consumer electronics procurement in Asia and specification-intensive automotive qualification in Germany and the United States.
China
Domestic EV powertrain manufacturers are scaling procurement of MnZn ferrite cores for onboard chargers and DC-DC converters. SAMR-administered GB standards on magnetic component efficiency are tightening material specifications and disqualifying legacy formulations. Manufacturing concentrates in the Yangtze River Delta around Shanghai and Suzhou, where powder-to-core integrated facilities serve both domestic automakers and export markets.
Japan
METI-enforced JIS standards on core-loss efficiency are constraining import eligibility and accelerating domestic supplier qualification protocols. Automotive Tier-1 suppliers in the Nagoya industrial corridor are consolidating approved vendor lists to three certified ferrite manufacturers per material grade. Tokyo-based OEM engineering teams are adopting topology-optimized core geometries within compressed six-month design cycles.
Germany
Industrial motor drive manufacturers are reformulating procurement specifications to prioritize ferrite cores validated under combined thermal and EMI stress protocols. EU F-Gas Regulation phase-down schedules are accelerating refrigerant system electrification and tightening electromagnetic compatibility requirements for compressor motor drives. Production clusters in Bavaria and Baden-Württemberg anchor European supply for renewable energy inverter applications.
United States
EPA and FCC electromagnetic interference limits are determining core specification minimums for telecommunications infrastructure and consumer electronics equipment. The Southeast manufacturing corridor spanning Tennessee and South Carolina is attracting ferrite core assembly operations to satisfy regional content requirements in automotive supply chains. Direct OEM contracting patterns are displacing fragmented multi-source purchasing among domestic power module manufacturers.
South Korea
Battery electric vehicle programs are multiplying magnetic component counts per platform, with traceability requirements from cell to chassis mandating single-source accountability. Domestic power electronics manufacturers in the Busan-Ulsan industrial zone are narrowing approved vendor lists and bypassing distributor channels to secure volume commitments. Government efficiency mandates on industrial motor drives are elevating procurement standards for variable-frequency applications.
Soft Ferrite Core Market Competitive Environment
The competitive structure tilts toward integrated powder-to-core manufacturers with certified low-loss portfolios under multiple jurisdiction standards. East Asian conglomerates with captive sintering capabilities occupy the premium tier, while European specialists anchor regional supply through application-specific formulations. Three archetypes dominate: vertically integrated chemical-to-component conglomerates, regional specialists in high-frequency formulations, and contract manufacturers serving automotive qualification programs. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for EV powertrain ramp volumes.
Among Japanese and European material science conglomerates, TDK Corporation, Hitachi Metals Ltd., and Ferroxcube International Holding B.V. exemplify the integrated manufacturing archetype. These entities occupy positions spanning powder synthesis through finished core delivery, with geographic footprints aligned to major automotive and industrial electrification clusters. Their market presence reflects the industry-wide shift toward consolidated supplier frameworks and direct OEM contracting relationships.
| Leading Market Players |
|---|
| TDK Corporation |
| Hitachi Metals Ltd. |
| Ferroxcube International Holding B.V. |
| Murata Manufacturing Co., Ltd. |
| DMEGC Magnetics Co., Ltd. |
| Toshiba Materials Co., Ltd. |
| VACUUMSCHMELZE GmbH & Co. KG |
| Acme Electronics Corporation |
| Taiyo Yuden Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Additive manufacturing adoption for topology-optimized ferrite core geometries is compressing prototype-to-production timelines while fragmenting supplier economics between high-volume sintering operations and agile low-volume fabricators. China's SAMR-administered GB standards on magnetic efficiency are simultaneously elevating certification costs for legacy MnZn formulations and rewarding certified low-loss portfolios with pricing power in automotive procurement channels.
Pricing Analysis
Margin tightening in standard-grade MnZn ferrite reflects raw material volatility in Chinese iron oxide refining corridors and procurement consolidation by East Asian automotive Tier-1 suppliers. Contract-based long-term offtake agreements dominate volume placements, with price differentiation anchored in JIS/GB certification tier and volume scale. Cost-down pressure on uncertified legacy formulations accelerates as European OEMs bypass distributor channels for direct manufacturer contracting. Consumer electronics adapters remain most price-sensitive; automotive electrification programs tolerate premium positioning for traceability-validated cores.
Supply Chain Analysis
Automotive qualification gating through JIS, GB, and REACH protocols is concentrating approved vendor lists to three certified suppliers per material grade across South Korean and Japanese power module manufacturers. Sintering capacity concentrates in China, Japan, and South Korea, with iron oxide precursor, rare earth dopants, and ceramic binders feeding from Chinese mining and chemical processing corridors. Single-source vulnerability persists in 1,200°C+ atmosphere-controlled firing expertise outside established East Asian production bases. Distribution runs through direct OEM contracting channels displacing fragmented multi-source purchasing in battery electric vehicle programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soft ferrite core market is consolidating around integrated powder-to-core manufacturers with multi-jurisdiction certification portfolios, with China's dual carbon mandates and automotive traceability requirements forcing sub-scale compounders toward exit or acquisition.
For Market Incumbents: Acquire captive sintering atmosphere control expertise to defend against substitute magnetics from silicon carbide and gallium nitride hybrid systems. Expand capacity in Yangtze River Delta clusters to satisfy SAMR-administered GB efficiency thresholds while consolidating three-supplier shortlists with European automotive OEMs facing REACH compliance deadlines. Certification investment in combined thermal and EMI stress protocols represents the critical defensive lever against emerging additive manufacturing challengers. For New Entrants and Emerging Players: Tier-2 automotive suppliers in India's industrial motor drive sector present the most penetrable white-space target, with BIS energy-efficiency labeling and CEA grid modernization programs creating import demand for certified ferrite cores. Topology-optimized core geometries for EV onboard charger applications offer a second entry vector, with European OEM engineering teams adopting compressed six-month design cycles that favor agile prototype fabricators. A go-to-market angle through direct technical collaboration with power electronics engineering teams bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by East Asian material science conglomerates seeking JIS-certified low-loss portfolios. Long-term viability across a 5-10 year window hinges on backward integration into powder synthesis and qualification under tightening dual carbon efficiency mandates. Acquisition target archetypes include regional specialists in NiZn high-frequency formulations and contract manufacturers with automotive traceability infrastructure. The signal to watch is narrowing approved vendor lists in South Korean battery electric vehicle programs, which indicates consolidation inflection when three-supplier concentration drops to two-supplier dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Synthesis | Hitachi Metals Ltd. secures cost leadership in ultra-low core-loss MnZn formulations through captive iron oxide refining. |
| Multi-Jurisdiction Certification Investment | TDK Corporation sustains automotive qualification under simultaneous JIS, GB, and IEC core-loss testing protocols. |
| Direct OEM Contracting Relationships | Ferroxcube International bypasses distributor channels to secure volume commitments with European renewable energy inverter developers. |
| Additive Manufacturing Capability Buildout | Topology-optimized core geometries compress EV power electronics design cycles from 18 months to six months. |
| Regional Assembly Footprint Expansion | Mexico and Vietnam contract manufacturing zones satisfy automotive regional content requirements for North American and European supply chains. |
Study Parameters
Independent corroboration across ferrite manufacturer technical directors, automotive Tier-1 procurement leads, and power electronics engineering teams underwrites the qualitative findings in this study. Primary interviews with plant managers at East Asian sintering facilities, downstream OEM magnetics buyers, and distribution channel partners were validated against secondary sources including SAMR GB standard filings, METI JIS efficiency mandates, SEC 10-K disclosures from listed material science conglomerates, and customs trade data on iron oxide precursor flows. Bottom-up volume modeling and top-down value triangulation were applied across the analysis window.
Comparable-period anchoring to historical EV powertrain penetration rates and renewable energy installation trajectories structured the projection horizon. Segmentation dimensions modeled include material chemistry (MnZn, NiZn, CoFe), integration depth (discrete component versus embedded module), manufacturing stage (raw material processing through assembly), and end-use certification tier (automotive traceability versus consumer electronics cost minimization). CAGRs were derived from slope-consistent growth rate analysis calibrated to magnetic component counts per electrified vehicle platform and solar inverter deployment schedules.
Caveats apply where raw material volatility in Chinese iron oxide refining or accelerated silicon carbide power electronics substitution could materially shift the outlook. Forecasts reflect assumptions on JIS/GB efficiency mandate enforcement timelines and automotive OEM consolidation of approved vendor lists. A model refresh is warranted upon material change in dual carbon compliance thresholds or EV platform standardization decisions affecting magnetic component specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Sintered Magnet Market
Magnetic Materials
Global Permanent Magnet Market
Magnetic Materials
Global Soft Magnetic Alloys Market
Magnetic Materials
North America Magnet Market
Magnetic Materials
Carbonyl Iron Powder Market
Magnetic Materials
North America Magnet Wire Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Neodymium [Nd-Fe-B] Magnet Market
Magnetic Materials
North America Samarium Cobalt Magnets Market
Magnetic Materials
Rare Earth Magnet Market
Magnetic Materials
Global Bonded Magnet Market
Magnetic Materials
Global Iron Powder Market
Magnetic Materials
Magnet Wire Market
Magnetic Materials
Magnetorheological Fluid Market
Magnetic Materials
Global Non-Oriented Electrical Steel Market
Magnetic Materials
Magnet Market