
 IVF Time-Lapse Imaging Devices Market | 2026-2036
IVF Time-Lapse Imaging Devices Market Size, Share, and Industry Trends Forecast 2026-2036
IVF Time-Lapse Imaging Devices Market Intelligence
Continuous morphokinetic analysis is rewriting how embryologists assess developmental competence without removing embryos from controlled incubation. Vitrolife Sweden AB leverages its integrated incubator-imager systems to dominate European supply chains for high-throughput fertility centers. Esco Medical Technologies anchors its position across Asia-Pacific through localized manufacturing and regional service infrastructure. Genea Biomedx differentiates by specializing in proprietary algorithm-driven embryo ranking tools that clinics adopt for standardized decision protocols.
IVF time-lapse imaging devices comprise incubator-integrated camera systems, standalone imaging platforms, and computational software that capture sequential embryo photographs at fixed intervals to document cleavage patterns, blastulation dynamics, and morphokinetic parameters without environmental disruption. These systems operate at 37°C, 5-6% CO₂, and low oxygen tension to maintain viability while generating quantitative developmental timelines for implantation prediction. Embryo monitors occupy the largest revenue pool due to replacement cycles in mature fertility markets, while software solutions represent the fastest-expanding margin segment as clinics seek cloud-enabled remote embryology review. Deployment through hybrid systems is gaining traction among mid-sized clinics balancing data sovereignty requirements with telemedicine access for distributed specialist networks.
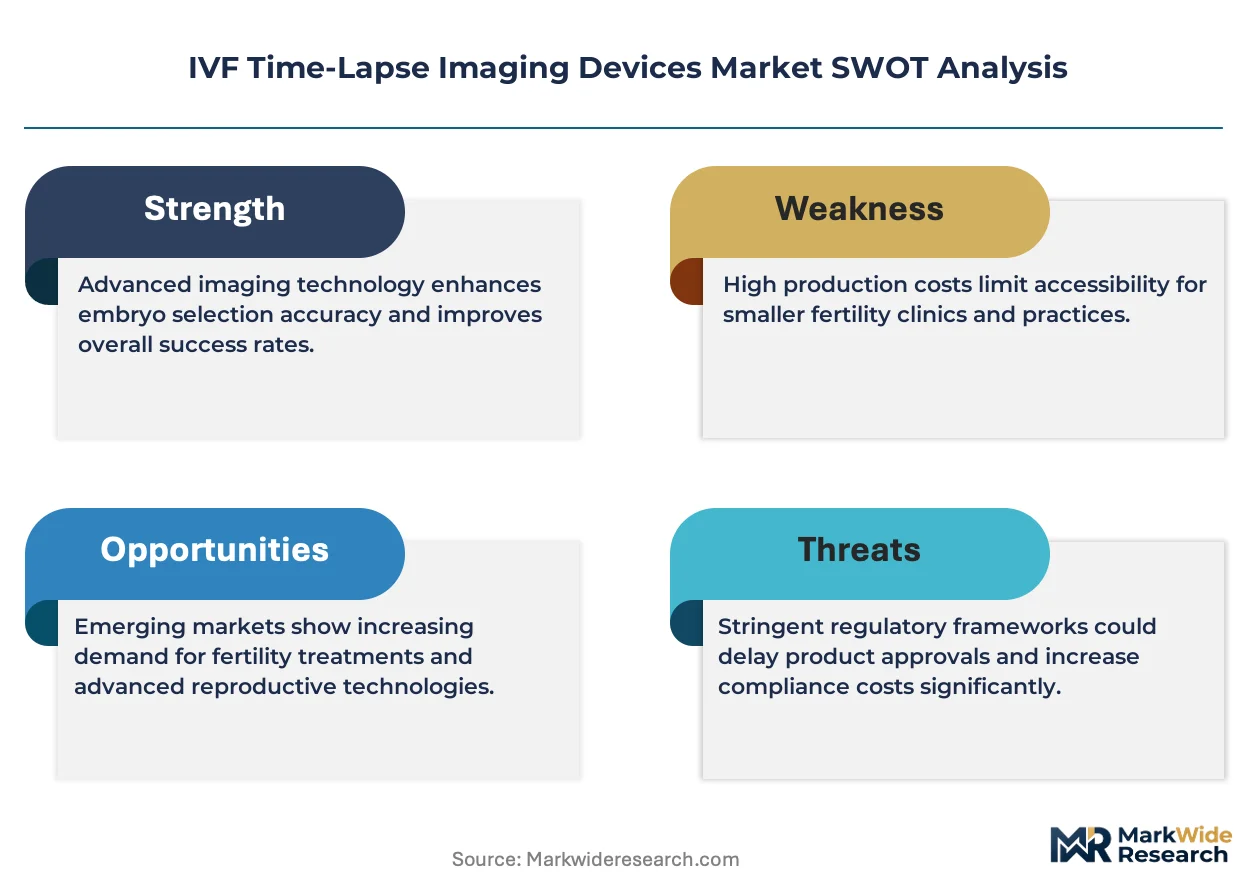
The FDA regulates these devices as Class II medical devices requiring 510(k) premarket notification for imaging components used in embryo culture. The EU MDR and ISO 13485 quality management standards shape conformity pathways, with notified bodies scrutinizing software validation for algorithm-assisted embryo classification. Japan's PMDA imposes additional clinical evidence requirements on time-lapse systems marketed with predictive outcome claims. Stakeholders must monitor how divergent software validation standards across FDA, EMA, and PMDA jurisdictions fragment product registration strategies and delay unified platform launches.
Market Dynamics
Algorithmic embryo scoring is compressing clinical decision cycles and forcing hardware manufacturers to deepen software competencies or surrender margin to specialized analytics vendors.
Growth Catalysts
- EU MDR software validation requirements:The EU Medical Device Regulation mandates rigorous algorithmic transparency for embryo classification tools, accelerating replacement of legacy imaging platforms with compliant integrated systems across German fertility networks.
- Time-lapse incubation protocols:Japanese and Australian clinics are standardizing uninterrupted morphokinetic monitoring to reduce manual embryo handling and improve implantation prediction accuracy.
- Cloud-enabled remote embryology:Distributed specialist networks in Nordic countries are adopting hybrid deployment models that balance data sovereignty with telemedicine access for rural patient populations.
Market Restraints
- Capital intensity of incubator-integrated systems:Mid-sized fertility clinics face compressed ROI timelines when upgrading from standalone microscopes to full environmental control platforms with embedded imaging.
- Supply concentration in optical sensor components:German and Japanese precision optics suppliers dominate high-resolution camera modules, creating vulnerability for device assemblers without captive component sourcing.
- Clinical validation timelines:Japan's PMDA requires prospective outcome data for predictive claims, extending registration cycles by 18-24 months versus imaging-only approvals.
Strategic Opportunities
- Underpenetrated Southeast Asian markets:Thailand and Singapore fertility hubs are expanding capacity without legacy equipment bases, enabling direct adoption of integrated time-lapse systems versus staged upgrades.
- AI-assisted embryo ranking standardization:Algorithm-driven morphokinetic scoring is displacing subjective grading in multi-site fertility networks seeking protocol consistency across embryologist teams.
- Subscription software monetization:Cloud-based remote review platforms enable recurring revenue streams from clinics that defer capital expenditure on full hardware replacement.
Industry Challenges
- Embryologist workflow retraining:Transition from static morphology assessment to continuous time-lapse interpretation requires substantial upskilling of laboratory personnel, slowing technology absorption in established clinics.
- Interoperability with legacy laboratory information systems:Proprietary data formats from dominant incubator-imager platforms create integration friction for clinics seeking unified electronic health record connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IVF Time-Lapse Imaging Devices Market |
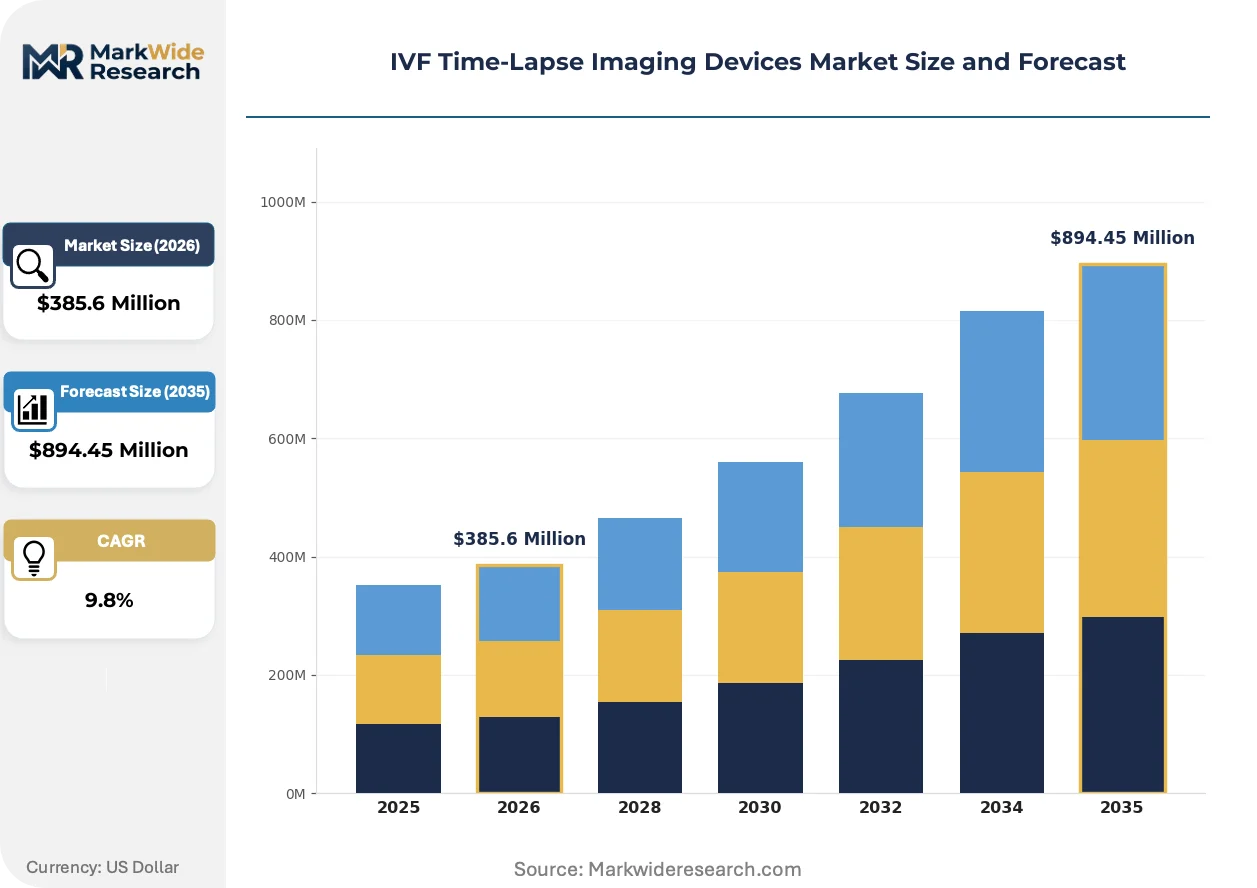
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $894.45 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embryo Monitors, Imaging Systems, Software Solutions, Accessories Technology: Digital Imaging, Light Microscopy, Thermal Imaging, Image Analysis End User: Fertility Clinics, Research Laboratories, Hospitals, Academic Institutions Deployment: Cloud-Based, On-Premise, Hybrid Systems, Mobile Solutions |
| Companies Covered | Vitrolife Sweden AB, Esco Medical Technologies, Genea Biomedx, ASTEC CO., LTD., CooperSurgical Inc., Weigao Group, Hua Yue Enterprise Holdings, Wuhan Huchuang Union Technology, Esco Lifesciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IVF Time-Lapse Imaging Devices Market Strategic Shifts & Innovations
Deep learning architectures trained on developmental timelines are displacing rule-based morphokinetic parameters as the primary basis for embryo selection, compressing the competitive window for hardware-centric vendors.
Multi-spectral imaging modules that capture both visible-light morphology and metabolic indicators through autofluorescence detection are hybridizing conventional time-lapse platforms with non-invasive viability assessment. High-throughput fertility centers in Germany and the Netherlands are piloting these configurations to reduce transfer of non-viable embryos. The structural consequence is a narrowing distinction between imaging hardware and metabolic analysis equipment, forcing vendors to acquire or partner for spectroscopic capabilities.
EU MDR's expanded software classification scope is redefining conformity pathways for algorithm-assisted embryo ranking tools, with notified bodies now requiring clinical performance studies for predictive modules previously cleared as decision-support. Manufacturers serving European fertility networks are restructuring quality management systems to ISO 13485:2016 standards for software lifecycle processes. The segment most affected is cloud-based analytics platforms, where remote algorithm updates trigger re-certification obligations not applicable to static embedded software.
Consolidated procurement by multi-clinic fertility networks is displacing individual site purchasing authority, with centralized technology committees standardizing across regional footprints. Equipment vendors are responding with enterprise pricing frameworks and dedicated account structures for network-level negotiations. This pattern is most visible in Australia, where specialized fertility groups have absorbed independent clinics and now control majority national capacity.
IVF Time-Lapse Imaging Devices Market Segmentation
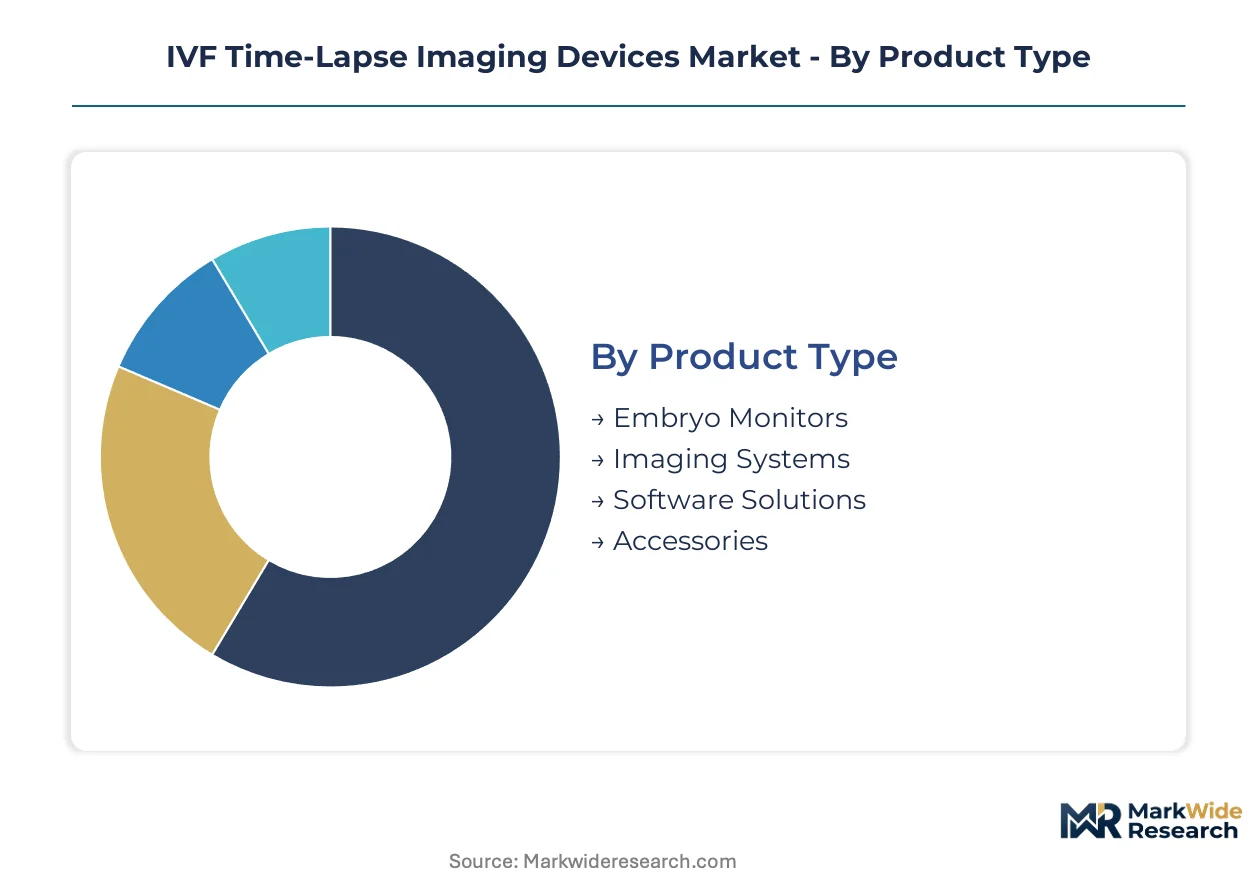
IVF time-lapse imaging devices fragment across hardware maturity, software sophistication, and clinical workflow integration. Each segment tier carries distinct procurement cycles, regulatory pathways, and margin structures that shape vendor strategy and clinic adoption timelines.
Product Type:
Mature hardware platforms dominate installed bases while emerging software layers capture expanding margin pools.
- Embryo Monitors:These incubator-integrated camera systems maintain 37°C, 5-6% CO₂, and low oxygen tension while capturing sequential embryo photographs at fixed intervals. Replacement cycles in German and Japanese fertility networks drive sustained demand as clinics upgrade legacy platforms to meet EU MDR software validation requirements.
- Software Solutions:Cloud-enabled algorithmic embryo ranking tools enable remote morphokinetic review and standardized decision protocols across distributed specialist networks. Nordic fertility groups adopt these fastest to balance data sovereignty with telemedicine access for rural patient populations.
- Imaging Systems:Standalone imaging platforms without full environmental control serve mid-sized clinics deferring capital expenditure on integrated incubator replacements.
- Accessories:Optical sensor modules, calibration tools, and consumable components support system maintenance and performance validation.
Embryo monitors handle the majority of throughput; software solutions are expanding most quickly on share.
Technology:
Cost tiers separate established optical methods from emerging computational and multi-spectral approaches.
- Digital Imaging:High-resolution CMOS and CCD sensor arrays form the backbone of modern time-lapse systems, enabling continuous image capture without mechanical shutter wear. German precision optics suppliers dominate sensor sourcing, creating supply concentration for device assemblers.
- Image Analysis:Deep learning architectures trained on developmental timelines displace rule-based morphokinetic parameters for embryo selection, compressing competitive windows for hardware-centric vendors.
- Light Microscopy:Conventional brightfield and phase-contrast methods persist in budget-conscious installations and research settings.
- Thermal Imaging:Infrared metabolic assessment remains experimental, with Dutch and German centers piloting hybrid configurations combining thermal data with morphokinetic timelines.
Digital imaging anchors current procurement budgets; image analysis is climbing the fastest on investment priority.
End User:
Customer type determines purchasing authority, with consolidated networks displacing individual site decision-making.
- Fertility Clinics:Specialized reproductive medicine centers generate primary demand, with Australian and Japanese clinic networks standardizing uninterrupted morphokinetic monitoring to reduce manual embryo handling. Consolidated procurement by multi-clinic groups now controls majority national capacity in several markets.
- Research Laboratories:Academic and commercial R&D facilities drive adoption of experimental multi-spectral and thermal imaging modules for non-invasive viability assessment protocol development.
- Hospitals:General hospital-based fertility services prioritize interoperable systems with existing electronic health record infrastructure.
- Academic Institutions:Training centers and university hospitals focus on platforms supporting embryologist workflow retraining and standardized competency development.
Fertility clinics command the dominant volume position; research laboratories are gaining share fastest on technology trial adoption.
Deployment:
Volume concentrates in on-premise installations while margin shifts toward hybrid and cloud configurations.
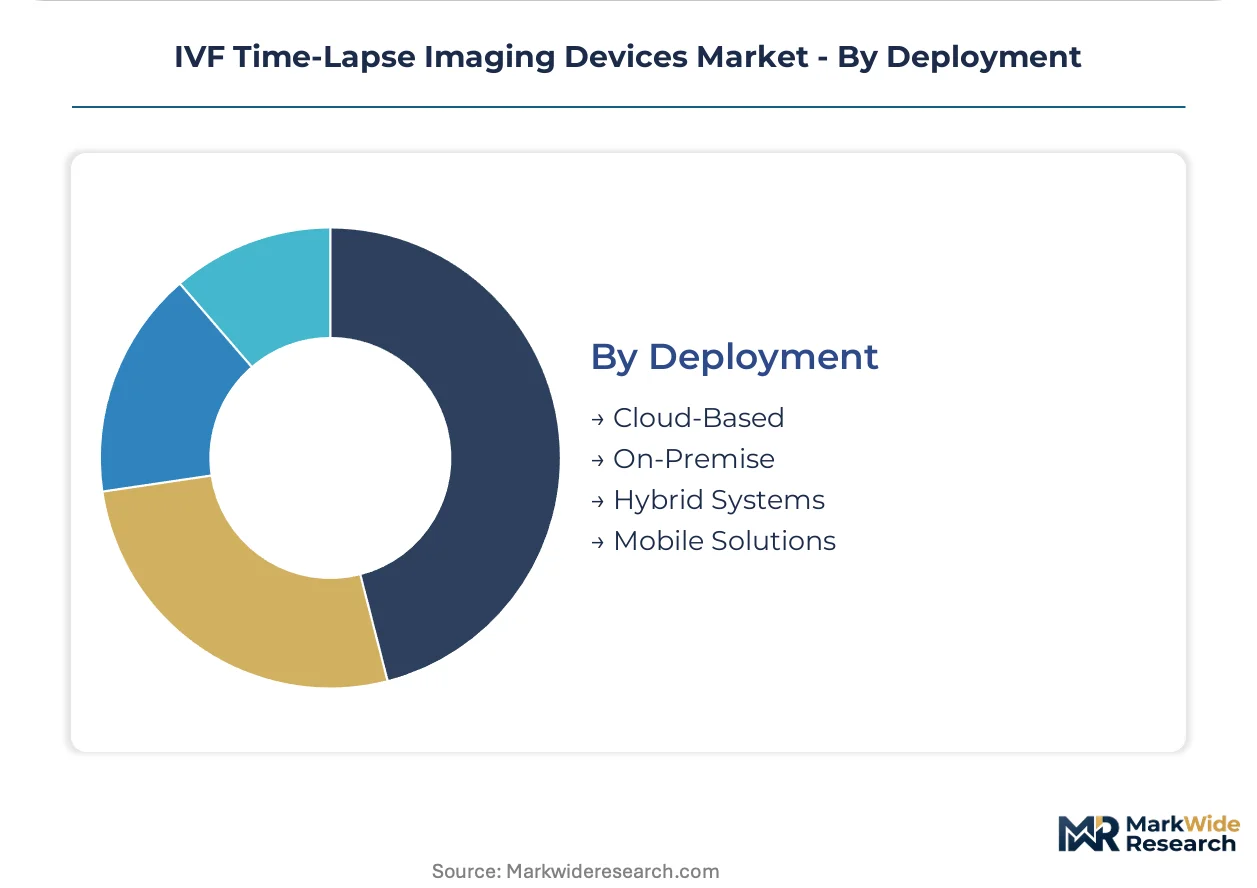
- On-Premise:Traditional server-based data storage and processing remains prevalent in mature markets with stringent data localization requirements, particularly German fertility networks navigating GDPR and EU MDR obligations.
- Hybrid Systems:Combined local-edge and cloud architectures balance data sovereignty with telemedicine access, gaining traction among mid-sized clinics and Nordic distributed specialist networks.
- Cloud-Based:Fully remote platforms enable subscription software monetization and recurring revenue streams from clinics deferring hardware replacement capital expenditure.
- Mobile Solutions:Tablet and smartphone-based review interfaces support remote embryologist consultation and emergency decision support.
On-premise deployment retains the largest installed base; hybrid systems are advancing fastest on new installation preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fertility clinic networks concentrate procurement authority in Germany, Japan, Australia, and the United States, while emerging demand surfaces in Thailand and Singapore. Specialized reproductive medicine centers drive equipment standardization across these markets.
Germany
Specialized fertility networks in Bavaria and North Rhine-Westphalia consolidate procurement of integrated monitoring platforms. EU MDR software validation requirements accelerate replacement of legacy imaging systems with compliant integrated incubator-imager configurations. Frankfurt and Munich clusters anchor multi-site standardization efforts across German-speaking fertility markets.
Japan
PMDA clinical evidence requirements extend registration timelines for predictive embryo ranking algorithms by 18-24 months versus imaging-only approvals. Tokyo and Osaka fertility centers standardize uninterrupted morphokinetic monitoring protocols to reduce manual embryo handling. Kanto region clinics lead adoption of time-lapse incubation systems for improved implantation prediction accuracy.
Australia
Consolidated procurement by specialized fertility groups now controls majority national capacity following absorption of independent clinics. Sydney and Melbourne networks drive enterprise pricing negotiations for integrated time-lapse platforms. Distributed specialist networks in Queensland adopt hybrid deployment models balancing data sovereignty with telemedicine access for rural patient populations.
United States
FDA 510(k) premarket notification governs imaging components used in embryo culture, with Class II device classification shaping conformity pathways. Greater Boston and Pacific Northwest research laboratories pilot multi-spectral imaging modules combining visible-light morphology with metabolic indicators. California fertility centers prioritize interoperable systems with existing electronic health record infrastructure.
Thailand
Bangkok fertility hubs expand capacity without legacy equipment bases, enabling direct adoption of integrated time-lapse systems versus staged upgrades. The country's national medical device regulator imposes clinical performance documentation for algorithm-assisted embryo classification tools. Private reproductive medicine centers in central Thailand anchor regional technology diffusion into neighboring Southeast Asian markets.
IVF Time-Lapse Imaging Devices Market Key Industry Players
Channel-controlling players compete with product-specialist players across incubator-integrated systems, standalone imaging platforms, and computational software layers. The vendor base clusters around three strategic archetypes: integrated system manufacturers with captive incubator technology, standalone imaging specialists, and algorithm-driven analytics vendors. Dominant competitive moves include strategic partnerships for spectroscopic capability acquisition and geographic expansion through localized manufacturing infrastructure.
Within the integrated system tier, Vitrolife Sweden AB and Esco Medical Technologies occupy positions reflecting European and Asia-Pacific manufacturing footprints respectively. Genea Biomedx exemplifies the algorithm-specialist archetype through proprietary embryo ranking tools. ASTEC CO., LTD. and CooperSurgical Inc. represent diversified medical technology conglomerates with reproductive medicine divisions. Among Asia-based fabricators, Weigao Group, Hua Yue Enterprise Holdings, and Wuhan Huchuang Union Technology sit within regional supply chains serving price-sensitive clinic networks.
| Leading Market Players |
|---|
| Vitrolife Sweden AB |
| Esco Medical Technologies |
| Genea Biomedx |
| ASTEC CO., LTD. |
| CooperSurgical Inc. |
| Weigao Group |
| Hua Yue Enterprise Holdings |
| Wuhan Huchuang Union Technology |
| Esco Lifesciences |
| Others |
Cost & Logistics Intelligence
Rotterdam-to-Singapore ocean freight corridors carry precision optical components for incubator-imager assemblies, with container rate volatility feeding directly into landed cost differentials between German and Asia-Pacific fertility networks. This logistics cost compression advantage for regional assemblers with captive sensor sourcing enables sharper price competition against EU-manufactured platforms facing EU MDR compliance overhead.
Pricing Analysis
Cost-plus contracts with German precision optics suppliers index to rare earth element benchmarks, embedding commodity exposure into embryo monitor pricing. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared predictive algorithms from imaging-only configurations and refurbished legacy platforms. Pricing pressure stems from mid-sized clinic consolidation into purchasing cooperatives demanding volume discounts. Research laboratories exhibit lowest price sensitivity due to grant-funded procurement, while independent fertility clinics in Southeast Asia face acute budget constraints.
Supply Chain Analysis
Export control regimes restricting high-resolution CMOS sensor technology limit flows from German and Japanese suppliers to Chinese device assemblers, fragmenting regional manufacturing strategies. Optical sensor modules, thermal calibration units, and cloud analytics subscriptions draw from concentrated German, Japanese, and South Korean production clusters. Single-source vulnerability concentrates in sCMOS detectors for multi-spectral configurations. Distribution runs through specialized fertility equipment distributors with embryologist training capabilities, bypassing general medical device channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through multi-clinic fertility network consolidation in Australia and Germany, shifting procurement authority from individual laboratory directors to centralized technology committees with enterprise-scale negotiating leverage.
For Market Incumbents: Build regulatory moats through EU MDR Annex IX certification for algorithm-assisted embryo ranking modules. Deepen software competencies through acquisition of deep learning specialists to counter margin compression from standalone analytics vendors. Anchor capacity in Singapore to mitigate tariff exposure on precision optics imports into Southeast Asian markets. For New Entrants and Emerging Players: Establish a beachhead in Thailand's fertility hub expansion, where greenfield clinic construction bypasses legacy equipment lock-in. Target subscription-based remote embryology platforms for Nordic distributed networks seeking data sovereignty-compliant telemedicine access. Partner with regional distributors offering embryologist certification programs to accelerate clinical validation timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates with underperforming reproductive medicine divisions lacking AI development capabilities. Long-term viability hinges on software-enabled recurring revenue transformation rather than hardware replacement cycles. Monitor PMDA registration acceleration for predictive claims as inflection signal for algorithmic embryo scoring standardization.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Software Lifecycle Certification | Notified body scrutiny of algorithm validation creates compliance barrier for non-integrated vendors. |
| Multi-Spectral Imaging Partnership | Spectroscopic capability acquisition narrows distinction between morphology and metabolic assessment platforms. |
| Hybrid Deployment Architecture Launch | Local-edge plus cloud configurations balance GDPR obligations with telemedicine access for rural networks. |
| Embryologist Workflow Training Program | Competency development accelerates technology absorption and creates switching costs for established clinics. |
| Southeast Asian Manufacturing Footprint | Localized assembly reduces landed cost for Thailand and Singapore fertility hubs expanding without legacy bases. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with embryology laboratory directors, fertility clinic procurement managers, biomedical equipment distributors, and reproductive medicine regulatory consultants. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body guidance documents, PMDA clinical evidence requirements, and hospital procurement contract disclosures. Bottom-up installation base modeling and top-down fertility center revenue allocation were cross-referenced for triangulation.
Calibration against historical replacement cycles and regulatory registration timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, deployment architecture, end-user category, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating technology adoption S-cycles and clinic network consolidation patterns. Forecast inputs included EU MDR transition completion rates and PMDA predictive claim approval velocity.
Stress conditions across freight cost volatility, rare earth element pricing, and regulatory registration delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fertility clinic network consolidation trajectories and algorithmic embryo scoring clinical validation progress. Material shifts in EU MDR software classification enforcement or PMDA evidentiary requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Refractive Surgery Devices Market
Medical Devices
Global Augmentative and Alternative Communication (AAC) Devices Market
Medical Devices
Aneurysm Coiling & Embolization Devices Market
Medical Devices
Low Vision Aids Market
Medical Devices
Europe Ultrasound Devices Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
3D Printing for Surgical Procedures Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Australia Minimally Invasive Surgery Devices Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Transradial Closure Devices Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Nitinol-Based Guide Wire Market
Medical Devices
Thermal Ablation Devices Market