
 EMEA Surgical Microscopes Market | 2026-2036
EMEA Surgical Microscopes Market Size, Share, and Industry Trends Forecast 2026-2036
EMEA Surgical Microscopes Market Intelligence
CE marking under the EU Medical Device Regulation is collapsing the supplier landscape as smaller manufacturers struggle with extended conformity assessment cycles. Carl Zeiss Meditec AG leverages its captive optics foundry to sustain margin control across neurosurgery configurations. Leica Microsystems anchors the premium dental segment through proprietary fluorescence filter technology.
Surgical microscopes are precision optical instruments combining stereoscopic eyepieces, motorized focusing stages, and integrated illumination systems to magnify anatomical structures during invasive procedures. Operating microscopes retain the largest revenue pool due to their ubiquity across OR suites, while fluorescence microscopy represents the fastest-expanding technology segment as surgeons demand real-time tissue differentiation. Digital microscopy is displacing conventional optical pathways in teaching hospitals seeking remote consultation capabilities.
The EU Medical Device Regulation and EMA guidance on fluorescence-guided surgery are tightening documentation requirements and reshaping product development priorities. Germany's KBA-equivalent notified bodies and France's ANSM are enforcing stricter post-market surveillance protocols that favor established manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor how fluorescence imaging reimbursement evolves under national health technology assessment frameworks.
Market Dynamics
Fluorescence-guided surgery is compressing purchasing cycles across German and French university hospitals as departments prioritize intraoperative tissue differentiation capabilities over conventional optical magnification.
Growth Catalysts
- EMA guidance on fluorescence-guided surgery:The European Medicines Agency's expanding reimbursement frameworks for image-guided interventions accelerate capital allocation toward hybrid optical systems in neurosurgery suites.
- United Kingdom ophthalmology modernization:NHS trusts are consolidating procurement for digital-ready microscope platforms to support cataract surgery backlogs and training pipeline expansion.
- Optical coherence tomography integration:Real-time OCT overlay capabilities are pulling upgrade demand from retinal surgery departments seeking sub-surface visualization without instrument exchange.
Market Restraints
- EU Medical Device Regulation conformity costs:Extended CE marking timelines and clinical evidence requirements for fluorescence modules are freezing smaller manufacturers out of the notified body queue.
- Specialized optical glass supply:German and Swiss precision optics foundries operate at capacity, creating 12-18 month lead times for apochromatic objective lenses.
- Fluorescence agent dependency:System utilization ties to indocyanine green and sodium fluorescein availability, exposing hospitals to pharmaceutical supply volatility.
Strategic Opportunities
- Saudi Arabia and UAE hospital construction:Greenfield medical cities in Riyadh and Dubai are specifying integrated surgical microscope-OR suites without legacy equipment constraints.
- Remote consultation infrastructure:4K digital video output standards create service revenue streams through telepathology and intraoperative remote mentoring subscriptions.
- France ANSM fast-track pathways:Priority review designations for breakthrough surgical visualization devices compress time-to-reimbursement for fluorescence-enabled platforms.
Industry Challenges
- Biomedical optics engineering talent:The intersection of precision mechanics, fluorescence physics, and surgical workflow design requires scarce hybrid skill sets concentrated in Stuttgart and Munich clusters.
- Legacy OR integration complexity:Teaching hospitals face cabling and software interoperability barriers when retrofitting digital heads-up displays onto 8-10 year old motorized stands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMEA Surgical Microscopes Market |
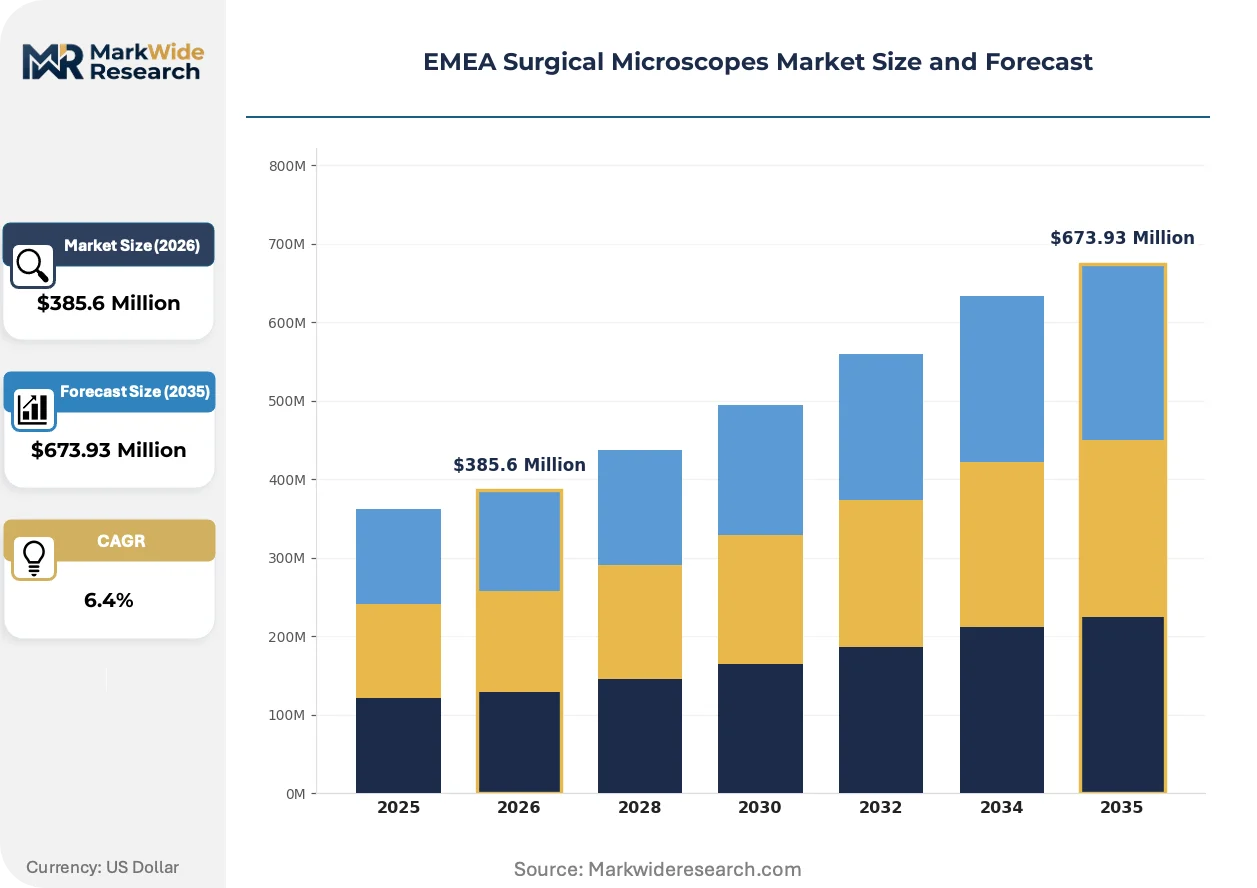
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operating Microscopes, Dental Microscopes, ENT Microscopes, Neurosurgery Microscopes Technology: Optical Coherent Tomography, Digital Microscopy, 3D Visualization, Fluorescence Microscopy End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Laboratories Application: Neurosurgery, Ophthalmology, Dentistry, Plastic Surgery |
| Companies Covered | Carl Zeiss Meditec AG, Leica Microsystems, Olympus Corporation, Alcon Inc., Topcon Corporation, Takagi Seiko Co. Ltd., Haag-Streit Surgical GmbH, ARI Medical Technology Co. Ltd., Synaptive Medical, Others |
| Regions Covered | EMEA: Germany, UK, France, Saudi Arabia, UAE, South Africa, Russia, Italy, Rest of EMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMEA Surgical Microscopes Market Strategic Shifts & Innovations
Digital imaging pipelines are displacing conventional binocular eyepieces as the primary surgeon interface, forcing manufacturers to reconfigure optical benches around sensor arrays rather than direct ocular pathways.
Fluorescence microscopy is bifurcating the installed base between premium hybrid systems and conventional white-light platforms. German neurosurgery departments are consolidating procurement around ICG-enabled configurations for vascular mapping. This technology shift is compressing margins on non-fluorescence inventory while rewarding captive filter technology holders.
The EU Medical Device Regulation is extending technical documentation requirements for software-driven illumination controls. Manufacturers must submit cybersecurity validation and algorithm transparency files alongside traditional optical performance data. French and British notified bodies are prioritizing fluorescence module submissions, creating regional approval speed differentials.
Hospital procurement committees are unbundling service contracts from capital equipment purchases. United Kingdom trusts now negotiate microscope maintenance through third-party clinical engineering consortia rather than manufacturer service divisions. This purchasing behavior shift is visible across NHS foundation trusts modernizing ophthalmology suites.
EMEA Surgical Microscopes Market Segmentation
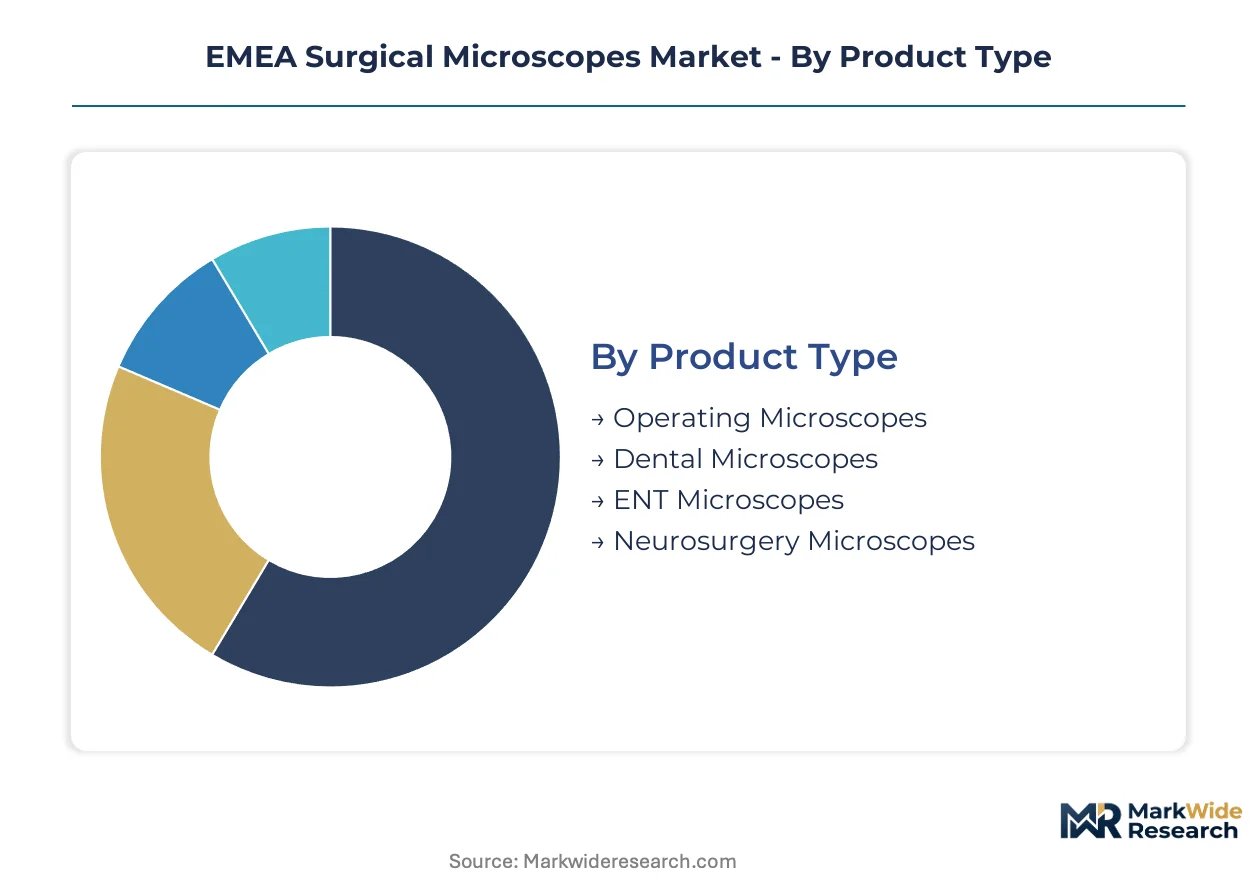
Surgical microscope procurement patterns diverge sharply across EMEA depending on whether systems serve high-throughput hospital suites or specialized research settings. Understanding these segment boundaries clarifies why German university hospitals prioritize fluorescence-enabled configurations while Gulf state greenfield projects demand integrated OR ecosystems.
Product Type:
German and French hospital procurement concentrates on premium configurations with fluorescence modules, while Gulf state medical cities specify bundled suites without legacy constraints.
- Operating Microscopes:General-purpose platforms with motorized focusing stages and halogen or LED illumination serve the broadest procedural range across OR suites. Demand clusters in United Kingdom NHS trusts modernizing cataract surgery infrastructure and Saudi hospital construction projects specifying integrated visualization systems.
- Neurosurgery Microscopes:High-magnification systems with apochromatic optics and integrated fluorescence filters enable vascular mapping and tumor margin delineation. German university departments are expanding installed bases of ICG-enabled configurations as EMA guidance extends reimbursement frameworks for image-guided interventions.
- Dental Microscopes:Compact bench-mounted units with 10x to 25x magnification support endodontic and periodontal procedures in private practice settings.
- ENT Microscopes:Long-reach stands with flexible suspension systems accommodate head-and-neck surgical positioning requirements in specialized otolaryngology departments.
Operating microscopes hold the largest share; momentum sits with neurosurgery microscopes.
Technology:
Cost tiers separate established optical pathways from sensor-array platforms requiring substantial software validation under EU MDR cybersecurity requirements.
- Fluorescence Microscopy:Filter-based systems excite indocyanine green or sodium fluorescein to reveal vascular structures and tissue perfusion in real time. French ANSM fast-track pathways are compressing approval timelines for breakthrough surgical visualization devices incorporating these modules.
- Digital Microscopy:Sensor-array platforms replacing binocular eyepieces with 4K video output enable remote consultation and teaching applications. United Kingdom foundation trusts are consolidating procurement around digital-ready platforms to address surgical backlogs and training pipeline expansion.
- Optical Coherence Tomography:Interferometric sub-surface imaging integrated into ophthalmology microscopes provides retinal layer visualization without instrument exchange.
- 3D Visualization:Stereoscopic display systems for surgeon comfort and assistant viewing in complex prolonged procedures.
Digital microscopy is expanding most quickly; fluorescence microscopy commands premium positioning.
End User:
Volume concentration sits with capital-rich hospital systems, while margin capture favors research laboratories requiring customized optical configurations.
- Hospitals:Tertiary centers with dedicated neurosurgery and ophthalmology departments drive fluorescence-enabled system procurement. German university hospitals are extending installed bases as EMA guidance reshapes capital allocation priorities toward hybrid optical platforms.
- Ambulatory Surgical Centers:High-throughput cataract and minor plastic surgery facilities in France and the United Kingdom favor cost-optimized configurations with rapid turnover capabilities.
- Clinics:Private dental and ophthalmology practices purchasing compact systems with limited multimodality expansion paths.
- Research Laboratories:Academic and pharmaceutical facilities requiring custom optical benches with modular illumination and documentation capabilities.
Hospitals dominate installed value; ambulatory surgical centers are gaining procurement velocity.
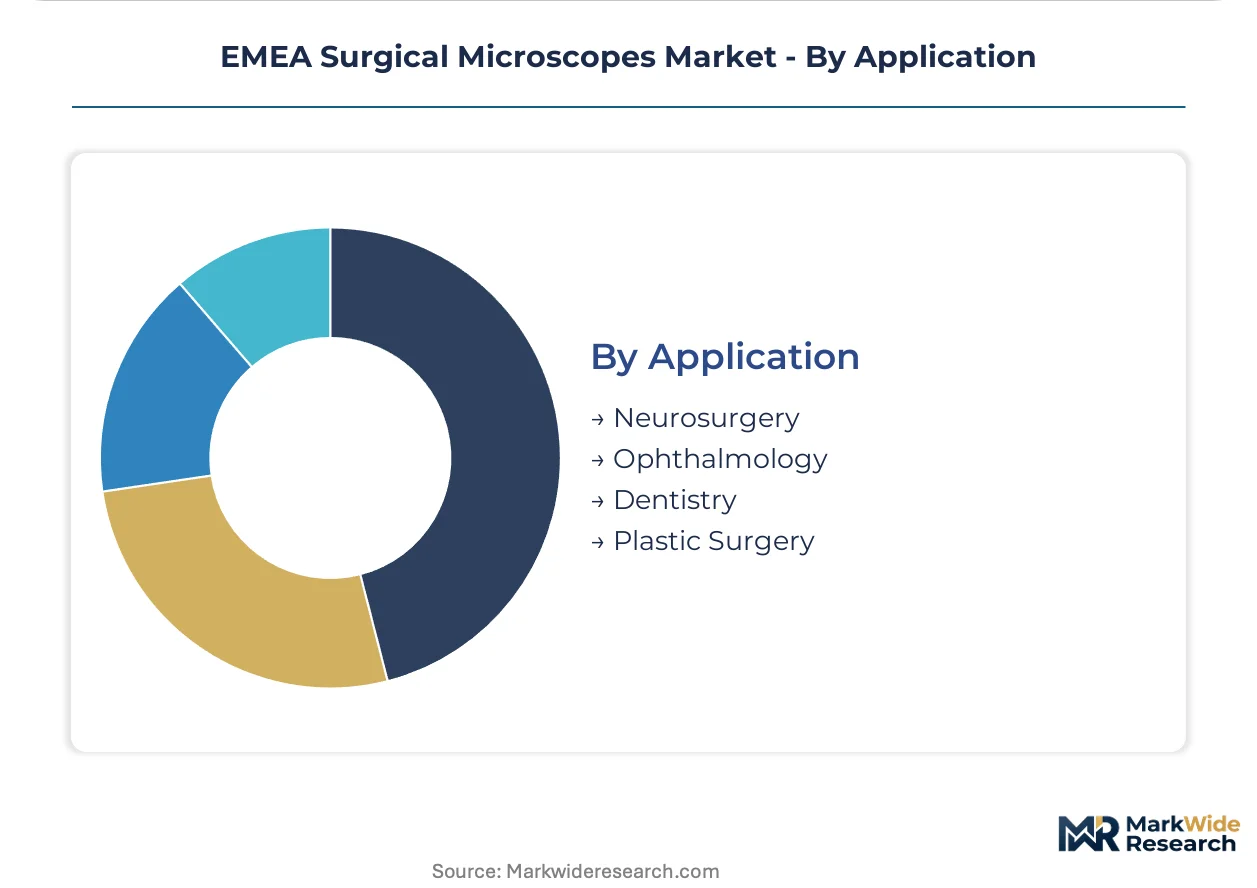
Application:
Application maturity separates established ophthalmology workflows from emerging fluorescence-guided protocols reshaping neurosurgical practice.
- Neurosurgery:Vascular mapping, tumor resection, and aneurysm clipping procedures demand ICG-enabled fluorescence and prolonged high-magnification stability. German departments are consolidating procurement around these configurations as reimbursement frameworks evolve.
- Ophthalmology:Cataract extraction and retinal surgery drive the highest procedure volumes across EMEA, with United Kingdom NHS trusts addressing surgical backlogs through digital platform modernization.
- Dentistry:Endodontic and microsurgical periodontal procedures in private practice settings.
- Plastic Surgery:Reconstructive microsurgery and flap perfusion assessment applications.
Ophthalmology generates the highest procedure volume; neurosurgery commands the steepest technology premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EMEA surgical microscopes market draws structural support from the Rhine-Main-Danube corridor linking German precision optics clusters to Mediterranean distribution ports, with the Channel Tunnel rail freight connection enabling rapid equipment transit between UK NHS procurement hubs and continental manufacturing centers.
Germany
EMA guidance on fluorescence-guided surgery and KBA-equivalent notified body enforcement are accelerating capital allocation toward hybrid optical platforms in university hospital neurosurgery departments. The EU MDR is extending CE marking timelines, freezing smaller manufacturers out of conformity assessment queues. Stuttgart and Munich optics clusters concentrate apochromatic lens production and fluorescence filter engineering talent.
United Kingdom
NHS foundation trusts are consolidating procurement for digital-ready microscope platforms to address cataract surgery backlogs and training pipeline expansion. The Medicines and Healthcare products Regulatory Agency is aligning post-market surveillance protocols with EU MDR cybersecurity requirements for software-driven illumination controls. London and Southeast teaching hospitals are retrofitting 4K video output standards for remote consultation infrastructure.
France
ANSM fast-track pathways for breakthrough surgical visualization devices are compressing time-to-reimbursement for fluorescence-enabled platforms in tertiary ophthalmology suites. The national health technology assessment framework is evolving coverage criteria for ICG-enabled vascular mapping procedures. Paris and Lyon university hospitals are unbundling service contracts from capital equipment purchases through third-party clinical engineering consortia.
Saudi Arabia
Greenfield medical cities in Riyadh are specifying integrated surgical microscope-OR suites without legacy equipment constraints as part of Vision 2030 healthcare infrastructure expansion. The Saudi Food and Drug Authority is harmonizing medical device registration pathways with EU MDR technical documentation standards. King Faisal Specialist Hospital and Research Centre anchors demand for premium neurosurgery configurations.
United Arab Emirates
Dubai Healthcare City and Abu Dhabi hospital construction projects are demanding bundled visualization ecosystems with remote mentoring capabilities for intraoperative consultation. MOHAP is enforcing cybersecurity validation requirements for digital microscopy platforms with cloud-connected documentation features. Cleveland Clinic Abu Dhabi and Sheikh Shakhbout Medical City are consolidating procurement around fluorescence-enabled hybrid systems.
EMEA Surgical Microscopes Market Key Industry Players
Listed leaders compete with private specialists across regulatory compliance capabilities and fluorescence module integration depth. The supplier landscape compresses as extended EU MDR conformity assessment cycles favor established players with dedicated regulatory affairs teams and captive optics foundries. Three archetypes dominate: integrated conglomerates with diversified medical device portfolios, precision optics specialists with captive manufacturing, and digital imaging platform developers. Competitive positioning hardens through M&A activity targeting fluorescence filter technology and strategic partnerships for OR integration software.
Within the integrated conglomerate tier, Carl Zeiss Meditec AG and Olympus Corporation occupy positions defined by backward integration into precision optics manufacturing and diversified surgical visualization portfolios. Leica Microsystems exemplifies the precision optics specialist archetype, anchoring premium segment positioning through proprietary fluorescence technology. These three companies represent the structural concentration of regulatory expertise and manufacturing scale that the EU MDR favors.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Leica Microsystems |
| Olympus Corporation |
| Alcon Inc. |
| Topcon Corporation |
| Takagi Seiko Co. Ltd. |
| Haag-Streit Surgical GmbH |
| ARI Medical Technology Co. Ltd. |
| Synaptive Medical |
| Others |
Cost & Logistics Intelligence
LED illumination modules displacing halogen assemblies are redrawing supplier maps from Stuttgart to Shenzhen while compressing aftermarket service margins across EMEA hospital procurement committees. This component substitution simultaneously shifts value capture toward semiconductor-qualified vendors and erodes the historical pricing power of legacy optics houses tethered to thermal management subsystems.
Pricing Analysis
Certification level under EU MDR and ISO 13485 creates the primary spread between premium fluorescence-enabled configurations and economy-tier white-light platforms. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales bundling intensity and software validation depth rather than optical performance alone. Cost compression in the standard tier is intensifying as United Kingdom NHS trusts unbundle service contracts and negotiate through third-party clinical engineering consortia. Ambulatory surgical centers exhibit the sharpest price sensitivity, while German university hospitals prioritize capability over acquisition cost.
Supply Chain Analysis
Inventory cycles for apochromatic objective lenses now stretch 12-18 months as German and Swiss precision optics foundries operate at capacity limits. Manufacturing gravity centers on Stuttgart, Munich, and Oberkochen for optical benches, with fluorescence filter coatings concentrated in Swissmedic-regulated Swiss facilities. Supply chain risk hinges on single-source dependency for specialized rare-earth-doped glass substrates. Distribution runs through manufacturer-direct hospital contracting in Germany, third-party clinical engineering consortia in France and the United Kingdom, and bundled OR suite integrators in Saudi Arabia and the UAE.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from sensor-array digital platforms that bypass conventional optical pathways, requiring defensive repositioning around fluorescence module integration depth and regulatory compliance velocity.
For Market Incumbents: Fortify captive fluorescence filter technology and backward integration into precision optics foundries to defend margin structure against digital-native entrants. Accelerate EU MDR technical documentation submission velocity to exploit approval queue bottlenecks that freeze smaller competitors. Prioritize software cybersecurity validation investment as French ANSM and United Kingdom MHRA tighten algorithm transparency requirements. For New Entrants and Emerging Players: Anchor in ambulatory surgical center cataract modernization programs across France and the United Kingdom where procurement committees favor cost-optimized digital-ready platforms over premium hybrid systems. Target NHS foundation trust consolidation waves with subscription-based remote mentoring service bundles rather than capital equipment sales. Pursue fast-track ANSM designation for breakthrough surgical visualization submissions to compress time-to-reimbursement. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors precision optics specialists with captive manufacturing and established regulatory affairs infrastructure over diversified conglomerates. Long-term viability rests on fluorescence-guided surgery reimbursement expansion under national health technology assessment frameworks. Monitor EMA guidance evolution on ICG-enabled vascular mapping as the primary inflection signal for neurosurgery configuration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR queue positioning determines competitive access timelines for fluorescence module submissions. |
| Fluorescence Filter Technology Acquisition | Proprietary ICG excitation capabilities anchor premium neurosurgery procurement decisions in German university hospitals. |
| Hospital System Partnership | NHS trust consolidation creates vendor consolidation pressure favoring digital-ready platform suppliers. |
| Software Companion Development | Cybersecurity validation and algorithm transparency files satisfy ANSM and MHRA post-market surveillance protocols. |
| Reimbursement Strategy | National health technology assessment framework alignment determines ICG-enabled procedure coverage in France and Germany. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with neurosurgery department heads, hospital procurement committee chairs, biomedical optics engineers, GPO contracts managers, and fluorescence agent pharmaceutical specialists. Secondary validation drew from EMA guidance documents, ANSM fast-track designation records, NHS procurement databases, EU MDR notified body submission logs, and German university hospital capital equipment budgets. Bottom-up installation base modeling triangulated against top-down addressable procedure volume estimates.
Across the analysis window, quantitative outputs reflect segmentation by product type, technology modality, end-user facility tier, and application specialty. CAGRs were derived from procedure volume growth rates, equipment replacement cycles, and reimbursement framework evolution assumptions. Forecast inputs incorporated fluorescence-guided surgery adoption curves, LED illumination substitution timelines, and digital microscopy penetration rates in teaching hospital settings.
Material uncertainties — regulatory timeline delays, fluorescence agent supply disruptions, and NHS procurement austerity measures — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Transcranial Magnetic Stimulators Market
Medical Devices
Reusable Resuscitators Market
Medical Devices
Snare Devices Market
Medical Devices
Nephrostomy Catheters Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Brazil Angioplasty Devices Market
Medical Devices
US Mechanical Ventilator Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
India Biopsy Devices Market
Medical Devices
Neuroendoscopy Devices Market
Medical Devices
Global Bone Cement Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
Thoracic Surgery Devices Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
Organ Care Systems (OCS) Market