
 Aneurysm Coiling & Embolization Devices Market | 2026-2036
Aneurysm Coiling & Embolization Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Aneurysm Coiling & Embolization Devices Market Insights
The distinction between academic medical centers and community hospitals is collapsing as endovascular coiling protocols standardize across facility tiers. Stryker leverages its broad neurovascular portfolio to sustain service contracts with high-volume stroke centers. Medtronic anchors the detachable coil segment through proprietary detachment technologies that reduce procedure variability.
Aneurysm coiling and embolization devices are implantable or injectable systems designed to occlude cerebral or peripheral vascular anomalies through mechanical obstruction or thrombogenic promotion, typically delivered via microcatheters under fluoroscopic guidance with platinum-tungsten alloy compositions providing radiopacity and controlled conformability. These devices serve the primary purpose of preventing aneurysm rupture or reducing blood flow to malformations without open craniotomy. Microcoils dominate procedural volumes across intracranial applications while liquid embolic agents capture expanding share in arteriovenous malformation cases where complex vascular geometry defies conventional coil packing. Neurovascular stents represent the highest-margin segment due to dual-function deployment as both flow diverters and coil-assist scaffolding in wide-neck aneurysm geometries.
FDA premarket notification pathways and EMA medical device regulation frameworks govern biocompatibility testing and clinical evidence requirements for neurovascular implants, with both agencies intensifying scrutiny of coating durability and detachment reliability. ISO 10993 biological evaluation standards further constrain material selection and surface treatment protocols for devices in sustained intravascular contact. Stakeholders must monitor evolving regulatory divergence between US and European post-market surveillance expectations as each jurisdiction implements distinct unique device identification and adverse event reporting timelines.
Market Dynamics
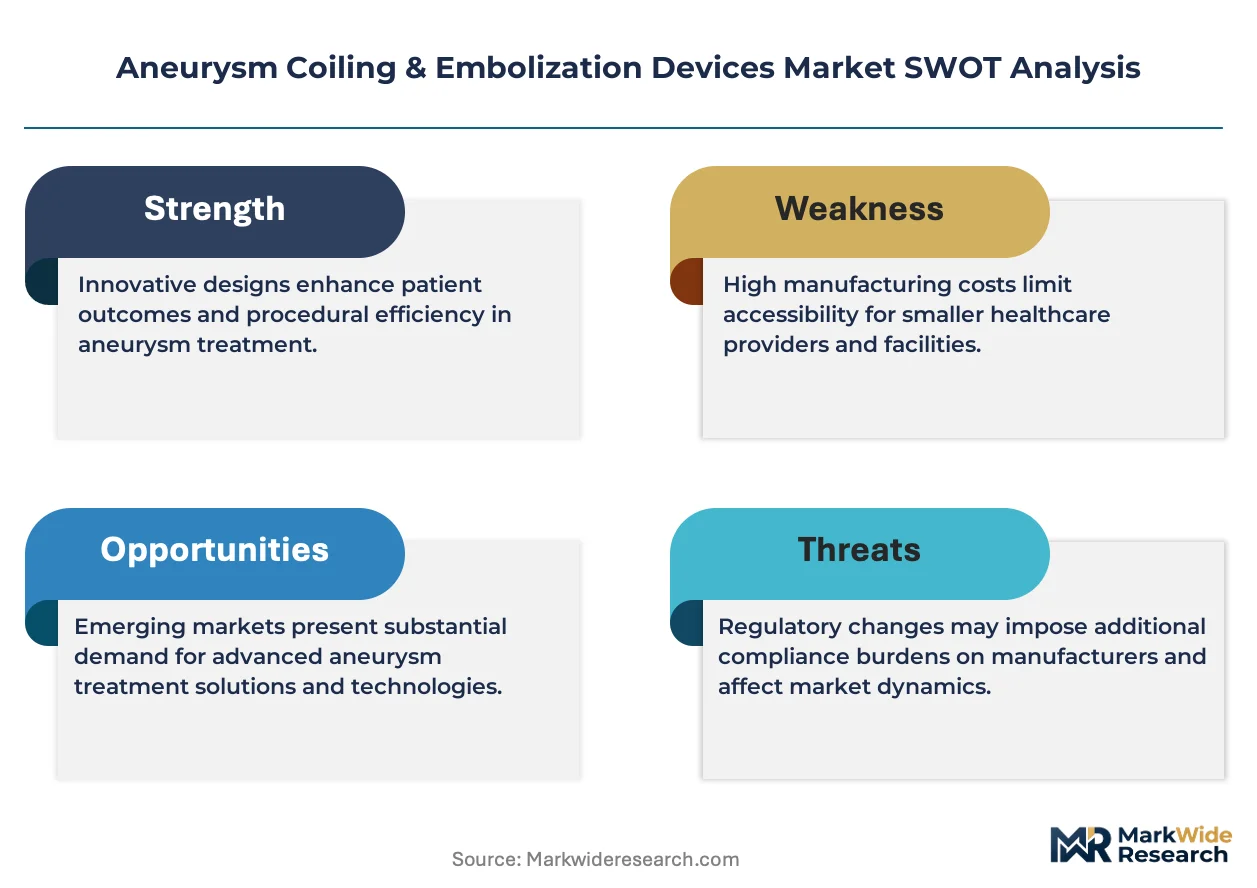
Platinum-tungsten alloy sourcing constraints are compressing coil manufacturing margins while simultaneously accelerating bioabsorbable polymer research programs across the neurovascular supply base.
Growth Catalysts
- EMA MDR convergence:Streamlined clinical evidence requirements for neurovascular implants are accelerating CE mark timelines for next-generation flow diverters.
- Endovascular suite expansion:Community hospitals in the United States are installing biplane angiography systems to capture transfer volume from academic stroke centers.
- Bioactive surface coatings:Hydrogel-based thrombogenic layers on microcoils are reducing recurrence rates in wide-neck aneurysm geometries.
Market Restraints
- Platinum price volatility:Spot market fluctuations for platinum-group metals directly impact coil production economics and inventory carrying costs.
- Single-source microcatheter dependence:Concentration of high-torque delivery system manufacturing in specific European industrial clusters creates supply vulnerability.
- FDA premarket approval timelines:Extended neurological device review queues delay commercialization of novel detachment mechanisms.
Strategic Opportunities
- India neurovascular infrastructure:Underpenetrated tertiary care networks in Maharashtra and Tamil Nadu present first-mover positioning for training-intensive coiling procedures.
- Flow diversion + coiling convergence:Dual-function devices combining scaffolding and embolization are creating premium procedural economics in complex aneurysm cases.
- Telestroke network integration:Remote consultation platforms are extending coiling candidate identification to rural emergency departments previously bypassed for transfer.
Industry Challenges
- Neurointerventionalist training pipelines:Fellowship program capacity constraints limit the annual supply of physicians qualified for independent aneurysm coiling.
- Legacy EMR integration:Procedural documentation systems require manual data entry bridges to capture device-specific outcomes for registry participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aneurysm Coiling & Embolization Devices Market |
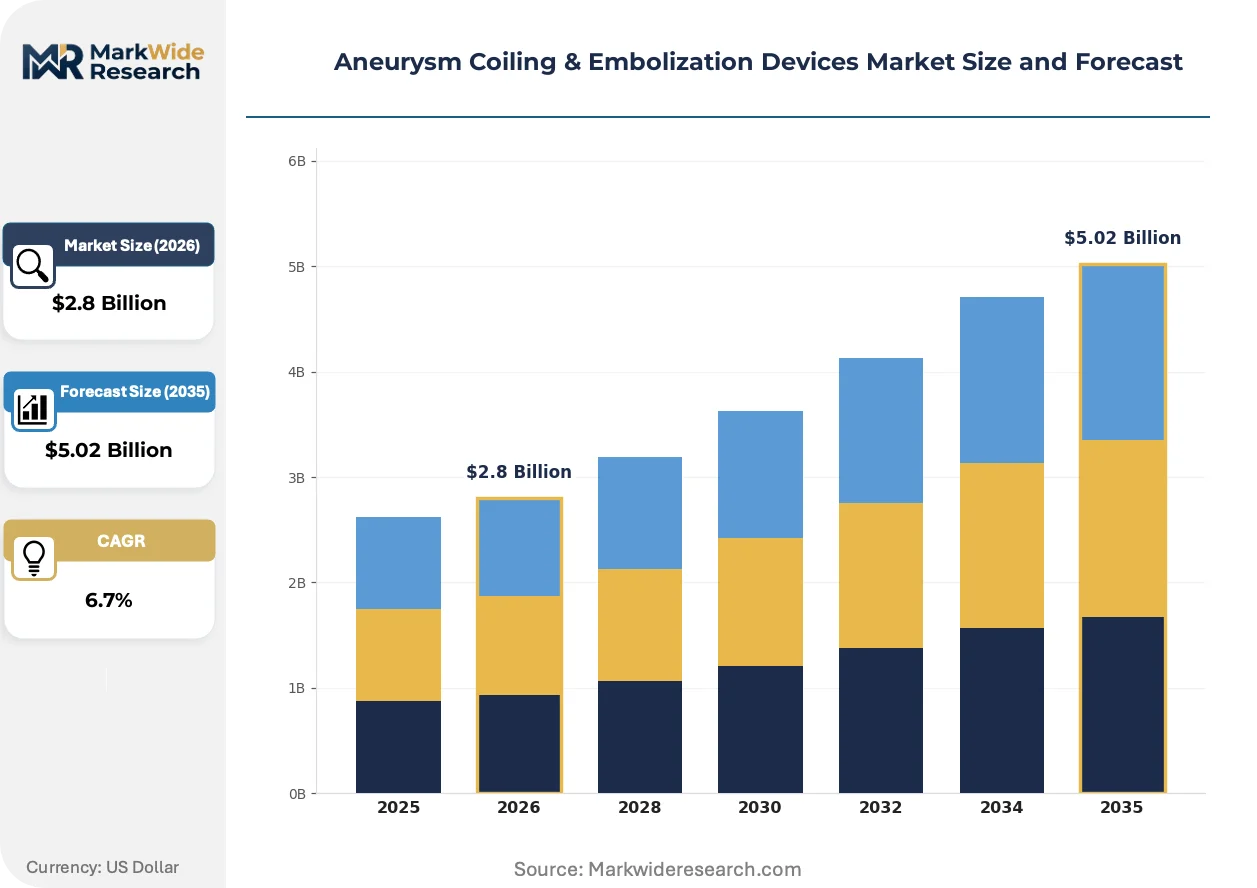
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcoils, Liquid Embolic Agents, Detachable Coils, Neurovascular Stents End User: Hospitals, Outpatient Surgical Centers, Specialty Clinics, Research Institutions Application: Intracranial Aneurysms, Peripheral Aneurysms, Arteriovenous Malformations, Ischemic Stroke Delivery Mode: Catheter-Based, Endovascular, Surgical Access, Hybrid Approaches |
| Companies Covered | Medtronic, Stryker, Johnson & Johnson, Terumo Corporation, MicroVention, Penumbra, BALT Group, Boston Scientific, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aneurysm Coiling & Embolization Devices Market Trends and Innovations
Device-level intelligence and procedural automation are redefining how aneurysm occlusion therapies are delivered, measured, and reimbursed across healthcare systems.
Shape-memory polymer microcoils are decomposing the traditional platinum-dominated coil market by offering controlled expansion profiles that conform to irregular aneurysm sac geometries. Academic medical centers in Germany and Japan are piloting these systems for complex fusiform cases where conventional packing densities prove insufficient. The structural consequence is decomposing the historical trade-off between radiopacity and conformability that has constrained coil design for two decades.
REACH chemical safety frameworks in Europe are tightening scrutiny of nickel release from neurovascular stent alloys, forcing manufacturers to validate alternative superelastic compositions. This regulatory pressure is compressing development timelines for next-generation flow diverters as firms front-load biocompatibility testing. The neurovascular stent segment is responding by accelerating cobalt-chromium substitution programs and pre-submission engagement with EMA notified bodies.
Service unbundling is fragmenting the traditional device-procurement bundle as United States hospital systems separate coil purchases from microcatheter and guidewire sourcing. IDNs are establishing direct relationships with specialized neurovascular distributors, bypassing general surgical supply intermediaries. This channel restructuring is most visible in the Southeast and Midwest regions where Catholic health systems and for-profit chains are consolidating endovascular purchasing authority.
Aneurysm Coiling & Embolization Devices Market Segmentation
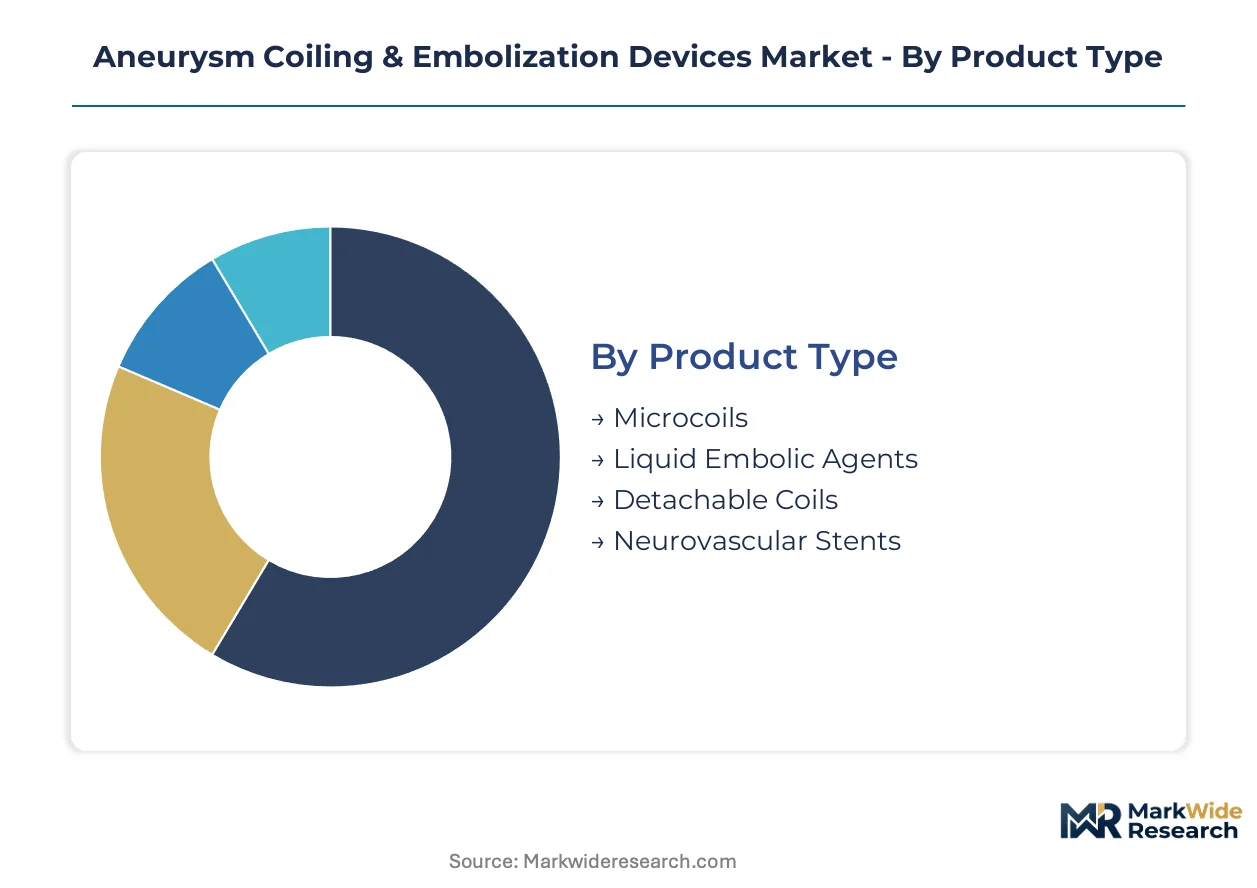
Device taxonomy in neurovascular therapeutics directly shapes reimbursement pathways, regulatory submission strategies, and purchasing committee composition across hospital systems. Segment boundaries reflect competing clinical philosophies between mechanical occlusion and flow modulation, with each category commanding distinct supply chain configurations and clinical training requirements.
Product Type:
FDA premarket approval timelines and EMA MDR clinical evidence requirements create divergent market access speeds across device categories, with flow diverters facing extended neurological device review queues while microcoils navigate streamlined 510(k) pathways.
- Microcoils:Platinum-tungsten alloy constructions deliver radiopacity and controlled conformability through helical or complex three-dimensional geometries. Demand concentrates in United States academic stroke centers where Medicare reimbursement favors catheter-based interventions for unruptured aneurysms; bioactive hydrogel coatings are reducing retreatment rates in wide-neck geometries.
- Liquid Embolic Agents:Ethylene-vinyl alcohol copolymers and n-butyl cyanoacrylate formulations polymerize upon vascular contact to achieve conformal filling of irregular malformation architectures. Adoption is accelerating in German and Japanese centers for arteriovenous malformation cases where conventional coil packing densities prove insufficient; REACH chemical safety frameworks are tightening scrutiny of solvent composition.
- Detachable Coils:Proprietary detachment technologies enable controlled release under fluoroscopic guidance.
- Neurovascular Stents:Dual-function deployment as flow diverters and coil-assist scaffolding commands premium positioning.
Microcoils handle the majority of throughput; liquid embolic agents are expanding most quickly on share.
End User:
Facility reimbursement tier and case volume thresholds determine device procurement authority, with IDNs consolidating purchasing across previously independent community hospitals.
- Hospitals:Tertiary care centers with biplane angiography suites capture complex aneurysm referrals and anchor manufacturer service contracts.
- Outpatient Surgical Centers:Ambulatory settings in United States markets are expanding endovascular capacity for elective coiling procedures.
- Specialty Clinics:Dedicated neurovascular centers concentrate fellowship-trained interventionalists and protocol standardization.
- Research Institutions:Academic medical centers in Germany and Japan pilot shape-memory polymer systems and next-generation flow diverters under investigational device exemptions.
Hospitals dominate absolute procedure volume; outpatient surgical centers are climbing the fastest as site-of-service migration accelerates.
Application:
Anatomical location and pathology type dictate device selection, with intracranial applications requiring higher radiopacity and detachment precision than peripheral interventions.
- Intracranial Aneurysms:Saccular and fusiform cerebral vascular anomalies represent the core addressable population for detachable coil systems.
- Peripheral Aneurysms:Splenic, renal, and visceral artery dilations employ adapted neurovascular technologies with modified delivery catheter lengths.
- Arteriovenous Malformations:Nidus architecture with high-flow shunting demands liquid embolic penetration or combined embolization strategies.
- Ischemic Stroke:Mechanical thrombectomy device convergence creates cross-training opportunities for neurointerventionalists.
Intracranial aneurysms command the steepest expansion trajectory; arteriovenous malformations show the fastest technology substitution as liquid embolics displace surgical resection.
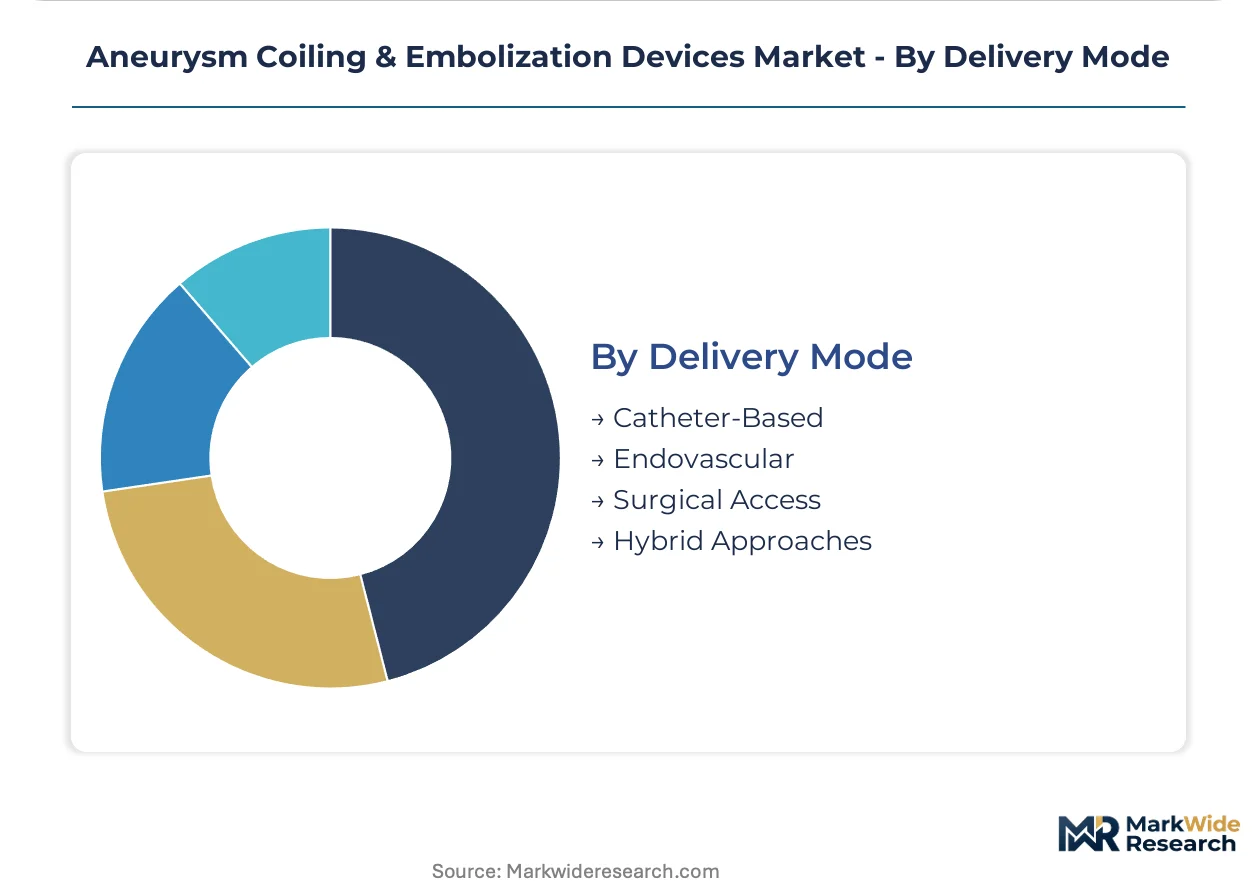
Delivery Mode:
Access strategy determines device compatibility, with catheter-based systems requiring dedicated microcatheter torque response and surgical access demanding hybrid operating room infrastructure.
- Catheter-Based:Transfemoral or transradial microcatheter advancement under roadmap guidance constitutes the standard approach for elective coiling.
- Endovascular:Broad category encompassing all intravascular access techniques without craniotomy.
- Surgical Access:Craniotomy with intraoperative angiography retains role for giant aneurysms requiring parent vessel reconstruction.
- Hybrid Approaches:Combined open surgical and endovascular techniques in specialized cerebrovascular centers.
Catheter-based delivery handles the majority of throughput; hybrid approaches are gaining share fastest as complex case complexity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites Europe's neurovascular device distribution hub status, while direct rail links from Germany's Ruhr industrial cluster feed platinum-tungsten alloy feedstock to coil manufacturers.
United States
Medicare reimbursement policies favor minimally invasive aneurysm interventions at academic stroke centers and community hospitals alike. FDA premarket approval pathways for neurological devices compress commercialization timelines for next-generation flow diverters. The Southeast and Midwest regions concentrate IDN purchasing authority where Catholic health systems consolidate endovascular procurement.
Germany
REACH chemical safety frameworks intensify scrutiny of nickel release from neurovascular stent alloys, accelerating cobalt-chromium substitution programs. EMA MDR convergence streamlines clinical evidence requirements for CE mark timelines on innovative coil designs. Academic medical centers in Bavaria pilot shape-memory polymer microcoils for complex fusiform aneurysm cases.
Japan
PMDA regulatory frameworks govern biocompatibility testing standards for sustained intravascular contact devices. METI industrial policy supports domestic neurovascular manufacturing capacity for platinum-tungsten alloy processing. The Kansai region around Osaka anchors specialized microcatheter production clusters serving Asia-Pacific distribution networks.
India
Underpenetrated tertiary care networks in Maharashtra and Tamil Nadu present first-mover positioning for training-intensive coiling procedures. CDSCO medical device regulations align with international standards to accelerate market entry for imported neurovascular implants. Mumbai and Chennai metropolitan areas expand biplane angiography suite installations to capture complex aneurysm referrals.
Aneurysm Coiling & Embolization Devices Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates that leverage broad neurovascular portfolios to sustain service contracts with high-volume stroke centers. The market structure reflects tiered competition between integrated device manufacturers and specialized neurovascular pure-plays. Three archetypes dominate: platinum-tungsten alloy specialists, flow diversion technology leaders, and liquid embolic formulators. M&A activity targets detachable coil technology assets while strategic partnerships address microcatheter supply vulnerabilities.
Among diversified conglomerates, Medtronic and Stryker occupy anchor positions exemplifying the integrated device manufacturer archetype. Medtronic represents the detachment technology specialization vector through proprietary release mechanisms. Stryker exemplifies portfolio breadth strategy spanning microcoils through flow diverters. Penumbra sits within the specialized neurovascular pure-play tier, representing the focused interventional technology archetype against diversified competitors.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Johnson & Johnson |
| Terumo Corporation |
| MicroVention |
| Penumbra |
| BALT Group |
| Boston Scientific |
| Cook Medical |
| Others |
Pricing and Supply Chain Analysis
Shape-memory polymer substitution for platinum-tungsten alloys is simultaneously relocating manufacturing toward Germany and Japan while compressing legacy coil pricing power in the United States. This material transition fragments the historical cost structure that anchored neurovascular device economics for two decades.
Pricing Analysis
Volume-discount tiering structures separate premium flow diverter systems from standard microcoil configurations and economy-tier liquid embolic agents. Price differentiation hinges on FDA premarket approval tier and after-sales technical support bundling. Margins are tightening due to platinum-group metal spot volatility and inventory carrying cost pressures. Community hospital IDNs exhibit highest price sensitivity; academic stroke centers prioritize detachment reliability over unit economics.
Supply Chain Analysis
Ruhr industrial cluster rail links to the Port of Rotterdam underwrite European neurovascular device distribution chokepoints. Platinum-tungsten alloy feedstock draws from Germany, Japan, and the United States; high-torque microcatheter manufacturing concentrates in Bavaria and Osaka. Single-source dependence on specialized European delivery system production creates tariff exposure vulnerability. Distribution runs through IDN consolidated purchasing committees and specialized neurovascular distributors bypassing general surgical supply intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telestroke network integration is transforming aneurysm coiling from episodic device sales into platform-mediated care coordination, with interoperability between remote consultation platforms and hospital EMR systems becoming the decisive ecosystem battleground.
For Market Incumbents: Secure proprietary detachment technology patents against bioabsorbable polymer substitution threats by accelerating cobalt-chromium alloy validation programs. Anchor service contracts with high-volume stroke centers through predictive maintenance agreements for biplane angiography systems. Vertical integration into microcatheter torque-response manufacturing mitigates European cluster supply vulnerability.
For New Entrants and Emerging Players: Neurointerventionalist training infrastructure gaps in Maharashtra and Tamil Nadu present white-space positioning for simulation-based credentialing platforms. Target underpenetrated Indian tertiary care networks with bundled device-training-reimbursement packages. Pursue CDSCO regulatory alignment as the fastest market entry pathway.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized neurovascular pure-plays with investigational device exemption pipelines in shape-memory polymers. Long-term viability over a multi-year horizon rests on REACH MDR compliance readiness and EMA notified body pre-submission engagement. Monitor FDA neurological device review queue compression as the signal for inflection timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Premarket approval pathways for novel detachment mechanisms compress commercialization timelines in the United States. |
| CE Marking Pathway | EMA MDR convergence accelerates market access for next-generation flow diverters across European tertiary care networks. |
| Hospital System Partnership | IDN consolidated purchasing authority in the Southeast and Midwest regions reshapes procurement channel economics. |
| Software Companion Development | Telestroke platform integration extends coiling candidate identification to rural emergency departments previously bypassed for transfer. |
| Reimbursement Strategy | Medicare policy alignment for catheter-based interventions anchors demand concentration at academic and community stroke centers. |
Research Methodology
Cross-validation between neurointerventionalist interviews and GPO contract database analysis anchors the qualitative findings in observable procurement behavior. Primary fieldwork engaged stroke center directors, hospital purchasing committee members, biomedical engineers specializing in angiography systems, and regulatory affairs leads at device manufacturers. Secondary validation drew from FDA 510(k) and PMA filings, EMA MDR submission databases, CMS Medicare reimbursement schedules, and hospital capital expenditure disclosures. Bottom-up procedure volume modeling triangulates against top-down manufacturer revenue segmentation.
Sensitivity analysis across platinum price volatility scenarios and neurointerventionalist training pipeline constraints tests forecast robustness. The analytical framework segments by product type, end user facility tier, anatomical application, and delivery mode across the projection horizon. CAGRs derive from procedure volume extrapolation moderated by reimbursement policy elasticity and technology substitution curves. Forecast inputs incorporate biplane angiography installation rates and REACH chemical safety framework implementation timelines.
Forecasts assume regulatory continuity in FDA premarket approval and EMA MDR regimes; material policy shifts would require re-modeling. Specific risk factors include platinum-group metal supply disruption, fellowship program capacity constraints, and IDN purchasing authority consolidation. Practitioners should keep alternative scenarios live as telestroke network penetration and bioabsorbable polymer clinical evidence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spherical IOL Market
Medical Devices
Mexico General Surgical Devices Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
External Nasal Dilator Market
Medical Devices
Germany Minimally Invasive Surgery Devices Market
Medical Devices
Endoscope Flushing Pumps Market
Medical Devices
3D Printed Prosthetics Market
Medical Devices
Needle Destroyer Market
Medical Devices
Otoscope Devices Market
Medical Devices
Non- Resorbable Cranial Fixation System Market
Medical Devices
Digital Blood Pressure Monitors Market
Medical Devices
Helium Free MRI Scanners Market
Medical Devices
Ultrasonic Medical Nebulizer Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Parenteral Feeding Devices Market