
 Global Augmentative and Alternative Communication (AAC) Devices Market | 2026-2036
Global Augmentative and Alternative Communication (AAC) Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Augmentative and Alternative Communication (AAC) Devices Market Analysis
Multi-source component procurement is broadening across AAC device manufacturers as supply chain resilience replaces single-source silicon dependencies. Tobii Dynavox leverages its captive eye-tracking sensor production to insulate margins from semiconductor volatility. Saltillo Corporation anchors North American distribution through dedicated clinician-facing sales channels. Smartbox Assistive Technology competes in Europe with modular hardware architectures that simplify field servicing.
Augmentative and Alternative Communication (AAC) Devices are electronic or non-electronic tools that substitute for or supplement natural speech, typically incorporating synthesized voice output, symbol-based interfaces, or physiological signal detection with response latencies under 300 milliseconds, designed to enable functional communication for individuals with speech impairments. Speech Generating Devices command the largest revenue pool due to Medicare and Medicaid reimbursement codes that specifically cover dedicated SGD hardware, while Software Applications represent the fastest-expanding margin segment as tablet-native platforms circumvent capital equipment procurement cycles. Gesture-Based Systems occupy a niche in pediatric rehabilitation where motor-planning limitations preclude fine motor control, though eye-tracking integration is displacing traditional switch access in advanced neurodegenerative cases.
The FDA regulates AAC devices as Class II medical instruments under 21 CFR 892.2050, requiring 510(k) premarket notification for speech synthesis hardware, while the EU Medical Device Regulation mandates notified body conformity assessment for software-driven communication aids sold in member states. Japan's PMDA applies pharmaceutical and medical device classification rules that delay market entry for non-Japanese manufacturers lacking domestic clinical data. Stakeholders must monitor whether WHO assistive technology priority list inclusion triggers procurement standardization in low-resource health systems.
Market Dynamics
Eye-tracking sensor integration is compressing device form factors while elevating clinical performance thresholds, forcing manufacturers to reconfigure hardware architectures around sub-300-millisecond response latency specifications.
Growth Catalysts
- Australia's National Disability Insurance Scheme:Participant-directed funding models empower end-users to select premium-tier devices, bypassing institutional procurement gatekeepers and accelerating upgrade cycles.
- FDA Breakthrough Device Designation:Expedited premarket review pathways for neurodegenerative communication aids compress regulatory timelines from 18 months to under 10 months.
- Pediatric rehabilitation centers:Motor-planning assessment protocols now mandate multi-modal access methods, driving parallel procurement of gesture-based and eye-tracking systems.
Market Restraints
- Semiconductor supply concentration:Single-source dependencies for specialized image-processing chips expose manufacturers to foundry allocation volatility in East Asian fabrication networks.
- Reimbursement code fragmentation:Medicare's dedicated SGD hardware codes exclude tablet-native software platforms, creating payment arbitrage that disadvantages modular architectures.
- Clinical validation timelines:PMDA requirements for domestic Japanese clinical data delay market entry by 24-36 months for non-Japanese manufacturers lacking local trial infrastructure.
Strategic Opportunities
- German pediatric speech therapy networks:Clinic consolidation into regional chains creates centralized procurement nodes for high-volume eye-tracking system deployment.
- WHO Assistive Technology Priority List inclusion:Standardization triggers in low-resource health systems could unlock pooled procurement mechanisms across Sub-Saharan African ministries.
- Cloud-based vocabulary synchronization:Convergence of edge-computing hardware with real-time lexicon updates enables subscription revenue models that displace capital equipment sales.
Industry Challenges
- Speech-language pathologist certification gaps:Specialized training for eye-tracking calibration and motor-access assessment lags device deployment, creating implementation bottlenecks in outpatient settings.
- Legacy switch-access infrastructure:Existing institutional investments in mechanical switch arrays resist full replacement, forcing hybrid compatibility engineering that extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Augmentative and Alternative Communication (AAC) Devices Market |
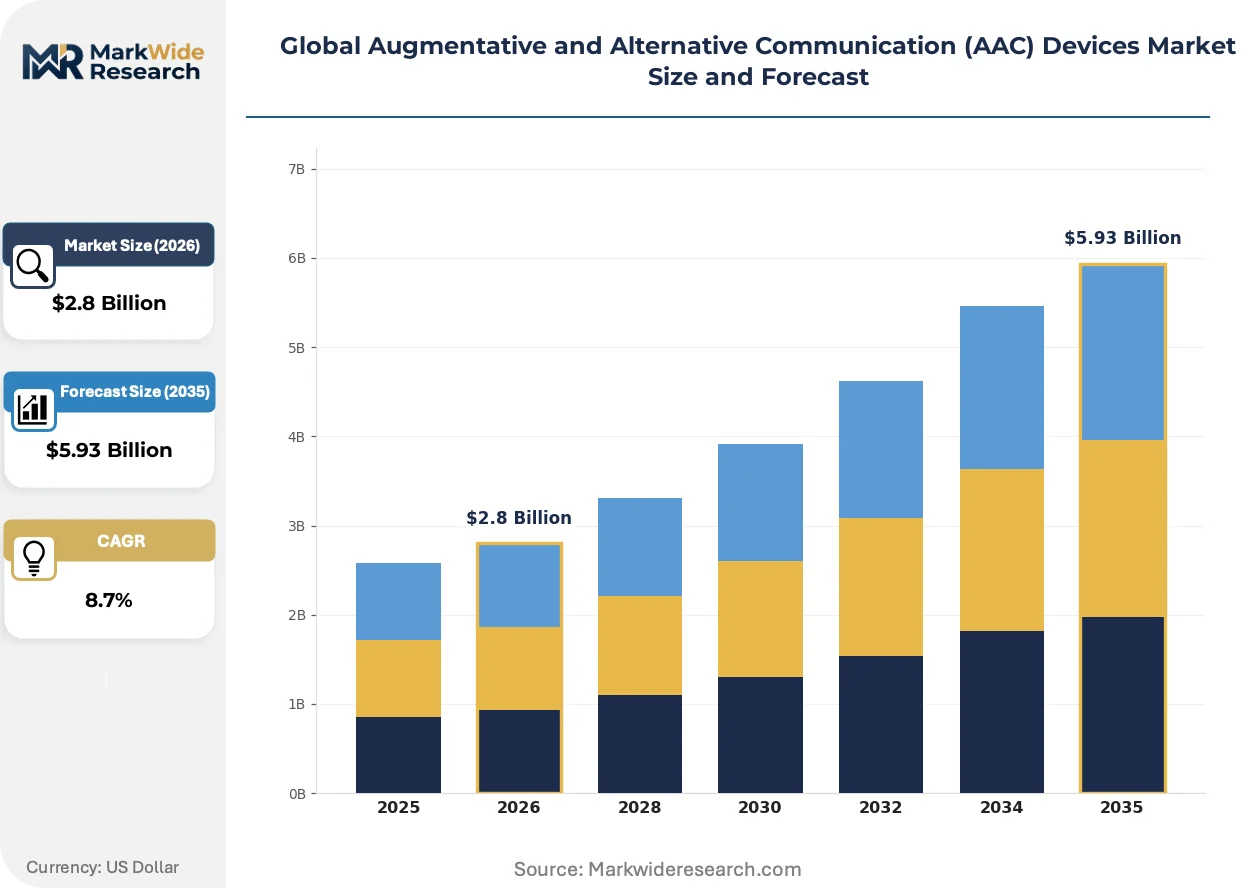
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
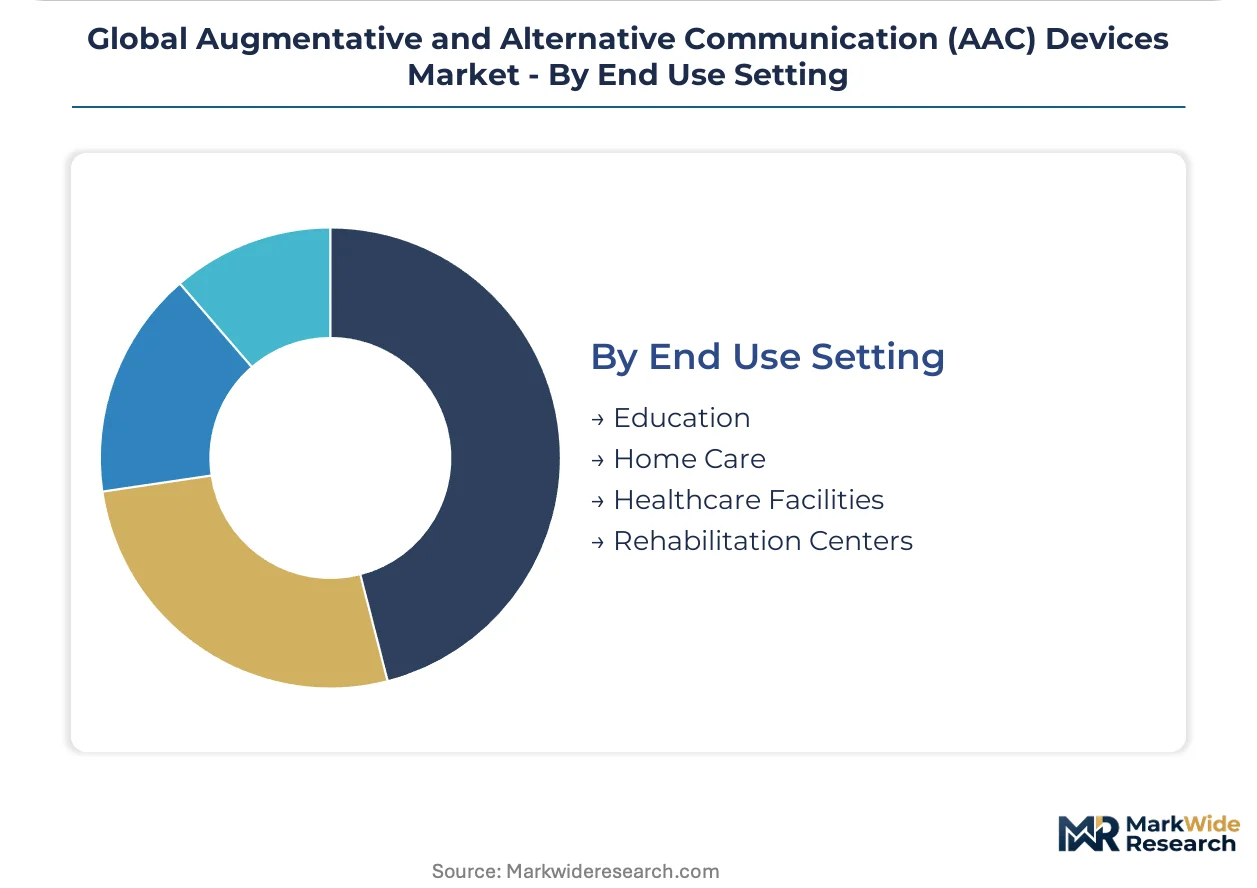
| Segmentation | Device Type: Speech Generating Devices, Communication Boards, Software Applications, Gesture-Based Systems User Group: Individuals with ALS, Individuals with Cerebral Palsy, Stroke Survivors, Non-Verbal Children Technology: Eye Tracking, Touch Screen, Switch Access, Voice Recognition End Use Setting: Education, Home Care, Healthcare Facilities, Rehabilitation Centers |
| Companies Covered | Saltillo Corporation, Smartbox Assistive Technology, Tobii Dynavox, Forbes AAC, Jabbla, PRC-Saltillo, Lingraphica, Control Bionics, Prentke Romich Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Augmentative and Alternative Communication (AAC) Devices Market Emerging Trajectories
Neural signal processing and ambient computing are dissolving the boundary between dedicated medical hardware and consumer electronics, redefining competitive moats around data interoperability rather than physical device specifications.
Embedded fNIRS sensors are expanding into wearable AAC form factors, enabling cortical blood-flow monitoring that predicts communicative intent before motor execution. German neurorehabilitation centers are piloting these systems for locked-in syndrome patients. The technology is expanding into home-care settings previously reserved for clinical-grade equipment, collapsing the distinction between inpatient and outpatient device categories.
EU Medical Device Regulation's software classification rules are reclassifying tablet-native communication aids as Class IIa medical devices, triggering notified body conformity assessments that add 12-18 months to European market entry. Speech-generating device manufacturers with existing MDR certifications are capturing shelf space while competitors await technical documentation review. Pediatric-focused platforms face particular scrutiny where symbol-based interfaces require usability validation under EN 62366 standards.
Direct-to-consumer distribution channels are circumventing traditional clinician-gatekeeper models in Australia's NDIS-funded ecosystem. Participants now configure devices through manufacturer-hosted virtual assessment platforms, displacing third-party assistive technology suppliers. This behavioral shift concentrates in metropolitan Sydney and Melbourne, where digital literacy among disability support coordinators enables self-service procurement workflows that bypass historical referral pathways.
Global Augmentative and Alternative Communication (AAC) Devices Market Segmentation

Device configuration and access-method selection dictate procurement cycles across AAC market segments. Upgrade patterns vary sharply by user pathology and reimbursement pathway, creating distinct replacement rhythms within each category.
Device Type:
Replacement cycles compress where software-native platforms displace dedicated hardware, while capital-intensive systems face extended amortization periods in institutional settings.
- Speech Generating Devices:Dedicated hardware units with synthesized voice output and customizable symbol grids. Medicare and Medicaid reimbursement codes in the US specifically cover SGD hardware, anchoring procurement in clinical and educational settings where dedicated equipment justifies premium pricing.
- Software Applications:Tablet-native platforms delivering AAC functionality through app-based interfaces. Australia's NDIS participant-directed funding accelerates upgrade cycles as end-users bypass institutional procurement gatekeepers to select premium software tiers.
- Communication Boards:Static or dynamic symbol-based displays without electronic voice synthesis. Demand concentrates in early intervention programs and resource-constrained settings where low-cost introduction to AAC concepts precedes technology adoption.
- Gesture-Based Systems:Motion-sensing interfaces capturing gross motor movements for selection control. Pediatric rehabilitation centers deploy these where motor-planning limitations preclude fine motor precision required for touch or eye-tracking access.
Volume placements concentrate in Speech Generating Devices; the faster expansion belongs to Software Applications.
User Group:
Pathology-specific disease progression rates determine device sophistication requirements and replacement urgency across user categories.
- Individuals with ALS:Rapidly degenerating motor function demands swift escalation from touch-based to eye-tracking to neural interfaces. FDA breakthrough device designation for neurodegenerative aids compresses regulatory timelines, accelerating access to emerging technologies.
- Non-Verbal Children:Developmental timelines require scalable systems that evolve from simple symbol-based boards to complex generative language platforms. German pediatric speech therapy clinic consolidation creates centralized procurement nodes for high-volume system deployment.
- Individuals with Cerebral Palsy:Stable but heterogeneous motor presentations necessitate multi-modal access methods with switch, touch, and eye-tracking flexibility. Assessment protocols now mandate parallel evaluation of gesture-based alternatives where motor planning variability complicates access method selection.
- Stroke Survivors:Recovery trajectories create temporary AAC needs that may resolve or persist, driving rental and short-term procurement models. Rehabilitation centers balance capital investment against uncertain long-term utilization rates.
Device complexity escalates fastest among Individuals with ALS; Non-Verbal Children generate the largest absolute placement volumes.
Technology:
Response latency specifications and calibration complexity differentiate access technologies, with clinical performance thresholds forcing hardware architecture reconfiguration.
- Eye Tracking:Infrared-based gaze detection with sub-300-millisecond response latencies. Tobii Dynavox leverages captive sensor production to insulate margins from semiconductor volatility while meeting clinical performance specifications.
- Touch Screen:Capacitive interfaces requiring fine motor precision for target acquisition. Tablet-native software platforms exploit consumer electronics supply chains to circumvent capital equipment procurement cycles.
- Switch Access:Mechanical or proximity-activated single or multiple switches for scanning-based selection. Legacy institutional investments in switch arrays resist full replacement, forcing hybrid compatibility engineering that extends development cycles.
- Voice Recognition:Speech-to-text and command interpretation for users with intelligible but limited verbal output. Ambient computing integration is dissolving boundaries between dedicated medical hardware and consumer electronics.
Switch Access retains the largest installed base; Eye Tracking climbs the fastest as neurodegenerative applications expand.
End Use Setting:
Reimbursement pathway and procurement authority structure vary sharply across care environments, shaping device selection criteria and pricing tolerance.
- Home Care:Participant-directed funding models in Australia's NDIS empower end-user device selection without institutional gatekeeper approval. Direct-to-consumer distribution channels now enable virtual assessment and self-service procurement in metropolitan Sydney and Melbourne.
- Education:School-district procurement cycles and individualized education plan mandates drive volume placements with extended replacement timelines. Symbol-based interface requirements face particular scrutiny under EN 62366 usability validation standards.
- Healthcare Facilities:Hospital and acute care settings prioritize rapid deployment and infection control over long-term customization. Cloud-based vocabulary synchronization enables real-time lexicon updates across institutional device fleets.
- Rehabilitation Centers:Motor-planning assessment protocols mandate multi-modal access method evaluation, driving parallel system procurement. German neurorehabilitation centers pilot embedded fNIRS sensors for locked-in syndrome patients, collapsing distinctions between inpatient and home-care device categories.
Education generates the largest placement volumes; Home Care is gaining share fastest as participant-directed funding models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundries in Taiwan and South Korea supply the specialized image-processing chips that anchor eye-tracking sensor production for AAC device manufacturers worldwide.
United States
Medicare and Medicaid reimbursement codes specifically cover dedicated speech generating device hardware, anchoring procurement in clinical and educational settings. FDA breakthrough device designation for neurodegenerative communication aids compresses regulatory timelines from 18 months to under 10 months. Saltillo Corporation and Lingraphica maintain dedicated clinician-facing sales channels across North American distribution networks.
Germany
Pediatric speech therapy clinics are scaling procurement of eye-tracking-enabled AAC systems as regional clinic consolidation creates centralized procurement nodes. EU Medical Device Regulation mandates notified body conformity assessment for software-driven communication aids sold in member states. Baden-Württemberg and Bavaria host neurorehabilitation centers piloting embedded fNIRS sensors for locked-in syndrome patients.
Australia
National Disability Insurance Scheme participant-directed funding models empower end-users to select premium-tier devices without institutional gatekeeper approval. Direct-to-consumer distribution channels enable virtual assessment and self-service procurement in metropolitan Sydney and Melbourne. TGA classification rules apply to software-driven communication aids entering the market.
Japan
PMDA pharmaceutical and medical device classification rules delay market entry for non-Japanese manufacturers lacking domestic clinical data. Requirements for domestic Japanese clinical data extend timelines by 24-36 months for manufacturers without local trial infrastructure. Tokyo and Osaka medical centers drive demand for advanced neurodegenerative communication aids.
United Kingdom
National Health Service procurement frameworks influence device selection criteria across England, Scotland, and Wales. Post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment requirements for manufacturers. London and Southeast England concentrate assistive technology assessment centers and specialist rehabilitation facilities.
Global Augmentative and Alternative Communication (AAC) Devices Market Vendor Landscape
Global majors compete with regional champions across distribution channel architecture and regulatory certification depth. The vendor base separates into three tiers: eye-tracking sensor specialists with captive production, software-native platform developers leveraging consumer electronics supply chains, and legacy hardware manufacturers defending institutional installed bases. Strategic moves concentrate on M&A for regulatory certification portfolios and geographic expansion through direct-to-consumer channels.
Within the eye-tracking specialist tier, Tobii Dynavox leverages captive sensor production to insulate margins from semiconductor volatility. Saltillo Corporation anchors North American distribution through dedicated clinician-facing sales channels. Smartbox Assistive Technology occupies a position in Europe with modular hardware architectures that simplify field servicing. These three exemplify how competitive positioning depends on supply chain control, regulatory certification breadth, and service network density rather than product specifications alone.
| Leading Market Players |
|---|
| Saltillo Corporation |
| Smartbox Assistive Technology |
| Tobii Dynavox |
| Forbes AAC |
| Jabbla |
| PRC-Saltillo |
| Lingraphica |
| Control Bionics |
| Prentke Romich Company |
| Others |
Supply Flow & Price Mechanics
Australia's NDIS participant-directed funding concentrates purchasing power among individual end-users rather than institutional procurement committees, anchoring premium-tier pricing for eye-tracking-enabled systems while compressing margins on entry-level switch-access hardware.
Pricing Analysis
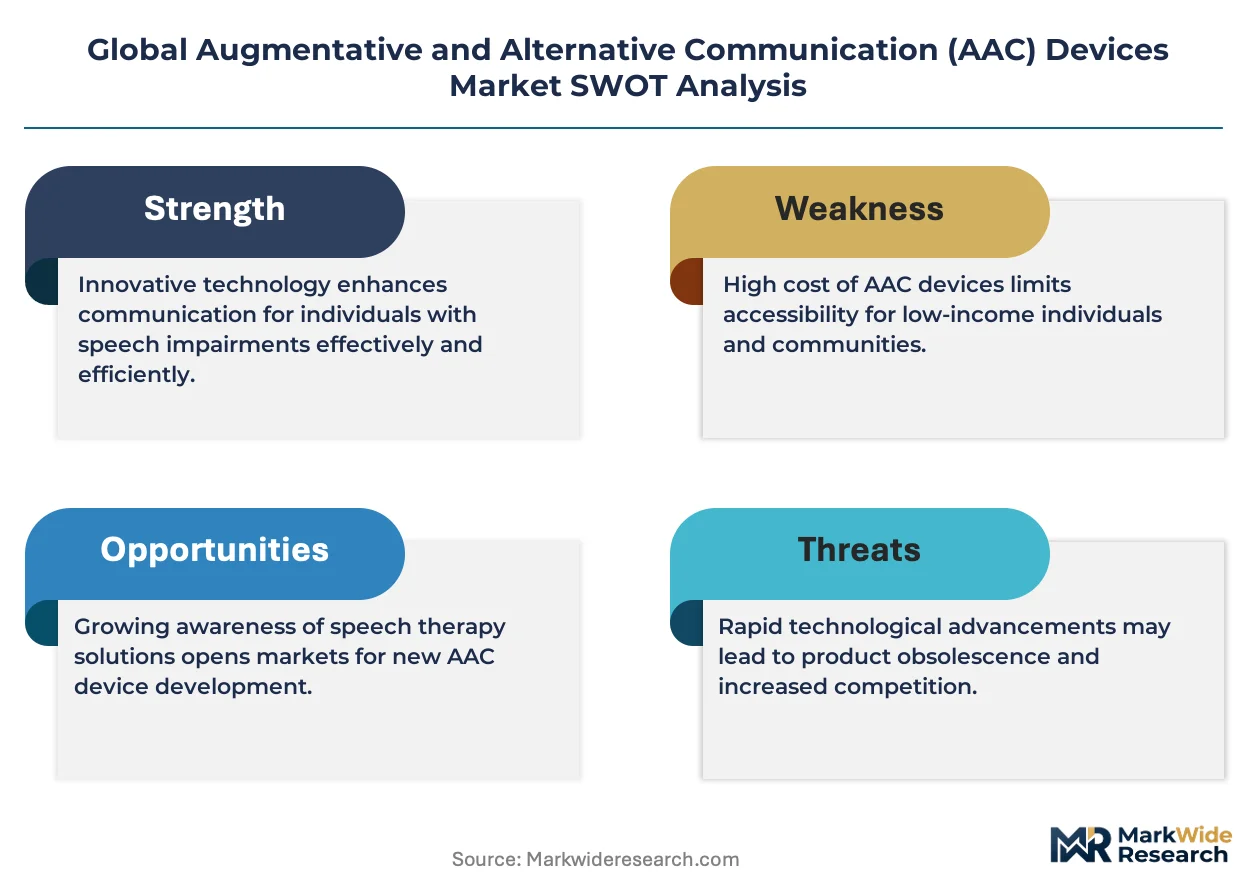
Warranty and field-service bundling separates premium AAC device tiers from unbundled software-only platforms. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough device designation status, eye-tracking sensor integration depth, and calibration support inclusion. Cost compression in tablet-native software tiers is intensifying because NDIS participants bypass traditional assistive technology supplier markups through direct-to-consumer channels. Pediatric rehabilitation centers exhibit highest price sensitivity due to municipal budget constraints, while neurodegenerative care settings tolerate premium pricing for sub-300-millisecond latency specifications.
Supply Chain Analysis
EU MDR and FDA 510(k) certification requirements gate market entry for component suppliers, concentrating qualified sensor vendors in Sweden, Taiwan, and the United States. Specialized infrared image-processing chips, medical-grade capacitive touch controllers, and fNIRS sensor modules feed from semiconductor foundries in Taiwan and South Korea. Single-source vulnerability for eye-tracking sensor ASICs exposes manufacturers to foundry allocation volatility in East Asian fabrication networks. Distribution runs through clinician-facing sales channels in North America, direct-to-consumer virtual assessment platforms in Australia, and regional clinic chains in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized image-processing chip fabrication capacity constraints prop pricing power for manufacturers with captive sensor production or long-term foundry agreements.
For Market Incumbents: Deepen backward integration into eye-tracking sensor production to insulate margins from semiconductor allocation volatility. Expand MDR certification portfolios to capture shelf space during competitor technical documentation review delays. Prioritize cloud-based vocabulary synchronization development to anchor subscription revenue models against tablet-native software platform displacement. For New Entrants and Emerging Players: Enter via direct-to-consumer virtual assessment platforms in Australia's NDIS-funded metropolitan markets where participant-directed funding bypasses institutional gatekeepers. Target German pediatric speech therapy clinic consolidation nodes for high-volume eye-tracking system deployment. Pursue FDA breakthrough device designation pathway to compress regulatory timelines against established competitor head starts. For Investors and Strategic Acquirers: The window for entry favors software-native platform developers with tablet-native architectures and NDIS distribution relationships. Long-term viability hinges on data interoperability moats rather than physical device specifications. Watch for WHO assistive technology priority list inclusion triggering pooled procurement standardization across Sub-Saharan African ministries as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Eye-Tracking Sensor Backward Integration | Captive production insulates Tobii Dynavox margins from Taiwan foundry allocation volatility. |
| Cloud Vocabulary Synchronization Platform | Real-time lexicon updates enable subscription revenue displacement of capital equipment sales. |
| MDR Certification Portfolio Expansion | Existing CE marking accelerates European market entry while competitors await notified body review. |
| Direct-to-Consumer Virtual Assessment | NDIS self-service procurement workflows in Sydney and Melbourne displace third-party suppliers. |
| FDA Breakthrough Device Pathway | Expedited premarket review compresses neurodegenerative aid timelines from 18 months to under 10 months. |
Methodological Framework
Document review covered FDA 510(k) filings, EU MDR technical documentation, and NDIS procurement databases, complemented by interviews with speech-language pathologists, biomedical engineers, hospital purchasing committee members, and assistive technology supplier executives. Secondary validation drew from CMS Medicare reimbursement code updates, TGA classification registers, and PMDA pharmaceutical and medical device submission records. Bottom-up demand modeling triangulated against top-down market sizing across device type, user pathology, access technology, and end-use setting dimensions.
Unit shipment and revenue projections across the analysis window applied patient population prevalence data, replacement cycle assumptions by pathology progression rate, and reimbursement pathway penetration by geography. Segmentation modeling incorporated device configuration, access method selection, and procurement authority structure variations. CAGRs derived from regression analysis of historical placement volumes against funding program expansion trajectories and regulatory approval timeline compression effects.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption scenarios or reimbursement code fragmentation shifts. Projections reflect assumptions regarding NDIS participant growth, FDA breakthrough designation pathway utilization rates, and EU MDR software classification enforcement consistency. A model refresh is warranted upon material change in WHO assistive technology priority list inclusion status or major foundry capacity allocation policy revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Arthroscopy Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Dosing Units Market
Medical Devices
Laser Resurfacing Market
Medical Devices
Airway Management Devices Market
Medical Devices
Veterinary Ultrasound Devices Market
Medical Devices
Hemoconcentrators Market
Medical Devices
Global Metal Implants and Medical Alloys Market
Medical Devices
Global Kidney Stone Retrieval Devices Market
Medical Devices
Supraglottic Device Market
Medical Devices
Coated Endotracheal Tube Market
Medical Devices
Europe Surgical Microscopes Market
Medical Devices
United States Implantable Medical Devices Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market