
 Radial Head Resection Implant Market | 2026-2036
Radial Head Resection Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Radial Head Resection Implant Market Insights
Implant maintenance and revision service contracts is hardening as a distinct revenue layer in orthopedic device portfolios. Stryker Corporation leverages its trauma platform breadth to anchor hospital system purchasing decisions. Zimmer Biomet Holdings, Inc. differentiates through specialized elbow reconstruction portfolios that sustain premium positioning. Arthrex, Inc. competes on suture anchor and fixation adjacencies that extend radial head procedure pull-through.
Radial head resection implants are orthopedic devices replacing the proximal radius following fracture, degenerative failure, or tumor resection, typically manufactured from titanium alloy or cobalt-chrome per ISO 5832 specifications to restore forearm rotation and axial stability. Metal implants dominate current volume owing to established biomechanical track records and surgeon familiarity, while PEEK-based polymer variants represent the fastest-expanding material class as modulus-matching reduces stress shielding complications. Among applications, trauma surgery occupies the largest implant placement volume, though revision surgery commands superior per-procedure economics due to operative complexity and specialized component requirements.
FDA 510(k) premarket notification requirements govern US commercialization pathways, while the EU Medical Device Regulation mandates notified body conformity assessment for CE-marked radial head systems in Europe. Japan's PMDA enforces QMS Ministerial Ordinance standards that condition market entry on local clinical bridging studies. Stakeholders must monitor evolving biocompatibility testing protocols and track which material platforms receive priority regulatory qualification across target geographies.
Market Dynamics
Radial head resection implant demand pivots on the tension between cobalt-chrome biomechanical reliability and PEEK polymer modulus-matching, with ISO 5832 material qualification timelines determining which platforms secure hospital formulary placement first.
Growth Catalysts
- Trauma surgery volume concentration:Upper extremity fracture incidence in the United States, Germany, and Japan sustains high-volume implant consumption, with level-one trauma centers standardizing radial head replacement protocols for complex Mason type-IV injuries.
- EU Medical Device Regulation pathway clarity:MDR notified body designation for orthopedic implant conformity assessment has compressed CE-marking timelines for established manufacturers, accelerating European commercialization velocity.
- PEEK polymer tribology advances:Carbon-fiber-reinforced polyetheretherketone formulations now achieve wear rates comparable to metal-on-polyethylene bearings, expanding material options for younger, active patient cohorts.
Market Restraints
- Titanium alloy feedstock volatility:Sponge titanium pricing swings tied to aerospace sector demand cycles compress implant margin structures, particularly for mid-tier manufacturers lacking long-term supply agreements.
- PMDA clinical bridging requirements:Japan's QMS Ministerial Ordinance mandates local comparator studies for novel radial head designs, extending time-to-market by 18-24 months versus FDA 510(k) pathways.
- Anatomic variability constraints:Proximal radius morphological heterogeneity limits standard implant sizing efficacy, driving revision rates in female and Asian patient subpopulations where commercial sizing matrices underperform.
Strategic Opportunities
- Revision surgery service bundling:Orthopedic clinics in the United States are unbundling explant analysis, component exchange, and rehabilitation into discrete revenue streams, creating attach-rate expansion potential.
- Patient-specific instrumentation convergence:3D preoperative planning software combined with disposable cutting guides is reducing operative time and implant malposition, with academic medical centers piloting subscription-based platform access.
- German outpatient surgery migration:Ambulatory surgery center reimbursement parity for selected elbow procedures under Germany's DRG system is shifting implant volume away from inpatient settings.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization protocol updates have strained notified body capacity, delaying regulatory submissions for next-generation surface coatings.
- Elbow arthroplasty fellowship pipeline:The subspecialty training bottleneck limits surgeon proficiency in complex radial head revision techniques, constraining addressable procedure volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radial Head Resection Implant Market |
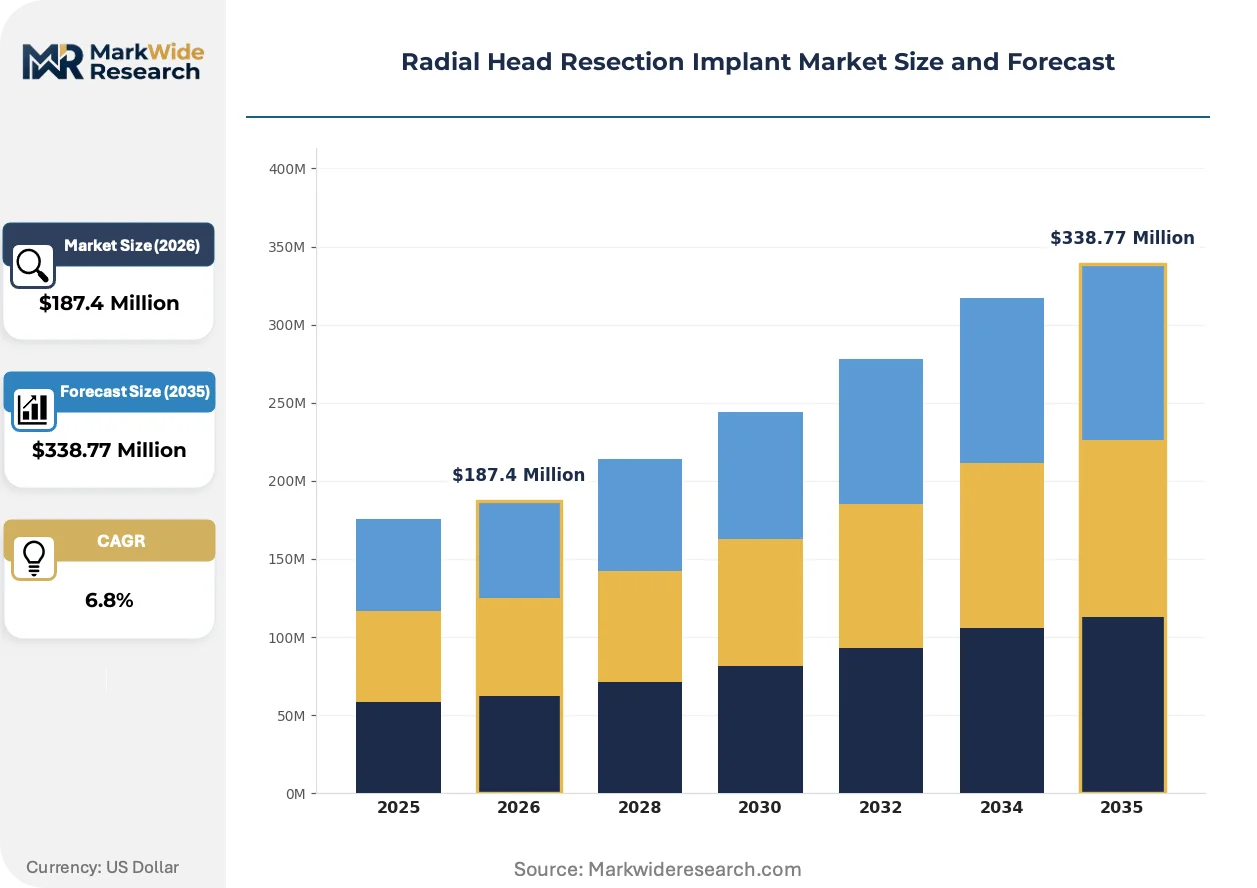
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Implants, Polymer Implants, Hybrid Implants, Biodegradable Implants End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Outpatient Surgery Centers Application: Trauma Surgery, Joint Surgery, Sports Injury, Revision Surgery Material: Stainless Steel, Titanium, PEEK, Composite Materials |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, Inc., DePuy Synthes, Smith & Nephew plc, Arthrex, Inc., Acumed LLC, Wright Medical Group N.V., Exactech, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radial Head Resection Implant Market Trends and Innovations
Radial head implant development is converging on material science breakthroughs and digital surgical planning, with regulatory science and procurement economics determining which innovations achieve commercial scale.
Modulus-matched PEEK radial head designs are decentralizing stress shielding risk away from the proximal radius metaphysis. Academic orthopedic departments in the United States and Germany are adopting these polymer systems for patients under fifty-five years of age. This material transition is decentralizing competitive advantage from legacy metal-forging expertise toward polymer processing and sterilization validation capabilities.
Japan's PMDA has tightened post-market surveillance requirements for permanent joint replacement devices under revised Ministerial Ordinance standards. Manufacturers must now submit annual safety reports and device-tracking data, increasing compliance overhead. Small-cap implant specialists without established Japanese regulatory affairs infrastructure are ceding market access to multinational trauma portfolios with dedicated Tokyo compliance teams.
Hospital procurement committees are consolidating radial head implant purchasing into system-wide orthopedic contracts, displacing individual surgeon preference contracting. Integrated delivery networks in the United States are standardizing on two-vendor trauma platforms, with radial head components included as line-item extensions. This concentration is most visible in the Southeast and Midwest regions, where Catholic health systems and for-profit chains have completed multi-hospital orthopedic service line integration.
Radial Head Resection Implant Market Segmentation
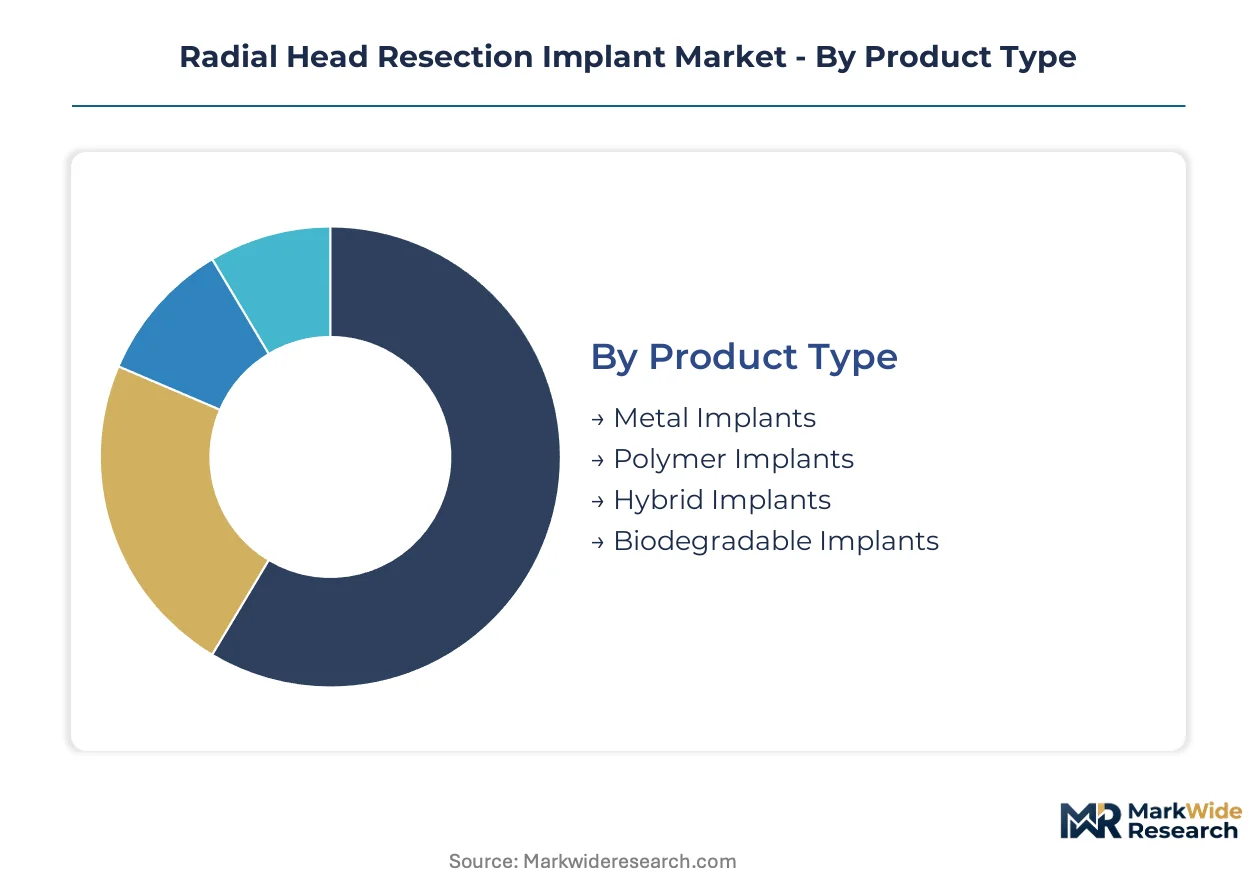
Radial head resection implant procurement stratifies across material platforms, surgical settings, and clinical indications. Hospital formulary committees weight biomechanical performance against sterilization logistics when segmenting vendor portfolios. Each category reveals distinct margin structures and regulatory qualification burdens that shape competitive positioning.
Product Type:
Manufacturing capacity clusters around forged metal platforms with established ISO 5832 supply chains, while polymer processing investments determine second-tier competitive entry.
- Metal Implants:Cobalt-chrome and titanium alloy constructs dominate current hospital purchasing, with level-one trauma centers in the United States and Germany standardizing these systems for Mason type-IV fracture protocols. Stryker and Zimmer Biomet anchor procurement contracts through trauma platform breadth.
- Polymer Implants:Carbon-fiber-reinforced PEEK formulations achieve modulus-matching that reduces proximal radius stress shielding. Academic medical centers in Germany and Japan are piloting these systems for patients under fifty-five years of age where long-term implant survival matters most.
- Hybrid Implants:Metal-polymer composite architectures combine cobalt-chrome articulating surfaces with PEEK stems for optimized tribology.
- Biodegradable Implants:Magnesium alloy and polylactic acid systems remain investigational, with limited commercial availability outside European orthopedic research consortia.
Metal implants absorb the bulk of installed capacity; polymer implants are expanding most quickly.
End User:
Site-of-care economics drive divergent pricing tolerances, with inpatient reimbursement rates sustaining premium component placement.
- Hospitals:Academic medical centers and community hospitals perform complex radial head revisions requiring specialized instrumentation sets and extended operative time. These institutions negotiate system-wide orthopedic contracts that bundle radial head components with trauma and arthroplasty platforms.
- Orthopedic Clinics:Specialized upper extremity practices generate high procedure volumes with standardized protocols. Clinics in the United States are unbundling explant analysis and component exchange into discrete revenue streams.
- Rehabilitation Centers:Post-operative rehabilitation facilities coordinate with implanting surgeons on range-of-motion protocols but do not directly procure devices.
- Outpatient Surgery Centers:Ambulatory settings in Germany are gaining DRG reimbursement parity for selected elbow procedures, shifting low-complexity trauma volume away from inpatient facilities.
Hospitals retain the dominant share of high-acuity procedures; outpatient surgery centers are climbing the fastest as reimbursement migrates.
Application:
Clinical indication determines component complexity and per-procedure economics, with revision cases commanding specialized explant instruments and custom sizing.
- Trauma Surgery:Acute fracture management represents the highest-volume indication, with radial head replacement standardizing for comminuted injuries unsuitable for internal fixation. United States trauma centers drive consumption through standardized Mason classification protocols.
- Revision Surgery:Component exchange procedures require explant analysis, bone loss management, and often custom-sized implants. These cases generate superior economics due to operative complexity and specialized instrument requirements.
- Joint Surgery:Degenerative elbow arthritis with radial head involvement drives elective replacement volume in aging patient cohorts.
- Sports Injury:Athletic trauma generates demand for rapid return-to-sport protocols, particularly in professional and collegiate settings.
Trauma surgery absorbs the bulk of installed capacity; revision surgery commands the steepest expansion trajectory in revenue per procedure.
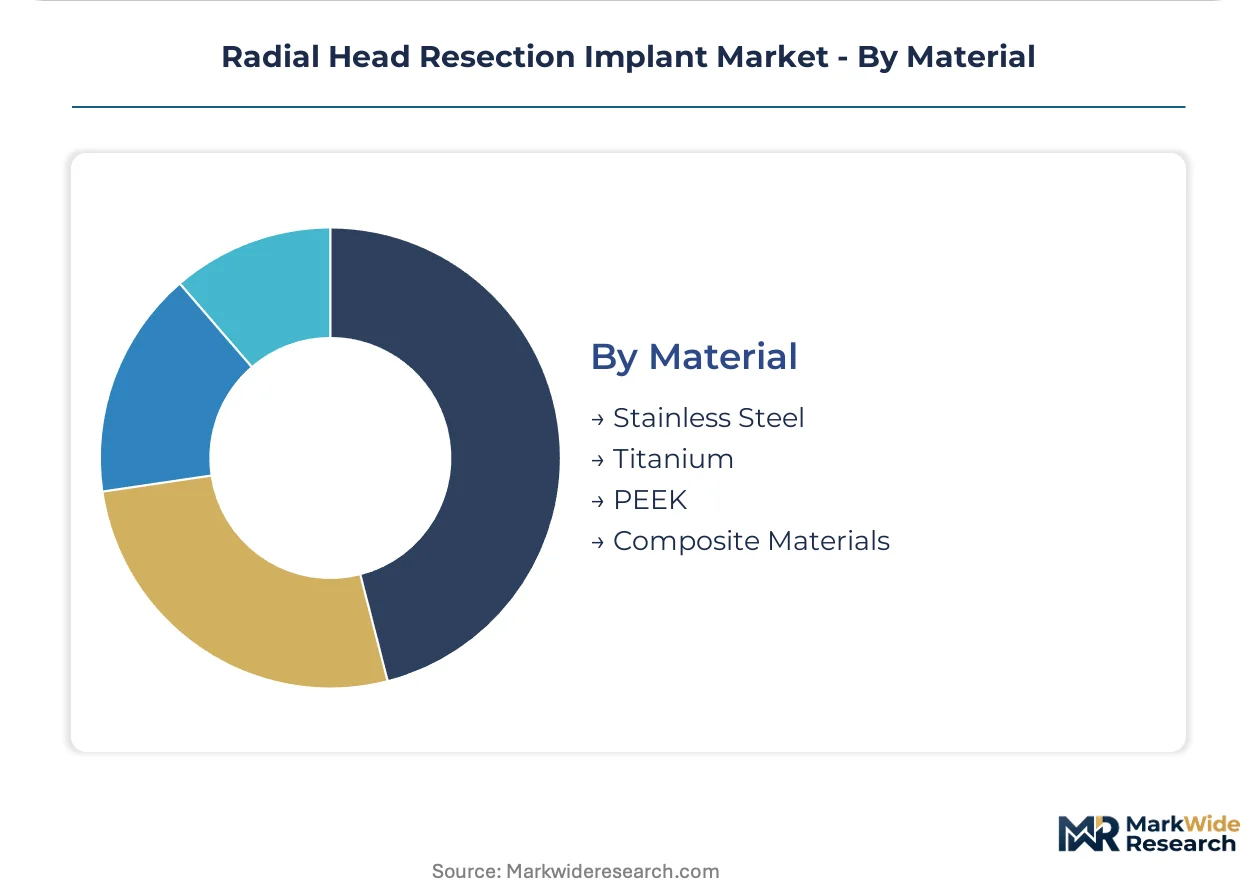
Material:
Feedstock qualification timelines and biocompatibility testing backlogs determine which material platforms secure regulatory clearance first.
- Titanium:Ti-6Al-4V ELI alloy per ISO 5832-3 specifications provides established osseointegration profiles and fatigue resistance. Aerospace sector demand cycles create sponge titanium pricing volatility that compresses margin structures for manufacturers lacking long-term supply agreements.
- PEEK:Polyetheretherketone with carbon fiber reinforcement achieves elastic modulus matching native bone, reducing stress shielding complications. Japan's PMDA and the FDA are prioritizing biocompatibility protocol updates for polymer bearing surfaces.
- Stainless Steel:316LVM grade retains niche usage in cost-sensitive markets and temporary spacer applications.
- Composite Materials:Ceramic-polymer and metal-matrix composites remain developmental, with limited commercial scale due to sterilization validation challenges.
Titanium absorbs the bulk of installed capacity; PEEK is gaining share fastest among younger patient cohorts seeking long-term implant survival.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Memphis anchors North American orthopedic implant distribution through FedEx logistics infrastructure that connects trauma centers across the continental United States. This hub-and-spoke configuration shapes how radial head resection implants reach surgical facilities.
United States
Level-one trauma centers in Baltimore and Houston drive standardized Mason type-IV fracture protocols that embed radial head replacement into emergency orthopedic workflows. FDA 510(k) premarket notification pathways compress clearance timelines for established manufacturers versus novel entrants. The Southeast corridor from Atlanta to Charlotte concentrates Catholic health system purchasing consolidation that bundles radial head components into multi-hospital orthopedic contracts.
Germany
Ambulatory surgery centers in Bavaria and North Rhine-Westphalia exploit DRG reimbursement parity for selected elbow procedures, shifting low-complexity trauma volume from inpatient facilities. EU Medical Device Regulation notified body designation for orthopedic conformity assessment has compressed CE-marking timelines for trauma portfolios. The Munich-Stuttgart industrial corridor hosts precision forging operations that supply cobalt-chrome implant blanks to European device assemblers.
Japan
Academic medical centers in Tokyo and Osaka pilot carbon-fiber-reinforced PEEK radial head systems for patients under fifty-five years where long-term implant survival dominates selection criteria. PMDA QMS Ministerial Ordinance mandates local comparator studies that extend time-to-market by eighteen to twenty-four months versus FDA pathways. The Kobe-Osaka medical device cluster concentrates sterilization validation capabilities for polymer bearing surfaces.
United Kingdom
NHS England specialized commissioning frameworks concentrate complex radial head revision procedures into designated tertiary centers in London and Manchester. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining UKCA marking for trauma implants. The Cambridge-Oxford arc hosts computational biomechanics research that informs patient-specific instrumentation development.
Australia
TGA priority review pathways for novel orthopedic materials accelerate market entry for modulus-matched polymer systems in Sydney and Melbourne teaching hospitals. Commonwealth funding for aged care orthopedic services expands elective radial head replacement volume in degenerative arthritis cohorts. The Melbourne biomedical precinct concentrates preclinical testing facilities that validate biocompatibility per ISO 10993 protocols.
Radial Head Resection Implant Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the radial head implant sector. Integrated trauma platform vendors anchor hospital system purchasing through breadth of orthopedic portfolios, while specialized elbow reconstruction firms sustain premium positioning through focused surgical technique adjacencies. Three archetypes dominate: multinational trauma conglomerates with full extremity portfolios, mid-cap upper extremity specialists, and polymer processing innovators. Competitive moves concentrate on M&A to secure CE-marked product lines and strategic partnerships to access Japanese regulatory infrastructure.
Within the multinational trauma tier, Stryker Corporation and Zimmer Biomet Holdings, Inc. occupy positions that exemplify platform breadth advantages in US hospital contract consolidation. Among specialized elbow reconstruction firms, Arthrex, Inc. represents the archetype of suture anchor and fixation adjacency strategies that extend radial head procedure pull-through. These three companies anchor the competitive structure that shapes procurement committee vendor selection across level-one trauma centers in the United States and Germany.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| DePuy Synthes |
| Smith & Nephew plc |
| Arthrex, Inc. |
| Acumed LLC |
| Wright Medical Group N.V. |
| Exactech |
| Medtronic plc |
| Others |
Pricing and Supply Chain Analysis
EU MDR biocompatibility testing mandates gate qualified supply access for radial head implant manufacturers, with ISO 10993 cytotoxicity protocol compliance separating premium-tier vendors from price-competitive alternatives in hospital formulary negotiations. These environmental and safety standards feed directly into sterilization validation costs that shape margin structures across cobalt-chrome and PEEK material platforms.
Pricing Analysis
Outcome-linked pricing anchors radial head implant procurement contracts, with revision surgery success rates and implant survival metrics determining value-based reimbursement tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by material certification grade and trauma platform breadth, with FDA 510(k) cleared systems commanding formulary preference. Cost compression in mid-tier titanium alloy segments intensifies because aerospace sponge titanium demand cycles squeeze feedstock availability. Academic medical centers exhibit lowest price sensitivity due to research funding offsets, while ambulatory surgery centers in Germany face acute reimbursement pressure under DRG parity rules.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume trauma center demand, with specialized orthopedic distributors managing instrumentation set logistics for revision procedures. Manufacturing concentrates in the United States, Germany, and Japan, with precision forging operations in the Munich-Stuttgart corridor supplying cobalt-chrome blanks and Kobe-Osaka clusters handling PEEK polymer sterilization validation. Feedstock dependencies span sponge titanium from aerospace suppliers, carbon-fiber-reinforced PEEK resin from chemical specialists, and cobalt-chrome alloy from industrial metal processors. Single-source vulnerability in titanium sponge supply creates margin volatility for manufacturers lacking long-term offtake agreements. Distribution runs through FedEx's Memphis hub for North American trauma center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with manufacturers pursuing backward integration into titanium sponge supply to defend margin structures against aerospace sector demand cycles.
For Market Incumbents: Acquire precision forging capacity in the Munich-Stuttgart industrial corridor to secure cobalt-chrome implant blank supply against European feedstock competition. Consolidate PEEK polymer sterilization validation capabilities through captive facilities or exclusive partnerships with Kobe-Osaka medical device clusters. Polymer processing expertise represents the priority defensive asset as modulus-matched implants displace metal systems in younger patient cohorts. For New Entrants and Emerging Players: Digital surgical planning platforms offer the lowest barrier entry vector, with subscription-based 3D preoperative software penetrating academic medical centers before hardware placement. Target German ambulatory surgery centers exploiting DRG reimbursement parity for elbow procedures, where established trauma conglomerates maintain weaker formulary lock-in. White-space exists in patient-specific instrumentation for Asian patient subpopulations where commercial sizing matrices underperform. For Investors and Strategic Acquirers: PMDA QMS Ministerial Ordinance compliance infrastructure acquisition is the leading indicator that a target possesses durable Japanese market access. Five-to-ten year viability hinges on polymer bearing surface biocompatibility validation capabilities rather than legacy metal-forging assets. Watch for CE-marked radial head portfolios from mid-cap upper extremity specialists as consolidation targets, with priority signal being notified body designation for orthopedic implant conformity assessment.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery networks in the Southeast United States consolidate trauma platform purchasing into two-vendor contracts. |
| CE Marking Pathway | EU MDR notified body designation compresses clearance timelines for established manufacturers versus novel entrants. |
| Backward Integration into Titanium Supply | Captive sponge titanium offtake agreements insulate margin structures from aerospace demand cycle volatility. |
| Software Companion Development | 3D preoperative planning platforms reduce operative time and implant malposition in academic medical center pilots. |
| Reimbursement Strategy | German DRG parity for ambulatory elbow procedures shifts volume toward outpatient surgery centers. |
Research Methodology
Document review covered FDA 510(k) premarket notification filings, EU MDR technical documentation, and PMDA QMS Ministerial Ordinance submissions, complemented by interviews with orthopedic trauma surgeons, hospital purchasing committee chairs, biomedical engineers at academic medical centers, and GPO contracts managers. Secondary validation drew from hospital procurement databases, CMS Medicare reimbursement schedules, German DRG classification manuals, and ISO 10993 biocompatibility testing protocols. Bottom-up implant volume modeling triangulated against top-down trauma surgery incidence estimates.
Historical trauma center procedure volumes cross-referenced against surgeon panel input on Mason classification protocol adoption across the projection horizon. Segmentation dimensions modeled include material platform, surgical setting, clinical indication, and regional regulatory pathway complexity. CAGRs derived from elasticity-adjusted demand functions incorporating PEEK polymer tribology advancement rates and titanium feedstock price volatility assumptions. Industry-specific inputs encompassed elbow arthroplasty fellowship pipeline constraints and post-market surveillance reporting burdens.
The model holds under stable regulatory pathway timelines and consistent trauma surgery reimbursement rates; deviation in biocompatibility testing protocol updates or sponge titanium supply disruptions would shift volume and value trajectories. Periodic stress-testing of base assumptions against notified body capacity constraints and polymer sterilization validation bottlenecks is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Mucosal Atomization Devices Market
Medical Devices
Pleural Catheters Market
Medical Devices
Medical Manifolds Market
Medical Devices
North America Medical Devices Market
Medical Devices
Cervical Spine System Market
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
Oxygenator Market
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Global Ventilators Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Global Suture Anchor Devices Market
Medical Devices
Superficial Radiation Therapy System Market
Medical Devices
Pelvic Reconstruction Market