
 Cardiac Rhythm Management (CRM) Devices Batteries Market | 2026-2036
Cardiac Rhythm Management (CRM) Devices Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Rhythm Management (CRM) Devices Batteries Market Outlook
Extended-cycle lithium iodide specifications is reorganizing procurement priorities across the CRM battery supply base. Medtronic leverages captive cell manufacturing to secure chemistry consistency for its implantable portfolio. Boston Scientific Corporation anchors North American supply through vertically integrated battery assembly operations. Abbott differentiates via high-reliability cell designs purpose-built for cardiac resynchronization therapy devices.
Cardiac Rhythm Management Devices Batteries are hermetically sealed electrochemical cells, predominantly lithium iodide or lithium carbon monofluoride chemistries, engineered to deliver stable voltage output over multi-year implantation cycles while withstanding physiological corrosion and thermal variation. These power units sustain pacemakers, implantable cardioverter defibrillators, and cardiac resynchronization therapy devices where premature depletion risks patient mortality. Battery chemistry segments reveal lithium iodide occupying the mature volume position due to decades of clinical validation, while lithium carbon monofluoride gains share in high-drain defibrillator applications where energy density requirements intensify. End user concentration tilts toward hospitals, though home healthcare providers represent the fastest-expanding channel as remote monitoring capabilities extend post-implant patient management beyond traditional clinical settings.
FDA premarket approval pathways and EU MDR technical documentation requirements impose stringent validation protocols on cell longevity, hermetic integrity, and biocompatibility testing that extend development timelines and elevate barrier costs for new entrants. ISO 14708 active implantable medical device standards further constrain design flexibility by mandating predictable discharge curves and fail-safe depletion indicators. Stakeholders must monitor evolving FDA guidance on battery end-of-life notification systems and EU battery regulation sustainability mandates that will reshape material sourcing and recycling obligations.
Market Dynamics
Extended-cycle lithium iodide specifications are compressing procurement timelines across the CRM battery supply base, forcing manufacturers to prioritize chemistry consistency and captive cell production over third-party sourcing strategies.
Growth Catalysts
- Aging demographics:Japan, Germany, and the United States exhibit expanding patient populations requiring pacemaker and ICD implantation, directly elevating battery procurement volumes.
- EU MDR technical documentation:Stricter validation protocols for hermetic integrity and biocompatibility are filtering out marginal suppliers and consolidating demand among qualified manufacturers.
- Remote monitoring infrastructure:Home healthcare providers are extending post-implant patient management capabilities, creating incremental battery replacement demand outside traditional hospital channels.
Market Restraints
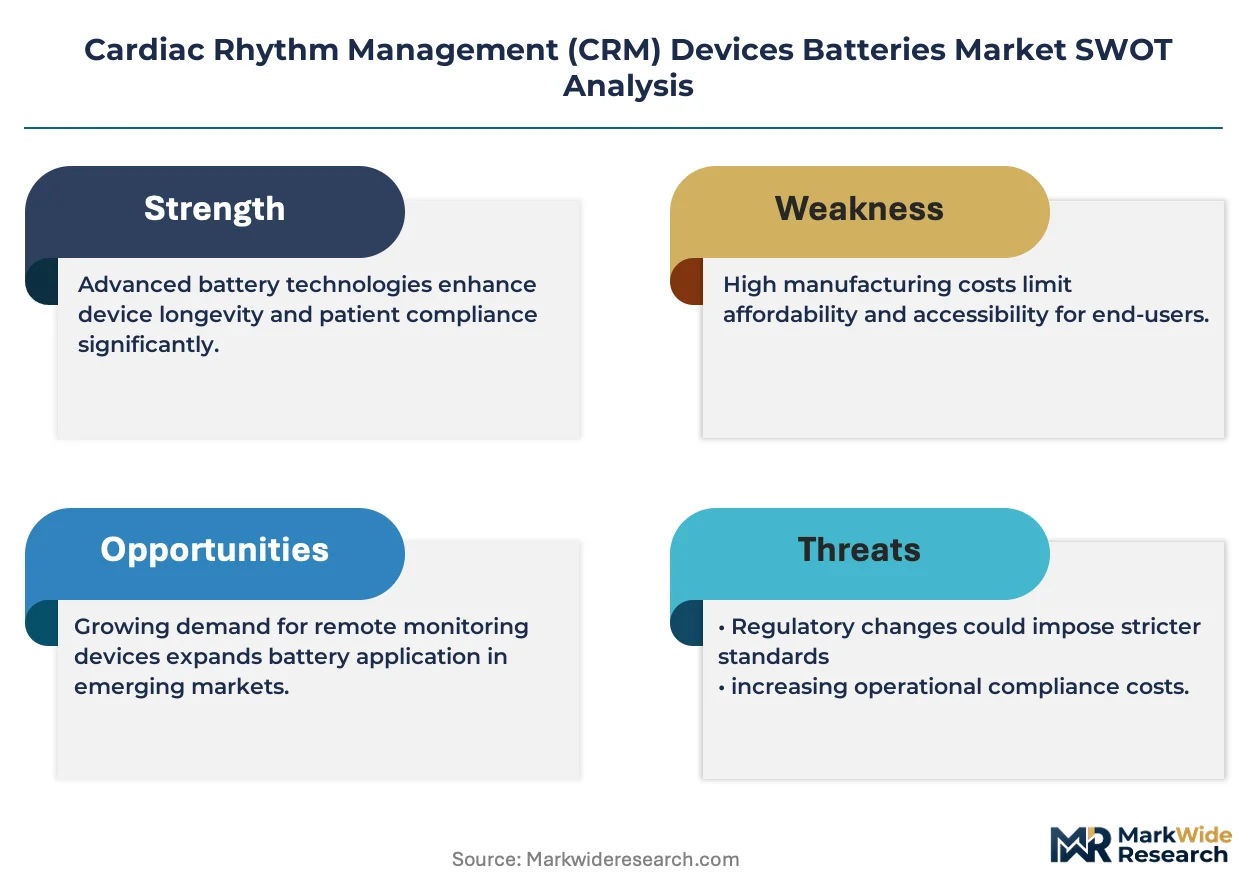
- Raw material concentration:Lithium iodide precursor supply concentrates among limited specialty chemical producers, exposing battery manufacturers to input cost volatility and allocation risk.
- FDA premarket approval timelines:Extended validation protocols for cell longevity and fail-safe depletion indicators stretch development cycles and elevate barrier costs for new entrants.
- Technical ceiling on energy density:Lithium iodide chemistry approaches theoretical limits for high-drain defibrillator applications, constraining device miniaturization trajectories.
Strategic Opportunities
- Home healthcare channel expansion:Remote monitoring capabilities enable battery procurement direct to ambulatory care settings, bypassing traditional hospital purchasing committees.
- EU battery regulation sustainability mandates:Material sourcing and recycling obligations create first-mover advantage for manufacturers establishing closed-loop lithium recovery systems.
- Cardiac resynchronization therapy convergence:Multi-chamber pacing requirements are driving demand for high-reliability cell designs with predictable discharge curves.
Industry Challenges
- Electrochemical engineering talent scarcity:Specialized expertise in hermetic sealing and physiological corrosion resistance remains concentrated among legacy implantable device manufacturers.
- ISO 14708 certification complexity:Active implantable medical device standards mandate predictable discharge curves that constrain design flexibility and extend validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Rhythm Management (CRM) Devices Batteries Market |
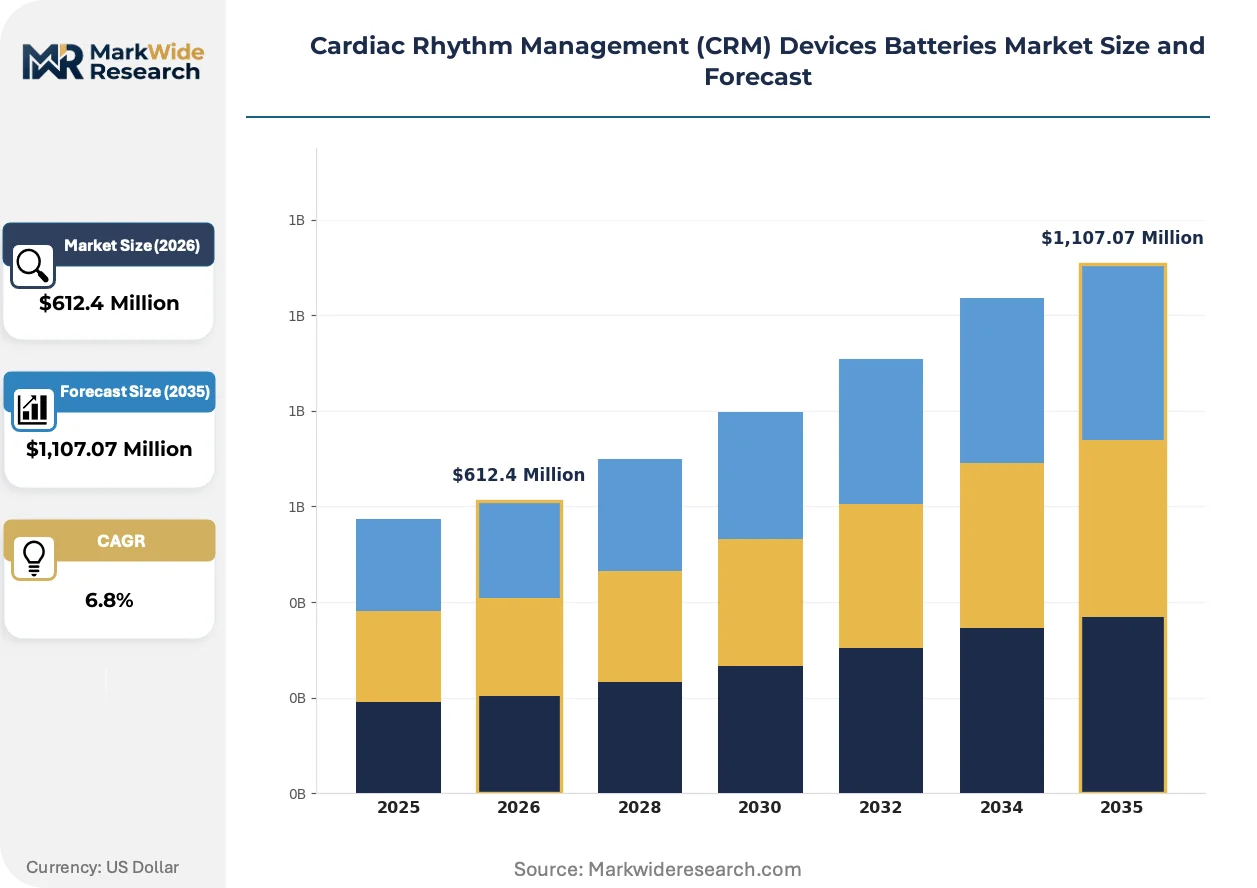
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Cardioverter Defibrillators, Pacemakers, Biventricular Pacemakers, Cardiac Resynchronization Therapy Devices Battery Chemistry: Lithium Iodide, Lithium Carbon Monofluoride, Lithium Cobalt Oxide, Lithium Iron Phosphate End User: Hospitals, Cardiology Clinics, Home Healthcare Providers, Long-Term Care Facilities Application: Arrhythmia Management, Heart Failure Treatment, Device Implantation, Remote Monitoring |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, BIOTRONIK, GE Healthcare, Philips Healthcare, St. Jude Medical, Greatbatch, EaglePicher Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Rhythm Management (CRM) Devices Batteries Market Strategic Shifts
Multiple forces are simultaneously reshaping CRM battery development priorities, from chemistry evolution to regulatory compliance architecture and procurement model transformation.
Lithium carbon monofluoride formulations are supplanting traditional lithium iodide in high-drain defibrillator applications where energy density requirements intensify. Device manufacturers are accelerating adoption of these alternative chemistries to enable smaller form factors and extended device longevity. This chemistry transition is compressing supplier qualification timelines as OEMs demand validated cell designs for next-generation ICD portfolios.
EU MDR technical documentation requirements are imposing stringent validation protocols on cell longevity and hermetic integrity testing. Manufacturers must now maintain comprehensive clinical evidence packages spanning entire device-battery system lifecycles. High-drain defibrillator segments face the steepest compliance burden, with notified body review timelines extending procurement planning horizons.
Hospital purchasing committees are fragmenting decision authority as remote monitoring capabilities shift post-implant management toward home healthcare providers. Battery procurement is increasingly bifurcating between acute care capital budgets and ambulatory care consumable streams. This channel disintermediation is most visible in Germany and Japan, where integrated care pathways accelerate patient discharge protocols.
Cardiac Rhythm Management (CRM) Devices Batteries Market Segmentation
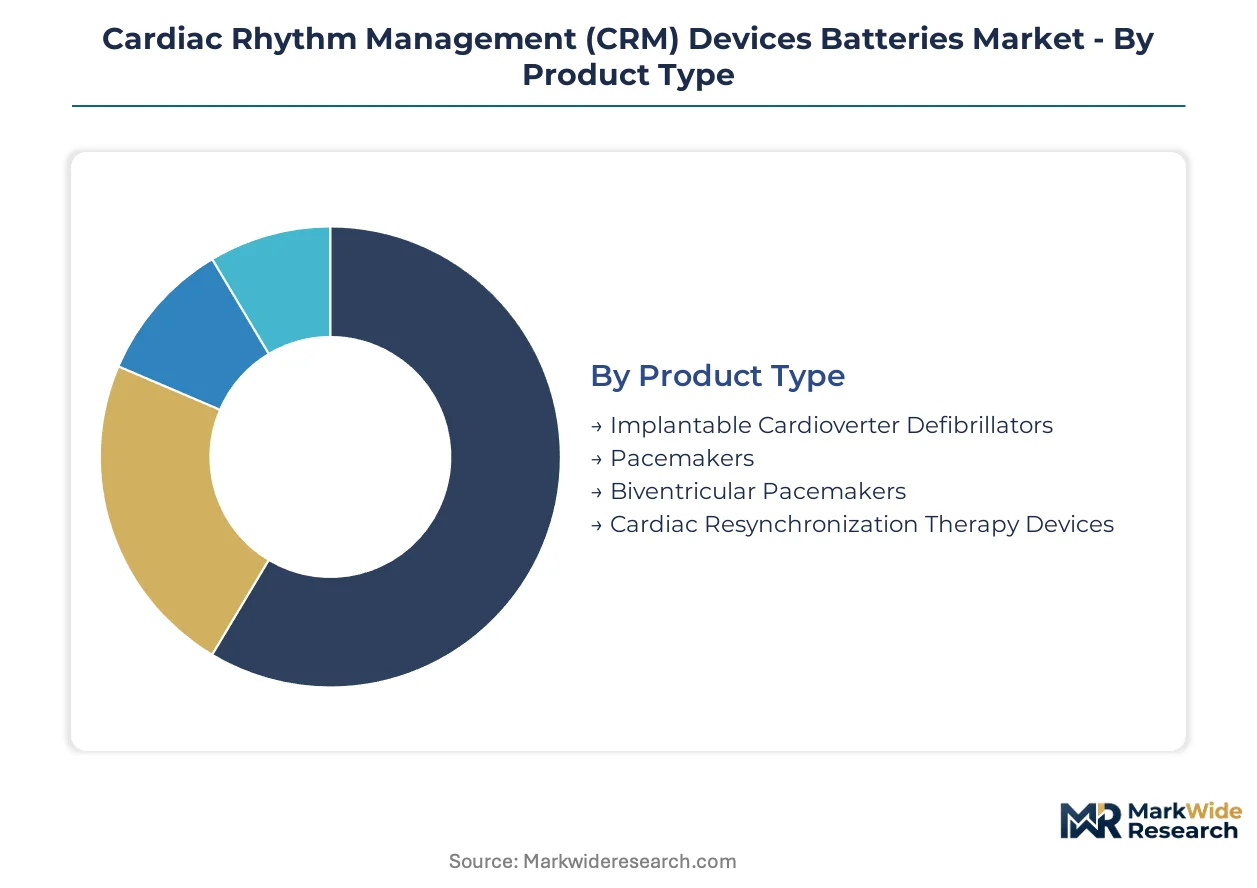
Segmentation in CRM batteries reveals how chemistry constraints and end-user channel shifts are fragmenting procurement authority. Device manufacturers must align cell specifications with both clinical application intensity and evolving care delivery settings.
Product Type:
Substitution pressure from rechargeable alternatives and leadless pacing systems is reshaping volume allocation across implantable categories.
- Implantable Cardioverter Defibrillators:High-drain devices demanding lithium carbon monofluoride cells for energy density. United States hospitals drive procurement volumes as sudden cardiac arrest prevention protocols expand.
- Pacemakers:Mature lithium iodide chemistry dominates single-chamber and dual-chamber configurations. German cardiology clinics anchor European demand through standardized bradycardia treatment pathways.
- Biventricular Pacemakers:Multi-lead configurations requiring predictable discharge curves for synchronized ventricular pacing.
- Cardiac Resynchronization Therapy Devices:Combined pacing-defibrillation functions straining battery longevity specifications.
Pacemakers anchor the volume base while Implantable Cardioverter Defibrillators gain share at the steepest rate.
Battery Chemistry:
Cost tier stratification separates validated legacy formulations from emerging high-performance alternatives facing extended qualification timelines.
- Lithium Iodide:Decades of clinical validation support predictable voltage decay profiles essential for pacemaker longevity. Japanese manufacturers favor this chemistry for its manufacturing consistency and established supply chains.
- Lithium Carbon Monofluoride:Superior energy density enables ICD miniaturization and extended replacement intervals. United States defibrillator OEMs are accelerating supplier qualification for next-generation portfolios.
- Lithium Cobalt Oxide:Higher voltage output suited for temporary external pacing applications with shorter implantation horizons.
- Lithium Iron Phosphate:Thermal stability characteristics attracting investigation for next-generation implantable designs.
Lithium Iodide commands the installed base while Lithium Carbon Monofluoride expands most quickly in high-drain segments.
End User:
Customer type diversification is fragmenting procurement authority as remote monitoring capabilities displace traditional hospital purchasing committees.
- Hospitals:Acute care settings with capital equipment budgets and committee-based vendor selection. Germany's integrated care networks concentrate implant volumes in tertiary centers with cath lab infrastructure.
- Home Healthcare Providers:Ambulatory monitoring services creating consumable battery demand outside institutional channels. United States remote patient monitoring reimbursement codes accelerate this shift.
- Cardiology Clinics:Outpatient implant centers with streamlined procurement for routine device replacements.
- Long-Term Care Facilities:Skilled nursing settings managing pacemaker-dependent patients with limited transfer capabilities.
Hospitals retain the procurement volume base while Home Healthcare Providers are climbing the fastest as monitoring infrastructure extends.
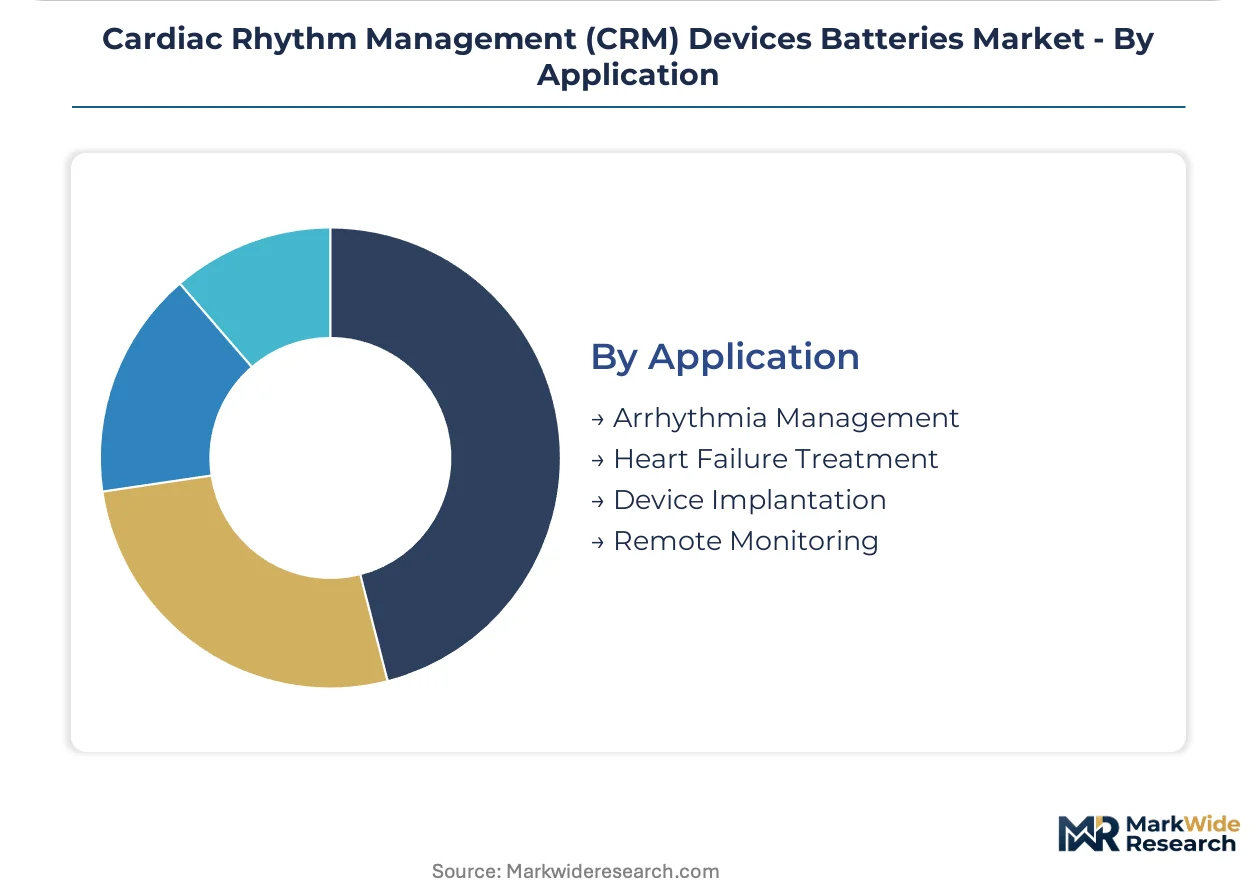
Application:
Application maturity varies sharply, with established arrhythmia protocols contrasting against emerging remote monitoring architectures still defining battery specifications.
- Arrhythmia Management:Core pacing and defibrillation functions driving baseline lithium iodide consumption. Japanese aging demographics sustain implant volumes for bradycardia and tachycardia indications.
- Remote Monitoring:Transmitter-equipped devices requiring supplemental power for wireless telemetry. United States home healthcare expansion is pulling battery demand toward ambulatory settings.
- Heart Failure Treatment:Cardiac resynchronization therapy combining multi-chamber pacing with diagnostic functions.
- Device Implantation:Surgical procedure category encompassing initial battery selection and replacement scheduling.
Arrhythmia Management anchors clinical volume while Remote Monitoring is gaining share fastest as connectivity becomes standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of lithium iodide precursors and finished CRM cells concentrate from established manufacturing clusters in the United States, Germany, and Japan toward implant centers in aging economies. Import dependency for specialty electrolyte materials creates vulnerability in supply security calculations. Regional regulatory divergence around battery sustainability mandates is fragmenting procurement compliance requirements.
United States
FDA premarket approval pathways for active implantable devices sustain demand for domestically validated cell designs with documented longevity profiles. Medicare reimbursement codes for remote patient monitoring accelerate home healthcare channel expansion beyond traditional hospital purchasing. Minneapolis and Boston medical device corridors concentrate vertically integrated battery assembly operations serving defibrillator OEMs.
Germany
EU MDR technical documentation requirements for hermetic integrity and biocompatibility filter supplier qualification toward established manufacturers with comprehensive clinical evidence packages. Germany's integrated care networks concentrate implant volumes in tertiary cath lab centers with standardized procurement protocols. Baden-Württemberg and Bavaria host precision engineering clusters supplying hermetic sealing expertise for next-generation cell designs.
Japan
PMDA consultation procedures for novel battery chemistries extend development timelines while aging demographics sustain bradycardia and tachycardia implant volumes. METI industrial policy supports domestic lithium iodide precursor production to reduce import exposure. Tokyo-Osaka medical device manufacturing belt anchors regional supply chains for pacemaker-dependent patient populations.
Switzerland
Swissmedic certification requirements for active implantable devices impose parallel validation protocols that elevate barrier costs for battery suppliers seeking market access. Precision manufacturing heritage in the Jura Arc and Zurich clusters supports high-reliability cell production for cardiac resynchronization therapy applications. Swiss purchasing committees prioritize chemistry consistency and predictable discharge curves in vendor selection criteria.
United Kingdom
MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while introducing separate conformity assessment timelines for battery-integrated devices. NHS England procurement frameworks consolidate demand among qualified suppliers with demonstrated hermetic integrity track records. London-Southeast medical technology corridor attracts cell design specialists serving European market access requirements.
Cardiac Rhythm Management (CRM) Devices Batteries Market Competitive Environment
Listed leaders compete with private specialists across chemistry validation and captive manufacturing capabilities. The supplier base consolidates around three tiers: diversified medical device conglomerates with in-house cell production, dedicated battery manufacturers serving multiple OEMs, and niche specialists focused on high-reliability formulations. Strategic archetypes include chemistry-integrated device manufacturers, independent cell suppliers, and materials-science specialists. Competitive positioning depends on backward integration into precursor supply and accelerated qualification timelines for next-generation formulations.
Among diversified medical technology conglomerates, Medtronic exemplifies the chemistry-integrated archetype through captive lithium iodide cell manufacturing. Boston Scientific Corporation and Abbott occupy positions spanning device-battery system development with differentiated reliability specifications for high-drain applications. These three companies represent the dominant competitive vector where manufacturing control over electrochemical consistency determines procurement relationships with implant centers.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| BIOTRONIK |
| GE Healthcare |
| Philips Healthcare |
| St. Jude Medical |
| Greatbatch |
| EaglePicher Technologies |
| Others |
Value Chain & Pricing Dynamics
FDA premarket approval pathways and EU MDR technical documentation requirements simultaneously gate supply qualification and enable price differentiation across chemistry tiers. Battery manufacturers must recover extended validation costs through premium positioning for hermetic-sealed lithium iodide cells, while procurement committees weigh chemistry consistency against total cost of ownership for multi-year implantation cycles.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with volume-scale and certification-grade price differentiation. Three-tier pricing separates FDA-validated premium cells from CE-marked standard formulations and economy-tier non-implantable alternatives. Pricing pressure stems from raw material concentration in lithium iodide precursors. High-volume hospital purchasing committees exhibit lowest price sensitivity due to patient-risk considerations, while ambulatory home healthcare providers face tighter consumable budgets.
Supply Chain Analysis
Strategic stockpiling of lithium iodide precursors dominates inventory strategy given limited specialty chemical producers and allocation risk exposure. Manufacturing concentrates in the United States, Germany, and Japan, drawing from Chilean lithium brine and Japanese iodine extraction. Single-source vulnerability runs through hermetic sealing equipment and specialty electrolyte formulations. Distribution runs through vertically integrated device OEMs and qualified cell suppliers serving implant centers directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates formidable defensive moats in this market, as FDA and EU MDR validation timelines extend to multiple years and clinical evidence requirements concentrate procurement among qualified suppliers with established longevity track records.
For Market Incumbents: Secure captive lithium iodide precursor supply through backward integration or long-term offtake agreements to defend against raw material allocation risk. Deepen hermetic sealing capabilities in Baden-Württemberg precision engineering clusters to maintain chemistry consistency advantages as lithium carbon monofluoride substitution pressure intensifies in high-drain defibrillator segments. For New Entrants and Emerging Players: Remote monitoring transmitter power requirements represent an underserved service layer where incumbents prioritize device-battery integration over standalone cell optimization. Target United States home healthcare providers with modular battery designs compatible with existing pacemaker portfolios, leveraging streamlined 510(k) pathways for supplemental power accessories rather than full device system approvals. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across lithium carbon monofluoride qualification programs as OEMs demand validated cell designs for next-generation ICD miniaturization. Acquisition targets should display established EU MDR technical documentation packages and hermetic integrity testing infrastructure. Watch FDA guidance on battery end-of-life notification systems as the signal for regulatory-driven consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Comprehensive clinical evidence packages filter marginal suppliers and consolidate procurement authority among qualified manufacturers with notified body relationships. |
| Captive Lithium Iodide Cell Manufacturing | In-house electrochemical production secures chemistry consistency for multi-year implantation cycles and reduces third-party allocation exposure. |
| Home Healthcare Channel Partnership | Remote patient monitoring reimbursement codes enable bypass of hospital purchasing committees for ambulatory battery replacement demand. |
| Hermetic Sealing Capability Expansion | Precision engineering clusters in Germany and Switzerland anchor high-reliability production for cardiac resynchronization therapy applications. |
| Closed-Loop Lithium Recovery Systems | EU battery regulation sustainability mandates create first-mover advantage for manufacturers establishing material recycling obligations. |
Study Parameters
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at device OEMs, then refined through secondary validation. Sources included FDA 510(k) and PMA filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, hospital procurement records, and ISO 14708 certification registries. Bottom-up cell volume estimates triangulated with top-down device implantation forecasts.
Variance decomposition across battery chemistry, end-user channel, and application intensity segments informed the analytical framework over the projection horizon. CAGRs derived from implant volume trajectories in aging demographics, chemistry substitution rates, and regulatory approval timelines. Industry-specific inputs incorporated PMDA consultation timelines for novel formulations and METI industrial policy support for domestic precursor production.
Underlying assumptions cover stable FDA and EU MDR regulatory frameworks, with deviation risk concentrated in raw material supply disruptions and accelerated chemistry transitions. Forecasts reflect these conditions throughout the modeling period. Revision becomes warranted when lithium iodide precursor allocation constraints or sustainability mandate enforcement intensity crosses thresholds that alter manufacturer qualification economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South America C-Arms Market
Medical Devices
Disposable Needle Guides Market
Medical Devices
Global Pulmonary Drug Delivery Systems Market
Medical Devices
Specimen Retrieval Nets Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Diode Laser Aesthetic Medical Device Market
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
US Nurse Call Systems Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Global Surgical Microscopes Market
Medical Devices
Medical Polyimide Tubing Market
Medical Devices
Global 3D Printed Surgical Models Market
Medical Devices
Global Thermoelectric Devices in Medical and Laboratory Offering Market
Medical Devices
Semiconductor Laser Therapeutic Device Market
Medical Devices
Global Surgical Visualization Products Market
Medical Devices
Europe Biopsy Devices Market