
 Thermal Ablation Devices Market | 2026-2036
Thermal Ablation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Ablation Devices Market Outlook
The EU Green Deal is decoupling thermal ablation procurement from conventional energy-intensive manufacturing benchmarks across European hospital networks. Medtronic leverages its integrated R&D infrastructure to sustain catheter innovation pipelines in radiofrequency systems. Boston Scientific Corporation anchors its competitive stance through geographic dominance in North American outpatient cardiac ablation. Johnson & Johnson differentiates via manufacturing scale across its Ethicon surgical portfolio.
Thermal ablation devices generate controlled thermal energy to destroy targeted tissue through electromagnetic, acoustic, or cryogenic mechanisms, typically operating at temperatures between 50°C and 100°C for radiofrequency and microwave modalities or sub-zero thresholds for cryoablation, serving primary purposes in tumor reduction, cardiac arrhythmia correction, and benign tissue elimination. Radiofrequency ablation occupies the largest installed base due to decades of clinical validation and broad reimbursement coverage, while microwave ablation extends faster heating profiles that reduce procedure times in hepatic and renal oncology. Robotic-assisted technology leads margin pools through premium pricing and precision positioning capabilities, though image-guided systems compete on capital efficiency and shorter training curves.
FDA 510(k) pathways govern US market entry for thermal ablation systems, while EU MDR requirements enforce stricter clinical evidence standards for CE marking renewal across European manufacturers. China's NMPA has accelerated review timelines for innovative minimally invasive devices under priority review channels. Stakeholders must monitor evolving reimbursement coding for outpatient ablation procedures against shifting site-of-care economics.
Market Dynamics
Minimally invasive oncology procedures are compressing hospital length-of-stay metrics and redirecting capital expenditure toward outpatient-compatible thermal ablation platforms. This structural shift forces manufacturers to reconcile premium precision engineering with ambulatory surgery center pricing constraints.
Growth Catalysts
- EU MDR compliance timelines:European hospital networks are accelerating replacement cycles for legacy radiofrequency systems ahead of CE marking renewal deadlines, creating pull-through demand for next-generation catheter platforms.
- China's NMPA priority review channels:Expedited regulatory pathways for innovative minimally invasive devices shorten time-to-revenue for microwave ablation entrants targeting hepatic oncology.
- Outpatient cardiac ablation migration:United States reimbursement coding increasingly favors same-day discharge arrhythmia procedures, expanding addressable procedure volume for cryoablation systems.
Market Restraints
- Capital equipment intensity:Robotic-assisted thermal ablation platforms require seven-figure capital commitments that constrain ambulatory surgery center adoption despite superior precision outcomes.
- Supply concentration in radiofrequency generators:Core power electronics manufacturing clusters in Germany and Japan create vulnerability to component lead-time volatility.
- Substitution from irreversible electroporation:Non-thermal tumor ablation modalities compete for overlapping oncology indications without heat-sink limitations near vascular structures.
Strategic Opportunities
- Underpenetrated renal oncology in India:Rising incidence of small renal masses coincides with expanding private hospital networks seeking differentiated interventional radiology capabilities.
- EU Green Deal procurement decoupling:European hospital sustainability mandates create first-mover advantage for manufacturers with low-carbon manufacturing footprints and recyclable catheter designs.
- Convergence of microwave ablation with AI-powered imaging:Real-time tissue temperature prediction algorithms enable novice operators to achieve expert-equivalent ablation margins.
Industry Challenges
- Interventional radiologist training bottlenecks:Procedural volume requirements for microwave ablation competency exceed available fellowship slots in United States academic medical centers.
- FDA 510(k) predicate device erosion:Substantial equivalence pathways narrow as legacy radiofrequency systems face safety-related recalls, forcing de novo review timelines.
- Integration complexity with PACS and EMR systems:Proprietary data formats from competing ablation platforms complicate multi-vendor hospital standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Ablation Devices Market |
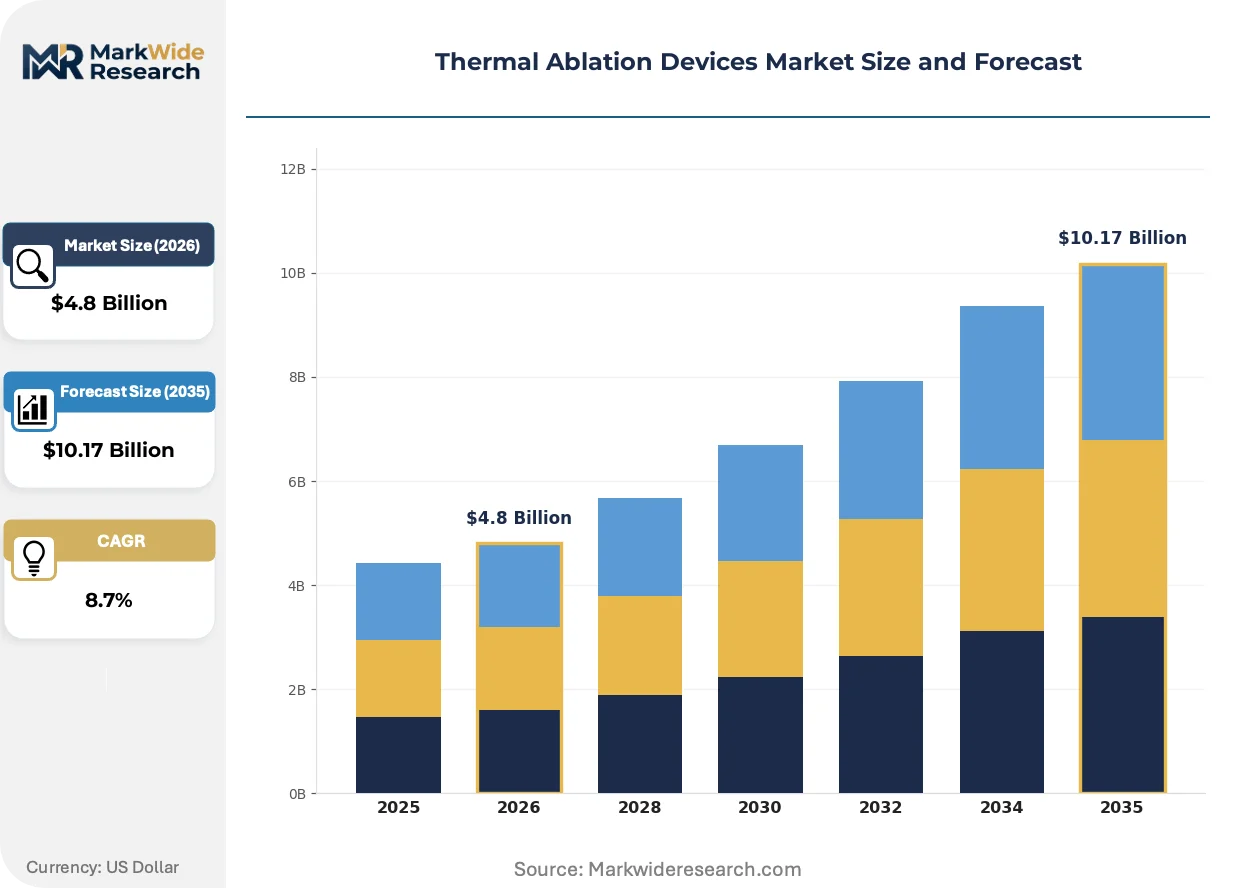
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency Ablation, Microwave Ablation, Laser Ablation, Cryoablation End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes Application: Oncology, Cardiology, Urology, Gastroenterology Technology: Minimally Invasive, Image-Guided, Robotic-Assisted, Conventional |
| Companies Covered | Medtronic, Boston Scientific Corporation, Johnson & Johnson, Abbott Laboratories, AngioDynamics, Smith & Nephew, Atricure, Olympus Corporation, CONMED Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Ablation Devices Market Strategic Shifts
Robotic positioning systems and real-time thermometry feedback loops are redefining precision benchmarks in interventional oncology. These advances compress the skill gradient between academic and community practice settings.
Microwave ablation is absorbing procedural share in hepatic and renal oncology through faster heating profiles that overcome perfusion-mediated cooling near vascular structures. Community hospital interventional radiology departments are adopting microwave platforms at accelerating rates to match academic center throughput metrics. This technology is absorbing the procedure-time advantage that previously justified patient referral to tertiary centers.
The EU MDR's stricter clinical evidence standards for CE marking renewal are forcing European manufacturers to generate prospective registry data for legacy radiofrequency systems. Industrial consequence includes delayed product launch timelines and elevated regulatory affairs headcount requirements. Cardiac ablation catheter portfolios face the most acute compliance burden given their higher-risk classification under Annex VIII rules.
Hospital procurement departments are unbundling capital equipment purchases from disposable catheter supply agreements to improve vendor leverage. This behavior disrupts traditional bundled pricing models that subsidized generator placement through catheter premium markups. The shift is most visible in German hospital networks where centralized purchasing cooperatives command substantial volume concentration.
Thermal Ablation Devices Market Segmentation
Thermal ablation device procurement varies sharply across clinical settings, with reimbursement coding and capital intensity driving divergent purchasing patterns. Segmentation reveals how regulatory classification shapes commercial strategy for manufacturers targeting specific procedure volumes.
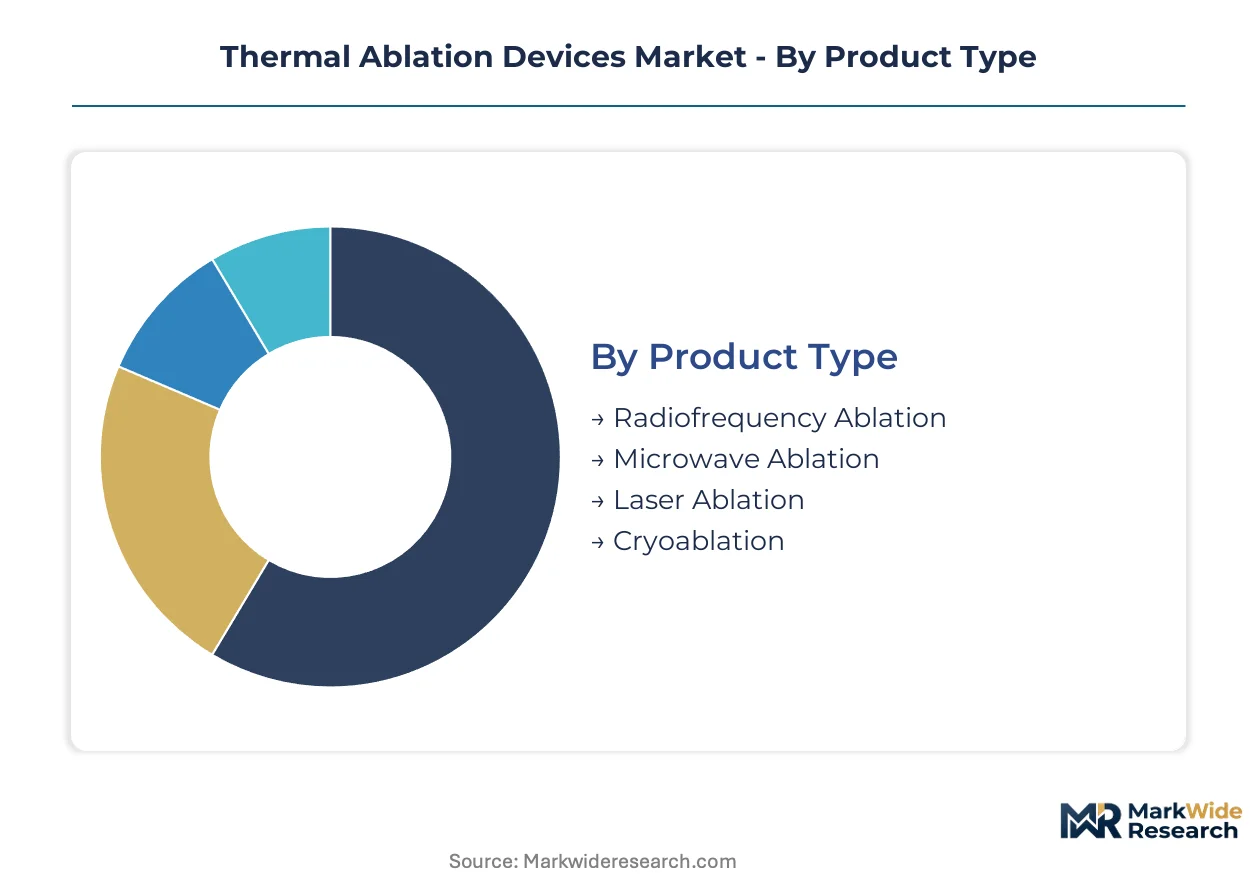
Product Type:
Radiofrequency and microwave systems face divergent FDA 510(k) predicate requirements, while cryoablation catheters trigger higher-risk device pathways demanding extensive clinical evidence packages.
- Radiofrequency Ablation:Electromagnetic energy delivery at 460-480 kHz generates resistive heating in target tissue. Demand concentrates in United States outpatient cardiac centers where CMS reimbursement favors established catheter platforms with decades of safety data.
- Microwave Ablation:Dielectric heating at 915 MHz or 2.45 GHz achieves faster thermal penetration than radiofrequency modalities. Chinese tertiary hospitals are absorbing microwave systems for hepatic oncology as NMPA priority review accelerates domestic manufacturer market entry.
- Laser Ablation:Nd:YAG and diode laser systems deliver precise photothermal energy for small-volume lesions.
- Cryoablation:Argon-based Joule-Thomson cooling achieves sub-zero tissue destruction without thermal char limitations.
Radiofrequency Ablation sits at the top of the volume ranking, with Microwave Ablation climbing the fastest.
End User:
Capital expenditure thresholds and procedure reimbursement differentials fragment purchasing authority across facility types, with ambulatory centers facing stricter equipment ROI requirements.
- Hospitals:Integrated interventional radiology suites command seven-figure capital budgets for robotic-assisted platforms. German university hospitals anchor European demand through centralized procurement cooperatives negotiating multi-year catheter supply agreements.
- Ambulatory Surgical Centers:Same-day discharge economics favor compact, mobile ablation generators with rapid setup protocols. United States freestanding cardiac centers are migrating cryoablation procedures from hospital campuses to capture facility fee differentials.
- Specialty Clinics:Pain management and varicose vein clinics deploy lower-power radiofrequency systems for office-based procedures.
- Research Institutes:Academic medical centers purchase experimental platforms for investigator-initiated trials.
Hospitals capture the dominant revenue share, though Ambulatory Surgical Centers are expanding most quickly.
Application:
Clinical indication determines thermal modality selection, with tumor proximity to critical structures and tissue perfusion characteristics driving technology matching.
- Oncology:Hepatic, renal, and lung tumor ablation demands precise margin control and real-time thermometry. Chinese public hospital networks are prioritizing microwave procurement for hepatocellular carcinoma given rising disease incidence and constrained surgical capacity.
- Cardiology:Atrial fibrillation ablation requires electroanatomic mapping integration and pulmonary vein isolation durability. United States electrophysiology labs are standardizing on cryoballoon or radiofrequency point-by-point approaches based on operator training pathways.
- Urology:Prostate and renal mass applications favor focal therapy preservation of functional tissue.
- Gastroenterology:Barrett's esophagus and pancreatic cancer palliation represent emerging interventional endoscopy applications.
Oncology leads absolute procedure volume, with Cardiology showing steepest expansion trajectory.
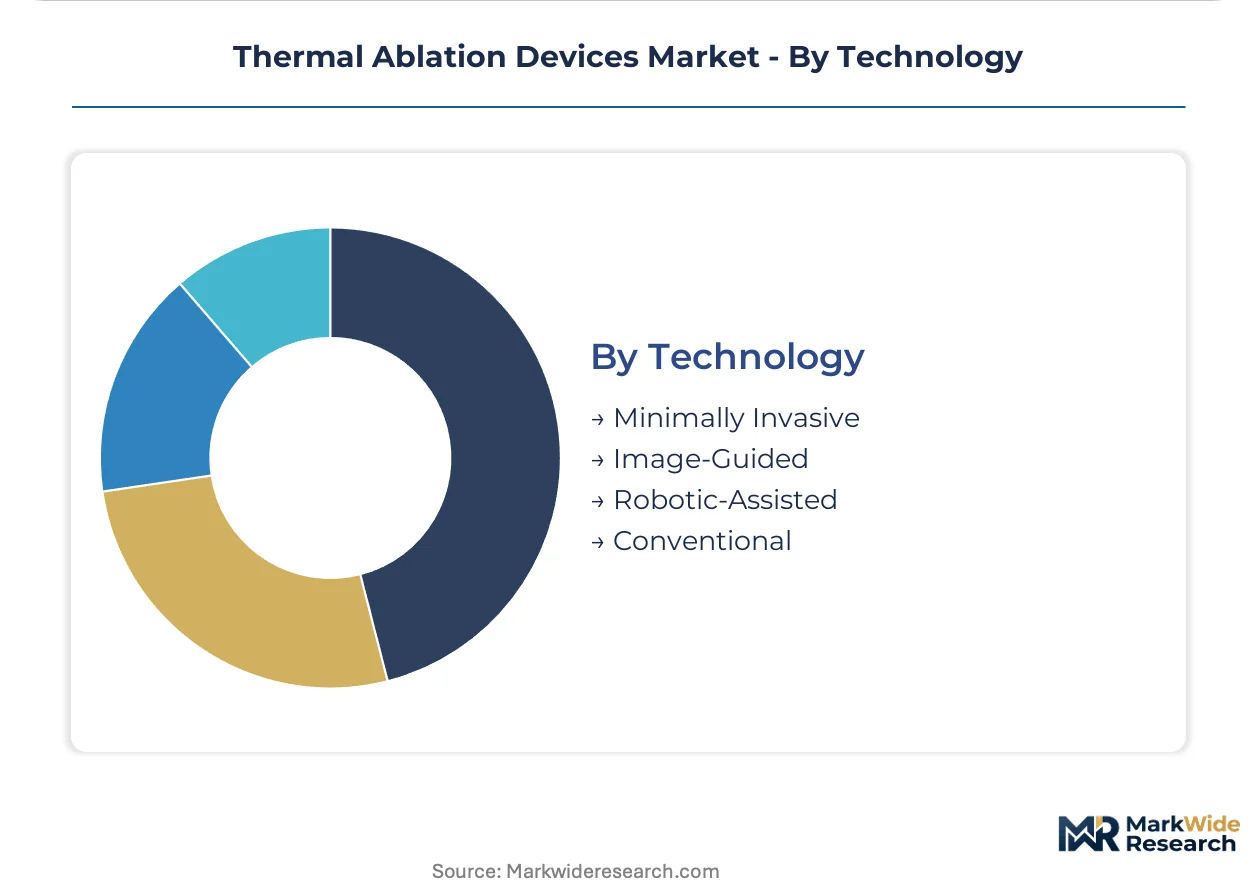
Technology:
Automation depth separates pricing tiers, with robotic positioning commanding capital premiums against manual image-guided alternatives.
- Minimally Invasive:Percutaneous and laparoscopic access routes reduce recovery time versus open surgical approaches. Indian private hospital networks are importing radiofrequency systems for interventional radiology departments seeking differentiated oncology capabilities.
- Image-Guided:CT, MRI, and ultrasound fusion enables real-time needle placement verification. Community hospitals in the United States are adopting ultrasound-guided microwave platforms to match academic center throughput without dedicated CT interventional suites.
- Robotic-Assisted:Stereotactic positioning and haptic feedback enable sub-millimeter accuracy in complex anatomies.
- Conventional:Manual probe placement with basic temperature monitoring serves cost-constrained settings.
Minimally Invasive platforms dominate installed base, with Robotic-Assisted systems gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional radiologists and cardiac electrophysiologists concentrate in tertiary hospital clusters across the United States, Germany, and China, anchoring procedural volume and technology adoption curves for thermal ablation platforms.
United States
FDA 510(k) clearance pathways and CMS reimbursement coding for outpatient cardiac ablation drive system procurement in electrophysiology labs. The agency's substantial equivalence framework governs market entry for radiofrequency and microwave modalities. The Cleveland Clinic and Mayo Clinic anchor demand for robotic-assisted platforms through high-volume arrhythmia centers.
Germany
Centralized hospital purchasing cooperatives negotiate multi-year catheter supply agreements for university hospital networks. EU MDR compliance timelines compress CE marking renewal cycles for legacy radiofrequency systems. The Rhine-Ruhr and Bavarian medical device clusters concentrate manufacturing of power electronics and generator components.
China
Rising hepatocellular carcinoma incidence and constrained surgical capacity accelerate microwave ablation adoption in public hospital networks. NMPA priority review channels expedite regulatory pathways for innovative minimally invasive devices. Shanghai and Beijing tertiary hospitals anchor demand for domestic and imported ablation systems.
Japan
PMDA regulatory frameworks enforce stringent clinical evidence standards for thermal ablation device approval. METI industrial policy supports domestic manufacturing of precision medical electronics. The Kanto region around Tokyo concentrates interventional radiology training programs and high-volume oncology centers.
India
Expanding private hospital networks in metropolitan areas seek differentiated interventional radiology capabilities for renal oncology. CDSCO regulatory pathways govern import and local manufacturing of ablation generators. Maharashtra and Karnataka anchor demand through Mumbai and Bangalore medical tourism corridors.
Thermal Ablation Devices Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the thermal ablation device landscape, with integrated medical technology conglomerates maintaining in-house manufacturing of generators and catheters while specialized firms outsource component fabrication. The vendor base stratifies across three tiers: diversified multinationals with full portfolio coverage, mid-cap specialists focused on single modalities, and regional assemblers serving price-constrained markets. Dominant competitive moves include M&A activity to acquire complementary imaging or navigation technologies, and capacity expansion in low-cost manufacturing jurisdictions to serve emerging market procurement.
Among diversified medical technology conglomerates, Medtronic, Boston Scientific Corporation, and Johnson & Johnson occupy positions representing integrated R&D-through-commercialization archetypes. Medtronic exemplifies the capital-intensive integrated model with captive supply of radiofrequency generator platforms. Boston Scientific Corporation represents geographic concentration strategies in North American outpatient settings. Johnson & Johnson's Ethicon surgical portfolio anchors manufacturing scale advantages across disposable catheter supply chains.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Abbott Laboratories |
| AngioDynamics |
| Smith & Nephew |
| Atricure |
| Olympus Corporation |
| CONMED Corporation |
| Others |
Value Chain & Pricing Dynamics
Radiofrequency generator power electronics anchor cost structures from German and Japanese component clusters through catheter premium markups to hospital procurement tiers. Bundled capital-plus-disposable agreements historically subsidized equipment placement while unbundling trends in German cooperatives now force transparent generator pricing against standalone catheter supply contracts.
Pricing Analysis
Bundled generator-catheter service splits dominate hospital procurement, though German purchasing cooperatives increasingly unbundle these agreements to improve vendor leverage. Pricing stratifies across robotic-assisted premium tiers, image-guided standard platforms, and manual economy systems differentiated by precision certification and after-sales service intensity. Cost compression in the economy tier intensifies as ambulatory surgery centers demand mobile generators with rapid setup protocols. Academic medical centers show lowest price sensitivity, prioritizing integration with electroanatomic mapping systems.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States maintain hub-and-spoke patterns for generator fulfillment to hospital networks. Manufacturing of core power electronics concentrates in the Rhine-Ruhr industrial cluster and Kanto region around Tokyo. Radiofrequency generators draw from specialized semiconductor foundries and precision medical cable suppliers. Single-source vulnerability in cryoablation argon gas delivery systems creates exposure to logistics chokepoints. Distribution runs through manufacturer-direct field service teams and third-party medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal ablation devices function as a stable compounder anchored by irreversible surgical procedure migration toward minimally invasive outpatient settings. The structural shift from open resection to percutaneous ablation sustains durable replacement demand across hospital and ambulatory channels.
For Market Incumbents: Hedge against irreversible electroporation substitution by accelerating microwave ablation portfolio expansion and securing NMPA priority review pathways for hepatic oncology indications. Deepen backward integration into precision catheter manufacturing to defend margin position as procurement unbundling intensifies.
For New Entrants and Emerging Players: Ambulatory surgery center partnerships offer the most penetrable channel for compact cryoablation platforms targeting United States cardiac migration. Focus initial commercialization on ultrasound-guided microwave systems for community hospital interventional radiology departments seeking academic-equivalent throughput without capital-intensive CT suite investments.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap specialists lack captive imaging navigation capabilities and face EU MDR compliance cost escalation. The sector supports long-term viability framing through recurring catheter revenue streams and robotic-assisted premium pricing durability. Target acquisition candidates with established hospital GPO contracts and microwave ablation regulatory clearances in China. Monitor NMPA priority review queue depth as inflection signal for competitive entry velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market entry for microwave ablation systems targeting hepatic oncology indications. |
| CE Marking Pathway | EU MDR compliance timelines force prospective registry investment for legacy radiofrequency catheter portfolios. |
| Hospital System Partnership | German university hospital cooperatives negotiate multi-year catheter supply agreements with embedded service commitments. |
| Software Companion Development | AI-powered thermometry prediction algorithms enable novice operators to achieve expert-equivalent ablation margins. |
| Reimbursement Strategy | CMS coding alignment for same-day discharge cardiac ablation expands addressable procedure volume for cryoablation platforms. |
Study Parameters
Coverage spans the United States, Germany, China, Japan, and India, with primary inputs from each market gathered through structured interviews with interventional radiologists, cardiac electrophysiologists, hospital procurement committee members, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, NMPA priority review disclosures, EU MDR technical documentation databases, and hospital procurement system records. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data across the analysis window.
Rate-of-change decomposition separated volume expansion from price-mix effects across technology tiers, with CAGRs derived from logistic adoption curves fitted to historical penetration patterns. Segmentation modeling incorporated product type, end-user facility class, clinical application, and automation depth dimensions. Industry-specific forecast inputs included hepatocellular carcinoma incidence trajectories, ambulatory surgery center certification growth, and interventional radiology fellowship completion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory pathway shifts, reimbursement coding revisions, and substitution from non-thermal ablation modalities. Outputs reflect documented assumptions around procedure migration velocity and capital equipment replacement cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
Temporary Pacing Leads Market
Medical Devices
Powered Wheelchair Market
Medical Devices
Brachytherapy Catheters Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
Non-Invasive Brain Trauma Monitoring Devices Market
Medical Devices
Osteotomy Plates Market
Medical Devices
Laparoscopic Devices Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
Orthodontic Headgear Market
Medical Devices
Venous Device Market
Medical Devices
Global Thrombectomy Devices Market
Medical Devices
Global Wearable Pregnancy Devices Market
Medical Devices
China Anesthesia Devices Market
Medical Devices
Infant Incubator Market