
 Medical Digital Imaging Devices Market | 2026-2036
Medical Digital Imaging Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Digital Imaging Devices Market Outlook
Oncology departments within hospital networks is broadening as the fastest-expanding end-use vertical for advanced imaging platforms. GE Healthcare leverages deep vertical integration across CT and MRI manufacturing to sustain equipment supply chain control. Siemens Healthineers anchors European installed base service contracts while competing aggressively in digital radiography upgrades across North American health systems.
Medical digital imaging devices encompass electronically controlled systems that capture, process, and display anatomical visual data using detector arrays with spatial resolution parameters measured in line pairs per millimeter, serving primarily to enable non-invasive diagnostic decision-making by clinicians. CT scanners command the largest installed base revenue pool among product types, while 3D imaging technology captures the fastest growth trajectory as surgical planning applications multiply across orthopedic and neurological procedures. Diagnostic centers represent a structurally expanding end user segment as outpatient imaging shifts accelerate away from inpatient hospital settings.
FDA software-as-a-medical-device regulations and CE marking requirements under the EU MDR jointly determine market access timelines and predicate device pathways for manufacturers seeking multi-jurisdictional approval. HIPAA data security standards and GDPR patient privacy frameworks further constrain cloud-connected imaging architectures, forcing vendors to architect region-specific data residency into platform designs. Stakeholders must weigh regulatory compliance investment against the pace of AI algorithm integration when allocating R&D budgets across product development pipelines.
Market Dynamics
AI-enabled diagnostic algorithms are compressing image interpretation timelines while forcing hardware manufacturers to redesign detector architectures for real-time inference workloads.
Growth Catalysts
- FDA Software-as-a-Medical-Device Framework:The FDA's evolving clearance pathways for AI diagnostic tools are accelerating commercialization timelines for algorithm developers seeking predicate device routes.
- Oncology Imaging Demand:Hospital network oncology departments are expanding procurement of advanced CT and MRI platforms to support precision radiation therapy planning and treatment response monitoring.
- 3D Surgical Planning:Orthopedic and neurological procedure volumes are driving detector array upgrades capable of sub-millimeter isotropic resolution for patient-specific implant modeling.
Market Restraints
- Rare Earth Magnet Supply Concentration:Superconducting MRI systems depend on niobium-titanium and helium-3 supply chains concentrated in limited extraction geographies, creating input cost volatility.
- EU MDR Compliance Burden:CE marking requirements under the EU Medical Device Regulation have extended technical documentation timelines and increased notified body audit costs for multi-jurisdictional manufacturers.
- Interoperability Friction:Legacy DICOM archive systems resist seamless integration with cloud-native AI inference platforms, forcing costly middleware development.
Strategic Opportunities
- Diagnostic Center Expansion:Outpatient imaging shifts away from inpatient hospital settings are creating greenfield installation demand for compact CT and digital radiography suites in ambulatory settings.
- GDPR-Compliant Cloud Architectures:Region-specific data residency requirements are opening architecture consulting revenue streams for vendors configuring hybrid edge-cloud processing pipelines.
- Photon-Counting CT Convergence:Direct conversion detector materials and deep learning reconstruction algorithms are converging to enable spectral imaging at dose levels previously unattainable with energy-integrating systems.
Industry Challenges
- Clinical AI Validation Talent Scarcity:Medical physicists with dual competency in machine learning model validation and regulatory submission writing command premium compensation, constraining R&D team scaling.
- Helium Cryogen Logistics:Closed-loop magnet cooling systems require specialized service technician networks that OEMs must rebuild as helium supply constraints tighten field maintenance response times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Digital Imaging Devices Market |
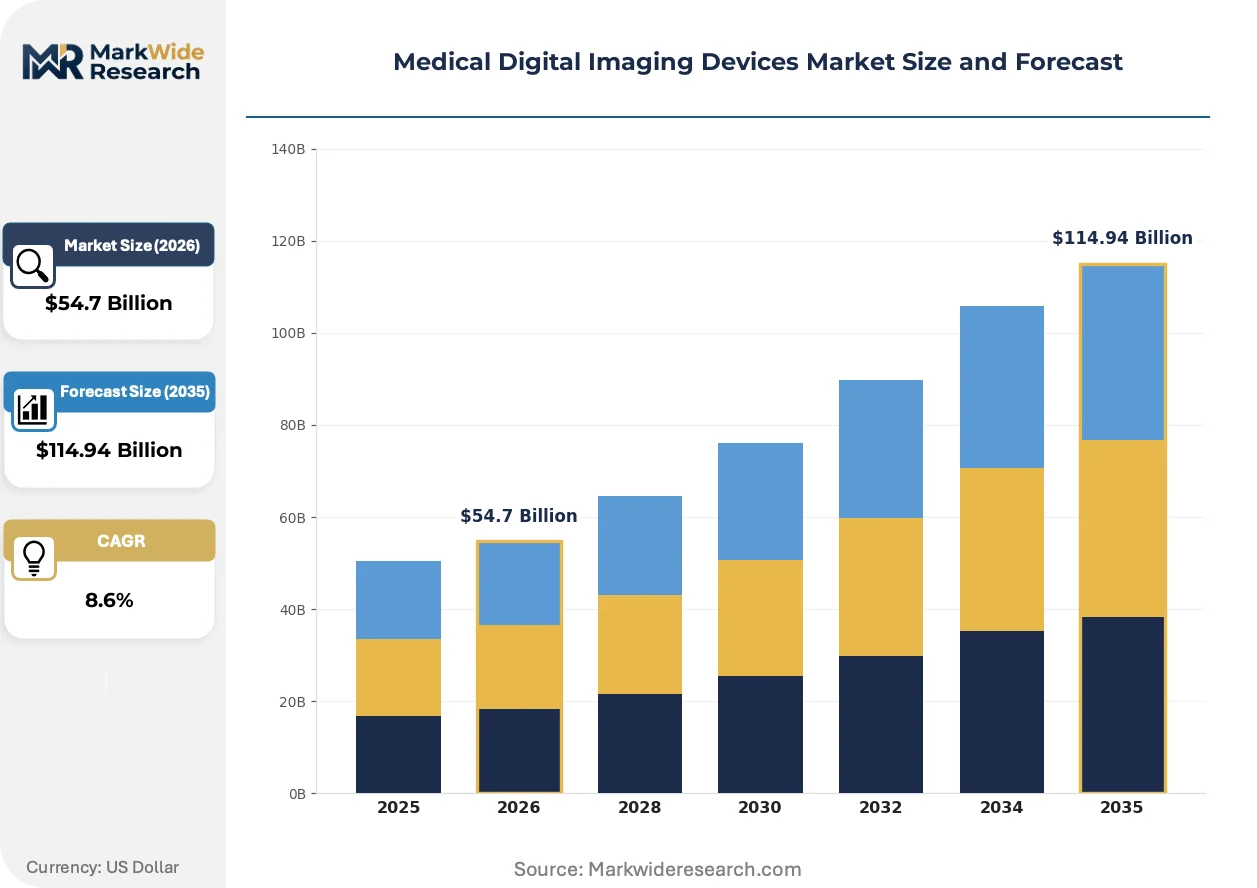
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $114.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Systems, MRI Machines, CT Scanners, X-ray Devices Technology: Digital Radiography, 3D Imaging, Computed Tomography, Magnetic Resonance Imaging End User: Hospitals, Diagnostic Centers, Research Laboratories, Outpatient Facilities Application: Oncology, Cardiology, Orthopedics, Neurology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, Carestream Health, Hitachi, Mindray Medical International, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Digital Imaging Devices Market Strategic Shifts
Detector material science and computational reconstruction are fusing to extract diagnostic information from lower radiation exposures while regulatory frameworks race to keep pace with algorithmic decision support.
Photon-counting CT detectors using cadmium telluride and cadmium zinc telluride semiconductors are automating material decomposition for automated calcium scoring and iodine quantification. Academic medical centers in Germany and the United States are replacing energy-integrating detector fleets ahead of standard depreciation cycles. The technology is automating previously manual spectral analysis workflows, compressing reporting turnaround for cardiovascular emergency departments.
The EU AI Act's risk classification system for medical device software is mandating conformity assessment procedures for diagnostic algorithms that influence clinical decision-making. Manufacturers must now document training data provenance and algorithmic performance across demographic subgroups before CE marking. High-risk imaging AI applications face the strictest transparency requirements, pushing developers toward explainable model architectures.
Health system consolidation is concentrating equipment purchasing authority within centralized value analysis committees. Independent imaging centers and smaller hospital networks are losing direct vendor negotiation leverage as contract terms standardize across integrated delivery networks. The United States exhibits the most pronounced buyer concentration, with ten health systems controlling a disproportionate share of annual modality procurement volume.
Medical Digital Imaging Devices Market Segmentation
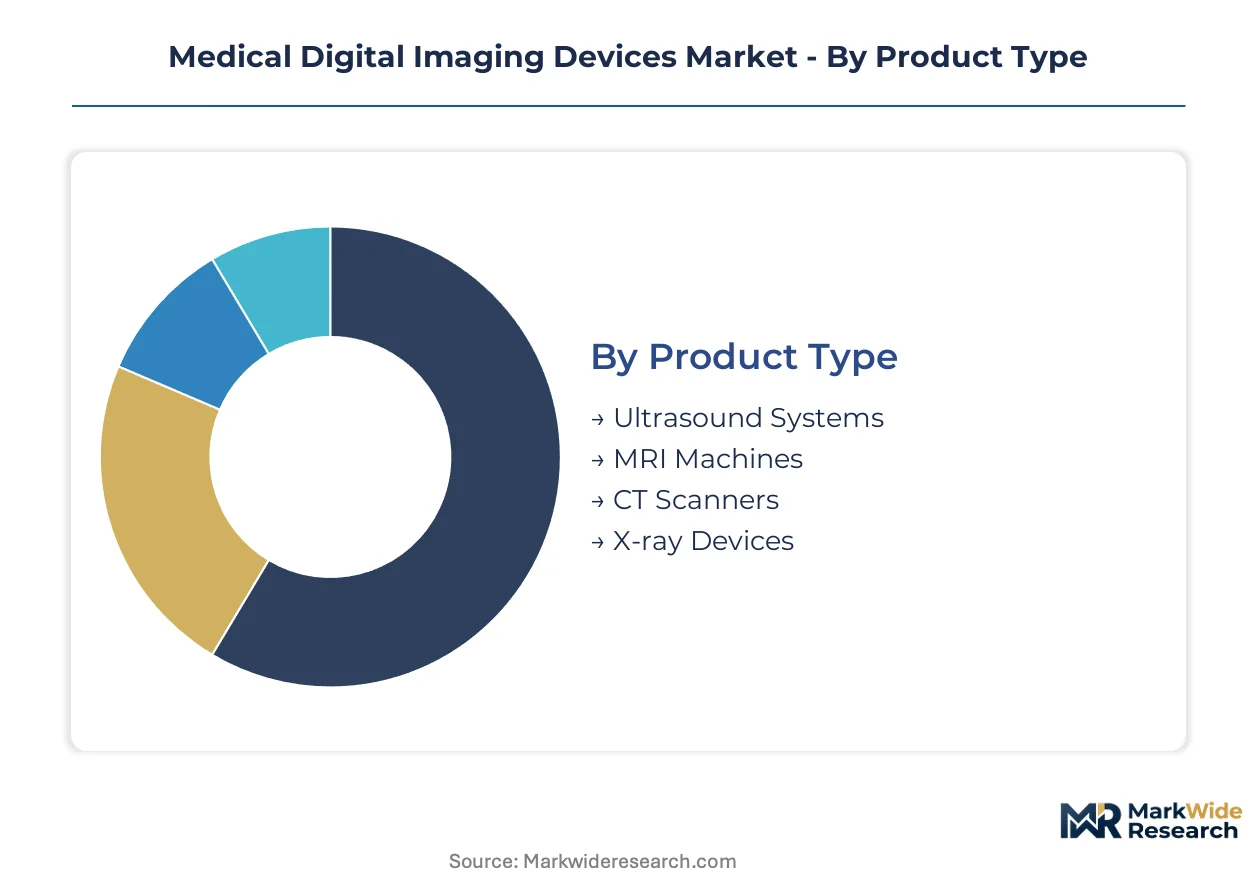
Medical digital imaging devices fragment across four structural dimensions that determine procurement patterns and technology roadmaps. Product type and technology segments define capital allocation priorities, while end-user and application categories shape go-to-market strategies for equipment vendors.
Product Type:
Standalone installations dominate hospital infrastructure, whereas embedded imaging modules integrate into hybrid surgical suites and point-of-care workflows.
- CT Scanners:Energy-integrating detectors currently predominate, though photon-counting architectures using cadmium telluride are displacing legacy fleets in German and US academic centers. Demand concentrates within oncology departments requiring sub-millimeter isotropic resolution for radiation therapy planning.
- MRI Machines:Superconducting systems utilizing niobium-titanium magnets and liquid helium cooling constitute the revenue core. Procurement in US health systems is accelerating for 3T platforms supporting neurological functional imaging, constrained by helium supply logistics and rare earth magnet cost volatility.
- Ultrasound Systems:Portable cart-based and handheld probe formats are expanding into emergency departments and ambulatory surgical centers for rapid cardiac and abdominal assessment.
- X-ray Devices:Digital radiography retrofit kits and dedicated chest/orthopedic systems serve high-throughput screening programs and trauma bays.
Volume placements concentrate in CT scanners; the faster expansion belongs to MRI machines.
Technology:
Cost tiers separate premium spectral capabilities from standard reconstruction platforms, with reimbursement differentials driving upgrade cycles.
- 3D Imaging:Cone-beam CT and tomosynthesis reconstruction algorithms enable patient-specific implant modeling. Orthopedic procedure volumes in US ambulatory surgery centers are driving detector array upgrades for surgical planning applications.
- Digital Radiography:Flat-panel detectors with cesium iodide or amorphous selenium conversion layers deliver immediate image availability. Diagnostic centers across the United States are prioritizing these systems for outpatient throughput efficiency.
- Computed Tomography:Iterative reconstruction and deep learning post-processing are reducing dose exposure while maintaining diagnostic confidence.
- Magnetic Resonance Imaging:Advanced coil arrays and compressed sensing acquisition are shortening scan durations for claustrophobic and pediatric populations.
Capital deployment concentrates in digital radiography; 3D imaging climbs the fastest.
End User:
Customer type determines service contract structures, with integrated delivery networks demanding enterprise-wide fleet standardization.
- Hospitals:Inpatient facilities anchor the installed base, with oncology and emergency departments driving modality-specific procurement. US health system consolidation is centralizing purchasing authority within value analysis committees.
- Diagnostic Centers:Freestanding outpatient imaging sites are expanding CT and digital radiography capacity as patient volumes shift away from hospital campuses. These facilities prioritize compact footprints and rapid turnaround protocols.
- Outpatient Facilities:Urgent care and specialty clinics are adopting point-of-care ultrasound and portable X-ray for same-day diagnosis.
- Research Laboratories:Preclinical imaging and pharmaceutical trial sites require high-field MRI and micro-CT for translational studies.
Equipment shipments concentrate in hospitals; diagnostic centers gain share fastest.
Application:
Clinical use case dictates resolution requirements, contrast protocols, and regulatory validation pathways for AI-enabled diagnostic algorithms.
- Oncology:Tumor staging and treatment response monitoring require multimodal imaging fusion across CT, MRI, and PET platforms. FDA software-as-a-medical-device clearances are accelerating AI lesion detection deployment in US cancer centers.
- Cardiology:Coronary CT angiography and cardiac MRI are expanding as first-line non-invasive alternatives to catheterization. Photon-counting CT enables automated calcium scoring and iodine quantification in emergency departments.
- Orthopedics:Weight-bearing CT and 3D implant templating support patient-specific surgical planning.
- Neurology:Functional MRI and diffusion tensor imaging guide neurosurgical intervention and stroke triage protocols.
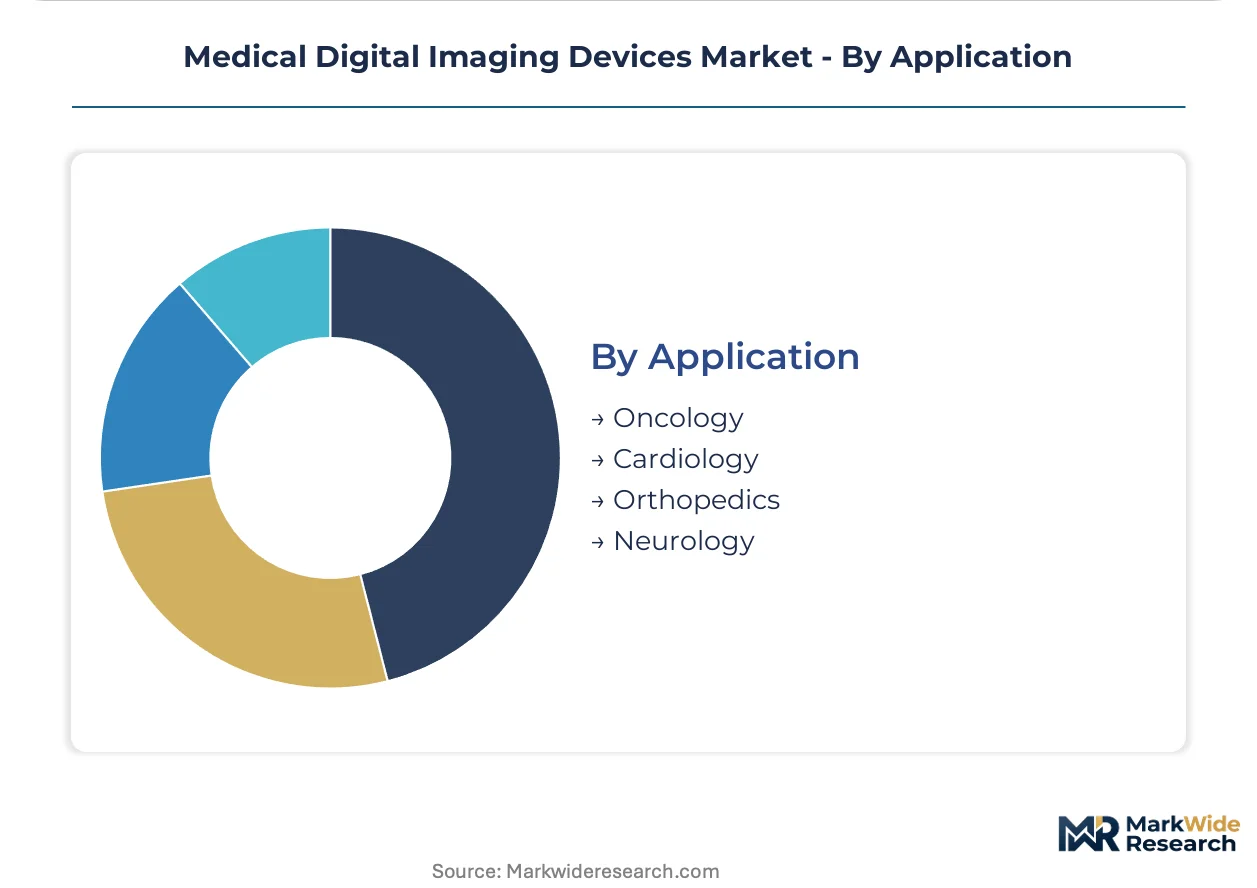
Procurement volumes concentrate in oncology; cardiology exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of superconducting magnets and detector arrays concentrates in Germany and the United States, while installed base expansion accelerates in China and India where hospital network modernization programs drive procurement. Consumption patterns diverge sharply between mature replacement markets and greenfield installations.
United States
Hospital system consolidation concentrates purchasing authority within ten integrated delivery networks controlling disproportionate annual modality procurement volume. FDA software-as-a-medical-device clearances are accelerating AI lesion detection deployment across cancer centers. The Greater Boston and San Francisco Bay Area clusters anchor venture funding for diagnostic algorithm startups.
Germany
Academic medical centers in Munich and Heidelberg are replacing energy-integrating CT detector fleets with photon-counting architectures ahead of standard depreciation cycles. EU MDR technical documentation requirements and notified body audit costs are extending CE marking timelines for multi-jurisdictional manufacturers. The Baden-Württemberg industrial corridor sustains precision engineering supply chains for MRI magnet fabrication.
China
Domestic manufacturers are capturing share in mid-tier CT and digital radiography segments as NMPA regulatory pathways streamline for locally developed imaging platforms. Provincial hospital tier-upgrading initiatives are expanding installed base capacity in secondary cities. The Yangtze River Delta cluster around Shanghai concentrates R&D investment for detector material science.
Japan
Compressed sensing acquisition and advanced coil array development are shortening MRI scan durations for claustrophobic and pediatric populations. PMDA consultation procedures for AI-enabled diagnostic software are establishing validation precedents for algorithm developers. The Kansai region around Osaka maintains specialized production capabilities for high-field magnet systems.
India
Diagnostic center entrepreneurs are expanding outpatient CT and digital radiography capacity as patient volumes shift away from tertiary hospital campuses. CDSCO medical device registration requirements are harmonizing with international standards for multinational OEM market entry. The Maharashtra-Gujarat corridor is emerging as a service hub for refurbished imaging equipment re-export.
Medical Digital Imaging Devices Market Competitive Environment
Top-tier vendors anchor the premium spectral imaging segment, while mid-tier Asian manufacturers compete on digital radiography and portable ultrasound price points. The vendor base separates into three archetypes: diversified healthcare conglomerates with captive magnet supply chains, specialized imaging OEMs focused on detector innovation, and emerging platform players leveraging AI algorithm differentiation. Competitive dynamics center on strategic partnerships for photon-counting detector material access and vertical integration into superconducting wire production.
Among diversified healthcare conglomerates, GE Healthcare and Siemens Healthineers exemplify the integrated manufacturing archetype with upstream control over cryogen logistics and magnet winding facilities. Koninklijke Philips N.V. occupies a position bridging diagnostic imaging hardware with enterprise informatics software. These three anchors represent distinct strategic postures: one emphasizing deep backward integration into component manufacturing, one combining European installed base service density with North American digital radiography expansion, and one integrating workflow software with modality hardware.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| FUJIFILM Holdings Corporation |
| Carestream Health |
| Hitachi |
| Mindray Medical International |
| Shimadzu Corporation |
| Others |
Value Chain & Pricing Dynamics
Hospital network consolidation into centralized value analysis committees is compressing vendor negotiation leverage and forcing OEMs to absorb detector material cost volatility into long-term service contracts rather than pass through to equipment pricing. This procurement concentration reshapes how manufacturers structure bundled financing and aftermarket service tiers across integrated delivery networks.
Pricing Analysis
Lead-time premiums for photon-counting CT detector arrays command significant markups over energy-integrating alternatives as academic medical centers in Germany and the United States accelerate fleet replacement ahead of standard depreciation cycles. Three-tier pricing structure across premium spectral, standard iterative reconstruction, and economy refurbished systems differentiates primarily by detector resolution grade and FDA software-as-a-medical-device clearance status. Cost compression in mid-tier digital radiography intensifies as domestic Chinese manufacturers expand NMPA-cleared capacity for provincial hospital tier-upgrading programs. Independent diagnostic centers exhibit highest price sensitivity, constrained by outpatient reimbursement compression, while consolidated US health systems leverage volume scale for enterprise fleet standardization.
Supply Chain Analysis
Single-source vulnerability sits with niobium-titanium superconducting wire and liquid helium cryogen supply chains concentrated in Germany, the United States, and limited extraction geographies. MRI magnet fabrication draws from rare earth element processing in China, precision winding capabilities in Baden-Württemberg, and helium-3 recovery infrastructure in North American natural gas fields. Tariff exposure on detector-grade cadmium telluride semiconductors imported from Yangtze River Delta processing facilities threatens photon-counting CT production timelines. Distribution runs through OEM direct sales forces for hospital network accounts and specialized imaging equipment distributors serving ambulatory diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photon-counting detector technology is displacing energy-integrating architectures in premium CT installations, compressing upgrade cycles and reallocating R&D investment toward direct conversion material science and deep learning reconstruction pipelines.
For Market Incumbents: Hedge against helium supply constraint escalation by securing long-term cryogen service technician network contracts and accelerating closed-loop magnet cooling system deployment across US installed bases. Backward integration into niobium-titanium wire production or strategic offtake agreements with Baden-Württemberg precision engineering suppliers reduces input cost volatility exposure. Prioritize FDA software-as-a-medical-device clearance pathways for AI-enabled diagnostic algorithms to maintain pricing power in oncology imaging segments. For New Entrants and Emerging Players: Launch via refurbished equipment re-export channels through the Maharashtra-Gujarat corridor, targeting diagnostic center entrepreneurs in India expanding outpatient CT capacity away from tertiary hospital campuses. White-space opportunity concentrates in compact digital radiography suites for US ambulatory surgical centers and portable ultrasound formats for emergency department point-of-care workflows. Differentiate through GDPR-compliant hybrid edge-cloud processing architectures for European diagnostic center contracts. For Investors and Strategic Acquirers: The window for entry favors specialized detector material science firms with cadmium zinc telluride semiconductor capabilities and AI algorithm developers with validated regulatory submission track records. Long-term viability hinges on convergence between hardware detector innovation and software diagnostic enablement across the technology transition. Monitor EU AI Act conformity assessment timeline acceleration as the inflection signal for imaging AI valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Development | Direct conversion materials enable spectral imaging at dose levels previously unattainable with energy-integrating systems. |
| FDA Software-as-a-Medical-Device Clearance | Predicate device pathways accelerate commercialization timelines for AI lesion detection algorithms in US cancer centers. |
| Helium Cryogen Logistics Rebuild | Specialized service technician networks address field maintenance response time constraints from supply tightening. |
| Diagnostic Center Partnership | Greenfield installation demand for compact CT suites expands as patient volumes shift to outpatient settings. |
| GDPR-Compliant Cloud Architecture | Region-specific data residency requirements open consulting revenue for hybrid edge-cloud processing pipelines. |
Study Parameters
Document review covered FDA 510(k) and De Novo clearance databases, EU MDR technical documentation guidance, and hospital procurement contract filings, complemented by interviews with biomedical engineers, GPO contracts managers, hospital purchasing committee chairs, and diagnostic center operations directors. Secondary validation drew from CMS Medicare reimbursement data, NMPA registration records, and hyperscaler healthcare cloud capex disclosures. Bottom-up installed base modeling and top-down health system capital expenditure triangulation anchored market sizing.
Cross-reference between historical replacement cycle analysis and expert panel input on photon-counting detector adoption timelines shaped projection parameters across the analysis window. Segmentation dimensions modeled include product type, technology tier, end-user facility category, and clinical application area. CAGRs derived from equipment shipment volume trajectories, service contract renewal rates, and algorithm licensing revenue mix. Forecast inputs incorporated helium supply constraint scenarios and EU AI Act risk classification implementation pacing.
Regulatory pathway delays, rare earth magnet export restriction escalation, and diagnostic center reimbursement compression are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding technology substitution elasticities and health system consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Mobile Radiography Systems Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
Industrial X-Ray Machine Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
US Magnetic Resonance Imaging Coils Market
Medical Imaging
Mammography Workstation Market
Medical Imaging
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
Robotic X-Ray Scanner Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
Global Mobile Medical Imaging Services Market
Medical Imaging
PET Radiotracer Market