
 Europe Ultrasound Devices Market | 2026-2036
Europe Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ultrasound Devices Market Analysis
Software-defined imaging capabilities and subscription-based workflow tools are consolidating how European hospitals procure ultrasound systems. Siemens Healthineers leverages its digital platform architecture to anchor long-term service contracts across German university hospitals. Philips competes through integrated informatics that extend device utility beyond radiology into point-of-care settings. Canon Medical Systems differentiates by specializing in cardiovascular applications where AI-assisted quantification commands premium positioning.
Europe ultrasound devices are electronic diagnostic instruments that generate real-time anatomical images using piezoelectric transducers operating at frequencies between 2 and 18 megahertz, primarily serving clinical visualization and interventional guidance across cardiology, obstetrics, and abdominal examinations. Cart-based systems dominate installed base value in tertiary hospitals while handheld segments capture fastest volume growth as general practitioners and emergency clinicians adopt pocket-sized probes for bedside triage. Doppler technology leads functional revenue pools given its critical role in hemodynamic assessment, whereas contrast-enhanced applications concentrate margin in specialized oncology and hepatology workflows.
The EU Medical Device Regulation and CE marking framework administered by notified bodies in Germany, France, and the Netherlands shape product standards and market access timelines, with EMA guidance on contrast agents additionally influencing technology development pathways. National health technology assessment bodies in England, France, and Italy determine reimbursement eligibility that directly conditions hospital procurement cycles. Stakeholders must monitor evolving harmonized standards under the EU AI Act as machine-learning diagnostic features become embedded in next-generation platforms.
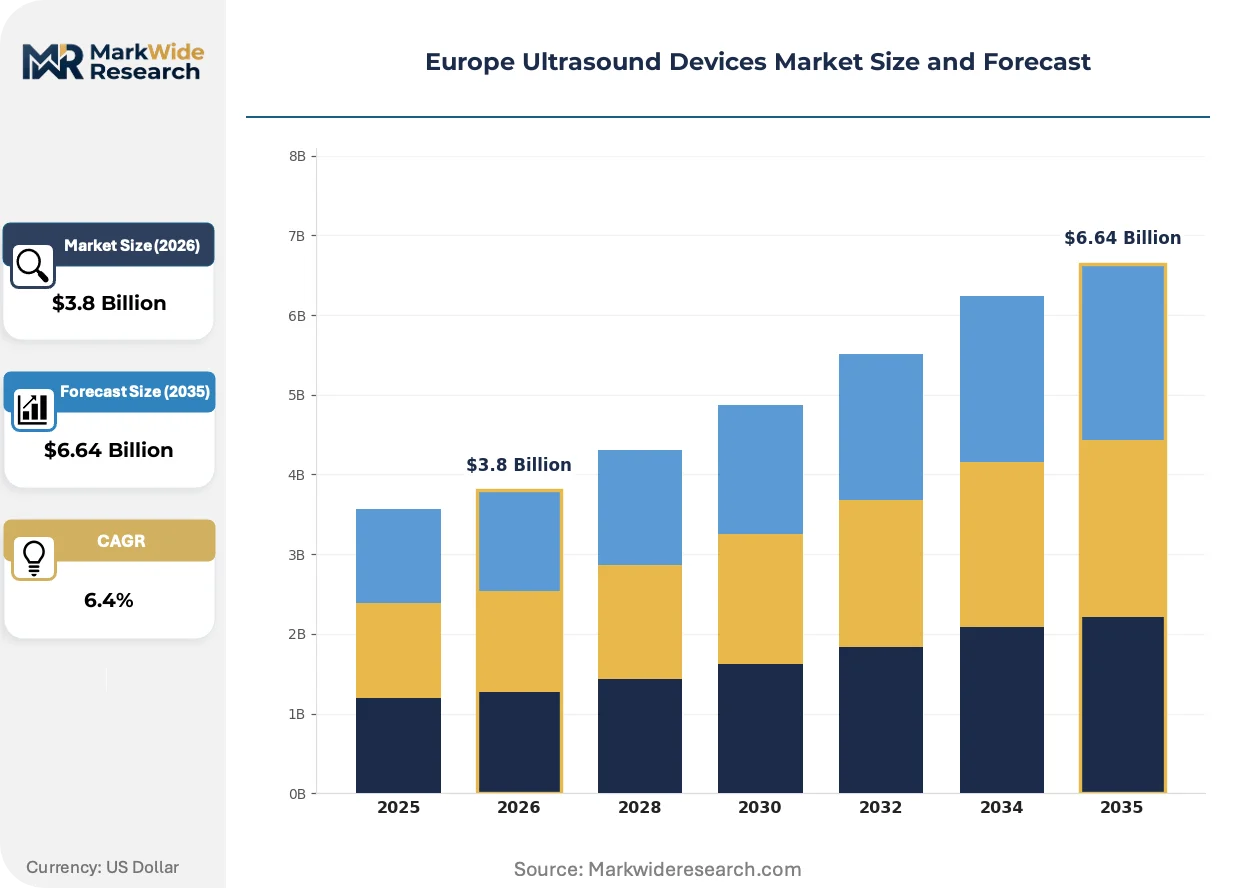
Market Dynamics
The EU Medical Device Regulation is compressing approval timelines while simultaneously elevating clinical evidence requirements, forcing manufacturers to restructure their regulatory affairs functions and clinical trial investments across the region.
Growth Catalysts
- Emergency department point-of-care adoption:Hospitals in Germany, France, and the United Kingdom are deploying handheld ultrasound systems for bedside triage, reducing reliance on centralized radiology departments.
- CE marking pathway harmonization:Notified bodies in Germany, France, and the Netherlands are streamlining conformity assessment procedures for software-defined imaging platforms.
- AI-assisted quantification:Machine learning algorithms embedded in cardiovascular and obstetric applications are expanding the addressable clinical user base beyond specialist radiologists.
Market Restraints
- Piezoelectric crystal supply concentration:Specialty transducer materials depend on concentrated Asian manufacturing bases, exposing European OEMs to input volatility and extended lead times.
- MDR clinical evidence escalation:The EU Medical Device Regulation mandates expanded post-market surveillance and clinical data collection, extending time-to-revenue for novel platform launches.
- CT and MRI substitution in oncology:Contrast-enhanced computed tomography and magnetic resonance imaging retain diagnostic preference for complex hepatic and oncologic staging in tertiary centers.
Strategic Opportunities
- Primary care underpenetration in Italy and Spain:General practitioner networks in Southern Europe maintain low ultrasound utilization rates relative to Northern European counterparts, presenting volume expansion potential for handheld probe manufacturers.
- EU AI Act compliance premium:Early alignment with harmonized standards for machine-learning diagnostic features creates differentiation positioning ahead of mandatory implementation timelines.
- Subscription-based workflow tools:Cloud-native image archiving and AI-powered reporting modules enable recurring revenue streams that decouple vendor economics from hardware replacement cycles.
Industry Challenges
- Clinical engineering workforce scarcity:Hospital biomedical departments face recruitment gaps for ultrasound system maintenance and probe repair, forcing reliance on manufacturer service contracts.
- Legacy PACS integration complexity:New software-defined platforms must interface with heterogeneous picture archiving systems installed across fragmented European hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ultrasound Devices Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Handheld, Portable, Cart-Based, Trolley-Based Technology: 2D, 3D, Doppler, Contrast-Enhanced Application: Cardiology, Obstetrics, Abdominal, Urology End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions |
| Companies Covered | Esaote SpA, Canon Medical Systems Corporation, GE Healthcare, Mindray Medical International Limited, Samsung Medison Co., Ltd., Koninklijke Philips N.V., FUJIFILM Holdings Corporation, Hitachi Medical Corporation, Siemens Healthineers AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ultrasound Devices Market Emerging Trajectories
Software-defined architectures are displacing hardware-centric platform designs across European imaging departments, compressing the traditional distinction between device procurement and digital service consumption.
Beamforming-on-chip technology is consolidating signal processing functions onto semiconductor substrates, reducing transducer head size and power consumption. Emergency clinicians and general practitioners are adopting these miniaturized probes for ambulatory and bedside applications. This consolidation is collapsing the price-performance gap between premium cart-based systems and handheld alternatives.
The EU AI Act is establishing conformity requirements for machine-learning diagnostic features embedded in next-generation platforms. Manufacturers must document algorithm training datasets and performance validation across diverse European patient populations. Cardiovascular quantification modules face the most stringent scrutiny given their role in therapeutic decision pathways.
Hospital procurement committees are unbundling hardware acquisition from software licensing and maintenance services. German university hospitals pioneered this separation, and French and English hospital networks are replicating the model. This reconfiguration shifts vendor relationships toward multi-year platform subscriptions rather than discrete capital equipment transactions.
Europe Ultrasound Devices Market Segmentation
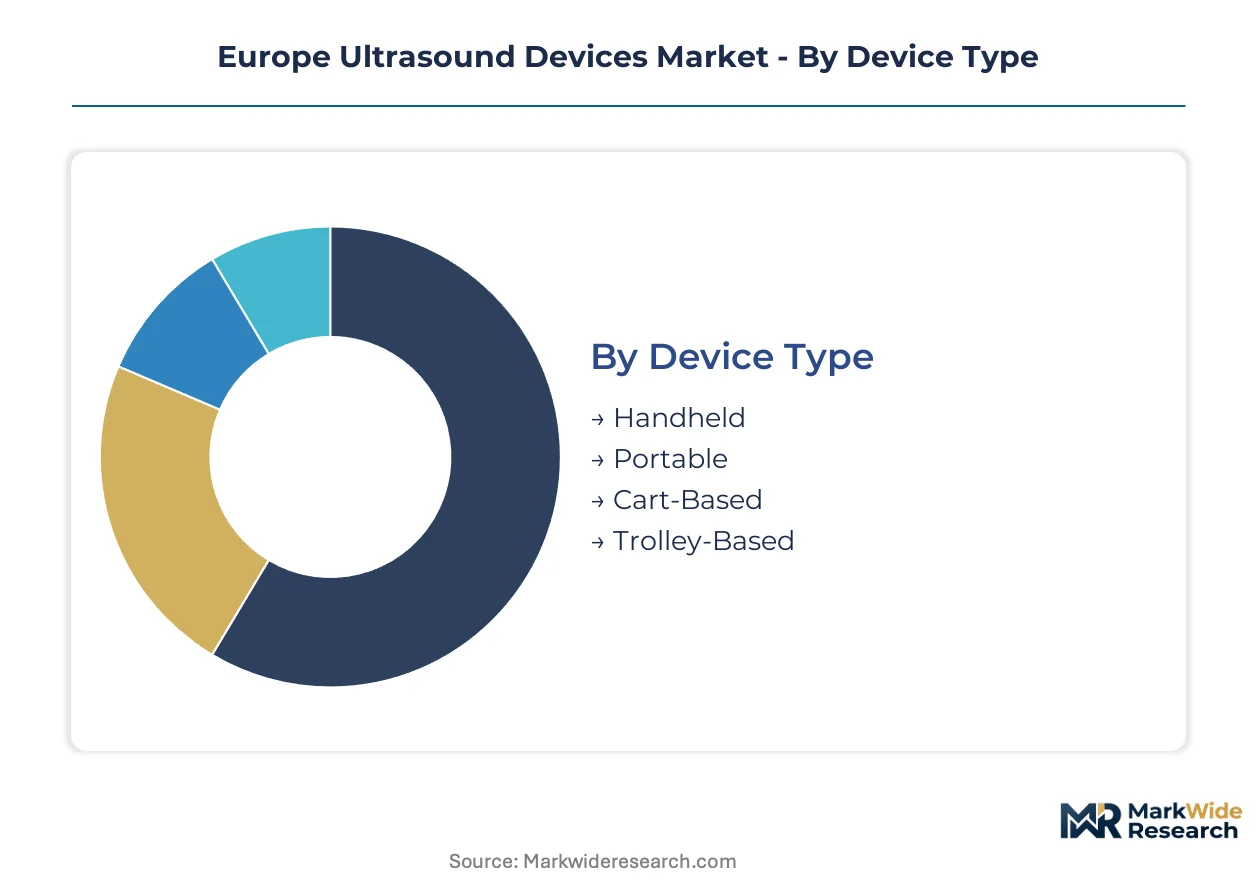
Ultrasound device segmentation in Europe reflects divergent procurement economics across acute care networks and ambulatory settings. Hardware form factors, imaging modalities, clinical applications, and facility types each structure distinct competitive arenas with unique margin profiles and regulatory pathways.
Device Type:
Cart-based systems command premium pricing in German and French university hospitals while handheld units capture volume expansion in primary care networks.
- Cart-Based:Full-platform systems integrate multi-probe connectivity and advanced beamforming processors for complex interventional guidance. German tertiary centers prioritize these configurations for cardiovascular and abdominal suites, though extended MDR approval timelines delay fleet refresh cycles.
- Handheld:Smartphone-connected probes and dedicated pocket units operate at 2-10 MHz with simplified interfaces for bedside triage. Emergency departments in the United Kingdom and France deploy these for rapid cardiac and lung assessment, bypassing radiology queue bottlenecks.
- Portable:Laptop-sized systems balance image quality against mobility for regional hospital networks and mobile screening programs.
- Trolley-Based:Mid-range configurations serve diagnostic centers in Italy and Spain with essential Doppler and 2D capabilities at lower capital commitment.
Mature deployment sits with cart-based platforms in Northern European tertiary networks. Newer deployment is concentrated in handheld segments across emergency and primary care settings.
Technology:
Functional imaging modalities stratify by clinical decision criticality and reimbursement eligibility across national health technology assessment frameworks.
- Doppler:Spectral and color flow mapping enables hemodynamic quantification for valvular assessment and vascular surveillance. French and English cardiology departments mandate Doppler capability for therapeutic planning, creating sustained replacement demand despite hardware commoditization.
- 2D:Conventional grayscale imaging remains the workhorse modality for abdominal and obstetric screening across high-volume diagnostic centers.
- 3D:Volume rendering supports fetal anomaly detection and complex cardiac structural analysis in specialized maternal-fetal medicine units.
- Contrast-Enhanced:Microbubble agent compatibility enables perfusion imaging for hepatic lesion characterization and oncology staging, concentrated in tertiary oncology centers with pharmacy infrastructure for contrast administration.
Revenue concentration follows Doppler-equipped platforms in cardiology workflows. Steepest expansion trajectory belongs to contrast-enhanced applications as EMA guidance stabilizes agent approval pathways.
Application:
Clinical use cases determine probe frequency selection, software module licensing, and service contract structures.
- Cardiology:Transthoracic and transesophageal protocols demand phased-array transducers at 2-5 MHz with dedicated quantification packages. German hospital networks invest heavily here given statutory reimbursement for echocardiography in heart failure management pathways.
- Obstetrics:First-trimester screening and fetal biometric measurement utilize 3-7 MHz curvilinear probes with automated measurement algorithms. French maternity units drive standardization through national quality assurance programs.
- Abdominal:Liver, renal, and gallbladder imaging supports generalist radiology across diagnostic centers in Italy and Spain.
- Urology:Transrectal and renal protocols serve prostate screening and nephrology departments with specialized endocavity probe requirements.
Procurement volume concentrates in obstetrics across national screening programs. Premium positioning is migrating toward cardiology as AI-assisted quantification commands higher software licensing fees.
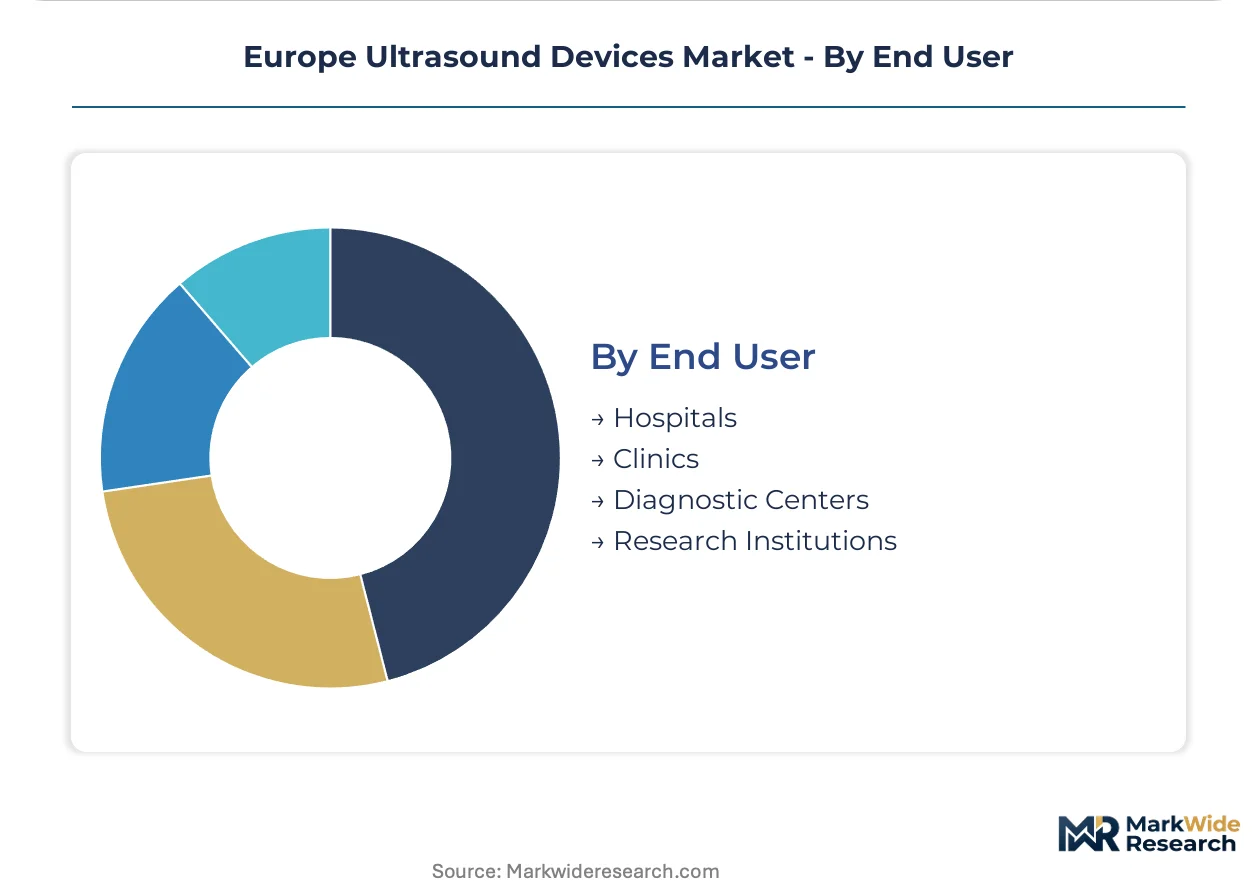
End User:
Facility type structures capital allocation cycles, maintenance outsourcing preferences, and digital integration requirements.
- Hospitals:Acute care networks in Germany, France, and the United Kingdom operate mixed fleets across radiology, cardiology, and point-of-care departments. These buyers negotiate enterprise service agreements with vendors and prioritize PACS interoperability.
- Clinics:General practitioner networks in Southern Europe represent underpenetrated volume for handheld probe manufacturers.
- Diagnostic Centers:Independent imaging facilities in England and Italy focus on throughput optimization and rapid report turnaround.
- Research Institutions:University hospitals and clinical trial sites drive early adoption of experimental modes including shear-wave elastography and photoacoustic hybrid systems.
Installed base value aggregates in hospital networks with multi-department deployments. Fastest volume gains are emerging in clinic settings as handheld technology collapses barriers to generalist adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European ultrasound device production concentrates in German and Dutch manufacturing clusters, while consumption distributes across hospital networks in Germany, France, the United Kingdom, Italy, and Spain with divergent procurement cycles.
Germany
University hospitals in Berlin and Munich drive cart-based system replacements for cardiovascular and interventional suites. The EU Medical Device Regulation administered by BfArM shapes approval timelines for software-defined platforms. The Baden-Württemberg medical technology corridor anchors Siemens Healthineers' service contract expansion across tertiary networks.
France
French maternity units and emergency departments generate sustained demand for obstetric and point-of-care systems. ANSM oversight of CE marking conformity assessments influences market access for handheld probe manufacturers. The Paris-Saclay cluster concentrates AI-assisted quantification development for cardiology applications.
United Kingdom
NHS England procurement frameworks prioritize PACS-integrated systems for radiology and point-of-care deployment. NICE health technology assessments determine reimbursement eligibility for contrast-enhanced applications. London hospital networks lead enterprise service agreement negotiations with vendors.
Italy
General practitioner networks in Lombardy and Emilia-Romagna represent underpenetrated volume for handheld ultrasound adoption. The Italian Medicines Agency implements EU MDR post-market surveillance requirements for device manufacturers. Milan-based diagnostic centers drive mid-range trolley system procurement for abdominal imaging workflows.
Spain
Regional health services in Catalonia and Madrid modernize imaging fleets with portable systems for mobile screening programs. The Spanish Agency for Medicines and Health Products coordinates notified body interactions for CE marking renewals. Barcelona hospital networks pilot subscription-based workflow tool implementations.
Europe Ultrasound Devices Market Vendor Landscape
Top-tier vendors anchor university hospital procurement committees across Northern Europe, while mid-tier specialists and Asian manufacturers compete on price-performance for clinic and diagnostic center segments. The vendor base stratifies across three tiers: integrated imaging conglomerates with digital platform architectures, cardiovascular application specialists commanding premium software licensing, and handheld probe disruptors collapsing barriers to generalist adoption. M&A activity concentrates on AI algorithm developers and cloud-native workflow tool providers. Strategic partnerships between device manufacturers and PACS vendors accelerate interoperability certification.
Within the integrated conglomerate tier, Siemens Healthineers AG and Koninklijke Philips N.V. exemplify platform-centric positioning through long-term service contract structures. Canon Medical Systems Corporation occupies a specialist position in cardiovascular quantification modules where AI-assisted features command premium positioning. Esaote SpA represents the European mid-tier archetype with focused regional penetration in Southern European diagnostic networks. These three anchors illustrate divergent competitive vectors: digital ecosystem lock-in, clinical application depth, and geographic specialization.
| Leading Market Players |
|---|
| Esaote SpA |
| Canon Medical Systems Corporation |
| GE Healthcare |
| Mindray Medical International Limited |
| Samsung Medison Co., Ltd. |
| Koninklijke Philips N.V. |
| FUJIFILM Holdings Corporation |
| Hitachi Medical Corporation |
| Siemens Healthineers AG |
| Others |
Supply Flow & Price Mechanics
Family-owned German transducer specialists anchor tier-one probe manufacturing, constraining supply elasticity and preserving pricing discipline across cart-based system negotiations. Their concentrated ownership patterns limit capacity expansion responsiveness, translating input scarcity into sustained premium positioning for multi-frequency probe arrays.
Pricing Analysis
Margin tightening in handheld segments reflects Asian probe manufacturer cost compression as Mindray and Samsung Medison scale production. Three-tier pricing structure across premium, standard, and economy levels stratifies by CE marking tier and after-sales service bundling. Pricing pressure stems from NHS England procurement frameworks demanding multi-year total-cost-of-ownership guarantees. Diagnostic centers in Italy and Spain exhibit highest price sensitivity, while German university hospitals prioritize PACS interoperability over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle German and French tertiary network demand, bypassing distributor markups for enterprise service agreements. Piezoelectric crystal production concentrates in China, Japan, and South Korea, with specialty ceramic substrates drawn from concentrated Asian manufacturing bases. Single-source vulnerability sits with PZT ceramic suppliers facing export license volatility. Distribution runs through authorized service organizations for probe repair and calibration certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
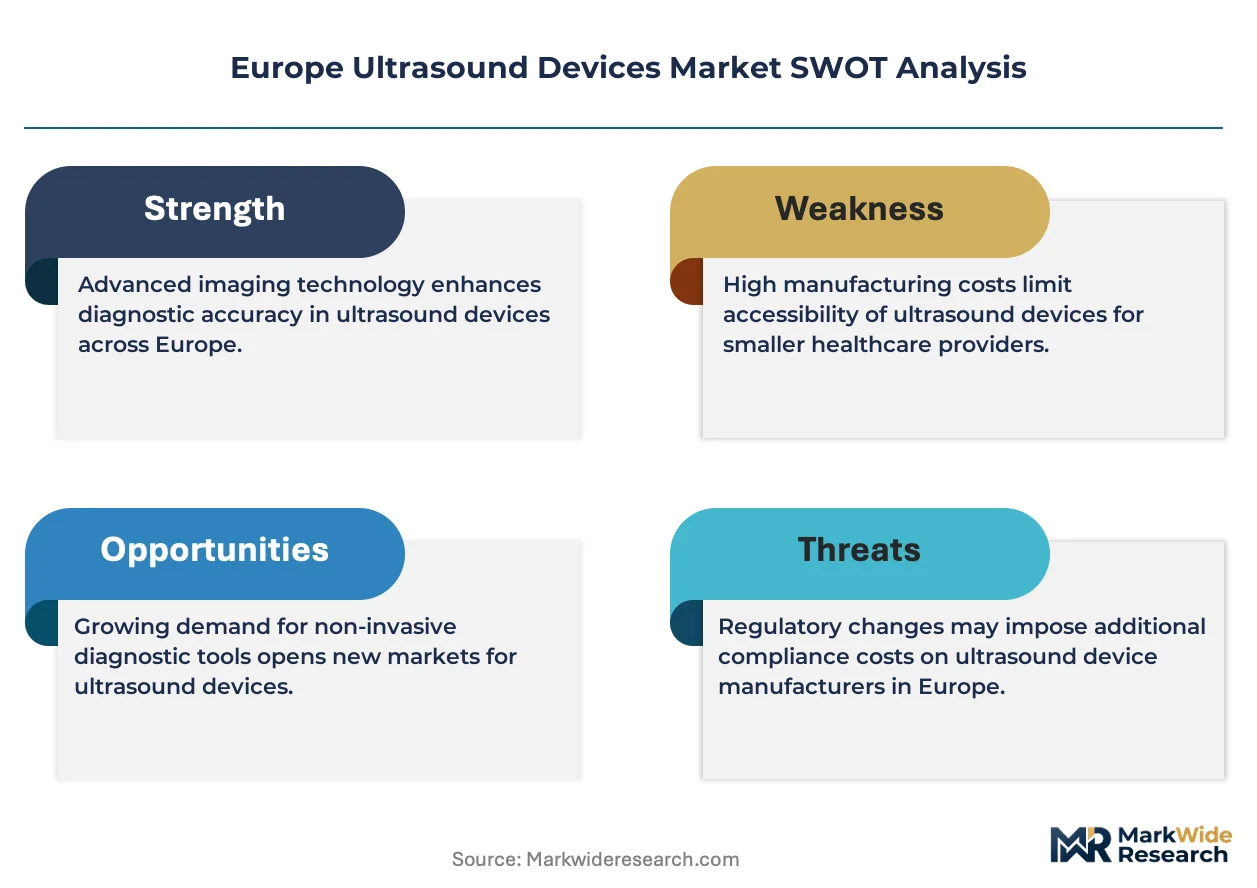
Specialty transducer material scarcity props pricing power for established probe manufacturers, constraining volume expansion for handheld disruptors dependent on outsourced crystal supply.
For Market Incumbents: Deploy backward integration into piezoelectric ceramic production to secure input supply against Asian export restrictions. Anchor long-term service contracts through software-defined platform lock-in, defending against handheld probe substitution in emergency department triage workflows. For New Entrants and Emerging Players: The mid-tier price-point gap between premium cart-based systems and economy handheld probes offers white-space entry for laptop-sized portable configurations. Target general practitioner networks in Southern Europe with simplified Doppler packages. Pursue ANSM fast-track CE marking for cardiovascular AI modules as differentiation anchor. For Investors and Strategic Acquirers: Distressed-cycle entries favor AI algorithm developers in Paris-Saclay and Cambridge clusters facing extended MDR approval cash burn. Long-term viability hinges on EU AI Act compliance certification ahead of mandatory implementation. Watch EMA contrast agent guidance stabilization as inflection signal for oncology application premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR clinical evidence requirements compress approval timelines for software-defined platforms. |
| Hospital System Partnership | NHS England enterprise agreements lock in multi-year PACS-integrated deployments across London networks. |
| Software Companion Development | Cloud-native AI quantification modules enable recurring revenue decoupled from hardware cycles. |
| Reimbursement Strategy | NICE health technology assessments determine eligibility for contrast-enhanced oncology workflows. |
| Backward Integration | In-house piezoelectric crystal production mitigates Asian supply concentration risk for probe arrays. |
Methodological Framework
Multi-period observation of hospital procurement cycles and notified body approval timelines anchored the trend analysis, supplemented by interviews with biomedical engineering directors, hospital purchasing committee chairs, GPO contracts managers, and ultrasound system service technicians. Secondary validation drew from EMA medical device guidance documents, BfArM MDR implementation reports, NHS procurement framework disclosures, and ANSM conformity assessment databases. Bottom-up installed base modeling triangulated against top-down vendor revenue segmentation.
Segment-weighting across device type, technology modality, clinical application, and facility tier structured the analytical framework. CAGRs were derived from logistic diffusion curves fitted to replacement cycle data and point-of-care adoption trajectories. Forecast inputs incorporated EU AI Act implementation phasing, MDR post-market surveillance cost escalation, and handheld probe battery efficiency improvement curves.
Inputs from hospital procurement databases and notified body approval registries were available through the study window; gaps in real-time service contract pricing introduce uncertainty bands around vendor revenue share estimates. Forecasts reflect documented assumptions regarding MDR transition completion and AI diagnostic feature reimbursement eligibility. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Surgical Visualization Products Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Spinal Needles Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
Electrosurgical Devices Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Digital Radiology Devices Market
Medical Devices
Tissue Embedding Center Market
Medical Devices
Home-Use Water Flosser Market
Medical Devices
Pacemaker Devices Market
Medical Devices
Global Electrophysiology Devices Market
Medical Devices
Global Body Contouring Devices Market
Medical Devices
Global Glucometer Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market