
 Tissue Culture Incubator Market | 2026-2036
Tissue Culture Incubator Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Culture Incubator Market Analytics
Modular platform configurations is broadening buyer choice in the tissue culture incubator landscape. Thermo Fisher Scientific leverages its vertical integration across temperature control and contamination management subsystems. Eppendorf AG anchors its position through precision engineering in benchtop CO2 incubator lines. Sartorius AG competes on digital connectivity platforms that integrate incubation data with downstream bioprocessing analytics.
A tissue culture incubator is a controlled-environment chamber that maintains temperature, humidity, and gas composition—typically 37°C, 95% relative humidity, and 5% CO2—to support sterile cell and tissue propagation. These units serve as foundational infrastructure for biopharmaceutical drug development, regenerative medicine research, and agricultural micropropagation programs. CO2 incubators command the largest installed base due to their centrality in mammalian cell culture workflows, while automated systems represent the fastest-expanding technology segment as laboratories pursue reduced manual intervention and improved reproducibility. Walk-in incubators occupy a mature niche serving industrial-scale seed culture operations where throughput requirements exceed standard chamber capacities.
The FDA enforces Current Good Manufacturing Practice requirements that dictate environmental monitoring and validation protocols for incubators used in therapeutic cell production. EMA's Annex 1 guidelines on sterile medicinal products directly shape European demand for closed-system incubator designs with integrated contamination barriers. ISO 14698 standards for cleanroom biocontamination control further constrain product specifications across export markets. Stakeholders must monitor evolving alignment between digital control capabilities and regulatory data-integrity requirements as audit trails become non-negotiable for commercial manufacturing approvals.
Market Dynamics
Stringent contamination control mandates from the FDA and EMA are compressing product lifecycles and forcing rapid upgrades to closed-system architectures across biopharmaceutical manufacturing workflows.
Growth Catalysts
- Annex 1 sterile product guidelines:EMA's updated requirements for barrier isolation in cell therapy production are accelerating replacement demand for legacy open-chamber designs across European contract manufacturing organizations.
- Cell therapy commercialization:Autologous and allogeneic CAR-T manufacturing scale-up is creating dedicated incubator procurement pipelines at centralized cleanroom facilities in the United States, Germany, and China.
- Automated environmental monitoring:Real-time CO2, temperature, and humidity sensing with cloud-based audit trails is becoming standard specification for IND-enabling studies and Phase I/II manufacturing suites.
Market Restraints
- Stainless steel and copper price volatility:Chamber fabrication costs fluctuate with commodity markets, squeezing margin structures for equipment manufacturers serving price-sensitive academic buyers.
- HEPA filtration supply concentration:Critical filter media production clusters in Germany and Japan, creating vulnerability to export licensing delays and extended lead times for validated components.
- Legacy equipment compatibility:Existing building management systems in older research facilities lack digital interfaces, forcing costly infrastructure retrofits to support connected incubator platforms.
Strategic Opportunities
- India's biologics manufacturing expansion:CDSCO's streamlined medical device registration pathways and PLI scheme incentives are attracting contract manufacturers seeking cost-competitive incubator deployment at scale.
- AI-driven predictive maintenance:Machine learning algorithms analyzing sensor telemetry can preempt contamination events and reduce unplanned downtime in high-value cell culture campaigns.
- Single-use incubation chambers:Disposable polymer inserts for specific cell therapy applications eliminate cross-contamination risks and reduce validation burden between patient-specific batches.
Industry Challenges
- Cleanroom technician scarcity:Qualified personnel for aseptic handling and environmental monitoring are in short supply, limiting operational throughput at new manufacturing sites.
- IQ/OQ/PQ validation timelines:Installation and operational qualification protocols for GMP-grade incubators extend 12-18 months, delaying revenue recognition for equipment vendors and facility operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Culture Incubator Market |
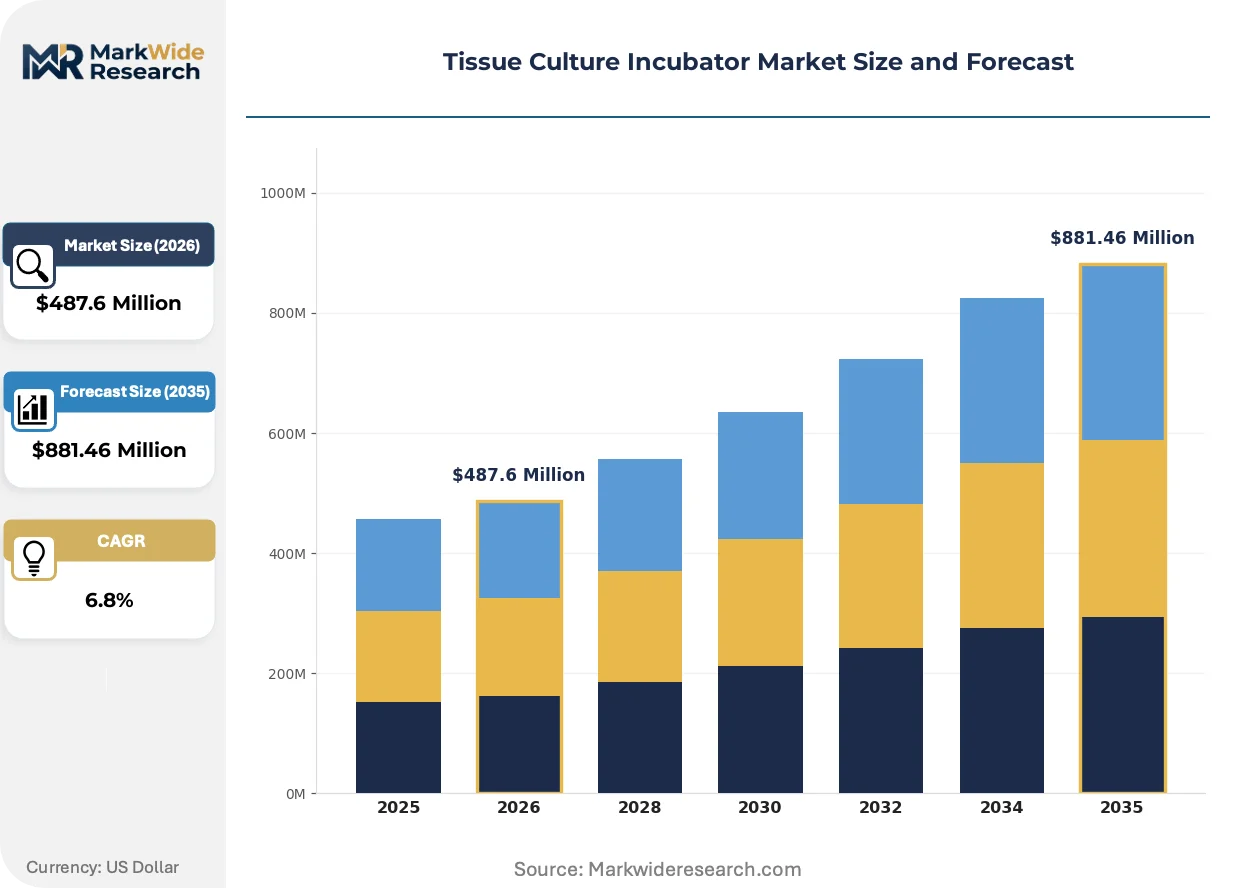
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Incubators, Walk-in Incubators, CO2 Incubators, R&d Incubators End User: Research Laboratories, Biopharmaceutical Companies, Academic Institutions, Agriculture Technology: Analog Control, Digital Control, Automated Systems, Hybrid Systems Application: Cell Culture, Micropropagation, Cryopreservation, Tissue Engineering |
| Companies Covered | Thermo Fisher Scientific Inc., Eppendorf AG, PHC Holdings Corporation, BINDER GmbH, Memmert GmbH + Co. KG, Sheldon Manufacturing Inc., Sartorius AG, Merck KGaA, NuAire, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Culture Incubator Market Evolving Landscape
Digital integration and contamination prevention technologies are converging to redefine equipment specifications across pharmaceutical and academic research environments. Vendors are racing to embed predictive capabilities and closed-system architectures that preempt regulatory rejection.
Hypoxia-capable CO2 incubators with precise O2 control down to 0.5% are overtaking standard atmospheric models in stem cell and tumor spheroid applications. Contract research organizations running 3D cell culture workflows specify these units for 40% of new incubator procurement in North America. The shift is compressing demand for basic CO2-only chambers in mid-tier research segments.
EMA's Annex 1 revision on sterile medicinal products now mandates continuous environmental monitoring with data integrity safeguards for all aseptic processing equipment. European manufacturers must deploy incubators with built-in particle counters and automated alarm systems to maintain manufacturing authorization. This regulatory pressure is accelerating replacement cycles for equipment installed before 2020 across Germany, France, and Switzerland.
Equipment-as-a-service contracts with bundled validation and maintenance support are displacing traditional capital purchase models among emerging biotechs with constrained balance sheets. Leasing structures reduce upfront cash requirements and transfer compliance risk to vendors. This financing innovation is most visible in the United States, where venture-backed cell therapy startups represent the fastest-growing buyer segment.
Tissue Culture Incubator Market Segmentation
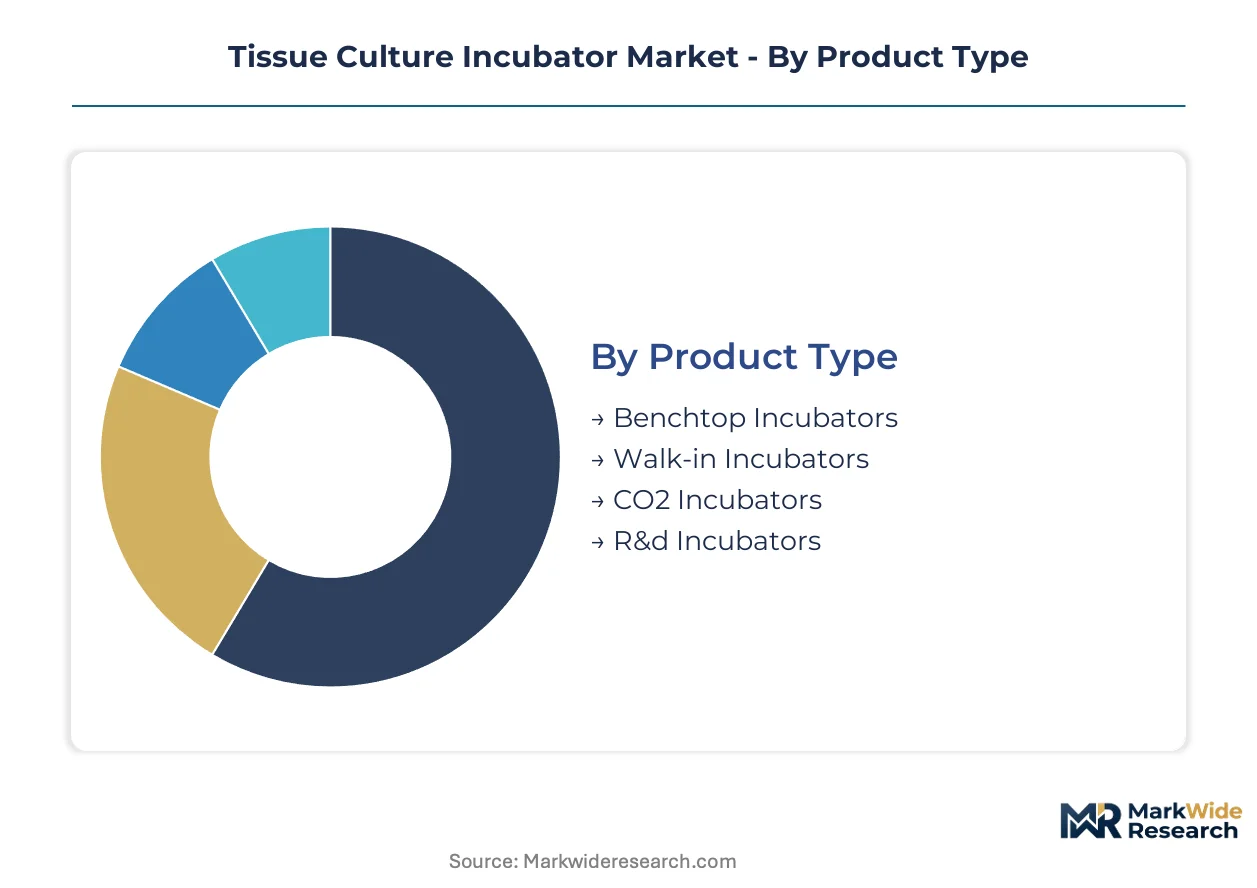
Equipment specifications diverge sharply across research and manufacturing workflows, with regulatory compliance requirements forcing distinct procurement patterns. Segmentation reveals how contamination control mandates and automation priorities reshape buyer decisions across facility types.
Product Type:
Replacement cycles accelerate where EMA Annex 1 and FDA cGMP standards render legacy open-chamber designs non-compliant, compressing typical ten-year equipment lifespans.
- CO2 Incubators:These units maintain precise 5% carbon dioxide concentration, 37°C temperature, and 95% relative humidity through sealed stainless-steel chambers with HEPA filtration. Biopharmaceutical companies in the United States, Germany, and China prioritize these for mammalian cell culture workflows under FDA and EMA sterile product guidelines.
- Benchtop Incubators:Compact footprint units with capacity for 50-200 liters serve space-constrained academic laboratories and startup biotechs. Research laboratories in Boston and San Francisco specify these for high-throughput screening where capital budgets limit walk-in or automated alternatives.
- Walk-in Incubators:Industrial-scale chambers exceeding 1,000-liter capacity support seed culture operations for commercial micropropagation.
- R&D Incubators:Flexible configurations with modular shelving and rapid parameter adjustment serve exploratory protocols without GMP validation requirements.
CO2 Incubators sits at the top of the volume ranking, with Automated Systems climbing the fastest.
End User:
Customer procurement authority varies with funding source and regulatory exposure, creating distinct price sensitivities and specification rigor across segments.
- Biopharmaceutical Companies:Commercial manufacturers require GMP-validated equipment with 21 CFR Part 11-compliant data logging for IND-enabling and Phase I/II production. These buyers in Germany and Switzerland face EMA Annex 1 mandates for continuous environmental monitoring and closed-system architectures.
- Research Laboratories:CROs and government facilities prioritize throughput and reproducibility over validation documentation. Contract research organizations running 3D cell culture workflows in North America now specify hypoxia-capable units for 40% of new incubator procurement.
- Academic Institutions:University core facilities balance equipment cost against multi-user accessibility and training burden.
- Agriculture:Commercial nurseries and seed companies deploy walk-in units for clonal propagation of high-value crops.
Biopharmaceutical Companies command the premium tier by validation requirement, while Research Laboratories expand most quickly by unit volume.
Technology:
Control system architecture determines integration capability with building management platforms and downstream analytics pipelines.
- Automated Systems:Robotic sample handling, automated decontamination cycles, and cloud-connected telemetry reduce manual intervention in high-value cell therapy manufacturing. These systems are gaining share fastest as cleanroom technician scarcity limits operational throughput at new manufacturing sites in the United States and China.
- Digital Control:Microprocessor-based PID regulation with touchscreen interfaces and USB data export serves regulated research environments. Academic medical centers in Germany and France specify these for preclinical studies requiring audit trails without full GMP automation.
- Analog Control:Dial-based temperature and CO2 regulation persists in legacy installations and budget-constrained settings.
- Hybrid Systems:Digital sensing with analog override capabilities bridge transition periods during facility upgrades.
Digital Control holds the largest installed base, with Automated Systems showing the steepest expansion trajectory.
Application:
Biological sample type dictates gas composition precision, contamination tolerance, and throughput requirements across equipment specifications.
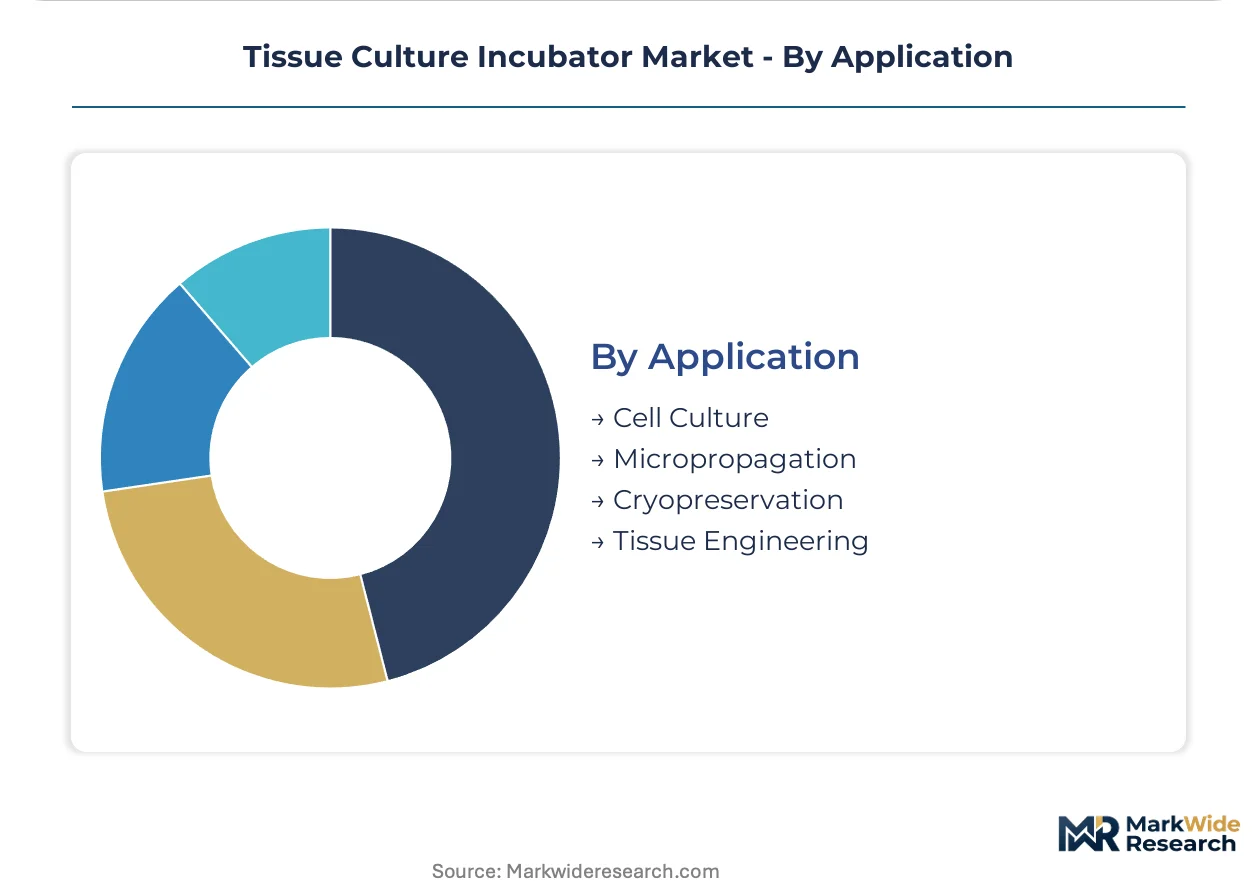
- Cell Culture:Mammalian and insect cell propagation demands strict 37°C temperature stability, 5% CO2, and ISO 5 air quality through HEPA filtration. Autologous and allogeneic CAR-T manufacturing scale-up in centralized United States and China facilities creates dedicated procurement pipelines for GMP-grade incubators.
- Tissue Engineering:Scaffold-based constructs and organoid development require hypoxia capabilities down to 0.5% O2 for stem cell maintenance. Research programs in Germany and Switzerland specify these parameters for tumor spheroid and regenerative medicine applications.
- Micropropagation:Plant tissue culture operates across wider temperature ranges with lower humidity requirements than mammalian systems.
- Cryopreservation:Controlled-rate freezing applications integrate incubation stages within broader cold-chain workflows.
Cell Culture dominates by revenue concentration, with Tissue Engineering gaining share fastest on regenerative medicine investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The tissue culture incubator industry traces its commercial origins to post-war German precision engineering and mid-century American laboratory equipment manufacturing, with both regions establishing foundational production capabilities that persist in today's concentrated supply landscape.
United States
Cell therapy manufacturing scale-up drives procurement across Greater Boston and San Francisco Bay Area biotech clusters. FDA cGMP requirements for IND-enabling studies mandate 21 CFR Part 11-compliant data logging systems. Cambridge, Massachusetts hosts centralized CAR-T production facilities where automated incubation platforms reduce cleanroom technician dependency.
Germany
EMA Annex 1 sterile product guidelines accelerate replacement demand for legacy open-chamber designs across contract manufacturing organizations. BfArM enforcement of barrier isolation standards elevates specifications for closed-system architectures. Heidelberg and Munich research corridors concentrate demand for hypoxia-capable units in regenerative medicine applications.
China
NMPA biologics approval pathway reforms attract domestic CDMO investment in incubator infrastructure. Dual carbon goals pressure manufacturers toward energy-efficient temperature control systems. Shanghai and Suzhou biotech parks deploy walk-in incubators for industrial-scale seed culture operations serving export markets.
Switzerland
Swissmedic manufacturing authorization requirements enforce continuous environmental monitoring with automated alarm systems. Basel pharmaceutical hub demands GMP-validated equipment for commercial cell therapy production. Geneva and Zurich academic medical centers specify digital control platforms for preclinical audit trails.
India
CDSCO streamlined medical device registration and PLI scheme incentives attract contract manufacturers seeking cost-competitive deployment. BIS standards adoption accelerates for export-oriented biologics facilities. Hyderabad and Bangalore biotech corridors expand incubator procurement for biosimilar development programs.
Tissue Culture Incubator Market Competitive Landscape
The competitive structure tilts toward diversified laboratory conglomerates with captive temperature control and contamination management capabilities. Three strategic archetypes dominate: precision-engineered German fabricators with heritage in thermal regulation, diversified life science conglomerates spanning upstream bioprocessing, and specialized cleanroom equipment providers with GMP validation expertise. M&A activity concentrates on digital connectivity platforms and automated sample handling capabilities, while capacity expansion targets India's emerging CDMO corridor.
Among diversified conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA exemplify the integrated life science archetype spanning reagents through equipment. Eppendorf AG represents the precision-engineering specialist position anchored in benchtop CO2 incubator lines. Sartorius AG occupies a position within the bioprocessing-integrated tier, with digital connectivity platforms linking incubation data to downstream analytics pipelines.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Eppendorf AG |
| PHC Holdings Corporation |
| BINDER GmbH |
| Memmert GmbH + Co. KG |
| Sheldon Manufacturing Inc. |
| Sartorius AG |
| Merck KGaA |
| NuAire, Inc. |
| Others |
Value Network & Pricing Analysis
EMA Annex 1 sterile product guidelines gate both qualified supply and premium-tier pricing access, as only manufacturers with validated HEPA filtration sourcing and closed-system fabrication capabilities can serve biopharmaceutical contract manufacturing organizations. Stainless steel and copper price volatility feeds directly into equipment cost structures, compressing margins for vendors serving academic buyers while elevating entry barriers for new fabricators.
Pricing Analysis
Equipment-as-a-service contracts with bundled validation support now anchor the dominant pricing structure, displacing traditional capital purchase models among venture-backed cell therapy startups. Price differentiation hinges on GMP certification tier and after-sales service bundling, with 21 CFR Part 11-compliant data logging commanding substantial premiums over research-grade configurations. Cost compression in the academic segment is intensifying because stainless steel and copper commodity fluctuations squeeze fixed-budget procurement. University core facilities exhibit the highest price sensitivity, while centralized CAR-T manufacturing sites in the United States and Germany demonstrate the least.
Supply Chain Analysis
Freight cost escalation from German and Japanese HEPA filtration clusters to global incubator assembly sites is reshaping component sourcing strategies for equipment manufacturers. Critical filter media production concentrates in Germany and Japan, while stainless steel chamber fabrication draws from Chinese and South Korean metalworking hubs. Single-source vulnerability in validated HEPA supply creates exposure to export licensing delays. Distribution runs through authorized dealer networks for GMP-grade equipment and direct e-commerce channels for research-tier sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on the shift toward automated platforms with predictive maintenance capabilities, which reduce service cost intensity while commanding premium positioning. Equipment vendors capturing this transition will outpace competitors locked in commodity chamber fabrication.
For Market Incumbents: Anticipate displacement pressure from emerging Asian fabricators with cost-advantaged stainless steel sourcing by deepening captive control over HEPA filtration supply chains. Prioritize certification investment for EMA Annex 1 compliance ahead of European contract manufacturing organization procurement cycles. Defensive consolidation around digital connectivity platforms will preempt software-native entrants from capturing bioprocessing data integration value.
For New Entrants and Emerging Players: Begin with India's CDSCO-registered contract manufacturing corridor, where PLI scheme incentives and streamlined medical device pathways reduce incumbent brand loyalty. Single-use incubation chambers for patient-specific cell therapy batches represent the most penetrable white space, as validation burden reduction commands urgent buyer attention. A go-to-market angle anchored in disposable polymer inserts bypasses the stainless steel commodity exposure squeezing established vendors.
For Investors and Strategic Acquirers: Valuations sit cheapest among precision-engineered German fabricators with heritage thermal regulation capabilities but lagging digital platform integration. Long-term viability over the coming decade favors vendors with automated sample handling and cloud-connected telemetry, as cleanroom technician scarcity accelerates replacement demand. The signal to watch is NMPA biologics approval volume in China, which will indicate whether domestic CDMO investment translates into sustained incubator procurement pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-System Architecture Development | EMA Annex 1 compliance secures manufacturing authorization for European biopharmaceutical clients. |
| Predictive Maintenance Platform Launch | Machine learning telemetry preempts contamination events in high-value CAR-T culture campaigns. |
| Single-Use Chamber Product Line | Disposable inserts eliminate cross-contamination risks between patient-specific autologous batches. |
| India Manufacturing Footprint Expansion | CDSCO registration and PLI incentives attract cost-competitive contract manufacturing deployment. |
| Cloud-Connected Data Integration | 21 CFR Part 11 audit trails satisfy FDA requirements for IND-enabling study documentation. |
Research Methodology
Coverage spans the United States, Germany, China, and India, with primary inputs from each region combining structured interviews with biopharmaceutical manufacturing executives, cleanroom facility managers, regulatory affairs specialists, and academic core facility directors. Secondary validation draws from FDA 510(k) filings, EMA manufacturing authorization databases, NMPA biologics approval records, and CDSCO medical device registration data. Bottom-up equipment shipment analysis and top-down biopharmaceutical capital expenditure triangulation anchor volume estimates.
Rate-of-change decomposition across the analysis window separates replacement cycle acceleration from net new facility expansion, with segmentation modeling across product type, end user, technology tier, and application area. CAGRs derive from fitted growth curves applied to equipment procurement pipelines linked to cell therapy manufacturing scale-up announcements. Hypoxia capability adoption rates and automated platform penetration serve as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt commodity price shocks in stainless steel and copper, geopolitical disruption to German-Japanese HEPA filtration supply chains, and regulatory timeline delays for novel cell therapy approvals. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Radiation Therapy Equipment Market
Medical Equipment
Automated Dialysis Concentrated Production Systems Market
Medical Equipment
Global Vacuum Mixing Devices Market
Medical Equipment
MRI Transport Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
Photorejuvenation Equipment Market
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
Brain Mapping Instruments Market
Medical Equipment
Europe Medical Device Reprocessing Market
Medical Equipment
Global Medical Device Reprocessing Market
Medical Equipment
Chile Radiotherapy Market
Medical Equipment
Medical Whirlpool Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
Asia-Pacific Nuclear Medicine Equipment Market
Medical Equipment
Operating Table Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market