
 Neurostimulation Devices Market | 2026-2036
Neurostimulation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Neurostimulation Devices Market Analysis
CE marking under the EU Medical Device Regulation is redrawing competitive access across European markets, raising clinical evidence requirements for implantable neuromodulation systems. Medtronic leverages decades of spinal cord stimulation expertise to sustain manufacturing scale across multiple continents. NeuroPace specializes in responsive neurostimulation for epilepsy, anchoring its position through proprietary seizure detection algorithms. Abbott differentiates with directional lead technology, competing on precision targeting in deep brain stimulation procedures.
Neurostimulation devices deliver targeted electrical impulses to neural tissue via implanted or external systems, typically operating at pulse frequencies between 2 Hz and 10,000 Hz to modulate pain signaling or restore motor function. These systems incorporate biocompatible titanium or platinum-iridium electrode arrays connected to pulse generators powered by lithium-ion cells or inductive charging. Spinal cord stimulators occupy the largest revenue pool in pain management, while deep brain stimulators command premium pricing in movement disorders. Implantable rechargeable devices represent the fastest-growing technology segment as patients seek reduced surgical replacement cycles.
The FDA's breakthrough device program and the EU MDR's clinical evaluation requirements shape product development timelines and market entry costs for manufacturers worldwide. Japan's PMDA enforces stringent good manufacturing practice audits for active implantable medical devices, limiting supplier turnover in that market. Stakeholders must monitor evolving reimbursement decisions from Germany's Federal Joint Committee and CMS coverage determinations, as these directly determine commercial viability for emerging indications beyond chronic pain.
Market Dynamics
Rechargeable battery chemistry and wireless charging architectures are compressing replacement surgery cycles, redirecting patient preference toward implantable systems with decade-long lifespans over legacy non-rechargeable pulse generators.
Growth Catalysts
- Breakthrough Device Designation:The FDA's accelerated pathway truncates commercialization timelines for neuromodulation innovators targeting treatment-resistant epilepsy and obsessive-compulsive disorder.
- German Reimbursement Expansion:Statutory health insurance coverage for deep brain stimulation in Parkinson's disease has broadened patient access across Bavaria and North Rhine-Westphalia.
- Directional Lead Technology:Steerable electrode arrays enable precise neural targeting, reducing side-effect profiles and expanding candidacy for movement disorder therapies.
Market Restraints
- Platinum-Iridium Concentration:Electrode array fabrication depends on South African and Russian supply chains for precious metal feedstock, exposing manufacturers to geopolitical input volatility.
- EU MDR Clinical Evidence Burden:CE marking under the Medical Device Regulation demands expanded post-market surveillance, extending regulatory friction for implantable neuromodulation systems.
- Pharmacological Substitution:High-frequency spinal cord stimulation competes with non-opioid analgesic pipelines and interventional pain procedures in chronic lower back pain.
Strategic Opportunities
- Closed-Loop Responsive Systems:Seizure detection algorithms paired with real-time stimulation adjustment represent white space beyond scheduled intermittent protocols.
- Japan's PMDA Streamlining:METI initiatives to harmonize good manufacturing practice audits with ISO 13485 reduce supplier turnover barriers for foreign device manufacturers.
- Psychiatric Indications:Vagus nerve stimulation for treatment-resistant depression awaits CMS national coverage determination, with commercial viability contingent on positive reimbursement.
Industry Challenges
- Neuroelectrophysiology Talent Scarcity:Biomedical engineers with combined expertise in neural signal processing and implantable hardware design command premium compensation, constraining R&D scaling.
- Multi-Site Clinical Trial Coordination:Movement disorder studies require synchronized enrollment across academic medical centers with specialized stereotactic surgical capabilities, prolonging evidence generation timelines.
- Legacy System Interoperability:Next-generation external programmers must maintain backward compatibility with implanted pulse generators from prior device generations, complicating software architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurostimulation Devices Market |
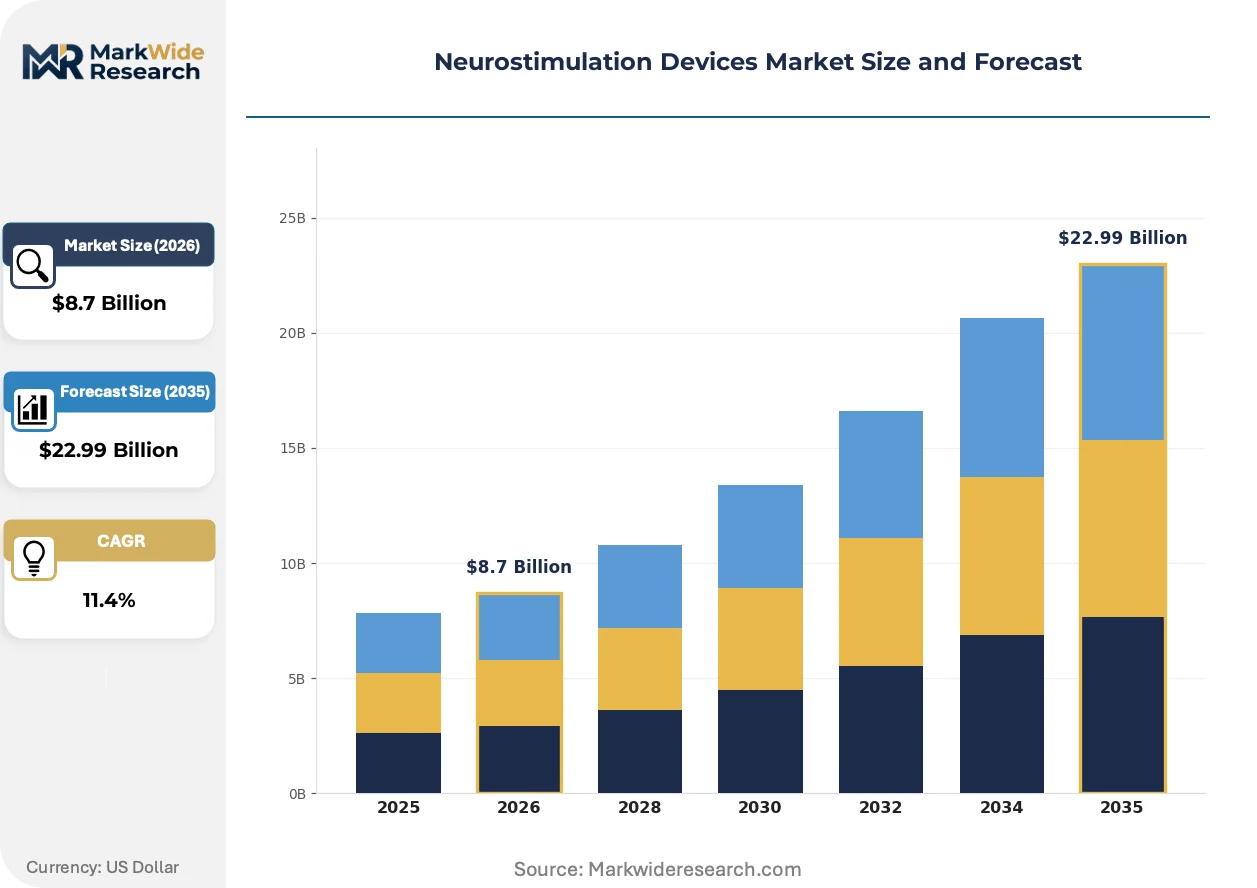
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Spinal Cord Stimulators, Deep Brain Stimulators, Peripheral Nerve Stimulators, Transcranial Magnetic Stimulators Indication: Pain Management, Movement Disorders, Epilepsy, Depression End User: Hospitals, Home Care Settings, Ambulatory Surgical Centers, Neurosurgery Clinics Technology: Implantable Devices, External Devices, Rechargeable Devices, Non-Invasive Devices |
| Companies Covered | Nevro Corp, NeuroPace, Medtronic, Inspire Medical Systems, Axonics Modulation Technologies, Boston Scientific Corporation, LivaNova PLC, Neuronetics, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurostimulation Devices Market Emerging Trajectories
Device architecture is fragmenting from monolithic implantable systems toward modular configurations where sensing, computation, and stimulation distribute across separate physical components.
Closed-loop responsive neurostimulation is decomposing the traditional open-loop paradigm where fixed stimulation parameters are programmed during surgical implantation. Epilepsy treatment centers in the United States are adopting seizure-responsive systems at accelerating velocity. This decomposition is compressing battery consumption and enabling personalized therapy adaptation without repeated surgical interventions.
EU MDR Article 10 clinical evaluation requirements are mandating systematic literature reviews and post-market clinical follow-up for all active implantable medical devices. Manufacturers must now maintain technical documentation demonstrating equivalence or generate proprietary clinical data. Implantable pulse generator categories face the steepest compliance burden, with notified body capacity constraints extending certification timelines.
Patient-directed therapy management via smartphone-connected external programmers is altering the traditional clinic-centric follow-up model. Pain management practices in Germany are unbundling device interrogation from physician visits, replacing quarterly office appointments with asynchronous remote monitoring. This behavioral shift is most pronounced among working-age chronic pain patients in urban catchment areas with reliable broadband infrastructure.
Neurostimulation Devices Market Segmentation
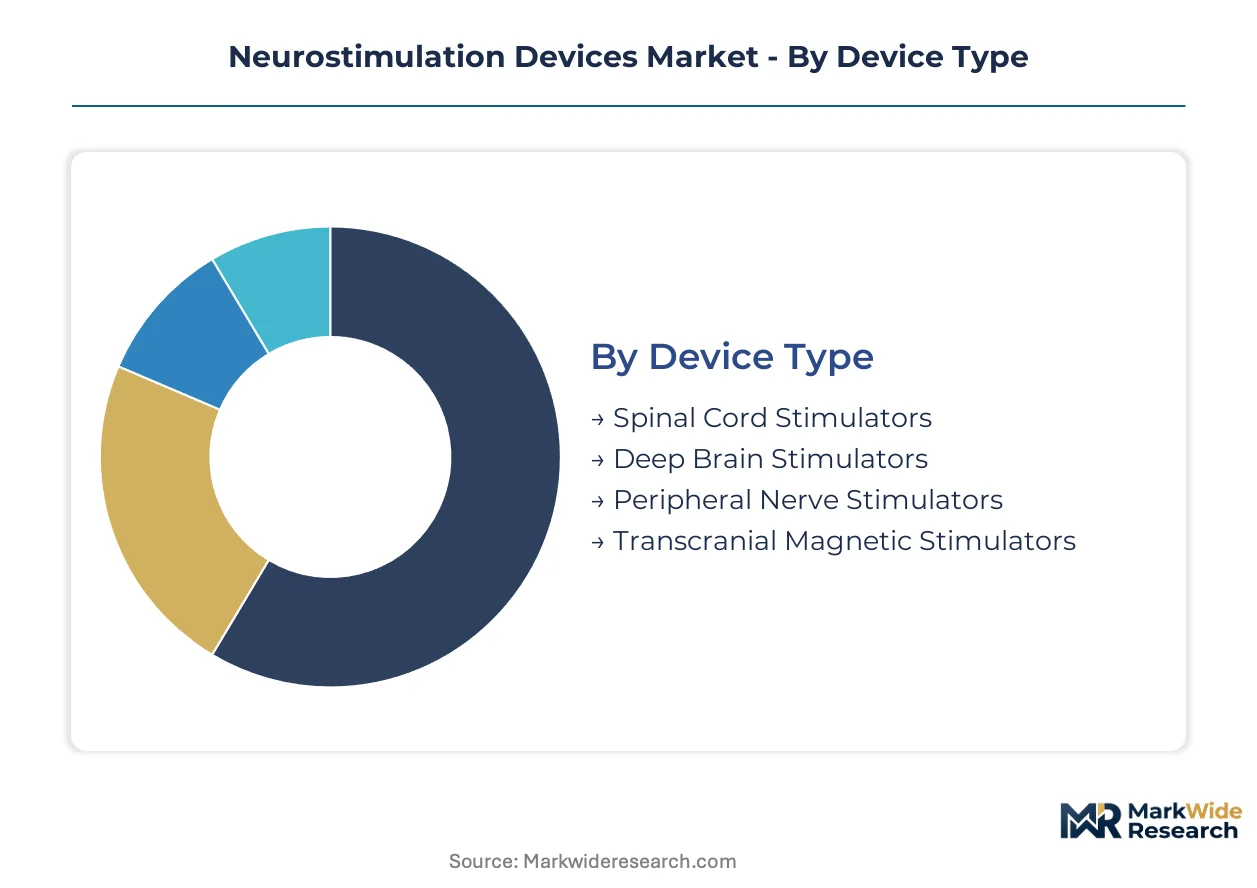
Segmentation in neurostimulation devices reveals distinct competitive dynamics across therapeutic applications and care delivery models. Each dimension carries unique substitution pressures from pharmacological alternatives, interventional procedures, or competing neuromodulation modalities.
Device Type:
Spinal cord stimulators face intensifying substitution from non-opioid analgesic pipelines and radiofrequency ablation procedures in chronic back pain, while deep brain stimulators defend against lesioning techniques through reversible, adjustable therapy.
- Spinal Cord Stimulators:These implantable systems deliver electrical impulses to the dorsal column via epidural leads, typically operating at 40-1000 Hz for neuropathic pain modulation. Demand concentrates in pain management clinics across the United States, where CMS reimbursement for failed back surgery syndrome sustains implant volumes despite pharmacological competition.
- Deep Brain Stimulators:Bilateral electrode arrays target subthalamic nucleus or globus pallidus interna with high-frequency stimulation (130-185 Hz) for Parkinson's disease and essential tremor. Germany's Federal Joint Committee expanded statutory reimbursement for movement disorder indications, broadening patient access beyond academic medical centers.
- Peripheral Nerve Stimulators:Targeted occipital or sacral nerve modulation for migraine and bladder dysfunction.
- Transcranial Magnetic Stimulators:Non-invasive cortical stimulation systems for depression and obsessive-compulsive disorder.
Spinal cord stimulators retain volume leadership; deep brain stimulators hold the steepest expansion curve.
Indication:
Pain management dominates procedure volumes but encounters margin compression from bundled payment models, while psychiatric indications await definitive reimbursement decisions to unlock commercial scale.
- Pain Management:Chronic neuropathic and nociceptive pain conditions including failed back surgery syndrome and complex regional pain syndrome. The United States accounts for the largest installed base of implantable pain devices, though commercial payers are tightening prior authorization requirements.
- Epilepsy:Responsive neurostimulation for drug-resistant partial-onset seizures with seizure detection algorithms. The FDA's breakthrough device designation pathway accelerated approval timelines for closed-loop systems targeting this indication.
- Movement Disorders:Parkinson's disease, essential tremor, and dystonia through subcortical target modulation.
- Depression:Vagus nerve stimulation and transcranial magnetic stimulation for treatment-resistant cases.
Pain management commands the largest revenue pool; epilepsy applications are climbing the fastest.
End User:
Site-of-care economics favor ambulatory surgical centers for routine generator replacements, while complex initial implants remain anchored to hospital neurosurgical suites with stereotactic capabilities.
- Hospitals:Academic medical centers with specialized functional neurosurgery programs handle complex deep brain stimulation implantations requiring intraoperative electrophysiological mapping.
- Ambulatory Surgical Centers:Spinal cord stimulator trials and generator replacements migrate to outpatient settings where procedure efficiency and lower facility fees improve economics.
- Home Care Settings:Patient-directed therapy management via external programmers and wireless monitoring platforms.
- Neurosurgery Clinics:Specialized movement disorder centers with integrated programming expertise.
Hospitals retain the highest acuity caseload; ambulatory surgical centers are gaining share fastest.
Technology:
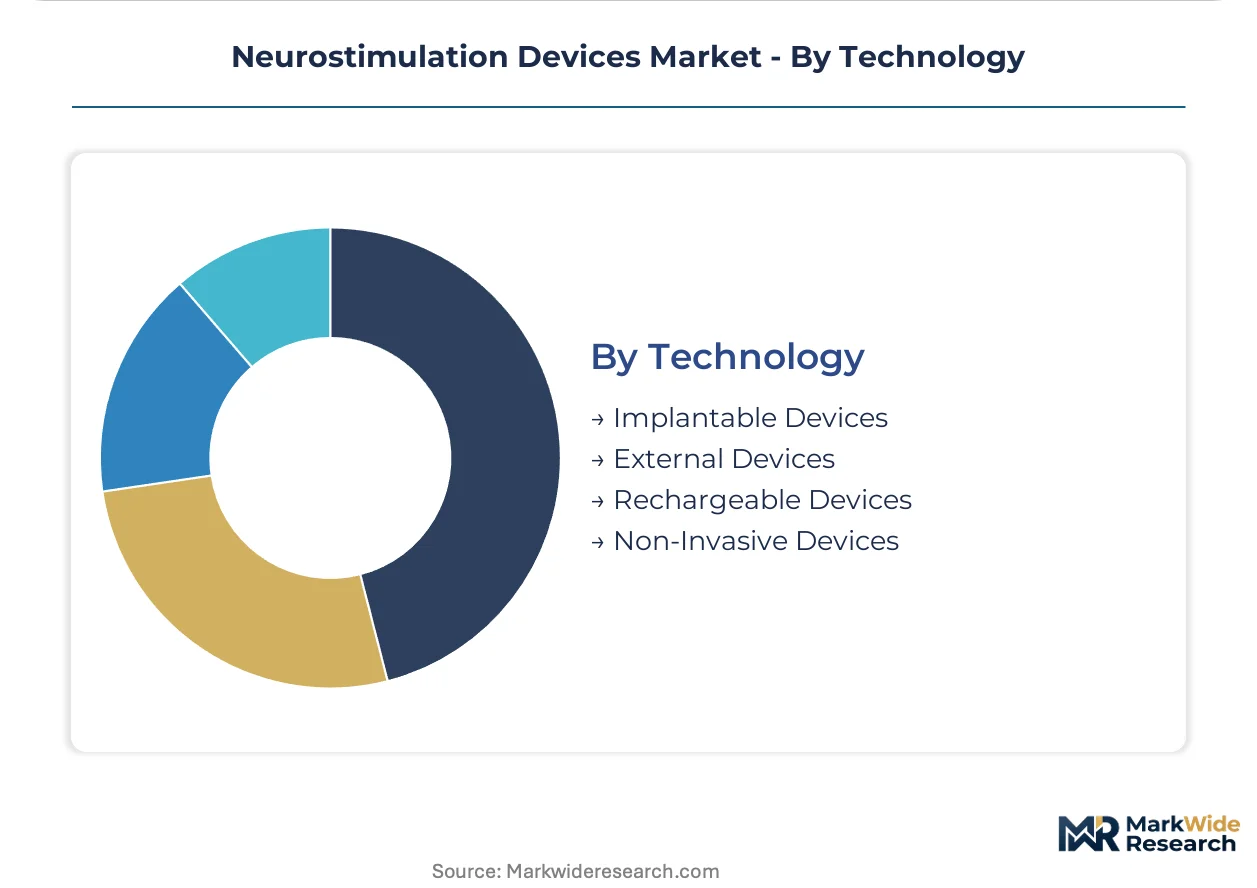
Rechargeable architectures command premium pricing through reduced replacement surgery burden, while external devices compete on access and capital efficiency for psychiatric indications.
- Implantable Devices:Fully internalized pulse generators with transcutaneous inductive charging or primary cell batteries. Germany's statutory health insurance system differentiates reimbursement rates between rechargeable and non-rechargeable systems.
- Rechargeable Devices:Lithium-ion powered implantable pulse generators with decade-long functional lifespans. Patient preference surveys in North America indicate strong willingness-to-pay for reduced surgical replacement cycles.
- External Devices:Transcutaneous electrical nerve stimulation and transcranial magnetic stimulation systems.
- Non-Invasive Devices:Surface electrode or magnetic coil systems without surgical implantation.
Implantable devices anchor revenue concentration; rechargeable configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pain management clinics and academic medical centers concentrate demand across distinct national healthcare systems, with reimbursement policies and regulatory pathways determining commercial access in each market.
United States
CMS reimbursement for failed back surgery syndrome sustains spinal cord stimulator volumes, while the FDA's breakthrough device designation accelerates approval timelines for closed-loop epilepsy systems. Commercial payers tighten prior authorization requirements, compressing margins. The Minneapolis-St. Paul corridor hosts concentrated functional neurosurgery expertise and device programming centers.
Germany
The Federal Joint Committee expanded statutory health insurance coverage for deep brain stimulation in Parkinson's disease, broadening patient access beyond academic centers. EU MDR Article 10 clinical evaluation requirements extend certification timelines for implantable pulse generators. Bavaria and North Rhine-Westphalia cluster movement disorder treatment centers with integrated stereotactic surgical capabilities.
Japan
METI initiatives to harmonize PMDA good manufacturing practice audits with ISO 13485 reduce barriers for foreign device manufacturers entering the active implantable market. Aging demographics expand the addressable patient pool for movement disorder therapies. The Kanto region around Tokyo concentrates university hospitals with established deep brain stimulation programs.
United Kingdom
NICE technology appraisals determine NHS commissioning for vagus nerve stimulation in treatment-resistant depression, with commercial viability contingent on positive reimbursement decisions. Post-Bre divergence from EU MDR creates parallel regulatory pathways. London and the Southeast anchor specialized epilepsy surgery centers adopting responsive neurostimulation systems.
Australia
TGA conformity assessment procedures for active implantable medical devices align with EU MDR standards, streamlining market entry for manufacturers with existing CE marking. Private health insurance funds differentiate coverage between rechargeable and non-rechargeable systems. New South Wales and Victoria concentrate functional neurosurgery services and pain management clinics.
Neurostimulation Devices Market Vendor Landscape
Player mix skews toward diversified medtech conglomerates with decades of neuromodulation expertise alongside specialized pure-plays targeting single therapeutic verticals. The competitive structure concentrates around three archetypes: full-line implantable device manufacturers, responsive neurostimulation specialists, and emerging entrants in peripheral nerve modulation. Dominant competitive moves include strategic portfolio diversification into adjacent indications and technology licensing agreements to access proprietary electrode or algorithmic assets.
Among diversified medtech conglomerates, Medtronic and Boston Scientific Corporation anchor the full-line implantable tier with established manufacturing scale across multiple continents. Abbott occupies a position on precision targeting through directional lead technology. Within the specialized tier, NeuroPace exemplifies the responsive neurostimulation archetype with proprietary seizure detection capabilities. Nevro Corp and Axonics Modulation Technologies represent the emerging peripheral nerve and rechargeable system specialists respectively.
| Leading Market Players |
|---|
| Nevro Corp |
| NeuroPace |
| Medtronic |
| Inspire Medical Systems |
| Axonics Modulation Technologies |
| Boston Scientific Corporation |
| LivaNova PLC |
| Neuronetics |
| Abbott |
| Others |
Supply Flow & Price Mechanics
Ninety-to-one-hundred-twenty-day electrode array lead times concentrate pricing power with South African and Russian platinum-iridium suppliers, compressing margins for pulse generator manufacturers while amplifying cost pass-through leverage for precious metal refiners serving the implantable neuromodulation tier.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation anchor electrode procurement agreements, with three-tier pricing structure across premium, standard, and economy levels differentiated by ISO 13485 certification tier and after-sales programming support bundling. Price erosion runs through the non-rechargeable pulse generator tier as CMS reimbursement compression intensifies hospital GPO negotiation leverage. Academic medical centers exhibit lowest price sensitivity due to bundled surgical margins, while ambulatory surgical centers face acute cost pressure from facility fee compression.
Supply Chain Analysis
Strait of Hormuz transit risk exposure concentrates in lithium-ion cell shipments from South Korean and Japanese battery manufacturers to pulse generator assembly plants in Ireland and Costa Rica. Platinum-iridium electrode feedstock draws from South African mining operations and Russian refining capacity, with single-source vulnerability in high-purity iridium sponge. Distribution runs through specialized medical device distributors with cold-chain capabilities for biocompatible component handling. Tariff exposure sits with Chinese-sourced ceramic capacitors and printed circuit board substrates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of biomedical engineers combining neural signal processing with implantable hardware design constrains R&D scaling across all competitive tiers, amplifying acquisition premiums for teams with closed-loop algorithm expertise.
For Market Incumbents: Secure exclusive supply agreements for platinum-iridium sponge through backward integration into South African mining partnerships, insulating against Russian supply disruption. Deepen vertical integration into lithium-ion cell manufacturing to compress battery replacement cycles and defend rechargeable system margins against emerging entrants with wireless charging architectures. For New Entrants and Emerging Players: Differentiate on psychiatric indication software algorithms for vagus nerve stimulation, where CMS national coverage determination pending status creates white space before reimbursement lock-in. Target ambulatory surgical center channel partnerships for spinal cord stimulator trials, exploiting site-of-care economics migration away from hospital neurosurgical suites. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because responsive neurostimulation algorithm assets command scarcity premiums as FDA breakthrough designations accelerate. Acquisition target archetype: pure-play seizure detection software firms with proprietary electrophysiology datasets. Signal to watch: Germany's Federal Joint Committee reimbursement expansions into obsessive-compulsive disorder as inflection indicator for psychiatric indication commercial viability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated approval timelines compress commercialization cycles for closed-loop epilepsy systems. |
| CE Marking Pathway Under EU MDR | Article 10 clinical evaluation requirements extend certification timelines for implantable pulse generators. |
| Hospital System Partnership | Academic medical center alliances secure stereotactic surgical capacity for complex deep brain stimulation implants. |
| Software Companion Development | Smartphone-connected external programmers enable patient-directed therapy management unbundled from clinic visits. |
| Reimbursement Strategy | CMS national coverage determination pursuit unlocks commercial scale for vagus nerve stimulation in depression. |
Methodological Framework
Desk research of FDA 510(k) filings, EU MDR notified body certification databases, and CMS national coverage determination records preceded structured interviews with functional neurosurgeons, hospital purchasing committee chairs, biomedical engineering directors, and GPO contracts managers. Secondary validation drew from hospital procurement databases, Medicare fee schedules, and patent filings for seizure detection algorithms. Bottom-up implant volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Variance decomposition across device type, indication, end-user site-of-care, and rechargeable versus non-rechargeable technology architecture informed the analytical framework. CAGRs derived from logistic diffusion modeling of adoption curves for closed-loop responsive systems, with inputs including Germany's Federal Joint Committee reimbursement expansion timelines and Japan's PMDA manufacturing practice audit harmonization progress.
The analysis sits within stated boundaries; outcomes outside FDA breakthrough designation velocity and EU MDR notified body capacity constraints would require recalibration. Forecasts reflect assumptions on CMS coverage determination timing and platinum-iridium supply chain stability. Practitioners should keep alternative scenarios live as German statutory health insurance reimbursement decisions and METI regulatory harmonization initiatives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
MRI Safe Defibrillator Market
Medical Devices
Crescent Ultrasonic Cleansers Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
Global Radial Artery Compression Devices Market
Medical Devices
Global Implantable Loop Recorder Market
Medical Devices
Wireless Surgical Cameras Market
Medical Devices
Neuromodulation Devices Market
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
Diabetic Eye Disease Devices Market
Medical Devices
Arthroscopy Market
Medical Devices
Digital Radiology Devices Market
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
Spinal Cord Stimulators Market
Medical Devices
Ultrasound Biometry Devices Market
Medical Devices
Global Diagnostic Catheter Market