
 Buccal Cavity Devices Market | 2026-2036
Buccal Cavity Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Buccal Cavity Devices Market Analysis
Asset-light licensing and contract manufacturing arrangements is fragmenting competitive dynamics across the buccal cavity devices landscape. Dentsply Sirona leverages its dental imaging infrastructure to cross-sell diagnostic tools that inform buccal drug delivery positioning. Planmeca Oy anchors Nordic design standards in intraoral scanner development that supports personalized buccal device fabrication. Envista Holdings Corporation competes through distributed service networks that reduce capital barriers for mid-sized clinic adoption.
Buccal cavity devices encompass drug delivery systems designed for administration via the mucosal lining of the inner cheek, typically formulated as bioadhesive films, erodible tablets, or viscous gels with residence times of 15-30 minutes to enable systemic absorption through the highly vascularized buccal epithelium. These systems bypass hepatic first-pass metabolism to achieve faster therapeutic onset for indications requiring rapid bioavailability. Films dominate current prescription volumes due to manufacturing scalability and patient acceptability advantages over viscous gel alternatives. Sublingual and buccal delivery modes command premium positioning in emergency medicine and breakthrough pain protocols where speed-to-effect determines clinical utility. Home care channels represent the fastest-expanding end user segment as self-administered smoking cessation and hormonal therapy protocols gain reimbursement traction.
FDA bioequivalence standards and EMA quality guidelines for oromucosal products shape formulation development timelines and generic substitution pathways across major markets. The US Pharmacopeia dissolution specifications and ISO 10993 biocompatibility testing frameworks impose material selection constraints that favor established polymer suppliers with validated documentation packages. Stakeholders must monitor evolving FDA guidance on complex generic buccal films and corresponding patent cliff exposures that will reshape competitive intensity without warning.
Market Dynamics
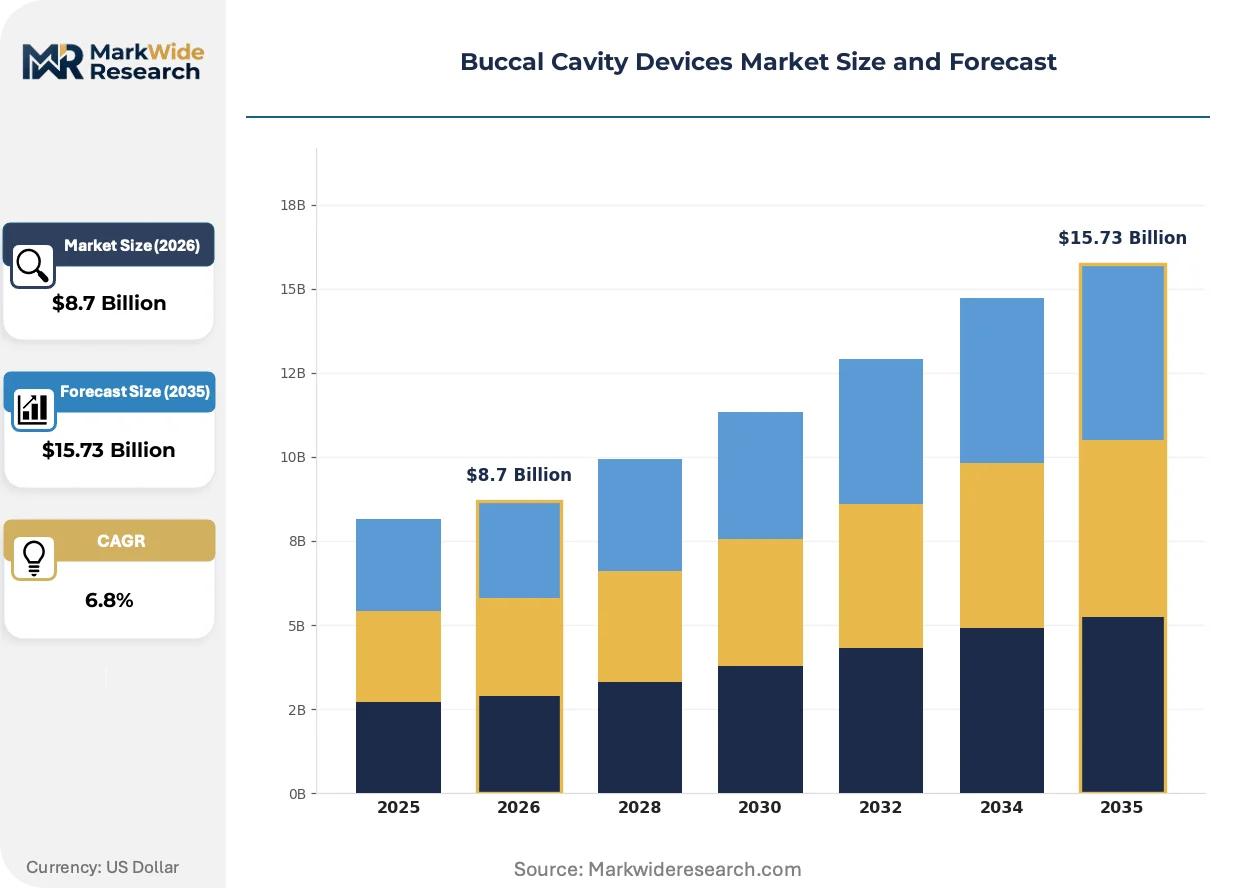
The buccal cavity devices market is restructuring around FDA bioequivalence pathway expansions that compress generic approval timelines from 36 months to under 18 months, forcing incumbent film manufacturers to defend formulation moats through polymer trade secrets rather than composition patents.
Growth Catalysts
- EMA quality guidelines for oromucosal products:Harmonized dissolution testing standards accelerate cross-border registration for European manufacturers seeking mutual recognition procedures.
- Breakthrough pain protocols in emergency medicine:Hospital formularies in the United States now mandate transmucosal fentanyl alternatives for rapid-onset analgesia, displacing intravenous administration in triage settings.
- Self-administered hormonal therapy:Home care reimbursement codes for testosterone and estrogen buccal films expand addressable populations beyond clinic-dependent injection regimens.
Market Restraints
- Polymer supply concentration:Carbomer and hydroxypropyl methylcellulose production clusters in China create raw material vulnerability for Western film formulators.
- ISO 10993 biocompatibility testing costs:Extended cytotoxicity and sensitization studies add 14-22 months to device qualification timelines.
- Competing sublingual spray formats:Liquid atomizers achieve comparable T-max values with simpler manufacturing equipment, pressuring film price premiums.
Strategic Opportunities
- India's CDSCO fast-track pathway:Local manufacturing incentives under the PLI scheme enable cost-competitive export bases for African and Southeast Asian markets.
- Pediatric buccal formulations:Dissolvable films for antiepileptic and antiemetic delivery address unmet needs in populations unable to swallow tablets.
- 3D printing convergence with intraoral scanning:Chairside fabrication of personalized buccal splints and drug-loaded matrices collapses dental-to-pharmacy distribution steps.
Industry Challenges
- Formulation scientist scarcity:Expertise in mucoadhesive polymer rheology and permeation enhancement resides with a narrow cohort of academic labs and retired industry specialists.
- Legacy ERP integration:Track-and-trace mandates for pharmaceutical serialization conflict with paper-based batch records at mid-sized contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buccal Cavity Devices Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lozenges, Films, Gels, Tablets Application: Pain Management, Nutritional Supplements, Hormonal Therapy, Smoking Cessation End User: Pharmacies, Hospitals, Home Care, Clinics Delivery Mode: Oral, Transmucosal, Sublingual, Buccal |
| Companies Covered | Carestream Dental, Planmeca Oy, Dentsply Sirona, Midmark Corporation, Envista Holdings Corporation, ACTEON Group Ltd., FONA Dental, Varex Imaging Corporation, Align Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buccal Cavity Devices Market Emerging Trajectories
Formulation science is converging with digital manufacturing to compress development cycles and enable patient-specific dosing geometries previously uneconomical at commercial scale.
Electrospun nanofiber matrices are migrating from research-stage curiosity to pilot production for buccal delivery. These fibrous webs achieve 400-600% surface area advantages over cast films, accelerating dissolution kinetics for poorly soluble APIs. Specialty CMOs in Switzerland and Massachusetts are installing multi-needle electrospinning lines to serve orphan drug sponsors seeking bioavailability enhancement without reformulation.
REACH Annex XVII restrictions on phthalate plasticizers are forcing polymer reformulations across European supply chains. Manufacturers are substituting citrate esters and bio-based adipates in film coatings, with migration studies now mandatory for all new oromucosal product registrations. German and French notified bodies have issued consolidated guidance documents to streamline substance evaluation.
Hospital procurement consortia are consolidating buccal film purchasing through single-source agreements that bundle analgesic, antiemetic, and smoking cessation portfolios. These multi-year contracts displace fragmented therapeutic-class bidding, pressuring smaller manufacturers to join preferred supplier networks or exit institutional channels entirely. The Veterans Health Administration and NHS England have both shifted to this model since 2024.
Buccal Cavity Devices Market Segmentation
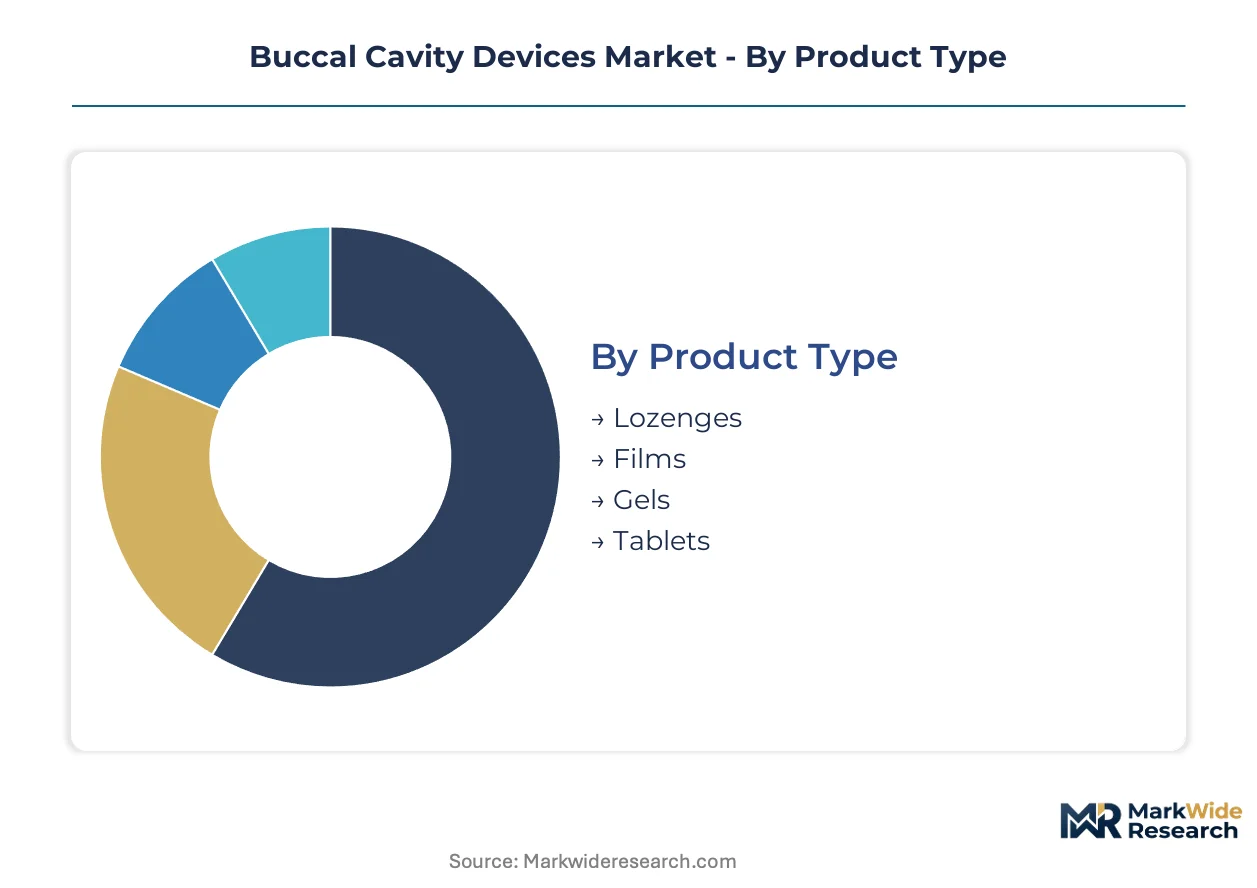
Buccal cavity devices fragment across formulation physics, therapeutic targets, and care settings. Each dimension carries distinct regulatory burdens and margin profiles that reshape competitive positioning.
Product Type:
After-sales service intensity concentrates in films and tablets where formulation troubleshooting requires polymer chemistry expertise and dissolution failure investigations.
- Films:Cast or extruded polymer matrices with mucoadhesive layers engineered for 15-30 minute residence times. Hospital formularies in the United States prioritize films for breakthrough pain protocols due to manufacturing reproducibility and dose uniformity. ISO 10993 biocompatibility documentation requirements favor suppliers with validated polymer supply chains.
- Tablets:Compressed bioadhesive cores with controlled erosion profiles. Demand clusters in hormonal therapy applications where patients require discrete self-administration outside clinical settings. EMA quality guidelines for oromucosal products impose dissolution specification burdens that extend development timelines.
- Lozenges:Hard candy matrices with API dispersed throughout sucrose or sugar alcohol bases.
- Gels:Viscous aqueous or non-aqueous preparations with thixotropic flow properties.
By volume, tablets lead. By growth pace, films are expanding most quickly.
Application:
Cost tier stratification separates premium hospital-administered analgesics from economy-positioned smoking cessation aids sold through retail pharmacy.
- Pain Management:Rapid-onset fentanyl and buprenorphine formulations for breakthrough cancer pain and emergency triage. FDA bioequivalence pathway expansions compress generic approval timelines, forcing incumbent manufacturers to defend through polymer trade secrets.
- Smoking Cessation:Nicotine replacement films and lozenges with gradual taper protocols. Home care reimbursement codes in the United States expand addressable populations beyond clinic-dependent interventions.
- Nutritional Supplements:Vitamin B12 and melatonin delivery for populations with swallowing difficulties.
- Hormonal Therapy:Testosterone and estrogen formulations bypassing hepatic first-pass metabolism.
By volume, pain management leads. By growth pace, hormonal therapy is gaining share fastest.
End User:
Customer type determines procurement leverage, with hospital consortia extracting multi-year bundled contracts that smaller home care channels cannot match.
- Hospitals:Institutional purchasers mandating transmucosal alternatives for rapid-onset analgesia in emergency departments. The Veterans Health Administration shifted to single-source agreements bundling analgesic, antiemetic, and smoking cessation portfolios.
- Home Care:Self-administered protocols for smoking cessation and hormonal therapy gaining reimbursement traction. Pediatric buccal formulations for antiepileptic delivery address unmet needs in populations unable to swallow tablets.
- Pharmacies:Retail dispensing of over-the-counter nicotine replacement and nutritional supplements.
- Clinics:Mid-sized facilities adopting distributed service networks that reduce capital barriers for intraoral scanner integration.
By volume, hospitals lead. By growth pace, home care shows the steepest expansion trajectory.
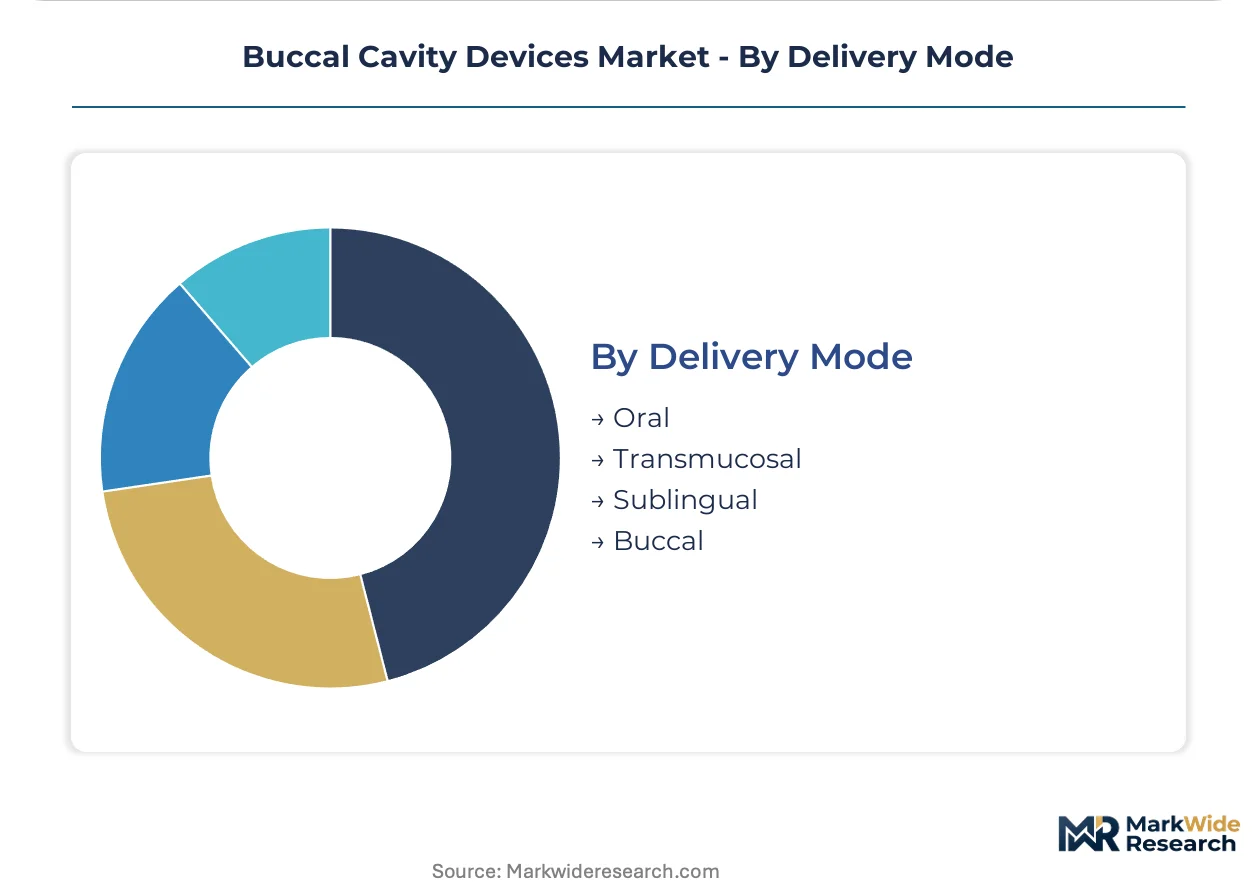
Delivery Mode:
Supply concentration in polymer feedstocks shapes which delivery modes achieve commercial viability at scale.
- Buccal:Administration via the inner cheek mucosa with systemic absorption through the highly vascularized epithelium. Carbomer and hydroxypropyl methylcellulose production clusters in China create raw material vulnerability for Western formulators.
- Sublingual:Under-tongue placement achieving faster T-max values for emergency medicine applications. Liquid atomizer alternatives achieve comparable pharmacokinetics with simpler manufacturing equipment, pressuring film price premiums.
- Oral:Traditional swallowable formats with hepatic first-pass metabolism.
- Transmucosal:Broader category encompassing buccal, sublingual, and gingival delivery routes.
By volume, buccal leads. By growth pace, sublingual is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in buccal cavity devices favor manufacturing bases with validated polymer supply chains and streamlined regulatory pathways. Western markets source specialized films from contract manufacturers in India and Switzerland, while intraoral scanning hardware flows predominantly from Nordic and North American production clusters.
United States
Hospital procurement consortia including the Veterans Health Administration drive institutional demand for rapid-onset analgesic films. FDA bioequivalence pathway expansions compress generic approval timelines from 36 months to under 18 months. Boston and Research Triangle Park host specialty CMOs installing electrospinning lines for orphan drug sponsors.
Germany
EMA quality guidelines for oromucosal products anchor dissolution testing standards that accelerate mutual recognition procedures across EU member states. REACH Annex XVII restrictions on phthalate plasticizers force polymer reformulations with citrate ester substitutions. Frankfurt and Munich concentrate notified body expertise for streamlined substance evaluation documentation.
Switzerland
Swissmedic oversight of complex generic buccal films attracts formulation sponsors seeking regulatory predictability. Specialty CMOs in Basel and Zurich leverage multi-needle electrospinning infrastructure to serve bioavailability enhancement contracts. Geneva hosts polymer suppliers with pre-validated ISO 10993 documentation packages.
India
CDSCO fast-track pathways under the PLI scheme enable cost-competitive export manufacturing for African and Southeast Asian markets. Mumbai and Hyderabad cluster contract research organizations with mucoadhesive polymer rheology expertise. Gujarat's pharmaceutical zones attract film formulators seeking carbomer and hydroxypropyl methylcellulose supply security.
Japan
PMDA quality guidelines for oromucosal products impose dissolution specification burdens that extend development timelines for foreign entrants. Tokyo and Osaka anchor dental imaging infrastructure that cross-sells into buccal drug delivery positioning. METI incentives support 3D printing convergence with intraoral scanning for chairside fabrication.
Buccal Cavity Devices Market Vendor Landscape
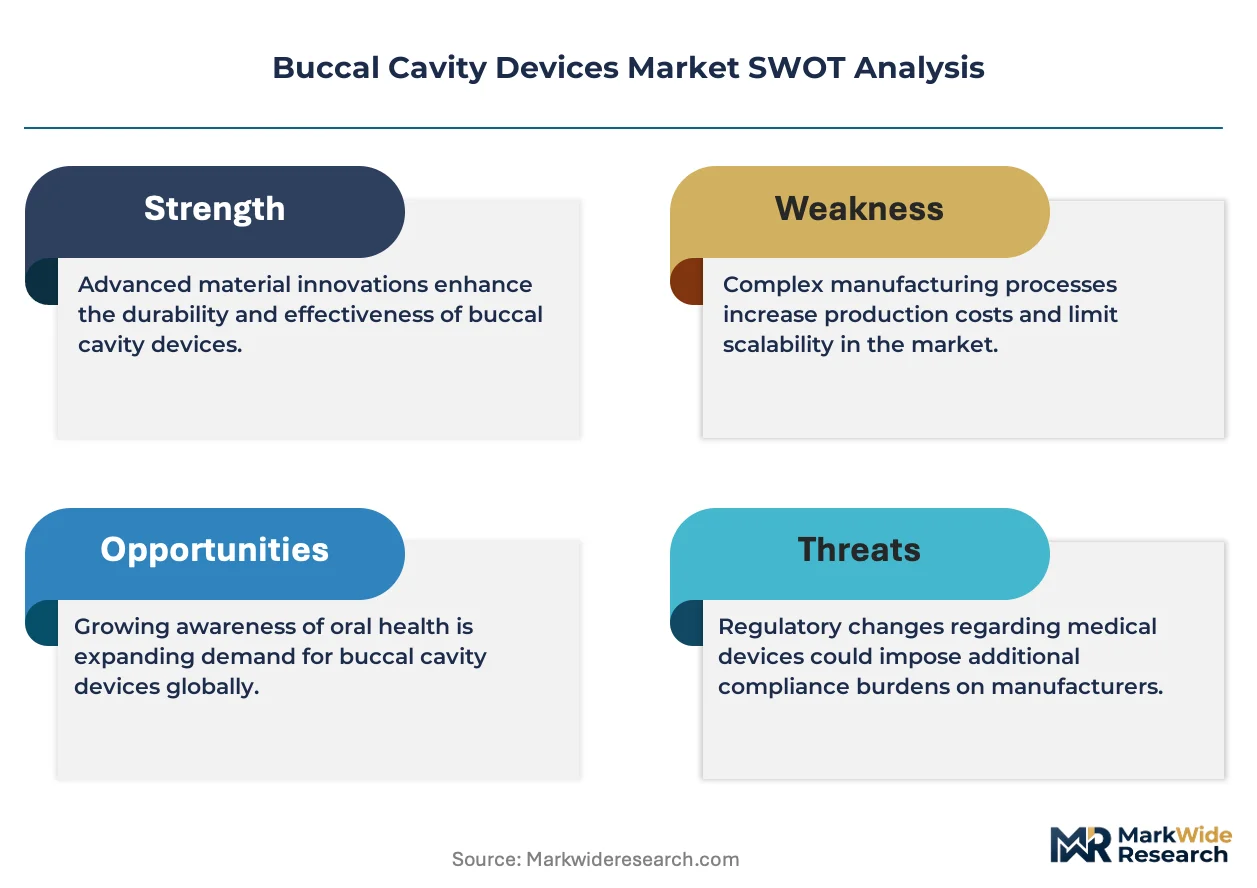
On the supply side, the industry is consolidating around asset-light licensing arrangements that fragment competitive dynamics across formulation and hardware segments. Strategic archetypes include dental imaging incumbents cross-selling diagnostic tools, Nordic design-led intraoral scanner developers, and distributed service network operators reducing capital barriers for mid-sized clinics. Dominant competitive moves encompass strategic partnerships for polymer supply security and technology licensing for electrospun nanofiber manufacturing scale-up.
Among Nordic design-standard bearers, Planmeca Oy exemplifies the intraoral scanner-to-personalized-fabrication convergence archetype. Dentsply Sirona occupies a position representing dental imaging infrastructure leverage for cross-selling into drug delivery positioning. Envista Holdings Corporation anchors the distributed service network model that reduces capital barriers for mid-sized clinic adoption.
| Leading Market Players |
|---|
| Carestream Dental |
| Planmeca Oy |
| Dentsply Sirona |
| Midmark Corporation |
| Envista Holdings Corporation |
| ACTEON Group Ltd. |
| FONA Dental |
| Varex Imaging Corporation |
| Align Technology |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Rotterdam container freight corridors transmit cost volatility from polymer feedstock concentration directly into film formulation economics, compressing margins for Western manufacturers while enabling tiered price positioning between validated-supply and generic-material tiers.
Pricing Analysis
Hospital procurement consortia anchor contract-based long-term offtake structures that bundle analgesic, antiemetic, and smoking cessation portfolios. Price differentiation separates FDA-validated polymer tiers from standard-grade alternatives, with ISO 10993 documentation commanding premiums. Pricing pressure stems from liquid atomizer substitutes achieving comparable T-max values with simpler capital equipment. Retail pharmacy channels exhibit highest price sensitivity, while emergency medicine formularies demonstrate lowest.
Supply Chain Analysis
Export-control restrictions on electrospinning equipment limit technology transfer to unlicensed CMOs, constraining nanofiber capacity expansion. Carbomer and hydroxypropyl methylcellulose production clusters in China, India, and Germany create geographic concentration for Western formulators. Raw material dependencies rest on petrochemical-derived acrylates, cellulose ethers, and bioadhesive resins. Single-source vulnerability in Chinese carbomer supply poses structural risk. Distribution runs through hospital procurement consortia, specialty CMO networks, and direct-to-clinic service arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales formulation troubleshooting and dissolution failure investigation services expand faster than hardware sales, converting device transactions into recurring technical support relationships.
For Market Incumbents: Entrench polymer trade secret protections as FDA bioequivalence pathways erode composition patent defenses. Backward integration into carbomer and hydroxypropyl methylcellulose supply secures raw material continuity against Chinese production volatility. Capacity addition in Swiss and Massachusetts electrospinning clusters captures orphan drug sponsor demand. For New Entrants and Emerging Players: Establish a beachhead in pediatric buccal formulations for antiepileptic and antiemetic delivery, where swallowing difficulties create unmet need. India's CDSCO fast-track pathway under PLI incentives offers the most penetrable regulatory entry point. Go-to-market through contract research organizations in Mumbai and Hyderabad leverages existing mucoadhesive polymer expertise. For Investors and Strategic Acquirers: Asset-light licensing specialists with validated ISO 10993 documentation packages and established hospital consortia relationships represent priority acquisition targets. Long-term viability hinges on convergence between intraoral scanning hardware and chairside drug-loaded matrix fabrication. Monitor FDA guidance releases on complex generic buccal films as inflection indicators for competitive intensity shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Supply Security Agreement | Carbomer and HPMC captive sourcing insulates Western formulators from Chinese production volatility. |
| Electrospinning Manufacturing Scale-Up | Multi-needle line installation in Basel and Zurich serves orphan drug bioavailability enhancement contracts. |
| Hospital System Partnership | Veterans Health Administration and NHS England bundled contracts displace fragmented therapeutic-class bidding. |
| Reimbursement Strategy Development | Home care code expansion for testosterone and estrogen films extends addressable populations beyond clinics. |
| Regulatory Approval Pathway | EMA mutual recognition and FDA bioequivalence streamlining accelerates cross-border generic film registration. |
Methodological Framework
Cross-validation between primary interviews with formulation scientists, regulatory affairs leads, hospital procurement managers, and polymer supply specialists anchors the qualitative findings. Secondary sources include FDA 510(k) filings, EMA oromucosal quality guidelines, USP dissolution specifications, ISO 10993 biocompatibility documentation, and hospital formulary databases. Bottom-up patient population modeling and top-down pharmaceutical spending triangulation reconcile volume estimates.
Calibration against historical electrospinning capacity additions and generic approval timeline compressions informs the analytical framework across the projection horizon. Segmentation dimensions encompass formulation physics, therapeutic target, care setting, and regional regulatory cluster. CAGRs derive from patent cliff exposure modeling and polymer supply elasticity assumptions. Forecast inputs include CDSCO fast-track utilization rates and REACH Annex XVII phthalate substitution timelines.
Stress conditions across carbomer supply disruption, FDA guidance revision, and electrospinning equipment export-control tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about bioequivalence pathway stability and hospital consortia purchasing consolidation. Cross-checking against CMS Medicare Part B reimbursement data and NHS England procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Foot Orthotic Insoles Market
Medical Devices
Australia Medtech Market
Medical Devices
Asia-Pacific Bathroom and Toilet Assist Devices Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Middle East and Africa Non-Surgical Procedures Market
Medical Devices
PDA Closure Devices Market
Medical Devices
Disposable Lancets Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
EMEA Surgical Microscopes Market
Medical Devices
Global Electrophysiology Devices Market
Medical Devices
Ventricle Assist Device Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Global Artificial Kidney Market
Medical Devices
Global Holter ECG Market
Medical Devices
Arthroscopic Shaver Market