
 Australia Minimally Invasive Surgery Devices Market | 2026-2036
Australia Minimally Invasive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Minimally Invasive Surgery Devices Market Outlook
Equipment leasing and managed service agreements is rewriting capital deployment across Australian surgical suites. Medtronic PLC leverages its end-to-end laparoscopic portfolio to anchor public hospital tenders in Victoria and Queensland. Boston Scientific Corporation competes through specialized interventional platforms for cardiovascular and urological minimally invasive procedures. Stryker Corporation sustains orthopedic navigation dominance by integrating digital visualization with its arthroscopic instrument lines.
Australia minimally invasive surgery devices comprise precision-engineered instruments, camera systems, robotic platforms, and energy devices designed for procedures through small incisions under image guidance, typically utilizing 5-12 mm trocar access with high-definition or 3D optical feedback. These systems reduce tissue trauma, shorten recovery intervals, and lower postoperative complication rates compared with open surgical alternatives. Surgical robots command premium positioning due to capital intensity and training requirements, while laparoscopic instruments generate recurring revenue through disposable component turnover. Endoscopy devices occupy mature volume leadership across gastrointestinal and diagnostic applications in Australian public health networks.
TGA pre-market conformity assessments and the Medical Devices Reforms shape product registration timelines and clinical evidence requirements for minimally invasive platforms entering Australia. State-level health procurement frameworks in New South Wales, Victoria, and Queensland further segment market access through centralized tender processes and preferred supplier panels. Stakeholders must monitor evolving TGA software-as-a-medical-device guidance and state hospital capital budgets to anticipate reimbursement and procurement shifts.
Market Dynamics
Public hospital procurement consortiums in New South Wales and Victoria are consolidating purchasing power around integrated laparoscopic platforms, compressing vendor margins while accelerating platform standardization across metropolitan surgical networks.
Growth Catalysts
- TGA Medical Devices Reforms:Streamlined pre-market assessment pathways for software-enabled surgical platforms are reducing registration timelines for innovative visualization systems entering Australian distribution.
- Metropolitan tertiary center expansion:Surgical volume concentration in Sydney, Melbourne, and Brisbane justifies capital-intensive robotic installations that drive recurring instrument revenue.
- Single-use instrument migration:Cross-contamination risk protocols in public health networks are accelerating disposable trocar and energy device adoption over reusable alternatives.
Market Restraints
- Capital intensity barriers:Robotic surgical platforms require AUD 2-4 million upfront investment plus dedicated facility infrastructure, limiting deployment to well-capitalized health services.
- Specialized technician scarcity:Biomedical engineering talent capable of maintaining integrated camera-robot-energy systems concentrates in Sydney and Melbourne, constraining regional rollout.
- Extended TGA conformity timelines:Novel energy-based surgical devices face prolonged clinical evidence requirements under updated essential principles, delaying market entry.
Strategic Opportunities
- Queensland regional hospital penetration:Secondary centers in Brisbane outer corridors and Gold Coast health districts present underdeveloped demand for laparoscopic platform leasing arrangements.
- Software-as-a-medical-device expansion:TGA guidance clarification on AI-enabled surgical planning tools creates regulatory runway for predictive analytics integration.
- Interventional endoscopy convergence:Gastroenterology suites are adopting hybrid therapeutic platforms that blur diagnostic and surgical procedure boundaries.
Industry Challenges
- Surgeon retraining logistics:Robotic platform proficiency requires 50-100 supervised procedures, creating throughput bottlenecks at accredited training sites.
- Legacy system interoperability:New visualization standards conflict with installed base camera towers across Victorian public hospital networks.
- Supply chain reconfiguration:Single-use instrument dependence exposes inventory positions to international freight volatility and customs processing delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Minimally Invasive Surgery Devices Market |
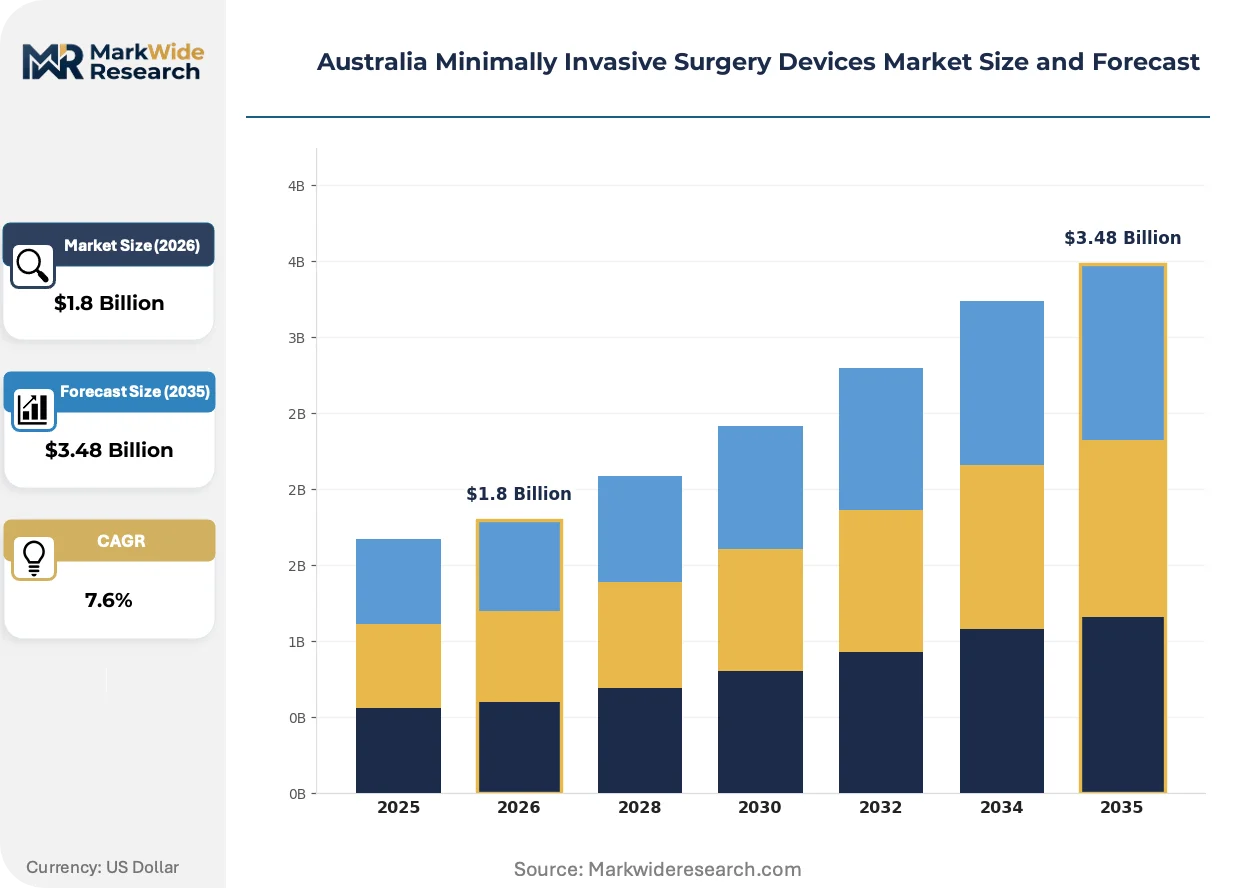
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Endoscopy Devices, Surgical Robots, Laparoscopic Instruments, Access Portals Application: Orthopedic Surgery, Cardiovascular Procedures, Urological Interventions, Gastrointestinal Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Technology: Optical Coherence Tomography, 3D Imaging, Robotic Assistance, Digital Visualization |
| Companies Covered | Medtronic PLC, Boston Scientific Corporation, Stryker Corporation, Zimmer Biomet, Intuitive Surgical Inc., Smith & Nephew, Koninklijke Philips NV, Siemens Healthineers, Olympus Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Minimally Invasive Surgery Devices Market Strategic Shifts
Digital integration across imaging, navigation, and energy delivery is collapsing procedural boundaries between diagnostic and therapeutic platforms in Australian surgical suites.
4K-3D hybrid visualization systems with integrated fluorescence guidance are rendering obsolete conventional 2D laparoscopic towers in metropolitan tertiary centers. Victorian public hospital procurement panels are mandating these platforms in new capital tenders. The technology is compressing vendor differentiation to software ecosystems and proprietary instrument lock-in.
TGA software-as-a-medical-device guidance issued in 2024 imposes clinical validation requirements on AI-enabled surgical planning tools. Manufacturers must demonstrate algorithm performance across Australian patient populations. Orthopedic navigation systems face the steepest compliance burden due to patient-specific implant matching complexity.
Managed service agreements now dominate capital equipment acquisition in New South Wales Health Pathology networks. Fixed per-procedure fees replace outright purchase, transferring utilization risk to device vendors. This model concentrates in high-volume metropolitan sites where case predictability supports risk pooling.
Australia Minimally Invasive Surgery Devices Market Segmentation
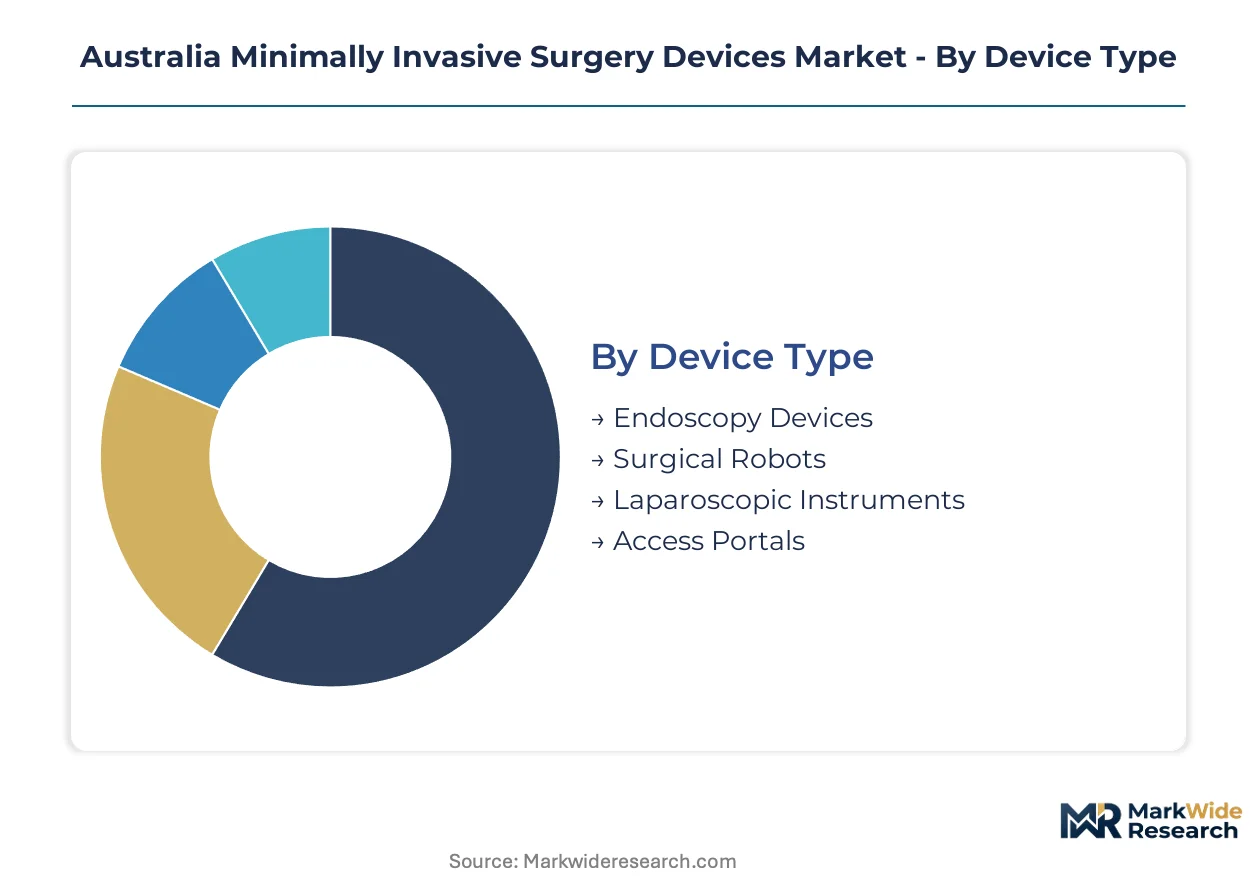
Device taxonomy in Australian minimally invasive surgery reveals distinct procurement rhythms. Capital-intensive platforms rotate on decade-long replacement cycles while disposable instruments generate quarterly replenishment orders that dominate vendor revenue streams.
Device Type:
Cycle times range from single-use disposables replaced per-procedure to robotic platforms depreciated over ten-year horizons.
- Endoscopy Devices:Flexible and rigid scopes with integrated camera channels process the highest procedural volumes across Australian public hospital networks. Gastroenterology suites in Sydney and Melbourne drive replacement demand as fiber optic components degrade under high-throughput sterilization protocols.
- Surgical Robots:Multi-armed da Vinci-style platforms command AUD 2-4 million capital outlays with proprietary instrument ecosystems. Tertiary centers in Brisbane justify installation through concentrated urological and gynecological case volumes that amortize fixed costs across high utilization rates.
- Laparoscopic Instruments:Graspers, scissors, and energy devices attach to reusable or disposable shafts depending on hospital sterilization capacity.
- Access Portals:Trocar and cannula systems establish pneumoperitoneum maintenance and instrument entry points.
Laparoscopic instruments anchor the volume base while surgical robots gain share at the steepest rate.
Application:
Procedure complexity tiers separate high-acuity interventions requiring robotic precision from high-volume standardizable techniques.
- Orthopedic Surgery:Arthroscopic joint repair and spinal navigation demand sub-millimeter accuracy that digital visualization systems now deliver through integrated optical tracking. Victorian public hospital procurement mandates 4K-3D hybrid platforms for new orthopedic suite capital allocations.
- Cardiovascular Procedures:Transcatheter valve replacement and electrophysiological ablation require specialized interventional platforms with fluoroscopy integration. Cardiac catheterization labs in Sydney's Royal Prince Alfred Hospital anchor demand for hybrid operating theater configurations.
- Urological Interventions:Prostatectomy and nephrectomy procedures represent established robotic surgery adoption.
- Gastrointestinal Surgery:Colorectal resection and bariatric procedures utilize standard laparoscopic towers.
Gastrointestinal surgery anchors the volume base while cardiovascular procedures expand most quickly.
End User:
Capital access stratification separates publicly funded tertiary centers from privately operated ambulatory facilities.
- Hospitals:Metropolitan tertiary public hospitals in New South Wales and Victoria consolidate purchasing power through state procurement consortiums. Centralized tender processes favor integrated platform vendors capable of delivering end-to-end laparoscopic ecosystems with training and maintenance bundles.
- Ambulatory Surgical Centers:Privately owned day-procedure facilities in Brisbane and Gold Coast corridors prioritize leasing arrangements over capital purchase. Per-procedure fee structures align vendor incentives with utilization optimization.
- Specialty Clinics:Gastroenterology and urology focused practices concentrate diagnostic endoscopy volumes.
- Research Laboratories:Academic medical centers in Melbourne and Sydney evaluate pre-commercial platforms.
Hospitals anchor the volume base while ambulatory surgical centers climb the fastest.
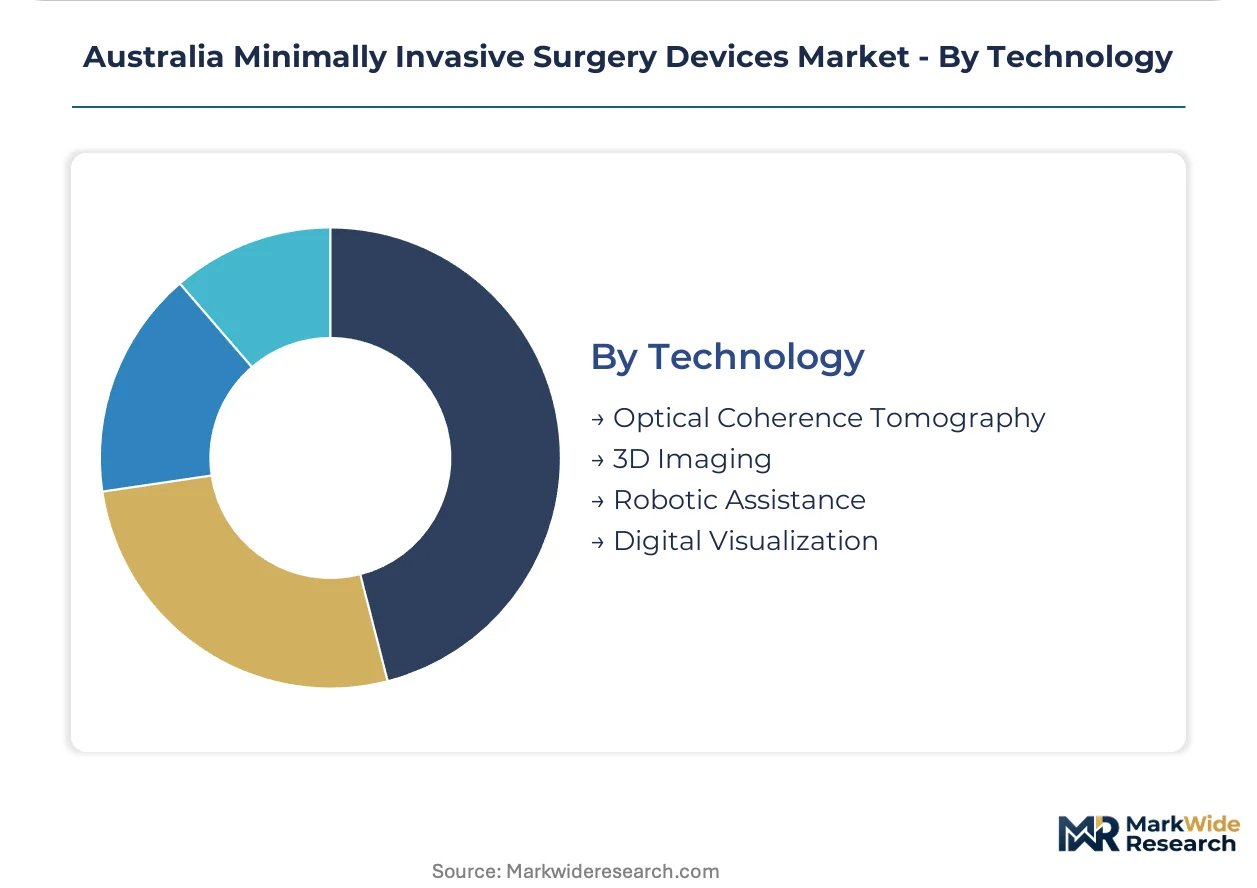
Technology:
Regulatory maturity separates TGA-cleared visualization standards from emerging software-enabled modalities awaiting conformity assessment.
- Digital Visualization:4K resolution camera towers with integrated insufflation and energy management now constitute baseline specifications in Victorian public tenders. New South Wales Health Pathology networks mandate these platforms for all metropolitan surgical suite refurbishments.
- Robotic Assistance:Telemanipulation systems with haptic feedback and motion scaling require dedicated facility infrastructure and surgeon credentialing pathways. TGA software-as-a-medical-device guidance imposes clinical validation requirements on autonomous surgical planning modules.
- 3D Imaging:Stereoscopic displays reduce depth perception errors in complex dissection.
- Optical Coherence Tomography:Microstructural tissue imaging enables real-time margin assessment.
Digital visualization anchors the volume base while robotic assistance shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's minimally invasive surgery devices sector operates as a net importer, with capital-intensive robotic platforms and specialized optical systems sourced predominantly from US and European manufacturing bases while domestic distribution networks handle final-mile service integration.
New South Wales
Metropolitan tertiary centers in Sydney anchor the nation's highest surgical robot density, with Royal Prince Alfred Hospital and Westmead Hospital driving da Vinci platform utilization for urological and gynecological procedures. State procurement consortiums under NSW Health Pathology mandate 4K-3D visualization standards in all new capital tenders. The Sydney Local Health District concentrates biomedical engineering talent for integrated system maintenance.
Victoria
Melbourne's Alfred Hospital and Royal Melbourne Hospital anchor public hospital adoption of laparoscopic platforms with bundled training and maintenance agreements. The state's Health Purchasing Victoria centralizes tender processes around integrated end-to-end surgical ecosystems. The Parkville biomedical precinct generates clinical validation data for TGA software-as-a-medical-device submissions.
Queensland
Brisbane's Princess Alexandra Hospital and Gold Coast University Hospital justify robotic installations through concentrated colorectal and bariatric case volumes. Queensland Health's procurement frameworks favor leasing arrangements over capital purchase in secondary centers. The state's regional hospital networks present underdeveloped demand for laparoscopic platform managed service agreements.
Western Australia
Sir Charles Gairdner Hospital in Perth maintains the state's highest minimally invasive surgical throughput for orthopedic navigation and spinal procedures. WA Health's centralized procurement operates with longer replacement cycles due to geographic isolation from eastern seaboard service hubs. The Perth metropolitan area concentrates the state's limited biomedical engineering capacity for complex system maintenance.
South Australia
Royal Adelaide Hospital anchors public sector adoption with focused deployment in gastrointestinal and hepatobiliary procedures. SA Health's smaller procurement scale limits vendor negotiation leverage compared with New South Wales and Victoria consortiums. The Adelaide biomedical corridor generates pre-commercial evaluation data for emerging optical coherence tomography platforms.
Australia Minimally Invasive Surgery Devices Market Competitive Environment
On the supply side, the industry is consolidated around multinational medical technology conglomerates with end-to-end platform capabilities, compressing margins for specialized instrument vendors while elevating barriers to entry for emerging players. Three strategic archetypes dominate: integrated platform vendors delivering camera-robot-energy ecosystems, specialized interventional device manufacturers, and diagnostic imaging hybrid players. Competitive moves concentrate on strategic partnerships with public procurement consortiums and portfolio diversification into software-enabled surgical planning modules.
Among US-based conglomerates, Medtronic PLC and Boston Scientific Corporation exemplify the integrated platform archetype, with the former anchoring public hospital tenders through comprehensive laparoscopic portfolios and the latter occupying specialized positions in cardiovascular and urological interventional segments. Stryker Corporation represents the orthopedic navigation specialization, integrating digital visualization with arthroscopic instrument lines to sustain dominance in joint repair procedures across Australian metropolitan tertiary centers.
| Leading Market Players |
|---|
| Medtronic PLC |
| Boston Scientific Corporation |
| Stryker Corporation |
| Zimmer Biomet |
| Intuitive Surgical Inc. |
| Smith & Nephew |
| Koninklijke Philips NV |
| Siemens Healthineers |
| Olympus Corporation |
| Others |
Value Chain & Pricing Dynamics
Sydney-Port Botany container freight corridors transmit cost volatility from Asia-Pacific manufacturing hubs into Australian surgical device pricing, compressing margins on imported robotic platforms while amplifying price differentiation between metropolitan tertiary centers and regional hospitals.
Pricing Analysis
Metropolitan hospital procurement consortiums anchor three-tier pricing structure across premium, standard, and economy levels. Premium robotic platforms command capital outlays justified by high utilization rates, while standard laparoscopic towers and economy disposable instruments stratify by sterilization protocol compliance and training bundle inclusion. Pricing pressure stems from NSW Health Pathology's mandated 4K-3D visualization standards, which force upgrade cycles before full depreciation. Regional hospitals exhibit highest price sensitivity due to constrained capital budgets, whereas Sydney and Melbourne tertiary centers prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Precision-machined surgical steel and optical sensor arrays feed from German, Japanese, and US manufacturing bases. Australian distributors draw from these concentrated supply nodes for camera towers, robotic arms, and energy devices. Single-source vulnerability concentrates in proprietary instrument ecosystems tied to specific robotic platforms. Distribution runs through state-level health procurement consortiums in New South Wales, Victoria, and Queensland, with final-mile service integration performed by domestic biomedical engineering networks concentrated in Sydney and Melbourne.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device category fragmentation across robotic, laparoscopic, and endoscopy platforms creates specialized vendor niches as TGA software-as-a-medical-device guidance splinters regulatory pathways and procurement requirements.
For Market Incumbents: Entrench platform dominance by securing preferred supplier status on NSW Health Pathology and Health Purchasing Victoria tender panels before TGA Medical Devices Reforms tighten evidence requirements. Deepen backward integration into AI-enabled surgical planning modules to preempt software-as-a-medical-device compliance burdens that threaten modular competitors. Lock in metropolitan tertiary centers with managed service agreements that transfer utilization risk and create switching costs.
For New Entrants and Emerging Players: Build out leasing-based go-to-market models targeting Queensland regional hospitals in Brisbane outer corridors and Gold Coast health districts, where capital constraints exclude outright robotic platform purchase. Focus initial penetration on disposable energy devices and single-use trocars where sterilization protocol shifts favor new suppliers over entrenched reusable instrument vendors. Pursue software companion development for existing installed base camera towers rather than competing on capital equipment.
For Investors and Strategic Acquirers: Specialized interventional platform developers with TGA-cleared cardiovascular or urological devices represent priority acquisition targets as consolidation pressure mounts from integrated ecosystem vendors. Long-term viability hinges on software-enabled revenue streams recurring across hardware replacement cycles. Watch for TGA guidance clarifications on AI surgical planning as inflection indicators for valuation step-ups in predictive analytics capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| TGA Software-as-a-Medical-Device Submission | Clinical validation for AI surgical planning tools unlocks recurring software revenue streams. |
| State Procurement Consortium Partnership | Preferred supplier status on NSW Health Pathology panels secures decade-long platform replacement cycles. |
| Managed Service Agreement Expansion | Per-procedure fee structures transfer utilization risk and deepen customer captivity in high-volume sites. |
| Biomedical Engineering Talent Acquisition | Sydney and Melbourne technician scarcity constrains regional rollout for competitors lacking service networks. |
| Single-Use Instrument Portfolio Development | Cross-contamination protocols in public health networks accelerate disposable migration over reusable alternatives. |
Study Parameters
Cross-validation between hospital procurement database analysis and TGA regulatory filing review anchors the qualitative findings in this study. Primary interviews with biomedical engineering directors, hospital purchasing committee members, GPO contracts managers, and laparoscopic surgeons informed demand-side dynamics. Secondary validation drew from TGA Medical Devices Reforms documentation, NSW Health Pathology tender records, Health Purchasing Victoria procurement frameworks, and Queensland Health capital budget disclosures. Bottom-up procedure volume modeling and top-down equipment installation tracking triangulated market sizing across the analysis window.
Calibration against historical replacement cycle data and state health capital budget trajectories shaped the projection framework. Segmentation dimensions span device type, application specialty, end-user facility tier, and technology maturity tier. CAGRs derive from fitted growth curves applied to equipment installation bases and per-procedure disposable consumption rates. Forecast inputs incorporate TGA software-as-a-medical-device guidance implementation timelines and state procurement panel technology mandate schedules.
Practitioners should monitor TGA essential principles updates and state health capital budget reallocations for early signals requiring forecast revision. Cross-checking against Australian Institute of Health and Welfare surgical procedure statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Device Outsourcing Market
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Cervical Fusion Market
Medical Devices
Artificial Urinary Sphincters Market
Medical Devices
Echogenic Catheters Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Organ Preservation Market
Medical Devices
Global Closed System Transfer Devices Market
Medical Devices
Digital Stethoscope Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
Asia-Pacific Ambulatory Infusion Pumps Market
Medical Devices
Russia Massage Equipment Market
Medical Devices
Morcellators Market
Medical Devices
Single-Use Centrifuge System Market
Medical Devices
Electrosurgery Accessories Market