
 Low Vision Aids Market | 2026-2036
Low Vision Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Low Vision Aids Market Analysis
A widening capability gap between optical heritage manufacturers and digital-native entrants is bifurcating competitive dynamics in low vision aids. Eschenbach Optik leverages century-old precision optics craftsmanship to sustain premium positioning across European specialized stores. eSight Corp. competes through wearable electronic platforms that integrate high-definition cameras with real-time image processing. HumanWare anchors North American distribution through rehabilitation center partnerships and direct-to-consumer channels.
Low vision aids encompass optical, electronic, and hybrid devices engineered to magnify, enhance contrast, or digitally process visual information for individuals with irreversible vision impairment, typically operating at magnification ranges from 2x to 75x depending on modality. Magnifiers and video magnifiers occupy the largest installed base due to established reimbursement pathways and clinician familiarity, while electronic aids represent the fastest-expanding margin pool as semiconductor miniaturization reduces unit costs. Telescopic lenses dominate distance-vision applications among educational institutions, where portability requirements favor lightweight optical designs over bulkier digital alternatives.
The FDA classifies electronic low vision aids as Class II medical devices requiring 510(k) clearance, while the EU Medical Device Regulation mandates CE marking with enhanced clinical evidence standards under EMA coordination. Japan's METI enforces JIS accessibility benchmarks that shape product specifications for domestic manufacturers and importers alike. Stakeholders must monitor evolving reimbursement coding decisions by Medicare and Japan's Ministry of Health, Labour and Welfare, as coverage determinations directly influence provider procurement velocity and patient out-of-pocket thresholds.
Market Dynamics
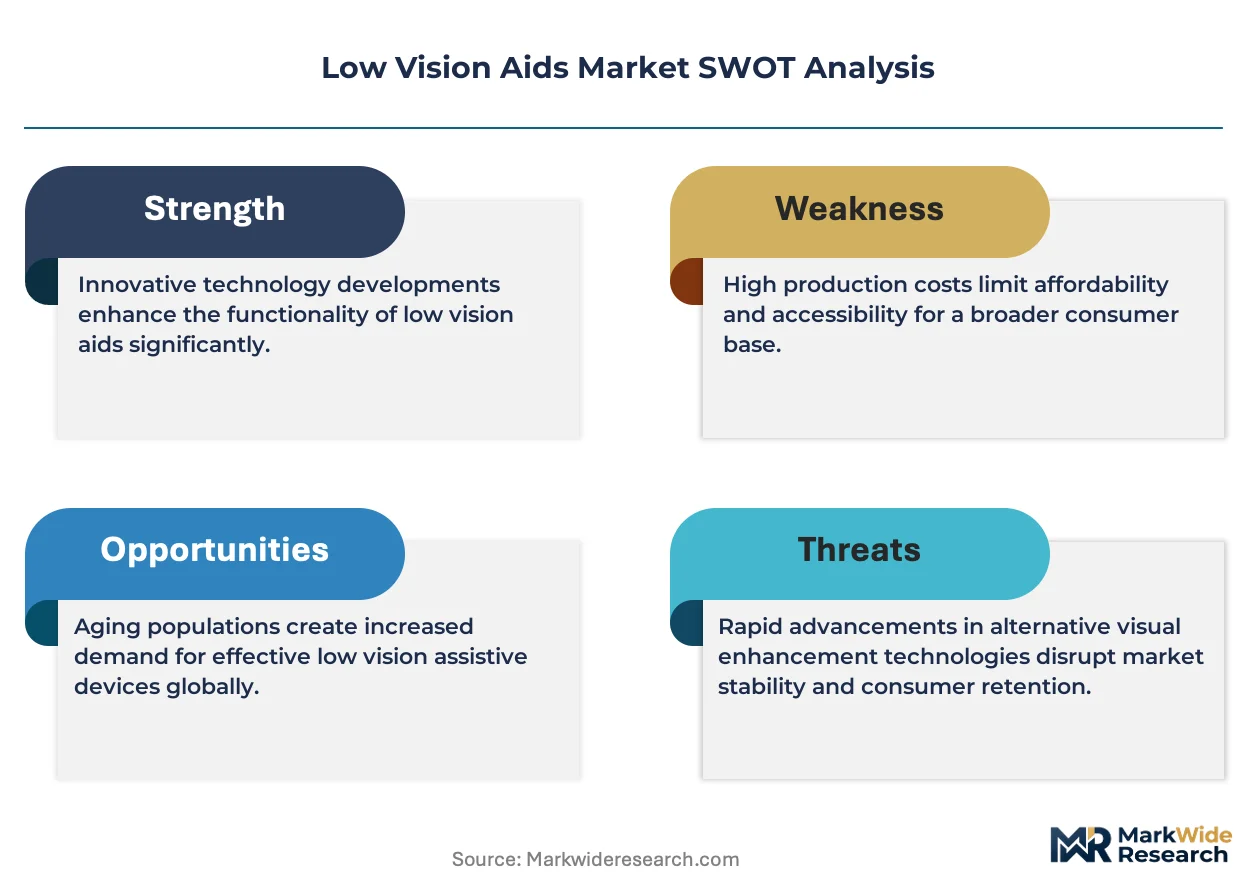
The low vision aids sector is experiencing a fundamental technology transition as semiconductor miniaturization enables camera-based electronic platforms to challenge traditional optical magnifiers at price points accessible to mass-market channels. This shift is compressing margins for heritage optics manufacturers while creating new reimbursement complexity for digital-native entrants.
Growth Catalysts
- Japan METI Accessibility Standards:Mandatory JIS benchmarks for public facilities and transportation infrastructure mandate procurement of certified low vision devices, creating institutional demand pull across municipal rehabilitation programs.
- Hybrid Optical-Digital Convergence:Devices combining precision lenses with real-time image processing address multiple impairment types simultaneously, expanding addressable patient populations beyond single-modality limitations.
- German Rehabilitation Center Expansion:EU Medical Device Regulation harmonization enables cross-border procurement frameworks, accelerating centralized purchasing of electronic aids by Bundeswehr and civilian rehabilitation networks.
Market Restraints
- Semiconductor Supply Concentration:Image sensor and processor fabrication concentrates in East Asian foundries, exposing device manufacturers to single-source vulnerability for critical components.
- FDA 510(k) Clinical Evidence Requirements:Electronic aid submissions require predicate device comparisons and performance validation studies that extend clearance timelines by 12-18 months versus optical device exemptions.
- Smartphone Camera Substitution:Native magnification and contrast adjustment applications on consumer mobile devices satisfy mild impairment needs at zero incremental hardware cost.
Strategic Opportunities
- India PLI Scheme for Medical Electronics:Production-linked incentives for domestic manufacturing of assistive devices reduce import duty exposure and enable price positioning below current landed cost structures.
- Direct-to-Consumer Channel Development:Telehealth-enabled remote fitting and prescription validation bypass traditional ophthalmology clinic gatekeepers, capturing patients earlier in impairment progression.
- ISO 9999 Standard Harmonization:Unified technical specifications for assistive products facilitate cross-border reimbursement recognition and reduce certification fragmentation for multi-market launches.
Industry Challenges
- Optometrist Training Deficits:Practitioners lack systematic education in electronic device prescription protocols, limiting patient referral rates for camera-based systems despite clinical efficacy evidence.
- Legacy System Integration Complexity:Electronic aids require compatibility with existing electronic health record workflows and telemedicine platforms, demanding costly software adaptation for institutional adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Vision Aids Market |
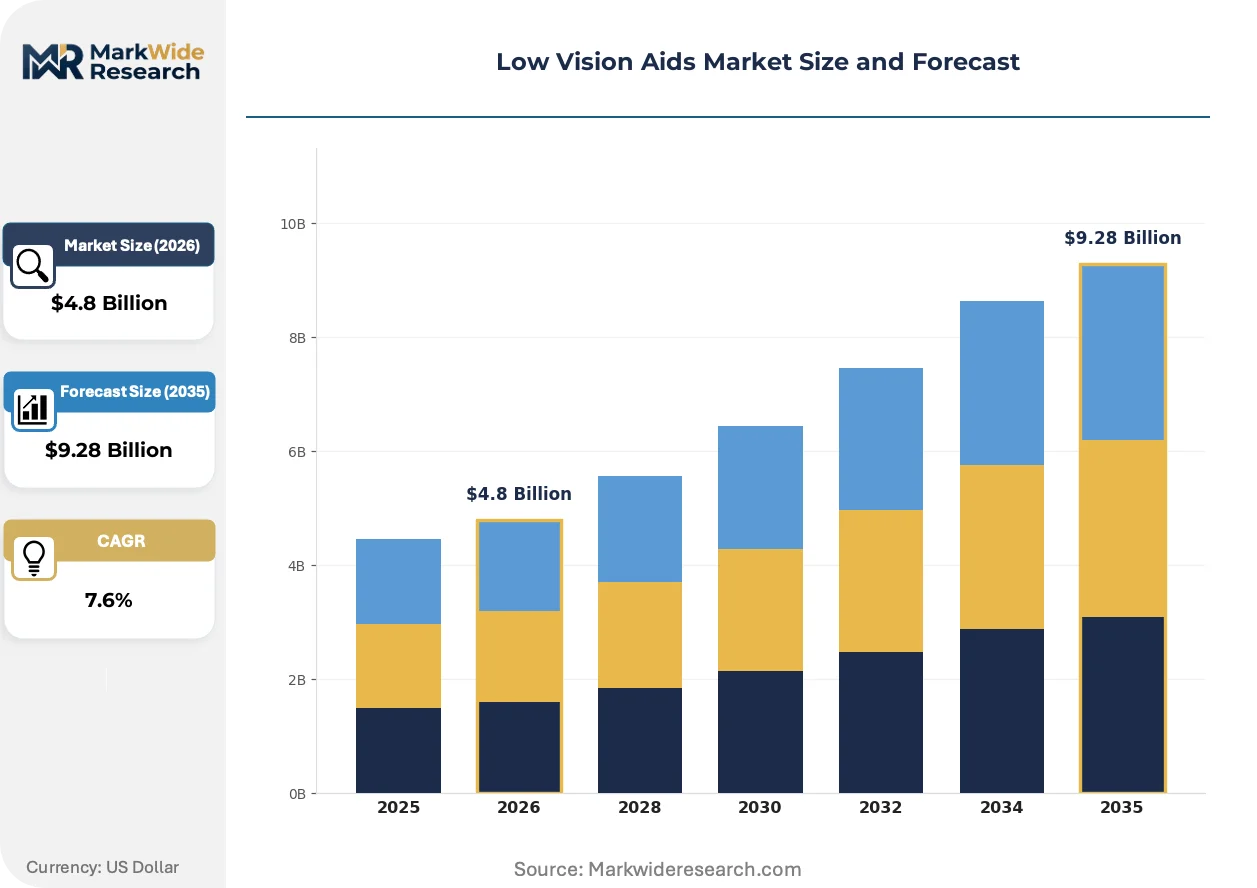
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnifiers, Telescopic Lenses, Electronic Aids, Video Magnifiers End User: Individuals, Healthcare Providers, Educational Institutions, Rehabilitation Centers Technology: Optical, Digital, Electronic, Hybrid Distribution Channel: Online, Retail, Healthcare Facilities, Specialized Stores |
| Companies Covered | eSight Corp., Schweizer Optik, Eschenbach Optik, Aumed Group Corp, LVI Low Vision International, HumanWare, ZOOMAX, Quantum, Enhanced Vision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Vision Aids Market Emerging Trajectories
Real-time image processing architectures are fundamentally altering how visual information gets presented to impaired users, shifting competitive advantage from optical precision to algorithmic performance. This transformation is redrawing capability boundaries between established and emerging market participants.
AI-powered scene interpretation is supplanting static magnification as the primary value driver in electronic low vision aids. These systems identify text, faces, and objects through neural network inference, then present audio or enhanced visual cues to users. Rehabilitation centers in Japan and Germany are piloting these platforms for workplace integration. The technology is supplanting occupational therapist-mediated task training by enabling independent navigation of complex visual environments.
EU Medical Device Regulation clinical evidence requirements are tightening post-market surveillance obligations for electronic low vision aids. Manufacturers must now maintain periodic safety update reports and vigilance databases beyond initial CE marking. Class IIa device reclassifications are most acute for wearable camera systems with software-driven outputs, forcing portfolio restructuring among European distributors.
Patients are bypassing traditional low vision clinics through direct online research and telehealth-enabled prescription pathways. This disintermediation compresses the evaluation window from months to weeks but increases return rates due to improper device matching. The pattern is most visible in North American markets where Medicare Advantage plans experiment with remote fitting reimbursement codes.
Low Vision Aids Market Segmentation
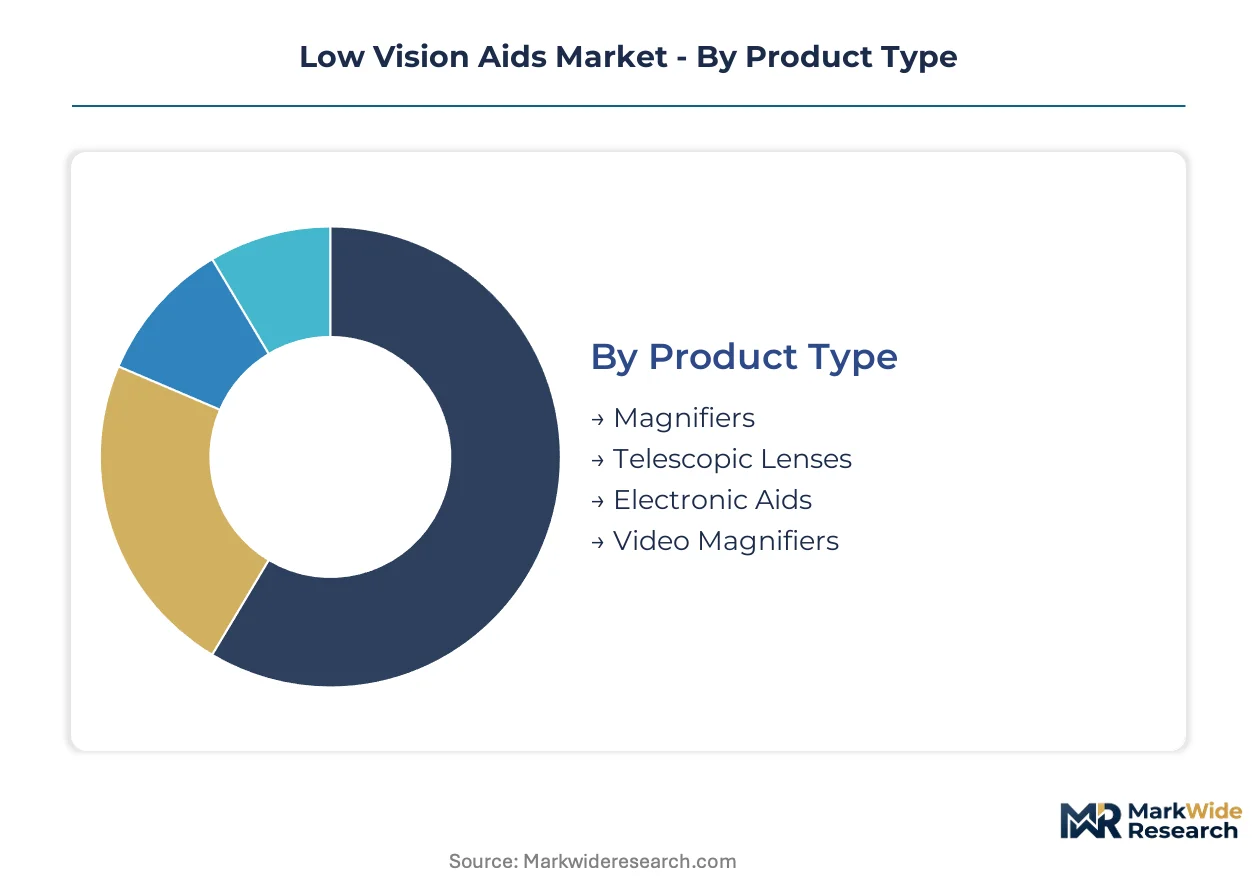
Segmentation in low vision aids reveals how substitution threats and reimbursement pathways reshape competitive boundaries across product categories. Understanding where smartphone cameras displace dedicated hardware versus where clinical-grade devices retain pricing power informs portfolio construction and channel strategy.
Product Type:
Magnifiers face the most acute substitution pressure from smartphone native applications, while electronic aids with proprietary image processing defend against commoditization through clinical validation and reimbursement lock-in.
- Magnifiers:Handheld and stand-mounted optical devices using precision-ground glass or acrylic lenses deliver 2x to 20x magnification without power requirements. Demand concentrates in German rehabilitation centers procuring under EU Medical Device Regulation frameworks, where durability specifications and institutional procurement contracts sustain volume despite consumer substitution.
- Electronic Aids:Wearable camera systems with real-time image processing and high-definition displays provide magnification up to 75x with contrast enhancement and scene interpretation. Japanese METI accessibility standards mandate certified device procurement for municipal programs, creating institutional demand pull that smartphone applications cannot satisfy.
- Telescopic Lenses:Bioptic and monocular optical systems for distance vision tasks in educational and mobility applications.
- Video Magnifiers:Desktop and portable CCTV-style systems combining camera, display, and illumination for extended reading tasks.
Magnifiers anchor the volume base while electronic aids gain share at the steepest rate.
End User:
Cost tier stratification separates reimbursement-dependent institutional procurement from out-of-pocket individual purchases, with educational institutions occupying a mid-tier position between clinical-grade and consumer-grade specifications.
- Rehabilitation Centers:Institutional purchasers operating under structured procurement frameworks demand FDA 510(k) or CE marked devices with clinical evidence packages and training support protocols. German Bundeswehr and civilian rehabilitation networks are expanding electronic aid procurement under harmonized EU Medical Device Regulation standards, with centralized purchasing reducing per-unit acquisition costs.
- Individuals:End-users with mild to moderate impairment increasingly research and purchase devices through direct-to-consumer channels, though return rates escalate when telehealth-enabled fitting protocols are skipped. Medicare Advantage plans in the United States are experimenting with remote fitting reimbursement codes that bypass traditional ophthalmology clinic gatekeepers.
- Healthcare Providers:Ophthalmology and optometry practices prescribing devices through clinical evaluation and insurance reimbursement pathways.
- Educational Institutions:Schools and universities procuring telescopic and video magnifier systems for student accommodation under disability services mandates.
Rehabilitation centers dominate procurement volume while individual direct purchases expand most quickly as telehealth infrastructure matures.
Technology:
Supply concentration in East Asian semiconductor fabrication shapes which technology platforms face component vulnerability versus which maintain diversified sourcing.
- Hybrid:Convergence architectures combining precision optical elements with digital image processing address multiple impairment types through single devices. Japanese manufacturers are prioritizing hybrid platforms under METI JIS accessibility benchmarks, with municipal rehabilitation programs piloting workplace integration for complex visual environment navigation.
- Electronic:Pure camera-based systems dependent on image sensors, processors, and displays with software-driven outputs. FDA Class II medical device classification with 510(k) clearance requirements and EU MDR post-market surveillance obligations create regulatory moats that optical-only competitors avoid.
- Optical:Traditional lens-based magnification without electronic components, exempt from most medical device regulatory pathways.
- Digital:Software-mediated enhancement on general-purpose computing platforms with lower hardware specificity.
Optical technology retains the largest installed base while hybrid platforms climb the fastest as semiconductor miniaturization enables cost-effective convergence.
Distribution Channel:
Customer type fragmentation across clinical, institutional, and consumer segments forces channel diversification that strains margin structures differently across each pathway.
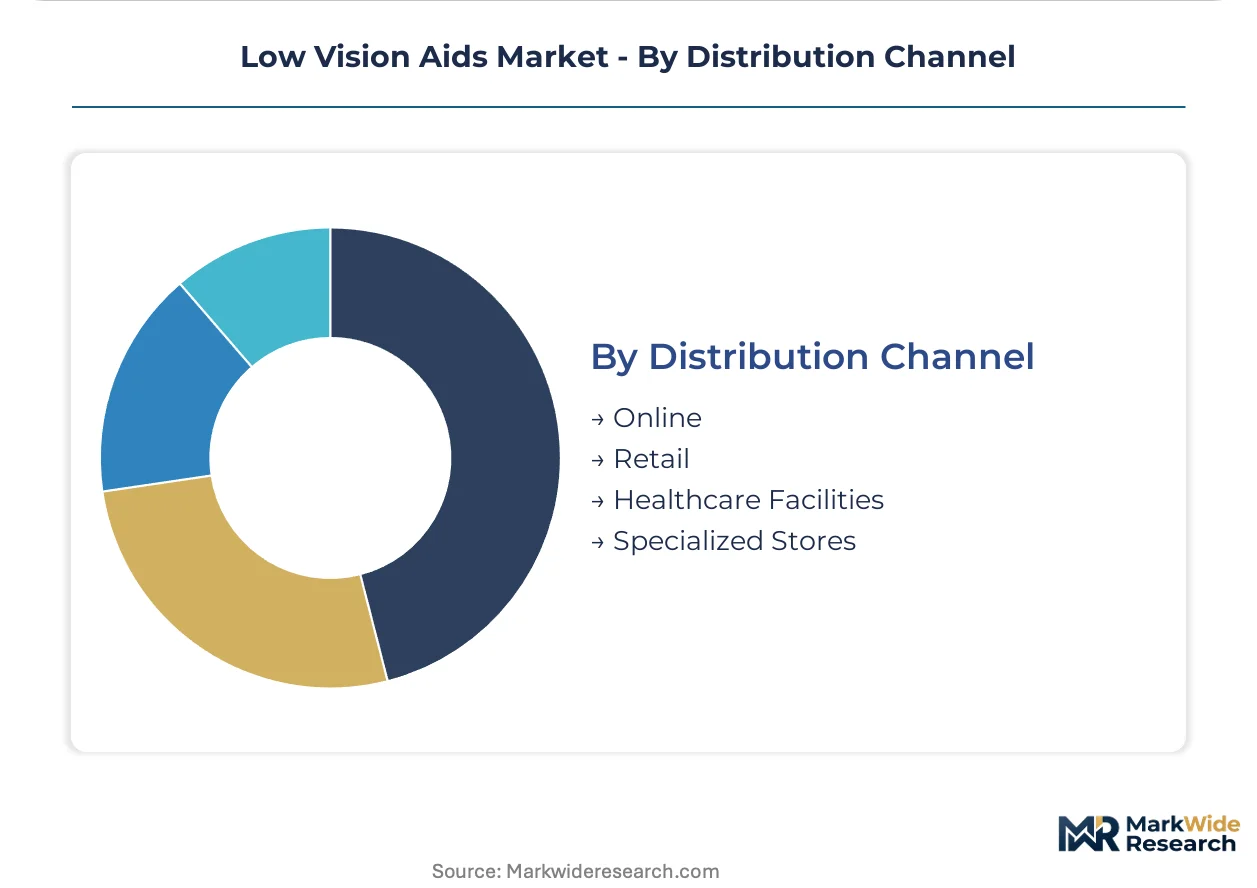
- Healthcare Facilities:Hospital and clinic-based dispensing integrated with electronic health record workflows and insurance reimbursement processing. Legacy system integration complexity demands costly software adaptation, with institutional adoption constrained by compatibility requirements with existing telemedicine platforms.
- Specialized Stores:Dedicated low vision and assistive technology retailers providing in-person fitting, training, and ongoing support services. Eschenbach Optik sustains premium positioning through European specialized store networks where century-old precision optics craftsmanship justifies price positioning.
- Online:Direct-to-consumer e-commerce with telehealth-enabled prescription validation and remote fitting protocols.
- Retail:General consumer electronics and pharmacy channels for entry-level magnifiers and basic optical devices.
Healthcare facilities dominate value capture while online channels expand most rapidly as remote fitting reimbursement codes proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. Japanese buyers absorb premium pricing for certified hybrid devices under institutional procurement, while Indian patients gravitate toward entry-level optical aids unless government subsidy programs intervene.
United States
Medicare Advantage plans are piloting remote fitting reimbursement codes that compress evaluation timelines from months to weeks. The FDA's 510(k) clearance pathway for Class II electronic devices mandates predicate comparisons that extend approval timelines versus optical exemptions. Boston's rehabilitation hospital network is expanding centralized procurement of video magnifier systems for veteran populations.
Germany
Bundeswehr and civilian rehabilitation networks are accelerating electronic aid procurement under harmonized EU Medical Device Regulation standards. The EU MDR's enhanced clinical evidence requirements and post-market surveillance obligations favor established manufacturers with regulatory infrastructure. Munich's assistive technology cluster is integrating telemedicine platforms with electronic health record workflows for institutional compatibility.
Japan
METI's mandatory JIS accessibility benchmarks for public facilities and transportation infrastructure create institutional demand pull across municipal rehabilitation programs. The Ministry of Health, Labour and Welfare's reimbursement determinations directly influence provider procurement velocity and patient out-of-pocket thresholds. Osaka manufacturers are prioritizing hybrid optical-digital platforms for workplace integration pilots.
India
The PLI scheme for medical electronics offers production-linked incentives that reduce import duty exposure and enable price positioning below current landed cost structures. CDSCO's medical device registration requirements are streamlining for domestically manufactured assistive products. Gujarat's emerging medical electronics manufacturing corridor is attracting component assembly investments for cost-sensitive market entry.
Low Vision Aids Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Heritage optical manufacturers sustain premium positioning through craftsmanship differentiation and specialized retail relationships. Digital-native entrants compete on semiconductor-enabled feature sets and direct-to-consumer channel economics. The dominant competitive moves are strategic partnerships with rehabilitation networks and portfolio diversification into hybrid convergence architectures.
Within the heritage optics tier, Eschenbach Optik and Schweizer Optik exemplify century-old precision craftsmanship positioning. eSight Corp. occupies the wearable electronic platform vector, representing digital-native entrants competing through real-time image processing integration. These three anchors illustrate how competitive advantage is shifting from optical precision to algorithmic performance and channel accessibility.
| Leading Market Players |
|---|
| eSight Corp. |
| Schweizer Optik |
| Eschenbach Optik |
| Aumed Group Corp |
| LVI Low Vision International |
| HumanWare |
| ZOOMAX |
| Quantum |
| Enhanced Vision |
| Others |
Supply Flow & Price Mechanics
Semiconductor miniaturization replacing bulk optical components simultaneously shifts manufacturing gravity toward East Asian foundries and compresses hardware margins across electronic aid tiers. This substitution dynamic forces heritage optics manufacturers to defend premium positioning through craftsmanship differentiation while digital-native entrants compete on feature density at mass-market price points.
Pricing Analysis
After-sales service contracts and training support packages drive lifetime value capture for institutional procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k) cleared devices with clinical evidence packages from basic optical magnifiers and smartphone-accessory peripherals. Cost compression in the electronic aid tier intensifies because semiconductor foundry competition reduces image sensor unit economics. Rehabilitation centers demonstrate lowest price sensitivity due to reimbursement pathways, while individual direct purchasers exhibit highest elasticity and elevated return rates.
Supply Chain Analysis
Inbound logistics costs from East Asian container ports to European and North American distribution hubs expose manufacturers to congestion volatility on the Shanghai-Rotterdam and Busan-Long Beach trade lanes. Image sensor fabrication concentrates in Taiwan and South Korea, while display panel assembly anchors in China and Vietnam. Supply chains draw from CMOS sensors, OLED microdisplays, and lithium-polymer battery cells. Single-source vulnerability for 7nm and below processor nodes creates procurement risk. Distribution runs through rehabilitation center networks, specialized retail, and direct-to-consumer telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Systematic shortages in optometrist training for electronic device prescription protocols create a bottleneck that constrains patient referral rates regardless of product efficacy. This capability gap separates manufacturers who invest in clinician education infrastructure from those dependent on traditional optical channel relationships.
For Market Incumbents: Fortify proprietary image processing algorithms through backward integration into semiconductor design partnerships, defending against digital-native entrants with superior AI scene interpretation. Escalate certification investments for EU MDR Class IIa reclassifications to maintain institutional procurement access. Deepen rehabilitation center training protocols to offset optometrist prescription deficits and sustain referral velocity. For New Entrants and Emerging Players: Anchor in India's PLI scheme manufacturing corridor to achieve landed cost positioning below import duty-burdened competitors. Target municipal rehabilitation programs in Japan where METI JIS accessibility mandates create institutional demand pull with limited domestic supply. Deploy telehealth-enabled remote fitting as the primary go-to-market angle to bypass ophthalmology clinic gatekeepers and compress evaluation timelines. For Investors and Strategic Acquirers: Capital is best deployed toward hybrid optical-digital platform developers with established CE marking and FDA 510(k) regulatory infrastructure. Long-term viability across the analysis window favors manufacturers with demonstrated institutional procurement relationships and software-driven recurring revenue models. Monitor Medicare Advantage remote fitting reimbursement code expansions as the critical inflection signal for direct-to-consumer channel economics.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR harmonization enables cross-border procurement by German rehabilitation networks under centralized purchasing frameworks. |
| Hybrid Platform Development | Convergence architectures address multiple impairment types simultaneously, expanding addressable patient populations beyond single-modality limitations. |
| Telehealth Integration Partnership | Remote fitting protocols bypass traditional ophthalmology gatekeepers and capture patients earlier in impairment progression. |
| Reimbursement Strategy Execution | Medicare Advantage and Japan MHLW coverage determinations directly influence provider procurement velocity and patient out-of-pocket thresholds. |
| Hospital System Partnership | Boston's rehabilitation hospital network demonstrates centralized procurement models for veteran populations with structured clinical evidence requirements. |
Methodological Framework
A standing panel of low vision rehabilitation directors, biomedical engineers at Bundeswehr facilities, ophthalmology procurement committee members, and METI accessibility standard officers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) clearance databases, EU MDR notified body submissions, Japan MHLW reimbursement determinations, and hospital GPO contract repositories. Bottom-up unit economics modeling and top-down market sizing triangulated volume and value estimates.
Consistency checks against external benchmarks validated projection outputs across the modeling period. The analytical framework segmented by product type, end user, technology platform, and distribution channel, with additional modeling of regulatory cluster effects. CAGRs derived from fitted growth curves incorporating semiconductor cost decline trajectories and reimbursement code expansion assumptions. Forecast inputs included image sensor price elasticity and optometrist training program penetration rates.
Material uncertainties — reimbursement coding reversals, semiconductor supply disruptions, and regulatory reclassification decisions — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology substitution rates and institutional procurement velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
France Contraceptive Devices Market
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market
Medical Devices
Medical Puncture Navigation Robot Market
Medical Devices
Fracture Fixation Products Market
Medical Devices
Hormonal Implants Market
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Global Surgical Polypropylene Mesh Market
Medical Devices
Powered Mattress System Market
Medical Devices
India Contraceptive Devices Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Membrane Oxygenators Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
Indwelling Pleural Catheters Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Australia Clear Aligner Market
Medical Devices
Portable OT Light Market