
 Asia-Pacific Refractive Surgery Devices Market | 2026-2036
Asia-Pacific Refractive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Refractive Surgery Devices Market Outlook
Hospital procurement consortia across the Asia-Pacific is reconfiguring how femtosecond laser platforms reach end users. Carl Zeiss Meditec leverages its established service infrastructure to sustain recurring revenue from high-margin maintenance contracts. Alcon anchors its position through direct specialist training programs that lock in physician loyalty. NIDEK competes aggressively on system pricing while extending localized manufacturing presence in the region.
Refractive surgery devices encompass excimer lasers, femtosecond lasers, diagnostic aberrometers, and microkeratomes engineered to reshape corneal stroma with sub-micron precision, typically operating at wavelengths of 193 nm for excimer ablation and pulse durations below 500 femtoseconds for flap creation or lenticule extraction. These systems correct ametropia by photoablative tissue removal or mechanical dissection, restoring emmetropic focus without permanent implantation. Femtosecond platforms now dominate capital expenditure flows among ophthalmology centers, while wavefront-guided customization commands premium positioning over conventional LASIK. SMILE procedures represent the fastest-growing procedural category as surgeons convert from flap-based techniques to single-incision lenticule extraction for myopia correction.
Japan's PMDA maintains stringent pre-market approval pathways for laser ophthalmic equipment, while Australia's TGA enforces ISO 13485 quality system mandates that filter out lower-tier manufacturers. India's CDSCO and China's NMPA both require local clinical trial data for Class C and D medical devices, extending time-to-market for imported platforms. Stakeholders must monitor how ASEAN harmonization of medical device directives reshapes registration burdens and whether domestic substitution policies in China redirect procurement toward local excimer laser developers.
Market Dynamics
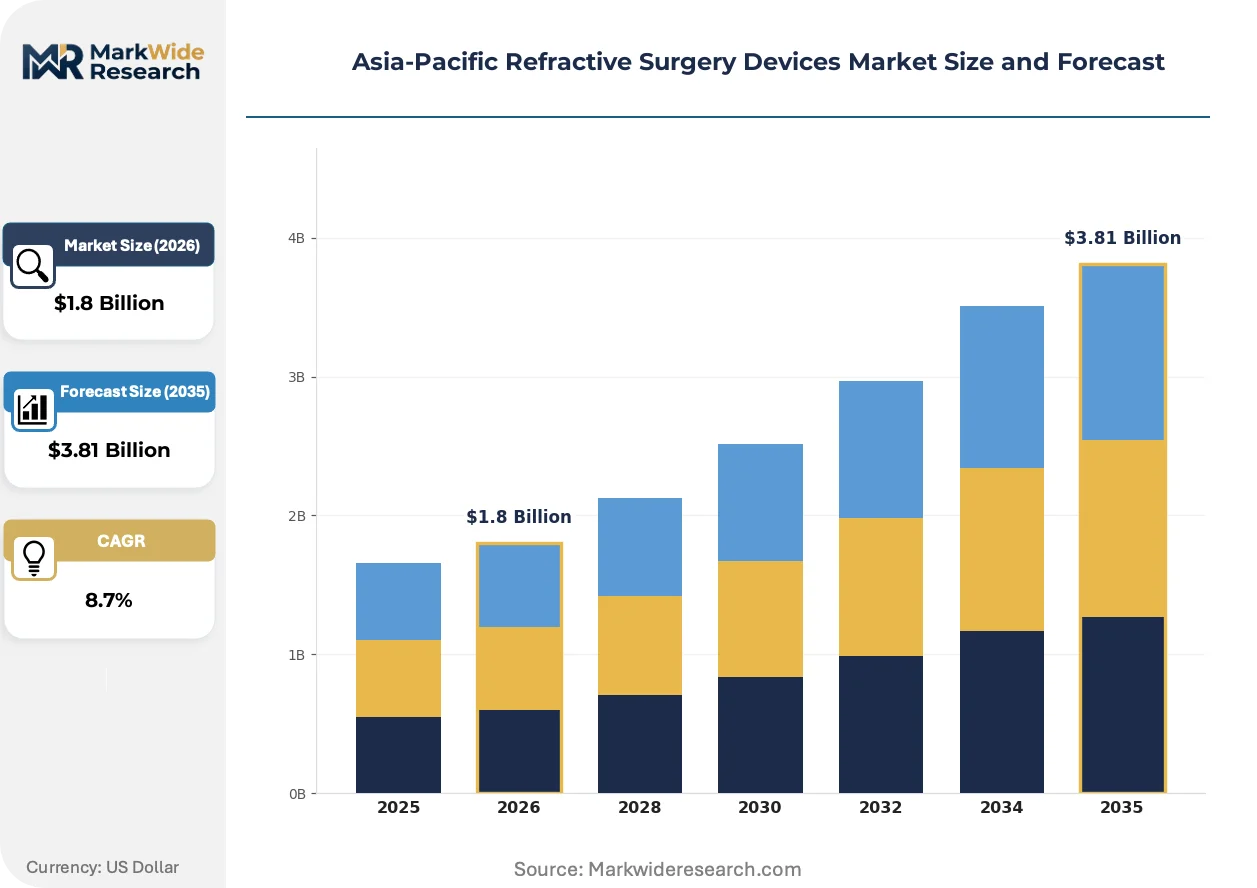
Femtosecond laser platforms are capturing capital allocation flows across ophthalmology centers as surgeons abandon mechanical microkeratomes for bladeless flap creation and lenticule extraction techniques. This technology substitution is compressing equipment replacement cycles and reshaping vendor-service relationships throughout the region.
Growth Catalysts
- Myopia Epidemic in Young Adults:China's tier-one cities report screening volumes exceeding 15 million annual eye examinations among university-age populations, creating sustained procedure pipeline demand for excimer and femtosecond systems.
- CDSCO Quality Harmonization:India's tightened medical device norms for imported excimer lasers are filtering substandard equipment, elevating average selling prices for compliant platforms while protecting patient outcomes.
- SMILE Procedural Conversion:Single-incision lenticule extraction techniques are displacing conventional LASIK flap procedures, driving replacement demand for compatible femtosecond platforms across Southeast Asian private ophthalmology chains.
Market Restraints
- Import Dependency for Optical Components:German and Japanese suppliers dominate ultrafast laser resonator assemblies, exposing procurement costs to EUR-JPY exchange volatility and concentrated supply risk.
- PMDA Approval Timelines:Japan's pre-market approval pathways for laser ophthalmic equipment extend registration durations to 24-36 months, delaying revenue recognition for novel platform introductions.
- Technical Limitation in Hyperopia Correction:SMILE techniques demonstrate reduced predictability for hyperopic corrections above +3.00 diopters, constraining addressable procedure volumes relative to excimer alternatives.
Strategic Opportunities
- Underpenetrated Secondary Cities:Vietnam's Ho Chi Minh City and Da Nang ophthalmology centers operate below 30% femtosecond laser penetration rates, presenting first-mover installation opportunities for equipment vendors with localized service capabilities.
- ASEAN Harmonization Tailwind:Converging medical device directives across Southeast Asian markets are reducing duplicate registration burdens, enabling centralized regulatory strategies for multi-country platform launches.
- Diagnostic-Ablative Convergence:Integration of high-resolution aberrometry with femtosecond treatment planning software is enabling same-day screening-to-surgery workflows, differentiating premium service offerings in saturated tier-one markets.
Industry Challenges
- Corneal Refractive Surgery Specialist Scarcity:Australia's TGA-mandated training hour requirements for SMILE certification create bottlenecks in qualified surgeon supply, constraining procedural throughput expansion.
- Legacy Excimer Laser Stranded Assets:China's NMPA clinical trial requirements for Class C device registrations complicate trade-in programs for 5-7 year old excimer platforms, depressing residual values and financing flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Refractive Surgery Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LASIK, PRK, SMILE, Cataract Technology: Laser-Assisted, Mechanical, Femtosecond, Wavefront Application: Myopia, Hyperopia, Astigmatism, Presbyopia End User: Hospitals, Clinics, Ophthalmology Centers, Others |
| Companies Covered | Johnson & Johnson Vision, Carl Zeiss Meditec, Alcon, Bausch + Lomb, NIDEK, Topcon Corporation, STAAR Surgical, SCHWIND eye-tech-solutions, Ziemer Ophthalmic Systems, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Refractive Surgery Devices Market Strategic Shifts
Wavefront-guided customization protocols and artificial intelligence-enhanced treatment planning are compressing variance in refractive outcomes while elevating patient selection precision. These capabilities are redefining competitive differentiation beyond hardware specifications toward integrated software-ecosystem value.
Femtosecond laser technology is migrating from flap creation applications toward all-in-one lenticule extraction and intrastromal incision platforms. High-volume ophthalmology chains in South Korea and Taiwan are adopting these consolidated systems at 18-24 month replacement cycles. The technology is migrating from premium positioning toward standard-of-care expectation, compressing margins for single-function legacy equipment.
China's NMPA and India's CDSCO now mandate local clinical trial data for Class C and D medical device registrations, extending time-to-market for imported excimer laser platforms by 12-18 months. This regulatory friction is redirecting foreign vendor strategies toward joint development partnerships with domestic manufacturers. Southeast Asian markets with ASEAN harmonization agreements are experiencing accelerated registration pathways as manufacturers leverage Singapore HSA approvals for regional mutual recognition.
Hospital procurement consortia across Thailand and Malaysia are consolidating equipment purchasing decisions into centralized tender processes, displacing individual surgeon-driven capital expenditure authority. Device vendors are responding with multi-system bundled offerings and performance-based maintenance contracts. This concentration is most visible in Bangkok and Kuala Lumpur, where three consortium groups control 60% of annual femtosecond laser acquisitions.
Asia-Pacific Refractive Surgery Devices Market Segmentation
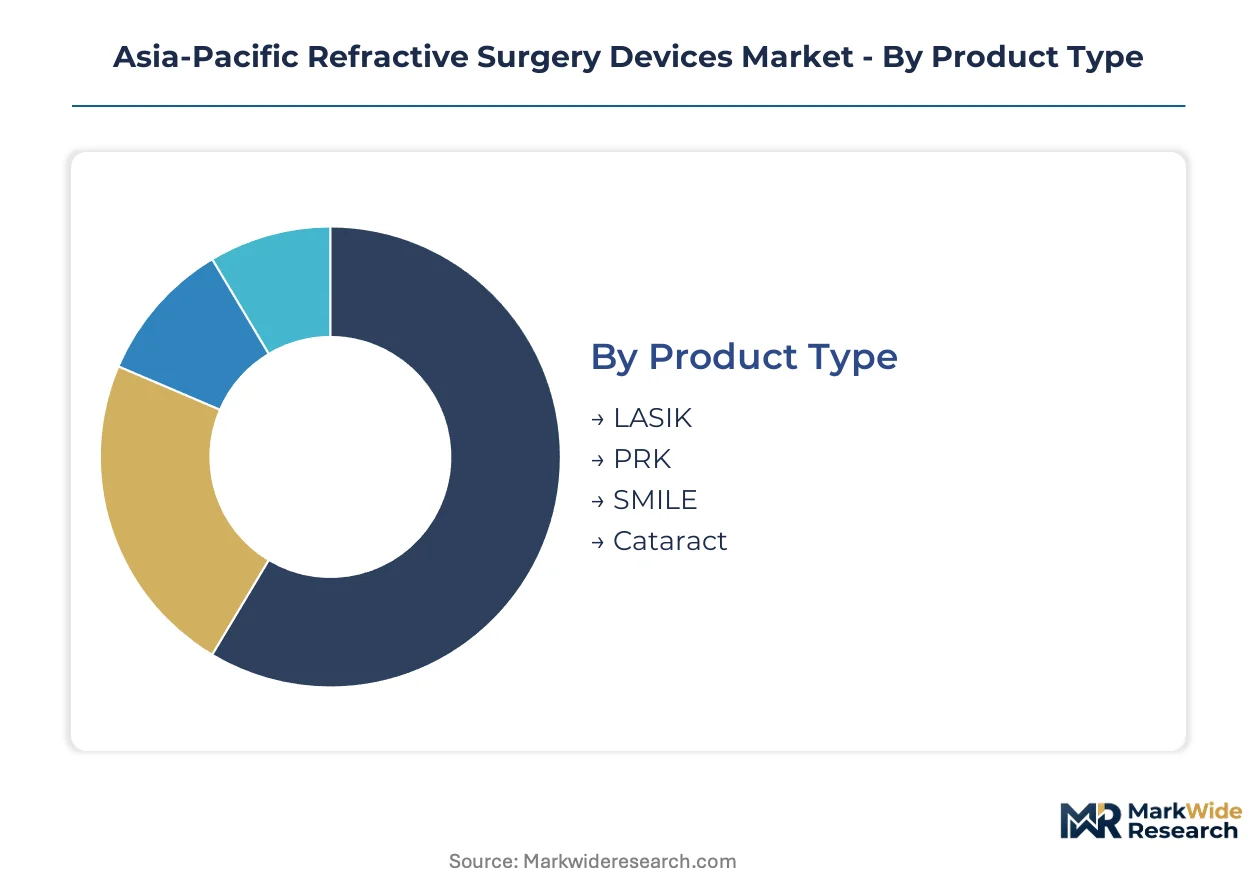
Refractive surgery devices segment across procedure type, ablation technology, visual indication, and care setting. Each dimension shapes equipment procurement patterns, service contract structures, and margin profiles differently across the Asia-Pacific region.
Product Type:
After-sales-service intensity varies sharply across procedure categories, with femtosecond-dependent platforms demanding specialized technician deployment and consumable replenishment cycles that lock vendors into multi-year maintenance relationships.
- SMILE:Single-incision lenticule extraction eliminates flap creation entirely, reducing postoperative dry eye incidence. Private ophthalmology chains in South Korea and Taiwan are converting conventional LASIK suites to SMILE-compatible configurations, driving replacement demand for integrated femtosecond platforms.
- LASIK:Flap-based laser-assisted stromal ablation remains the volume workhorse across India's tier-two cities where equipment amortization cycles extend beyond seven years. CDSCO's tightened quality norms for imported excimer lasers are elevating compliance costs for legacy system operators.
- PRK:Surface ablation without flap creation serves thin-cornea patients and military recruits across Australia's defense-linked screening programs.
- Cataract:Refractive lens exchange procedures overlap with premium IOL implantation workflows in Thailand's medical tourism corridors.
SMILE holds the largest share; momentum sits with LASIK in cost-sensitive secondary markets.
Technology:
Capital allocation patterns across the Asia-Pacific reveal a cost-tier stratification, with university hospitals absorbing premium wavefront-guided platforms while independent clinics prioritize mechanical reliability over diagnostic sophistication.
- Femtosecond:Ultrafast pulse lasers below 500 femtoseconds enable bladeless flap creation and lenticule extraction with sub-micron precision. China's NMPA clinical trial requirements for Class C device registrations are extending time-to-market for imported platforms, favoring vendors with localized manufacturing partnerships.
- Wavefront:Aberrometry-guided customization maps higher-order optical aberrations for personalized ablation profiles. Japan's PMDA maintains stringent pre-market approval pathways that filter out lower-tier manufacturers, protecting premium positioning for compliant systems.
- Laser-Assisted:Broad category encompassing excimer-based tissue photoablation at 193 nm wavelength across conventional treatment protocols.
- Mechanical:Microkeratome blade systems persist in Vietnam's emerging markets where capital constraints outweigh precision advantages of laser platforms.
Femtosecond dominates capital flows; wavefront platforms are gaining share fastest in saturated tier-one markets.
Application:
Volume concentration varies by visual indication, with myopia correction absorbing the majority of screening-to-surgery pipelines while hyperopia and presbyopia applications remain technically constrained or demographically limited.
- Myopia:Corrective procedures for nearsightedness address the dominant visual impairment across East Asian youth populations. China's tier-one cities report screening volumes exceeding 15 million annual eye examinations among university-age cohorts, sustaining procedure pipeline demand.
- Astigmatism:Toric ablation protocols correct corneal curvature irregularities, frequently combined with myopia or hyperopia treatment in wavefront-guided platforms.
- Hyperopia:Farsightedness correction above +3.00 diopters demonstrates reduced predictability with SMILE techniques, constraining addressable volumes relative to excimer alternatives.
- Presbyopia:Age-related near-vision loss correction targets working professionals over 45, overlapping with premium lens exchange procedures rather than corneal reshaping.
Myopia correction commands the largest share; astigmatism combination procedures show the steepest expansion trajectory as diagnostic precision improves.
End User:
Customer type determines procurement authority structures, with hospital consortia centralizing tender decisions while individual ophthalmology centers retain surgeon-driven capital expenditure autonomy.
- Ophthalmology Centers:Specialized refractive surgery facilities concentrate high-volume procedural throughput and premium platform adoption. Bangkok and Kuala Lumpur consortia control 60% of annual femtosecond laser acquisitions through centralized tender processes.
- Hospitals:General acute care institutions integrate refractive services within broader ophthalmology departments, prioritizing multi-purpose diagnostic equipment over dedicated laser platforms.
- Clinics:Small-format private practices in Indonesia and the Philippines operate below 30% femtosecond penetration, presenting first-mover installation opportunities for vendors with localized service capabilities.
- Others:Military screening facilities, corporate wellness programs, and medical tourism operators constitute fragmented demand pockets with specialized procurement timelines.
Ophthalmology centers hold the largest share; clinics in underpenetrated secondary cities are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA clinical trial mandates for Class C and D medical devices are redirecting foreign vendor strategies toward joint development partnerships with domestic manufacturers. India's CDSCO tightened quality norms for imported excimer lasers are elevating compliance costs while protecting patient outcomes. Japan's PMDA maintains stringent pre-market approval pathways that filter out lower-tier manufacturers.
China
Screening volumes in Beijing, Shanghai, and Guangzhou exceed 15 million annual eye examinations among university-age cohorts, sustaining procedure pipeline demand for excimer and femtosecond systems. NMPA requires local clinical trial data for Class C and D device registrations, extending time-to-market for imported platforms by 12-18 months. The Yangtze River Delta and Pearl River Delta clusters concentrate domestic substitution policies redirecting procurement toward local excimer laser developers.
India
Tier-two cities extend equipment amortization cycles beyond seven years for flap-based laser-assisted stromal ablation systems, sustaining LASIK as the volume workhorse. CDSCO tightened medical device quality norms for imported excimer lasers filter substandard equipment, elevating average selling prices for compliant platforms. Maharashtra and Karnataka ophthalmology centers absorb premium wavefront-guided platforms while independent clinics prioritize mechanical reliability over diagnostic sophistication.
Japan
Pre-market approval pathways for laser ophthalmic equipment extend registration durations to 24-36 months, delaying revenue recognition for novel platform introductions. PMDA maintains stringent quality system mandates that protect premium positioning for compliant systems. The Kanto region around Tokyo concentrates high-volume procedural throughput and premium platform adoption among specialized refractive surgery facilities.
South Korea
High-volume ophthalmology chains adopt consolidated femtosecond systems at 18-24 month replacement cycles, migrating technology from premium positioning toward standard-of-care expectation. MFDS regulatory frameworks align with international standards while maintaining rigorous device safety protocols. The Seoul Capital Area drives fastest-growing procedural category conversion as surgeons shift from flap-based techniques to single-incision lenticule extraction for myopia correction.
Australia
TGA enforces ISO 13485 quality system mandates that filter out lower-tier manufacturers from the ophthalmic laser equipment market. Mandated training hour requirements for SMILE certification create bottlenecks in qualified surgeon supply, constraining procedural throughput expansion. Sydney and Melbourne hospital procurement consortia centralize equipment purchasing decisions into centralized tender processes, displacing individual surgeon-driven capital expenditure authority.
Asia-Pacific Refractive Surgery Devices Market Competitive Environment
On the supply side, the industry is consolidating around multi-product ophthalmic portfolios with integrated service ecosystems. Three to five dominant vendors capture the majority of capital expenditure flows across the region's premium ophthalmology centers. Strategic archetypes include German-Japanese precision equipment specialists, American diversified eye care conglomerates, and Swiss-German niche laser technology developers. Competitive moves center on localized manufacturing partnerships to bypass extended regulatory timelines, and multi-system bundled offerings with performance-based maintenance contracts to secure hospital consortium procurement decisions.
Within the diversified eye care conglomerate tier, Johnson & Johnson Vision and Alcon occupy positions that span diagnostic through surgical intervention portfolios. Carl Zeiss Meditec exemplifies the German precision equipment specialist archetype, anchoring premium positioning through established service infrastructure. NIDEK represents the Japanese diversified ophthalmic technology developer, competing on system pricing while extending localized manufacturing presence. These three anchors collectively shape vendor-service relationships and maintenance contract structures throughout the Asia-Pacific region.
| Leading Market Players |
|---|
| Johnson & Johnson Vision |
| Carl Zeiss Meditec |
| Alcon |
| Bausch + Lomb |
| NIDEK |
| Topcon Corporation |
| STAAR Surgical |
| SCHWIND eye-tech-solutions |
| Ziemer Ophthalmic Systems |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on German and Japanese ultrafast laser resonator assemblies determines both pricing tier spreads and supply chain shape across the Asia-Pacific refractive surgery devices market. Procurement costs for excimer and femtosecond platforms swing with EUR-JPY exchange volatility, compressing margins for vendors locked into long-term service contracts while elevating premiums for systems with localized component sourcing.
Pricing Analysis
Certification level creates the primary spread between premium and standard equipment tiers, with PMDA-approved and NMPA-registered platforms commanding substantial premiums over non-compliant alternatives. Pricing stratifies across three tiers: wavefront-guided femtosecond systems with integrated diagnostics at the premium level, conventional femtosecond platforms at standard positioning, and refurbished excimer lasers serving cost-constrained secondary markets. Price erosion runs through the standard tier as ASEAN harmonization reduces registration barriers and expands vendor competition. Independent clinics in Vietnam and Indonesia exhibit highest price sensitivity, while hospital procurement consortia in Bangkok and Kuala Lumpur absorb premium positioning through centralized tender processes.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from German and Japanese optical component suppliers anchor working capital structures for equipment vendors serving the region. Manufacturing concentration rests on Germany, Japan, and Switzerland for ultrafast laser resonators, precision optics, and motion control systems. Critical dependencies include titanium-sapphire crystals, excimer gas mixtures, and sub-micron positioning stages. Single-source vulnerability in femtosecond laser cavity assemblies exposes procurement timelines to concentrated supplier capacity. Distribution runs through authorized dealer networks with localized service technicians, supplemented by direct hospital consortium contracts in consolidated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory clusters and procedural adoption stages creates multiple niche entry points. SMILE conversion in South Korea and Taiwan, combined with underpenetrated secondary cities in Southeast Asia, generates demand pockets beyond incumbent strongholds.
For Market Incumbents: Pre-empt SMILE-compatible platform commoditization by embedding proprietary treatment planning software and locking in multi-year maintenance contracts. Counter NIDEK's aggressive system pricing through performance-based service agreements that tie vendor revenue to procedural uptime metrics. Fortify position against domestic Chinese excimer laser developers by accelerating joint manufacturing partnerships that bypass NMPA clinical trial timelines.
For New Entrants and Emerging Players: Pursue first-mover installation opportunities in Vietnam's Ho Chi Minh City and Da Nang ophthalmology centers, where femtosecond penetration rates sit below 30%. Target India's tier-two cities with refurbished platform leasing models that align payment schedules to equipment utilization rates. Lead with localized technician training programs that address Australia's TGA-mandated SMILE certification bottlenecks.
For Investors and Strategic Acquirers: ASEAN harmonization of medical device directives reshapes the acquisition landscape by reducing duplicate registration burdens and enabling centralized regional strategies. Position for 5-10 year viability by targeting Swiss-German niche laser technology developers with proprietary femtosecond IP and established Asia-Pacific service footprints. Monitor CDSCO enforcement actions against non-compliant imported excimer lasers as an inflection indicator for market share redistribution toward quality-certified vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Localized Manufacturing Partnership | Bypasses NMPA and CDSCO clinical trial requirements, compressing time-to-market for imported platforms. |
| Software-Ecosystem Integration | Links diagnostic aberrometry to femtosecond treatment planning, differentiating beyond hardware specifications. |
| Performance-Based Maintenance Contract | Aligns vendor revenue with procedural uptime, securing hospital consortium procurement decisions in Bangkok and Kuala Lumpur. |
| Surgeon Certification Program | Addresses Australia's TGA-mandated training bottlenecks while locking in physician loyalty to specific platforms. |
| Refurbished Platform Leasing Model | Matches payment schedules to utilization rates, penetrating India's cost-sensitive tier-two cities. |
Study Parameters
Desk research of regulatory filings, hospital procurement databases, and GPO contracts preceded structured interviews with refractive surgeons, biomedical engineers, hospital purchasing committee members, and ophthalmology chain procurement directors. Secondary validation drew from PMDA approval databases, NMPA registration records, CDSCO quality norm notifications, and ASEAN medical device harmonization documentation. Analysts triangulated bottom-up equipment installation estimates with top-down capital expenditure flows from ophthalmology center financial disclosures.
Assumptions held fixed across the modeling period include continued PMDA pre-market approval stringency, NMPA clinical trial mandates for Class C and D devices, and ASEAN directive convergence timelines. The analytical framework modeled procedure type, ablation technology, visual indication, and care setting dimensions. CAGRs derived from equipment replacement cycle compression in South Korea and Taiwan, procedural conversion rates from LASIK to SMILE, and penetration trajectories in underdeveloped secondary cities. Forecast inputs included myopia screening volumes in China's tier-one cities and femtosecond laser installation rates across Southeast Asian private ophthalmology chains.
Macroeconomic conditions sit as an overlay; deviation in EUR-JPY exchange rates, ophthalmology center capital expenditure cycles, or regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spinal Traction Market
Medical Devices
Blood Warmers Market
Medical Devices
Veterinary Procedure Lights Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Global Ureteroscopes Market
Medical Devices
Pulmonology Lasers Market
Medical Devices
Knotless Suture Anchors Market
Medical Devices
North America Ultrasound Probe Disinfection Market
Medical Devices
Tracheostomy Tubes Market
Medical Devices
Global Venous Stents Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Digital Stethoscope Market
Medical Devices
Flow Cytometry Products Market
Medical Devices
Peripheral Embolization Device Market
Medical Devices
Skincare Devices Market
Medical Devices
Transcatheter Aortic Valve Implantation (TAVI) Market