
 3D Printing for Surgical Procedures Market | 2026-2036
3D Printing for Surgical Procedures Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing for Surgical Procedures Market Insights
Multi-material jetting with integrated bioactive coatings is reconfiguring how surgical implants achieve osseointegration and antimicrobial performance. Stratasys leverages its polymer expertise to dominate hospital-based point-of-care manufacturing in North America. Materialise anchors European regulatory consulting and patient-specific device design workflows. EOS sustains leadership in metal powder-bed fusion for titanium orthopedic implants.
3D printing for surgical procedures encompasses additive manufacturing of patient-matched anatomical models, surgical guides, and permanent implants using ISO 10993-certified polymers, titanium alloys, or resorbable ceramics with layer resolutions below 50 microns to enable preoperative planning and intraoperative precision. Biocompatible materials command the deepest margin pools due to raw material scarcity and sterilization validation requirements, while SLS and SLA technologies lead installed-base expansion across hospital networks. Orthopedic surgery generates the highest procedure volume for patient-specific cutting guides and acetabular cups, whereas neurosurgery represents the fastest-growing application as cranial plate complexity drives adoption.
FDA 510(k) and EU MDR frameworks govern device safety and clinical evidence requirements, with FDA's Emergency Use Authorizations during supply shortages accelerating temporary point-of-care production permissions. ISO 13485 quality management and ASTM F3335 standards for powder-bed fusion define manufacturing repeatability thresholds that determine market access. Stakeholders must monitor evolving reimbursement codes for patient-specific implants across Medicare, NHS England, and China's NHSA to calibrate commercialization investments against actual payment velocity.
Market Dynamics
Patient-specific manufacturing is compressing traditional implant supply chains from months to days, forcing orthopedic device makers to reconfigure production networks around hospital-integrated point-of-care facilities rather than centralized factories.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's tailored review framework for patient-matched devices reduces clearance timelines for biocompatible titanium implants, accelerating commercialization for US hospital networks.
- Acetabular cup complexity:Orthopedic surgery departments demand anatomically matched hip implants that conventional machining cannot produce, pulling additive manufacturing into standard-of-care protocols.
- Resorbable ceramic advances:Hydroxyapatite-composite filaments with tunable degradation profiles enable craniomaxillofacial implants that eliminate secondary removal surgeries.
Market Restraints
- Titanium powder supply concentration:Spherical Ti-6Al-4V feedstock production clusters in Germany and China, exposing device makers to export restriction risks and price volatility.
- ISO 13485 certification timelines:Quality management system validation for point-of-care manufacturing extends 18-24 months, blocking hospital network expansion.
- Stereolithography size limitations:Build envelope constraints restrict patient-specific pelvic reconstruction plates to sub-300mm dimensions, excluding complex oncologic cases.
Strategic Opportunities
- Neurosurgical cranial plating:Complex craniofacial trauma reconstruction in Germany's Level I trauma centers remains underpenetrated by patient-matched titanium solutions.
- China's NHSA reimbursement expansion:Provincial pilot programs for customized orthopedic implants signal pending national coverage decisions that would unlock hospital procurement budgets.
- Multi-material jetting convergence:Integration of antimicrobial silver-doped polymers with structural PEEK substrates enables next-generation spinal fusion cages with infection-resistant surfaces.
Industry Challenges
- Biomedical engineer scarcity:Hospital networks lack personnel trained in DICOM-to-STL segmentation, bottlenecking preoperative planning workflows.
- Legacy PACS integration:Point-of-care 3D printing systems require middleware development to interface with existing radiology infrastructure, extending deployment cycles.
- Sterilization validation gaps:Gamma and EO sterilization protocols for porous titanium lattice structures lack ASTM consensus standards, forcing device-specific validation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing for Surgical Procedures Market |
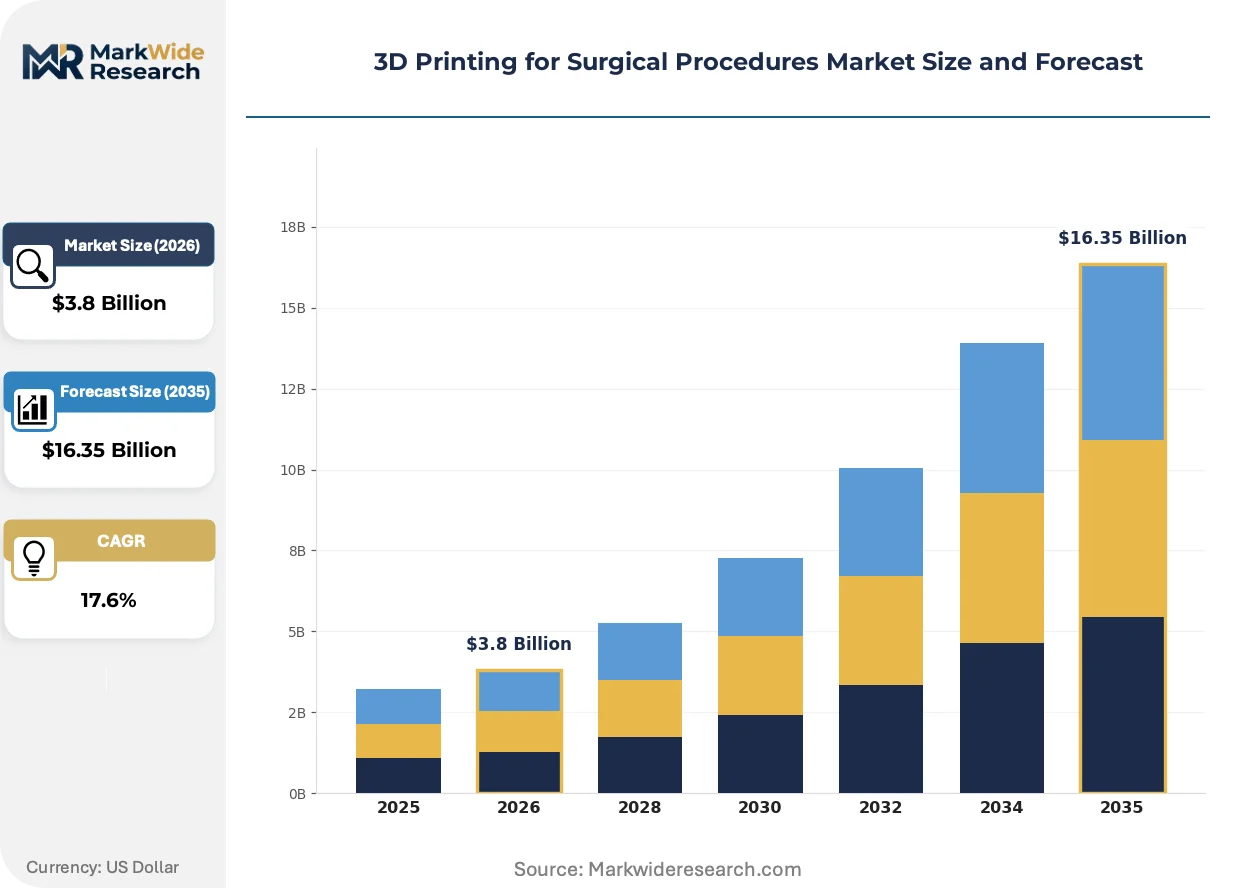
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biocompatible Materials, Surgical Guides, Anatomical Models, Implants Technology: SLS, FDM, SLA, PolyJet Application: Orthopedic Surgery, Dental Surgery, Cardiac Surgery, Neurosurgery End User: Hospitals, Clinics, Research Labs, Private Practices |
| Companies Covered | Stratasys, 3D Systems, Materialise, EnvisionTEC, Renishaw, EOS, Formlabs, Axial3D, Organovo Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing for Surgical Procedures Market Trends and Innovations
Computational design automation and in-situ monitoring systems are collapsing the traditional boundaries between preoperative planning, manufacturing execution, and surgical implantation, creating closed-loop workflows that bypass conventional device supply chains entirely.
Continuous liquid interface production with oxygen-permeable membranes is rendering obsolete batch-based vat polymerization for surgical guides, as Cleveland Clinic and Mayo Clinic surgical planning departments adopt same-day turnaround protocols for emergency trauma cases, compressing device procurement from weeks to hours.
EU MDR's strengthened clinical evidence requirements for patient-matched implants are forcing European orthopedic device makers to establish prospective registries, with Germany's BfArM mandating post-market surveillance data that smaller manufacturers cannot generate without hospital network partnerships, advantaging established quality system operators.
Surgeon-led design customization is fragmenting procurement authority from centralized hospital supply chains to individual surgical service lines, with US academic medical centers establishing direct material purchase agreements with polymer suppliers, bypassing traditional device distributor markups in high-volume joint replacement programs.
3D Printing for Surgical Procedures Market Segmentation
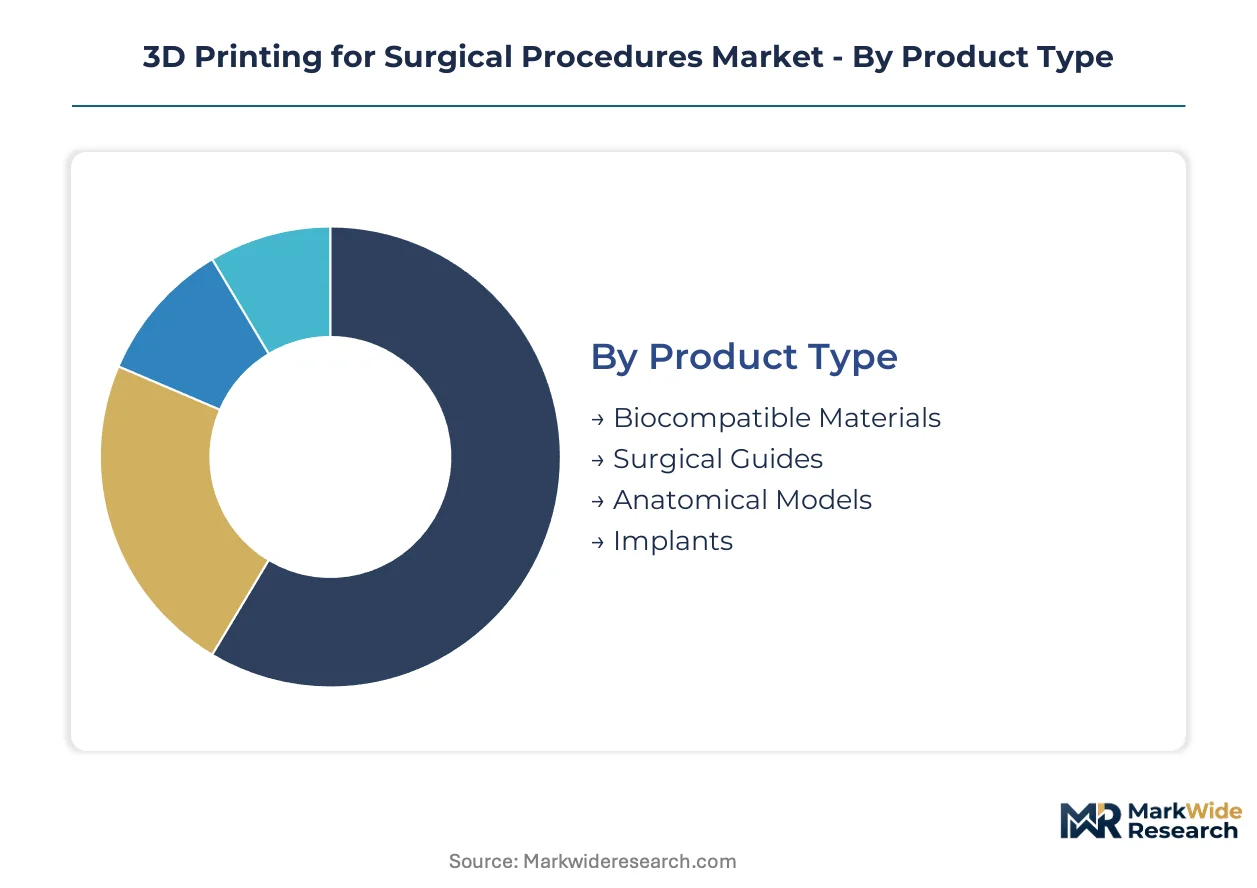
Segmentation in 3D printing for surgical procedures reveals divergent commercial rhythms across product categories. Cycle times for anatomical models span hours versus months for permanent implants, reshaping inventory strategies and capital allocation priorities across hospital networks.
Product Type:
Biocompatible materials turn inventory fastest with recurring sterilization validation cycles, while implants lock capital longest through extended regulatory clearance timelines.
- Biocompatible Materials:ISO 10993-certified titanium alloys, PEEK polymers, and resorbable hydroxyapatite composites require lot-specific biocompatibility testing. Demand clusters at German orthopedic networks and US academic medical centers where point-of-care manufacturing protocols mandate just-in-time material procurement.
- Implants:Patient-matched acetabular cups and cranial plates fabricated via powder-bed fusion or material jetting carry permanent implant liability classifications. FDA 510(k) pathways for titanium devices compress clearance timelines, pulling investment toward US hospital-integrated production facilities.
- Surgical Guides:Sterilizable drill and cutting guides produced through vat photopolymerization enable intraoperative precision with 24-48 hour turnaround at Cleveland Clinic and Mayo Clinic surgical planning departments.
- Anatomical Models:Preoperative visualization tools using full-color multi-material jetting support complex oncologic resections at China's top-tier hospitals where surgeon training programs drive procurement.
Biocompatible materials dominate installed base. Implants are where expansion concentrates.
Technology:
Cost tier stratification separates capital-intensive metal systems from accessible polymer platforms, with mid-tier hospitals gravitating toward lower equipment thresholds.
- SLS:Selective laser sintering of titanium and cobalt-chrome powders produces load-bearing orthopedic implants with isotropic mechanical properties. Germany's EOS systems anchor European trauma center deployments where MDR compliance demands validated process control.
- SLA:Stereolithography achieves sub-50-micron resolution for surgical guides but faces build envelope constraints excluding complex pelvic reconstructions. US dental surgery clinics adopt same-day guide production workflows.
- FDM:Fused deposition modeling of biocompatible PEEK and PLA offers lowest capital entry point for hospital networks piloting point-of-care programs.
- PolyJet:Multi-material jetting enables gradient structures combining rigid and flexible zones in single builds, commanding premium pricing at neurosurgical centers.
SLS anchors high-value implant production. PolyJet is climbing the fastest in preoperative planning applications.
Application:
Procedure volume and reimbursement velocity determine technology deployment patterns across surgical disciplines.
- Orthopedic Surgery:Patient-specific cutting guides and acetabular cups generate highest procedure volumes with established CPT reimbursement codes. US hospital networks expand joint replacement programs with hospital-integrated manufacturing.
- Neurosurgery:Complex cranial plate reconstructions for trauma and oncology cases demand anatomical precision unattainable through conventional machining. Germany's Level I trauma centers drive adoption of titanium lattice structures.
- Dental Surgery:Implant surgical guides and orthodontic models represent mature adoption with saturated installed base across private practices.
- Cardiac Surgery:Preoperative models for congenital heart defects and valve planning remain emerging with limited reimbursement pathways constraining hospital investment.
Orthopedic surgery commands largest installed equipment base. Neurosurgery is gaining share fastest as cranial complexity drives patient-matched solutions.
End User:
Customer type determines procurement authority concentration versus fragmentation across supply chains.
- Hospitals:Academic medical centers and large health systems centralize capital investment in point-of-care manufacturing with direct material purchasing agreements bypassing traditional distributors.
- Clinics:Ambulatory surgery centers outsource model and guide production to centralized service bureaus, prioritizing turnaround over capital deployment.
- Research Labs:University-affiliated facilities drive technology validation for next-generation bioactive coatings and resorbable ceramics.
- Private Practices:Individual dental and orthopedic surgeons purchase anatomical models and surgical guides through distributor networks with limited design customization.
Hospitals dominate capital deployment. Clinics are where service-based revenue models concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement authority concentrates with academic medical centers in the United States, Germany, and China, where reimbursement frameworks and manufacturing ecosystems support point-of-care adoption.
United States
Cleveland Clinic and Mayo Clinic surgical planning departments drive same-day turnaround protocols for emergency trauma cases. FDA's tailored 510(k) review framework for patient-matched devices reduces clearance timelines for biocompatible titanium implants. Boston and Minneapolis medical device clusters anchor hospital-integrated manufacturing investments.
Germany
EOS systems anchor European trauma center deployments where MDR compliance demands validated process control. BfArM mandates post-market surveillance data for patient-matched implants, advantaging established quality system operators. Munich and Hamburg orthopedic networks expand patient-specific acetabular cup programs.
China
Provincial pilot programs for customized orthopedic implants signal pending national coverage decisions that would unlock hospital procurement budgets. NMPA regulatory pathways for 3D-printed medical devices streamline commercialization for domestic manufacturers. Beijing and Shanghai top-tier hospitals drive anatomical model adoption for surgeon training.
United Kingdom
NHS England reimbursement frameworks for patient-specific implants determine commercialization investment velocity across hospital networks. MHRA post-Brexit regulatory alignment with EU MDR creates transitional compliance burdens for device makers. London academic medical centers centralize capital investment in point-of-care manufacturing.
Japan
PMDA approval pathways for titanium lattice structures support cranial plate complexity in trauma reconstruction. METI industrial policy promotes domestic additive manufacturing capabilities for medical applications. Tokyo and Osaka medical device clusters develop next-generation bioactive coatings.
3D Printing for Surgical Procedures Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around equipment manufacturers with installed-base advantages, software-integrated service providers, and material specialists with biocompatibility certifications. Three archetypes dominate: polymer platform generalists, metal powder-bed fusion specialists, and regulatory consulting-integrated design houses. Competitive moves concentrate on strategic hospital network partnerships and point-of-care manufacturing facility deployments.
Within the equipment manufacturer tier, Stratasys and 3D Systems occupy positions as North American polymer platform anchors, while Materialise exemplifies the European regulatory consulting-integrated archetype. EOS represents the metal powder-bed fusion specialist position in German orthopedic trauma center deployments.
| Leading Market Players |
|---|
| Stratasys |
| 3D Systems |
| Materialise |
| EnvisionTEC |
| Renishaw |
| EOS |
| Formlabs |
| Axial3D |
| Organovo Holdings |
| Others |
Pricing and Supply Chain Analysis
Titanium powder supply concentration in Germany and China creates dual vulnerability to export restrictions and commodity volatility, compressing margin pools for device makers while simultaneously forcing hospital networks toward long-term offtake contracts that reshape procurement authority toward centralized materials management.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate titanium feedstock procurement, with spherical Ti-6Al-4V powder commanding premium spreads over standard alloy grades due to atomization process complexity. Price differentiation rests on ISO 13485 certification tier and sterilization validation completeness, with FDA-cleared lots capturing 15-20 point spreads over CE-marked equivalents. Cost compression in surgical guide production is intensifying as same-day turnaround protocols commoditize vat photopolymerization services. Ambulatory surgery centers exhibit highest price sensitivity, while academic medical centers prioritize quality system documentation over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for orthopedic device makers dependent on spherical titanium powder feedstock. Manufacturing gravity centers on Germany, China, and the United States for powder-bed fusion systems, with PEEK polymer resin production clustering in Belgium and Japan. Raw material dependencies span titanium sponge, cobalt-chrome powder, and medical-grade photopolymers. Single-source vulnerability persists for electron beam melting equipment. Distribution runs through hospital-integrated point-of-care facilities for high-volume joint replacement programs, while clinics rely on regional service bureaus for anatomical model fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's streamlined 510(k) pathway for patient-matched devices represents a regulatory inflection that compresses commercialization timelines and accelerates hospital network penetration, positioning point-of-care manufacturing as the dominant disruption vector across surgical implant supply chains.
For Market Incumbents: Build regulatory filing capacity as the defensive moat against emerging polymer platform specialists. Secure backward integration into titanium powder atomization to neutralize German and Chinese supply concentration risks. Anchor hospital network partnerships through ISO 13485 consulting services that extend beyond equipment sales into quality system co-development, blocking entrant access to procurement committees. For New Entrants and Emerging Players: China's provincial orthopedic implant pilot programs offer the most penetrable geographic entry point before national NHSA reimbursement decisions lock in incumbent relationships. Target neurosurgical cranial plating in German Level I trauma centers where EOS system saturation has created service gaps for complex lattice structures. Lead with DICOM-to-STL segmentation software rather than hardware to bypass capital-intensive equipment sales cycles. For Investors and Strategic Acquirers: China's NMPA reimbursement expansion reshapes the acquisition landscape toward domestic device makers with established hospital relationships. Frame long-term viability around regulatory consulting-integrated design houses with EU MDR compliance infrastructure that smaller manufacturers cannot replicate independently. Monitor BfArM post-market surveillance mandates as the signal for consolidation pressure on undercapitalized European orthopedic networks.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic protocols establish same-day turnaround as the competitive baseline for trauma cases. |
| FDA 510(k) Submission | Streamlined review frameworks for patient-matched titanium implants compress clearance timelines against EU MDR pathways. |
| Backward Integration into Powder Atomization | Captive spherical Ti-6Al-4V supply neutralizes German and Chinese export restriction exposure for device makers. |
| Software Companion Development | DICOM-to-STL segmentation tools bypass legacy PACS integration bottlenecks that extend hospital deployment cycles. |
| Reimbursement Strategy | NHSA provincial pilot alignment positions domestic Chinese manufacturers for national coverage expansion decisions. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases preceded structured interviews with orthopedic surgeons, biomedical engineers, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary validation drew from CMS Medicare reimbursement data, NHS England procurement records, and NMPA registration filings. Bottom-up procedure volume estimates triangulated against top-down capital equipment installed base analysis across the analysis window.
Assumptions held reimbursement velocity constant at observed Medicare, NHS England, and NHSA provincial pilot levels, with sensitivity analysis varying FDA clearance timeline compression and titanium powder price volatility. Segmentation modeling spanned product type, technology platform, surgical application, and end-user archetype, with regional regulatory clusters treated as distinct adoption curves. CAGRs derived from equipment replacement cycles, hospital network expansion plans, and procedure volume elasticity to patient-specific implant availability. Forecast inputs incorporated EOS and Stratasys shipment disclosures alongside Cleveland Clinic and Mayo Clinic surgical planning department capacity announcements.
The forecast holds incumbent behavior within observed patterns; aggressive point-of-care manufacturing investments by polymer platform generalists or metal powder-bed specialists would shift outcomes toward faster hospital network saturation than modeled. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Embolic Protection Device Market
Medical Devices
Blood Collection Vacuum Devices Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
Anterior Cervical Plating Market
Medical Devices
Global Breast Biopsy Devices Market
Medical Devices
BFS Syringes Market
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
Contact and Intraocular Lenses Market
Medical Devices
Catheter Securement Devices Market
Medical Devices
Global Occlusion Devices Market
Medical Devices
Additional Defibrillator Accessories (AED) Market
Medical Devices
Clot Management Devices Market
Medical Devices
United Kingdom Aesthetic Devices Market
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Urodynamic Catheter Market