
 Global Dental Caries Detectors Market | 2026-2036
Global Dental Caries Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Caries Detectors Market Foresight
Dental equipment distribution is rewriting how caries detection technologies reach end users. Planmeca leverages its integrated imaging ecosystem to control premium channel access across Nordic markets. Dentsply Sirona anchors North American supply through its direct sales force and service infrastructure. KaVo Dental specializes in high-volume clinic partnerships, sustaining manufacturing scale that competitors struggle to match.
Dental caries detectors are optical and electrochemical instruments that quantify demineralization or bacterial activity within enamel and dentin structures, typically operating at wavelengths between 400 and 700 nanometers for fluorescence-based modalities. Their primary commercial purpose is to enable non-invasive, repeatable screening that reduces reliance on visual-tactile examination alone. Digital imaging occupies the largest installed base among product categories, while quantitative light-induced fluorescence captures expanding margin pools in pediatric and orthodontic settings. Near-infrared light technology leads R&D investment intensity, though electrical impedance spectroscopy competes for portability-sensitive applications in mobile dental units.
The FDA's 510(k) framework governs premarket notification for optical diagnostic devices in the United States, while the EU MDR and CE marking requirements reshape conformity assessment burdens for European manufacturers. Japan's PMDA maintains distinct clinical evidence standards that delay entry for novel photothermal radiometry systems. Stakeholders must monitor how divergent regulatory timelines across FDA, EMA, and PMDA jurisdictions affect product launch sequencing and capital allocation priorities.
Market Dynamics
Fluorescence-based detection systems are compressing the diagnostic workflow from chairside examination to treatment planning, forcing incumbents to reconfigure hardware-software integration or cede installed base to optical specialists.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined premarket notification for optical diagnostic devices reduces clearance timelines, enabling faster commercialization of fluorescence-based systems in United States metropolitan dental clusters.
- Pediatric screening protocols:Quantitative light-induced fluorescence gains traction in orthodontic and pediatric settings where non-invasive repeatability reduces patient anxiety and improves compliance rates.
- Near-infrared R&D intensity:Wavelength optimization research between 700-1500 nanometers is expanding detection depth into dentin structures, addressing limitations of visible-light modalities.
Market Restraints
- EU MDR conformity burdens:Enhanced clinical evidence requirements for CE marking under the Medical Device Regulation extend certification timelines and inflate documentation costs for European manufacturers.
- Optical component supply concentration:Precision filter and sensor fabrication concentrates in East Asian contract manufacturers, exposing procurement to geopolitical friction and capacity constraints.
- Electrical impedance portability:Battery-powered alternatives compete for mobile dental unit deployments where mains power is unavailable, fragmenting technology standardization.
Strategic Opportunities
- Brazil preventive expansion:Dental clinic networks in São Paulo and Rio de Janeiro are scaling screening programs, creating demand for digital caries detection platforms in Latin America's largest dental market.
- Photothermal radiometry entry:Novel thermal emission detection methods await PMDA clinical validation in Japan, offering first-mover advantage for temperature-based bacterial activity quantification.
- Direct-to-clinic distribution:Bypassing traditional dental supply houses through manufacturer-owned service infrastructure captures margin and tightens customer relationships.
Industry Challenges
- Optical calibration expertise:Maintenance of fluorescence intensity standards requires specialized biomedical engineers, creating talent scarcity in secondary dental markets.
- Legacy imaging integration:Chairside software from incumbent radiography vendors resists interoperability with standalone caries detection hardware, complicating workflow adoption.
- Reimbursement code alignment:Diagnostic procedure classification varies across national health systems, delaying insurance coverage parity with traditional tactile examination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Caries Detectors Market |
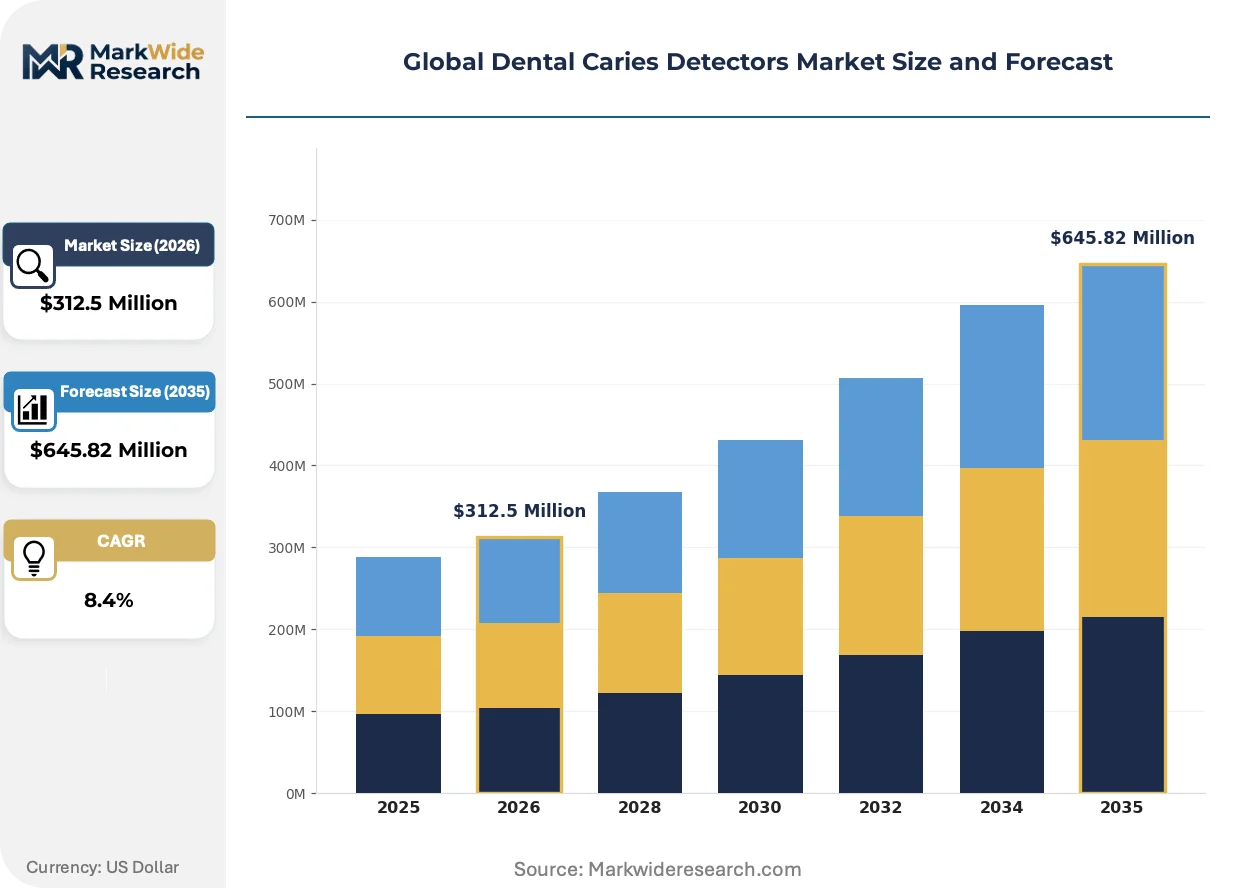
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Fluorescence, Electric Conductance, Fiber Optic Transillumination, Digital Imaging, Quantitative Light-induced Fluorescence Technology: Near-infrared Light, Ultrasound, Photothermal Radiometry, Optical Coherence Tomography, Electrical Impedance Spectroscopy Application: Early Detection, Cavity Assessment, Orthodontic Evaluation, Periodontal Diagnosis, Preventive Dentistry End User: Dental Clinics, Academic Research Institutions, Mobile Dental Units, Public Health Centers, Diagnostic Labs |
| Companies Covered | Planmeca, Air Techniques, Dentsply Sirona, Carestream Health, Straumann Group, KaVo Dental, 3Shape, VATECH, ACTEON Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Caries Detectors Market Shifts & Advancements
Convergence of artificial intelligence inference with real-time optical sensing is redefining diagnostic accuracy benchmarks and compressing the value chain from hardware manufacture to clinical decision support.
Near-infrared transillumination is collapsing the boundary between detection and monitoring by enabling sub-surface lesion tracking without ionizing radiation. Large group practices in United States metropolitan clusters are deploying these systems across multiple operatories to standardize diagnostic protocols. The technology is collapsing capital allocation toward integrated platforms that combine detection, documentation, and patient communication in single hardware units.
Japan's PMDA maintains distinct clinical evidence standards for photothermal and thermographic diagnostic modalities, creating regulatory friction that delays market entry relative to FDA-cleared optical alternatives. Domestic manufacturers prioritize PMDA-compliant trial designs that emphasize longitudinal sensitivity data over cross-sectional accuracy metrics. Pediatric and orthodontic specialists in Tokyo and Osaka dental clusters represent the initial addressable population for novel thermal detection systems.
Group procurement consortia are consolidating purchasing authority across dental service organizations, displacing individual practitioner discretion in equipment selection. United States-based dental support organizations negotiate enterprise-wide agreements that specify interoperability requirements and service response times. This concentration is visible most acutely in Texas and Florida, where multi-location practices standardize on single-vendor imaging ecosystems to reduce training overhead and parts inventory complexity.
Global Dental Caries Detectors Market Segmentation
Technology heterogeneity across detection modalities creates distinct procurement patterns. Clinicians weigh diagnostic depth against workflow integration, while regulatory clearance trajectories fragment vendor strategies across geographies.
Product Type:
Cost tier stratification separates premium optical systems from portable electrochemical alternatives, with reimbursement alignment determining clinical adoption velocity.
- Digital Imaging:CCD and CMOS sensor arrays capture high-resolution enamel surface topology for chairside visualization. Large group practices in Texas and Florida dental clusters standardize procurement of these systems to reduce training overhead across multiple operatories. The installed base concentrates in United States metropolitan markets where enterprise purchasing agreements specify interoperability with existing radiography infrastructure.
- Quantitative Light-induced Fluorescence:405-nanometer excitation wavelengths quantify mineral loss through autofluorescence decay measurements. Pediatric specialists in Tokyo and Osaka deploy these systems for anxiety-reducing repeat screening in orthodontic settings. PMDA clinical evidence requirements for longitudinal sensitivity data delay Japanese market entry relative to FDA-cleared alternatives.
- Laser Fluorescence:Diode-based excitation at 655 nanometers enables bacterial metabolite detection through porphyrin fluorescence.
- Electric Conductance:Resistance-based mineral content assessment offers battery-powered portability for resource-constrained environments.
- Fiber Optic Transillumination:Visible-light transmission imaging identifies proximal caries without ionizing radiation exposure.
Digital imaging commands the established base. The steepest expansion runs through quantitative light-induced fluorescence.
Technology:
Application context determines wavelength selection, with depth penetration requirements driving R&D allocation toward near-infrared optimization.
- Near-infrared Light:Transillumination at 700-1500 nanometers penetrates dentin structures without ionizing radiation. United States-based dental service organizations deploy these systems across operatories to standardize sub-surface lesion tracking protocols. Wavelength optimization research is expanding detection depth beyond visible-light limitations.
- Electrical Impedance Spectroscopy:Alternating current resistance measurements quantify demineralization through ionic conductivity changes. Mobile dental units in São Paulo and Rio de Janeiro clinic networks favor these battery-powered alternatives where mains power is unavailable. The technology competes for portability-sensitive deployments in Brazil's expanding preventive screening programs.
- Photothermal Radiometry:Thermal emission detection quantifies bacterial activity through temperature differential analysis.
- Optical Coherence Tomography:Interferometric depth-resolved imaging provides cross-sectional enamel structure visualization.
- Ultrasound:Acoustic impedance mapping offers radiation-free alternative for enamel density assessment.
Near-infrared light dominates current installed capacity. Photothermal radiometry is gaining share fastest pending PMDA validation completion.
Application:
Reimbursement code alignment varies across diagnostic intent, with preventive protocols receiving differential coverage compared to established disease assessment.
- Early Detection:Non-invasive screening protocols identify demineralization before cavitation enables remineralization therapy. Public health centers in Germany are expanding these programs through statutory insurance preventive benefit structures. The application reduces long-term restorative costs but requires sustained reimbursement parity with tactile examination.
- Preventive Dentistry:Risk stratification and monitoring protocols track lesion progression without intervention. Academic research institutions in Japan conduct longitudinal trials validating fluorescence-based monitoring against histological gold standards. PMDA evidence requirements emphasize sensitivity over specificity for these protocols.
- Cavity Assessment:Established lesion characterization guides restoration extent and material selection.
- Orthodontic Evaluation:Proximal caries detection during fixed appliance therapy addresses access limitations.
- Periodontal Diagnosis:Root caries assessment in compromised dentition supports comprehensive treatment planning.
Early detection captures the majority of current procedural volume. Preventive dentistry is climbing the fastest as reimbursement frameworks evolve.
End User:
Procurement authority concentration reshapes vendor access strategies, with individual practitioner discretion displacing toward organizational purchasing.
- Dental Clinics:Private practice and group practice settings generate the primary demand volume for integrated detection platforms. Nordic markets exhibit premium channel control through integrated imaging ecosystem vendors. Direct-to-clinic distribution models are capturing margin from traditional dental supply houses.
- Mobile Dental Units:Transportable screening services in underserved regions require portable, battery-operated systems. Brazilian clinic networks in São Paulo and Rio de Janeiro are scaling these deployments for school-based preventive programs. Electrical impedance and ultrasound technologies compete for these power-constrained applications.
- Academic Research Institutions:Clinical trial sites generate validation data for regulatory submissions across FDA, EMA, and PMDA jurisdictions.
- Public Health Centers:Government-funded screening programs in Germany and Japan prioritize cost-effective, high-throughput modalities.
- Diagnostic Labs:Centralized image interpretation services are emerging for teledentistry applications.
Dental clinics retain the dominant procurement position. Mobile dental units are expanding most quickly in emerging market preventive programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's 510(k) pathway acceleration for optical diagnostic devices anchors United States market expansion, while divergent regulatory timelines across EMA and PMDA jurisdictions reshape product launch sequencing for fluorescence-based systems.
United States
Metropolitan dental clusters in Texas and Florida drive enterprise procurement of integrated detection platforms. Dental support organizations negotiate system-wide interoperability requirements that standardize hardware-software integration across multi-location practices. Large group practices in these states consolidate purchasing authority through direct manufacturer agreements.
Germany
Statutory insurance preventive benefit structures expand early detection protocols through public health center networks. EU MDR conformity assessment requirements extend certification timelines for CE marking of novel optical modalities. Bavarian and North Rhine-Westphalian dental clinic networks scale screening programs with cost-effective digital imaging platforms.
Japan
PMDA clinical evidence standards for photothermal radiometry systems delay market entry relative to FDA-cleared alternatives. Longitudinal sensitivity data requirements shape domestic manufacturer trial designs. Tokyo and Osaka pediatric specialists represent the initial addressable population for thermal detection modalities pending regulatory validation.
Brazil
School-based preventive programs in São Paulo and Rio de Janeiro clinic networks scale mobile dental unit deployments. ANVISA regulatory pathways for optical diagnostic devices accommodate faster clearance for fluorescence-based systems. Battery-powered electrical impedance systems compete for power-constrained applications in underserved regions.
Global Dental Caries Detectors Market Competitive Landscape
Integrated imaging ecosystem vendors and standalone optical specialists split the market between premium channel control and workflow-specific penetration. Consolidation concentrates around manufacturers with captive service infrastructure and direct-to-clinic distribution capabilities. Three archetypes dominate: Nordic ecosystem integrators, North American direct sales forces, and high-volume clinic partnership specialists. Competitive moves center on hardware-software bundling and geographic expansion through manufacturer-owned service networks.
Among Nordic ecosystem integrators, Planmeca anchors premium channel access through integrated imaging platforms. Dentsply Sirona exemplifies the North American direct sales archetype with established service infrastructure. KaVo Dental occupies the high-volume partnership tier, sustaining manufacturing scale through clinic network relationships. These three entities represent distinct strategic positions without overlapping core competencies.
| Leading Market Players |
|---|
| Planmeca |
| Air Techniques |
| Dentsply Sirona |
| Carestream Health |
| Straumann Group |
| KaVo Dental |
| 3Shape |
| VATECH |
| ACTEON Group |
| Others |
Supply & Pricing Matrix
Single-source dependency on East Asian precision filter and sensor fabrication exposes procurement to geopolitical friction, compressing both pricing tier spreads and supply chain resilience across fluorescence-based and near-infrared modalities. This concentration forces tiered pricing separation between premium integrated platforms and portable electrochemical alternatives, with battery-powered systems in Brazilian mobile units commanding lower absolute prices but higher per-unit margins due to reduced component complexity.
Pricing Analysis
Configured-to-order pricing for integrated imaging ecosystems commands spreads of 40-60 percent above standard fluorescence-based detector SKUs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA 510(k)-cleared systems and EU MDR-compliant variants anchoring premium tiers. Cost compression in standard-tier digital imaging stems from group procurement consortia consolidating purchasing authority across United States dental service organizations. Pediatric specialists in Japanese orthodontic settings exhibit lowest price sensitivity due to PMDA-mandated longitudinal validation requirements, while Brazilian public health screening programs drive volume demand at economy tier.
Supply Chain Analysis
Export-control regime restrictions on precision optical components limit flows from Japan and South Korea to certain end-use destinations, constraining capacity allocation for near-infrared sensor arrays. Manufacturing concentration centers on China, Japan, and South Korea for CMOS sensors, interference filters, and diode lasers. Component sourcing draws from German precision optics specialists for calibration standards and Taiwanese contract manufacturers for PCB assembly. Single-source vulnerability concentrates in 655-nanometer diode supply for laser fluorescence systems. Distribution runs through manufacturer-owned service infrastructure and traditional dental supply houses, with direct-to-clinic models capturing margin in Nordic and North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware-software integration is collapsing the value chain toward platform economics, with interoperability requirements from United States dental support organizations forcing consolidation around captive imaging ecosystems.
For Market Incumbents: Build switching-cost moats through proprietary calibration protocols and exclusive service infrastructure. Deepen backward integration into precision filter manufacturing to reduce East Asian supply exposure. Anchor position by acquiring niche optical specialists with PMDA-compliant trial designs before photothermal radiometry validation completes. Threat vector: standalone AI inference engines disintermediating hardware margins. For New Entrants and Emerging Players: Pursue white-space penetration in Brazil's mobile dental unit segment, where ANVISA pathways accommodate faster clearance and battery-powered electrical impedance systems face limited incumbent competition. Target São Paulo and Rio de Janeiro school-based screening programs with portable form factors and local service partnerships. Go-to-market angle: direct municipal contracting bypassing traditional supply house channels. For Investors and Strategic Acquirers: The market sits at a standardization phase that favors integrated platform vendors over standalone modality specialists. Five-to-ten year viability hinges on FDA-EU-Japan regulatory triangulation capabilities and captive service network density. Acquisition target archetype: optical component suppliers with biomedical calibration expertise and existing CE marking infrastructure. Signal to watch: PMDA photothermal radiometry clearance timelines as inflection indicator for thermal detection modality viability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Streamlined premarket notification for fluorescence-based systems compresses United States commercialization timelines. |
| CE Marking Pathway Investment | EU MDR clinical evidence preparation extends certification timelines but secures premium channel access across German clinic networks. |
| Hospital System Partnership | Enterprise agreements with United States dental support organizations standardize interoperability requirements across multi-location practices. |
| Software Companion Development | AI-integrated diagnostic platforms from Nordic ecosystem vendors collapse workflow from detection to treatment planning. |
| Reimbursement Strategy | Alignment with German statutory insurance preventive benefit structures expands early detection protocol coverage. |
Research Methodology
A spread of perspectives from biomedical engineers, dental clinic procurement managers, GPO contracts specialists, and regulatory affairs leads converged on the working assumptions for installed base estimates and adoption velocity. Primary fieldwork with fluorescence system technicians and pediatric orthodontic specialists informed workflow integration barriers. Secondary validation drew from FDA 510(k) databases, PMDA submission records, EUDAMED CE marking registries, and German statutory insurance reimbursement schedules. Bottom-up unit economics triangulated against top-down market sizing across technology modalities.
Demand-supply balance modeling calibrated penetration rates against regulatory clearance trajectories and group practice procurement consolidation trends across the projection horizon. Segmentation dimensions spanned detection technology, application intent, end-user procurement authority, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in comparable diagnostic device categories. Industry-specific inputs included wavelength optimization R&D pipeline assessment and dental service organization expansion trajectories in Texas and Florida metropolitan clusters.
Sensitivities concentrate around PMDA validation timelines for photothermal radiometry, EU MDR documentation burden inflation, and East Asian optical component export restriction escalation. Forecasts reflect assumptions on reimbursement code parity evolution and group practice procurement authority concentration. Material shifts in FDA 510(k) optical device classification or Japanese thermal detection modality clearance would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Pelvic Floor Diagnostics Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
Electrochemical Biosensors Market
Diagnostic Devices
Counterfeit Drug Detection Device Market
Diagnostic Devices
Non-Invasive Biosensors Market
Diagnostic Devices
Ocular Allergy Diagnostic System Market
Diagnostic Devices
Portable Diagnostic Devices Market
Diagnostic Devices
Europe Companion Diagnostics Market
Diagnostic Devices
Hearing Screening Diagnostic Devices Market
Diagnostic Devices
Europe Point of Care Diagnostics Market
Diagnostic Devices
Coronary Heart Disease Diagnostic Imaging Devices Market
Diagnostic Devices
Biopsy Guidance System Market
Diagnostic Devices
Urine Analyzers Market
Diagnostic Devices
Procalcitonin Antibody Market
Diagnostic Devices
North America Saliva Test Devices Market
Diagnostic Devices
Diagnostic Ophthalmic Devices Market