
 Refurbished MRI Systems Market | 2026-2036
Refurbished MRI Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Refurbished MRI Systems Market Analytics
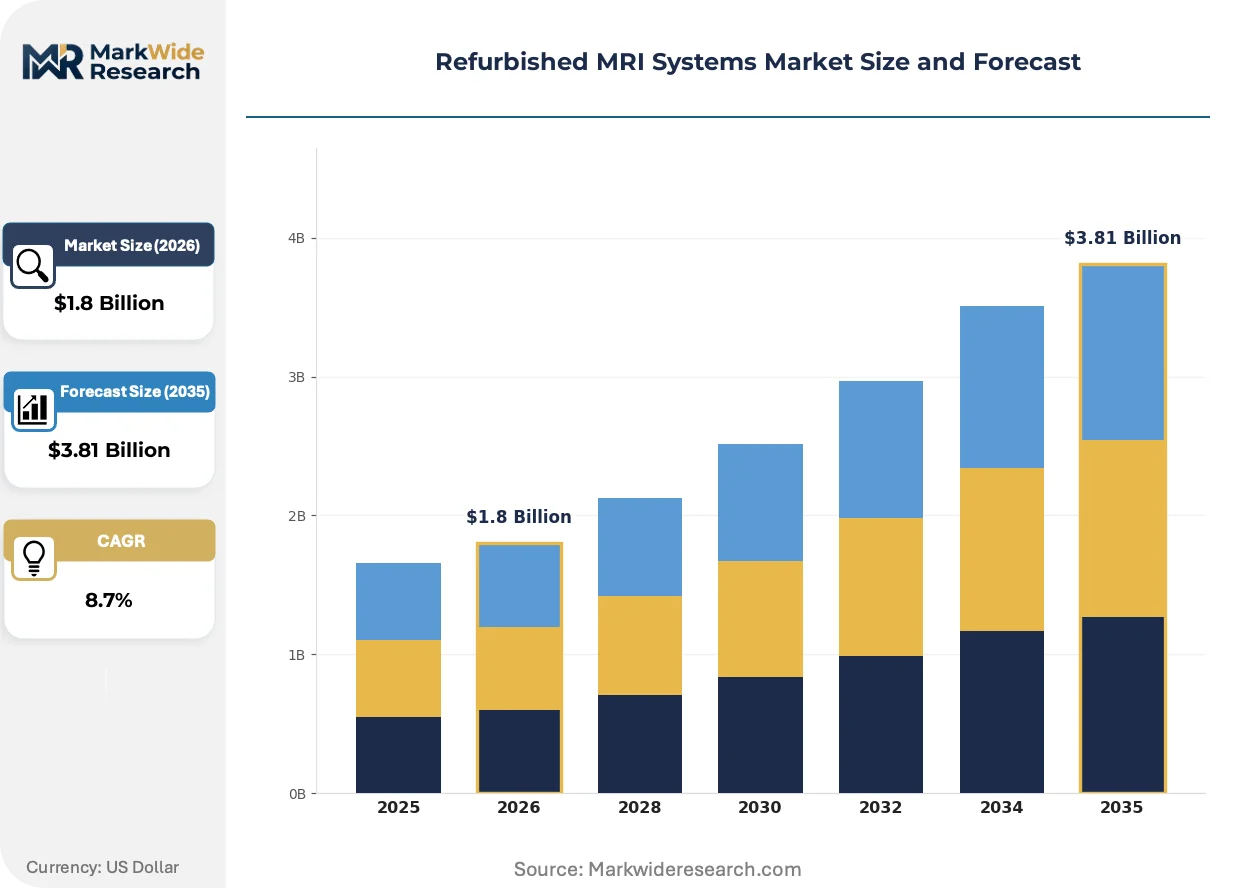
Diagnostic imaging centers is rotating toward refurbished MRI systems as hospital capital expenditure tightens across mature healthcare markets. GE Healthcare leverages its OEM refurbishment infrastructure to sustain parts availability and technical certification for remanufactured units. Siemens Healthineers anchors its secondary market presence through controlled asset recovery programs that extend equipment lifecycle value. Koninklijke Philips N.V. competes by specializing in software-upgradeable refurbished platforms that narrow the performance gap with new installations.
Refurbished MRI systems are pre-owned magnetic resonance imaging units restored to manufacturer-specified performance through component replacement, magnetic field recalibration, and software revalidation, typically achieving 1.5T to 3.0T field strength parity with original specifications for diagnostic imaging workflows. Closed MRI systems dominate transaction volumes in the secondary market due to their prevalence in the installed base and standardized refurbishment protocols that reduce reconditioning variability. Superconducting technology leads the technology segment by residual value, while open MRI systems attract growing interest from bariatric and claustrophobic patient segments where magnet geometry flexibility commands pricing premiums.
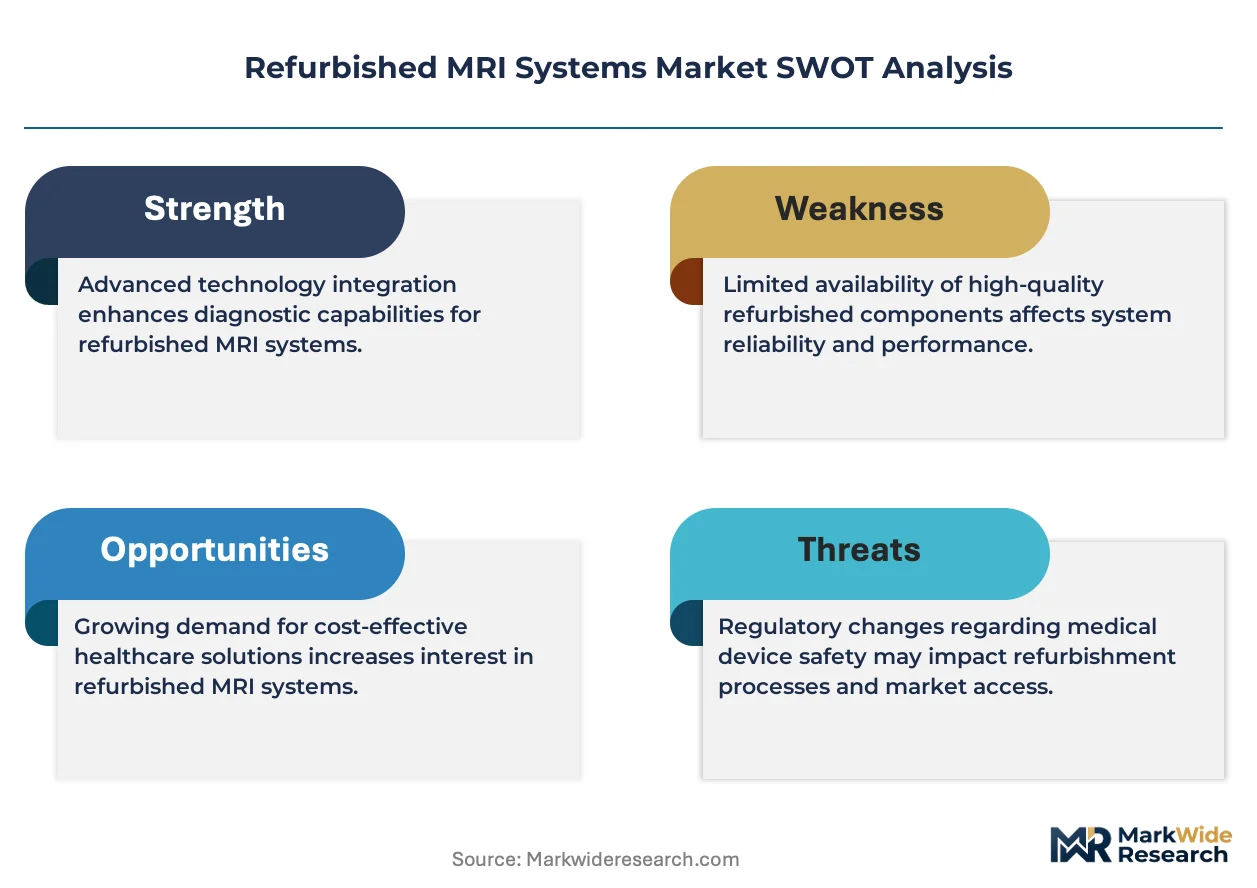
FDA 510(k) clearance requirements for refurbished devices, combined with ISO 13485 quality management systems and EU MDR technical documentation obligations, elevate compliance costs for non-OEM refurbishers and consolidate market access around certified remanufacturing networks. The EU AI Act introduces emerging scrutiny of AI-enabled diagnostic software embedded in refurbished systems, potentially requiring revalidation of algorithmic performance claims. Stakeholders must monitor regulatory divergence between FDA predicate-device pathways and EU MDR conformity assessment routes when structuring cross-border refurbishment operations.
Market Dynamics
Capital budget compression across hospital systems is accelerating rotation toward certified pre-owned imaging infrastructure, with procurement officers now treating refurbishment quality grades as primary vendor selection criteria rather than secondary cost considerations.
Growth Catalysts
- ISO 13485 certification expansion:Third-party refurbishers achieving quality management accreditation unlock hospital procurement eligibility previously reserved for OEM channels, broadening competitive supply.
- Diagnostic imaging center consolidation:Mid-scale radiology networks pursuing equipment standardization across multi-site footprints favor refurbished fleet uniformity over mixed-vendor new purchases.
- Superconducting magnet recycling protocols:Advances in cryogenic system reclamation and helium recovery reduce reconditioning input costs for high-field systems.
Market Restraints
- Helium supply volatility:Price swings in cryogenic gas markets compress refurbishment margins for superconducting MRI units dependent on magnet cooling system restoration.
- FDA 510(k) pathway complexity:Substantial equivalence documentation requirements for refurbished devices with modified software create regulatory friction for independent refurbishers lacking predicate device libraries.
- Fixed-site installation economics:Shielding and siting costs for closed-bore systems limit addressable demand to facilities with existing MRI infrastructure, excluding greenfield outpatient clinics.
Strategic Opportunities
- India hospital infrastructure expansion:Government health scheme coverage extension and medical device manufacturing incentives under PLI schemes create procurement pull for cost-optimized imaging.
- Open-bore bariatric application growth:Patient geometry flexibility in refurbished open systems commands pricing premiums in obesity-focused surgical centers and claustrophobic-sensitive practices.
- AI-enabled diagnostic software integration:Convergence of refurbished hardware platforms with algorithmic image analysis tools creates upgradeable system value propositions.
Industry Challenges
- Field service engineer scarcity:Specialized training requirements for superconducting magnet maintenance and cryogenic system troubleshooting limit refurbishment throughput capacity.
- Cross-border certification reciprocity gaps:Divergent technical documentation requirements between FDA predicate pathways and EU MDR conformity assessments fragment refurbishment operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refurbished MRI Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI Systems, Open MRI Systems, Extremity MRI Systems, Mobile MRI Systems Technology: Superconducting, Permanent Magnet, Open-Field, Hybrid End User: Hospitals, Diagnostic Imaging Centers, Academic Institutions, Research Facilities Application: Neurology, Orthopedics, Cardiology, Oncology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., CANON MEDICAL SYSTEMS CORPORATION, Avante Health Solutions, Block Imaging, Soma Technology, Integrity Medical Systems, Atlantis Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refurbished MRI Systems Market Evolving Landscape
Software-defined imaging capabilities are compressing hardware replacement cycles, with refurbished platforms increasingly valued for their upgradeable architecture rather than static field strength specifications alone.
Magnetic field homogeneity correction technology is bifurcating the refurbishment value chain. Advanced shimming coil arrays and active compensation systems enable older magnet cores to meet contemporary diagnostic protocols. Academic medical centers in Germany and university hospital networks in the United States are prioritizing these upgrade paths over new system procurement. The technology is bifurcating quality tiers within the secondary market, separating software-enhanced refurbishment from basic component replacement.
EU MDR technical documentation obligations and the EU AI Act algorithmic validation requirements are tightening compliance scope for refurbished systems with embedded diagnostic software. Independent refurbishers face elevated conformity assessment costs relative to OEM-controlled remanufacturing networks. Secondary market participants in the Netherlands and Sweden are consolidating certification capabilities to spread fixed compliance investments across larger transaction volumes.
Hospital procurement officers are unbundling after-sales service contracts from equipment acquisition, negotiating separate maintenance terms with third-party service organizations. This disintermediation compresses OEM service attach rates and opens refurbishment vendors to compete on multi-vendor maintenance capabilities. The pattern is most visible in United States health system purchasing cooperatives and German hospital procurement alliances.
Refurbished MRI Systems Market Segmentation
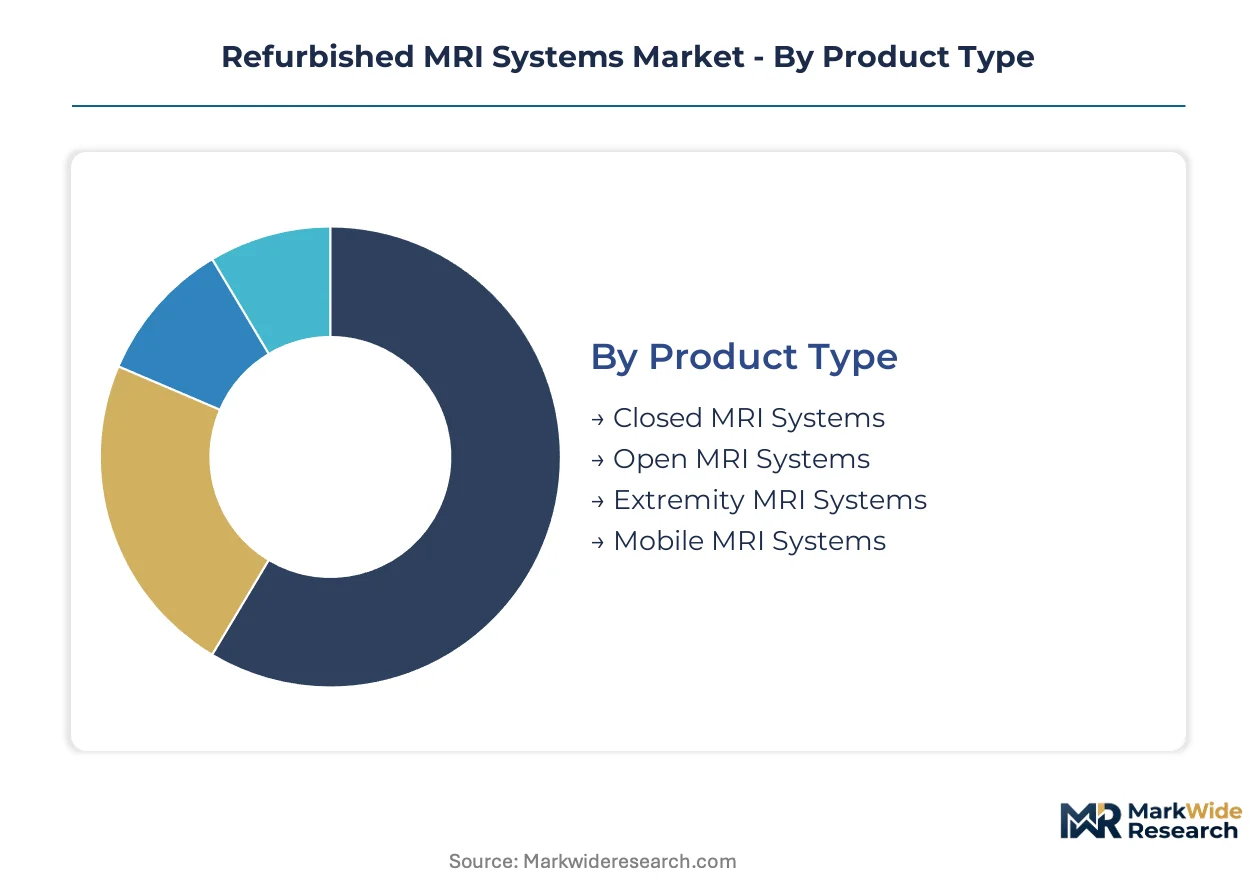
Refurbished MRI procurement patterns diverge sharply across product configurations and clinical applications. Understanding these segment boundaries clarifies where refurbishment economics outperform new system acquisition.
Product Type:
Closed MRI systems dominate domestic refurbishment flows in the United States and Germany where installed base density supports standardized reconditioning protocols. Open and extremity variants increasingly serve export-led demand from India and Southeast Asian markets seeking geometry-flexible alternatives.
- Closed MRI Systems:Cylindrical bore configurations with 1.5T to 3.0T field strength constitute the refurbishment volume core. Academic medical centers in the United States prioritize these units for neurovascular and cardiac protocols where magnetic field homogeneity requirements remain stringent.
- Open MRI Systems:Vertical or horizontal open magnet geometries eliminate claustrophobia barriers and accommodate bariatric patient populations. Surgical centers in Germany and obesity-focused clinics in India command pricing premiums for these configurations where patient comfort drives referral patterns.
- Extremity MRI Systems:Dedicated limb and joint imaging platforms with compact footprints serve orthopedic practices and sports medicine clinics.
- Mobile MRI Systems:Trailer-mounted or containerized units enable rural deployment and temporary capacity expansion for screening campaigns.
Closed MRI systems command the established base. The steepest expansion runs through Open MRI Systems.
Technology:
Superconducting platforms anchor the premium refurbishment tier due to residual magnet value and helium recovery economics. Permanent magnet and hybrid alternatives address cost-constrained deployments where siting infrastructure limitations preclude cryogenic system installation.
- Superconducting:Niobium-titanium coil arrays cooled by liquid helium enable high-field diagnostic performance. FDA 510(k) clearance pathways for refurbished superconducting units favor OEM-controlled remanufacturing networks with established predicate device libraries.
- Permanent Magnet:Ferrite or rare-earth magnetic materials operate without cryogenic cooling, reducing refurbishment input costs and siting complexity. Diagnostic imaging centers in India favor these systems for mid-tier urban deployments where power reliability varies.
- Open-Field:Resistive or permanent magnet architectures with non-enclosed geometries sacrifice peak field strength for patient accessibility.
- Hybrid:Combined superconducting and permanent magnet configurations optimize specific anatomical applications.
Superconducting technology retains the highest residual value. Permanent Magnet configurations are climbing the fastest among cost-optimized procurement segments.
End User:
Hospital systems concentrate refurbishment demand through centralized procurement alliances, while diagnostic imaging centers pursue fleet standardization across multi-site networks. Academic and research end users prioritize upgradeable platforms for protocol development flexibility.
- Hospitals:Integrated health systems with capital expenditure compression rotate toward certified pre-owned infrastructure. German hospital procurement alliances unbundle equipment acquisition from service contracts, opening third-party refurbishment vendor access.
- Diagnostic Imaging Centers:Mid-scale radiology networks favor refurbished fleet uniformity over mixed-vendor new purchases. United States health system purchasing cooperatives drive volume aggregation for these independent operators.
- Academic Institutions:University hospital networks require software-upgradeable platforms supporting research protocol evolution.
- Research Facilities:Specialized imaging centers prioritize magnetic field stability and gradient performance for experimental applications.
Hospitals anchor procurement volume. Diagnostic Imaging Centers are gaining share fastest through network consolidation.
Application:
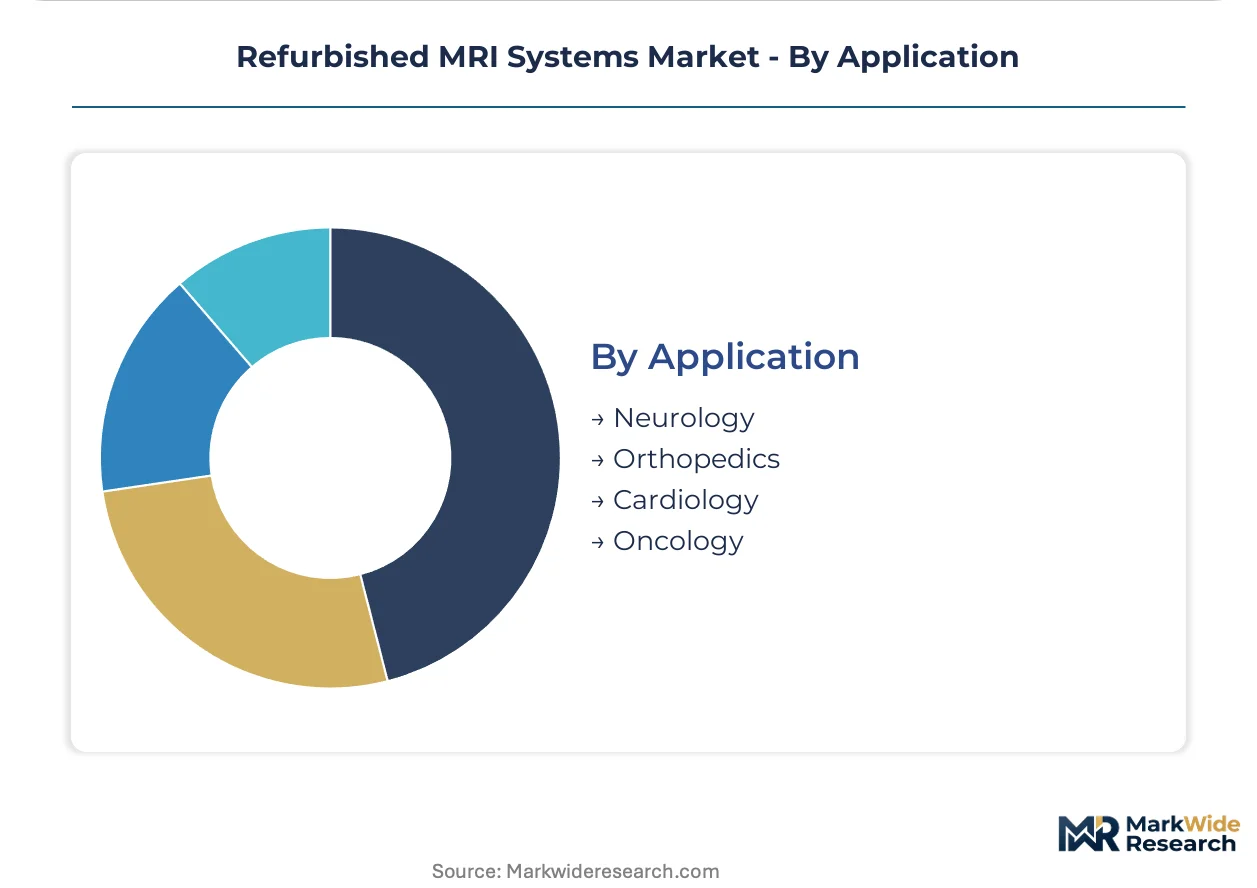
Neurology and orthopedic imaging concentrate refurbishment demand due to protocol standardization and high scan volume economics. Cardiology and oncology applications require specialized coil configurations and contrast-enhanced sequences that constrain secondary market suitability.
- Neurology:Brain and spine protocols demand high-field strength and advanced gradient systems for diffusion tensor and functional imaging. Academic medical centers in Germany prioritize refurbished 3.0T systems for these applications.
- Orthopedics:Musculoskeletal imaging tolerates broader field strength ranges and benefits from dedicated extremity coil configurations. Sports medicine clinics in the United States drive demand for compact refurbished systems.
- Cardiology:Cardiac MRI requires ECG-gated sequences and specialized phased-array coils.
- Oncology:Tumor staging and treatment response monitoring demands multi-parametric imaging capabilities.
Neurology commands the established base. Orthopedics shows the steepest expansion trajectory through outpatient clinic deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refurbishment capacity clusters around OEM-controlled remanufacturing networks in the United States, Germany, and India, where installed base density and regulatory certification infrastructure overlap. Third-party vendors concentrate in the Netherlands and Sweden to serve cross-border EU demand. Hospital procurement alliances in each geography shape vendor access patterns.
United States
Academic medical centers in Boston and university hospital networks in California drive demand for software-upgradeable 3.0T systems. FDA 510(k) clearance pathways favor OEM-controlled refurbishment networks with established predicate device libraries. GE Healthcare maintains remanufacturing operations in Wisconsin to sustain parts availability for secondary market units.
Germany
Hospital procurement alliances in Bavaria and North Rhine-Westphalia unbundle equipment acquisition from service contracts, opening third-party vendor access. EU MDR technical documentation obligations and ISO 13485 quality management standards elevate compliance costs for independent refurbishers. Siemens Healthineers anchors controlled asset recovery programs in Erlangen to extend equipment lifecycle value.
India
Government health scheme coverage extension and medical device manufacturing incentives under PLI schemes create procurement pull for cost-optimized imaging. CDSCO medical device regulations and BIS quality standards shape import and refurbishment compliance requirements. Diagnostic imaging centers in Maharashtra and Karnataka favor permanent magnet configurations for mid-tier urban deployments.
Netherlands
Secondary market participants consolidate certification capabilities in Rotterdam and Amsterdam to spread fixed EU MDR compliance investments across larger transaction volumes. EU AI Act algorithmic validation requirements tighten scrutiny of diagnostic software embedded in refurbished systems. Cross-border refurbishment operations serve German and Belgian hospital procurement alliances.
Sweden
Independent refurbishers concentrate conformity assessment capabilities in Stockholm and Gothenburg to address EU MDR technical documentation obligations. Helium recovery protocols and cryogenic system reclamation reduce reconditioning input costs for superconducting MRI units. Regional vendors export refurbished open-bore systems to bariatric-focused surgical centers in neighboring markets.
Refurbished MRI Systems Market Competitive Landscape
Concentration sits with OEM-controlled remanufacturing networks that leverage established predicate device libraries and FDA 510(k) clearance pathways. Independent refurbishers cluster in EU certification hubs to spread fixed compliance costs. Three archetypes dominate: OEM-captive remanufacturers with full technical certification infrastructure, third-party specialists with ISO 13485 accreditation unlocking hospital procurement eligibility, and regional consolidators aggregating cross-border refurbishment volumes. Competitive moves center on controlled asset recovery program expansion and multi-vendor maintenance capability development.
Among OEM-captive remanufacturers, GE Healthcare, Siemens Healthineers, and Koninklijke Philips N.V. exemplify the integrated refurbishment archetype. These Netherlands- and Germany-based entities occupy positions where technical certification infrastructure and parts availability sustain secondary market presence. GE Healthcare represents the OEM-captive model with remanufacturing networks anchored in established installed base regions. Siemens Healthineers exemplifies controlled asset recovery program structures that extend equipment lifecycle value. Koninklijke Philips N.V. sits within the software-upgradeable platform specialization, narrowing performance gaps with new installations through algorithmic enhancement capabilities.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| CANON MEDICAL SYSTEMS CORPORATION |
| Avante Health Solutions |
| Block Imaging |
| Soma Technology |
| Integrity Medical Systems |
| Atlantis Worldwide |
| Others |
Value Network & Pricing Analysis
Magnet core refurbishment economies concentrate around OEM-controlled facilities in Wisconsin, Erlangen, and Bangalore, where scale in cryogenic system reclamation and parts remanufacturing simultaneously depresses unit cost floors and elevates barriers for independent competitors lacking comparable throughput.
Pricing Analysis
Volume-discount tiering structures separate OEM-certified remanufactured systems from ISO 13485-accredited third-party refurbishment and uncertified secondary resale. Price differentiation hinges on FDA 510(k) clearance documentation and after-sales service bundling, with academic medical centers least sensitive and Indian diagnostic imaging centers most responsive to unbundled equipment-only quotes. Cost compression in the third-party tier is intensifying because helium recovery protocol investments are spreading fixed reclamation costs across larger magnet core volumes.
Supply Chain Analysis
Superconducting magnet core lead times stretch 16-24 weeks for niobium-titanium coil arrays drawn from United States, Japanese, and German superconductor foundries. Helium supply rests on Qatar, Algeria, and Russian extraction infrastructure, with single-source vulnerability concentrated in cryogenic gas logistics chokepoints at Rotterdam and Singapore transshipment hubs. Distribution runs through OEM direct sales for hospital procurement alliances and third-party refurbisher networks serving independent diagnostic imaging centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a regulatory-entrenchment defensive moat where FDA predicate device libraries and ISO 13485 certification infrastructure create switching costs that lock hospital procurement officers into established remanufacturing relationships.
For Market Incumbents: Consolidate controlled asset recovery programs in India and Germany to preempt third-party ISO 13485 accreditation expansion. Deepen backward integration into superconducting coil remanufacturing to offset helium supply volatility squeezing refurbishment margins. Capture hospital procurement alliance service contract disintermediation by offering multi-vendor maintenance capabilities that independent refurbishers cannot replicate.
For New Entrants and Emerging Players: CDSCO fast-track approval pathways for refurbished permanent magnet systems offer the most penetrable entry point into Maharashtra and Karnataka diagnostic imaging center procurement. Target bariatric-focused surgical centers in Germany and India with open-bore geometry specialization where patient comfort commands pricing premiums unavailable in commoditized closed-bore segments. Lead with software-upgradeable platform positioning to narrow performance gaps with OEM remanufactured units.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ISO 13485-accredited third-party refurbishers with consolidated EU MDR certification capabilities in the Netherlands and Sweden. Five-to-ten year viability hinges on AI-enabled diagnostic software integration trajectories where algorithmic validation requirements under EU AI Act favor scaled compliance investments. Monitor helium market price stabilization as the inflection signal for superconducting refurbishment margin recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Expansion | Unlocks hospital procurement eligibility previously reserved for OEM channels in German procurement alliances. |
| Helium Recovery Protocol Investment | Reduces reconditioning input costs for superconducting MRI units dependent on magnet cooling system restoration. |
| AI-Enabled Software Integration | Creates upgradeable system value propositions converging refurbished hardware with algorithmic image analysis tools. |
| Controlled Asset Recovery Program | Extends equipment lifecycle value through OEM-managed secondary market presence in installed base regions. |
| Multi-Vendor Maintenance Capability | Captures procurement officer demand for unbundled service contracts separate from equipment acquisition. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement officers, biomedical engineering directors, GPO contracts managers, and refurbishment vendor operations leads and refined through secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation registries, hospital procurement alliance contract disclosures, and ISO 13485 certification records. Bottom-up unit volume estimates triangulated with top-down expenditure analysis across the projection horizon.
Variance-decomposition framing structured the analytical approach across product type, technology architecture, end-user facility scale, and regional regulatory cluster dimensions. CAGRs were derived from installed base retirement curves and replacement demand elasticity modeling. Forecast inputs incorporated helium market price trajectory assumptions and CDSCO regulatory pathway evolution for import refurbishment compliance.
Underlying assumptions cover superconducting magnet core availability and EU AI Act algorithmic validation implementation timelines, with deviation risk concentrated in helium supply disruption and cross-border certification reciprocity gaps fragmenting refurbishment operations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Europe Medical Automation Market
Medical Equipment
Medical Oxygen Systems Market
Medical Equipment
Asia-Pacific Medical Carts Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
China Radiotherapy Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
Europe Medical Device Reprocessing Market
Medical Equipment
Sanitary Napkin Equipment Market
Medical Equipment
Terminal Sterilization Market
Medical Equipment
PCR Plate Sealer Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Global Portable Beds Market
Medical Equipment
Medical Gas Cylinders Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
Embedded Disinfection Cabinet Market
Medical Equipment
Biomedical Refrigerators and Freezers Market