
 Left Atrial Appendage (LAA) Closure Device Market | 2026-2036
Left Atrial Appendage (LAA) Closure Device Market Size, Share, and Industry Trends Forecast 2026-2036
Left Atrial Appendage (LAA) Closure Device Market Foresight
CE marking under the EU Medical Device Regulation (MDR) is unwinding competitive access across European markets, raising barriers for newer entrants while consolidating advantage among established manufacturers. Boston Scientific Corporation leverages its integrated catheter lab relationships to sustain placement momentum in transcatheter systems. Abbott Laboratories anchors its position through specialized structural heart portfolios that dominate hybrid procedure workflows. AtriCure, Inc. differentiates via surgical clip platforms that occupy a distinct indication niche alongside percutaneous alternatives.
Left atrial appendage closure devices are implantable mechanical occluders, typically constructed from nitinol mesh with polyester fabric membranes, designed to seal the LAA ostium and prevent thrombus egress in patients with non-valvular atrial fibrillation. The implant segment commands premium pricing due to permanent biocompatibility requirements and long-term durability validation, while the delivery system segment experiences rapid upgrade cycles as catheter ergonomics and fluoroscopic navigation improve. Transcatheter delivery mode leads procedural volume globally, though surgical approaches retain relevance in concomitant cardiac surgery cases where direct visualization optimizes placement accuracy.
FDA premarket approval pathways and EMA MDR conformity assessments shape product development timelines and commercial launch sequencing across major markets. The analysis indicates reimbursement determinations by CMS and parallel health technology assessment bodies in France and Germany will determine whether LAA closure expands beyond anticoagulation-intolerant populations to broader stroke prevention protocols. Stakeholders must monitor evolving anticoagulant pharmacotherapy guidelines, as shifts in bleeding risk calculus could either reinforce device demand or redirect patients toward pharmaceutical management depending on comparative effectiveness evidence.
Market Dynamics
Transcatheter delivery systems are compressing procedural timelines and displacing surgical alternatives, forcing manufacturers to recalibrate R&D priorities around catheter ergonomics and real-time imaging integration rather than implant durability alone.
Growth Catalysts
- EMA MDR pathway streamlining:The European Medicines Agency's consolidated conformity assessments for Class III implantable devices are accelerating market access timelines for manufacturers with established quality management systems.
- Hybrid operating room expansion:Cardiac centers across Germany, France, and Italy are retrofitting surgical suites for combined catheter-based and open procedures, creating dedicated LAA closure workflows.
- Nitinol mesh fabrication advances:Laser-cut superelastic alloys with enhanced fatigue resistance are extending implant lifecycle validation, supporting permanent biocompatibility claims under FDA premarket approval standards.
Market Restraints
- Platinum-iridium electrode cost volatility:Precious metal price fluctuations in catheter tip components are compressing gross margins on delivery systems amid fixed reimbursement ceilings.
- Single-source fluoroscopy dependency:Concentrated supply of high-resolution C-arm imaging systems from German and Japanese manufacturers creates procedural bottlenecks during equipment maintenance cycles.
- Anticoagulant pharmacotherapy substitution:Direct oral anticoagulants with improved bleeding risk profiles are retaining eligible patients in pharmaceutical management protocols rather than device referral pathways.
Strategic Opportunities
- India's CDSCO accelerated approval track:The national pharmaceutical regulator's priority review pathway for cardiovascular devices is opening commercialization channels ahead of full MDR harmonization.
- Convergent electrophysiology-LAA workflows:Integration of atrial fibrillation ablation with same-session appendage closure is creating bundled procedure demand in tertiary cardiac centers.
- Remote proctoring networks:Real-time surgical support via low-latency video platforms is enabling community hospital adoption without on-site specialist residency requirements.
Industry Challenges
- Interventional echocardiography skill scarcity:Transesophageal imaging expertise required for procedural guidance remains concentrated in academic medical centers, limiting workforce scalability.
- FDA PMA supplement backlog:Iterative catheter design modifications trigger extended regulatory review cycles, delaying ergonomic improvements from reaching clinical practice.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Left Atrial Appendage (LAA) Closure Device Market |
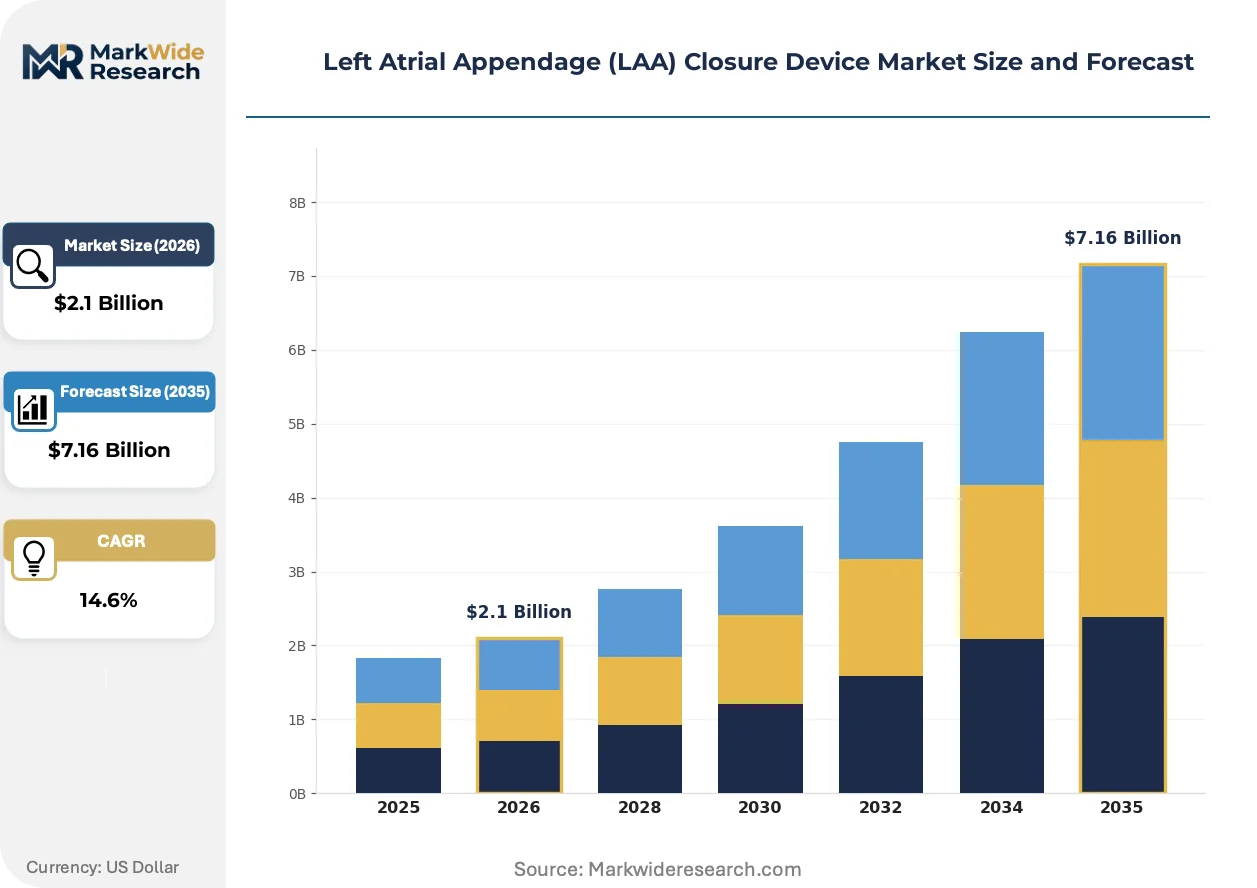
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Device, Implant, Accessory, Delivery System End User: Hospitals, Outpatient Clinics, Cardiac Centers, Research Institutions Delivery Mode: Transcatheter, Surgical, Hybrid, Percutaneous Indication: Atrial Fibrillation, Stroke Prevention, Thromboembolism, Cardiovascular Disorders |
| Companies Covered | Boston Scientific Corporation, Abbott Laboratories, AtriCure, Inc., Johnson & Johnson, Lifetech Scientific, Occlutech, Cardia, Inc., Lepu Medical Technology, SentreHEART, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Left Atrial Appendage (LAA) Closure Device Market Shifts & Advancements
Device miniaturization and procedural simplification are converging to expand treatable patient populations beyond anticoagulation-intolerant cohorts, reshaping competitive differentiation around operator learning curves and complication rates.
Self-expanding nitinol occluders with integrated anchoring mechanisms are decomposing the traditional separation between implant stability and delivery system complexity. Hybrid cardiac centers in the United States and Germany are adopting these platforms for same-day discharge protocols. The technology is decomposing established training hierarchies by reducing fluoroscopy exposure time and enabling broader operator certification.
EU MDR Article 120 transitional provisions are forcing systematic clinical data regeneration for legacy CE-marked devices, compressing available review resources at notified bodies. Manufacturers with pre-2021 approvals face parallel compliance deadlines while navigating divergent national implementation timelines. The surgical clip segment is responding through prospective registry investments to satisfy post-market surveillance requirements under the new framework.
Institutional procurement committees are consolidating vendor relationships around comprehensive structural heart portfolios rather than standalone LAA devices. Integrated catheter lab contracts with multi-year service agreements are displacing transactional implant purchasing across North American hospital systems. This concentration is most visible in integrated delivery networks where standardization incentives override individual physician preference.
Left Atrial Appendage (LAA) Closure Device Market Segmentation
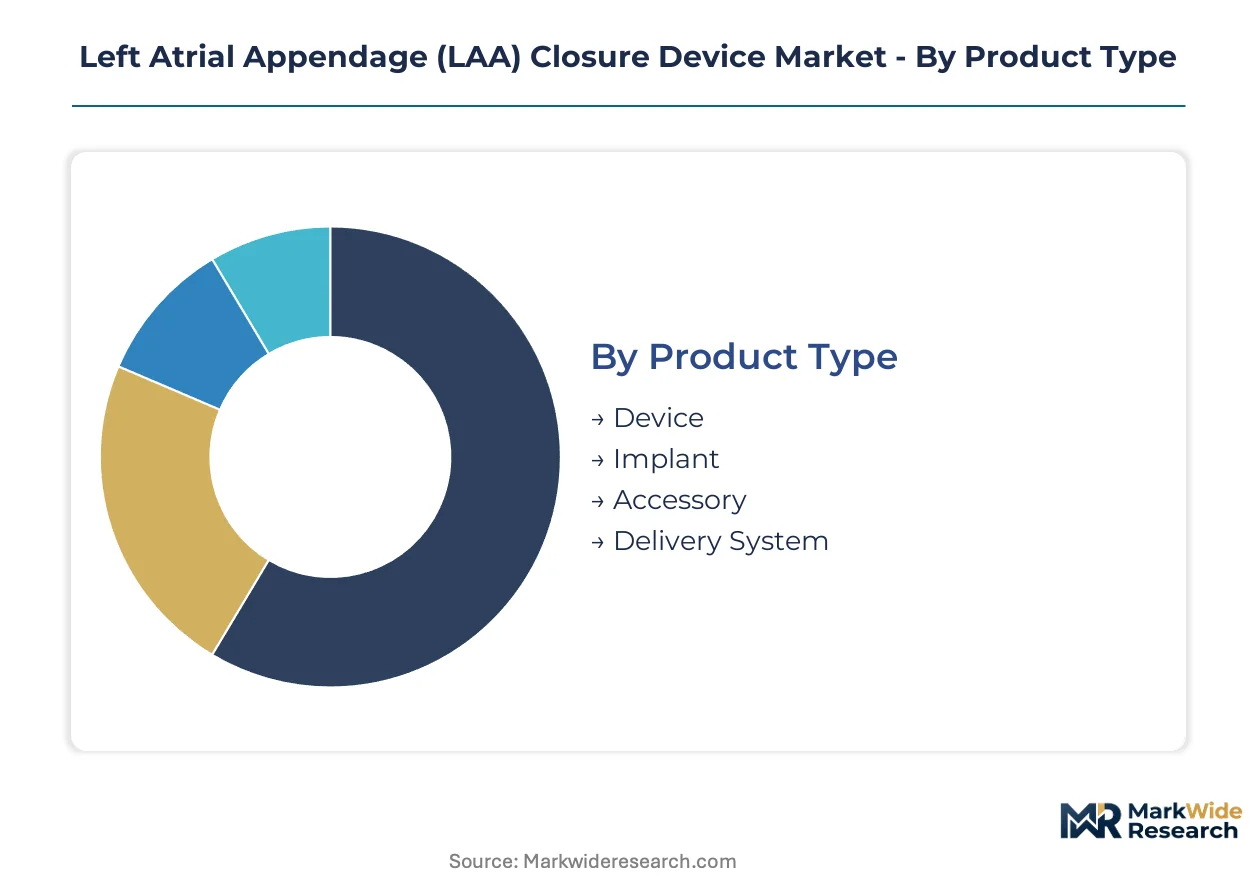
Segmentation in the LAA closure device market reveals how purchasing authority, procedural setting, and patient acuity reshape vendor engagement models. Manufacturers must align product configurations with distinct clinical workflows across catheter labs, hybrid suites, and surgical theaters.
Product Type:
Implantable occluders dominate domestic manufacturing footprints in the United States and Germany, while delivery systems concentrate assembly in cost-optimized Asian supply chains for re-export.
- Device:Complete system assemblies integrating implant and delivery components. German cardiac centers specify integrated platforms to streamline procurement standardization across multi-site networks.
- Implant:Nitinol mesh occluders with polyester fabric membranes requiring permanent biocompatibility validation. FDA premarket approval pathways and EMA MDR conformity assessments govern commercial access timelines for these highest-value components.
- Accessory:Sheaths, guidewires, and sizing balloons. These items generate recurring revenue streams but face margin compression from hospital group purchasing consolidation.
- Delivery System:Catheter-based deployment mechanisms with steerable tips and fluoroscopic markers. Transcatheter delivery mode advancement is compressing upgrade cycles for these components.
Implant holds the largest share; momentum sits with delivery system innovation.
End User:
Cost tier stratification separates capital-intensive integrated delivery networks from independent outpatient facilities with constrained equipment budgets.
- Hospitals:Acute care facilities with catheterization laboratories and hybrid operating rooms. These institutions command volume-based pricing leverage and multi-year service agreements.
- Outpatient Clinics:Ambulatory settings performing same-day discharge protocols. CMS reimbursement determinations shape procedure economics for this expanding channel.
- Cardiac Centers:Specialized structural heart programs with electrophysiology integration. German centers are retrofitting surgical suites for combined catheter-based and open procedures.
- Research Institutions:Academic medical centers conducting post-market surveillance under EU MDR Article 120 transitional provisions. These sites generate clinical data supporting expanded indications.
Hospitals anchor volume; cardiac centers are climbing the fastest.
Delivery Mode:
Application complexity separates minimally invasive approaches from open surgical alternatives, with hybrid workflows emerging in tertiary referral patterns.
- Transcatheter:Percutaneous femoral access with fluoroscopic and echocardiographic guidance. This approach captures concentrated demand across North American hospital systems seeking reduced recovery timelines.
- Surgical:Direct visualization through thoracotomy or sternotomy. Concomitant cardiac surgery cases retain this mode where placement accuracy optimizes alongside valve or bypass procedures.
- Hybrid:Combined catheter-based and surgical techniques in equipped operating rooms. German, French, and Italian centers are creating dedicated LAA closure workflows through suite retrofitting.
- Percutaneous:Minimally invasive access distinct from formal transcatheter protocols. This segment serves specific anatomical variations requiring alternative vascular entry points.
Transcatheter commands procedural volume; hybrid configurations are gaining share fastest.
Indication:
Patient risk stratification separates anticoagulation-intolerant populations from broader stroke prevention candidates eligible for device therapy.
- Atrial Fibrillation:Non-valvular arrhythmia driving LAA thrombus formation. Device eligibility hinges on CHA₂DS₂-VASc scoring and bleeding risk assessment.
- Stroke Prevention:Primary indication for mechanical occlusion in patients contraindicated for long-term anticoagulation. Health technology assessment bodies in France and Germany are evaluating expansion beyond this narrow cohort.
- Thromboembolism:Established or suspected LAA thrombus requiring intervention. Acute presentations demand expedited procedural protocols with specialized imaging.
- Cardiovascular Disorders:Broader comorbidities including heart failure and coronary artery disease influencing device selection and antithrombotic management.
Stroke prevention anchors reimbursement; atrial fibrillation volumes are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS reimbursement determinations in the United States are expanding procedure access beyond anticoagulation-intolerant cohorts, while EMA MDR transitional provisions compress commercial timelines across European markets. German cardiac centers are retrofitting hybrid suites at the fastest pace globally, and India's CDSCO priority pathway is accelerating market entry for structural heart portfolios.
United States
Integrated delivery networks in Texas and Florida are consolidating vendor relationships around multi-year catheter lab service agreements. FDA premarket approval pathways govern commercial sequencing for nitinol mesh occluders, with iterative design modifications triggering extended review cycles. The Cleveland Clinic and Mayo Clinic anchor structural heart training networks that propagate operator certification standards nationwide.
Germany
Bavarian and North Rhine-Westphalian cardiac centers are expanding hybrid operating room capacity for combined ablation-appendage closure workflows. EMA MDR Article 120 conformity assessments are forcing systematic clinical data regeneration for legacy CE-marked devices, compressing notified body review resources. Berlin and Munich academic medical centers generate post-market surveillance data supporting expanded indication claims under the new regulatory framework.
India
Maharashtra and Karnataka hospital systems are adopting remote proctoring networks to bypass interventional echocardiography skill scarcity in tier-two cities. CDSCO accelerated approval tracks for cardiovascular devices are opening commercialization channels ahead of full MDR harmonization with European standards. Apollo Hospitals and Fortis Healthcare anchor catheter-based LAA closure training programs across Delhi-NCR and Chennai clusters.
Japan
PMDA consultation pathways are streamlining pre-submission dialogue for nitinol fatigue validation protocols required under amended pharmaceutical and medical device regulations. Kanto and Kansai regions concentrate structural heart procedure volume, with Tokyo University Hospital and Osaka University Hospital serving as proctoring hubs for community hospital expansion. METI industrial policy supports domestic manufacturing of laser-cut superelastic alloys for regional supply security.
China
NMPA innovative device designation pathways are compressing review timelines for catheter-based delivery systems with integrated anchoring mechanisms. Yangtze River Delta and Pearl River Delta manufacturing clusters dominate nitinol mesh fabrication for export markets, while Beijing-Tianjin-Hebei academic centers validate same-day discharge protocols. Fuwai Hospital and Zhongshan Hospital anchor national training networks for transcatheter LAA closure standardization.
Left Atrial Appendage (LAA) Closure Device Market Competitive Landscape
Listed leaders compete with private specialists across integrated catheter lab contracting, with public companies leveraging balance sheet capacity for multi-year service agreements while private operators retain flexibility in niche indication segments. The vendor base stratifies into three tiers: diversified medtech conglomerates with structural heart portfolios, pure-play occluder specialists, and regional fabricators serving cost-optimized procurement channels. Dominant competitive moves include portfolio bundling around comprehensive structural heart contracts and backward integration into nitinol mesh fabrication to secure supply continuity.
Among diversified medtech conglomerates, Boston Scientific Corporation and Abbott Laboratories exemplify the integrated portfolio archetype, anchoring vendor relationships through catheter lab ecosystem control. AtriCure, Inc. occupies a distinct position within the surgical clip segment, representing the pure-play specialist model alongside percutaneous alternatives. These three entities collectively illustrate the competitive tension between procedure workflow integration and indication-specific technology differentiation.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Abbott Laboratories |
| AtriCure, Inc. |
| Johnson & Johnson |
| Lifetech Scientific |
| Occlutech |
| Cardia, Inc. |
| Lepu Medical Technology |
| SentreHEART, Inc. |
| Others |
Supply & Pricing Matrix
Laser-cut nitinol mesh substitution for woven polyester membranes is redrawing manufacturing geography toward Yangtze River Delta clusters while compressing implant pricing premiums through standardized superelastic alloy sourcing.
Pricing Analysis
Certification level (FDA PMA-grade versus CE MDR-transitional) creates the primary spread between implant tiers, with pre-2021 legacy devices trading at discounts against fully validated next-generation occluders. Three-tier pricing structure across premium integrated-system contracts, standard transactional implant sales, and economy accessory bundles reflects procurement consolidation pressure from North American integrated delivery networks. Cost compression in delivery systems is intensifying because precious metal electrode volatility meets fixed CMS reimbursement ceilings. Independent outpatient clinics exhibit highest price sensitivity, while German cardiac centers with hybrid suite investments prioritize system integration over unit economics.
Supply Chain Analysis
Strategic stockpiling of nitinol raw ingot dominates manufacturer inventory posture given superelastic alloy lead time variability, contrasting with just-in-time assembly for catheter handle components. Supply concentrates in China's Yangtze River Delta for mesh fabrication, Germany's precision laser-cutting corridors for frame production, and Costa Rica's medtech parks for final sterile packaging. Raw material dependencies encompass nickel-titanium alloy feedstock, platinum-iridium electrode wire, and medical-grade polyester fabric. Single-source vulnerability in high-resolution C-arm imaging systems from Japanese and German OEMs creates procedural bottlenecks. Distribution runs through GPO-negotiated hospital system contracts with multi-year service agreements displacing spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LAA closure device market sits in early-cycle expansion as same-day discharge protocols broaden treatable populations beyond anticoagulation-intolerant cohorts into primary stroke prevention pathways.
For Market Incumbents: Compound catheter lab ecosystem control through backward integration into nitinol mesh fabrication, securing captive supply against Yangtze River Delta concentration risk while embedding multi-year service agreements that raise switching costs for integrated delivery networks. Deepen structural heart portfolio bundling to defend against pure-play surgical clip specialists occupying concomitant cardiac surgery workflows. For New Entrants and Emerging Players: Anchor in India's tier-two city hospital systems where remote proctoring networks bypass interventional echocardiography skill scarcity and CDSCO accelerated approval tracks compress commercialization timelines ahead of MDR harmonization. Target outpatient clinic channels with simplified delivery system ergonomics that reduce fluoroscopy exposure and enable broader operator certification without academic medical center residency requirements. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play occluder specialists with established CE MDR Article 120 compliance packages and prospective registry investments satisfying post-market surveillance requirements, as these assets command scarcity premium in consolidation scenarios. Monitor anticoagulant pharmacotherapy guideline revisions as the critical inflection signal; shifts toward improved bleeding risk profiles in direct oral anticoagulants would redirect patient flows away from device referral pathways.| Strategic Initiative | Industry Significance |
|---|---|
| CE MDR Article 120 Compliance Investment | Systematic clinical data regeneration secures notified body resources ahead of legacy device deadline compression. |
| Hybrid Operating Room Partnership | German cardiac center retrofitting creates dedicated ablation-appendage closure workflow capture. |
| Remote Proctoring Network Deployment | Real-time surgical support enables community hospital adoption without on-site specialist residency infrastructure. |
| Nitinol Mesh Backward Integration | In-house superelastic alloy fabrication insulates against precious metal price volatility and supply concentration risk. |
| Same-Day Discharge Protocol Validation | CMS reimbursement determination support expands procedure economics beyond anticoagulation-intolerant populations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA PMA submission databases, EMA MDR Article 120 transitional filing records, and CMS Medicare procedure claims data. Interviews with structural heart program directors, catheterization laboratory managers, biomedical engineering procurement leads, and GPO contract specialists inform demand-side validation. Bottom-up implant volume estimates triangulate against top-down hospital system expenditure analysis across the analysis window.
Segmentation dimensions modeled encompass product type (implant, delivery system, accessory), delivery mode (transcatheter, surgical, hybrid), end-user setting (hospital, outpatient clinic, cardiac center), and indication severity (stroke prevention, atrial fibrillation with comorbidities). CAGRs derive from procedure volume trajectory analysis combined with pricing elasticity assumptions around reimbursement determination impacts. Forecast inputs incorporate hybrid suite installation rates and interventional echocardiography workforce expansion constraints.
Decision-makers should treat outputs as directional under assumptions of stable anticoagulant pharmacotherapy guidelines and sustained CMS reimbursement parity; material deviation in bleeding risk calculus or coverage determination would warrant model refresh. Revision becomes warranted when direct oral anticoagulant comparative effectiveness evidence crosses thresholds that redirect patient referral patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Sialendoscopes Market
Medical Devices
Bone Power Tools Market
Medical Devices
Vein Illumination Devices Market
Medical Devices
Global Implantable Cardiac Monitor Market
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
Global Surgical Microscopes Market
Medical Devices
Wearable Insulin Pump Market
Medical Devices
Cardioscope Market
Medical Devices
Urine Flow Meters Market
Medical Devices
Europe Intraocular Lens Market
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
Peripheral Embolization Device Market
Medical Devices
ETCO2 Masks Market
Medical Devices
Global Extremities Market