
 Isobornyl Acrylate Market | 2026-2036
Isobornyl Acrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Isobornyl Acrylate Market Intelligence
A strategic shift from single-source contracts to multi-source procurement for specialty monomers is recalibrating supply chain strategies for coatings and adhesives formulators. This diversification mitigates risks associated with raw material volatility. In this environment, Evonik leverages its extensive production network to ensure consistent supply. NIPPON SHOKUBAI differentiates through its focus on high-purity grades for demanding electronics applications, while Sartomer positions itself as a key supplier for energy-curing technologies.
Isobornyl acrylate (IBOA) is a monofunctional acrylate monomer characterized by its bulky, cyclic structure. This chemical composition imparts excellent thermal stability, low shrinkage, and superior adhesion to substrates in polymer systems. It serves as a reactive diluent in ultraviolet (UV) and electron beam (EB) curable formulations. Coatings applications represent the largest segment, driven by performance needs in automotive and industrial finishes, while the adhesives category is expanding rapidly.
Regulatory frameworks are a primary influence on material selection. The European Union's REACH legislation and the US EPA's Toxic Substances Control Act (TSCA) impose strict registration and evaluation requirements for chemical substances. These rules, alongside China's initiatives to reduce volatile organic compound (VOC) emissions, favor the use of IBOA in compliant, low-VOC systems. The key decision for manufacturers now revolves around investing in bio-based feedstock development to meet future sustainability criteria.
Market Dynamics
The central structural force shaping the isobornyl acrylate market is the global regulatory clampdown on volatile organic compounds. This pressure, exemplified by frameworks like the EU Green Deal, directly favors IBOA's use as a reactive diluent in compliant formulations.
Growth Catalysts
- Low-VOC Regulations:Mandates in Europe and China to reduce industrial emissions are accelerating the replacement of solvent-based systems with UV/EB-curable technologies, where IBOA is a key component for achieving desired viscosity and performance without adding VOCs.
- Automotive Coatings Demand:The automotive sector's requirement for durable, scratch-resistant, and high-gloss finishes drives IBOA consumption. Its properties enhance the performance of clear coats, topcoats, and plastic component finishes, aligning with OEM quality standards.
- Energy Curing Technology:Advances in UV-LED and electron beam curing equipment make the process faster and more energy-efficient. This technological maturation lowers the barrier to entry for formulators, expanding the addressable market for compatible monomers like isobornyl acrylate.
Market Restraints
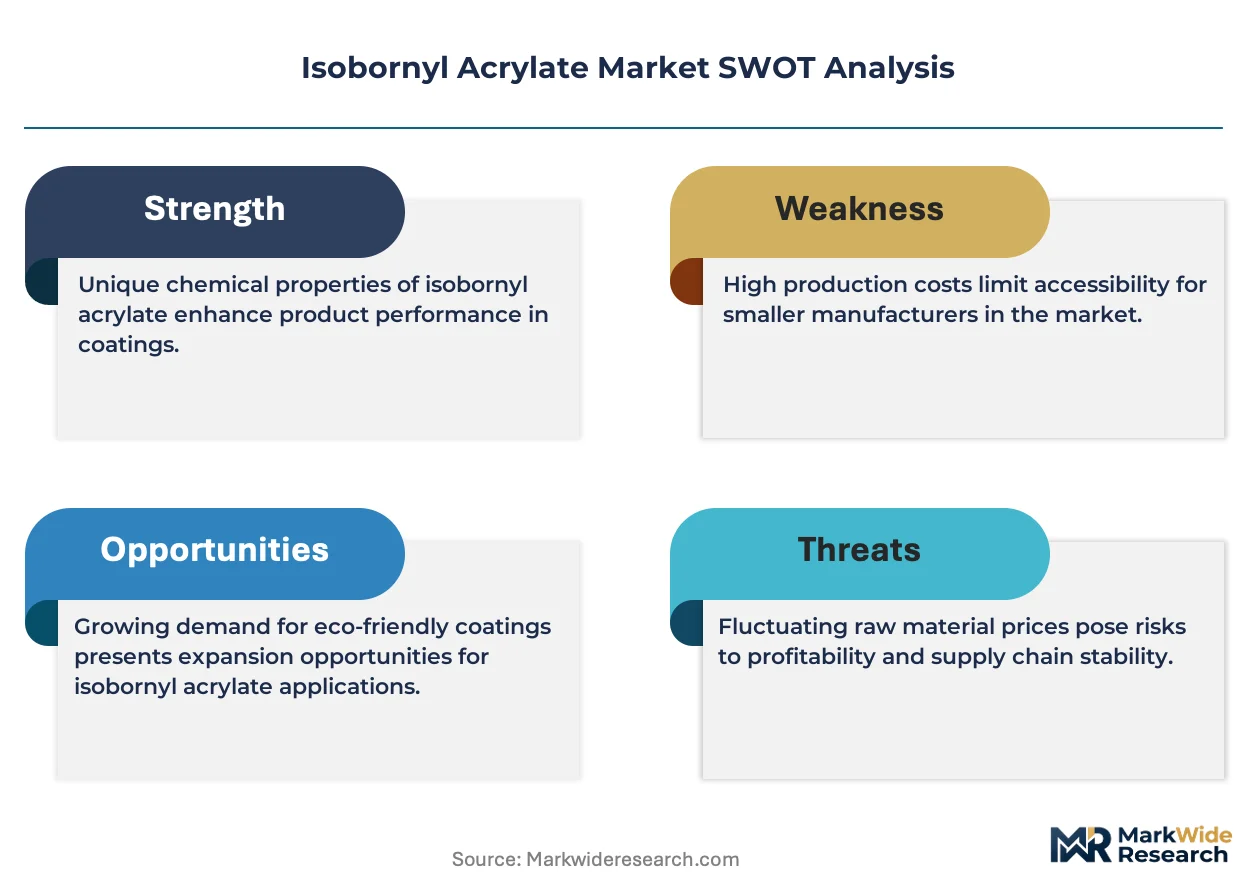
- Feedstock Price Volatility:The price of IBOA is closely tied to its petrochemical-derived feedstocks, particularly camphene. Fluctuations in crude oil prices and supply-chain disruptions for these precursors introduce significant cost instability for monomer producers and formulators.
- Substitution from Other Monomers:Formulators can substitute IBOA with other cyclic or functional monomers, such as isobornyl methacrylate (IBOMA) or tetrahydrofurfuryl acrylate (THFA), based on specific performance requirements, cost considerations, and regional availability, limiting market penetration.
- Supply Chain Concentration:A significant portion of global IBOA production capacity is concentrated in China. This geographic centralization creates vulnerability to regional policy changes, logistical bottlenecks, or trade disputes, posing a supply risk for consumers in other regions.
Strategic Opportunities
- Bio-Based Feedstock Development:Investing in the development and scaling of bio-based IBOA derived from renewable sources like bio-terpenes presents a major opportunity. This aligns with corporate sustainability goals and appeals to end-users seeking a lower carbon footprint.
- 3D Printing and Additive Manufacturing:The unique properties of IBOA, such as low shrinkage and high glass transition temperature, make it an ideal monomer for photopolymer resins used in stereolithography (SLA) and digital light processing (DLP) 3D printing applications.
- Geographic Expansion in Electronics:There is an opportunity to supply high-purity IBOA to burgeoning electronics manufacturing hubs in Southeast Asian countries. These markets require advanced materials for conformal coatings, encapsulants, and adhesives in semiconductor and display production.
Industry Challenges
- Complex Regulatory Compliance:Manufacturers face significant operational hurdles in navigating the complex and divergent chemical registration requirements of frameworks like the EU's REACH and the US EPA's TSCA, which can delay market access and increase administrative costs.
- Purity and Quality Control:Achieving and maintaining the ultra-high purity levels demanded by the electronics and optical industries is a persistent challenge. It requires substantial investment in advanced purification processes and stringent quality assurance protocols to minimize contaminants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isobornyl Acrylate Market |
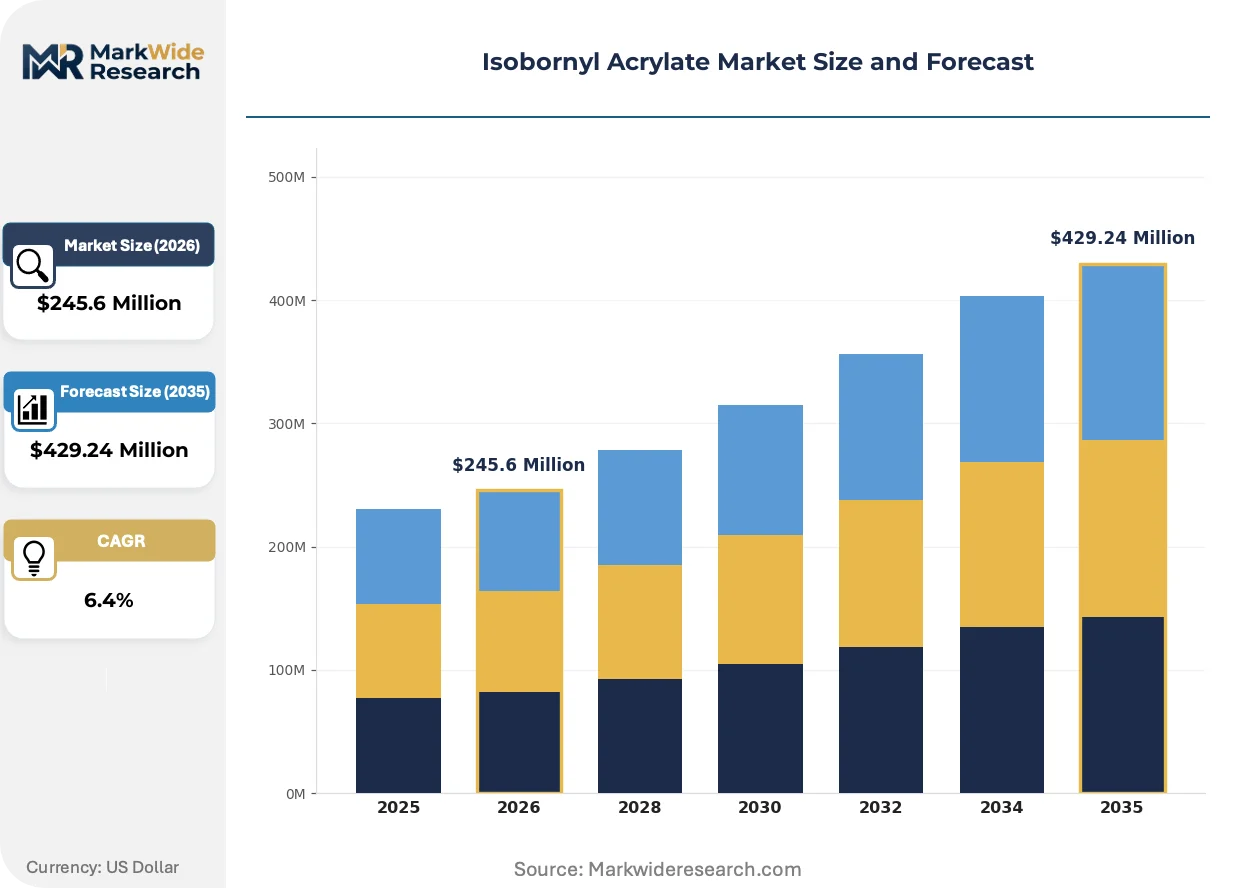
| Market Size in 2026 | $245.6 Million |
| Market Size in 2035 | $429.24 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monomers, Polymers, Blends, Additives Application: Coatings, Adhesives, Inks, Sealants End User: Automotive, Electronics, Construction, Textiles Form: Liquid, Solid, Paste, Gel |
| Companies Covered | NIPPON SHOKUBAI, Osaka Organic Chemical Industry Ltd., Evonik, Sartomer, IGM Resins, Solvay, Wuxi Acryl Technology, Green Pine, Tianchi Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isobornyl Acrylate Market Strategic Shifts & Innovations
Material science advancements are intersecting with stringent environmental standards to redefine product development and application scope. The market is evolving beyond commodity grades toward specialized formulations that solve specific performance challenges in high-tech industries, driven by regulatory tailwinds.
High-purity IBOA grades are specifically engineered to offer superior optical clarity and minimal ionic contamination for sensitive end-uses. Manufacturers in the microelectronics and optical film sectors are steadily adopting these premium materials. This specialization is expanding into new demanding applications like advanced display technologies, high-resolution photopolymers for additive manufacturing, and optical fiber coatings.
China's "dual carbon" goals and related MEE policies are imposing stricter limits on industrial VOC emissions. This regulatory action directly compels formulators of coatings, inks, and adhesives to shift away from solvent-borne systems toward 100% solids UV-curable technologies. The industrial coatings segment in manufacturing zones like the Pearl River Delta is most affected, accelerating the transition to compliant systems using reactive diluents like IBOA.
A strategic move toward multi-sourcing specialty monomers is altering how large-scale formulators manage their supply chains. This diversification from reliance on single-supplier contracts is a direct response to raw material price volatility and geopolitical supply risks. This procurement trend is most visible among multinational coatings and adhesives producers who are building more resilient networks across suppliers in both Asia and North America.
Isobornyl Acrylate Market Segmentation
Understanding the Isobornyl Acrylate market through segmentation reveals the diverse applications and product forms driving its expansion. This breakdown highlights the specific performance requirements and end-user demands that shape product development and market strategies for manufacturers.
Product Type:
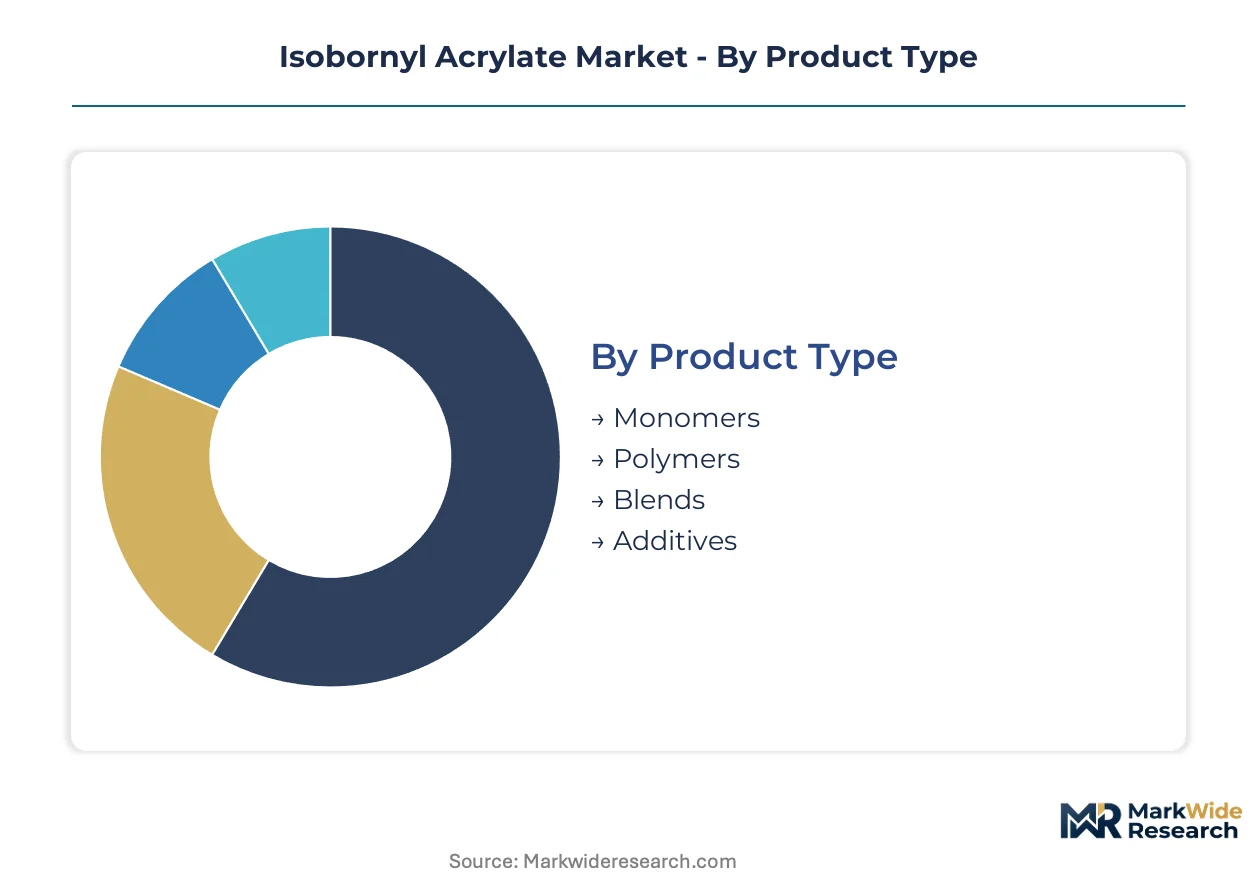
The Isobornyl Acrylate market differentiates across a spectrum from highly customized blends to standardized monomers, reflecting varied performance requirements.
- Monomers:Isobornyl Acrylate Monomers are the base chemical, characterized by a bulky, cyclic structure that imparts excellent thermal stability. Demand is high in UV-curable formulations for industrial coatings in China, where low-VOC systems are mandated by MEE policies.
- Polymers:Isobornyl Acrylate Polymers are formed from the monomer, offering enhanced film-forming properties and chemical resistance. These are crucial for high-performance automotive clear coats, particularly in European markets adhering to stringent environmental standards.
- Blends:These formulations combine IBOA with other acrylates or additives to achieve specific performance profiles for specialized industrial applications.
- Additives:Isobornyl Acrylate serves as a reactive diluent, reducing viscosity and enhancing curing speed in various resin systems.
Leading the category by volume: Monomers. Growing fastest: Blends.
Application:
The utility of isobornyl acrylate spans a range of applications, each presenting distinct cost structures and performance expectations.
- Coatings:Isobornyl acrylate enhances scratch resistance, adhesion, and flexibility in UV-curable coatings for various substrates. The automotive sector in Germany utilizes these for durable exterior finishes and interior components.
- Adhesives:IBOA contributes to high bond strength, low shrinkage, and thermal stability in UV-curable adhesive formulations. Electronics manufacturing in South Korea increasingly adopts these for device assembly and protection.
- Inks:IBOA improves adhesion and cure speed in UV-curable inks for packaging and graphic arts printing.
- Sealants:Isobornyl acrylate provides weather resistance and flexibility to sealants used in construction and automotive assembly.
Coatings maintain the largest share, while adhesives exhibit the steepest expansion trajectory.
End User:
End-user industries for isobornyl acrylate exhibit varying consumption volumes, driven by specific material requirements and production scales.
- Automotive:This sector demands IBOA for high-performance clear coats and primers, offering UV resistance and durability against environmental factors. OEMs in Japan integrate IBOA into their paint systems for enhanced finish quality and longevity.
- Electronics:The electronics industry uses high-purity IBOA in conformal coatings and encapsulants for semiconductors and displays, minimizing ionic contamination. Manufacturers in Taiwan require these for advanced device protection and optical clarity.
- Construction:IBOA is incorporated into flooring, roofing, and architectural coatings for enhanced durability and UV resistance.
- Textiles:The textile industry utilizes IBOA in specialized coatings for fabric protection and performance enhancement in technical textiles.
The automotive sector commands the highest material volume, with electronics manufacturing quickly gaining share.
Form:
Isobornyl acrylate is available in various physical forms, each catering to different processing requirements and application maturity levels.
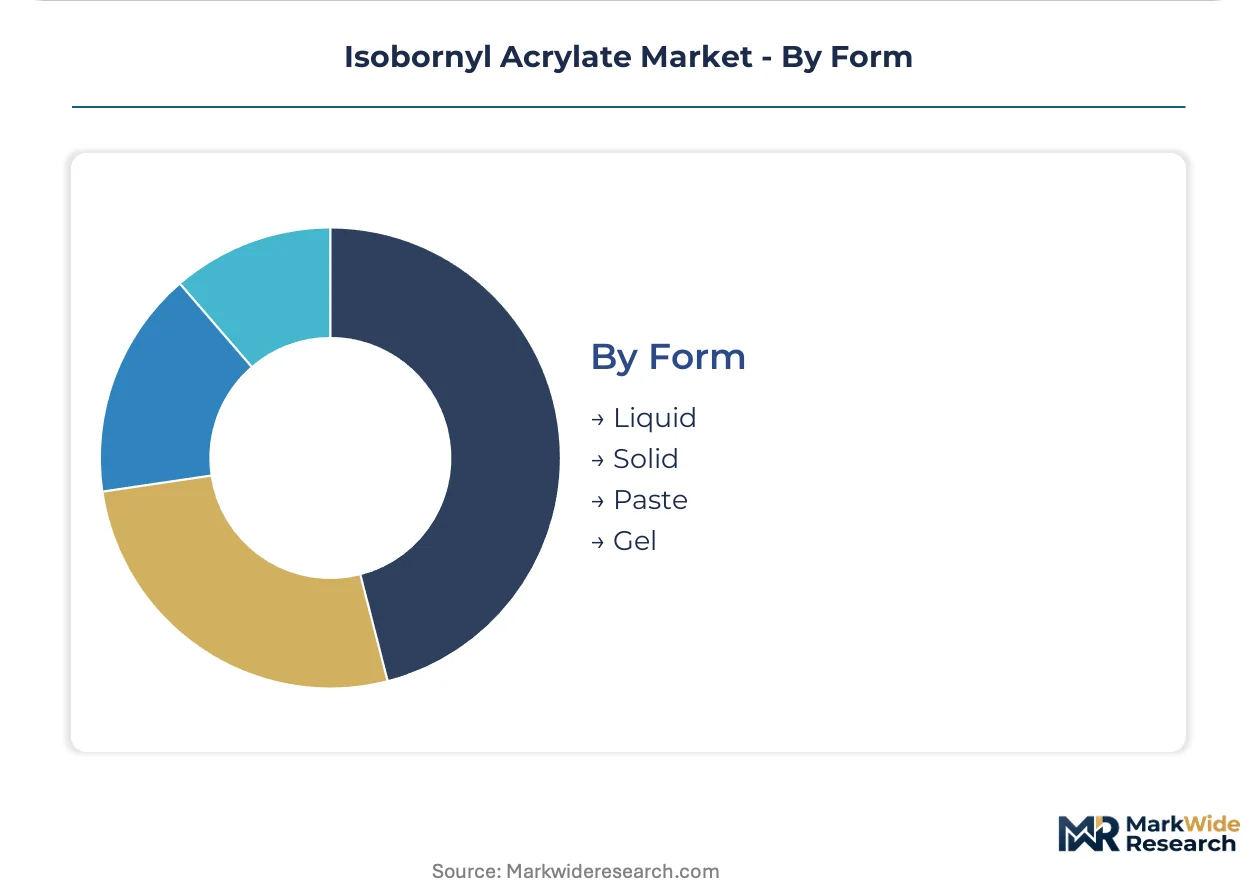
- Liquid:The most common form, liquid IBOA is directly used as a reactive diluent in UV/EB curable formulations, facilitating ease of handling. This form is widely adopted in industrial coatings production across Europe for its versatility.
- Solid:Solid IBOA offers convenience for specific compounding processes and applications requiring higher purity or controlled release. It finds niche use in certain specialty polymer systems and additive manufacturing.
- Paste:Isobornyl acrylate pastes are formulated for specific applications requiring higher viscosity or ease of application in specialized industrial settings.
- Gel:Gel forms of IBOA are utilized in specialized applications where controlled flow and curing characteristics are essential, such as optical fiber coatings.
Liquid IBOA dominates the market, while solid forms show emerging interest for niche applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's significant role in petrochemical feedstock production and its concentration of Isobornyl Acrylate manufacturing capacity anchors the global supply chain. This geographic focus influences material availability and cost dynamics across international markets. Formulators worldwide depend on these supply streams for their UV-curable systems.
China
Demand for IBOA in China stems from its burgeoning automotive and electronics manufacturing sectors. The country's "dual carbon" goals and MEE policies impose strict limits on industrial VOC emissions. The Pearl River Delta manufacturing zones are rapidly transitioning to compliant UV-curable systems.
Germany
German automotive manufacturers require IBOA for high-performance clear coats and durable exterior finishes. The EU Green Deal and REACH legislation drive the adoption of low-VOC, UV-curable formulations. The automotive clusters in Bavaria and Baden-Württemberg integrate IBOA into advanced paint systems.
United States
The United States experiences strong demand for IBOA in industrial coatings and 3D printing applications. The US EPA's Toxic Substances Control Act (TSCA) mandates stringent chemical substance evaluations. Advanced manufacturing hubs in the Midwest and Southeast utilize IBOA for specialized polymer systems.
Japan
Japanese electronics and automotive OEMs prioritize high-purity IBOA for advanced display technologies and enhanced finish quality. METI promotes sustainable manufacturing practices and material innovation. Production facilities in the Kanto region focus on specialized IBOA grades for optical fiber coatings.
South Korea
Electronics manufacturing in South Korea increasingly adopts IBOA for high-strength adhesives and encapsulants in semiconductors. MFDS regulates chemical substances, ensuring product safety and quality. Device assembly plants in the Seoul Capital Area demand high-purity IBOA for advanced device protection.
Isobornyl Acrylate Market Key Industry Players
Differentiation through specialization dominates the current landscape for isobornyl acrylate producers. The market exhibits a tiered structure, encompassing large, integrated chemical companies and specialized monomer manufacturers. Key strategic archetypes include global integrated chemical producers, niche high-purity suppliers, and regional focused suppliers. Portfolio diversification into bio-based feedstocks and geographic expansion into emerging electronics hubs represent dominant competitive moves, reflecting efforts to mitigate supply chain risks and meet evolving sustainability demands. The shift towards multi-source procurement further shapes these competitive dynamics.
Among the global integrated chemical producers, Evonik leverages its extensive production network to ensure consistent supply across diverse regions, supporting large-scale formulators. NIPPON SHOKUBAI exemplifies a high-purity specialist, focusing its offerings for demanding electronics applications where minimal ionic contamination is crucial. Sartomer occupies a position as a key supplier for energy-curing technologies, providing specialized solutions for UV and EB curable formulations across industrial and automotive sectors. These companies represent distinct strategic approaches within the competitive environment, responding to the growing demand for low-VOC and high-performance materials.
| Leading Market Players |
|---|
| NIPPON SHOKUBAI |
| Osaka Organic Chemical Industry Ltd. |
| Evonik |
| Sartomer |
| IGM Resins |
| Solvay |
| Wuxi Acryl Technology |
| Green Pine |
| Tianchi Chemical |
| Others |
Cost & Logistics Intelligence
Large formulators sourcing isobornyl acrylate for high-performance applications often engage in long-term contract pricing. This approach mitigates raw material volatility and ensures consistent supply for their demanding production schedules.
Pricing Analysis
Warranty bundling and technical support often accompany premium IBOA grades, particularly for electronics and automotive applications. The primary pricing model is contract-based long-term offtake, ensuring stability for both producers and large-volume buyers. Price differentiation stems from purity levels required for sensitive electronics and the volume scale of the order. Pricing softness runs through standard grades due to substitution from other monomers. Electronics manufacturers exhibit the least price sensitivity for ultra-high purity IBOA.
Supply Chain Analysis
Isobornyl acrylate production relies heavily on petrochemical-derived feedstocks like camphene. Supply concentration centers on China, which hosts a significant portion of global manufacturing capacity. This geographic centralization creates vulnerability to regional policy shifts and logistical bottlenecks. Downstream distribution runs through a mix of direct sales to large, integrated chemical companies and specialized distributors serving smaller formulators globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a vertical-integration race, with players pursuing control over bio-based feedstock development to meet future sustainability criteria.
For Market Incumbents: Cement market leadership by investing in diversified feedstock procurement outside of primary petrochemical sources. Expand production capacity for high-purity IBOA grades in strategic regions like Europe and Southeast Asia to mitigate supply chain risks. Develop advanced certification processes to differentiate premium offerings against emerging substitute technologies. Prioritize R&D in bio-based IBOA to future-proof product portfolios against evolving environmental regulations.
For New Entrants and Emerging Players: Specialized distributors offer a viable entry point for niche IBOA applications. Target the underpenetrated 3D printing and additive manufacturing segments, which value IBOA's low shrinkage and high glass transition temperature. Focus on high-purity grades for burgeoning electronics manufacturing hubs in Southeast Asian countries. Develop strong technical support and customized formulation services to build customer loyalty.
For Investors and Strategic Acquirers: Distressed-cycle entries favor acquirers with strong balance sheets in specialty chemical sectors. Long-term viability hinges on the continued global shift towards low-VOC, UV-curable systems. Identify acquisition targets with proprietary bio-based feedstock technologies or advanced purification capabilities for electronics applications. The commercialization of scalable bio-based IBOA production warrants ongoing watch as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Addresses supply chain concentration risk and serves growing electronics demand in new hubs. |
| Bio-based Feedstock Development | Aligns with sustainability goals and reduces reliance on volatile petrochemical inputs. |
| High-Purity Grade Specialization | Meets stringent requirements for advanced electronics and optical film applications. |
| Strategic Partnerships for 3D Printing | Expands market reach into rapidly growing additive manufacturing applications. |
| Enhanced Regulatory Compliance Expertise | Navigates complex global chemical registration requirements, ensuring market access. |
Research Approach
Customs and trade data, industry association reports, and company financial filings formed the secondary backbone for this analysis. This was combined with primary interviews with R&D directors, procurement leads in automotive and electronics, and regulatory affairs specialists. The study employed both bottom-up and top-down triangulation to validate market size and growth figures.
An integrated bottom-up and top-down approach defined the forecast framework across the analysis window. The model segmented the market by grade tier, end-use industry, application, and regional production hub. Compound annual growth rates were derived through regression analysis and expert consensus, factoring in crude oil price trends and regional VOC emission targets.
Caveats apply where geopolitical events, feedstock price shocks, or new substitute technologies could materially shift the outlook. Forecasts reflect assumptions documented through extensive primary and secondary research. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
Australia Adhesives Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
Tile Adhesive Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Structural Sealants Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Global Underfill Material Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
Correction Fluid and Tape Market
Adhesives & Sealants
Paper-Backing Abrasive Adhesive Discs Market