
 Tile Adhesive Market | 2026-2036
Tile Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Tile Adhesive Market Outlook
Commercial contractors are redrawing demand patterns as large-format tile specifications displace traditional ceramic formats in hospitality and retail fit-outs. Mapei S.p.A leverages its vertically integrated pigment and polymer operations to sustain margin control across thin-set and medium-bed product lines. Sika AG anchors its position through cement-based technology leadership in European infrastructure restoration, while Pidilite Industries dominates India's contractor channel with localized formulation labs in Gujarat and Maharashtra.
Tile adhesive comprises a polymer-modified cementitious or resin-based bonding compound engineered to secure ceramic, porcelain, and natural stone tiles to substrates, with open times typically ranging from twenty to thirty minutes and shear adhesion strengths exceeding one megapascal per EN 12004 classification. The compound functions primarily to distribute load, accommodate substrate movement, and prevent delamination under thermal and moisture cycling. Cement-based technology leads volume globally due to cost parity with conventional mortar, though epoxy adhesives command premium positioning in industrial chemical-exposure environments. Water-based formulations represent the fastest-growing technology segment as regulatory pressure on solvent emissions intensifies across North American and European manufacturing jurisdictions. Thin-set adhesives occupy the mature core of the product-type matrix, while medium-bed formulations capture expanding share as tile dimensions exceed sixty centimeters and lippage tolerance tightens.
EPA VOC regulations and REACH chemical authorization requirements in Europe are reshaping formulation chemistry, compelling manufacturers to phase out solvent-based carriers in favor of aqueous polymer dispersions. India's BIS certification mandates and China's GB standards for construction adhesives further fragment compliance architectures, raising barriers for unqualified suppliers. Stakeholders must monitor evolving substrate preparation protocols and polymer raw-material availability as specification-grade projects increasingly require extended open-time performance guarantees.
Market Dynamics
Large-format tile specifications are compressing contractor procurement cycles and forcing reformulation across adhesive chemistry as substrate preparation standards tighten for porcelain panels exceeding 120 centimeters.
Growth Catalysts
- EPA VOC limits:Federal emission caps on solvent-based carriers are accelerating water-based polymer dispersion adoption across North American manufacturing bases, expanding addressable project pools in LEED-certified commercial construction.
- India's western states:Maharashtra and Gujarat floor-area expansion rates are outpacing national averages, concentrating demand for cement-based thin-set and medium-bed formulations in high-rise residential towers.
- Polymer modification:Ethylene vinyl acetate and styrene-butadiene latex advances are extending open times beyond thirty minutes, enabling single-worker installation of rectified porcelain in hospitality fit-outs.
Market Restraints
- Portland cement volatility:Clinker energy costs and carbon border adjustments are compressing margins on commodity-grade cementitious adhesives, particularly for European exporters.
- Epoxy resin concentration:Bisphenol-A supply chain bottlenecks in Northeast Asian petrochemical hubs are constraining premium industrial-grade adhesive availability for chemical-exposure environments.
- Substrate compatibility limits:Existing cement-based chemistry fails on gypsum board and existing vinyl surfaces without specialized primers, fragmenting specification-grade project workflows.
Strategic Opportunities
- China's coastal provinces:Guangdong and Jiangsu urban renewal programs are mandating tile-over-tile renovation adhesives, opening retrofit application segments distinct from new construction.
- EU Green Deal embodied carbon tracking:Construction product environmental performance declarations are creating preference premiums for low-carbon cement substitutes in public procurement.
- Prefabricated bathroom units:Offsite manufacturing integration of tile-adhesive bonding stations is compressing on-site labor requirements for modular hotel and hospital construction.
Industry Challenges
- EN 12004 certification timelines:Extended shear adhesion and open-time testing protocols are delaying product launches by eight to fourteen months for reformulated aqueous systems.
- Substrate movement accommodation:Thermal expansion coefficient mismatches between large-format porcelain and concrete slabs are driving callback rates and warranty claims in exterior facade applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tile Adhesive Market |
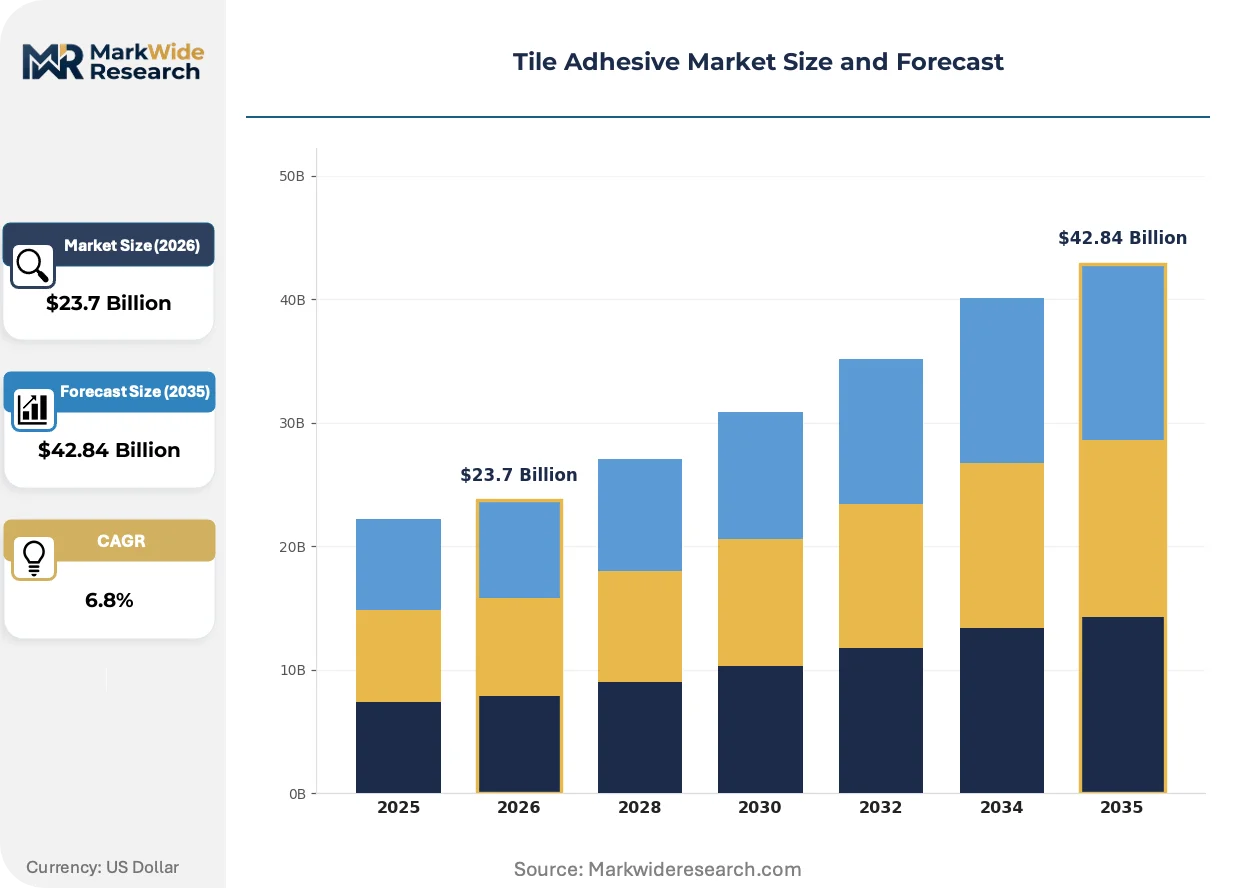
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Interior Walls, Exterior Walls, Floors, Ceilings Product Type: Thin-set Adhesives, Medium-bed Adhesives, Epoxy Adhesives, Mastic Adhesives End User: Residential, Commercial, Industrial, DIY Technology: Water-based, Solvent-based, Polyurethane, Cement-based |
| Companies Covered | Mapei S.p.A, Arkema, BASF SE, Pidilite Industries, H.B. Fuller Company, Henkel AG & Co. KGaA, AkzoNobel N.V., Ardex Group, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tile Adhesive Market Strategic Shifts
Adhesive chemistry is converging with substrate preparation automation and digital specification tools, compressing the traditional separation between material selection and installation methodology.
Hybrid cement-polymer formulations are miniaturizing the performance gap between economy-grade thin-sets and premium medium-bed systems. Commercial contractors in US hospitality and retail fit-outs are adopting these intermediate products at accelerated pace. This convergence is miniaturizing the SKU complexity that distributors must stock while maintaining specification compliance across project tiers.
REACH chemical authorization requirements are forcing phase-outs of specific isocyanate hardeners in reactive resin adhesives. European manufacturers are reformulating with silane-terminated polyurethane alternatives at accelerated R&D spend. Industrial flooring contractors in Germany and Benelux are absorbing premium pricing for compliant systems to maintain project eligibility under public tender rules.
Specification-grade buyers are consolidating adhesive selection authority within centralized procurement functions, displacing traditional field-level purchasing discretion. Large commercial contractors in India's western states are mandating pre-approved manufacturer lists for all projects exceeding 10,000 square meters. This concentration is most visible in Mumbai and Ahmedabad luxury residential developments where developer-brand relationships override subcontractor preferences.
Tile Adhesive Market Segmentation
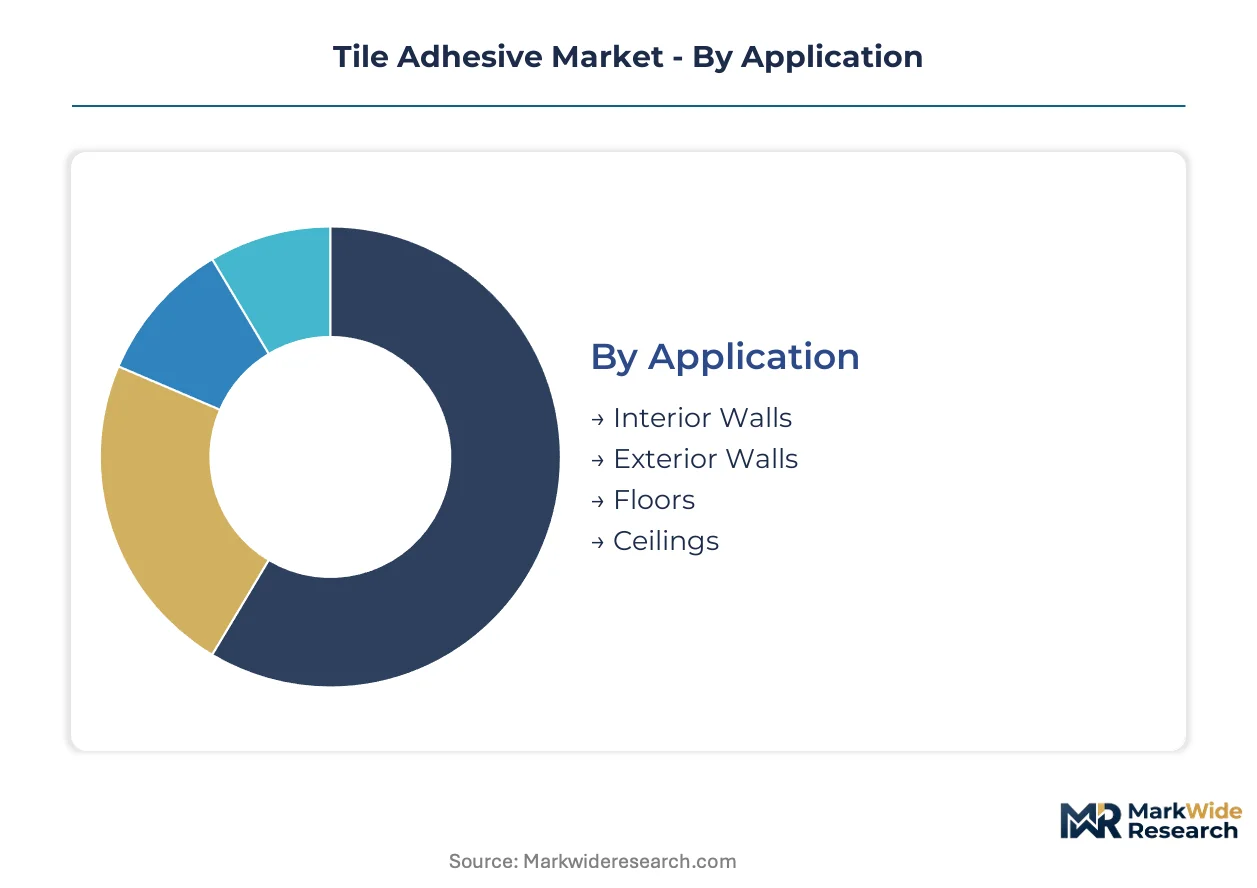
Tile adhesive procurement fragments across substrate demands, installation constraints, and regulatory exposure. Specification-grade buyers prioritize chemistry compatibility over unit cost when porcelain formats exceed 60 centimeters. Understanding segment substitution pressures reveals where formulation innovation unlocks pricing power versus commodity compression.
Application:
Interior wall applications face the strongest substitution threat from peel-and-stick membrane systems in residential renovation, while floor and exterior segments defend adhesive incumbency through load-bearing and weathering requirements that tapes cannot satisfy.
- Floors:Cement-based thin-set and medium-bed formulations dominate due to shear strength requirements under point loads. Demand concentrates in India's western states and China's coastal provinces where high-rise residential towers specify rectified porcelain for common areas. Thermal cycling resistance separates specification-grade products from economy alternatives in underfloor heating installations.
- Exterior Walls:Polymer-modified cementitious systems with enhanced flexibility accommodate thermal expansion differentials between large-format porcelain and concrete substrates. Façade applications in European commercial construction require EN 12004 C2 classification minimum, compressing unqualified supplier participation. Wind load and freeze-thaw exposure drive premium chemistry adoption.
- Interior Walls:Standard thin-set adhesives serve ceramic and porcelain formats in residential bathrooms and kitchens. DIY channel growth in North American home improvement retail favors pre-mixed paste formats over powder systems requiring on-site water addition.
- Ceilings:Specialized non-sag formulations with thixotropic additives prevent tile slippage on overhead substrates. Limited volume concentrates in commercial hospitality and healthcare fit-outs where maintenance access dictates hard-surface finishes over suspended ceilings.
Floors retain volume leadership across all geographies; exterior walls hold the steepest expansion curve as ventilated façade systems gain specification share.
Product Type:
Cost tier stratification separates specification-grade projects demanding extended open times and deformability from economy residential applications where powder thin-sets suffice.
- Thin-set Adhesives:Powder cementitious systems modified with EVA or SBR latex dominate global volume through cost parity with site-mixed mortar. India's contractor channel specifies these for standard ceramic formats in mass residential construction. BIS certification requirements fragment supplier eligibility in Maharashtra and Gujarat procurement.
- Medium-bed Adhesives:Thicker-bed formulations with enhanced non-slump characteristics accommodate large-format tiles exceeding 120 centimeters while maintaining lippage tolerance. US hospitality and retail fit-outs specify these for rectified porcelain installation by single workers. Premium pricing reflects extended open times beyond 30 minutes.
- Epoxy Adhesives:Two-component reactive resin systems command industrial flooring and chemical-exposure environments through superior chemical resistance and bond strength. REACH authorization constraints on isocyanate hardeners are forcing silane-terminated polyurethane reformulation in European manufacturing.
- Mastic Adhesives:Pre-mixed organic formulations serve light-duty residential wall applications where moisture exposure is minimal. EPA VOC limits are compressing solvent-based carrier formulations in favor of water-based acrylic alternatives.
Thin-set adhesives retain volume leadership; medium-bed formulations are gaining share fastest as tile dimensions expand across commercial specification.
End User:
Customer type determines procurement authority concentration, with commercial contractors consolidating manufacturer pre-approval lists while residential channels fragment across retail and professional installer segments.
- Commercial:Large-format specifications in hospitality, retail, and healthcare drive medium-bed and epoxy adoption. Centralized procurement functions in India's luxury residential developers override subcontractor preferences for projects exceeding 10,000 square meters. LEED certification requirements in North American commercial construction favor water-based low-VOC formulations.
- Residential:Professional installer channels favor powder thin-sets for cost efficiency in standard ceramic applications. DIY segment growth in North American home improvement retail accelerates pre-mixed and ready-to-use paste demand despite unit cost premiums.
- Industrial:Chemical processing, food and beverage, and pharmaceutical facilities specify epoxy systems for resistance to aggressive cleaning agents and thermal shock. Bisphenol-A supply constraints in Northeast Asian petrochemical hubs are limiting premium system availability.
- DIY:Convenience-oriented consumers in developed markets select pre-mixed mastic and organic adhesives for small-scale bathroom and kitchen renovation. Shelf stability and application forgiveness outweigh performance specifications in purchase decisions.
Commercial end users retain volume leadership; industrial applications are climbing the fastest as chemical-exposure specifications tighten across food safety and pharmaceutical manufacturing.
Technology:
Regulatory pressure on solvent emissions is accelerating chemistry transition timelines, with water-based systems displacing incumbent formulations faster than raw material cost optimization would dictate.
- Cement-based:Portland cement and calcium aluminate formulations modified with redispersible polymer powders dominate global volume through substrate compatibility and cost structure. Clinker energy costs and EU carbon border adjustments are compressing margins on commodity-grade exports.
- Water-based:Aqueous polymer dispersions of EVA, acrylic, and SBR latex represent the fastest-growing technology segment. EPA VOC limits and REACH chemical authorization are mandating formulation shifts across North American and European manufacturing bases.
- Solvent-based:Organic carrier systems face phased phase-out under federal emission caps, with remaining demand concentrating in specialized industrial applications where water incompatibility persists. Reformulation costs and EN 12004 recertification timelines delay product launches.
- Polyurethane:Silane-terminated and moisture-cure systems capture industrial flooring and exterior façade applications requiring high elongation and crack-bridging. Isocyanate hardener restrictions under REACH are accelerating silane-terminated alternatives in German and Benelux manufacturing.
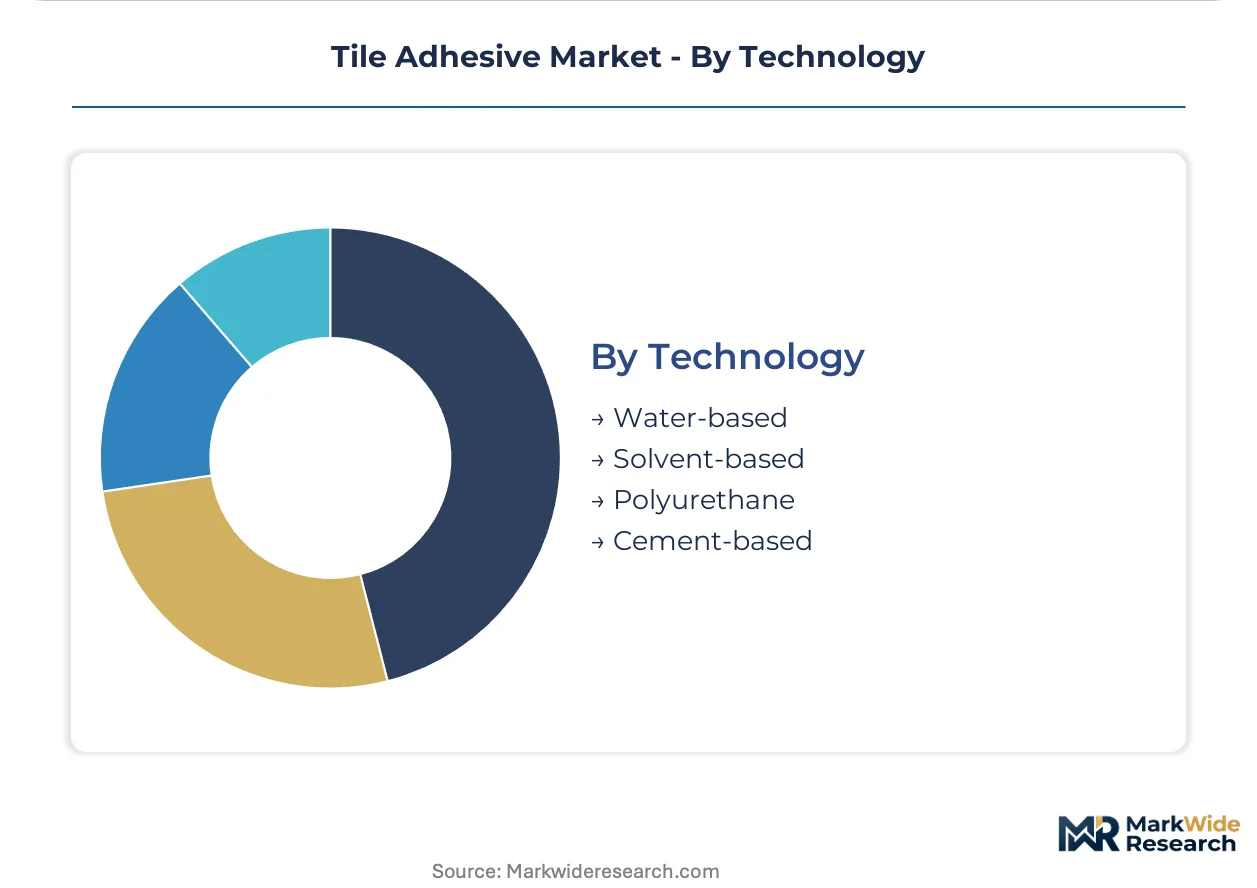
Cement-based technology retains volume leadership; water-based formulations are expanding most quickly as regulatory compliance becomes non-negotiable in specification-grade procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export cementitious formulations to Middle Eastern infrastructure contractors, while Chinese coastal producers supply water-based polymer systems to Southeast Asian retail channels.
United States
Commercial hospitality fit-outs in Florida and Texas drive medium-bed adhesive consumption for large-format porcelain. EPA VOC emission caps under the Clean Air Act accelerate water-based polymer dispersion adoption across manufacturing bases in Georgia and Ohio. Atlanta contractors specify extended open-time products for single-worker installation of rectified tiles.
Germany
Industrial flooring restoration in the Ruhr region and commercial façade renovation in Berlin sustain epoxy and polyurethane demand. REACH chemical authorization requirements force silane-terminated polyurethane reformulation, eliminating isocyanate hardeners from reactive resin adhesives. Cologne-Bonn manufacturing clusters supply compliant systems to Benelux public tenders.
China
Urban renewal programs in Guangdong and Jiangsu provinces mandate tile-over-tile renovation adhesives for retrofit applications. GB standards for construction adhesives fragment compliance architectures, raising barriers for unqualified suppliers. Shenzhen and Shanghai manufacturers concentrate water-based formulation capacity for coastal province distribution.
India
High-rise residential towers in Maharashtra and Gujarat specify cement-based thin-set and medium-bed formulations for common area flooring. BIS certification mandates restrict supplier eligibility in western state procurement channels. Mumbai and Ahmedabad luxury developers consolidate pre-approved manufacturer lists for projects exceeding 10,000 square meters.
United Arab Emirates
Hospitality and retail fit-outs in Dubai and Abu Dhabi import European medium-bed systems for large-format specification compliance. Local regulators align with Gulf Standardization Organization requirements for construction chemical imports. Jebel Ali logistics corridors distribute imported adhesives to Saudi Arabian and Qatari contractor channels.
Tile Adhesive Market Competitive Environment
Listed leaders compete with private specialists across formulation chemistry and geographic reach. The vendor base concentrates around cementitious technology leaders, polymer modification specialists, and regional distribution consolidators. Three archetypes dominate: vertically integrated chemical conglomerates, construction-focused adhesive pure-plays, and regional formulation laboratories serving contractor channels. Capacity expansion in water-based manufacturing and strategic partnerships for raw-material security represent the dominant competitive vectors.
Within the construction-focused tier, Mapei S.p.A and Sika AG exemplify European adhesive pure-plays with cementitious technology leadership. Pidilite Industries occupies a position as an India-based specialist with localized formulation infrastructure. These three anchors represent distinct geographic and technology positioning archetypes without overlapping core market footprints.
| Leading Market Players |
|---|
| Mapei S.p.A |
| Arkema |
| BASF SE |
| Pidilite Industries |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| AkzoNobel N.V. |
| Ardex Group |
| Sika AG |
| Others |
Value Chain & Pricing Dynamics
Water-based polymer dispersion substitution for solvent-based carriers redistributes manufacturing capacity toward coastal chemical clusters and compresses pricing premiums historically commanded by compliant European imports. This chemistry migration simultaneously elevates logistics costs for inland project sites and fragments procurement authority between distributor networks and direct manufacturer relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates specification-grade medium-bed systems from commodity thin-sets and DIY pre-mixed pastes. Certification grade under EN 12004 and BIS mandates, alongside volume scale for projects exceeding 10,000 square meters, drive price differentiation between tiers. Cost compression in cement-based commodity grades is intensifying because clinker energy costs and carbon border adjustments squeeze European exporter margins. Residential DIY channels exhibit highest price sensitivity, while commercial contractors with centralized procurement functions absorb premium pricing for extended open-time guarantees.
Supply Chain Analysis
Inbound logistics costs from Northeast Asian petrochemical hubs through congested container lanes elevate landed costs for epoxy resin and specialty polymer modifiers. Manufacturing concentrates in China, India, and Germany, with raw material dependencies on Portland cement clinker, ethylene vinyl acetate latex, and bisphenol-A feedstocks. Single-source vulnerability in isocyanate hardener supply chains exposes European formulators to REACH-mandated reformulation delays. Distribution runs through regional distributor networks serving contractor channels, with direct manufacturer relationships penetrating large commercial accounts in luxury residential developments.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Large-format tile specification penetration in commercial construction sits at early-cycle expansion, with rectified porcelain exceeding 120 centimeters capturing specification share faster than substrate preparation standards can standardize. Water-based formulation mandates across North American and European jurisdictions accelerate chemistry transition timelines beyond raw-material cost optimization alone would dictate.
For Market Incumbents: Shield specification-grade positioning by securing captive supply of redispersible polymer powders and silane-terminated polyurethane alternatives before REACH authorization constraints harden. Backward integration into EVA and SBR latex production defends margin control against petrochemical feedstock volatility. Prioritize BIS certification maintenance in Maharashtra and Gujarat procurement channels where developer pre-approved manufacturer lists are consolidating.
For New Entrants and Emerging Players: Differentiate on water-based formulation speed-to-market for EPA-compliant commercial construction segments where incumbent recertification timelines lag. Target India's western state contractor channels with localized formulation labs bypassing established distributor relationships. Pursue tile-over-tile renovation adhesive positioning in China's coastal province urban renewal programs as a distinct application segment from new construction specifications.
For Investors and Strategic Acquirers: EU Green Deal embodied carbon tracking reshapes the acquisition landscape toward low-carbon cement substitute technologies eligible for public procurement preference premiums. Five-to-ten year viability favors manufacturers with vertically integrated pigment and polymer operations capable of margin control across thin-set and medium-bed product lines. Monitor EN 12004 certification backlog durations as an inflection indicator for reformulated aqueous system launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Manufacturing Capacity Expansion | EPA VOC compliance unlocks LEED-certified commercial project eligibility in Georgia and Ohio manufacturing bases. |
| Backward Integration into Polymer Modification | In-house EVA and SBR latex production insulates margin control from Northeast Asian petrochemical hub volatility. |
| Localized Formulation Laboratory Network | Gujarat and Maharashtra labs capture contractor channel preference in India's western state high-rise residential towers. |
| Silane-Terminated Polyurethane Reformulation | REACH-compliant systems maintain project eligibility under Benelux and German public tender rules. |
| Tile-Over-Tile Renovation Adhesive Development | Guangdong and Jiangsu urban renewal programs open retrofit application segments distinct from new construction. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with commercial contractors, formulation chemists, and distributor procurement managers; and secondary validation through customs trade data, construction chemical association reports, and SEC filings from listed manufacturers. Plant managers at cementitious adhesive facilities, technical R&D directors at polymer modification specialists, and channel partners serving hospitality fit-out contractors provided operational perspective. Bottom-up volume triangulation across application segments and top-down value reconciliation against disclosed revenue ranges anchored the market sizing framework.
Across the analysis window, projections incorporate chemistry transition timelines, regulatory compliance deadlines, and substrate preparation protocol evolution as independent variables. Segmentation dimensions span product type, application substrate, end-user procurement authority, and technology chemistry class. CAGRs derive from weighted average of segment-specific growth trajectories, with large-format tile specification penetration and water-based formulation adoption curves as primary demand-side inputs. Clinker energy cost indices and polymer raw material availability constraints feed supply-side boundary conditions.
Material uncertainties — Portland cement volatility, REACH authorization delays for isocyanate alternatives, and substrate movement accommodation failures in exterior façade applications — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement consistency and specification-grade project flow continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Epoxy Adhesive Market
Adhesives & Sealants
Temporary Bonding Adhesives Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Adhesives Market
Adhesives & Sealants
United States Construction Adhesives and Sealants Market
Adhesives & Sealants
Melamine Based Adhesives Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Indonesia Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Urea-Formaldehyde Glues and Resins Market
Adhesives & Sealants
North America Epoxy Curing Agents Market
Adhesives & Sealants
Europe Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Acrylic Glue Market
Adhesives & Sealants
Global Human Fibrin Glue Market
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
Epoxy Curing Agents Market
Adhesives & Sealants
Co-Polymer Sealants Market