
 Protein Purification Resin Market | 2026-2036
Protein Purification Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Purification Resin Market Analytics
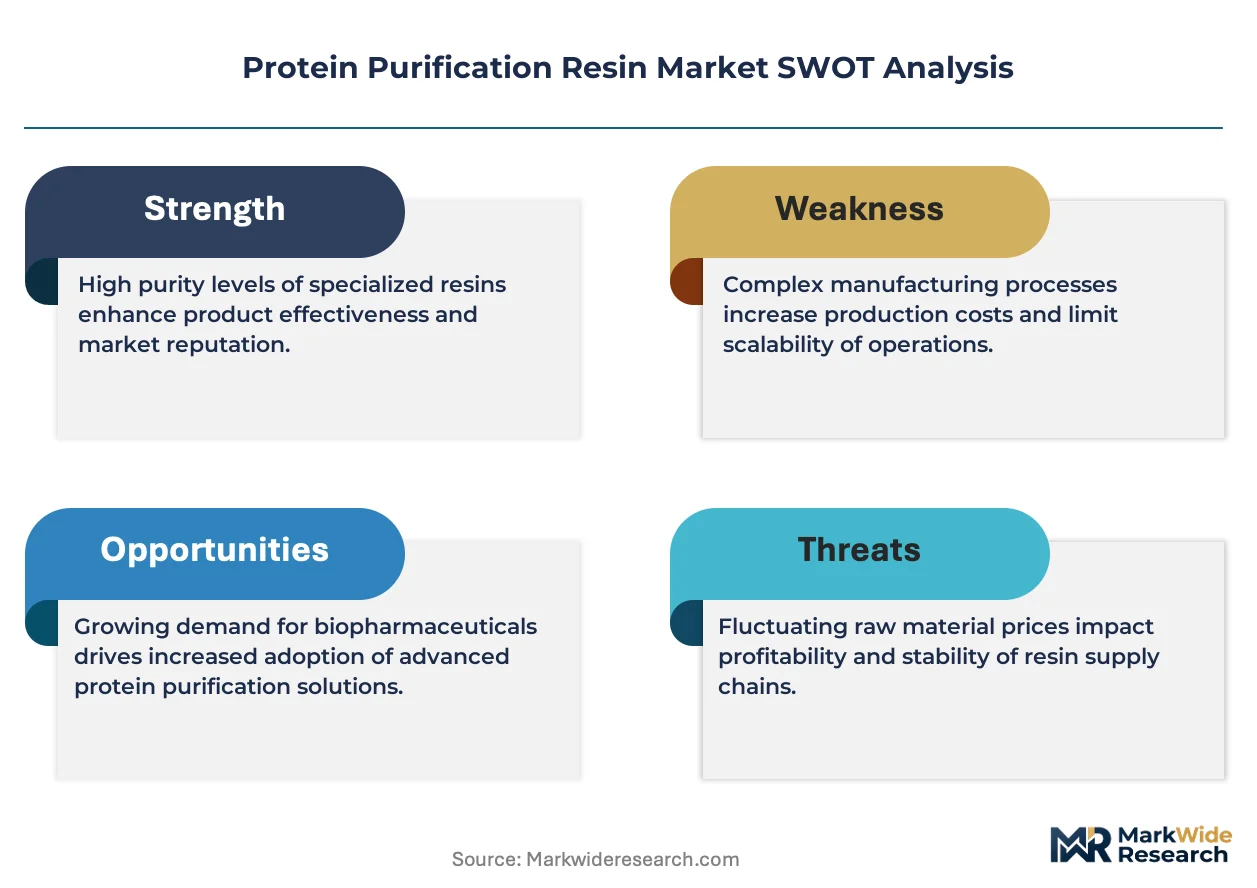
Pharmaceutical-grade resin specifications is rotating toward higher binding capacity and lower leachable profiles. Merck KGaA leverages its integrated chromatography platform to control supply chains from raw material to validated columns. Danaher Corporation anchors its position through Pall Life Sciences filtration and purification technologies. Repligen Corporation specializes in protein A affinity ligands that dominate mAb capture steps.
Protein purification resin comprises porous polymeric or inorganic matrices functionalized with ligands that selectively bind target proteins from complex biological mixtures, with typical particle sizes ranging from 30 to 100 micrometers and pore structures engineered for specific molecular weight ranges. These materials enable downstream bioprocessing by separating impurities from therapeutic proteins, vaccines, and diagnostic reagents at manufacturing scale. Affinity resin commands the largest value share due to protein A ligand dominance in monoclonal antibody workflows, while mixed-mode resin represents the fastest-expanding category as manufacturers seek to reduce column count and buffer consumption in multi-step purification trains. Pre-packed columns are gaining share over bulk resin among contract manufacturing organizations prioritizing operational consistency and reduced validation burden.
FDA enforces current Good Manufacturing Practice requirements for resin reproducibility and extractable profiles in biologics manufacturing, while EMA's Guideline on Process Validation mandates documented resin lifetime studies for marketing authorization. China's NMPA aligns with ICH Q5A-Q5D standards for viral clearance validation, creating compliance complexity for multinational suppliers. ISO 13485 certification and USP <129> analytical procedures further shape product qualification protocols across jurisdictions. Stakeholders must monitor evolving regulatory harmonization between FDA process analytical technology initiatives and EMA's quality-by-design expectations for continuous bioprocessing adoption.
Market Dynamics
Biopharmaceutical manufacturers are consolidating purification steps to reduce facility footprint and buffer consumption, compressing demand for single-purpose resins while elevating mixed-mode and multimodal chemistries that combine ion exchange with hydrophobic interaction mechanisms.
Growth Catalysts
- FDA Process Analytical Technology:The initiative mandates real-time release testing, forcing manufacturers to adopt resins with consistent lot-to-lot performance and validated lifetime studies.
- Continuous bioprocessing:Perfusion cell culture systems generate higher cell densities, requiring resins with elevated binding capacity and faster mass transfer kinetics to handle concentrated feed streams.
- China biologics manufacturing expansion:NMPA alignment with ICH viral clearance standards is driving domestic facility construction and resin qualification programs across Shanghai and Suzhou industrial clusters.
Market Restraints
- Protein A ligand supply concentration:Natural ligand sourcing depends on limited fermentation capacity in Denmark and South Korea, creating bottleneck risk for affinity resin production.
- EMA extractable/leachable thresholds:Tightening guidelines on organic compound release from polymer matrices extend validation timelines and disqualify legacy resin formats.
- Single-use substitution:Pre-packed disposable columns reduce bulk resin volume demand among contract manufacturing organizations prioritizing operational flexibility over unit cost.
Strategic Opportunities
- India CDMO expansion:CDSCO streamlined biologics approval pathways and PLI scheme incentives are attracting multinational purification technology transfers to Hyderabad and Bangalore.
- Gene therapy vectors:AAV and lentiviral purification workflows require novel affinity ligands beyond protein A, opening white space for synthetic peptide and nanobody resin development.
- ISO 13485 certification arbitrage:Diagnostic-grade resin qualification protocols are converging with pharmaceutical standards, enabling suppliers to serve dual end-use markets with single manufacturing lines.
Industry Challenges
- Chromatography modeling expertise:Mechanistic simulation tools for resin screening and process optimization require specialized biochemical engineers in short supply across contract manufacturing organizations.
- Resin lifetime validation burden:FDA current Good Manufacturing Practice requirements for documented cleaning and reuse cycles demand extensive stability data generation before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Purification Resin Market |
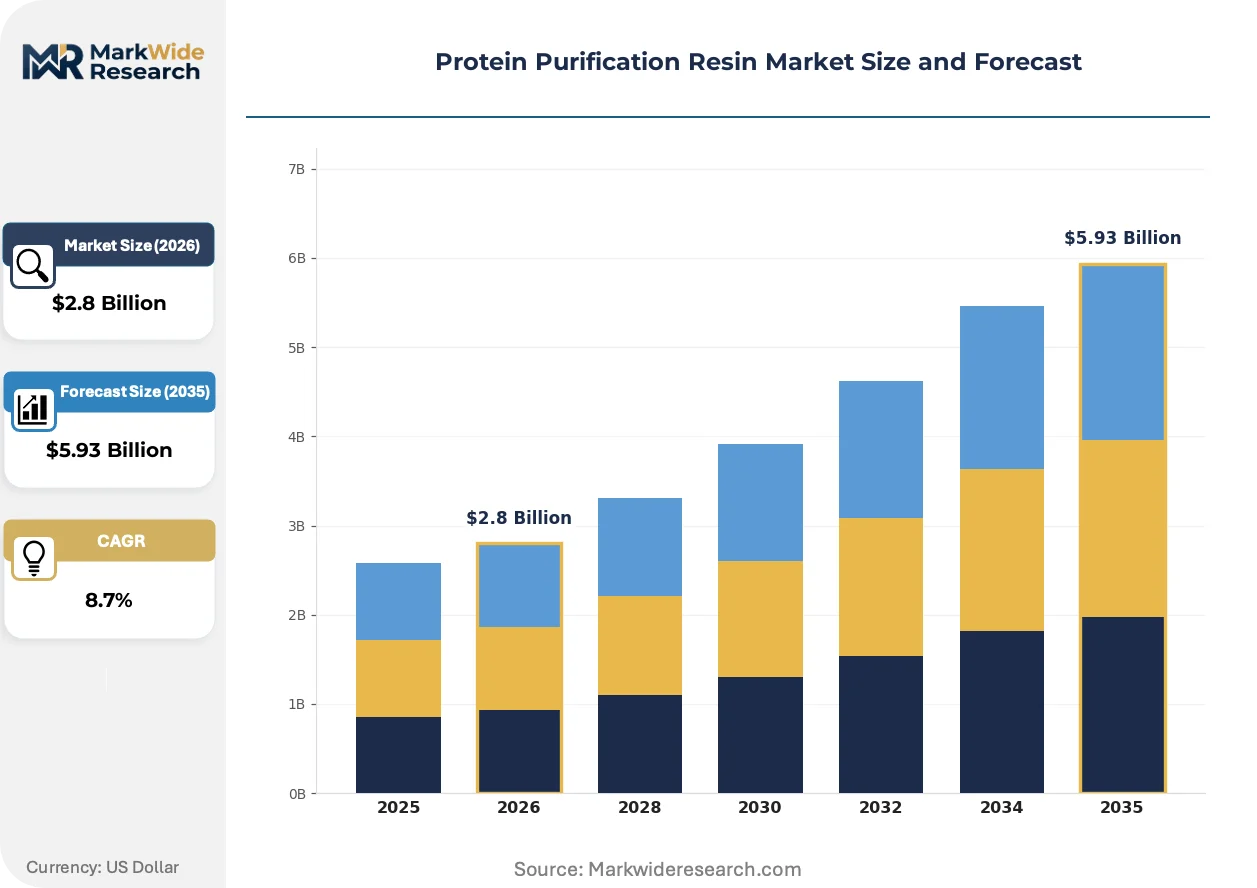
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Affinity Resin, Ion Exchange Resin, Gel Filtration Resin, Mixed-Mode Resin End User: Biotechnology Companies, Pharmaceutical Firms, Research Laboratories, Academic Institutions Application: Protein Analysis, Vaccine Development, Monoclonal Antibody Production, Research and Development Form: Bulk Resin, Pre-Packed Columns, Disposable Kits, Custom Solutions |
| Companies Covered | Merck KGaA, Bio-Rad Laboratories, Danaher Corporation, Tosoh Bioscience, Agilent Technologies, Repligen Corporation, Purolite, GenScript, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Purification Resin Market Evolving Landscape
Continuous manufacturing architectures are collapsing traditional batch purification trains, forcing resin suppliers to engineer materials compatible with integrated flow paths and automated control systems rather than discrete unit operations.
Multimodal resin chemistries combining charged and hydrophobic ligands on a single bead are supplanting sequential ion exchange and hydrophobic interaction chromatography steps in monoclonal antibody workflows. Biopharmaceutical manufacturers in Germany and Switzerland are adopting these formats to halve column footprint and buffer volume. The consolidation is compressing demand for single-mechanism resins while elevating suppliers with integrated multimodal platforms.
EMA's Guideline on Process Validation now explicitly addresses continuous bioprocessing submissions, requiring resin suppliers to demonstrate performance across variable flow rates and loading densities. European manufacturers are responding with enhanced regulatory affairs capabilities and documented viral clearance studies aligned with ICH Q5A-Q5D. The policy shift is accelerating qualification timelines for resins validated specifically for continuous capture operations.
Contract development and manufacturing organizations are unbundling resin supply from equipment procurement, negotiating direct resin contracts separate from chromatography system vendors. This disintermediation is most visible in the United States, where large CDMOs maintain qualified supplier lists spanning multiple resin chemistries and formats. The pattern is forcing resin manufacturers to build dedicated technical service teams for direct customer support rather than relying on equipment OEM channels.
Protein Purification Resin Market Segmentation
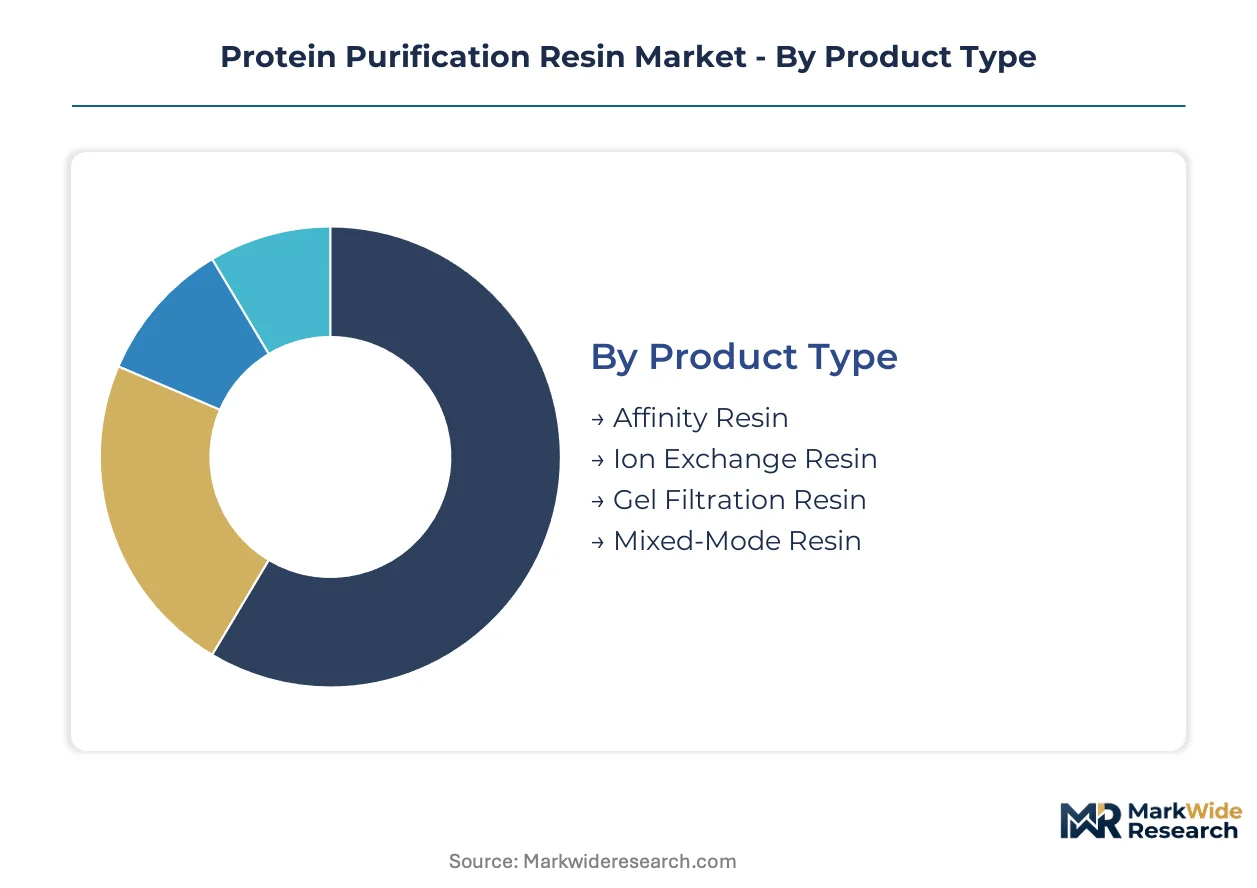
Resin suppliers must navigate divergent performance requirements across monoclonal antibody manufacturing, gene therapy workflows, and diagnostic applications. Each segment demands distinct binding kinetics, regulatory documentation, and supply chain configurations that reshape competitive positioning.
Product Type:
Mixed-mode chemistries face the most intense substitution pressure from multimodal alternatives that compress purification trains, while single-mechanism formats defend share through validated legacy processes.
- Affinity Resin:Protein A ligand matrices dominate monoclonal antibody capture with binding capacities exceeding 60 grams per liter. Demand concentrates among FDA-regulated biologics manufacturers in Massachusetts and North Carolina who require documented viral clearance studies.
- Mixed-Mode Resin:Combined ion exchange and hydrophobic interaction ligands reduce column count in downstream processing. German and Swiss manufacturers adopt these formats most aggressively to halve buffer consumption and facility footprint.
- Ion Exchange Resin:Cation and anion variants provide charge-based separation for intermediate polishing steps.
- Gel Filtration Resin:Size-exclusion matrices enable final polishing based on molecular weight differentiation.
Affinity resin anchors the volume base while mixed-mode resin gains share at the steepest rate.
End User:
Cost tier stratification separates high-volume biologics manufacturers from price-sensitive academic buyers who prioritize grant-funded procurement flexibility.
- Pharmaceutical Firms:Integrated biologics divisions operate captive purification suites with validated resin lifetime studies. These end-users in the United States and Germany drive demand for pre-packed columns with documented extractable profiles.
- Biotechnology Companies:Venture-backed developers outsource manufacturing to contract organizations while retaining early-stage process development in-house. Boston and San Francisco clusters prioritize resin platforms compatible with rapid technology transfers.
- Research Laboratories:Small-scale purification for analytical validation and method development.
- Academic Institutions:Grant-dependent procurement favoring bulk resin formats and open-source chromatography protocols.
Pharmaceutical firms generate the highest per-customer revenue while biotechnology companies expand most quickly through venture financing cycles.
Application:
Volume concentration in monoclonal antibody production creates margin pressure that propagates through supplier pricing negotiations.
- Monoclonal Antibody Production:Protein A capture followed by ion exchange and hydrophobic interaction polishing constitutes the industry standard workflow. Chinese facilities in Shanghai and Suzhou industrial clusters are scaling resin qualification programs to meet NMPA viral clearance requirements.
- Vaccine Development:Viral vector and subunit purification requires resin chemistries distinct from antibody workflows. EMA process validation guidelines mandate documented resin performance across variable loading densities for European manufacturing sites.
- Protein Analysis:Analytical-scale purification for characterization and quality control.
- Research and Development:Early-stage process development with emphasis on screening resin chemistries.
Monoclonal antibody production commands the dominant revenue share while vaccine development applications climb fastest on pandemic preparedness investment.
Form:
Customer type dictates format preference, with contract manufacturing organizations driving pre-packed adoption and academic buyers defending bulk resin procurement.
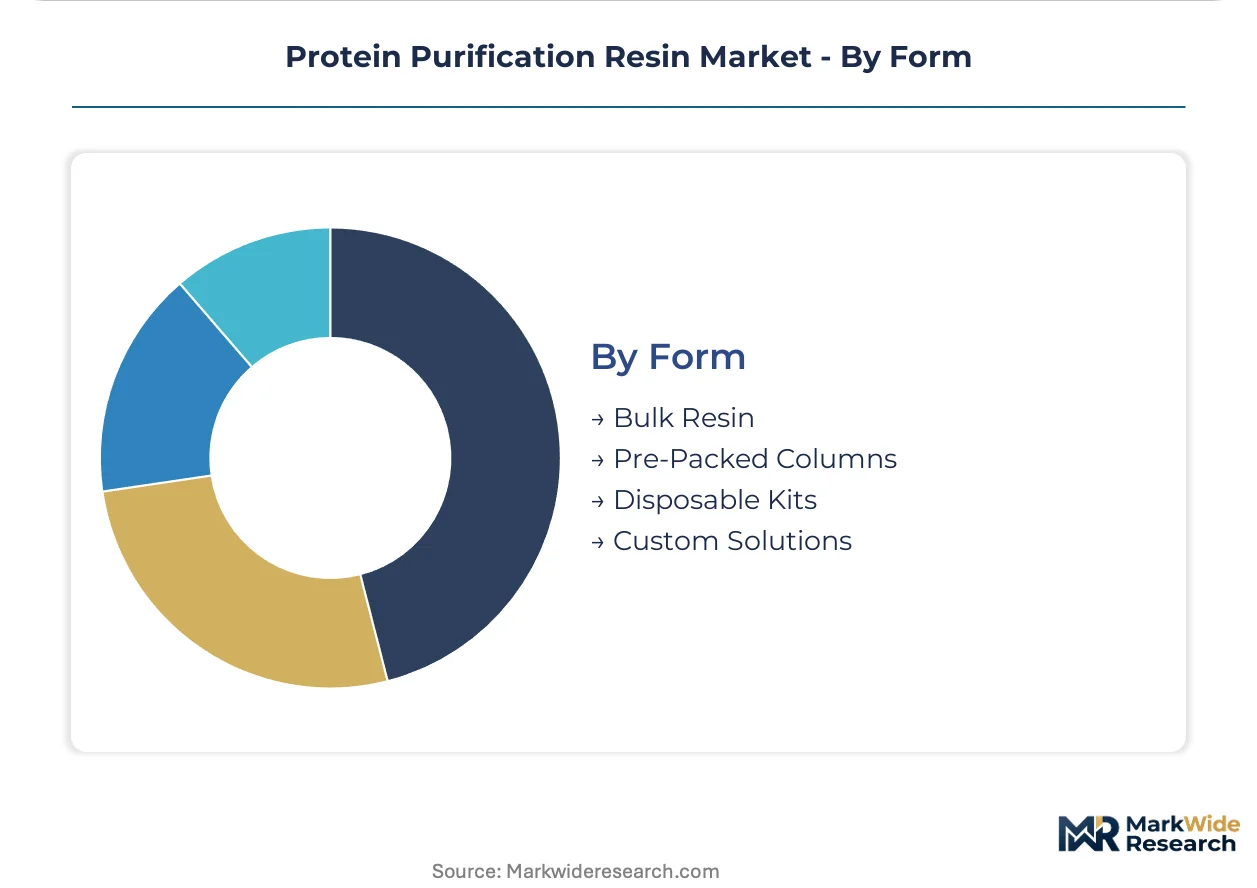
- Pre-Packed Columns:Validated, ready-to-use formats eliminate packing variability and reduce qualification burden. United States CDMOs negotiate direct resin contracts separate from chromatography system vendors to secure operational consistency.
- Bulk Resin:Unpacked matrices offer unit cost advantages for high-volume manufacturers with in-house packing expertise. Legacy biologics facilities in Germany and Switzerland maintain captive packing operations to optimize resin utilization rates.
- Disposable Kits:Single-use formats for clinical trial material production and campaign-based manufacturing.
- Custom Solutions:Ligand immobilization on proprietary matrices for specialized affinity purification requirements.
Bulk resin retains volume leadership among established manufacturers while pre-packed columns expand most rapidly through CDMO channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Resin supply chains concentrate in established biomanufacturing corridors where regulatory infrastructure and fermentation capacity co-locate. Three countries dominate installed base and new facility investment.
United States
FDA Process Analytical Technology mandates drive resin qualification intensity among Massachusetts and North Carolina biologics manufacturers. The agency's current Good Manufacturing Practice requirements for documented lifetime studies extend validation timelines. Greater Boston and Research Triangle Park clusters anchor captive purification suite expansion by integrated pharmaceutical divisions.
Germany
EMA's Guideline on Process Validation explicitly addresses continuous bioprocessing submissions, requiring variable flow rate performance documentation. German manufacturers adopt multimodal resin formats most aggressively to compress column footprint. Bavaria and Baden-Württemberg industrial zones concentrate legacy biologics facilities maintaining in-house packing operations.
China
NMPA alignment with ICH Q5A-Q5D viral clearance standards accelerates domestic resin qualification programs. The regulator's biologics manufacturing expansion policies concentrate investment in Shanghai and Suzhou industrial clusters. Domestic facility construction scales protein A affinity resin consumption for monoclonal antibody workflows.
Switzerland
Swissmedic pharmaceutical manufacturing standards exceed baseline EMA thresholds for extractable and leachable profiles. Swiss biopharmaceutical manufacturers prioritize pre-packed column formats to reduce operational variability. Basel and Zürich pharmaceutical corridors integrate resin supply into continuous manufacturing architectures.
India
CDSCO streamlined biologics approval pathways and PLI scheme incentives attract multinational purification technology transfers. The national pharmaceutical regulator's convergence with ICH standards reduces qualification friction for imported resin platforms. Hyderabad and Bangalore CDMO clusters negotiate direct resin contracts separate from chromatography system vendors.
Protein Purification Resin Market Competitive Landscape
Concentration sits with diversified life science conglomerates controlling integrated chromatography platforms from ligand fermentation through validated column supply. Three strategic archetypes populate the competitive set: diversified conglomerates with captive resin manufacturing, specialized affinity ligand developers, and regional bulk matrix suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as participants secure fermentation assets and viral clearance documentation.
Among diversified life science conglomerates, Merck KGaA, Danaher Corporation, and Thermo Fisher Scientific exemplify integrated platform control spanning raw material sourcing to regulatory documentation. Merck KGaA anchors German manufacturing infrastructure. Danaher Corporation occupies a position spanning filtration and purification technology convergence. Thermo Fisher Scientific represents North American scale advantages in analytical validation and customer technical service deployment.
| Leading Market Players |
|---|
| Merck KGaA |
| Bio-Rad Laboratories |
| Danaher Corporation |
| Tosoh Bioscience |
| Agilent Technologies |
| Repligen Corporation |
| Purolite |
| GenScript |
| Thermo Fisher Scientific |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty-day lead times for protein A ligand fermentation batches concentrate pricing power with Danish and South Korean suppliers who control the upstream biological production. This inventory compression forces biopharmaceutical manufacturers into long-term offtake contracts that lock in resin costs across multi-year purification campaigns, while spot-market exposure remains limited to bulk ion exchange matrices with commoditized chemistries.
Pricing Analysis
FDA current Good Manufacturing Practice dictates the pricing tier structure across pharmaceutical-grade resin markets. Three-tier pricing stratifies across validated pre-packed columns, qualified bulk resin, and research-grade unpackaged matrices. Price differentiation centers on viral clearance documentation depth and extractable profile certification. Pricing pressure intensifies in ion exchange categories where Chinese manufacturers expand fermentation capacity. Contract manufacturing organizations exhibit highest price sensitivity due to campaign-based procurement, while integrated biologics divisions prioritize performance consistency over unit cost.
Supply Chain Analysis
Strategic stockpiling of protein A ligand inventories dominates procurement strategy among Massachusetts and North Carolina biologics manufacturers seeking to buffer against fermentation batch variability. Supply concentrates in Denmark, South Korea, and Germany where biological production infrastructure and regulatory documentation capabilities co-locate. Raw material dependencies include recombinant protein fermentation media, agarose bead matrices, and synthetic polymer backbones. Single-source vulnerability in natural ligand production creates bottleneck exposure. Distribution runs through direct technical service relationships rather than equipment OEM channels as CDMOs disintermediate procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with specialized resin formats as gene therapy vector purification creates demand niches beyond established monoclonal antibody workflows. AAV and lentiviral applications require novel affinity ligands that incumbent protein A dominance does not address.
For Market Incumbents: Fortify ligand fermentation capacity through captive biological production investments in Denmark or South Korea to secure supply chain control against emerging synthetic peptide competitors. Deepen regulatory affairs capabilities for continuous bioprocessing validation documentation as EMA submission requirements tighten. Prioritize ISO 13485 certification arbitrage to serve diagnostic and pharmaceutical end-uses through unified manufacturing lines. For New Entrants and Emerging Players: CDSCO fast-track pathways for biologics manufacturing incentives in Hyderabad and Bangalore offer the most penetrable entry corridor. Target gene therapy vector purification workflows where protein A ligand incumbents lack established positioning. Pursue direct technical service team deployment to match CDMO procurement disintermediation patterns visible in United States contract negotiations. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because diversified life science conglomerates will absorb specialized affinity ligand developers to secure integrated platform control. Target acquisition archetypes include synthetic peptide resin specialists with viral clearance documentation and regional bulk matrix suppliers in India or China. Watch for NMPA domestic facility construction permits crossing threshold volumes as inflection signal for China demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Protein A Ligand Fermentation Capacity Expansion | Captive biological production in Denmark or South Korea secures supply chain control against synthetic peptide substitution threats. |
| Continuous Bioprocessing Regulatory Documentation Investment | EMA submission capabilities for variable flow rate performance accelerate qualification timelines for integrated capture operations. |
| Gene Therapy Vector Affinity Ligand Development | AAV and lentiviral purification workflows open white space beyond established monoclonal antibody resin dominance. |
| ISO 13485 Certification Arbitrage Execution | Unified manufacturing lines serve diagnostic and pharmaceutical end-uses with converging qualification protocols. |
| Direct CDMO Technical Service Team Deployment | Disintermediation from chromatography system vendors requires dedicated customer support capabilities in United States clusters. |
Research Methodology
Operator-level perspectives from downstream process development scientists, regulatory affairs managers at biologics manufacturers, and procurement leads at contract manufacturing organizations anchored the qualitative base. Secondary validation drew from FDA BLA submissions, EMA process validation guidelines, NMPA biologics manufacturing permits, and USP analytical procedure documentation. Bottom-up resin consumption estimates triangulated against top-down biologics capacity expansion announcements across Massachusetts, North Carolina, Bavaria, and Shanghai industrial clusters.
Sensitivity analysis tested binding capacity assumptions, viral clearance validation timelines, and continuous bioprocessing adoption curves across the projection horizon. Segmentation dimensions modeled include resin chemistry type, end-user integration level, application workflow, and geographic regulatory cluster. CAGRs derived from installed base expansion rates, facility construction pipelines, and per-unit consumption intensity trends. Forecast inputs incorporated protein A ligand fermentation batch yields and pre-packed column format penetration rates among CDMOs.
Decision-makers should treat outputs as directional under base assumptions of NMPA-ICH alignment maintenance and EMA continuous processing guideline stability; material deviation would warrant model refresh. Revision becomes warranted when gene therapy vector manufacturing capacity crosses clinical-to-commercial scale thresholds or when synthetic peptide ligand binding capacities approach protein A performance parity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Sodium Hyaluronate-Based Products Market
Specialty Chemicals
Halogen-Free Flame Retardants Market
Specialty Chemicals
Global Cyclodextrin Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Metominostrobin Market
Specialty Chemicals
Thermolysin Market
Specialty Chemicals
4-ADPA Market
Specialty Chemicals
Divinylbenzene (DVB) Market
Specialty Chemicals
Global Fabric Softener Sheet Market
Specialty Chemicals
Aerosol Cans Market
Specialty Chemicals
Global Flame Retardants Market
Specialty Chemicals
Enzyme Inhibitors Market
Specialty Chemicals
Europe Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Chemicals
Micronized PTFE Market
Specialty Chemicals
Polyglycerol Sebacate (PGS) Market