
 Global Acrylate Monomers Market | 2026-2036
Global Acrylate Monomers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acrylate Monomers Market Foresight
Modular formulation bundling is shifting how coating manufacturers procure acrylate monomers, with buyers now sourcing pre-optimized monomer packages rather than individual grades to reduce in-house blending complexity. BASF SE leverages its integrated C1 chemistry platform to sustain captive acrylic acid supply for downstream monomer production. Arkema anchors its position through specialty hydroxyethyl acrylate grades serving high-performance adhesives in European automotive assembly.
Acrylate monomers are ester derivatives of acrylic acid, typically polymerizing through free-radical mechanisms at temperatures between 60°C and 90°C to form thermoplastic or crosslinked resins with glass transition temperatures tunable from -50°C to +100°C depending on ester chain length. Butyl acrylate dominates volume demand as the backbone soft monomer in waterborne architectural coatings, while hydroxyethyl acrylate commands premium positioning in radiation-curable industrial finishes due to its hydroxyl functionality enabling urethane crosslinking. Methyl acrylate competes primarily in textile finishing applications where stiffness and abrasion resistance prove critical.
EPA oversight of VOC emissions under the Clean Air Act shapes formulation requirements for architectural coatings in the United States, while REACH registration and the EU Green Deal's chemical sustainability targets constrain monomer import and production standards across Europe. China's MEE enforces wastewater and air emission limits around acrylic acid production clusters in Jiangsu and Zhejiang provinces. Stakeholders must monitor regulatory divergence between jurisdictions to determine where regional formulation adaptation or standardized global product platforms offer superior returns.
Market Dynamics
Waterborne coating formulations are compressing formulation cycles and forcing acrylate monomer suppliers to deliver pre-optimized packages rather than commodity grades, restructuring procurement relationships across automotive refinishing and industrial maintenance sectors.
Growth Catalysts
- REACH compliance deadlines:EU Green Deal mandates for low-VOC acrylic systems are pulling reformulated monomer grades into European architectural coatings.
- Coastal chemical clustering:Jiangsu and Zhejiang province production hubs now supply derivative plants across Vietnam, Indonesia, and Thailand.
- Radiation-curable industrial finishes:Hydroxyethyl acrylate demand is accelerating from urethane crosslinking requirements in high-performance wood and metal coatings.
Market Restraints
- Propylene feedstock volatility:Acrylic acid production costs swing with naphtha-cracker margins and refinery operating rates.
- MEE emission enforcement:China's Ministry of Ecology and Environment wastewater limits constrain capacity expansion in Yangtze River Delta clusters.
- Waterborne system performance gaps:Solvent-borne alternatives retain adhesion and block resistance advantages in severe-service industrial applications.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic acrylic acid and ester production incentives could localize supply for South Asian coatings demand.
- Bio-based acrylic acid routes:Fermentation and glycerol-to-acrylic pathways are converging with conventional petrochemical production economics.
- Pre-optimized monomer bundling:Coating manufacturers are accepting formulation-ready packages that embed rheology modifiers and adhesion promoters.
Industry Challenges
- Free-radical polymerization expertise:Formulation chemists capable of tuning glass transition temperatures across -50°C to +100°C ranges remain scarce.
- Multi-jurisdiction registration timelines:REACH, EPA TSCA, and China's MEE notification requirements extend new grade commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acrylate Monomers Market |
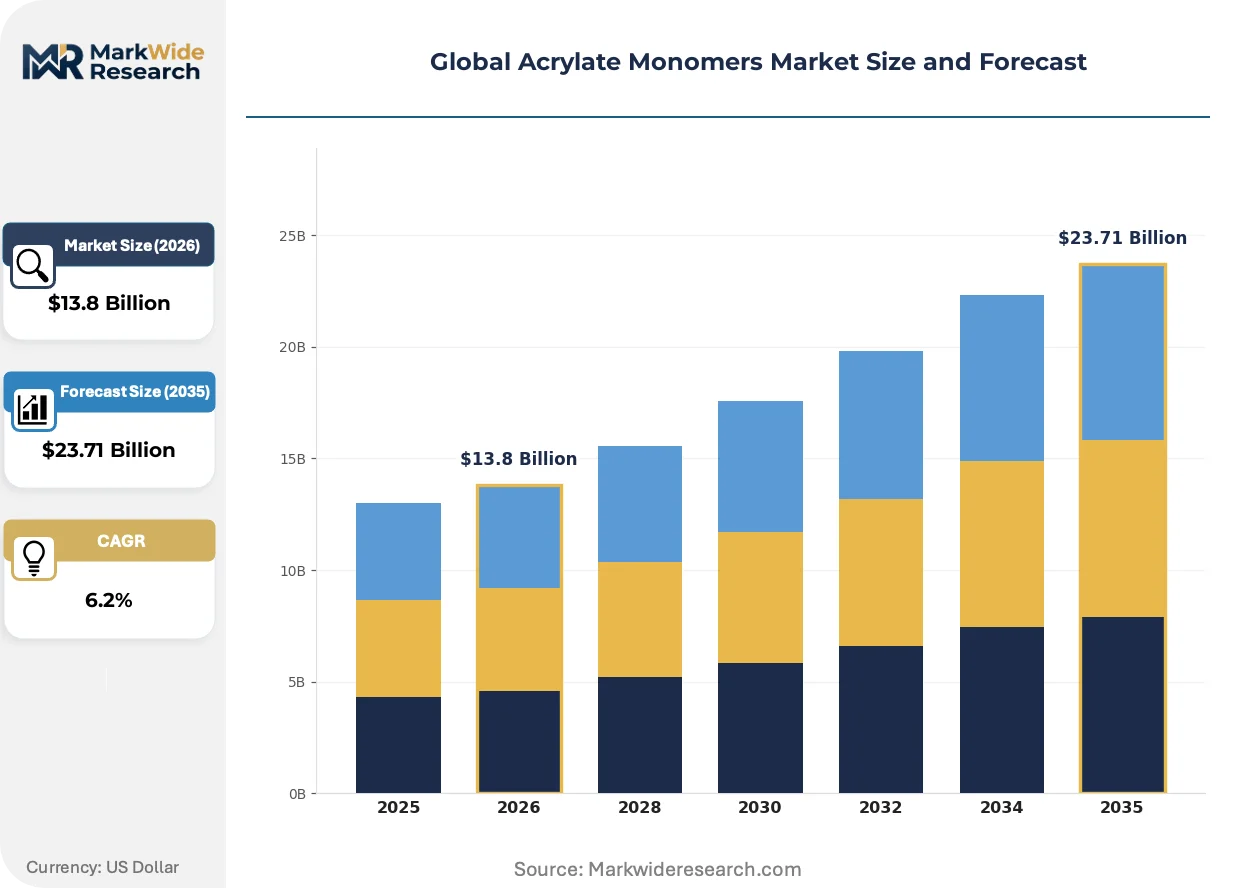
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $23.71 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methyl Acrylate, Ethyl Acrylate, Butyl Acrylate, 2-Ethylhexyl Acrylate, Hydroxyethyl Acrylate Application: Adhesives, Paints & Coatings, Textile Finishing, Plastics Modification, Sealants End User Industry: Construction, Packaging, Personal Care, Electronics, Agriculture Form: Liquid, Powder, Suspension, Emulsion |
| Companies Covered | BASF SE, Arkema, Dow, Evonik Industries AG, Nippon Shokubai Co., Ltd., LG Chem, Mitsubishi Chemical Group Corporation, SABIC, Formosa Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acrylate Monomers Market Shifts & Advancements
Formulation science is compressing the boundary between monomer synthesis and coating performance, with suppliers now embedding functionality deeper into raw material design rather than leaving optimization to downstream blenders.
Hybrid waterborne-UV curing systems are unifying the application convenience of aqueous delivery with the instant cure and hardness of radiation processing. Automotive assembly plants in Germany and tier suppliers in Guangdong are piloting these dual-cure clearcoats for interior trim. This convergence is unifying previously separate supply chains for thermal and energy-cured coating components.
EPA oversight under the Clean Air Act is tightening architectural coating VOC limits in ozone non-attainment zones across California and Texas. Reformulation to compliant acrylic systems is forcing raw material substitutions in maintenance and decorative segments. California's South Coast Air Quality Management District rules are driving the most aggressive monomer grade turnover.
Coating manufacturers are consolidating supplier relationships around fewer monomer partners capable of delivering certified low-VOC packages. Tier-one automotive refinishers in the United States and Western Europe now require pre-audited supply chains with documented carbon footprints. This concentration is visible in procurement patterns among the largest North American architectural coatings producers.
Global Acrylate Monomers Market Segmentation
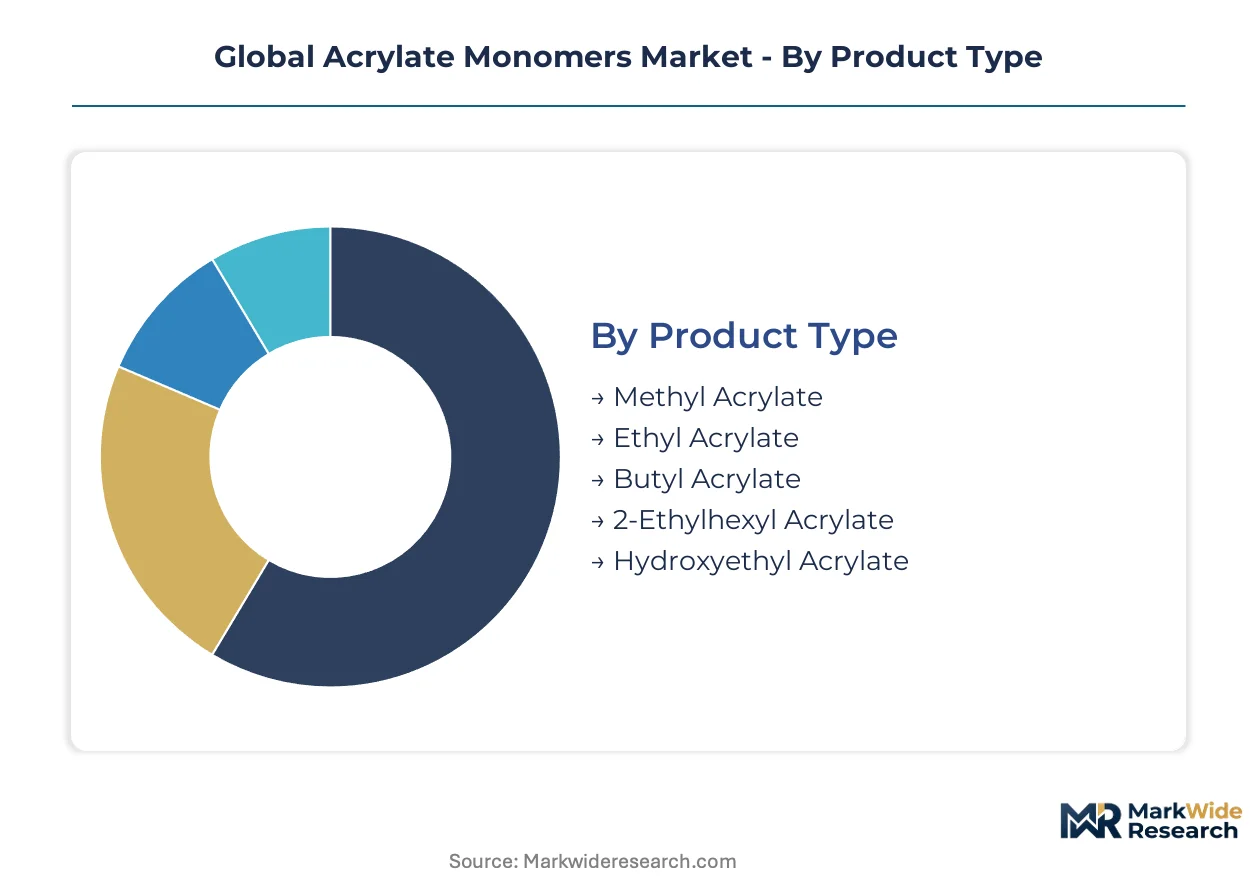
Acrylate monomer procurement patterns diverge sharply across product grades, with coating manufacturers selecting between commodity esters for volume formulations and functional monomers for specialized crosslinking. Segmentation discipline reveals where margin pools concentrate versus where capacity expansion races toward commoditization.
Product Type:
Customization intensity spans from standardized commodity esters to engineered hydroxyl-functional grades requiring precise glass transition tuning.
- Butyl Acrylate:The soft monomer backbone for waterborne architectural coatings, formulated at 40-60% of total resin solids. Demand concentrates in Jiangsu province coating clusters serving Southeast Asian export markets, with MEE emission enforcement constraining regional capacity additions.
- Hydroxyethyl Acrylate:Hydroxyl functionality enables urethane crosslinking in radiation-curable industrial wood and metal finishes. German automotive assembly plants and Guangdong tier suppliers pilot dual-cure clearcoats, pulling premium-grade volumes into radiation-curing supply chains.
- Methyl Acrylate:Textile finishing applications exploit stiffness and abrasion resistance in fabric treatment baths.
- Ethyl Acrylate:Pressure-sensitive adhesive formulations leverage moderate Tg and tack balance.
- 2-Ethylhexyl Acrylate:Low-Tg soft monomer for extreme flexibility requirements in sealant compounds.
Most installed capacity flows through Butyl Acrylate. Expansion is steepest in Hydroxyethyl Acrylate.
Application:
Volume scale inversely correlates with formulation complexity, with commodity coatings consuming bulk esters while specialty adhesives command functional premiums.
- Paints & Coatings:Waterborne architectural and automotive refinish formulations drive baseline demand, with EPA Clean Air Act compliance forcing VOC-compliant acrylic substitutions across California and Texas ozone non-attainment zones.
- Adhesives:High-performance automotive assembly bonds require hydroxyethyl acrylate grades with documented REACH registration and carbon footprint auditing for tier-one European and North American suppliers.
- Sealants:Construction joint compounds utilize low-modulus ester blends for movement accommodation.
- Textile Finishing:Methyl acrylate stiffness properties serve abrasion-resistant fabric treatments.
- Plastics Modification:Impact modifiers and processing aids incorporate acrylate copolymers for PVC and engineering resin compatibility.
Paints & Coatings absorbs the greatest monomer tonnage. Adhesives generates the highest margin per kilogram.
End User Industry:
Customer sophistication stratifies between specification-driven sectors demanding certified supply chains and price-sensitive bulk consumers.
- Construction:Architectural coatings and sealants dominate consumption, with reformulation cycles accelerating under tightening VOC regulations across multiple jurisdictions.
- Packaging:Pressure-sensitive labels and flexible laminates require food-contact compliant monomer grades with migration testing documentation.
- Electronics:Photoresist and display adhesive applications demand ultra-low metal ion specifications.
- Personal Care:Hair fixative polymers utilize specialty esters with cosmetic ingredient registry compliance.
- Agriculture:Seed coating and controlled-release formulations employ acrylate copolymers for film-forming properties.
Construction commands the largest volume position. Electronics exhibits the most stringent purity requirements.
Form:
Physical state determines logistics economics and formulation integration methods, with liquid bulk dominating high-volume supply and dispersed forms serving niche processing constraints.
- Liquid:Bulk tanker and drum deliveries serve coating manufacturers with in-house blending capabilities, offering lowest per-kilogram logistics cost for high-throughput operations.
- Emulsion:Pre-dispersed aqueous systems reduce emulsification energy and equipment investment for smaller formulation operations.
- Suspension:Bead polymerization feedstocks require controlled particle size distribution for consistent reactor performance.
- Powder:Solid handling suits remote construction sites and powder coating compounding operations lacking liquid storage infrastructure.
Liquid form moves through the majority of installed distribution infrastructure. Emulsion is gaining share in waterborne formulation integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical engineering established acrylic acid production economics during the 1960s, scaling esterification routes that now dominate global supply. Contemporary demand patterns reflect this industrial lineage while shifting toward Asian manufacturing gravity.
China
Jiangsu and Zhejiang province coating clusters consume butyl acrylate volumes for waterborne architectural exports to Vietnam and Indonesia. MEE wastewater enforcement constrains Yangtze River Delta capacity additions. Ningbo and Taizhou chemical parks now supply derivative plants across Southeast Asia with pre-optimized monomer packages.
Germany
Ludwigshafen and Marl industrial complexes anchor European acrylic acid production through integrated C1 chemistry platforms. REACH registration deadlines and EU Green Deal low-VOC mandates pull reformulated hydroxyethyl acrylate grades into automotive assembly clearcoats. Bavarian automotive plants pilot dual-cure radiation systems for interior trim applications.
United States
Texas Gulf Coast petrochemical corridors process propylene feedstocks into acrylic acid for downstream ester production. EPA Clean Air Act enforcement tightens architectural coating specifications across California and Texas ozone non-attainment zones. Houston-area refineries swing output with naphtha-cracker margins.
Japan
Kawasaki and Yokkaichi chemical complexes produce ultra-low metal ion acrylate grades for photoresist and display adhesive applications. METI industrial standards govern food-contact compliant monomer specifications for pressure-sensitive label exports. Japanese electronics manufacturers demand documented supply chain carbon footprints.
India
Gujarat and Maharashtra industrial corridors import acrylic acid for downstream esterification into textile finishing and construction sealant applications. PLI scheme incentives for specialty chemicals could localize acrylic acid production for South Asian coatings demand. Dahej and Mundra port zones concentrate formulation operations.
Global Acrylate Monomers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across functional specialization, with hydroxyethyl acrylate specialists commanding price multiples over butyl acrylate bulk suppliers. The vendor base stratifies into three tiers: integrated petrochemical majors with captive acrylic acid supply, regional esterification specialists serving proximate coating clusters, and functional monomer innovators targeting radiation-curable niches. Dominant competitive moves include backward integration into propylene feedstocks and pre-optimized monomer bundling that embeds rheology modifiers.
Within the integrated major tier, BASF SE anchors European supply through its Ludwigshafen complex, while Arkema occupies a position among specialty hydroxyl-functional grade producers. Dow represents North American scale capabilities across commodity ester production. These three exemplify how geographic concentration of petrochemical infrastructure shapes competitive positioning.
| Leading Market Players |
|---|
| BASF SE |
| Arkema |
| Dow |
| Evonik Industries AG |
| Nippon Shokubai Co., Ltd. |
| LG Chem |
| Mitsubishi Chemical Group Corporation |
| SABIC |
| Formosa Plastics Corporation |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers in China's Yangtze River Delta and family-owned mid-caps in Germany's Rhineland shape supply discipline through captive propylene access and long-term offtake contracting. Their ownership structures insulate pricing power from spot volatility while concentrating margin capture in integrated coastal complexes serving Southeast Asian derivative demand.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates hydroxyethyl acrylate for automotive clearcoats from commodity butyl acrylate for architectural coatings and generic methyl acrylate for textile finishing. Price differentiation hinges on REACH registration tier and carbon footprint certification for tier-one automotive suppliers. Cost compression in standard-grade butyl acrylate is intensifying because Jiangsu province MEE enforcement limits capacity additions. Construction sealant formulators exhibit highest price sensitivity, while German automotive OEMs accept premium positioning for documented supply chain auditing.
Supply Chain Analysis
Bulk liquid freight economics from Ningbo and Taizhou chemical parks to Vietnam and Indonesia coating plants anchor regional distribution cost structures. Geographic supply concentration centers on China, Germany, and the United States as propylene feedstock availability dictates acrylic acid production placement. Raw material flows draw from naphtha cracker operations, refinery propylene streams, and glycerol fermentation pilot routes. Single-source vulnerability runs through Yangtze River Delta wastewater enforcement that constrains expansion. Distribution runs through pre-optimized monomer packages delivered direct to coating manufacturer blending operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in hydroxyethyl acrylate premium tiers as automotive assembly plants adopt dual-cure radiation systems, while bio-based acrylic acid routes compress feedstock costs for forward-integrated players.
For Market Incumbents: Acquire fermentation-based acrylic acid pilot assets to secure cost-down positioning against glycerol-to-acrylic pathways converging with petrochemical economics. Backward integration into Jiangsu province propylene supply hedges MEE enforcement risk. Capacity addition in India's Gujarat corridor under PLI scheme incentives captures South Asian coatings demand before domestic acid production localizes. For New Entrants and Emerging Players: Begin with specialty hydroxyl-functional grades for radiation-curable wood and metal finishes where formulation expertise scarcity limits incumbent replication. India's textile finishing segment offers lowest penetration barriers against established methyl acrylate suppliers. Partner with Guangdong tier suppliers piloting dual-cure clearcoats to embed specifications early in automotive supply chain qualification. For Investors and Strategic Acquirers: Valuations sit cheapest among regional esterification specialists serving proximate coating clusters without captive acrylic acid supply. Long-term viability favors assets with documented REACH registration and carbon footprint auditing capabilities for tier-one automotive and electronics customers. Watch MEE wastewater enforcement intensity in Yangtze River Delta as inflection indicator for Chinese supply constraint and regional price firming.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstocks | Ludwigshafen and Marl complexes demonstrate how C1 chemistry platforms sustain captive supply economics. |
| Pre-Optimized Monomer Bundling | Ningbo chemical parks now deliver formulation-ready packages embedding rheology modifiers to Vietnamese coating plants. |
| Green Manufacturing Transition | Fermentation and glycerol-to-acrylic pathways are converging with conventional production economics in pilot scale. |
| Long-term Supply Agreement | Tier-one automotive refinishers in Germany require pre-audited chains with documented carbon footprints. |
| Joint Venture | Guangdong tier suppliers partner with radiation-curing specialists to pilot dual-cure clearcoats for interior trim. |
Research Methodology
Multiple input streams — technical R&D directors at monomer producers, procurement leads at downstream coating OEMs, distribution channel partners in Southeast Asia, and regulatory affairs specialists — were reconciled against customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from integrated petrochemical majors. Bottom-up plant capacity assessments and top-down end-use demand modeling were cross-validated through primary interviews and secondary source triangulation.
Historical capacity utilization patterns were cross-referenced against panel input from plant managers and procurement executives to anchor projections across the analysis window. Segmentation dimensions modeled include product grade tier, end-use industry, physical form, and regional production hub. CAGRs were derived from supply-demand balance modeling incorporating propylene feedstock cost trajectories and regulatory compliance cost layering for low-VOC formulation transitions.
Caveats apply where MEE enforcement intensity, REACH registration deadline extensions, or propylene cracker margin volatility could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Recovered Carbon Black Market
Bulk Chemicals
Europe Gamma Butyrolactone Market
Bulk Chemicals
Furandicarboxylic Acid Market
Bulk Chemicals
Nickel Nitrate Hexahydrate Market
Bulk Chemicals
Alunite Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
Caustic Potash Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
Crude Tall Oil Derivative Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
Sodium Sulphate Market
Bulk Chemicals
Sodium Bromide Market
Bulk Chemicals
Ammonium Carbonate Market
Bulk Chemicals
Chloroacetophenone Market
Bulk Chemicals
Phosphorus and Derivatives Market