
 Indonesia Sealants Market | 2026-2036
Indonesia Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Sealants Market Foresight
Specialty distributor networks across the archipelago is reshaping how sealant suppliers reach project sites. Henkel leverages its adhesive-sealant portfolio breadth to sustain contractor loyalty in Java's infrastructure corridor. BASF anchors technical specification-setting through direct engagement with EPC firms specifying polyurethane systems for marine environments. Sika competes on construction chemical integration, bundling waterproofing with structural bonding solutions for high-rise developers.
Indonesia sealants comprise formulated polymeric compounds—silicone, polyurethane, acrylic, and epoxy chemistries—engineered to fill joints, prevent moisture ingress, and accommodate substrate movement across temperature cycles from 25°C to 45°C ambient. Silicone dominates exterior glazing and weatherseal specifications due to UV stability and 25-year durability ratings, while polyurethane captures expansion joint applications where elastomeric recovery under cyclic loading matters. Epoxy segments serve industrial flooring and chemical containment where rigid, high-strength bonding takes priority over flexibility.
BIS-equivalent SNI certification administered by Indonesia's National Standardization Agency mandates product testing for construction sealants, creating compliance barriers for untested imports. The country's Ministry of Public Works and Housing enforces green building guidelines through GREENSHIP certification, pushing low-VOC and solvent-free formulations into specification defaults. Stakeholders must monitor enforcement intensity at provincial building departments, where permit approval timelines increasingly hinge on documented SNI traceability rather than manufacturer declarations alone.
Market Dynamics
Indonesia's SNI mandatory certification for building materials is redirecting procurement toward locally tested formulations and compressing import-dependent supply chains. Construction activity concentrates in Java's infrastructure corridor and Batam's industrial zone, reshaping logistics networks and distributor strategies.
Growth Catalysts
- Jakarta commercial high-rise development:Glass curtain wall specifications drive silicone sealant volumes as developers pursue GREENSHIP certification for premium office assets.
- GREENSHIP building guidelines:Low-VOC and solvent-free formulation mandates push specification defaults toward compliant domestic production.
- Polyurethane marine applications:Batam's shipyard and port infrastructure expansion creates sustained demand for elastomeric expansion joint systems.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate input costs fluctuate with regional refinery capacity, compressing margin visibility for polyurethane formulators.
- SNI testing backlog:Indonesia's National Standardization Agency laboratory capacity constraints extend certification timelines for new product introductions.
- Acrylic substitution in interior applications:Lower-cost water-based acrylics displace silicone in non-structural sealing where UV exposure is minimal.
Strategic Opportunities
- Sumatra infrastructure corridor:Trans-Sumatra toll road and port development projects remain underpenetrated relative to Java, offering first-mover positioning for compliant suppliers.
- Epoxy industrial flooring:Chemical processing and electronics manufacturing investments in Cikarang create demand for rigid, high-strength containment systems.
- Specialty distributor networks:Archipelago logistics fragmentation rewards localized inventory and technical service capabilities unreachable by direct import channels.
Industry Challenges
- Formulation chemist scarcity:Indonesia's technical talent pool for polymer rheology and adhesion science lags behind regional competitors in Thailand and Malaysia.
- Provincial permit inconsistency:Building department enforcement intensity varies across Java, Sumatra, and Sulawesi, complicating nationwide rollout of certified products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Sealants Market |
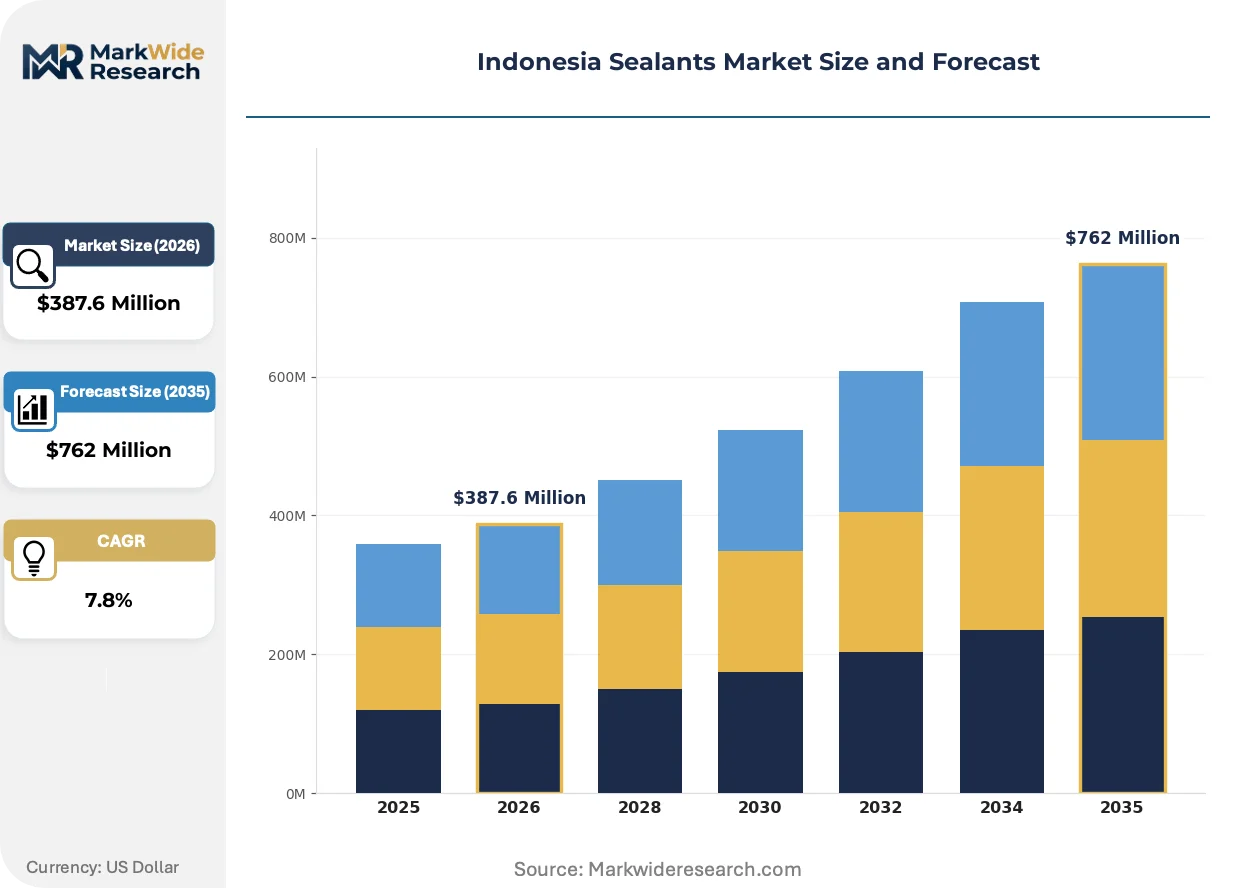
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $762 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Silicone, Epoxy End User: Construction, Automotive, Aerospace, Marine Application: Sealing, Bonding, Insulating, Coating Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | BASF, H.B. Fuller, Henkel, Bostik, Mapei, 3M, Dow Chemical, Dextone Indonesia, Sika, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Sealants Market Shifts & Advancements
Digital specification tools and low-carbon formulation mandates are compressing traditional technical sales cycles and elevating transparency requirements across Indonesia's construction chemical procurement.
Hybrid silicone-polyurethane intermediates are digitizing how EPC firms model joint movement and thermal cycling across Jakarta's high-rise glazing systems. Major contractors now require BIM-integrated sealant performance data before final specification lock, compressing the window for technical substitution. This digitization is compressing the traditional 90-day specification cycle into 30-day decision windows.
GREENSHIP certification administered by the Green Building Council Indonesia is tightening VOC thresholds for interior-grade sealants used in commercial developments. The industrial consequence is a formulation pivot toward waterborne and silyl-terminated polymer systems. High-rise residential towers in Jakarta's CBD and BSD City corridor are most affected, with developers now requiring documented solvent-free content in submittal packages.
Buyer concentration among Indonesia's top ten property developers is consolidating procurement authority into centralized technical committees. Specialty distributors with archipelago warehousing and certified technical staff are displacing traditional trading houses in Batam and Surabaya project sites. This shift is most visible in industrial zone developments where just-in-time delivery and on-site applicator training have become non-negotiable bid requirements.
Indonesia Sealants Market Segmentation
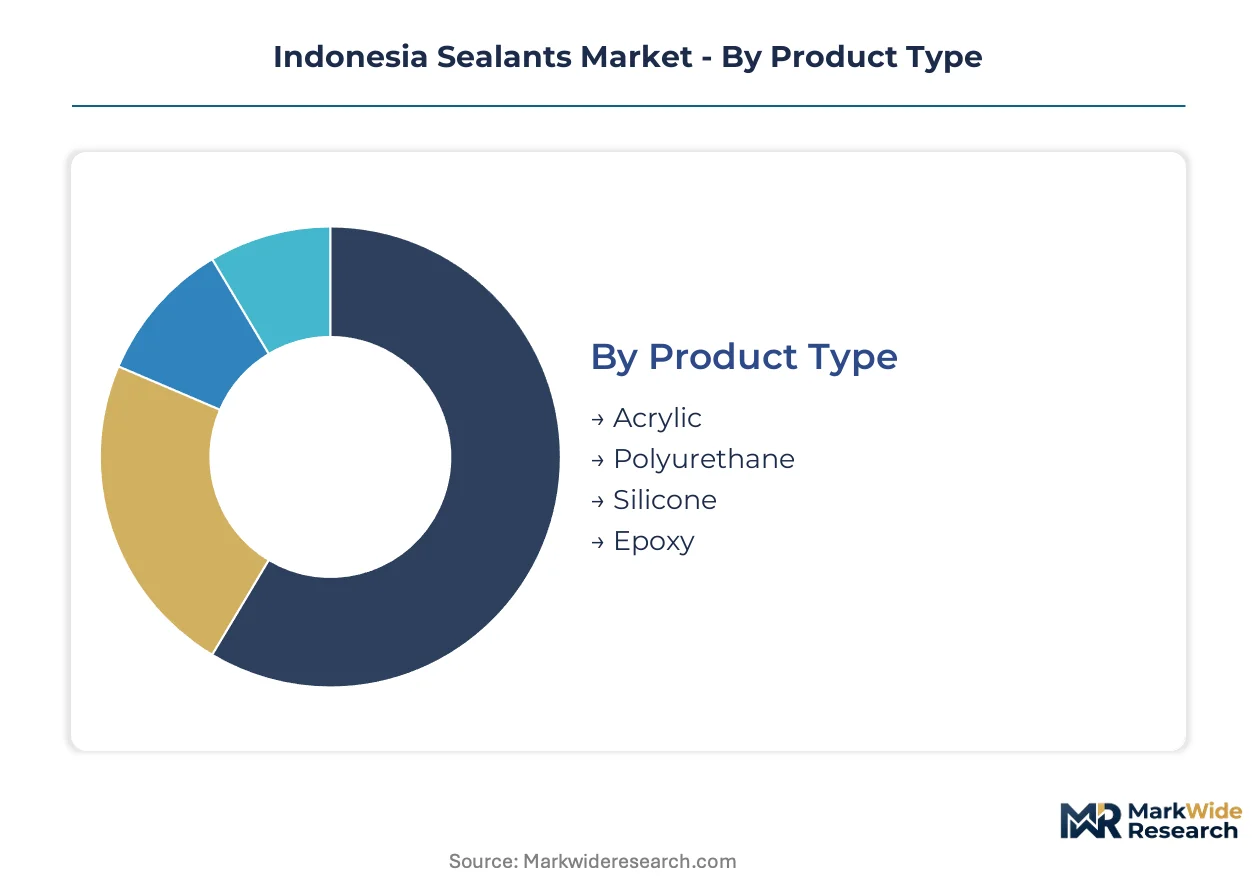
Indonesia's sealant procurement patterns diverge sharply across chemistries and end-use verticals, with SNI certification requirements and GREENSHIP building standards forcing specification discipline that rewards tested formulations over generic imports.
Product Type:
Mature silicone formulations anchor exterior specifications while emerging hybrid chemistries capture growth in movement-critical joints.
- Silicone:UV-stable polysiloxane formulations dominate Jakarta's glass curtain wall specifications, where 25-year durability ratings and GREENSHIP low-VOC compliance are mandatory for premium commercial towers in the CBD and BSD City corridor.
- Polyurethane:Elastomeric polyol-isocyanate systems capture expansion joint applications across Batam's shipyard infrastructure and Trans-Java toll road viaducts, where cyclic loading recovery under tropical temperature swings from 25°C to 45°C determines specification.
- Acrylic:Water-based formulations displace silicone in interior non-structural sealing across Sumatra residential projects where UV exposure is absent and cost sensitivity dominates procurement.
- Epoxy:Rigid bisphenol-A systems serve Cikarang industrial flooring and chemical containment specifications requiring compressive strength over flexibility.
Silicone retains volume leadership through Jakarta high-rise concentration; polyurethane holds the steepest expansion curve on marine and infrastructure momentum.
End User:
Construction procurement concentrates authority while industrial verticals fragment specification pathways across specialized technical committees.
- Construction:General contractors and EPC firms in Java's infrastructure corridor bundle waterproofing with structural bonding solutions, with centralized technical committees at Indonesia's top ten property developers consolidating procurement authority.
- Marine:Batam shipyard operators and port authorities specify elastomeric polyurethane systems for dock expansion joints and vessel sealing, with just-in-time delivery requirements displacing traditional trading houses.
- Automotive:Assembly plants in Karawang and Bekasi demand silyl-terminated polymer sealants for body-in-white applications, though domestic formulation capabilities lag Thai and Malaysian competitors.
- Aerospace:MRO facilities at Soekarno-Hatta and Halim Perdanakusuma import certified aviation-grade silicones through specialty distributors with archipelago warehousing.
Construction commands absolute volume share; marine applications are climbing the fastest on port infrastructure investment.
Application:
Functional requirements split procurement between movement-accommodating joints and rigid structural bonds with divergent formulation priorities.
- Sealing:Weatherseal and glazing applications across Jakarta commercial towers specify silicone for thermal cycling accommodation and moisture ingress prevention.
- Bonding:Structural adhesive applications in high-rise construction and industrial assembly favor epoxy and modified silicone systems with documented load-bearing capacity.
- Insulating:Thermal and acoustic isolation in GREENSHIP-certified buildings drives specification of low-density polyurethane foams and specialized acoustic sealants.
- Coating:Protective epoxy coatings for chemical processing facilities in Cikarang and Merak require SNI-tested formulations with documented solvent-free content.
Sealing maintains volume dominance through construction intensity; bonding functions are gaining share fastest on structural engineering integration.
Distribution Channel:
Logistics fragmentation across the archipelago rewards localized inventory positions unreachable by direct import channels.
- Distributors:Specialty networks with certified technical staff and archipelago warehousing displace trading houses in Surabaya and Batam, where on-site applicator training has become a non-negotiable bid requirement.
- Direct Sales:Multinational suppliers engage EPC firms and top-tier developers directly for polyurethane marine systems and high-rise silicone specifications, bypassing intermediaries for technical complexity.
- Retail:Hardware chains and construction material outlets serve renovation and residential repair segments in secondary cities with standardized acrylic and silicone cartridges.
- Online:E-commerce platforms capture small-volume procurement for interior-grade sealants, though SNI traceability requirements limit penetration in certified construction applications.
Distributor networks retain volume leadership through technical service differentiation; direct sales channels are expanding most quickly on marine and high-rise specification complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's National Standardization Agency enforces SNI certification for construction sealants, redirecting procurement toward locally tested formulations and compressing import-dependent supply chains across the archipelago.
Java
Jakarta's commercial high-rise segment drives silicone sealant volumes as developers pursue GREENSHIP certification for premium office assets in the CBD and BSD City corridor. The Ministry of Public Works and Housing enforces green building guidelines through provincial building departments, where permit approval timelines increasingly hinge on documented SNI traceability. Cikarang's industrial zone anchors demand for epoxy flooring systems in electronics manufacturing and chemical processing facilities.
Sumatra
Trans-Sumatra toll road and port development projects create sustained demand for polyurethane expansion joint systems across Medan and Palembang construction corridors. SNI testing requirements administered by Indonesia's National Standardization Agency extend certification timelines, creating compliance barriers for untested imports. Batam's shipyard operators and port authorities specify elastomeric polyurethane systems for dock infrastructure, with just-in-time delivery requirements displacing traditional trading houses.
Sulawesi
Makassar's emerging commercial construction sector drives specification of low-VOC acrylic sealants in residential and mid-rise developments where cost sensitivity dominates procurement. Provincial building departments enforce GREENSHIP guidelines with variable intensity, complicating nationwide rollout of certified products. Kendari's nickel processing industrial zone generates demand for chemical-resistant epoxy containment systems in mining-related infrastructure.
Kalimantan
Balikpapan and Samarinda infrastructure projects tied to resource extraction drive procurement of structural bonding solutions for industrial facility construction. The Ministry of Public Works and Housing mandates SNI traceability for public works contracts, compressing supply chain options for EPC firms. Pontianak's cross-border trade corridor with Malaysia creates distribution channel complexity for certified product verification.
Indonesia Sealants Market Competitive Landscape
On the supply side, the industry is moderately consolidated around multinational chemical conglomerates with integrated construction chemical portfolios, while regional specialists and local distributors occupy service-intensive niches. Three strategic archetypes dominate: global adhesive-sealant majors with specification-setting authority, construction chemical integrators bundling waterproofing with structural solutions, and archipelago-focused distributors with certified technical staff. Capacity expansion into compliant local formulation and strategic partnerships with EPC firms represent the dominant competitive moves.
Among the multinational majors, BASF anchors technical specification-setting through direct engagement with engineering firms, while Henkel leverages portfolio breadth to sustain contractor loyalty in Java's infrastructure corridor. Sika occupies a position exemplifying construction chemical integration, bundling waterproofing with structural bonding solutions. Dextone Indonesia represents the domestic formulation archetype, navigating SNI certification requirements to serve region-specific demand.
| Leading Market Players |
|---|
| BASF |
| H.B. Fuller |
| Henkel |
| Bostik |
| Mapei |
| 3M |
| Dow Chemical |
| Dextone Indonesia |
| Sika |
| Others |
Supply & Pricing Matrix
Cikarang's petrochemical cluster anchors Indonesia's sealant feedstock supply, with polyol and isocyanate availability fluctuations transmitting directly into polyurethane formulation costs and downstream contractor pricing power across Java's infrastructure corridor.
Pricing Analysis
SNI certification grade creates the primary spread between premium silicone specifications for Jakarta high-rises and economy acrylic alternatives for Sumatra residential projects. Three-tier pricing structure across certified premium, standard-compliant, and non-certified economy levels stratifies procurement. Cost compression in polyurethane segments intensifies because petrochemical feedstock volatility erodes margin visibility for formulators serving Batam marine applications. Volume contractors in Java's commercial construction demonstrate lowest price sensitivity due to specification lock-in, while provincial residential developers in Sulawesi prioritize unit cost minimization.
Supply Chain Analysis
Tariff exposure between China and Indonesia elevates landed costs for epoxy resin precursors and specialty silicone intermediates. Manufacturing concentrates in China, South Korea, and domestic Indonesian formulation facilities near Jakarta and Surabaya. Raw material sourcing draws from regional polyol producers, isocyanate suppliers, and fumed silica distributors. Single-source vulnerability persists for aviation-grade silicone imports serving MRO facilities at Soekarno-Hatta. Distribution runs through specialty archipelago networks with certified technical staff displacing direct import channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's sealant market demands substitution defense against water-based acrylics displacing silicone in interior non-structural applications where SNI certification is absent and cost sensitivity dominates procurement.
For Market Incumbents: Build regulatory moats through accelerated SNI certification investment at Indonesia's National Standardization Agency, compressing approval timelines that currently disadvantage import-dependent competitors. Deepen technical service capabilities across Sumatra's underpenetrated infrastructure corridor before regional specialists establish distributor relationships. Backward integration into polyol blending at Cikarang reduces exposure to petrochemical feedstock volatility threatening polyurethane margin stability. For New Entrants and Emerging Players: Pursue archipelago distributor partnerships with certified applicator training capabilities in Surabaya and Makassar, where centralized procurement authority has not yet consolidated. Target Sulawesi's emerging commercial construction sector with low-VOC acrylic formulations priced below GREENSHIP-mandatory silicone specifications. Anchor go-to-market strategy through direct engagement with provincial building departments enforcing variable SNI compliance intensity. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specialty distributor networks with archipelago warehousing and certified technical staff represent scarce, defensible assets unreachable by direct import channels. Acquisition targets include domestic formulators navigating SNI requirements with established EPC firm relationships. Monitor GREENSHIP enforcement intensity at Jakarta's provincial building departments as inflection indicator for premium silicone specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| SNI Certification Acceleration | Compresses approval timelines at Indonesia's National Standardization Agency, creating first-mover advantage for compliant formulations. |
| Backward Integration into Polyol Blending | Captive supply of polyurethane precursors at Cikarang insulates margins from regional petrochemical volatility. |
| Specialty Distributor Acquisition | Archipelago warehousing with certified technical staff displaces trading houses in Batam and Surabaya project sites. |
| GREENSHIP-Compliant Formulation Pivot | Low-VOC and solvent-free systems capture Jakarta CBD premium tower specifications requiring documented compliance. |
| Sumatra Infrastructure Corridor Expansion | Trans-Sumatra toll road and port development projects remain underpenetrated relative to Java's saturated corridor. |
Research Methodology
Initial hypotheses were tested against primary input from EPC firm procurement directors, specialty distributor technical staff, and polymer formulation chemists, and refined through secondary validation against Indonesia's National Standardization Agency certification records, Ministry of Public Works and Housing GREENSHIP registry data, and customs import documentation for sealant precursors. Bottom-up demand modeling across construction, marine, automotive, and aerospace verticals was triangulated with top-down supply-side capacity assessments at Cikarang and Surabaya formulation facilities.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by chemistry type, end-use vertical, application function, and distribution channel, with CAGRs derived from project pipeline analysis across Java, Sumatra, Sulawesi, and Kalimantan development corridors. Forecast inputs incorporated SNI certification timeline assumptions, GREENSHIP enforcement trajectory at provincial building departments, and petrochemical feedstock price sensitivity parameters for polyurethane systems.
Sensitivities concentrate around SNI laboratory capacity constraints extending certification timelines, provincial permit enforcement inconsistency complicating nationwide product rollout, and acrylic substitution acceleration in cost-sensitive residential segments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Adhesives Market
Adhesives & Sealants
Australia Adhesives Market
Adhesives & Sealants
Temporary Bonding Adhesives Market
Adhesives & Sealants
Asia-Pacific Epoxy Curing Agents Market
Adhesives & Sealants
Global Electronics Adhesives Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
Asia-Pacific Polyurethane Adhesives Market
Adhesives & Sealants
Tissue Sealants and Tissue Adhesive Market
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Global Adhesive Coating Market
Adhesives & Sealants
Global Silicone Adhesives and Sealants Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Urea-Formaldehyde Glues and Resins Market
Adhesives & Sealants
Global Construction Silicone Sealants Market
Adhesives & Sealants
Water-Borne Adhesives Market
Adhesives & Sealants
France Adhesives Market