
 Europe Contact Adhesives Market | 2026-2036
Europe Contact Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Contact Adhesives Market Foresight
Modular bonding kits is rebalancing how European manufacturers procure contact adhesives for assembly lines. Henkel AG & Co. KGaA leverages its formulation depth to supply reactive systems for automotive body shops. Sika AG anchors construction-grade contact adhesives through direct technical service teams across Central Europe. Jowat AG specializes in woodworking applications, competing on hot melt expertise for furniture and panel producers.
Europe contact adhesives are bonding agents formulated from synthetic rubbers, polychloroprene, or polyurethane dispersions that cure at room temperature under pressure to create flexible, high-strength joints between diverse substrates. These formulations typically achieve peel strengths exceeding 3.5 N/mm and operate across temperature ranges from -40°C to 120°C, serving industries where mechanical fastening would damage thin or dissimilar materials. Water-based formulations now lead product type demand as REACH VOC restrictions tighten across member states, while solvent-based grades retain share in specialty automotive and marine applications where rapid tack development remains critical. Pressure-sensitive variants represent the fastest-expanding product type segment, driven by electronics assembly and temporary fixturing in precision manufacturing.
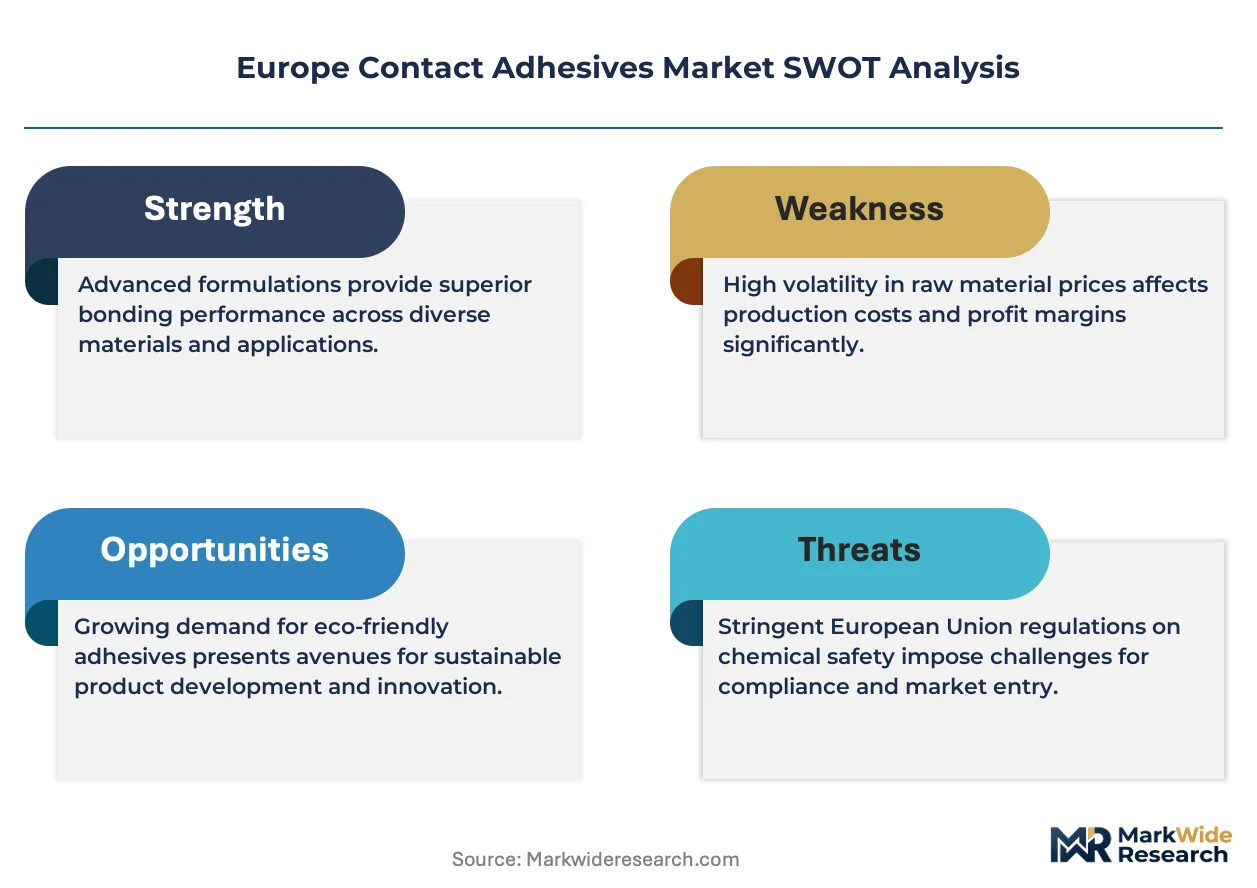
REACH registration requirements and the EU Green Deal carbon border adjustments are reshaping raw material sourcing decisions for adhesive compounders. ECHA substance evaluations now target residual monomer content in neoprene-based contact cements, forcing reformulation investments across German and French production facilities. EMA and national health regulators in Italy and Spain are aligning workplace exposure limits with CLP hazard classifications, elevating demand for low-odor, water-dispersed alternatives. Stakeholders must monitor how the EU F-Gas Regulation and evolving ecodesign standards for vehicles redirect specification flows between solvent, water, and reactive chemistries.
Market Dynamics
REACH VOC restrictions and the EU Green Deal are compressing solvent-based formulation share while forcing capital reallocation toward water-dispersed and reactive systems across German, French, and Italian production facilities.
Growth Catalysts
- Automotive lightweighting mandates:OEMs in Germany and France are substituting mechanical fasteners with adhesive bonding to achieve emission targets. Bond line optimization now drives specification volume for high-peel-strength neoprene and polyurethane systems.
- ECHA substance evaluations:Regulatory pressure on residual monomers is accelerating reformulation investment. Compounders are securing registration dossiers for low-odor water-based alternatives ahead of evaluation deadlines.
- Construction renovation waves:Energy retrofit programs across Italy and Spain are expanding contact adhesive consumption for flooring, wall paneling, and insulation attachment where mechanical fixation penetrates thermal envelopes.
Market Restraints
- Chloroprene feedstock concentration:Polychloroprene latex supply concentrates among Asian petrochemical complexes. European compounders face margin pressure from freight volatility and currency exposure on imported raw materials.
- Solvent retention in marine and specialty automotive:Water-based systems fail to achieve rapid tack development required by boat builders and motorsport fabricators. Regulatory friction from REACH derogation complexity prolongs solvent dependence in these niches.
- Thermoplastic welding substitution:Polyolefin and polyamide substrates in automotive interiors increasingly migrate toward vibration and laser welding. Adhesive bonding loses specification share where joint geometry permits thermal fusion.
Strategic Opportunities
- Polish and Romanian manufacturing expansion:Automotive tier suppliers are relocating assembly capacity to lower-cost EU member states. Local adhesive blending and technical service presence remains underdeveloped relative to production growth.
- Pressure-sensitive electronics assembly:Temporary fixturing for semiconductor and display manufacturing requires clean-removal contact adhesives. Formulators can capture specification share currently held by Japanese and Korean suppliers.
- CSRD-aligned carbon accounting:The Corporate Sustainability Reporting Directive creates procurement preference for adhesives with verified lifecycle carbon footprints. Early movers in environmental product declaration certification gain specification access.
Industry Challenges
- Formulation chemist scarcity:Expertise in waterborne polyurethane dispersion stability and rheology modification is concentrating among retiring specialists. Recruitment pipelines fail to replace technical depth lost to retirement waves.
- REACH registration cost recovery:Small and mid-scale compounders face extended payback periods on dossier preparation for niche raw materials. Registration cost concentration is forcing portfolio rationalization and withdrawal of specialty grades.
- Legacy equipment incompatibility:Water-based systems require heated tanks and modified spray equipment. Automotive body shops and furniture manufacturers resist capital expenditure on application infrastructure conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Contact Adhesives Market |
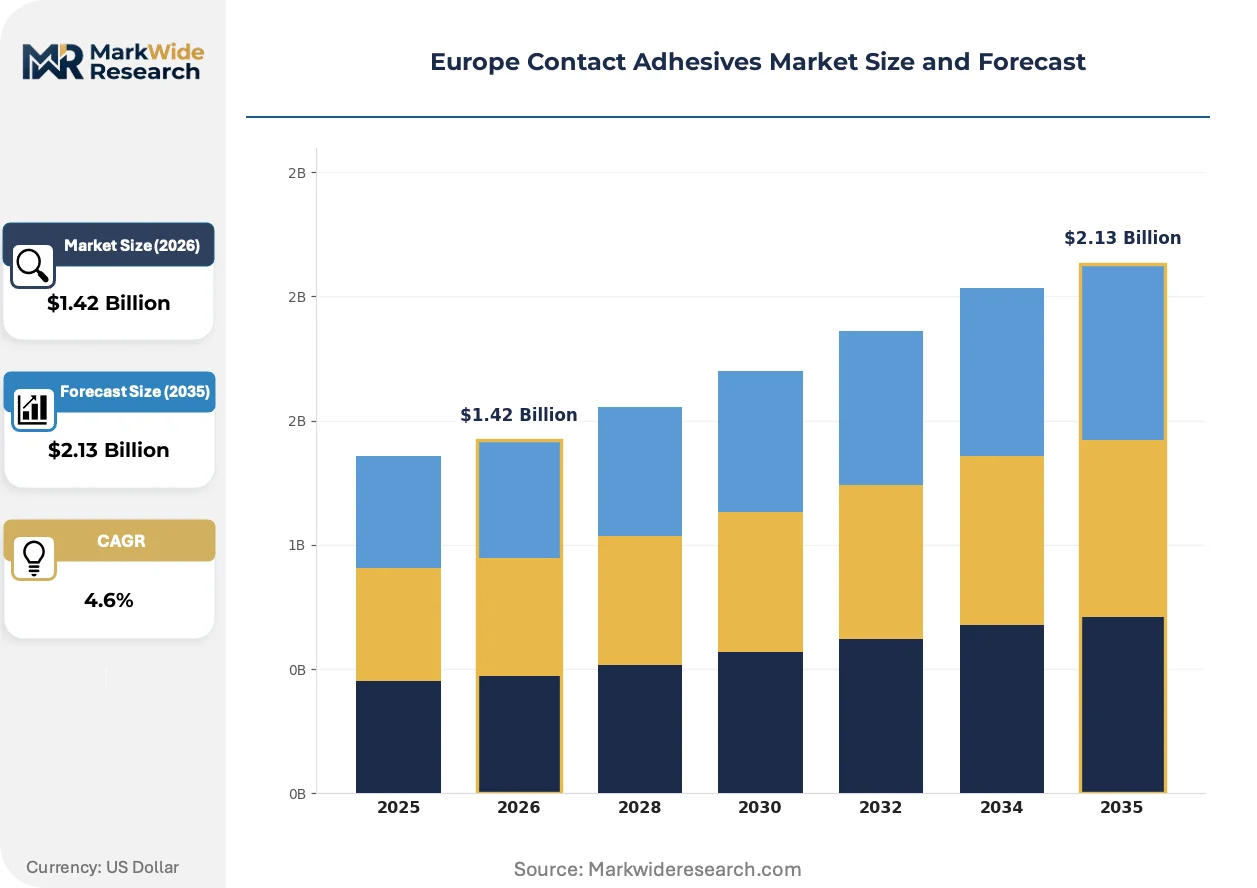
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Pressure-Sensitive End Use Industry: Construction, Automotive, Woodworking, Electronics Formulation Type: Single-Part, Two-Part, Reactive, Non-Reactive Distribution Channel: Direct Sales, Online Retail, Wholesale, Specialty Stores |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Arkema Group, H.B. Fuller, Sika AG, Jowat AG, Avery Dennison Corporation, Collano Adhesives AG, Beardow Adams, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Contact Adhesives Market Shifts & Advancements
Formulation chemistry and application methodology are diverging sharply between high-volume waterborne systems and precision reactive platforms, with regulatory pressure as the primary forcing mechanism.
Hot-melt reactive polyurethane (PUR) technology is absorbing specification share from conventional solvent contact cements in furniture and panel manufacturing. German and Austrian woodworking clusters are retrofitting application lines for moisture-curing PUR at pace exceeding waterborne adoption. The technology is absorbing margin compression from solvent taxation by eliminating drying energy and VOC abatement costs.
The EU F-Gas Regulation and evolving ecodesign standards for vehicles are redirecting specification flows between chemistries. Automotive OEMs now require adhesive suppliers to document global warming potential of blowing agents and residual solvents in product carbon footprints. Marine and specialty transport segments in Italy and Greece face compressed compliance timelines as derogation windows narrow.
Modular bonding kits are consolidating procurement decisions among tier suppliers. Automotive assemblers in Germany now specify pre-measured adhesive-cartridge systems with integrated static mixers, displacing bulk tank installations and on-site metering. This pattern is most visible in Stuttgart and Munich manufacturing corridors where just-in-sequence delivery mandates compress inventory tolerance.
Europe Contact Adhesives Market Segmentation
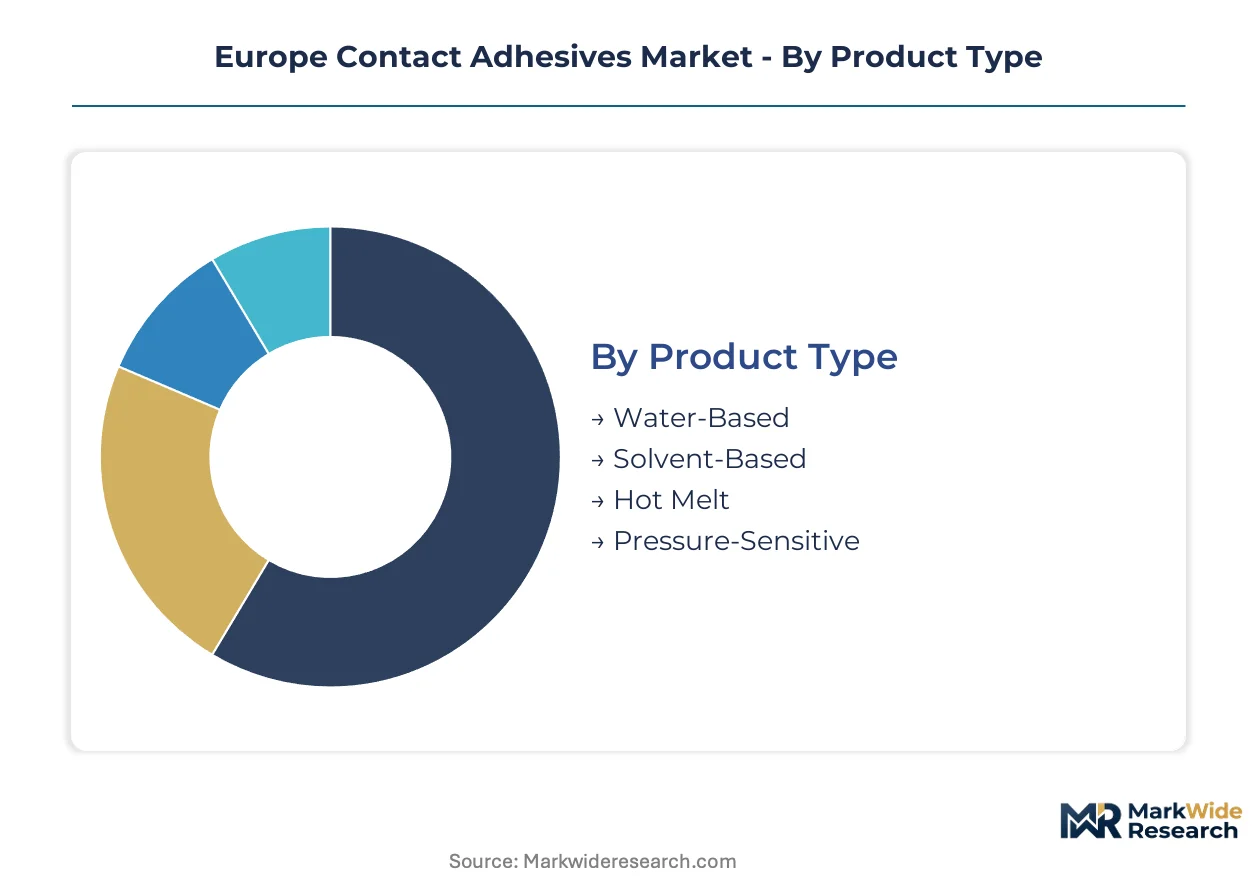
Contact adhesive procurement in Europe fragments across formulation chemistry, application method, and supply chain configuration. Specification flows differ sharply between automotive OEMs demanding reactive systems and construction contractors purchasing bulk waterborne grades through wholesale channels.
Product Type:
Standardization dominates high-volume waterborne production while solvent and reactive systems retain customization depth for specialty applications.
- Water-Based:Polyurethane and neoprene latex dispersions serve construction flooring and panel assembly across Germany and France. REACH VOC limits are compressing solvent share and redirecting specification volume toward heated-tank application systems in furniture manufacturing clusters.
- Solvent-Based:Rapid-tack chloroprene cements retain specification in marine construction and motorsport fabricators in Italy and Greece. ECHA substance evaluations on residual monomers are forcing reformulation investments ahead of registration deadlines.
- Hot Melt:Moisture-curing reactive polyurethanes are retrofitting woodworking lines in German and Austrian furniture clusters, eliminating drying energy costs.
- Pressure-Sensitive:Clean-removal formulations for temporary electronics fixturing are gaining specification from semiconductor and display manufacturers in the Netherlands and Ireland.
Most installed capacity flows through Water-Based. Expansion is steepest in Pressure-Sensitive.
End Use Industry:
Volume concentration sits with mature construction and automotive sectors while electronics emerges as the margin-rich growth pocket.
- Construction:Flooring, wall paneling, and insulation attachment drive bulk consumption across Italian and Spanish energy retrofit programs. Contact adhesives replace mechanical fixation where thermal envelope penetration must be minimized.
- Automotive:Body-in-white bonding and interior assembly in German OEMs and tier suppliers anchor regional demand. Lightweighting mandates are substituting adhesive bonding for mechanical fasteners to achieve emission targets.
- Woodworking:Furniture and panel producers in Polish and Romanian manufacturing corridors are absorbing specification share as production relocates from Western Europe.
- Electronics:Temporary fixturing for semiconductor and display manufacturing requires precision application systems currently dominated by Asian suppliers.
Construction commands the largest specification volume. Electronics is climbing the fastest as clean-room requirements tighten.
Formulation Type:
Reactive chemistries command premium pricing while non-reactive systems compete on throughput and equipment compatibility.
- Single-Part:Ready-to-use dispersions dominate construction and woodworking where on-site metering complexity must be minimized. Shelf stability and ambient curing simplify logistics for Polish and Romanian distributors.
- Two-Part:Metered mixing systems serve automotive body shops requiring adjustable cure rates and bond line optimization for dissimilar substrates.
- Reactive:Moisture-curing and UV-activated systems are penetrating automotive and electronics assembly where joint strength and thermal resistance justify process complexity.
- Non-Reactive:Physical drying formulations retain cost-sensitive construction applications despite VOC taxation and energy-intensive drying requirements.
Non-Reactive retains the widest installed base. Reactive systems are gaining specification share fastest in automotive and precision manufacturing.
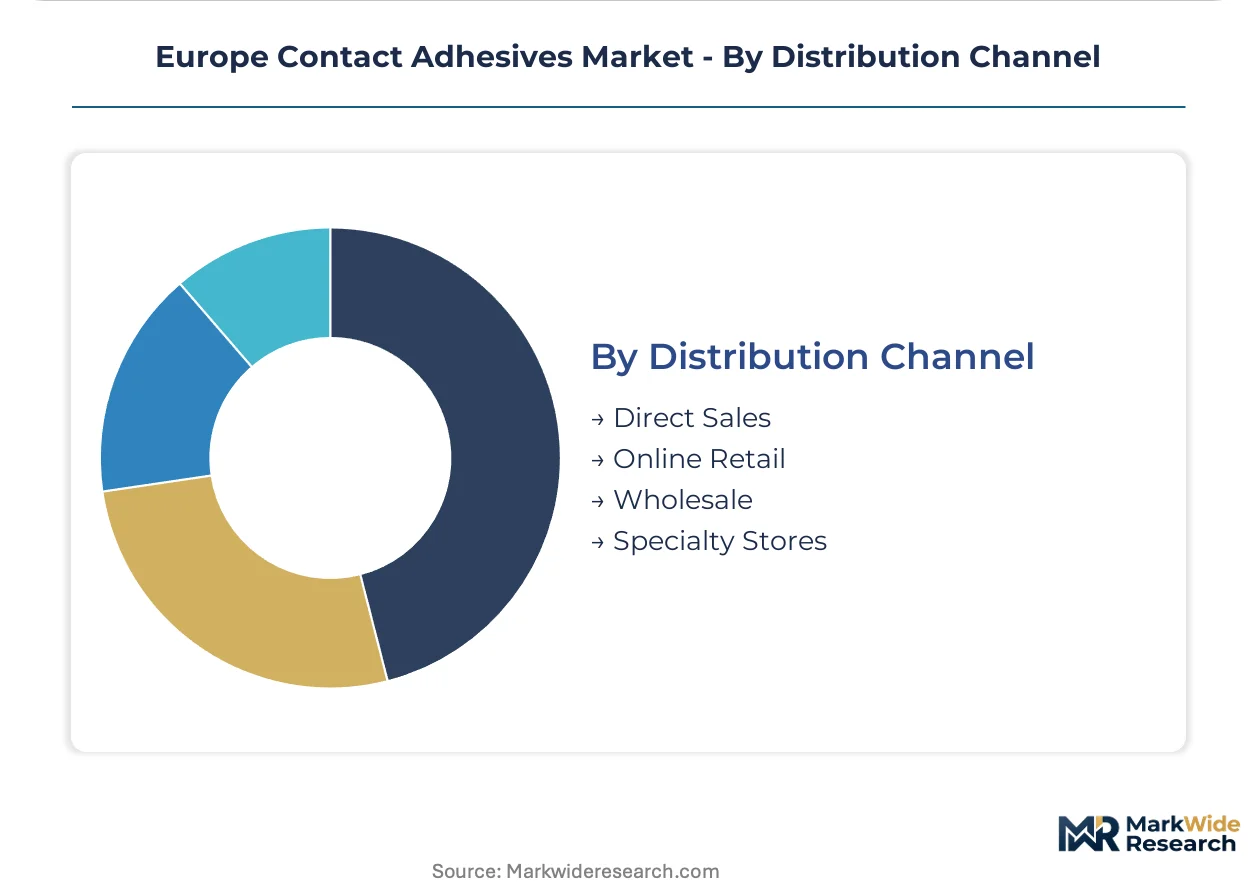
Distribution Channel:
Direct technical service locks in automotive specification while wholesale and online channels fragment construction procurement.
- Direct Sales:Technical service teams from major compounders anchor automotive and large woodworking accounts across German manufacturing corridors. Just-in-sequence delivery mandates compress inventory tolerance and favor integrated supply relationships.
- Online Retail:Small-batch procurement for maintenance and repair operations is migrating to digital platforms, particularly among Polish and Romanian contractors.
- Wholesale:Construction-grade volume flows through regional distributors in Italy and Spain with bulk tank delivery and application equipment leasing.
- Specialty Stores:Marine and motorsport fabricators in Greece and Italy source solvent-based grades through niche retailers with formulation expertise and derogation documentation support.
Wholesale channels handle the largest volume throughput. Online Retail is expanding most quickly as small-contractor digital adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical conglomerates pioneered industrial contact adhesive formulations during the post-war reconstruction era, establishing formulation expertise that still anchors European production capacity. REACH implementation subsequently redistributed compounding investments toward member states with favorable regulatory interpretation.
Germany
Automotive OEMs in Stuttgart and Munich corridors specify reactive polyurethane systems for body-in-white bonding under EU Green Deal emission mandates. KBA vehicle certification protocols now require documented carbon footprints for adhesive inputs. Bavarian and Baden-Württemberg manufacturing clusters host technical service teams serving just-in-sequence delivery contracts.
France
Construction renovation programs across Île-de-France drive waterborne neoprene consumption for flooring and wall paneling applications. ANSM workplace exposure guidelines align with CLP hazard classifications for residual monomer content. Auvergne-Rhône-Alpes industrial zones concentrate furniture manufacturing migrating toward moisture-curing hot melt systems.
Italy
Marine fabricators in Liguria and Tuscany retain solvent-based chloroprene specifications for rapid-tack hull assembly despite REACH derogation complexity. Energy retrofit waves across Lombardy and Veneto expand contact adhesive attachment for insulation systems. ECHA substance evaluations target neoprene residual monomers at compounder facilities near Milan.
Poland
Automotive tier suppliers relocating assembly capacity from Western Europe generate unmet demand for local adhesive blending and technical service presence. Polish distributors handle growing waterborne volume through heated-tank application systems leased to furniture manufacturers. Warsaw and Kraków logistics corridors consolidate procurement for Central European manufacturing.
Spain
Construction-grade bulk consumption concentrates in Madrid and Barcelona metropolitan renovation markets where thermal envelope penetration must be minimized. Spanish wholesalers deliver tank-installed systems with application equipment leasing to regional contractors. EU F-Gas Regulation compliance timelines compress specification windows for foam-bonding adhesives in building insulation.
Europe Contact Adhesives Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and technical service depth, with reactive systems commanding pricing multiples over standard waterborne grades. The vendor base concentrates among German and Swiss specialty chemical conglomerates with integrated raw material positions, while mid-scale compounders compete on regional logistics and application equipment bundling. Three archetypes dominate: diversified adhesive majors with automotive certification depth, woodworking specialists with hot melt expertise, and construction-focused regional blenders with distribution density. Competitive dynamics center on REACH registration cost recovery through portfolio rationalization and backward integration into polyurethane dispersion production.
Among diversified majors, Henkel AG & Co. KGaA and Sika AG exemplify premium-tier positioning through automotive and construction certification depth. Jowat AG occupies a specialist position within woodworking and furniture adhesive supply. These three anchors demonstrate how formulation expertise concentrates among German and Swiss headquartered entities with decades of European regulatory navigation experience.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Arkema Group |
| H.B. Fuller |
| Sika AG |
| Jowat AG |
| Avery Dennison Corporation |
| Collano Adhesives AG |
| Beardow Adams |
| Others |
Supply & Pricing Matrix
Chloroprene latex feedstock costs transmit directly from Asian petrochemical complexes through European compounder margins to automotive OEM procurement tiers, with freight volatility and currency exposure amplifying price spreads between waterborne and solvent-based formulations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered reactive systems from commodity waterborne grades and unregistered solvent-based niche products. Price differentiation hinges on certification depth for automotive OEMs and volume scale for construction contractors. Cost compression in economy-tier waterborne segments is intensifying because heated-tank application infrastructure amortization concentrates among smaller Polish and Romanian distributors. Construction contractors exhibit highest price sensitivity, while German automotive OEMs prioritize bond-line performance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart and Munich automotive corridors, while wholesale distributors serve fragmented Italian and Spanish construction markets. Raw material sourcing draws from German polyurethane dispersion producers, French neoprene latex compounders, and imported Asian chloroprene feedstocks. Distribution runs through technical service teams for automotive accounts and bulk tank leasing networks for construction contractors. Single-source vulnerability concentrates in polychloroprene latex supply from Asian petrochemical complexes, exposing European blenders to freight rate volatility and currency fluctuation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe contact adhesives constitute a late-cycle quality story as REACH compliance costs filter out marginal compounders and procurement concentrates among specification-certified suppliers capable of documented carbon footprint verification.
For Market Incumbents: Deepen backward integration into polyurethane dispersion production to capture margin compression from raw material volatility. Secure ECHA registration dossiers for low-odor water-based alternatives ahead of residual monomer evaluation deadlines. Anchor automotive certification depth against thermoplastic welding substitution threats in interior assembly applications. For New Entrants and Emerging Players: The price-point gap between premium reactive systems and economy waterborne grades offers entry space for mid-tier compounders with regional logistics advantages. Polish and Romanian automotive tier supplier corridors present the most penetrable geography given underdeveloped local blending capacity. Pursue technical service partnerships with relocated Western European furniture manufacturers as a go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration cost recovery timelines exceed small-compounder cash flow horizons. Five-to-ten year viability favors targets with captive dispersion production and existing automotive OEM qualification. Monitor ECHA substance evaluation timelines as inflection indicators for portfolio rationalization waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Dispersion | Captive supply of critical raw materials insulates margins from Asian chloroprene price volatility. |
| ECHA Pre-Registration Dossier Investment | Early mover advantage secures market access ahead of residual monomer evaluation deadlines. |
| Carbon Footprint Certification Program | CSRD-aligned environmental product declarations unlock procurement preference from German OEMs. |
| Technical Service Expansion in Poland | Proximity to relocated automotive tier suppliers captures just-in-sequence delivery mandates. |
| Hot Melt Reactive PUR Capacity Buildout | Moisture-curing systems displace solvent contact cements in Bavarian furniture manufacturing clusters. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with adhesive formulators, automotive Tier 1 procurement leads, construction distributor managers, and ECHA regulatory affairs specialists against secondary validation from Cefic chemical industry reports, Eurostat trade data, KBA vehicle certification filings, and EU F-Gas Regulation implementation trackers.
Historical trendline analysis across product type, formulation chemistry, end-use industry, and regional production hub dimensions anchors the projection framework. CAGRs derive from segment-level volume trajectories calibrated against macroeconomic drivers and regulatory compliance timelines. Forecast inputs incorporate automotive lightweighting mandate intensity, construction renovation program allocations, and REACH evaluation schedule pacing.
The model assumes a particular technology adoption path; alternative pathways for moisture-curing reactive polyurethane would alter the outlook if woodworking line retrofit acceleration exceeds waterborne system adoption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
Acrylate Oligomer Market
Adhesives & Sealants
Paper-Backing Abrasive Adhesive Discs Market
Adhesives & Sealants
Co-Polymer Sealants Market
Adhesives & Sealants
Global Electrically Conductive Adhesives Market
Adhesives & Sealants
Fuel Resistant Sealant Market
Adhesives & Sealants
Singapore Adhesives Market
Adhesives & Sealants
Solvent Based Laminating Adhesives Market
Adhesives & Sealants
Skin Adhesives Market
Adhesives & Sealants
Textile Adhesives Market
Adhesives & Sealants
US Pressure Sensitive Adhesives Market
Adhesives & Sealants
Ocular Sealants and Glues Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
North America Laminating Adhesives Market
Adhesives & Sealants
Dibutyl Maleate (DBM) Market
Adhesives & Sealants
Europe Polyurethane (PU) Hot-Melt Adhesives Market