
 Paper-Backing Abrasive Adhesive Discs Market | 2026-2036
Paper-Backing Abrasive Adhesive Discs Market Size, Share, and Industry Trends Forecast 2026-2036
Paper-Backing Abrasive Adhesive Discs Market Analytics
Buyer concentration in automotive OEM supply chains is decoupling from traditional distributor networks as tier-one manufacturers direct-source consumables. Saint-Gobain leverages integrated mineral supply chains to sustain cost positions in European automotive programs. Mirka anchors Nordic market share through dust-extraction-compatible disc systems. Klingspor competes on breadth, spanning construction and metalworking channels across Central European markets.
Paper-backing abrasive adhesive discs consist of abrasive grains bonded to a flexible kraft paper substrate with pressure-sensitive or heat-activated adhesives, typically ranging from 80 to 400 grit for controlled material removal. These discs attach to orbital or rotary sanders for surface preparation, finishing, and deburring across industrial and commercial workflows. Ceramic material formulations command premium positioning as they outlast alumina alternatives in high-pressure metalworking applications. Woodworking remains the volume anchor, though automotive refinishing generates disproportionate margin pools due to certification requirements and color-matching precision standards.
EPA workplace silica standards and OSHA permissible exposure limits shape product development cycles, pushing manufacturers toward low-dust ceramic formulations and vacuum-compatible disc interfaces. REACH substance restrictions in Europe limit certain resin binders, compelling reformulation investments for market access continuity. Stakeholders must track evolving MEE enforcement patterns in China alongside dual carbon compliance timelines that affect paper substrate sourcing decisions.
Market Dynamics
Automotive OEM supply chains are decoupling from traditional abrasive distributors as tier-one manufacturers impose direct-sourcing mandates for certified consumables, compressing intermediary margins while elevating compliance documentation requirements.
Growth Catalysts
- Ceramic-grade formulations:Superior longevity in high-pressure metalworking applications is pulling demand from alumina alternatives in German automotive refinishing operations.
- EPA workplace silica standards:Tightened permissible exposure limits are accelerating vacuum-compatible disc adoption across US construction and manufacturing facilities.
- Dust-extraction systems:Integration with orbital sander platforms is creating pull-through demand for interface-compatible abrasive discs in Nordic woodworking clusters.
Market Restraints
- Kraft paper substrate volatility:Pulp supply concentration in Nordic and Baltic regions exposes manufacturers to input cost swings and carbon compliance timeline pressures.
- REACH substance restrictions:ECHA limitations on certain phenolic resin binders force reformulation investments that delay European market access for non-compliant suppliers.
- Film-backed substitutes:Polyester and polyimide backing materials offer superior tear resistance in wet sanding applications, threatening paper-back share in marine and automotive finishing.
Strategic Opportunities
- Chinese MEE enforcement patterns:Strengthened dust emission inspections at manufacturing facilities are creating compliance-driven upgrade cycles for certified abrasive systems.
- Dual carbon compliance timelines:Paper substrate sourcing from certified sustainable forestry programs opens premium positioning in EU Green Deal-aligned procurement frameworks.
- Robotic sanding integration:Automated surface preparation cells in automotive paint shops demand consistent grit quality and automated disc-change compatibility.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous EPA, REACH, and GB standard compliance requires parallel testing protocols that extend product launch windows.
- Legacy sander interface fragmentation:Proprietary hook-and-loop patterns across tool manufacturers force SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper-Backing Abrasive Adhesive Discs Market |
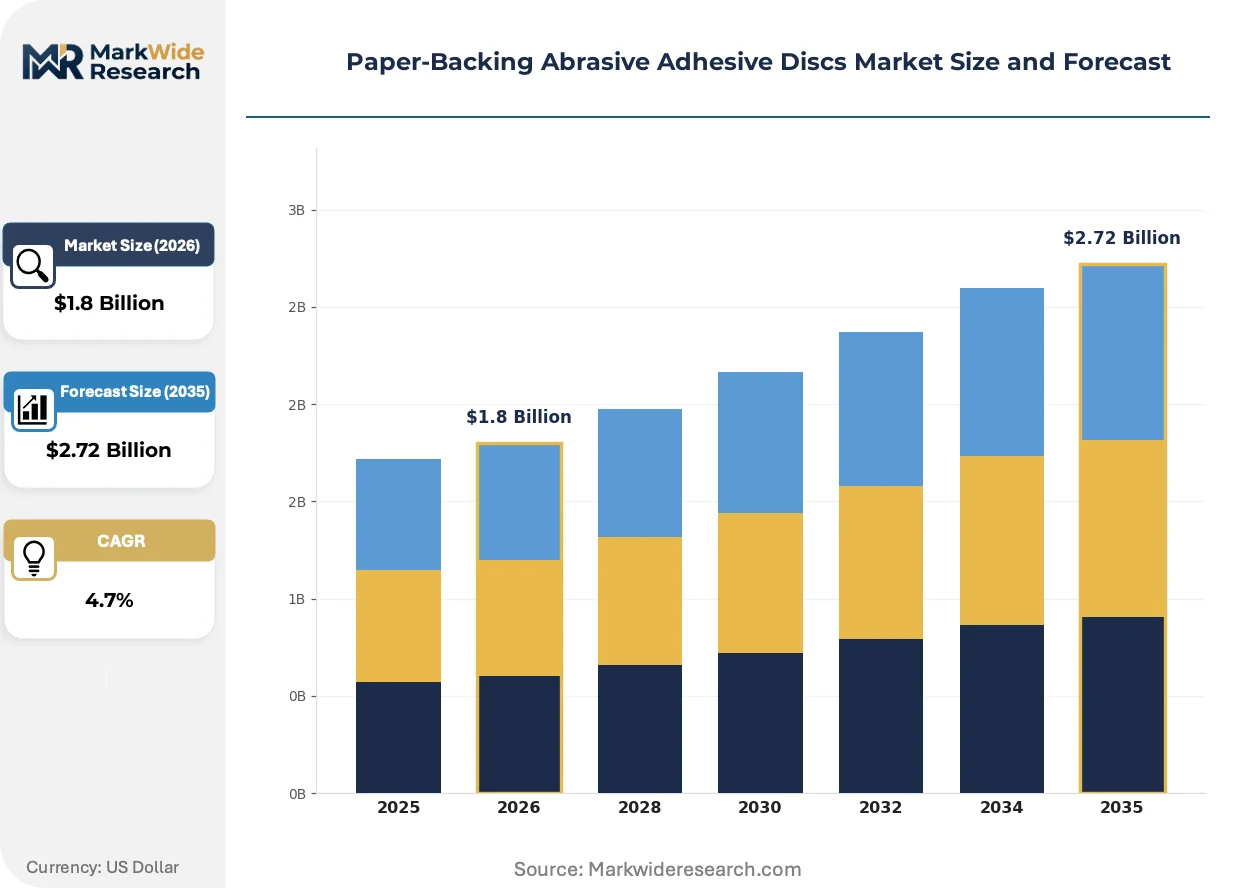
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc, Belt, Sheet, Roll Material: Alumina, Silicon Carbide, Zirconia, Ceramic Application: Woodworking, Metalworking, Automotive, Construction End User: Manufacturers, DIY Consumers, Contractors, Repair Shops |
| Companies Covered | 3M, Saint-Gobain, Mirka, sia Abrasives Industries AG, Sunmight USA Corporation, Norton Abrasives, Klingspor, Carborundum Universal, Hermes Abrasives, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper-Backing Abrasive Adhesive Discs Market Evolving Landscape
Surface preparation workflows are converging around connected dust extraction and precision grit engineering, compressing tolerance windows while elevating consumable performance specifications.
Ceramic aluminum oxide grains bonded with engineered heat-activated adhesives are electrifying high-pressure metalworking applications. German automotive OEM paint preparation shops are specifying these formulations for robotic sanding cells. The technology is electrifying margin structures as ceramic-grade discs command sustained premiums over conventional alumina alternatives despite higher unit costs.
REACH substance restrictions on specific phenolic resin binders are compelling binder chemistry overhauls across European supply chains. ECHA enforcement timelines are compressing reformulation windows for manufacturers serving automotive and aerospace qualified supplier programs. German industrial manufacturing belt OEMs are accelerating supplier audits to verify compliant resin systems before contract renewals.
Direct-sourcing mandates from tier-one automotive manufacturers are disintermediating traditional abrasive distributors. Tier-one suppliers are establishing captive consumables procurement functions with embedded quality engineering teams. This pattern concentrates most visibly in German automotive supply chains where OEM qualification requirements exceed distributor technical capabilities.
Paper-Backing Abrasive Adhesive Discs Market Segmentation
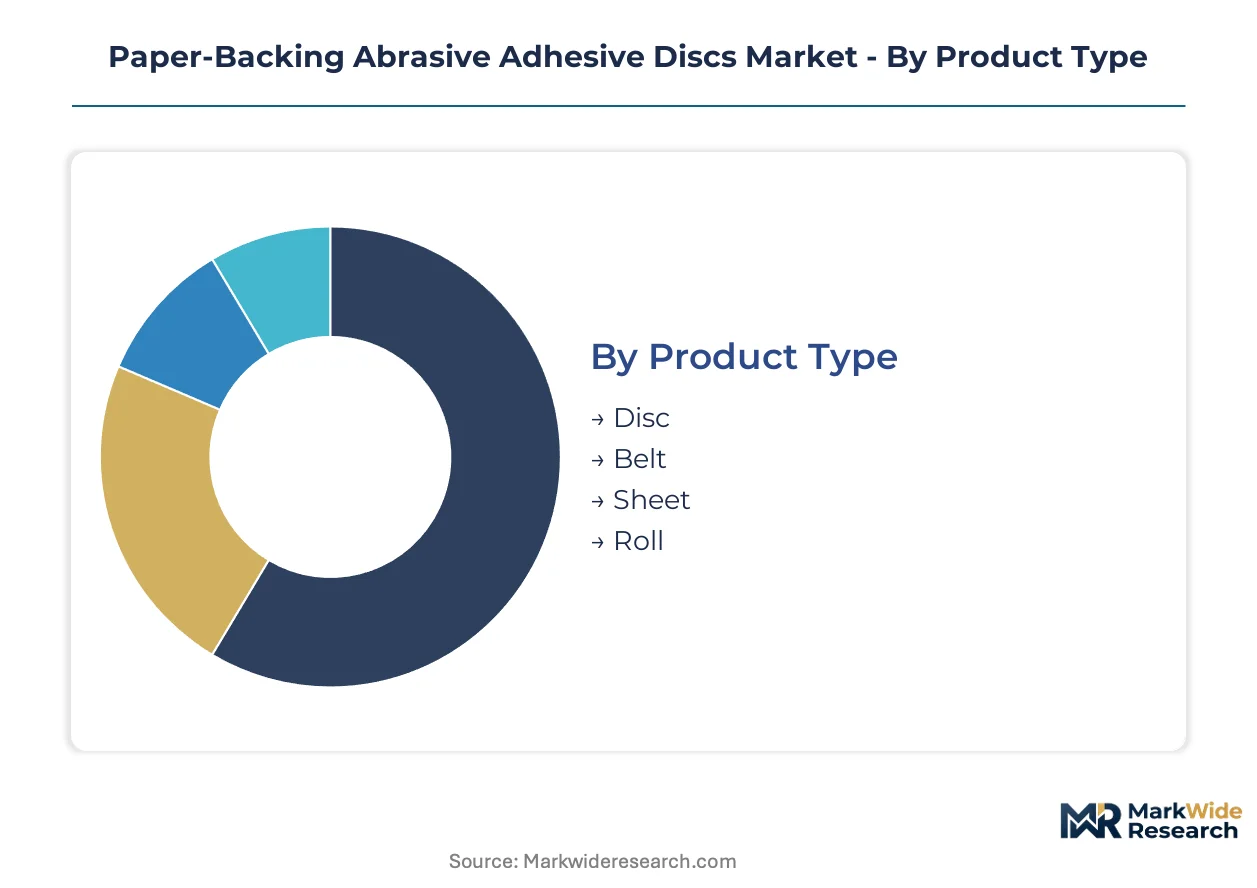
Certification requirements fragment demand across abrasive grades, with automotive OEM programs mandating REACH-compliant ceramic formulations while construction channels absorb cost-optimized alumina alternatives. Material specifications and end-user compliance burdens create distinct margin tiers that reshape supplier prioritization.
Product Type:
Disc formats carry the heaviest certification documentation burden, particularly for automotive OEM supply chains requiring batch traceability and dust-emission test reports.
- Disc:Pressure-sensitive adhesive mounting suits orbital sander platforms in automotive refinishing and robotic sanding cells. German OEM paint preparation shops specify these for precision grit consistency and vacuum-extraction compatibility.
- Belt:Continuous-loop construction serves stationary sanding stations in high-volume woodworking mills. Nordic pulp-processing equipment manufacturers drive specification standards for tear resistance under sustained tension.
- Sheet:Hand-sanding formats dominate DIY retail channels and spot-repair applications where tool investment is minimal.
- Roll:Custom-cut lengths support fabrication shops with variable-format requirements, reducing SKU complexity for distributors serving fragmented metalworking customers.
Disc sits at the top of the volume ranking, with Belt climbing the fastest on automated processing equipment upgrades.
Material:
Raw material sourcing costs stratify competitive positioning, with ceramic commanding premium placement against commodity alumina alternatives.
- Ceramic:Engineered aluminum oxide grains with self-sharpening crystalline structure outlast conventional abrasives in high-pressure metalworking. German automotive supply chains specify these for robotic sanding cells where disc-change downtime carries six-figure hourly costs.
- Alumina:Brown and white fused aluminum oxide variants anchor volume production for general-purpose woodworking and construction sanding where unit economics outweigh longevity concerns.
- Zirconia:Heavy-duty coated grains target stainless steel and exotic alloy processing in aerospace-qualified supplier programs.
- Silicon Carbide:Harder, more brittle grain structure excels in glass, stone, and lacquer finishing where minimal substrate damage is critical.
Alumina retains the largest volume footprint, though Ceramic gains share fastest on automotive precision requirements.
Application:
End-use certification intensity varies sharply, with automotive and aerospace channels imposing supplier audit regimes absent from construction procurement.
- Automotive:OEM paint preparation and refinishing operations demand REACH-compliant resin binders, vacuum-compatible disc interfaces, and grit consistency tolerances tighter than industrial norms. Tier-one manufacturers direct-source these consumables, bypassing traditional distribution.
- Metalworking:High-pressure grinding and deburring operations prioritize ceramic formulations for thermal stability and reduced disc-change frequency in automated cells.
- Woodworking:Volume anchor segment spanning furniture manufacturing, millwork, and flooring installation where dust-extraction integration is becoming standard specification.
- Construction:Price-sensitive drywall finishing and general contractor procurement tolerates higher dust generation and shorter abrasive life in exchange for lower unit costs.
Woodworking holds the volume lead, with Automotive expanding most quickly on direct-sourcing mandate proliferation.
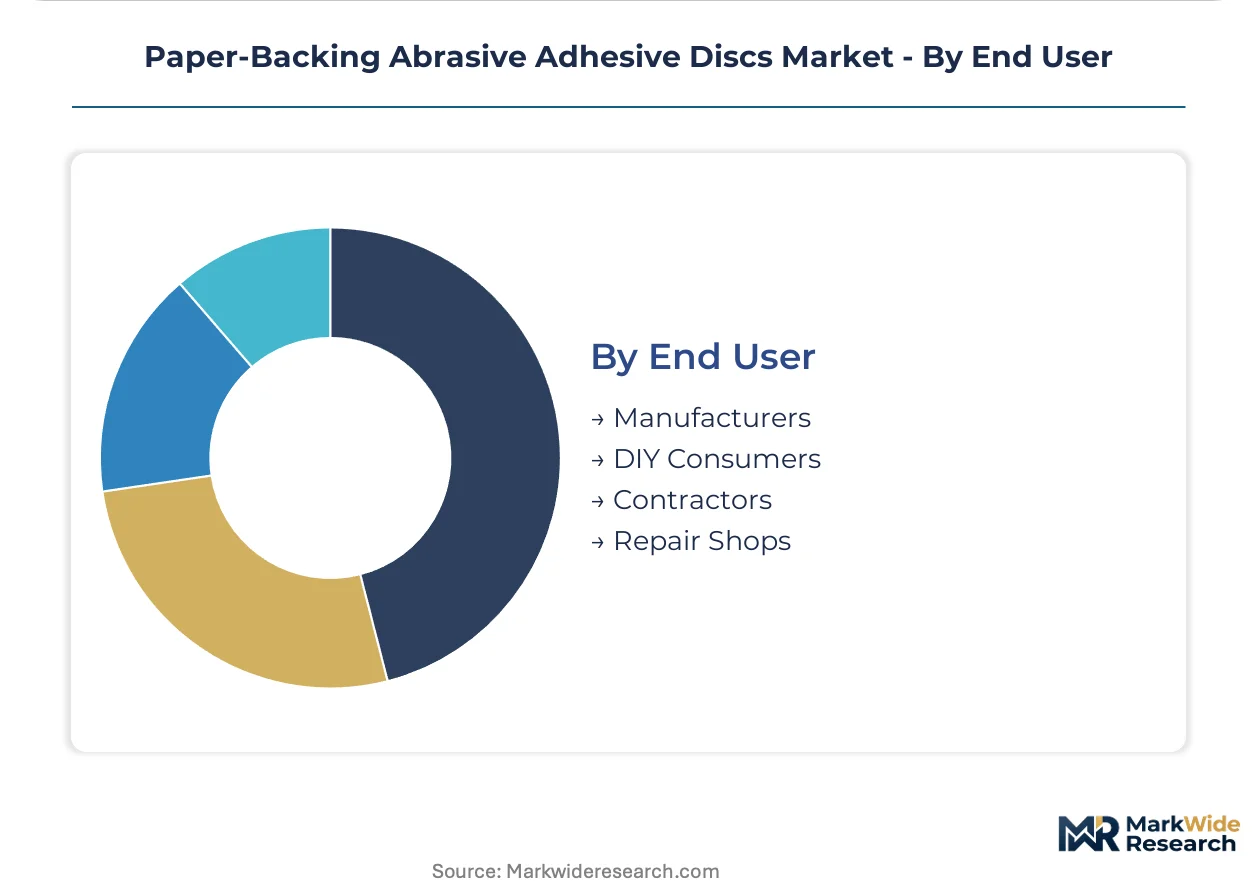
End User:
Procurement sophistication divides the customer base, with qualified manufacturers embedding quality engineering teams while contractor channels prioritize availability and price.
- Manufacturers:Captive procurement functions in automotive and aerospace tier-one suppliers specify certified abrasives with embedded compliance documentation, compressing distributor margins while elevating technical service requirements.
- Repair Shops:Independent automotive refinishing operations balance certification needs against inventory constraints, creating demand for mid-tier ceramic grades with streamlined documentation.
- Contractors:Construction and installation trades purchase through distributor networks with limited technical specification involvement, prioritizing product availability and bulk pricing.
- DIY Consumers:Retail-channel purchasers drive commoditization pressure in sheet and roll formats, with brand recognition and shelf placement determining selection.
Manufacturers represent the deepest value pool, with Repair Shops showing the steepest expansion trajectory on automotive aftermarket growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supply chains demand REACH-certified ceramic abrasives, while China's MEE enforcement drives compliance upgrades in manufacturing clusters. These divergent regulatory pressures reshape procurement patterns across major industrial economies.
United States
EPA workplace silica standards and OSHA permissible exposure limits compel vacuum-compatible disc adoption in construction and automotive refinishing. Regional enforcement varies, with California's Division of Occupational Safety and Health applying stricter interpretation than federal baselines. Detroit-area automotive paint shops specify dust-extraction-integrated systems for robotic sanding cells.
Germany
Automotive OEM direct-sourcing mandates concentrate demand for ECHA-compliant resin binders in Bavaria and Baden-Württemberg. KBA vehicle certification requirements cascade into supplier audit regimes for consumables. Stuttgart's tier-one manufacturers embed quality engineering teams to verify batch traceability before contract renewals.
China
MEE strengthened dust emission inspections at manufacturing facilities trigger upgrade cycles for certified abrasive systems. Dual carbon compliance timelines affect paper substrate sourcing decisions for export-oriented producers. Yangtze River Delta woodworking equipment manufacturers specify extraction-compatible disc interfaces for domestic and European-bound machinery.
Japan
METI industrial efficiency guidelines promote automated surface preparation in automotive and electronics manufacturing. JIS standards for abrasive performance create technical barriers for non-compliant imports. Nagoya's automotive component suppliers specify consistent grit quality for robotic sanding integration.
India
BIS certification requirements for industrial abrasives expand as domestic automotive production scales. PLI scheme incentives for manufacturing equipment indirectly pull demand for precision finishing consumables. Tamil Nadu's automotive clusters near Chennai adopt ceramic-grade formulations for export-qualified supplier programs.
Paper-Backing Abrasive Adhesive Discs Market Competitive Landscape
European producers anchor the premium tier through integrated mineral supply chains and REACH-compliant formulations; Asian fabricators hold volume positions in cost-optimized alumina segments. Market structure reflects a bifurcated pattern: consolidated leadership in certified automotive supply chains coexists with fragmented competition in construction and DIY channels. Three archetypes dominate—vertically integrated mineral-to-disc manufacturers, specialized dust-extraction system partners, and broad-line distributors spanning multiple industrial verticals. Capacity expansion in ceramic grain production and strategic partnerships with orbital sander OEMs represent the dominant competitive vectors.
Among European-based integrated manufacturers, Saint-Gobain and Klingspor occupy positions exemplifying mineral supply chain control and multi-channel breadth respectively. Mirka anchors Nordic market presence through dust-extraction-compatible system positioning. These three entities represent distinct strategic archetypes: captive raw material security, geographic diversification across Central European construction and metalworking channels, and sanding ecosystem integration rather than standalone consumable supply.
| Leading Market Players |
|---|
| 3M |
| Saint-Gobain |
| Mirka |
| sia Abrasives Industries AG |
| Sunmight USA Corporation |
| Norton Abrasives |
| Klingspor |
| Carborundum Universal |
| Hermes Abrasives |
| Others |
Value Network & Pricing Analysis
Captive mineral supply chains anchor Saint-Gobain's cost positions in European automotive programs, allowing premium ceramic-grade pricing while competitors absorb volatile alumina spot markets. This integration choice insulates margin structures from kraft paper substrate swings that compress pricing power for non-integrated fabricators serving construction channels.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for commodity alumina discs, forcing European producers to emphasize REACH-certified ceramic tiers. Pricing stratifies across premium certified grades for automotive OEMs, standard industrial formulations for metalworking, and economy alumina for construction contractors. Cost compression in the economy tier intensifies as Asian fabricators scale output, while automotive buyers show minimal price sensitivity given robotic sanding downtime costs. Price differentiation hinges on certification documentation burden and vacuum-extraction interface compatibility.
Supply Chain Analysis
Baltic Sea pulp freight costs feed directly into kraft paper substrate economics, amplifying margin pressure when Nordic carbon compliance timelines accelerate. Supply concentrates in Germany for precision ceramic grain engineering, China for volume alumina processing, and Finland for dust-extraction-compatible disc systems. Raw material dependencies span engineered aluminum oxide from integrated smelters, phenolic resin binders subject to ECHA restrictions, and pressure-sensitive adhesives from petrochemical feedstocks. Single-source vulnerability in Nordic pulp supply exposes manufacturers to input cost spikes. Distribution runs through captive direct-sourcing channels for automotive OEMs and fragmented distributor networks for construction trades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory compliance mandates perpetually upgrade installed abrasive bases across automotive and manufacturing verticals. The structural force of tightening dust-emission standards ensures replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Hedge against film-backed substitute encroachment by deepening captive ceramic grain capacity and accelerating REACH-compliant resin binder certification. Film-backed polyester alternatives threaten paper-back share in wet sanding marine and automotive finishing applications. Prioritize backward integration into engineered mineral supply to defend margin structures against volatile spot markets. For New Entrants and Emerging Players: Launch via dust-extraction system partnerships targeting Nordic woodworking equipment OEMs seeking integrated consumable suppliers. The most penetrable white space sits in certified sustainable forestry paper substrates for EU Green Deal-aligned procurement frameworks. Construction contractor channels in Central Europe offer volume entry points with lower certification barriers than automotive supply chains. For Investors and Strategic Acquirers: Roll-up economics work for regional abrasive distributors because automotive direct-sourcing mandates are compressing intermediary margins and forcing consolidation among sub-scale players. The 5-10 year viability window favors targets with embedded quality engineering capabilities serving qualified supplier programs. Watch MEE enforcement intensity in Chinese manufacturing clusters as the inflection signal for compliance-driven upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Resin Reformulation | ECHA binder restrictions force chemistry overhauls for European automotive market access continuity. |
| Ceramic Grain Capacity Expansion | German OEM robotic sanding cells specify self-sharpening crystalline structures for reduced changeover downtime. |
| Dust-Extraction System Partnership | Mirka anchors Nordic share through orbital sander platform integration rather than standalone consumable supply. |
| Sustainable Forestry Certification | EU Green Deal procurement frameworks reward paper substrate sourcing from certified chain-of-custody programs. |
| Automotive Direct-Sourcing Captive Function | Tier-one manufacturers embed quality engineering teams to verify batch traceability before contract renewals. |
Research Methodology
Multiple input streams — structured interviews with automotive procurement directors, abrasive plant managers, and woodworking equipment OEMs; trade data from customs filings and Cefic industry reports; SEC 10-K disclosures from integrated manufacturers — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from ECHA substance restriction databases, EPA workplace silica standard enforcement records, and MEE dust emission inspection protocols. Primary fieldwork captured specification dynamics in German automotive supply chains and Nordic dust-extraction system integrations.
Data-stream reconciliation across product type, material grade, application intensity, and end-user procurement sophistication enabled granular volume and value modeling throughout the forecast period. CAGRs were derived from segment-level growth differentials weighted by automotive certification upgrade cycles and construction channel replacement rates. Industry-specific forecast inputs included robotic sanding cell adoption curves and REACH reformulation investment timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ECHA binder restriction acceleration or Baltic pulp supply disruptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Nigeria Tile Adhesive Market
Adhesives & Sealants
Malaysia Adhesives and Sealants Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
Thailand Adhesives and Sealants Market
Adhesives & Sealants
Global Human Fibrin Glue Market
Adhesives & Sealants
Vietnam Construction Chemicals Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Middle-East and Africa Acrylic Adhesives Market
Adhesives & Sealants
Acrylates Copolymer Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market
Adhesives & Sealants
Solvent-Borne Adhesives Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
North America Epoxy Curing Agents Market