
 Spray Glue Market | 2026-2036
Spray Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Spray Glue Market Analytics
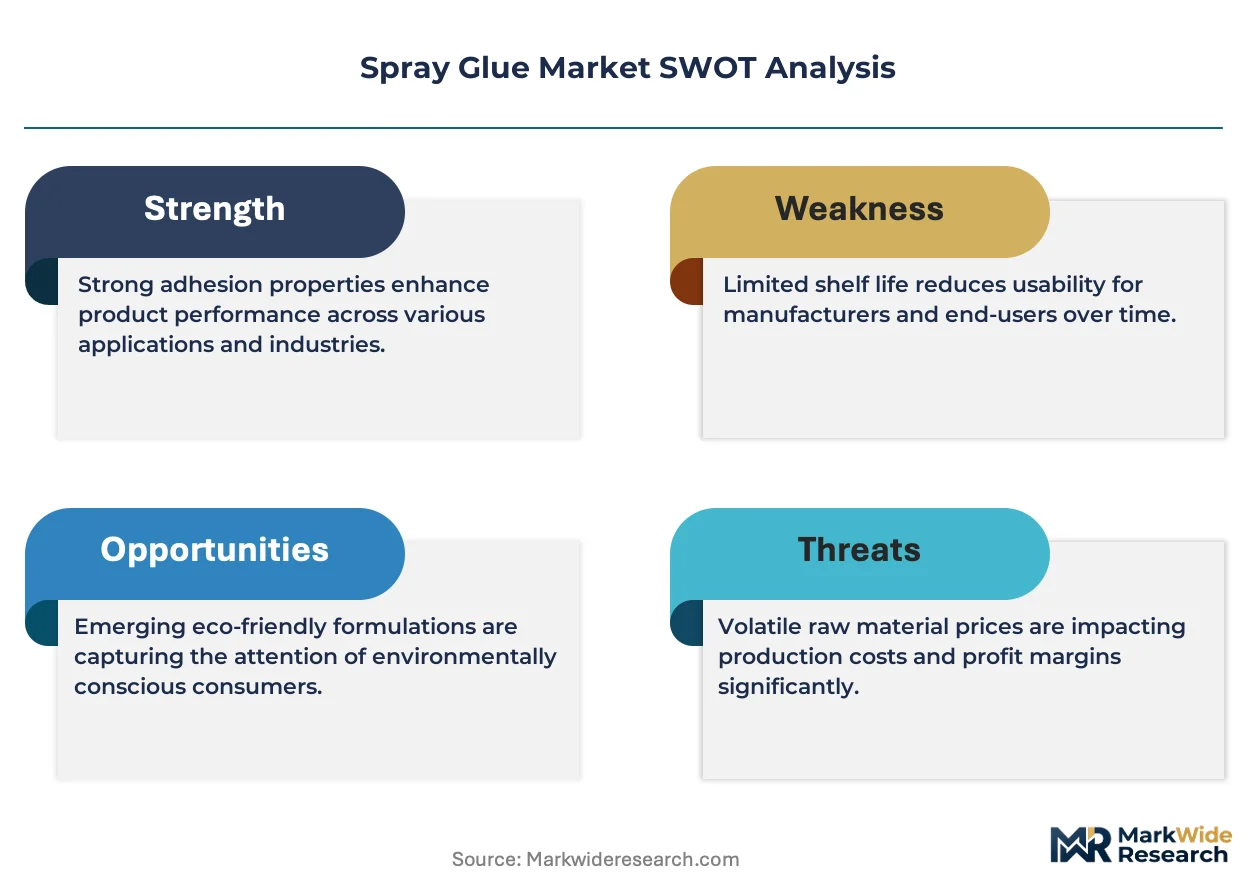
REACH is hardening the cost-of-entry calculus for spray adhesive manufacturers targeting European markets. Henkel AG & Co. KGaA leverages its captive resin synthesis capabilities to absorb compliance costs internally. 3M sustains technology leadership through fluoropolymer barrier coatings that reduce solvent emissions. H.B. Fuller Company anchors its position in North American woodworking with hot-melt spray systems that bypass solvent regulations entirely.
Spray glue comprises aerosol-dispensed adhesive formulations, typically containing synthetic elastomers or acrylic polymers suspended in hydrocarbon propellant blends with viscosities ranging from 50 to 500 centipoise for controlled tack development. The product serves industrial bonding, temporary positioning, and decorative assembly where liquid adhesive application proves impractical. Acrylic adhesives dominate automotive interior assembly due to their resistance to plasticizer migration from vinyl substrates. Polyurethane adhesives represent the fastest-expanding category in construction, driven by structural bonding of engineered wood products and insulated panel systems. Rubber adhesives remain mature in craft and household segments where repositionability and low cost outweigh performance demands.
The EPA regulates volatile organic compound emissions under 40 CFR Part 59, while OSHA enforces permissible exposure limits for hexane and toluene in manufacturing facilities; ISO 10993 governs biocompatibility for medical device bonding applications. These frameworks compel manufacturers to validate alternative propellant chemistries and document workplace exposure controls. Stakeholders must monitor evolving state-level air quality regulations and decide whether to centralize formulation compliance in dedicated regional facilities or distribute reformulation costs across existing plant networks.
Market Dynamics
REACH compliance in Europe is compressing formulation margins while simultaneously rewarding manufacturers with captive resin synthesis capabilities, creating a bifurcation between integrated compounders and formulation-dependent competitors.
Growth Catalysts
- Automotive lightweighting mandates:Assembly plants in Germany and the US Midwest are expanding spray adhesive use for bonding composite panels and interior trim, replacing mechanical fasteners to reduce vehicle mass.
- 40 CFR Part 59 reformulation:EPA volatile organic compound regulations are accelerating water-based and low-emission propellant development, opening compliance-premium pricing tiers for early movers.
- Engineered wood construction:Structural insulated panel manufacturers in the Pacific Northwest and Scandinavian timber clusters are adopting polyurethane spray systems for field assembly speed.
Market Restraints
- Hydrocarbon propellant cost volatility:Liquefied petroleum gas feedstock prices track crude oil benchmarks, compressing gross margins for aerosol-dependent product lines during energy price spikes.
- Isocyanate supply concentration:Polyurethane adhesive precursors concentrate among German and Chinese chemical conglomerates, creating single-source vulnerability for North American formulators.
- Hot-melt spray substitution:Solvent-free hot-melt systems are displacing conventional spray glues in woodworking and packaging applications where equipment capital is available.
Strategic Opportunities
- Medical device bonding certification:ISO 10993 biocompatibility validation opens surgical instrument and wearable device assembly segments with pricing multiples above industrial grades.
- India manufacturing clusters:PLI scheme incentives for electronics and automotive assembly are creating first-mover advantages for adhesive suppliers establishing local formulation capacity.
- Fluoropolymer barrier coatings:Convergence of aerosol technology with low-permeability film deposition is enabling solvent emission reductions without reformulating adhesive chemistry.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in rheology modification and propellant compatibility is concentrating among aging technical workforces in Midwestern US and German industrial regions.
- Dual validation timelines:Simultaneous EPA 40 CFR Part 59 and REACH dossier submissions require 18-24 month compliance cycles, freezing product pipeline velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spray Glue Market |
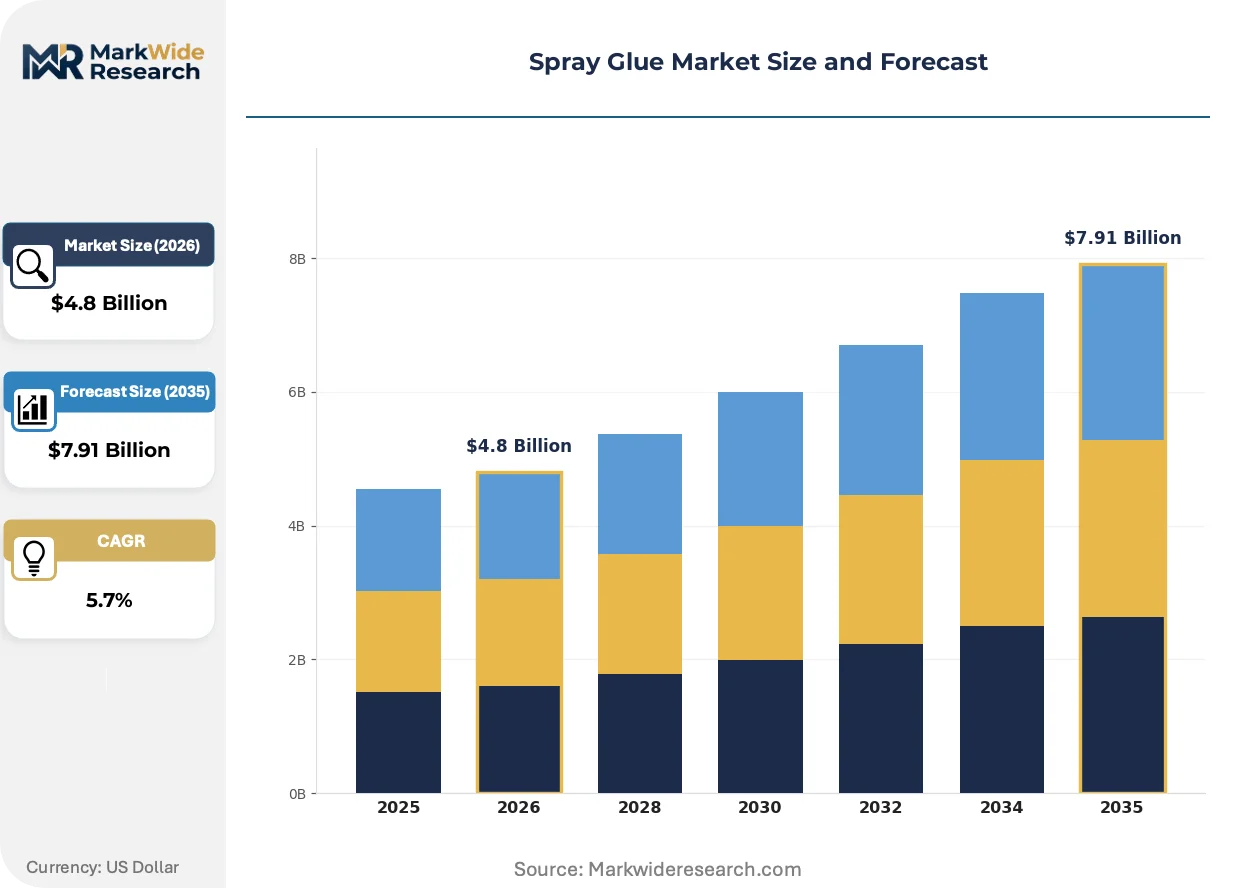
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic Adhesive, Rubber Adhesive, Polyurethane Adhesive, Silicone Adhesive Application: Woodworking, Automotive, Construction, Crafts End User: Households, Manufacturing Units, Educational Institutions, Hobbyists Sales Channel: Online Retail, Specialty Stores, Supermarkets, Distributors |
| Companies Covered | 3M, Henkel AG & Co. KGaA, H.B. Fuller Company, Arkema Group, Sika AG, Avery Dennison Corporation, Illinois Tool Works, Bostik, Kissel+Wolf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spray Glue Market Evolving Landscape
Robotic dispensing integration and propellant chemistry substitution are compressing application labor costs while regulatory frameworks fragment across major manufacturing jurisdictions.
Precision robotic spray systems are automating adhesive deposition in automotive final assembly lines, eliminating manual application variability. Tier 1 suppliers in Stuttgart and Detroit are retrofitting existing paint booths with coordinated motion platforms at 12-18 month payback thresholds. This automation is compressing skilled technician headcount requirements while tightening bond-line consistency specifications.
REACH Annex XVII restrictions on volatile organic compounds are forcing reformulation investments across European production networks. ECHA substance evaluation cycles are extending registration timelines for novel propellant candidates, advantaging incumbents with existing dossier portfolios. German industrial manufacturers are responding by consolidating specification approvals around pre-certified adhesive platforms to reduce supplier qualification burden.
Direct procurement from compounders is displacing distribution intermediaries in high-volume automotive and construction segments. Tier 1 buyers in Bavaria and Michigan are establishing vendor-managed inventory programs with annual volume commitments. This channel compression is most visible in polyurethane construction adhesives, where project-scale orders now bypass regional distributors entirely.
Spray Glue Market Segmentation
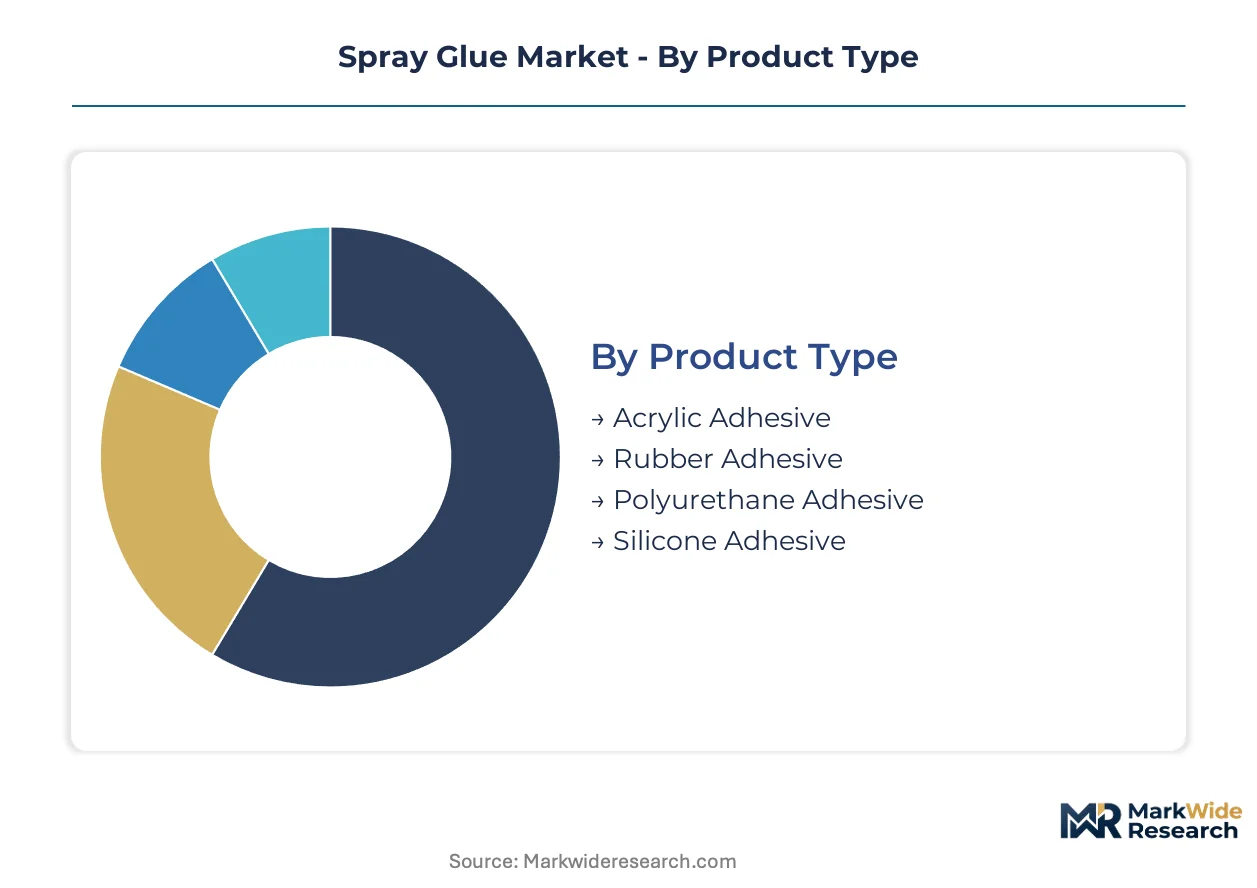
Spray glue segmentation reveals divergent margin structures across chemistry platforms and distribution channels. Product type concentration among integrated resin manufacturers shapes competitive access, while application fragmentation creates divergent compliance burdens across automotive, construction, and consumer segments.
Product Type:
Supply concentration in polymer feedstocks concentrates margin capture among captive resin producers in Germany and the US Gulf Coast.
- Acrylic Adhesive:Formulations based on methyl methacrylate and butyl acrylate copolymers deliver plasticizer resistance critical for vinyl substrate bonding. Automotive interior assembly plants in Stuttgart and Detroit specify acrylic systems for dashboard lamination and headliner attachment, where migration resistance prevents surface degradation over vehicle lifetime.
- Polyurethane Adhesive:Two-component systems combining polyol resins with isocyanate hardeners achieve structural bond strengths exceeding wood substrate failure limits. Construction crews in Pacific Northwest timber clusters and Scandinavian engineered wood facilities deploy polyurethane spray systems for structural insulated panel field assembly, compressing installation timelines versus mechanical fastening.
- Rubber Adhesive:Natural and synthetic elastomer formulations suspended in hydrocarbon solvents provide repositionable tack for temporary bonding applications.
- Silicone Adhesive:Cross-linked polysiloxane chemistry delivers temperature resistance spanning automotive underhood to electronics potting applications.
Today's leader: Acrylic Adhesive. Tomorrow's challenger: Polyurethane Adhesive.
Application:
Cost tier stratification separates specification-grade industrial applications from price-sensitive consumer segments, with compliance costs widening the gap.
- Automotive:Lightweighting mandates from NHTSA fuel economy standards and EU CO2 regulations drive spray adhesive substitution for mechanical fasteners in composite panel bonding. Assembly plants in Michigan and Bavaria specify low-VOC formulations meeting 40 CFR Part 59 and REACH Annex XVII limits, with qualification cycles locking in supplier relationships for platform generations.
- Construction:Field assembly speed requirements favor polyurethane spray systems over cartridge adhesives in timber frame and panelized construction. Building code adoption of mass timber standards in Washington, Oregon, and British Columbia creates specification pull for structural bonding systems with documented load-bearing capacity.
- Woodworking:Cabinet and furniture manufacturers balance solvent emission compliance against capital constraints limiting hot-melt spray equipment adoption.
- Crafts:Repositionability and low odor drive formulation preferences in educational and hobbyist settings where ventilation is limited.
Automotive commands premium pricing. Construction is gaining share fastest.
End User:
Volume concentration among manufacturing units enables direct procurement bypassing distribution markup, while fragmented household demand sustains retail channel infrastructure.
- Manufacturing Units:Tier 1 automotive suppliers and construction material producers negotiate annual volume commitments with vendor-managed inventory terms. Plants in industrial clusters around Detroit, Stuttgart, and Shanghai consolidate specification approvals to reduce supplier qualification overhead, favoring adhesive platforms with pre-certified regulatory dossiers.
- Households:Consumer purchasing concentrates in home improvement retail and e-commerce channels, with price sensitivity limiting formulation complexity to single-component, low-VOC systems.
- Educational Institutions:Bulk procurement through district-level contracts prioritizes safety certification and low-odor formulations for classroom use.
- Hobbyists:Specialized retailers serve model building and craft segments with precision-application formats and archival-quality adhesives.
Manufacturing Units dominate volume. Households represent margin expansion opportunity.
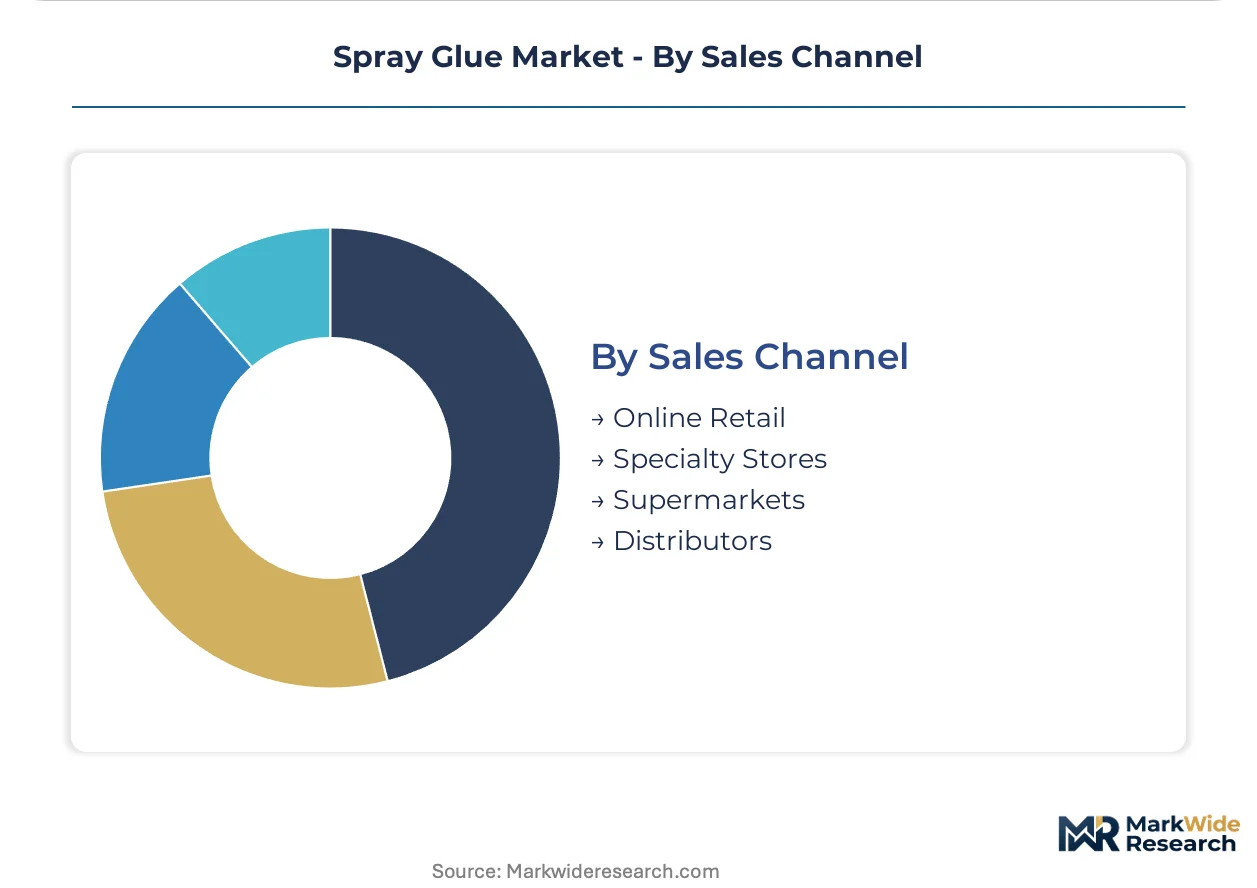
Sales Channel:
Customer type fragmentation across industrial procurement teams and individual consumers forces parallel channel strategies with divergent service requirements.
- Distributors:Regional industrial distributors maintain technical sales capabilities and local inventory for just-in-time manufacturing supply. Midwest US and German distribution networks concentrate polyurethane adhesive stocking points near automotive and construction manufacturing clusters, with application engineering support justifying margin capture versus direct procurement.
- Online Retail:E-commerce platforms aggregate fragmented household and small commercial demand, with search visibility and review dynamics determining SKU success. Amazon and specialized adhesive retailers compete on shipping speed and technical content depth for DIY project customers.
- Specialty Stores:Hobby and craft retailers provide hands-on product demonstration and project-specific guidance.
- Supermarkets:Mass retail placement reaches occasional-use consumers with limited brand loyalty and price-driven selection.
Distributors retain industrial lock-in. Online Retail is eroding consumer channel share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with specialized expertise in rheology modification and propellant compatibility concentrate in Midwestern US industrial corridors and German manufacturing regions, anchoring innovation capacity in these geographies.
United States
Automotive lightweighting mandates from NHTSA fuel economy standards drive spray adhesive substitution for mechanical fasteners in Michigan assembly plants. EPA 40 CFR Part 59 regulates volatile organic compound emissions, accelerating water-based propellant development. Detroit and Stuttgart industrial clusters specify low-VOC formulations with qualification cycles locking in supplier relationships for platform generations.
Germany
REACH Annex XVII restrictions on volatile organic compounds force reformulation investments across European production networks. ECHA substance evaluation cycles extend registration timelines for novel propellant candidates. Bavarian automotive manufacturers consolidate specification approvals around pre-certified adhesive platforms to reduce supplier qualification burden.
China
Dual carbon goals under MEE supervision compress hydrocarbon propellant use in manufacturing facilities. GB standards govern aerosol product safety and environmental compliance. Yangtze River Delta electronics assembly clusters adopt spray adhesives for device bonding as domestic automotive production scales.
India
PLI scheme incentives for electronics and automotive assembly create first-mover advantages for adhesive suppliers establishing local formulation capacity. BIS certification requirements shape product entry protocols. Maharashtra and Gujarat manufacturing corridors attract regional formulation facilities to serve domestic OEM demand.
Japan
METI industrial standards emphasize low-emission manufacturing processes in chemical production. JIS standards govern adhesive performance specifications for automotive and electronics applications. Kanto region precision manufacturers specify spray systems for electronics assembly where bond-line consistency requirements exceed manual application tolerances.
Spray Glue Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated resin manufacturers with captive feedstock capabilities, formulation specialists serving specification-grade industrial segments, and regional compounders competing on price in consumer and craft applications. Dominant competitive moves include backward integration into resin synthesis to absorb regulatory compliance costs, and geographic expansion through local formulation licensing to bypass import tariff exposure.
Among diversified chemical conglomerates, 3M and Henkel AG & Co. KGaA exemplify integrated players with captive technology portfolios. H.B. Fuller Company occupies a position within the specialty formulation tier. These three anchors represent divergent strategic postures: technology leadership through barrier coating innovation, compliance absorption through internal resin production, and segment focus through solvent-free system development.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Arkema Group |
| Sika AG |
| Avery Dennison Corporation |
| Illinois Tool Works |
| Bostik |
| Kissel+Wolf GmbH |
| Others |
Value Network & Pricing Analysis
Hydrocarbon propellant feedstock costs transmit directly from crude oil benchmarks through formulation margins to end-user pricing tiers, with automotive buyers in Stuttgart and Detroit absorbing premium grades while household segments face economy-tier compression.
Pricing Analysis
Bundled technical service contracts separate specification-grade automotive supply from unbundled commodity transactions in consumer channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification burden and volume commitment, with REACH-compliant formulations commanding premium positioning. Price erosion runs through craft and household tiers as private-label competition intensifies. Manufacturing units demonstrate lowest price sensitivity due to qualification lock-in, while hobbyist segments exhibit acute elasticity to unit cost shifts.
Supply Chain Analysis
Freight cost volatility from Middle East petrochemical feedstocks and Asia-Pacific isocyanate origins compress margins for North American formulators lacking captive resin capabilities. Supply concentrates in Germany, China, and the US Gulf Coast for polymer precursors, with propellant blending anchored in regional aerosol manufacturing clusters. Raw material dependencies span liquefied petroleum gas, methylene diphenyl diisocyanate, and acrylic monomer streams. Single-source vulnerability for polyurethane hardeners creates procurement risk. Distribution runs through vendor-managed inventory programs for automotive Tier 1 suppliers and regional industrial distributors for mid-volume construction accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spray glue market functions as a stable compounder anchored by automotive lightweighting mandates that perpetuate specification-grade demand across vehicle platform cycles.
For Market Incumbents: Hedge against hot-melt spray substitution in woodworking by accelerating water-based propellant certification under EPA 40 CFR Part 59. Deepen backward integration into acrylic resin synthesis to internalize REACH compliance costs and protect margin structure from hydrocarbon feedstock volatility.
For New Entrants and Emerging Players: Capture white-space opportunity in Indian electronics assembly corridors under PLI scheme incentives, where domestic formulation capacity gaps persist. Target medical device bonding segments requiring ISO 10993 validation, as pricing multiples exceed industrial grades and incumbent qualification burdens deter rapid response.
For Investors and Strategic Acquirers: Roll-up economics work for regional compounders with captive propellant blending assets because regulatory fragmentation across EPA, REACH, and GB standards fragments scale advantages and rewards local compliance infrastructure. Monitor ECHA substance evaluation timelines as inflection signal for propellant chemistry substitution windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Henkel and 3M absorb REACH compliance costs through captive polymer production capabilities. |
| Water-Based Propellant Development | EPA 40 CFR Part 59 reformulation opens compliance-premium pricing tiers for early movers. |
| Medical Device Certification Investment | ISO 10993 validation unlocks surgical instrument assembly with pricing multiples above industrial grades. |
| Regional Formulation Licensing | Local capacity in Maharashtra and Gujarat bypasses import exposure and BIS certification delays. |
| Robotic Dispensing Integration | Stuttgart and Detroit assembly plants achieve 12-18 month payback through bond-line consistency gains. |
Research Methodology
Direct dialogue with adhesive formulation chemists, automotive Tier 1 procurement directors, construction material distributors, and regulatory compliance officers grounded qualitative findings in operational reality. Secondary validation drew from EPA 40 CFR filings, ECHA registration dossiers, ACC industry statistics, and customs trade data for polymer feedstock flows. Bottom-up and top-down triangulation reconciled plant-level capacity assessments with macro consumption trends.
Top-down modeling anchored aggregate market sizing while bottom-up segmentation by chemistry platform, application vertical, and end-user category validated granular projections across the analysis window. CAGRs derived from regression against automotive production forecasts, construction spending indices, and regulatory phase-in timelines. Modeled inputs included hydrocarbon propellant price elasticity, REACH compliance cost pass-through rates, and hot-melt substitution penetration curves.
Underlying measurement precision varies by segment; automotive and construction applications carry tighter precision than fragmented household consumption. Forecasts reflect documented assumptions about regulatory enforcement intensity and feedstock cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific Flock Adhesives Market
Adhesives & Sealants
Dispersion Adhesives Market
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
Epoxy Glue Market
Adhesives & Sealants
South America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Malaysia Sealants Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
US Adhesives and Sealants Market
Adhesives & Sealants
Roofing Adhesive Market
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
US Pressure Sensitive Adhesives Market