
 Middle-East and Africa Reactive Adhesives Market | 2026-2036
Middle-East and Africa Reactive Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Reactive Adhesives Market Foresight
UV-curable adhesive chemistry is tilting manufacturing workflows toward faster cure cycles and reduced volatile organic compound footprints. Henkel AG & Co. KGaA leverages its European R&D base to sustain technology leadership in radiation-cured systems for electronics assembly across North African contract manufacturers. Sika AG anchors its regional position through construction-specialized epoxy and polyurethane portfolios tailored to Gulf megaproject specifications. Dow competes on manufacturing scale, operating integrated resin production that controls raw material cost volatility for structural bonding applications.
Reactive adhesives are thermosetting polymer systems that cure through chemical cross-linking reactions triggered by heat, moisture, radiation, or catalyst exposure, typically achieving lap shear strengths exceeding 15 MPa in structural epoxy formulations. These materials bond dissimilar substrates—metals, composites, ceramics, and engineered plastics—where mechanical fastening fails or adds unacceptable weight. Epoxy formulations dominate structural applications in automotive and construction sectors due to superior thermal resistance and load-bearing performance. Polyurethane adhesives lead growth in flexible bonding and sealing applications where substrate movement tolerance and impact resistance prove critical. Water-based technology remains marginal in the region due to ambient humidity challenges and slower cure kinetics, while UV-cured systems capture share in electronics potting and precision coating lines.
Saudi Standards, Metrology and Quality Organization technical regulations and South African Bureau of Standards adhesive performance classifications shape product compliance requirements for market access across the region. ECHA REACH substance restrictions and EU Green Deal carbon border adjustment mechanisms exert extraterritorial pressure on formulation chemistry for exporters serving European-linked supply chains. Stakeholders must monitor regulatory divergence between Gulf harmonization initiatives and sub-Saharan national standards regimes when configuring regional product portfolios and certification investments.
Market Dynamics
Gulf megaproject procurement is compressing cure-cycle requirements and forcing reformulation toward rapid-setting epoxy and polyurethane systems that withstand desert thermal cycling.
Growth Catalysts
- NEOM and Qiddiya infrastructure pipelines:Saudi Arabia's giga-project construction schedules demand structural bonding systems with 24-hour full-load-bearing capacity, pulling advanced two-part epoxy formulations into specification.
- SASO technical regulation harmonization:Unified Gulf standards for construction adhesive performance are eliminating redundant certification costs and accelerating product registration across Bahrain, Oman, and Kuwait.
- UV-curable electronics potting:North African contract manufacturers serving European automotive tier-1 suppliers are retrofitting coating lines with mercury-arc and LED-cure systems for smartphone and sensor assembly.
Market Restraints
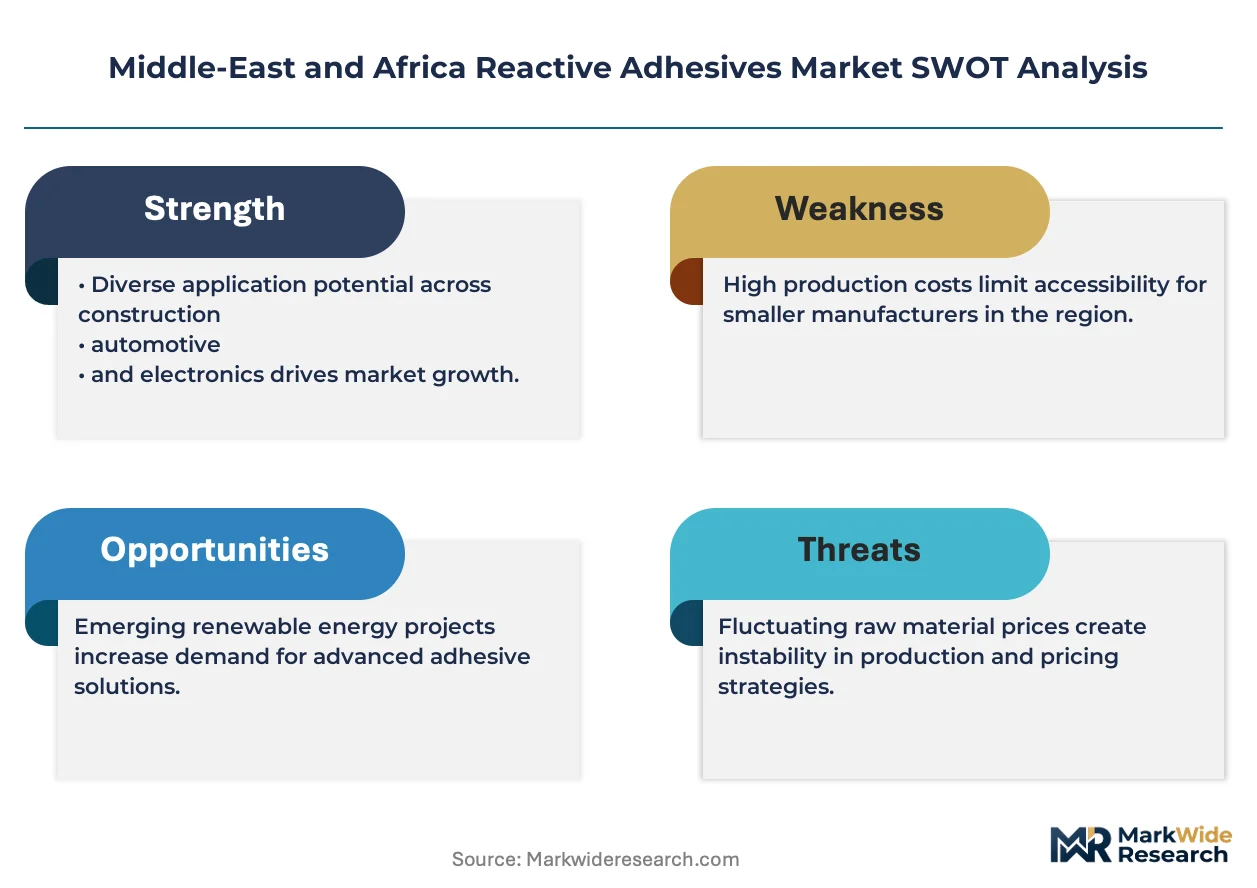
- Petrochemical feedstock volatility:Epoxy resin production depends on bisphenol-A and epichlorohydrin derived from propylene and benzene supply chains concentrated in the Arabian Gulf, exposing formulators to input cost swings.
- REACH substance restrictions:ECHA candidate list updates on isocyanates and certain amine hardeners are blocking formulation exports to EU-linked supply chains unless hazard classifications are re-engineered.
- Ambient humidity cure inhibition:Water-based polyurethane dispersions face technical limitations in coastal Red Sea and Indian Ocean climates where year-round humidity exceeds 70 percent, slowing surface drying and bond development.
Strategic Opportunities
- Ethiopian and Kenyan manufacturing zones:Textile and leather processing clusters in the East African Community are underpenetrated by reactive adhesive suppliers, creating first-mover positioning for footwear and automotive interior bonding specialists.
- EU Green Deal carbon border adjustments:Low-carbon epoxy formulations using bio-based hardeners and recycled content feedstocks will capture preferential access to European markets as CBAM phase-in expands to cover chemical imports.
- Hybrid cyanoacrylate-epoxy systems:Converging instant-fix and structural-load technologies are opening precision assembly applications in medical device and electronics repair channels previously served by mechanical fastening.
Industry Challenges
- Formulation chemist scarcity:The region lacks sufficient technical talent trained in thermoset polymer rheology and substrate-specific adhesion science, forcing suppliers to import R&D capacity from European or Asian facilities.
- SASO and SABS dual certification timelines:Parallel conformity assessment processes for Gulf and South African market access extend product launch cycles by 8-14 months, delaying revenue realization.
- Legacy solvent-based inventory:Distributors and applicators hold substantial stocks of high-VOC adhesive systems that must be depleted before low-emission replacements can achieve volume scale, creating channel conflict.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Reactive Adhesives Market |
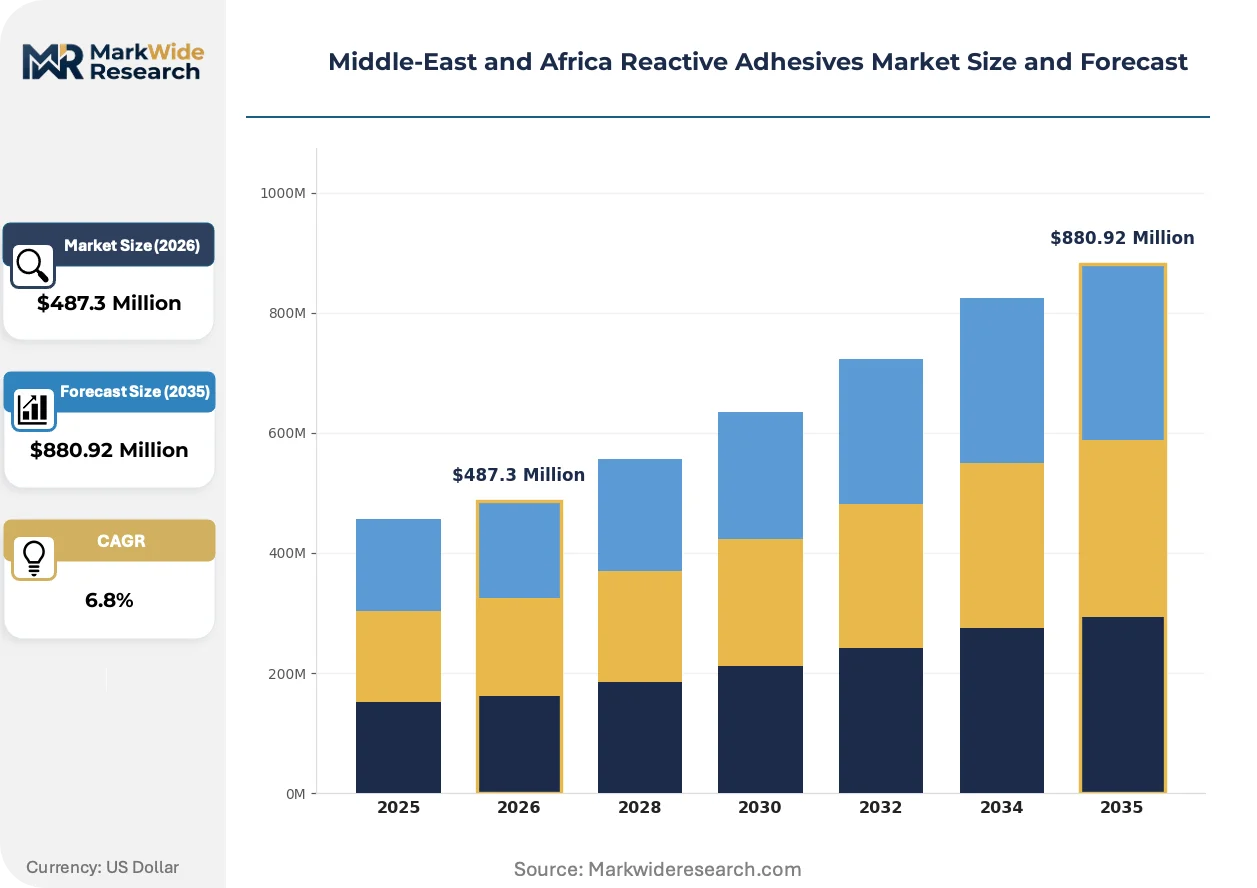
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
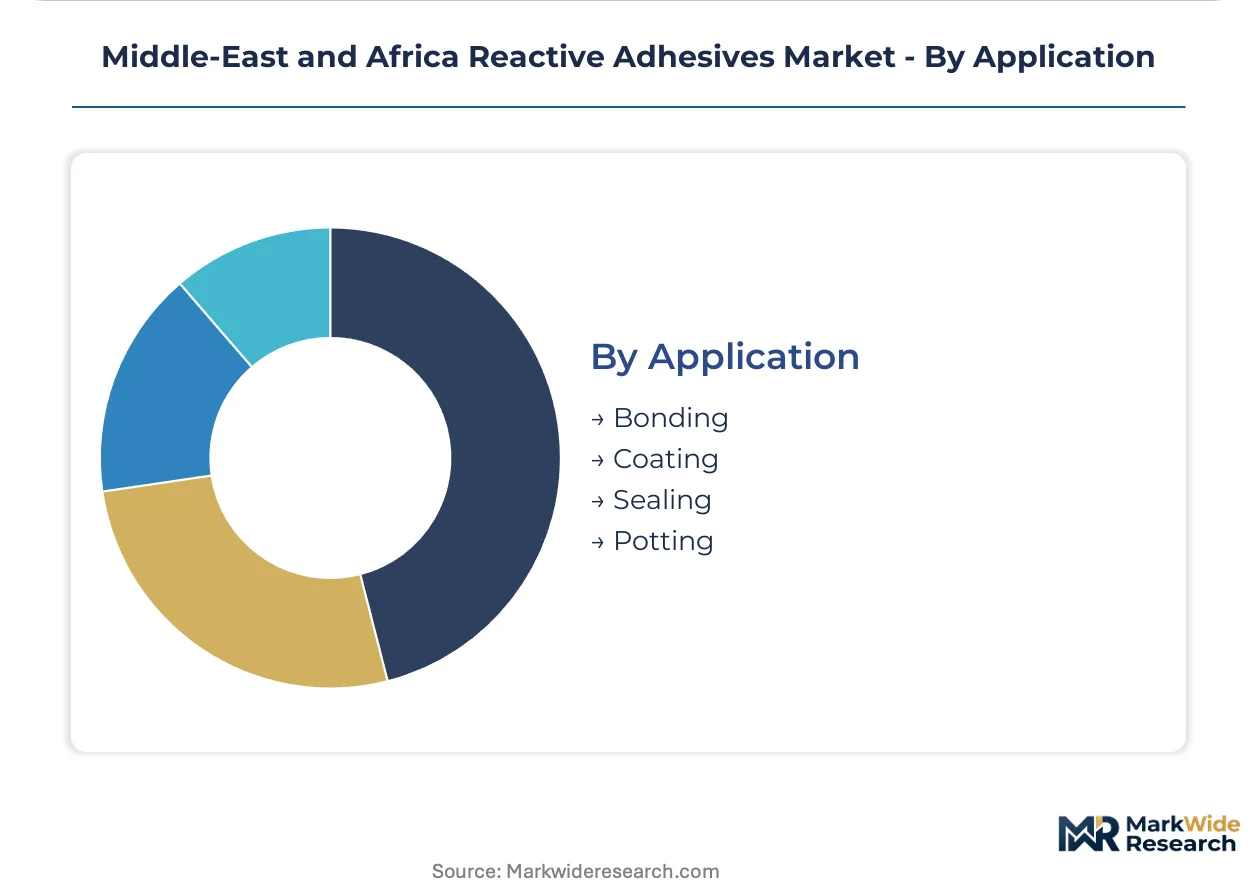
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylate End User: Automotive, Construction, Electronics, Packaging Technology: Hot Melt, Solvent-Based, Water-Based, UV-Cured Application: Bonding, Coating, Sealing, Potting |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Sika AG, Arkema Group, H B Fuller Company, Dow, Huntsman International LLC, Avery Dennison Corporation, Jowat SE, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Reactive Adhesives Market Shifts & Advancements
Formulation chemistry is pivoting toward radiation-cure and moisture-stable systems that eliminate thermal processing steps and expand bonding latitude in uncontrolled field environments.
Dual-cure epoxy-acrylate hybrid chemistry is collapsing the distinction between factory-controlled and on-site adhesive application. Saudi precast concrete producers and UAE aluminum facade installers are adopting these systems to achieve tack-free handling within minutes while building ultimate structural strength over 24 hours. The technology is collapsing capital requirements for heated curing infrastructure across Middle Eastern construction sites.
ECHA REACH restriction proposals on aromatic amine hardeners and certain isocyanate prepolymers are forcing reformulation investments. Industrial consequence includes accelerated migration to aliphatic amine and cycloaliphatic alternatives with equivalent thermal performance but modified handling protocols. Construction adhesive portfolios serving European-linked supply chains are most affected, with Gulf-based formulators establishing dedicated low-hazard product lines.
Specification-driven procurement consolidation is compressing supplier rosters at major Gulf contractors. Saudi Binladin Group and UAE-based Arabtec procurement departments are reducing approved vendor lists from 15-20 adhesive suppliers to 4-6 strategic partners with full technical service capability. This pattern is most visible in structural glazing and cladding installation contracts where single-source accountability for bond failure liability has become non-negotiable.
Middle-East and Africa Reactive Adhesives Market Segmentation
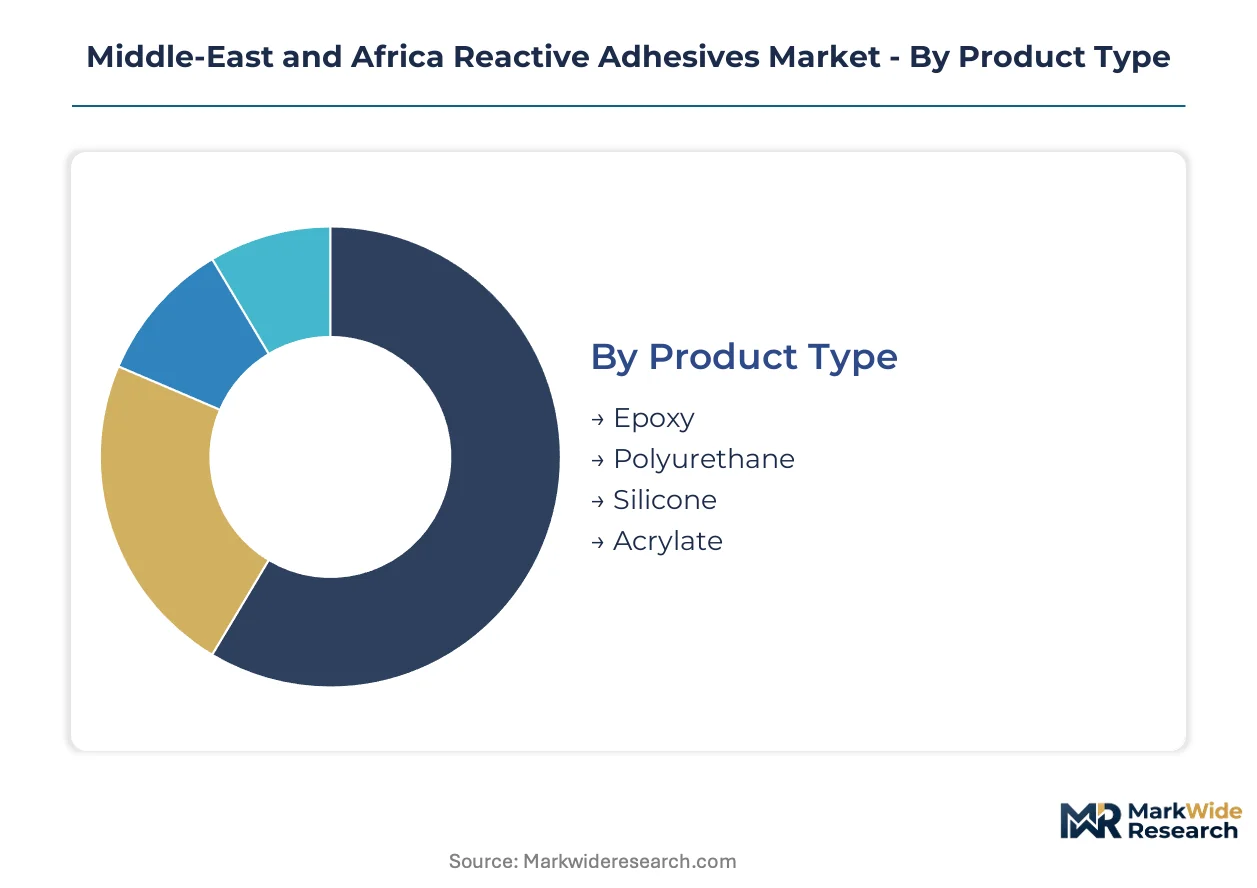
Reactive adhesive procurement patterns across the Middle-East and Africa diverge sharply by substrate requirements, cure conditions, and regulatory exposure. Understanding these segment boundaries enables suppliers to align formulation investments with concentrated demand pockets in Gulf construction and North African electronics manufacturing.
Product Type:
Mature structural chemistries dominate Gulf megaproject procurement, while emerging flexible systems capture automotive interior and electronics potting applications.
- Epoxy:Two-part thermosetting systems built from bisphenol-A and epichlorohydrin precursors deliver lap shear strengths exceeding 15 MPa for load-bearing structural joints. Saudi NEOM and Qiddiya infrastructure pipelines specify rapid-setting epoxy formulations with 24-hour full-load-bearing capacity, pulling advanced systems into construction procurement.
- Polyurethane:Isocyanate-terminated prepolymers cure through moisture reaction to form flexible bonds tolerating substrate movement and thermal cycling. UAE aluminum facade installers and Saudi precast concrete producers favor these systems for cladding and panel bonding where impact resistance and elongation prove critical.
- Silicone:Condensation-cure polysiloxane chemistry provides temperature stability from -50°C to 200°C for sealing applications in Saudi petrochemical facilities and UAE solar installations.
- Acrylate:Free-radical polymerization systems cure under UV or visible light exposure for electronics potting and precision coating lines serving North African contract manufacturers.
Epoxy handles the majority of throughput; acrylate is the fastest mover on share.
End User:
Construction procurement volumes anchor regional demand, though automotive and electronics segments command premium pricing for specification-grade formulations.
- Automotive:Structural bonding of aluminum body-in-white assemblies and carbon fiber reinforced polymer components reduces mechanical fastening weight. Moroccan and South African vehicle assembly plants specify epoxy and polyurethane systems for crash-resistant joints.
- Construction:Structural glazing, cladding installation, and precast concrete panel bonding consume the largest formulation volumes across Gulf Cooperation Council member states. Saudi Binladin Group procurement consolidation is compressing supplier rosters to 4-6 strategic partners with full technical service capability.
- Electronics:Smartphone sensor assembly and automotive control module potting drive UV-curable acrylate demand in Tunisian and Egyptian contract manufacturing zones.
- Packaging:Flexible film lamination and carton sealing applications favor hot melt and water-based systems, though humidity challenges limit water-based penetration in coastal Red Sea climates.
Construction commands the dominant share of volume; electronics is climbing the fastest on specification intensity.
Technology:
Cure mechanism selection hinges on line speed requirements, VOC exposure limits, and ambient environmental control availability.
- Hot Melt:Thermoplastic polymer systems applied molten and solidifying on cooling deliver instant handling strength for packaging and woodworking applications. Ethiopian and Kenyan textile processing clusters favor these systems for footwear bonding where equipment simplicity outweighs ultimate thermal resistance.
- Solvent-Based:Solutions of reactive polymers in organic carriers provide long open times and excellent substrate wetting for difficult-to-bond surfaces. Legacy inventory stocks in regional distributor channels create transition friction toward low-emission alternatives.
- Water-Based:Polyurethane dispersions and epoxy emulsions reduce VOC exposure but face cure inhibition in coastal Red Sea and Indian Ocean climates where ambient humidity exceeds 70 percent year-round.
- UV-Cured:Photoinitiator-accelerated acrylate and epoxy-acrylate hybrid systems achieve tack-free cure in seconds under mercury-arc or LED exposure. North African electronics manufacturers retrofit coating lines to meet European automotive tier-1 supplier specifications.
Solvent-based technology still handles substantial legacy volume; UV-cured systems are gaining share fastest on line speed advantages.
Application:
Functional requirements determine formulation viscosity, cure profile, and performance specification stringency.
- Bonding:Structural load transfer between dissimilar substrates—metals, composites, ceramics, engineered plastics—where mechanical fastening fails or adds unacceptable weight. Saudi megaproject specifications demand 24-hour full-load-bearing capacity for structural joints.
- Coating:Protective and decorative layers applied to substrates for corrosion resistance, electrical insulation, or aesthetic finish. Electronics potting applications in Tunisia and Egypt specify UV-curable coatings for sensor protection.
- Sealing:Gap-filling and environmental barrier functions accommodating joint movement and thermal expansion. UAE building envelope contractors specify silicone and polyurethane sealants for facade weatherproofing.
- Potting:Encapsulation of electronic components to protect against moisture, vibration, and thermal shock. Automotive control modules and smartphone assemblies drive acrylate and epoxy potting compound demand.
Bonding commands the largest application volume; potting is expanding most quickly on electronics manufacturing growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle-East and Africa reactive adhesives trade flows reflect heavy reliance on imported formulated systems, with Gulf petrochemical feedstock advantages only partially offsetting European and Asian dominance in specialty adhesive manufacturing. Regional formulation capacity concentrates in Saudi Arabia and the UAE, while sub-Saharan markets remain import-dependent for specification-grade products.
Saudi Arabia
NEOM and Qiddiya megaprojects drive structural epoxy consumption for precast concrete panel bonding and facade installation. SASO technical regulations harmonize construction adhesive performance standards across Gulf markets, streamlining product registration. Riyadh-based formulators are expanding two-part polyurethane production to serve domestic infrastructure procurement.
United Arab Emirates
Aluminum cladding and structural glazing contracts in Dubai and Abu Dhabi specify rapid-cure polyurethane systems for high-rise envelope bonding. MOHAP chemical safety protocols align with ECHA REACH substance restrictions for products entering European-linked supply chains. Jebel Ali industrial zone hosts regional blending operations serving re-export markets.
South Africa
Automotive assembly plants in Gauteng and Eastern Cape provinces specify epoxy and polyurethane crash-resistant joints for aluminum body-in-white construction. SABS adhesive performance classifications create compliance barriers for imported formulations lacking local certification. Durban chemical manufacturing clusters are retrofitting for low-VOC water-based polyurethane dispersions.
Egypt
Electronics contract manufacturers in the Suez Canal Economic Zone drive UV-curable acrylate demand for smartphone sensor potting and automotive control module encapsulation. National chemical regulator requirements are converging with EU import standards for European tier-1 supplier qualification. Cairo-Alexandria corridor distributors hold substantial legacy solvent-based inventory awaiting depletion.
Morocco
Automotive interior and footwear manufacturing in Tangier Med and Casablanca clusters favor hot-melt and reactive polyurethane systems for leather bonding and textile lamination. ANSSA chemical safety assessments govern workplace exposure limits in adhesive application facilities. Kenitra Atlantic Free Zone is attracting North African contract manufacturers serving European automotive supply chains.
Middle-East and Africa Reactive Adhesives Market Competitive Landscape
On the supply side, the industry is tiered between integrated multinational chemical conglomerates and regional formulation specialists serving construction and industrial niches. European-headquartered suppliers dominate specification-grade structural adhesives through Gulf megaproject procurement relationships, while Asian manufacturers compete on cost for volume construction applications. Three strategic archetypes define competitive positioning: petrochemical-integrated resin producers controlling raw material economics, construction-specialized formulators with technical service depth, and electronics-focused radiation-cure suppliers. Capacity expansion and portfolio diversification toward low-hazard formulations represent the dominant competitive moves as regulatory pressure intensifies.
Among the disclosed participants, Henkel AG & Co. KGaA and Sika AG exemplify the European formulation leadership archetype, with Henkel representing radiation-cured systems expertise and Sika occupying the construction-specialized position. Dow sits within the integrated petrochemical producer tier, leveraging captive resin production for structural bonding cost control. These three anchors illustrate the competitive structure: technology leadership through European R&D proximity, construction application depth through regional specification relationships, and manufacturing scale through feedstock integration.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Sika AG |
| Arkema Group |
| H B Fuller Company |
| Dow |
| Huntsman International LLC |
| Avery Dennison Corporation |
| Jowat SE |
| Others |
Supply & Pricing Matrix
Petrochemical feedstock volatility concentrated in Arabian Gulf propylene and benzene supply chains compresses margin buffers for epoxy resin formulators while simultaneously widening pricing spreads between integrated producers and import-dependent compounders. This single-source dependency on Gulf petrochemical infrastructure forces buyers into long-term offtake negotiations that stratify procurement costs across specification-grade construction adhesives.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where pricing stratifies across premium, standard, and economy tiers differentiated by certification grade and volume scale. SASO-compliant formulations command measurable premiums over non-certified alternatives in Gulf megaproject procurement. Cost compression in standard-grade epoxy systems is intensifying because Saudi Binladin Group and Arabtec procurement consolidation squeezes mid-tier suppliers. Small-scale Ethiopian and Kenyan textile manufacturers exhibit highest price sensitivity, while European-linked automotive tier-1 suppliers prioritize specification compliance over unit cost.
Supply Chain Analysis
Bisphenol-A and epichlorohydrin precursors draw from integrated petrochemical complexes concentrated in Saudi Arabia, the UAE, and Kuwait, with specialty amine hardeners and isocyanate prepolymers sourcing from German and Belgian chemical manufacturers. Tariff exposure on REACH-restricted substance imports from Europe creates formulation chokepoints for suppliers serving EU-linked supply chains. Distribution runs through Jebel Ali and Riyadh regional blending hubs serving re-export markets across sub-Saharan Africa, with Durban and Cairo-Alexandria corridors handling specification-grade imports for South African and Egyptian manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist scarcity across thermoset polymer rheology and substrate-specific adhesion science constrains regional R&D capacity, forcing suppliers to import technical talent from European or Asian facilities and creating defensive moats for incumbents with established training pipelines.
For Market Incumbents: Insulate specification-grade positions by deepening captive resin production capacity in Saudi Arabia's Jubail industrial zone and accelerating SASO-SABS dual certification investments to compress rival product launch timelines. REACH substance restriction updates on aromatic amine hardeners threaten portfolio viability for European-linked supply chains; establishing dedicated low-hazard product lines in Riyadh-based facilities secures continuity. Channel control through technical service bundling with Gulf megaproject contractors reinforces switching costs against emerging Asian cost competitors. For New Entrants and Emerging Players: East African Community textile and leather processing clusters in Ethiopia and Kenya represent the most penetrable entry point, with footwear bonding and automotive interior applications currently served by high-cost European imports. North African electronics contract manufacturing zones in Tunisia and Egypt offer secondary beachheads where UV-curable acrylate demand outpaces local supply. A technical partnership with European radiation-cure equipment suppliers enables rapid coating line retrofit credibility without proprietary R&D investment. For Investors and Strategic Acquirers: EU Green Deal carbon border adjustment phase-in reshapes the acquisition landscape toward low-carbon epoxy formulators using bio-based hardeners and recycled content feedstocks. Long-term viability over the next decade rests on positioning for preferential European market access as CBAM coverage expands. Vertically integrated Saudi formulators with captive bisphenol-A supply and established Gulf megaproject relationships represent the target archetype. The signal to watch is ECHA candidate list expansion on additional isocyanate classifications, which would accelerate consolidation pressure on hazard-exposed regional portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Production | Captive bisphenol-A supply insulates Saudi formulators from propylene volatility and European import dependency. |
| Dual-Cure Epoxy-Acrylate Hybrid Formulation Launch | Saudi precast concrete producers eliminate heated curing infrastructure capital requirements through rapid tack-free handling. |
| SASO-SABS Harmonized Certification Investment | Parallel Gulf and South African conformity assessment compression accelerates product registration across Bahrain, Oman, and Kenya. |
| Low-Hazard Aliphatic Amine Product Line Expansion | REACH-compliant construction adhesive portfolios maintain European-linked supply chain access amid ECHA restriction proposals. |
| East African Technical Service Partnership | Ethiopian and Kenyan textile clusters gain localized footwear bonding support previously available only through European distributors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with formulation chemists, Gulf megaproject procurement directors, and North African electronics contract manufacturing operations heads; and secondary validation through customs trade data, SASO technical regulation filings, and ECHA REACH substance restriction updates. Plant managers at Saudi and UAE resin production facilities, distribution channel partners in Jebel Ali and Durban, and technical R&D directors at European headquarters provided operational perspective. Bottom-up volume estimates from adhesive consumption by end-use application triangulated against top-down petrochemical feedstock demand models.
Forecast inputs considered cure technology adoption curves, regulatory compliance cost trajectories, and megaproject procurement pipeline visibility across the projection horizon. Segmentation dimensions modeled include product chemistry, end-use industry, cure mechanism technology, and regional production hub. CAGRs derived from intensity-of-use coefficients applied to construction, automotive, and electronics manufacturing output projections, with explicit incorporation of SASO harmonization timeline assumptions and ECHA restriction proposal implementation probabilities.
Practitioners should monitor ECHA candidate list expansion, Gulf petrochemical capacity utilization rates, and East African manufacturing zone investment announcements for early signals of forecast revision. Cross-checking against ACC and Cefic regional chemical output benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Soft Skin Adhesives Market
Adhesives & Sealants
Australia Sealants Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
Anti-Adhesion Products Market
Adhesives & Sealants
Global Engineering Adhesives Market
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
Middle-East and Africa Contact Adhesives Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
Global Electronics Adhesives Market
Adhesives & Sealants
Global Automotive Adhesive Market
Adhesives & Sealants
North America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Global Hygiene Adhesives Market