
 Epoxy Active Diluent Market | 2026-2036
Epoxy Active Diluent Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxy Active Diluent Market Intelligence
Custom formulation support, offered alongside bulk chemical sales, is realigning how end-users procure epoxy active diluents for specific performance targets. Hexion Inc. leverages its extensive product portfolio to serve diverse end-markets like construction and automotive. Huntsman Corporation specializes in high-performance formulations for the demanding aerospace composites sector. Evonik Industries AG positions itself through a focus on specialty additives and sustainable product development to meet stricter environmental mandates.
Epoxy active diluents are reactive, low-viscosity compounds, typically glycidyl ethers, added to epoxy formulations. Their primary function is to reduce the viscosity of the resin system, which enhances flow, improves wetting of substrates, and allows for higher filler loading. Aliphatic diluents dominate volume sales, primarily for their use in large-scale coatings and sealant applications. Glycidyl ethers, a more specialized product type, are critical for high-performance composites where maintaining thermal and mechanical properties is paramount for the electronics and aerospace end-user segments.
Regulations from Europe's ECHA under REACH and the US EPA's rules on volatile organic compounds (VOCs) steer product development toward safer, lower-emission diluents. In parallel, China's MEE enforces stringent environmental standards that impact manufacturing processes and raw material sourcing for chemical producers. Suppliers must now decide whether to invest in bio-based alternatives or focus on optimizing existing chemistries to meet evolving global compliance demands.
Market Dynamics
The central force shaping the epoxy active diluent market is the global regulatory mandate for lower volatile organic compound (VOC) emissions. This pressure from bodies like the US EPA and Europe's ECHA dictates product innovation, raw material selection, and market access.
Growth Catalysts
- Aerospace Composites Advancement:The aerospace sector's push for lightweight, high-strength materials drives demand for specialized glycidyl ethers that reduce viscosity without compromising the thermal or mechanical integrity of advanced composite structures.
- Stringent Environmental Regulations:Rules on VOCs from the US EPA and Europe's REACH framework compel coatings and adhesives formulators to replace traditional solvents with reactive diluents, directly boosting consumption in these large-volume segments.
- Electronics Miniaturization:The continuous trend of smaller, more powerful electronic devices requires epoxy encapsulants with superior flow and wetting properties, a performance characteristic directly enhanced by the use of specific active diluents.
Market Restraints
- Petrochemical Feedstock Volatility:The price and availability of key precursors for glycidyl ethers, such as epichlorohydrin and various alcohols, are tied to volatile petrochemical markets, creating cost instability for diluent manufacturers and end-users.
- High Cost of REACH Compliance:For producers selling into Europe, the significant data generation and registration costs mandated by the ECHA under REACH create a high barrier to entry for new chemical substances, potentially stifling innovation.
- Substitution from Water-Borne Systems:In certain low-to-mid performance applications like general purpose coatings and civil engineering, the adoption of water-borne epoxy systems can reduce or eliminate the need for viscosity-modifying active diluents.
Strategic Opportunities
- Bio-Based Diluent Development:There is a significant commercial opportunity in developing and scaling production of epoxy active diluents derived from renewable feedstocks like plant oils, meeting market demand for sustainable and low-carbon-footprint solutions.
- Wind Energy Sector Expansion:The growing scale of wind turbine blades requires vast quantities of high-performance epoxy systems; developing diluents that improve resin infusion for these massive composite structures is a major growth vector.
- Penetration in Automotive Adhesives:As automakers replace mechanical fasteners with structural adhesives to bond dissimilar materials and reduce vehicle weight, the demand for custom-formulated epoxy systems with optimized rheology presents a key opportunity.
Industry Challenges
- Global Regulatory Harmonization:Manufacturers face significant complexity and R&D costs in developing formulations that simultaneously comply with the distinct chemical safety and environmental standards of the US EPA, Europe's ECHA, and China's MEE.
- Supply Chain Concentration:A reliance on specialized raw materials produced in geographically concentrated areas, such as chemical hubs in China and Germany, exposes the supply chain to disruption risks from logistical bottlenecks or regional policy changes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epoxy Active Diluent Market |
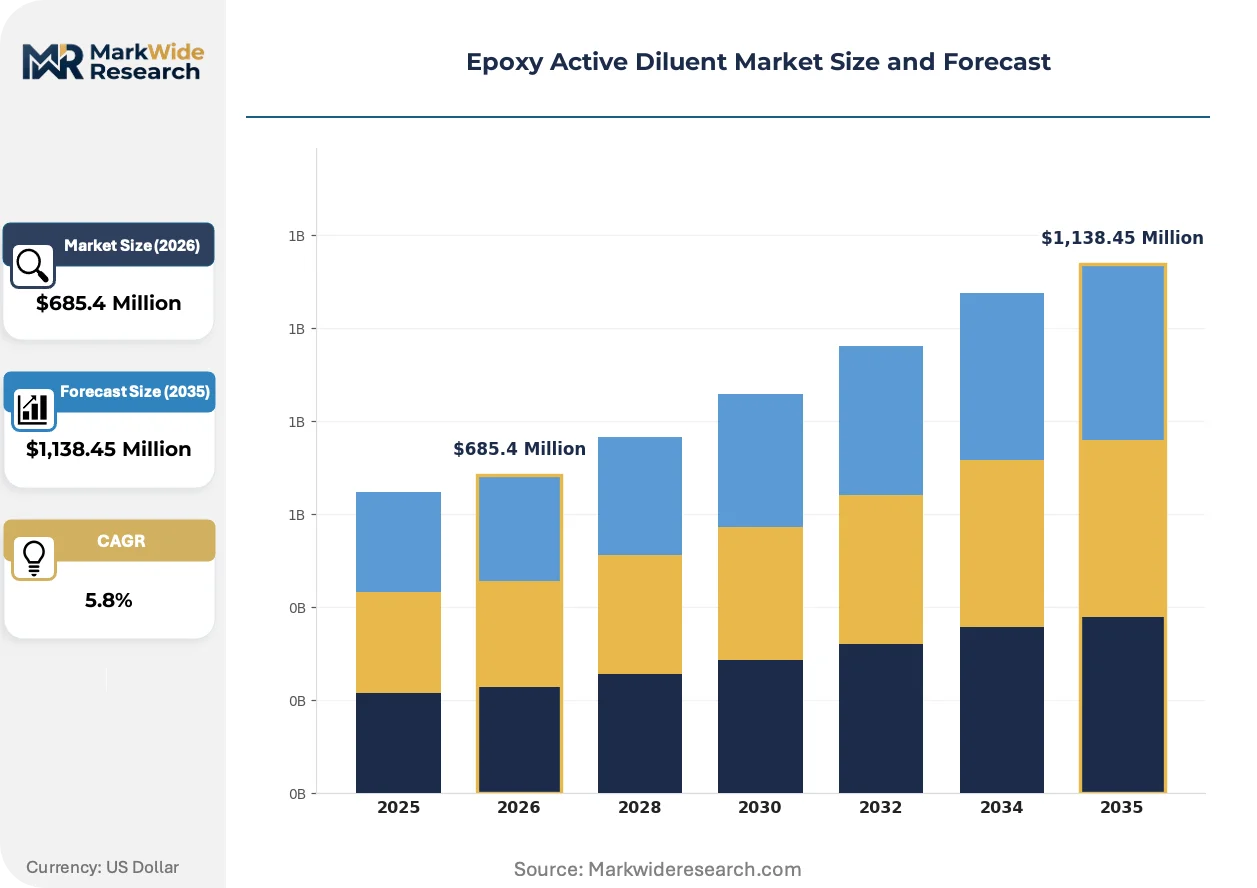
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aromatic Diluents, Aliphatic Diluents, Glycidyl Ethers, Others Application: Coatings, Adhesives, Sealants, Composites End User: Construction, Automotive, Aerospace, Electronics Distribution Channel: Online, Direct Sales, Wholesalers, Retailers |
| Companies Covered | BASF SE, Cardolite Corporation, Hexion Inc., Aditya Birla Chemicals, KUKDO Chemical, Huntsman Corporation, Evonik Industries AG, Mitsubishi Chemical Group, Olin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxy Active Diluent Market Strategic Shifts & Innovations
Intensifying scrutiny over chemical safety is creating a dual track for innovation. Material science advancements for higher performance must now directly integrate with a non-negotiable mandate for sustainable, lower-emission product development to secure market viability.
Bio-based diluents, derived from renewable sources like epoxidized vegetable oils, function to lower the carbon footprint of epoxy systems. Initially adopted in construction and flooring for green building certifications, their performance profile is improving. This technology is expanding into more demanding automotive and electronics applications that were previously the exclusive domain of petroleum-derived glycidyl ethers.
China's Ministry of Ecology and Environment (MEE) enforces stringent GB standards limiting VOC content in industrial products. This regulation directly forces reformulation for any company manufacturing in or exporting products to China. The coatings and adhesives sectors are most affected, accelerating a shift away from traditional aliphatic diluents toward compliant reactive alternatives within this critical market.
A notable behavioral shift sees end-users moving from transactional, price-based purchasing toward collaborative formulation partnerships with suppliers. This model sidelines traditional distributors unable to provide application engineering support, favoring technically adept manufacturers. The trend is most pronounced in the aerospace and high-frequency electronics industries, where achieving specific performance outcomes is the primary driver for procurement.
Epoxy Active Diluent Market Segmentation
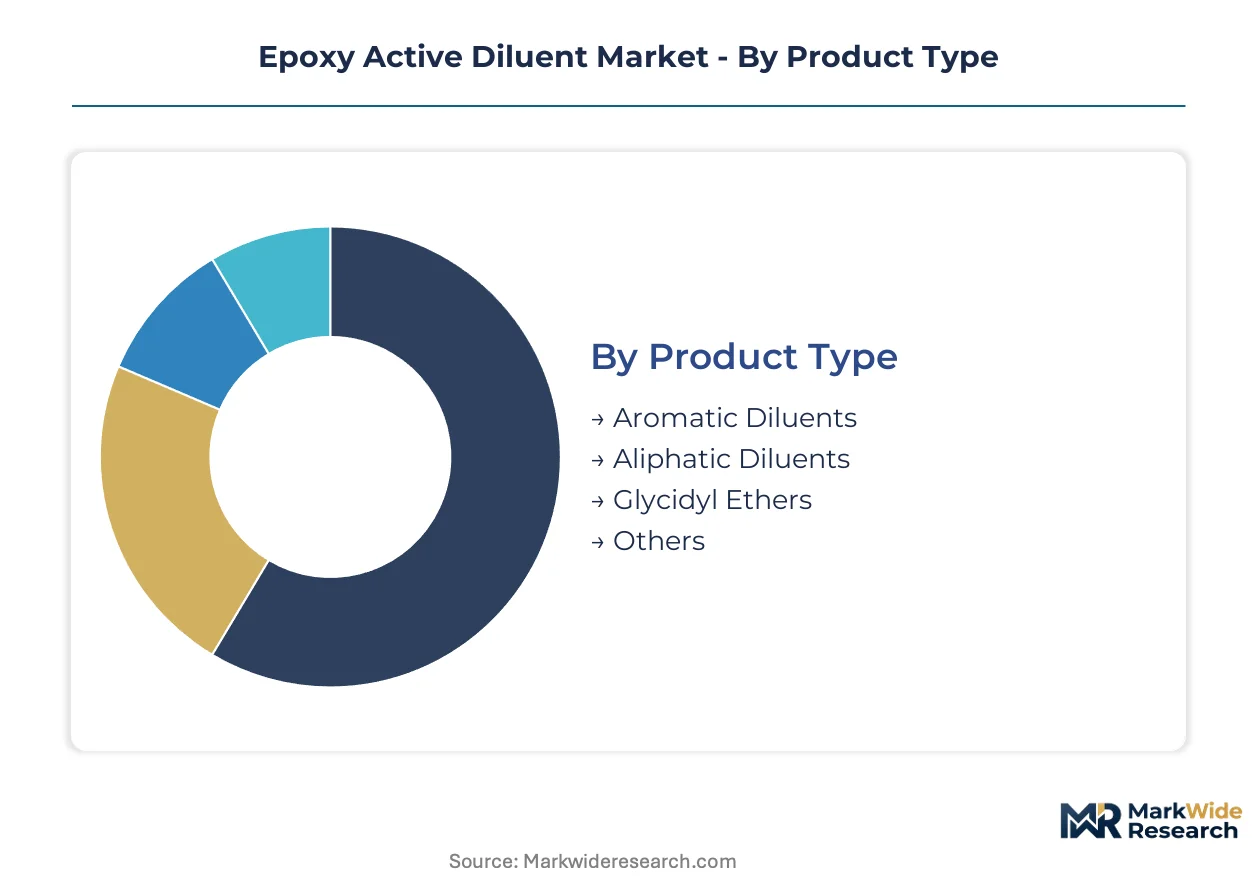
Understanding the segmentation of the epoxy active diluent market is crucial for identifying specific demand patterns and strategic investment areas within the chemical industry. Each segment reflects distinct performance requirements, regulatory influences, and end-user procurement behaviors, shaping product development and market access strategies.
Product Type:
Epoxy active diluent formulations vary significantly in their integration depth, from standalone viscosity modifiers to embedded chemical components.
- Glycidyl Ethers:These specialized compounds are critical for high-performance applications, maintaining thermal and mechanical properties in demanding environments. Demand concentrates in advanced manufacturing hubs in Germany and China, particularly for aerospace composites and high-frequency electronics.
- Aliphatic Diluents:Characterized by their low cost and broad compatibility, these diluents primarily serve large-scale applications requiring significant viscosity reduction. Their consumption is highest in the construction and general industrial coatings sectors, driven by volume and ease of processing.
- Aromatic Diluents:These products offer specific performance benefits, such as enhanced solvent resistance and higher thermal stability, for niche industrial applications. Their use is often tied to specific resin systems requiring improved chemical resistance.
- Others:This category encompasses emerging chemistries like bio-based alternatives and novel reactive diluents designed for ultra-low VOC formulations. Development in this area is driven by evolving environmental mandates from the US EPA and Europe's ECHA.
Volume placements concentrate in Aliphatic Diluents; the faster expansion belongs to Glycidyl Ethers.
Application:
The diverse functional utility of epoxy active diluents necessitates distinct formulations tailored for specific application environments.
- Coatings:Epoxy diluents significantly reduce the viscosity of coating formulations, improving application properties and allowing for higher solids content to meet VOC regulations. This application segment sees high volume consumption in industrial and protective coatings across construction and marine sectors.
- Composites:Active diluents are essential for reducing resin viscosity in composite manufacturing, facilitating better fiber impregnation and void reduction in complex structures. The aerospace industry and wind energy sector in Europe and the US drive demand for high-performance diluents in this segment.
- Adhesives:In adhesive formulations, these compounds enhance flow characteristics, improve wetting of diverse substrates, and contribute to the final mechanical properties of the cured bond. Automotive structural adhesives represent a key growth area for specialized diluent use.
- Sealants:Diluents in sealant formulations improve workability and allow for higher filler loading, which is crucial for cost-effectiveness and performance in construction and general assembly. Environmental regulations from China's MEE influence the shift towards compliant reactive alternatives.
Demand for Coatings drives significant volume, while Composites exhibits specialized growth.
End User:
End-user industries dictate both the performance requirements and the procurement patterns for epoxy active diluents.
- Aerospace:This sector requires diluents that maintain the thermal and mechanical integrity of lightweight, high-performance composites used in aircraft structures. Manufacturers like Huntsman Corporation focus on specialized formulations for this demanding segment.
- Automotive:Epoxy active diluents are increasingly critical for structural adhesives and coatings that contribute to vehicle lightweighting and enhanced durability. The shift towards electric vehicles in Germany and China is accelerating demand for these materials.
- Construction:This segment utilizes epoxy diluents primarily in flooring, protective coatings, and repair mortars to improve workability and durability. The drive for green building certifications influences the adoption of lower-VOC formulations.
- Electronics:Miniaturization trends in electronics necessitate epoxy encapsulants with superior flow and wetting properties, a characteristic directly enhanced by specific active diluents. China's electronics manufacturing industry represents a significant consumption hub.
The Construction sector consumes high volumes, whereas Aerospace demands advanced material specifications.
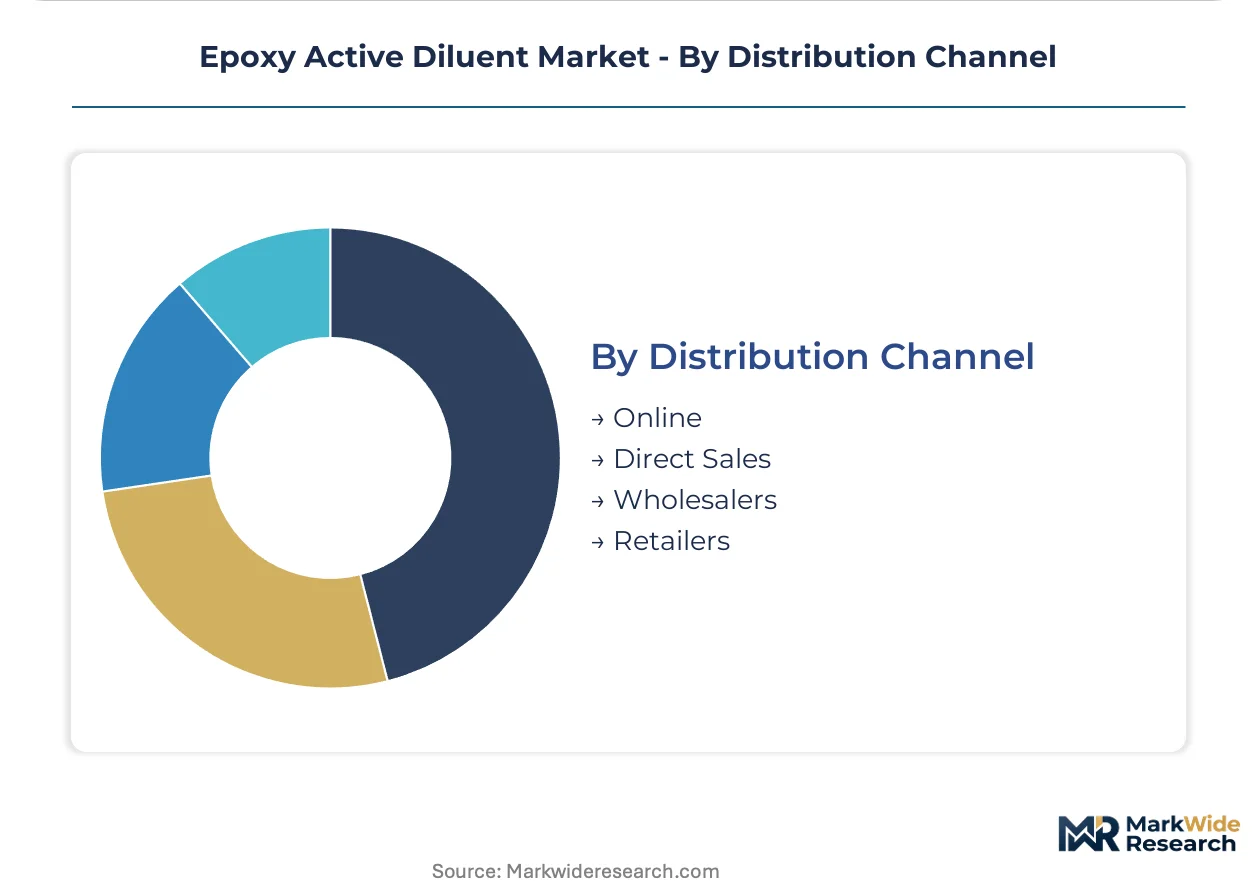
Distribution Channel:
The supply concentration for epoxy active diluents varies by distribution channel, reflecting diverse customer scales and technical support needs.
- Direct Sales:This channel facilitates direct engagement between manufacturers and large-volume industrial customers, offering custom formulation support and technical service. Key players like Hexion Inc. leverage direct sales for strategic accounts in automotive and construction.
- Wholesalers:Wholesalers serve a broad range of smaller and mid-sized industrial customers, providing logistical efficiency and product availability across various regions. This channel often handles standard aliphatic diluents for general-purpose applications.
- Online:The online channel caters to smaller businesses, research institutions, and specialized niche markets seeking specific diluent chemistries in smaller quantities. Digital platforms offer convenience and expanded product access.
- Retailers:Retailers primarily serve the DIY market and very small professional users for applications like hobbyist projects or minor repairs. Product offerings through this channel are typically pre-packaged and less specialized.
Large-scale procurement predominantly occurs via Direct Sales, with Wholesalers serving a more fragmented customer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The epoxy active diluent market exhibits a clear production-consumption divide, with advanced manufacturing hubs in China and Germany anchoring significant supply. Demand concentrates across diverse end-user industries in key regions, driven by specific application requirements and evolving regulatory landscapes. This global market sees specialized diluents produced in one region often consumed across international borders.
China
High volume consumption for electronics miniaturization and automotive lightweighting drives demand in China. The Ministry of Ecology and Environment (MEE) enforces stringent GB standards directly influencing reformulation efforts. Industrial clusters in the Yangtze River Delta and Pearl River Delta drive significant demand for compliant reactive alternatives.
Germany
The automotive sector's shift towards electric vehicles and high-performance composites in aerospace drives demand for specialized glycidyl ethers in Germany. Europe's ECHA under REACH mandates push for safer, lower-emission diluents. Chemical production centers like Ludwigshafen focus on sustainable product development for global markets.
United States
Aerospace composites advancement and stringent US EPA regulations on VOCs compel formulators to adopt reactive diluents. The US EPA's rules boost consumption in large-volume coatings and adhesives segments. Major manufacturing regions, including the Gulf Coast and Midwest, utilize these materials for diverse industrial applications.
Japan
Electronics miniaturization and precision manufacturing demand epoxy encapsulants with superior flow and wetting properties in Japan. METI's industrial policies support innovation in high-performance materials for advanced applications. The Kanto region's electronics industry drives the adoption of specialized active diluents.
India
Infrastructure development and a growing automotive sector are increasing the demand for epoxy active diluents in coatings and adhesives across India. BIS standards are gradually aligning with international environmental norms for chemical products. Industrial corridors in Maharashtra and Gujarat are expanding their consumption of these compounds.
Epoxy Active Diluent Market Key Industry Players
Top-tier vendors anchor the integrated chemical supply chain, offering extensive product portfolios and technical support, while a broader base of specialized manufacturers and regional suppliers caters to niche applications. This market structure features global chemical giants, specialty chemical producers, and regional formulators. Strategic archetypes include diversified chemical conglomerates, high-performance material specialists, and sustainable solution providers, each addressing distinct market needs. Competitive moves involve portfolio diversification into bio-based alternatives, strategic partnerships for application engineering support, and capacity expansions to meet regional demand spikes.
On the premium-tier vector, Huntsman Corporation exemplifies a focus on high-performance formulations critical for demanding aerospace composites, representing a specialized approach to advanced material requirements. Evonik Industries AG sits within the archetype of specialty additive providers, emphasizing sustainable product development to meet evolving environmental mandates and stricter regulatory compliance. Hexion Inc., a diversified chemical company, anchors a broad product portfolio and leverages its extensive offering to serve diverse end-markets, including construction and automotive applications, showcasing a comprehensive market presence.
| Leading Market Players |
|---|
| BASF SE |
| Cardolite Corporation |
| Hexion Inc. |
| Aditya Birla Chemicals |
| KUKDO Chemical |
| Huntsman Corporation |
| Evonik Industries AG |
| Mitsubishi Chemical Group |
| Olin Corporation |
| Others |
Cost & Logistics Intelligence
Bio-based diluent development is simultaneously reshaping cost economics and concentrating supply chains towards renewable feedstock sources. This transition impacts raw material procurement and market pricing for epoxy active diluents.
Pricing Analysis
Cost-down pressure on aliphatic diluents accelerates due to their commodity nature and competition from water-borne systems. The dominant pricing model is contract-based long-term offtake for large volumes, while smaller buyers use per-unit transactional pricing. Price differentiation stems from customization level for specific performance targets and the quality grade required for high-performance applications. Construction end-users exhibit the highest price sensitivity, whereas aerospace and electronics buyers prioritize performance over cost.
Supply Chain Analysis
Direct sales channels handle large-volume industrial customers seeking custom formulation support and technical service. The supply chain concentrates in chemical hubs within China, Germany, and the United States. Production relies on key precursors like epichlorohydrin and various alcohols, alongside emerging plant oils for bio-based alternatives. A structural risk involves petrochemical feedstock volatility, creating cost instability for manufacturers. Wholesalers serve a more fragmented customer base for standard aliphatic diluents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The epoxy active diluent market is rapidly becoming a vertical-integration race, with players aggressively pursuing upstream control over bio-based feedstock sourcing. This strategy aims to secure sustainable raw material supply and meet evolving environmental mandates.
For Market Incumbents: Deploy custom formulation partnerships to deepen engagement with high-performance end-users like aerospace and electronics. Incumbents must invest in R&D for bio-based alternatives to counter the threat of stricter environmental regulations and competition from water-borne systems. Expanding capacity for lower-VOC compliant chemistries in key regions like China and Germany also reinforces market position.
For New Entrants and Emerging Players: Bio-based diluent innovations offer a technology-first wedge into the automotive adhesives sector, targeting lightweighting initiatives. New entrants can also focus on specialized glycidyl ethers for the expanding wind energy composites market. The most penetrable segment lies within mid-performance construction coatings, leveraging green certifications for market entry. A go-to-market angle involves offering sustainable solutions with clear environmental compliance benefits.
For Investors and Strategic Acquirers: Re-rating potential sits with specialty chemical producers given the sustained demand for high-performance, compliant formulations. Investors should target companies with strong intellectual property in bio-based diluents or ultra-low VOC chemistries for long-term viability. A key signal to watch as an inflection indicator is the implementation of new environmental mandates from China's MEE or Europe's ECHA, particularly those specifying renewable content.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Bio-based Diluents | Secures supply for growing demand in green building and automotive sectors. |
| R&D Investment in Ultra-low VOC Chemistries | Addresses stringent US EPA and ECHA regulations for coatings and adhesives. |
| Strategic Partnership for Application Engineering | Provides custom formulation support to aerospace and electronics end-users. |
| Backward Integration into Renewable Feedstocks | Mitigates petrochemical feedstock volatility and enhances sustainability profile. |
| Geographic Expansion in China's Electronics Hubs | Captures demand from miniaturization trends and MEE compliance requirements. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with technical R&D directors, procurement leads at automotive OEMs, environmental compliance officers, and composite material engineers validated market dynamics. This approach combined bottom-up market sizing with top-down validation of demand drivers. US EPA reports and ECHA REACH dossiers provided critical regulatory context.
Market volume and value were modeled at a granular level across product type, application, end-user, and key regional regulatory clusters. Compound Annual Growth Rates were derived from historical growth trends, projected end-user industry expansion, and anticipated regulatory impacts across the analysis window. Key industry-specific forecast inputs included petrochemical feedstock price trends and bio-based material adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen geopolitical events or rapid shifts in environmental policy. Projections reflect current assumptions about technological development and regulatory enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Firestop Sealants Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Melamine Formaldehyde (MF) Market
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
2K Epoxy Adhesives Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
Asia-Pacific Polyurethane Adhesives Market
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
Global Construction Silicone Sealants Market
Adhesives & Sealants
EMEA Epoxy Adhesives Market
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
North America Hot Melt Adhesives Market
Adhesives & Sealants
US Tile Adhesive Market
Adhesives & Sealants
Global Glass Bonding Adhesive Market