
 Structural Sealants Market | 2026-2036
Structural Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Structural Sealants Market Analytics
REACH compliance in Europe is consolidating the cost-of-entry calculus for structural sealant manufacturers, favoring firms with in-house toxicology and substitution R&D capabilities. Sika AG leverages its Swiss manufacturing base and vertical integration in silicone intermediates to sustain premium positioning across facade bonding applications. Dow anchors North American supply through controlled-access distribution of structural glazing silicones, while Henkel AG & Co. KGaA competes on automotive direct-glazing specifications with specialized two-component polyurethane systems.
Structural sealants are load-bearing adhesive compounds, typically formulated from silicone, polyurethane, or polysulfide polymers with tensile strengths exceeding 0.5 MPa and elongation capacities above 200%, designed to transfer structural stresses between substrates while maintaining environmental sealing. Silicone formulations dominate high-rise curtain wall installations due to UV stability and movement accommodation, whereas polyurethane variants capture automotive and transportation bonding where impact resistance and paint compatibility matter. Single-component moisture-cure technology leads volume shipments for on-site construction, while two-component systems command margin pools in factory-controlled aerospace and electronics assembly.
The EPA regulates VOC emissions from architectural sealants under 40 CFR 59, while the EU Green Deal and F-Gas Regulation constrain fluorinated blowing agents in polyurethane formulations. China's GB standards and MEE enforcement on formaldehyde and benzene content in building materials reshape import requirements and domestic formulation practices. Stakeholders must monitor divergence between European hazard-based restrictions and performance-based North American codes when allocating R&D budgets across regional product portfolios.
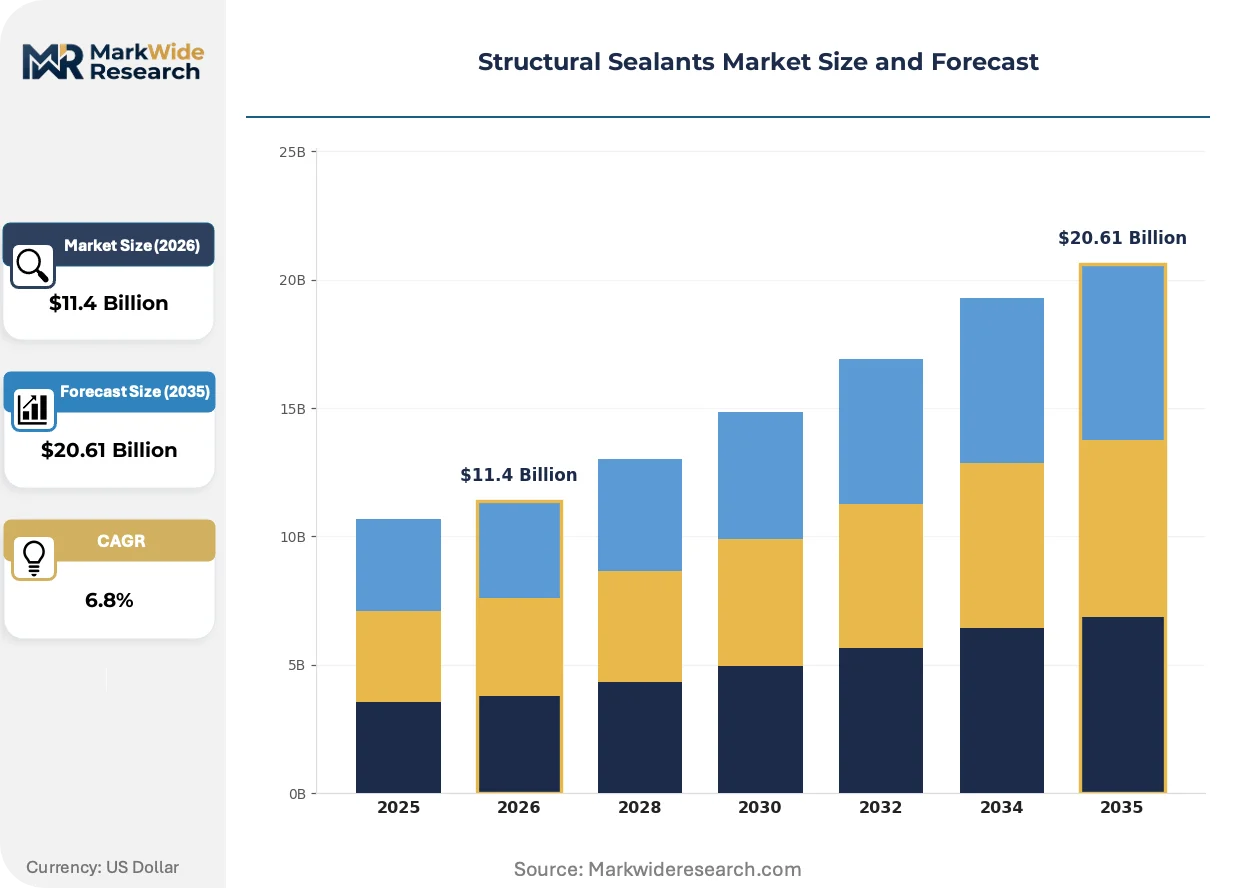
Market Dynamics
Curtain wall specification tightening across China's tier-one cities is compressing qualification timelines for structural sealant suppliers while simultaneously expanding bonded glazing square footage per high-rise project.
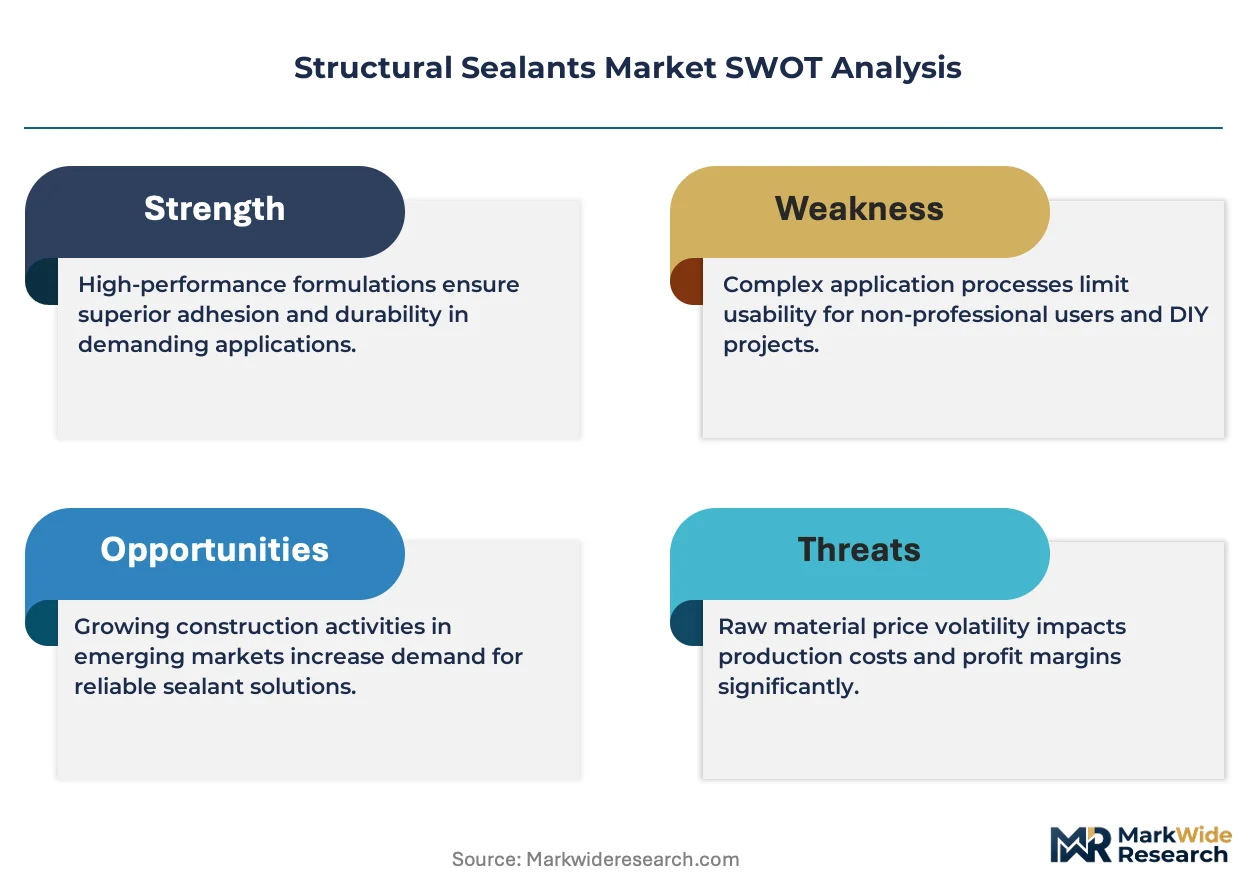
Growth Catalysts
- GB standard upgrades:China's MEE enforcement on formaldehyde and benzene content in building materials is accelerating substitution of solvent-based systems with silyl-modified polymer formulations in facade applications.
- Automotive direct-glazing:Windshield bonding specifications for electric vehicle platforms are expanding demand for two-component polyurethane systems with crash-resistant modulus profiles.
- Silicone intermediate supply:Captive production of dimethylsiloxane feedstock in Zhejiang and Shandong provinces is compressing raw material lead times for domestic sealant compounders.
Market Restraints
- Organotin catalyst restrictions:REACH Annex XVII limitations on dibutyltin compounds in Europe are forcing reformulation of condensation-cure silicones with alternative tin-free catalysts at elevated R&D cost.
- Polyol supply concentration:Polyether polyol production for polyurethane sealants clusters in the US Gulf Coast and Northeast Asia, exposing formulators to freight rate volatility and force majeure risk.
- Movement accommodation limits:Polysulfide sealants face displacement in high-rise applications due to inferior UV resistance compared to silicone alternatives, constraining addressable market scope.
Strategic Opportunities
- India green building codes:GRIHA and IGBC certification mandates in commercial construction are creating specification pull for low-VOC structural bonding systems in Mumbai and Bangalore high-rise developments.
- Prefabricated facade modules:Factory-controlled curtain wall assembly is shifting volume toward two-component metering equipment and automated dispensing systems with integrated quality logging.
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon blowing agents is incentivizing investment in water-blown and pentane-based polyurethane foam technologies for thermal-break bonding applications.
Industry Challenges
- Adhesion certification timelines:ETAG 002 and ASTM C1184 qualification protocols for structural glazing silicones require 12-18 month weathering and mechanical testing cycles, delaying product commercialization.
- Application technician training:Proper joint dimensioning and surface preparation for load-bearing silicone bonds demands certified installer networks that remain underdeveloped in secondary Chinese construction markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Structural Sealants Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Silicone, Polysulfide, Acrylic Application: Construction, Automotive, Aerospace, Electronics End User: Manufacturers, Contractors, DIY Consumers, Engineers Technology: Single-Component, Two-Component, Pre-Cured, In-Situ |
| Companies Covered | 3M, Sika AG, Henkel AG & Co. KGaA, H.B. Fuller, Dow, Arkema, BASF, Pidilite Industries, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Structural Sealants Market Evolving Landscape
Hybrid polymer chemistry is dissolving traditional material boundaries between silicone, polyurethane, and modified silane systems, enabling single-product platforms to span multiple specification regimes.
MS polymer technology is converging with silyl-terminated polyether backbones to deliver paintable, low-modulus structural bonds for automotive and transportation OEMs seeking to consolidate adhesive SKUs across assembly plants. Tier-one suppliers in Germany and Japan are qualifying these hybrids for direct-to-metal applications previously reserved for two-component polyurethanes. The convergence is compressing the historical segmentation between construction and automotive formulation expertise, forcing compounders to build cross-industry testing capabilities.
REACH authorization requirements for Substances of Very High Concern are eliminating legacy plasticizer chemistries from polysulfide and polyurethane sealant formulations across European facade and infrastructure projects. ECHA's 2024-2025 sunset date cluster for phthalate and organotin compounds is accelerating substitution program investments by sealant manufacturers with significant EU revenue exposure. The regulatory pressure is most acute in renovation and refurbishment segments where existing specification libraries reference now-restricted chemistries.
Specification authority is migrating from general contractors to facade engineering consultants and curtain wall system houses with proprietary structural calculations and bonding warranties. This buyer concentration is displacing distributor-led product selection in high-rise commercial projects across Shenzhen, Shanghai, and Singapore. The shift is most visible in signature architecture competitions where envelope performance guarantees override commodity procurement criteria.
Structural Sealants Market Segmentation
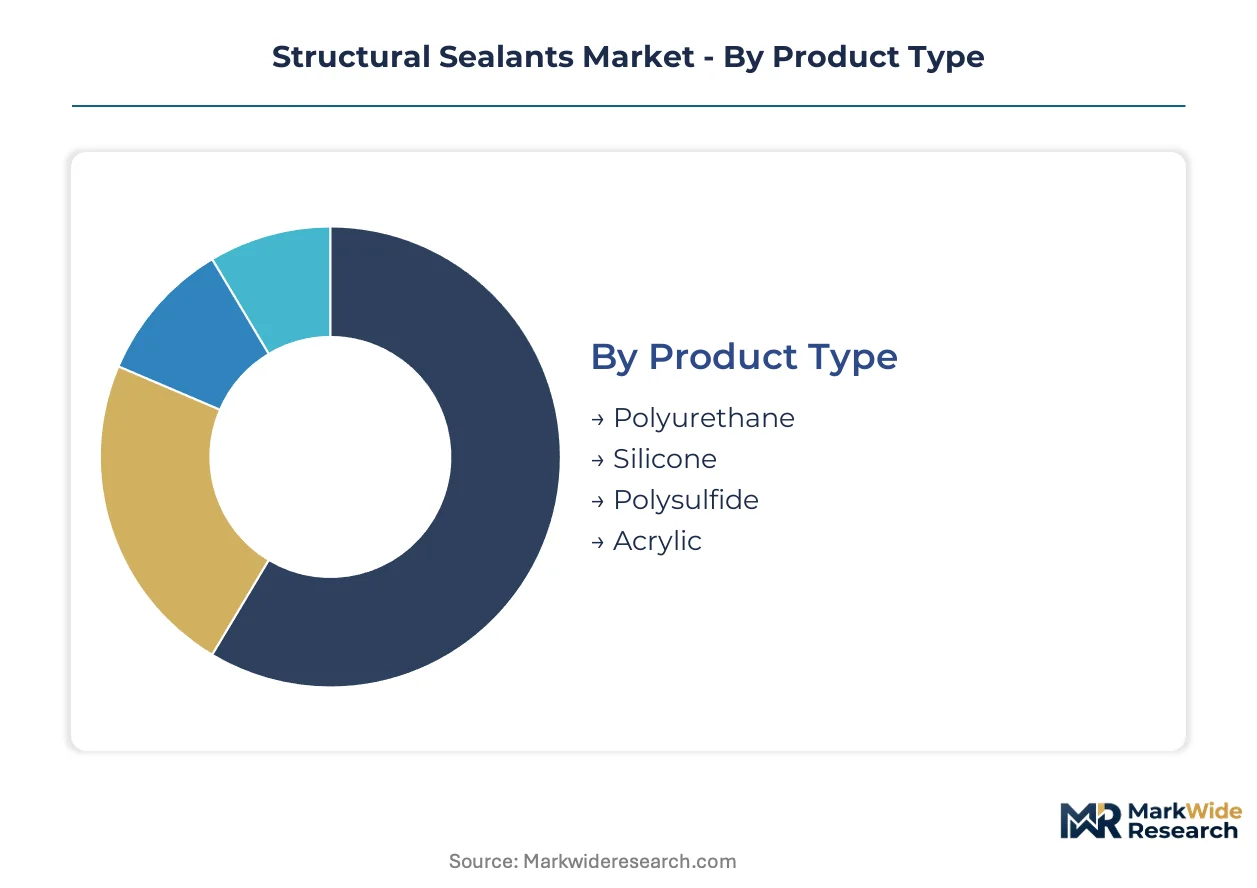
Structural sealant procurement decisions hinge on specification authority migration toward facade engineering consultants and system houses. Certification burdens vary sharply across product chemistries and application contexts, creating tiered entry barriers that reshape competitive positioning.
Product Type:
Silicone formulations carry the heaviest certification load, requiring ETAG 002 and ASTM C1184 weathering protocols spanning 12-18 months. Polyurethane and polysulfide variants face REACH Annex XVII constraints on organotin catalysts and phthalate plasticizers.
- Silicone:UV-stable, high-elongation formulations dominate high-rise curtain wall installations. Demand concentrates in China's tier-one cities where GB standard upgrades on formaldehyde content accelerate silyl-modified polymer substitution. MEE enforcement compresses qualification timelines while expanding bonded glazing square footage per project.
- Polyurethane:Impact-resistant systems with crash-resistant modulus profiles capture automotive direct-glazing specifications for electric vehicle platforms. Demand clusters in Germany and Japan where tier-one suppliers qualify hybrids for direct-to-metal applications previously reserved for two-component systems.
- Polysulfide:Legacy infrastructure applications face displacement due to inferior UV resistance compared to silicone alternatives.
- Acrylic:Lower-cost formulations serve interior and non-structural sealing where load-bearing capacity requirements relax.
Silicone sits at the top of the volume ranking, with polyurethane climbing the fastest.
Application:
Construction absorbs the majority of material volume through curtain wall and high-rise glazing projects. Automotive and aerospace segments command premium pricing through factory-controlled assembly environments with integrated quality logging systems.
- Construction:Curtain wall specification tightening across Shenzhen, Shanghai, and Singapore compresses supplier qualification timelines. Prefabricated facade modules shift volume toward two-component metering equipment and automated dispensing with quality logging.
- Automotive:Windshield bonding specifications for electric vehicle platforms expand demand for two-component polyurethane systems. OEMs seek SKU consolidation across assembly plants through paintable, low-modulus hybrid platforms.
- Aerospace:Factory-controlled environments demand two-component systems with 12-18 month qualification cycles and rigorous mechanical testing protocols.
- Electronics:Miniaturization trends drive precision dispensing requirements for thermal management and environmental sealing in controlled manufacturing settings.
Construction holds the dominant share position, with automotive gaining share fastest on electrification trends.
End User:
Procurement authority concentrates among specification engineers and facade consultants with proprietary structural calculations and bonding warranties. DIY consumers face exclusion from structural applications due to installation certification requirements.
- Manufacturers:Prefabricated facade module producers and automotive OEMs drive two-component system adoption through captive metering equipment investments.
- Contractors:General contractors lose specification influence to facade engineering consultants with envelope performance guarantees.
- DIY Consumers:Limited to non-structural acrylic applications; excluded from load-bearing silicone and polyurethane procurement.
- Engineers:Facade engineering consultants and curtain wall system houses displace distributor-led product selection in signature architecture competitions.
Manufacturers command the highest volume pull, with engineers expanding influence fastest through specification authority migration.
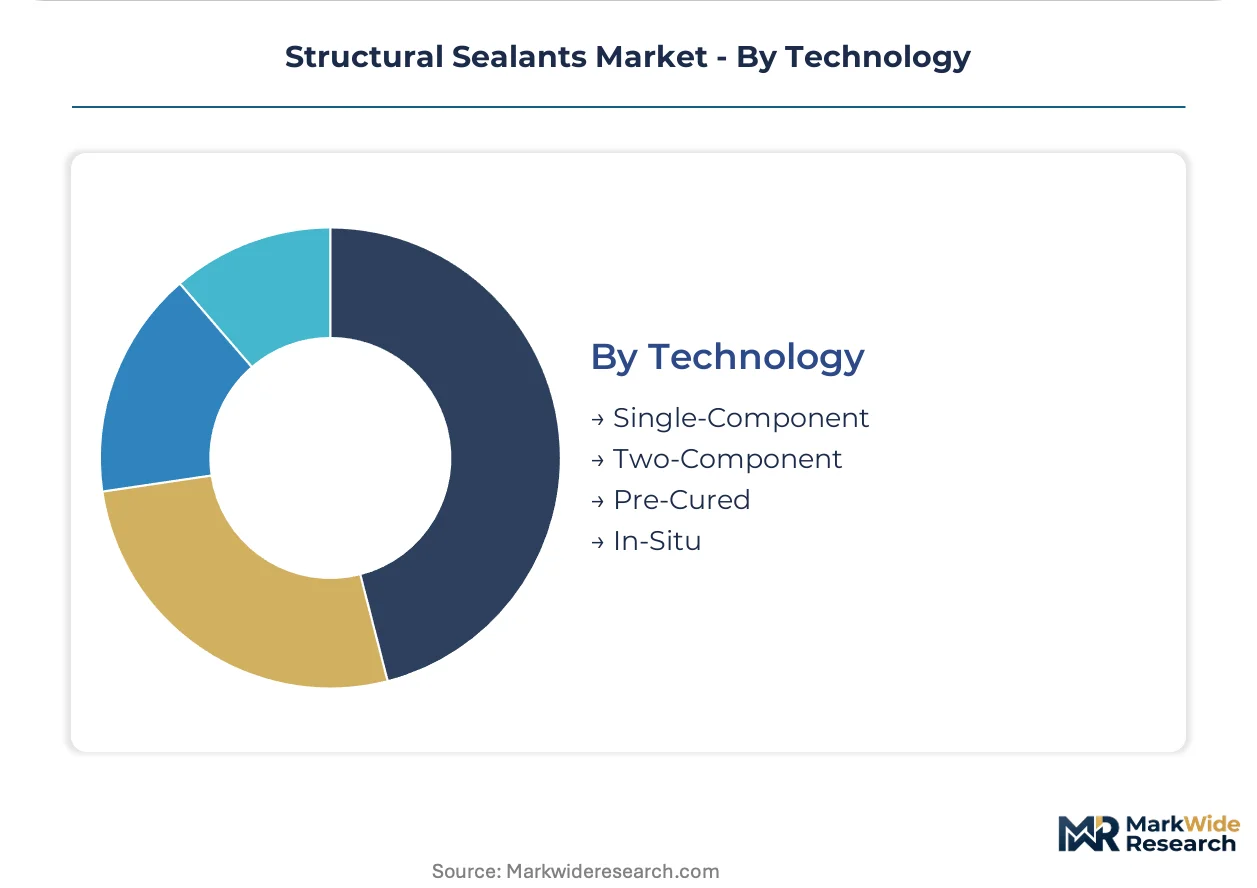
Technology:
Moisture-cure single-component systems dominate on-site construction volume, while two-component platforms capture margin pools in factory-controlled environments with precise metering requirements.
- Single-Component:Moisture-cure technology leads construction shipments for on-site curtain wall installation where joint dimensioning and surface preparation demand certified technician networks.
- Two-Component:Metering-dependent systems command aerospace and electronics assembly margins through factory-controlled quality assurance.
- Pre-Cured:Factory-manufactured gasket alternatives serve modular construction where field curing time constraints apply.
- In-Situ:Site-applied formulations accommodate irregular substrate conditions in renovation and refurbishment segments.
Single-component technology anchors volume leadership, with two-component platforms expanding most quickly in prefabrication trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Structural sealant manufacturing originated in German and Swiss chemical laboratories during the mid-20th century, with industrial scaling following post-war reconstruction demands. The technology diffused through North American automotive adoption and Asian construction booms.
China
Megacity infrastructure in Shenzhen and Shanghai drives specification volume for curtain wall bonding systems. MEE enforcement of GB standards on formaldehyde and benzene content accelerates silyl-modified polymer substitution in facade applications. Zhejiang and Shandong provinces host captive dimethylsiloxane production facilities serving domestic compounders.
Germany
Automotive direct-glazing specifications for electric vehicle platforms expand demand for two-component polyurethane systems. REACH Annex XVII limitations on organotin catalysts force reformulation investments by sealant manufacturers with EU revenue exposure. The Rhine-Ruhr industrial corridor concentrates formulation R&D and toxicology testing capabilities.
United States
High-rise commercial construction in New York and Chicago sustains demand for UV-stable silicone curtain wall installations. EPA regulation under 40 CFR 59 constrains VOC emissions from architectural sealant formulations. The US Gulf Coast hosts concentrated polyether polyol production for polyurethane sealant feedstock.
Japan
Precision assembly requirements in electronics and aerospace factory environments drive two-component metering system adoption. METI industrial standards govern structural bonding performance specifications for transportation applications. The Kansai region around Osaka maintains specialized hybrid polymer research facilities.
India
GRIHA and IGBC green building certification mandates in Mumbai and Bangalore commercial construction create specification pull for low-VOC structural bonding systems. BIS standards on building material emissions reshape import requirements and domestic formulation practices. The Delhi-NCR corridor concentrates facade engineering consultant networks influencing procurement decisions.
Structural Sealants Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive silicone intermediate production. Three tiers separate premium formulation specialists from regional compounders and commodity acrylic producers. Strategic moves concentrate on backward integration into dimethylsiloxane feedstock and hybrid polymer R&D partnerships with automotive OEMs.
Among Swiss and German chemical conglomerates, Sika AG and Henkel AG & Co. KGaA exemplify the premium-tier archetype through specialized structural glazing and automotive direct-glazing expertise. Dow represents North American supply anchoring through controlled-access distribution networks. These three occupy positions defined by geographic manufacturing bases and end-use certification depth rather than scale alone.
| Leading Market Players |
|---|
| 3M |
| Sika AG |
| Henkel AG & Co. KGaA |
| H.B. Fuller |
| Dow |
| Arkema |
| BASF |
| Pidilite Industries |
| DuPont |
| Others |
Value Network & Pricing Analysis
Dimethylsiloxane spot prices in Zhejiang and Shandong provinces cascade through silicone sealant manufacturing into three-tier pricing structures across premium, standard, and economy levels. Raw material volatility compresses margins for non-integrated compounders while captive producers extract differential rents.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ETAG 002-certified structural glazing silicones from commodity construction grades and interior acrylic formulations. Certification depth and captive dimethylsiloxane supply anchor premium positioning, while freight-adjusted polyol costs pressure polyurethane margins. Cost compression in standard-tier construction silicones is intensifying because Shandong domestic producers expand dimethylsiloxane capacity. DIY consumers exhibit highest price sensitivity; facade engineering consultants demonstrate lowest sensitivity due to performance guarantee obligations.
Supply Chain Analysis
Direct-to-OEM channels handle automotive and aerospace demand with metering equipment integration, while distributor-led construction sales serve fragmented contractor networks. Dimethylsiloxane production concentrates in China, Germany, and the United States; polyether polyol supply clusters in the US Gulf Coast and Northeast Asia. Formulation draws from silicone intermediates, polyol feedstocks, and tin-free catalyst substitutes. Single-source vulnerability in organotin catalyst alternatives following REACH Annex XVII restrictions elevates reformulation risk. Distribution runs through controlled-access technical service networks for structural glazing specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Structural sealants function as a stable compounder anchored by irreversible building code upgrades in China's tier-one megacities. Specification authority migration toward facade engineers creates durable incumbent advantages.
For Market Incumbents: To counter hybrid polymer substitution in automotive direct-glazing, deepen backward integration into dimethylsiloxane feedstock and accelerate ETAG 002 qualification pipelines for silyl-modified polymer platforms. Channel control through certified installer networks in secondary Chinese markets reinforces specification lock-in against regional compounders. For New Entrants and Emerging Players: Begin with India's GRIHA-certified commercial construction in Mumbai and Bangalore, where BIS standard enforcement creates import substitution openings for low-VOC structural bonding systems. Partner with prefabricated facade module producers seeking two-component metering equipment integration to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs and 12-18 month certification timelines strand sub-scale European compounders. Target mid-tier formulators with captive toxicology capabilities and established MEE compliance in China as acquisition candidates. Watch for inflection when Indian green building code adoption accelerates specification pull for hybrid polymer platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Intermediates | Captive dimethylsiloxane supply in Zhejiang compresses raw material lead times against Shandong competitors. |
| Hybrid Polymer R&D Partnership | Automotive OEMs in Germany and Japan qualify silyl-terminated polyether platforms for direct-to-metal bonding. |
| Certified Installer Network Expansion | Secondary Chinese construction markets lack qualified technicians for ETAG 002-compliant joint preparation. |
| REACH-Compliant Reformulation Program | Tin-free catalyst substitution addresses ECHA sunset dates for organotin compounds in European facade applications. |
| Prefabrication Equipment Integration | Factory-controlled curtain wall assembly shifts volume toward automated two-component metering with quality logging. |
Research Methodology
Bottom-up construction and automotive modeling reconciled against top-down silicone intermediate production tracking forms the analytical core of this study. Primary interviews with facade engineering consultants, automotive Tier 1 procurement managers, sealant plant managers, and MEE regulatory officers combined with secondary validation from customs data, SEC 10-K filings, and Cefic chemical industry reports. Cross-referencing bottom-up project pipelines with top-down dimethylsiloxane capacity announcements ensures volume consistency.
Input-output matrices map raw material flows through formulation tiers to end-use demand across product chemistry, application context, and technology type. Segmentation dimensions include certification grade, end-use industry, curing technology, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections and capacity utilization trends. Key inputs encompass GB standard enforcement timelines, ETAG 002 qualification success rates, and electric vehicle platform ramp schedules.
Several conditions sit outside the modeled scope, including force majeure disruptions in US Gulf Coast polyol production and unilateral tariff adjustments on Chinese silicone exports. Forecasts reflect assumptions about MEE enforcement continuity and REACH authorization timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
US Pressure Sensitive Adhesives Market
Adhesives & Sealants
Asia-Pacific Cyanoacrylate Adhesives Market
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
Adhesives and Sealants Distribution Market
Adhesives & Sealants
Marine Sealants Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Global Hygiene Adhesives Market
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
North America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Global Non-Woven Adhesives Market
Adhesives & Sealants
Conductive Adhesive Market
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
North America Automotive Adhesives and Sealants Market
Adhesives & Sealants
Nigeria Tile Adhesive Market