
 North America Polyurethane (PU) Hot-Melt Adhesives Market | 2026-2036
North America Polyurethane (PU) Hot-Melt Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Polyurethane (PU) Hot-Melt Adhesives Market Analytics
High-performance reactive-grade specifications is reorganizing competitive dynamics across the North America Polyurethane (PU) Hot-Melt Adhesives Market. Henkel AG & Co. KGaA leverages its captive polyurethane chemistry expertise to anchor supply relationships with tier-one automotive seating suppliers. H.B. Fuller Company sustains formulation leadership through dedicated R&D facilities in Minnesota and Illinois. Dow dominates upstream polyol supply, giving it cost-positioning advantages across industrial adhesive segments.
Polyurethane hot-melt adhesives are thermoplastic or reactive systems formulated from polyols and isocyanates that cure through moisture reaction or cooling to form durable elastomeric bonds with high flexibility and temperature resistance; they are engineered primarily for structural bonding in applications requiring rapid set times combined with long-term durability under thermal and mechanical stress. Industrial adhesives command the largest volume position due to saturated demand from panel lamination and composite assembly operations across the Midwest manufacturing belt. Automotive adhesives represent the fastest-expanding application category as OEMs pursue reduced interior weight and elimination of mechanical fasteners in electric vehicle platforms. Solvent-free formulations are capturing margin concentration as environmental compliance costs reshape procurement criteria for major buyers.
EPA enforcement of VOC limits under the Clean Air Act intersects with OSHA workplace exposure standards to mandate solvent-free and low-emission adhesive systems in U.S. manufacturing facilities. Health Canada's PMRA and Environment and Climate Change Canada impose parallel restrictions on hazardous air pollutants that affect cross-border formulation harmonization for suppliers serving both markets. Stakeholders must monitor evolving state-level regulations in California and New York that frequently prefigure federal standards and determine early-mover advantages in compliant product development.
Market Dynamics
EPA enforcement of VOC limits under the Clean Air Act is compressing formulation timelines across the North American polyurethane hot-melt adhesives supply base. Tier-one automotive seating suppliers in Detroit and Ontario now mandate solvent-free reactive systems as a condition of contract renewal.
Growth Catalysts
- Electric vehicle platform redesign:OEMs in Michigan and Ontario are eliminating mechanical fasteners from interior assemblies. PUR hot-melt bonding reduces component weight while maintaining structural integrity under thermal cycling.
- Clean Air Act compliance deadlines:EPA enforcement of amended VOC emission standards is disqualifying solvent-based competitors from federal procurement contracts. Manufacturers with captive reactive-grade capacity capture displaced volume.
- Great Lakes manufacturing corridor concentration:Panel lamination operations across Ohio, Indiana, and Illinois generate sustained demand for high-tack industrial formulations. Proximity to polyol supply from Texas Gulf Coast petrochemical hubs reduces inbound logistics costs.
Market Restraints
- Isocyanate feedstock volatility:MDI and TDI pricing fluctuates with crude oil derivatives and regional refinery capacity. Formulators lack long-term hedging instruments for these specialized chemical inputs.
- Reactive system technical limitations:Moisture-cure PUR adhesives require controlled ambient humidity for consistent crosslinking. Arid Southwestern U.S. manufacturing environments experience elevated rejection rates during low-humidity winter months.
- Cross-border regulatory friction:Health Canada's PMRA maintains divergent hazard classification protocols from EPA standards. Suppliers serving both markets incur duplicate testing and documentation costs for formulation harmonization.
Strategic Opportunities
- Texas Gulf Coast petrochemical integration:Proximity to expanding polyol production capacity enables backward integration into captive raw material supply. Integrated producers capture margin compression from merchant market volatility.
- Battery pack thermal management bonding:Electric vehicle battery module assembly requires thermally conductive adhesives with flame-retardant properties. PUR formulations with ceramic fillers address this emerging specification gap.
- California Air Resources Board pre-emptive compliance:CARB's anticipated 2027 low-VOC amendments will extend beyond federal Clean Air Act requirements. Early formulation certification creates preferential supplier status with West Coast OEMs.
Industry Challenges
- Reactive adhesive application engineering scarcity:Moisture-cure system deployment requires specialized dispensing equipment calibration and substrate preparation protocols. Technical service teams with cross-functional polymer chemistry and automation expertise command premium compensation.
- Legacy solvent-based inventory stranding:Distributors and contract manufacturers hold depreciating stocks of non-compliant adhesive systems. Write-downs compress working capital availability for compliant product line transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Polyurethane (PU) Hot-Melt Adhesives Market |
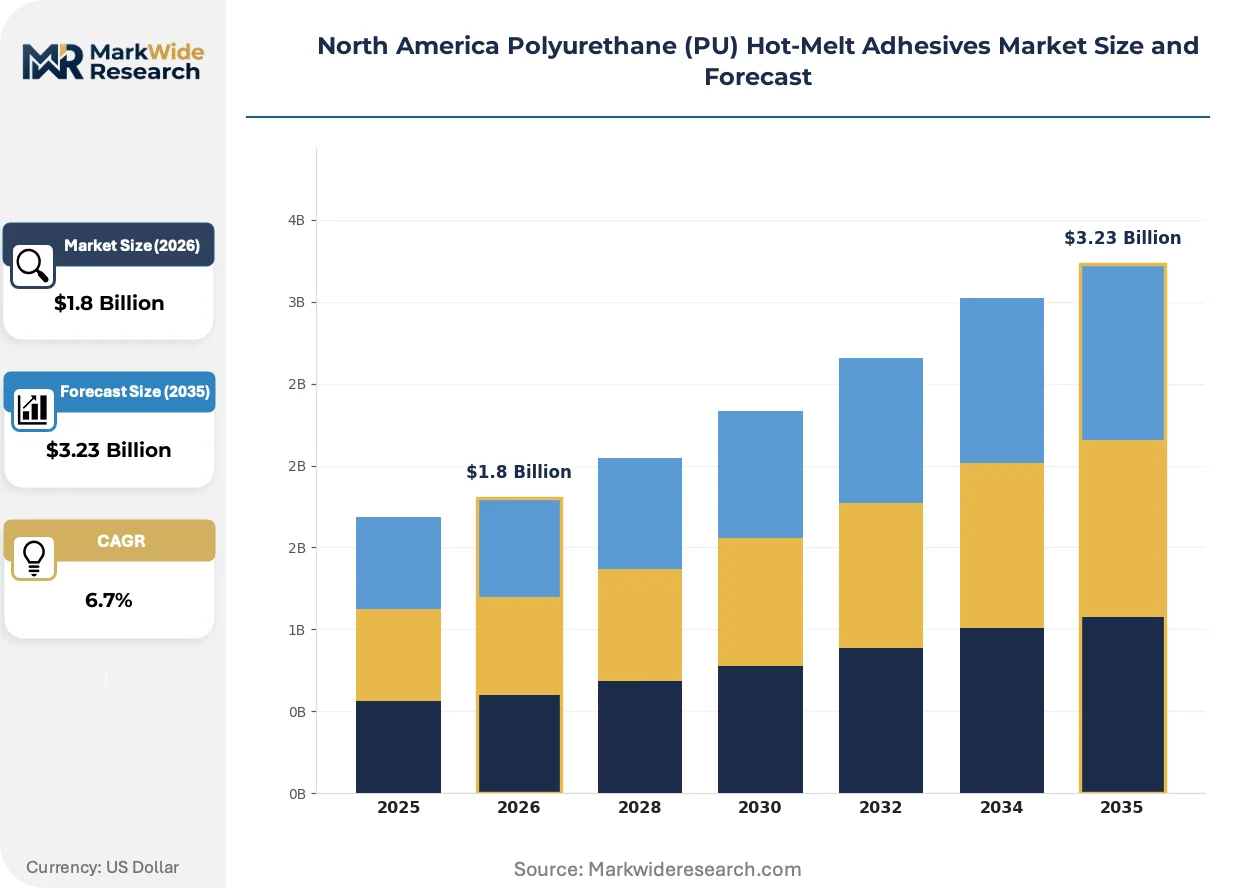
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Adhesives, Packaging Adhesives, Construction Adhesives, Automotive Adhesives Application: Woodworking, Furniture Assembly, Footwear, Automotive Interiors Formulation: Solve-Based, Solvent-Free, Hot-Melt, Reactive End User: Manufacturers, Contractors, Retailers, Distributors |
| Companies Covered | 3M, Arkema Group, H.B. Fuller Company, Henkel AG & Co. KGaA, Sika AG, Huntsman International LLC, Dow, BASF SE, Franklin International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Polyurethane (PU) Hot-Melt Adhesives Market Evolving Landscape
Formulation chemistry is diverging along performance-grade lines as end-use specifications harden. Suppliers now maintain parallel development tracks for commodity industrial grades and specialized automotive reactive systems.
Hybrid PUR-epoxy systems are fragmenting the high-performance structural bonding segment. These formulations combine the rapid green strength of hot-melt application with epoxy-class thermal resistance. Tier-one automotive suppliers in Ontario and Michigan are qualifying hybrid systems for electric vehicle battery tray assemblies. The technology is fragmenting incumbent PUR suppliers into reactive-grade specialists versus commodity industrial formulators.
EPA's 2024 amendments to National Emission Standards for Hazardous Air Pollutants are accelerating solvent-free formulation transitions. The rulemaking tightens permissible VOC content in adhesive manufacturing operations. Automotive OEMs in the Midwest are now rejecting supplier proposals that include solvent-based alternatives in their technical submissions. Formulators with dedicated reactive R&D facilities in Minnesota and Illinois are capturing specification-driven procurement.
Buyer consolidation among tier-one seating suppliers is compressing supplier qualification cycles. Magna, Lear, and Adient now mandate dual-source reactive PUR capacity with identical performance specifications. This concentration is forcing mid-sized formulators to license proprietary curing catalyst technology rather than develop independent IP. The pattern is most visible in Detroit-area procurement offices where OEM-directed supplier reduction programs eliminate single-source adhesive relationships.
North America Polyurethane (PU) Hot-Melt Adhesives Market Segmentation
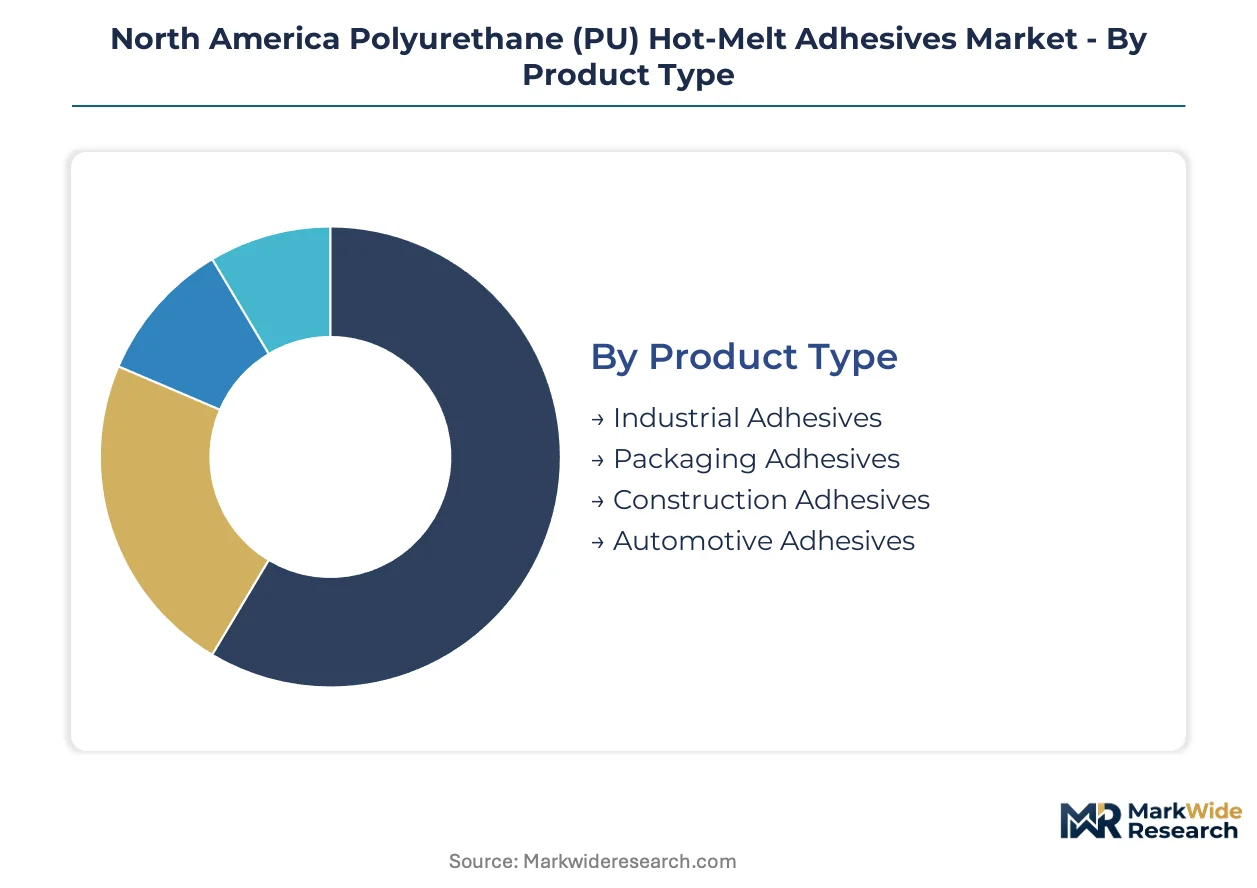
Segmentation in the North America Polyurethane (PU) Hot-Melt Adhesives Market reveals divergent demand patterns across industrial corridors and regulatory jurisdictions. Understanding where each segment concentrates geographically and which end-use specifications dominate procurement criteria enables suppliers to align formulation investments with actual contract flows.
Product Type:
Domestic manufacturing corridors in the Great Lakes and Texas Gulf Coast drive volume for industrial grades, while automotive specifications concentrate procurement decisions in Detroit and Ontario.
- Industrial Adhesives:Thermoplastic formulations engineered for rapid set times and high initial tack dominate panel lamination and composite assembly across Ohio, Indiana, and Illinois. Midwest manufacturers specify these grades for automated production lines where throughput speed determines line economics.
- Automotive Adhesives:Reactive moisture-cure systems formulated for structural bonding in interior assemblies are displacing mechanical fasteners in Michigan and Ontario electric vehicle platforms. OEMs mandate solvent-free specifications as a condition of tier-one supplier qualification.
- Packaging Adhesives:Lower-viscosity hot-melt grades serve folding carton and case-sealing operations concentrated in Wisconsin and Pennsylvania paperboard manufacturing clusters.
- Construction Adhesives:High-build reactive formulations address subfloor and insulation panel bonding in residential and commercial building across Texas and Florida construction markets.
Industrial Adhesives holds the largest share; momentum sits with Automotive Adhesives.
Application:
Cost tier differentiation separates specification-driven automotive interiors from price-sensitive furniture assembly, with woodworking occupying a mid-tier position on performance-per-dollar metrics.
- Automotive Interiors:Headliner, door panel, and seating assembly applications in Detroit-area plants require reactive-grade PUR with controlled open times and humidity-independent cure profiles. OEM-directed weight reduction programs are expanding adhesive bonding surface area per vehicle.
- Woodworking:Edgebanding and veneer lamination operations across the Carolina furniture belt specify medium-viscosity hot-melt systems with balanced green strength and sandability. Carolina manufacturers prioritize formulations compatible with existing edgebander equipment fleets.
- Furniture Assembly:Mattress and upholstered furniture producers in Mississippi and Tennessee utilize commodity-grade thermoplastic PUR for frame and spring unit attachment where cost-per-pound dominates procurement.
- Footwear:Upper-to-sole bonding applications in Maine and Massachusetts specialty manufacturers demand flexible grades with abrasion resistance and cold-crack performance.
Woodworking commands volume concentration; Automotive Interiors is climbing the fastest on specification upgrades.
Formulation:
Margin structure stratifies sharply between commodity thermoplastic production and reactive system specialization, with regulatory compliance costs compressing returns on legacy solvent-containing formulations.
- Solvent-Free:100% solids reactive and hot-melt systems engineered for EPA Clean Air Act compliance are capturing procurement preference across federal contracting and tier-one automotive supply chains. Formulators with dedicated Minnesota and Illinois R&D facilities hold qualification advantages.
- Reactive:Moisture-cure PUR systems requiring controlled ambient humidity for crosslinking deliver structural performance in load-bearing applications. Arid Southwestern manufacturing environments experience elevated rejection rates during winter low-humidity conditions.
- Hot-Melt:Thermoplastic formulations that set on cooling serve high-speed packaging and woodworking applications where rapid handling strength is required.
- Solvent-Based:Legacy formulations facing disqualification from federal procurement under amended National Emission Standards for Hazardous Air Pollutants; remaining demand concentrates in non-regulated specialty applications.
Solvent-Free formulations hold the largest share; Reactive systems are gaining share fastest on automotive specification penetration.
End User:
Customer type determines technical service intensity and contract structure, with manufacturers demanding application engineering support while distributors prioritize inventory turns and shelf stability.
- Manufacturers:Direct procurement by automotive seating suppliers and panel laminators in the Great Lakes corridor involves long-term supply agreements with embedded technical service requirements. These buyers specify performance metrics and audit formulation consistency.
- Distributors:Regional adhesive distributors serving job shops and smaller woodworking operations across the Midwest and Southeast manage working capital exposure on reactive system shelf-life limitations.
- Contractors:Construction adhesives procurement by flooring and insulation installation contractors in Texas and Florida operates on project-based spot purchasing with price sensitivity.
- Retailers:Consumer-packaged small-volume sales through hardware and home improvement channels represent minimal revenue concentration for specialized PUR formulators.
Manufacturers holds the largest share; momentum sits with Distributors as mid-sized formulators expand regional coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyol production capacity clusters along the Texas Gulf Coast, while formulation and consumption concentrate in the Great Lakes automotive corridor and Eastern Canadian manufacturing belt. This supply-demand geography shapes logistics economics and regulatory exposure across the North American market.
United States
Automotive OEMs in Michigan and Ohio are expanding PUR hot-melt procurement for electric vehicle interior lightweighting. EPA enforcement of amended National Emission Standards for Hazardous Air Pollutants is disqualifying solvent-based alternatives from federal contracts. Detroit-area tier-one seating suppliers now mandate solvent-free reactive systems as a condition of supplier qualification.
Canada
Cross-border automotive supply chains in Ontario are synchronizing adhesive specifications with Michigan assembly plants. Health Canada's PMRA maintains divergent hazard classification protocols from EPA standards, forcing duplicate testing costs on formulators serving both markets. The Windsor-Toronto corridor hosts concentrated panel lamination operations generating sustained industrial-grade demand.
Mexico
Expanding automotive assembly capacity in Nuevo León and Guanajuato is creating downstream adhesive demand as OEMs localize interior component sourcing. Mexico's environmental regulator SEMARNAT is tightening VOC emission limits in manufacturing zones, pressuring suppliers to transition from solvent-based systems. Querétaro's growing aerospace cluster represents an emerging specification-driven segment for structural bonding applications.
North America Polyurethane (PU) Hot-Melt Adhesives Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American PUR hot-melt adhesives market. The supplier base organizes into three tiers: integrated chemical majors with captive polyol supply, specialized adhesive formulators with dedicated reactive R&D facilities, and regional distributors with formulation blending capabilities. Competitive dynamics center on qualification speed with tier-one automotive seating suppliers and backward integration into Texas Gulf Coast petrochemical feedstocks.
Among integrated chemical majors, Dow and BASF SE occupy positions anchored by upstream polyol production capacity. Henkel AG & Co. KGaA and H.B. Fuller Company represent the specialized formulator archetype, with dedicated R&D infrastructure supporting reactive-grade development. These players exemplify the technology-capture strategy required for automotive specification penetration.
| Leading Market Players |
|---|
| 3M |
| Arkema Group |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| Sika AG |
| Huntsman International LLC |
| Dow |
| BASF SE |
| Franklin International |
| Others |
Value Network & Pricing Analysis
Long-term reactive-grade supply agreements with tier-one automotive seating suppliers in Detroit and Ontario lock in both polyol feedstock access and price visibility across volatile MDI and TDI markets. These contracts insulate qualified formulators from spot-market swings while compressing margins for distributors holding non-compliant solvent-based inventory.
Pricing Analysis
EPA's National Emission Standards for Hazardous Air Pollutants dictates the pricing tier structure across the North American PUR hot-melt adhesives market. Three-tier pricing separates automotive reactive grades from industrial thermoplastic formulations and stranded solvent-based legacy stocks. Price differentiation centers on certification grade for Clean Air Act compliance and volume scale in Great Lakes corridor procurement. Cost compression in commodity industrial grades is intensifying because captive polyol supply at Dow and BASF SE enables integrated producers to undercut merchant-market formulators. Distributors serving job shops and smaller woodworking operations exhibit the highest price sensitivity, while OEM-directed tier-one seating suppliers prioritize specification adherence over unit cost.
Supply Chain Analysis
Strategic stockpiling of MDI and TDI feedstocks dominates inventory strategy among integrated producers with Texas Gulf Coast petrochemical access, while just-in-time delivery prevails among regional formulators lacking backward integration. Supply concentrates in the United States, Canada, and Mexico, with polyol production anchored in Texas and formulation operations clustering in Michigan, Ohio, and Ontario. Raw material dependencies rest on crude oil derivatives, regional refinery capacity, and specialized isocyanate intermediates. Single-source vulnerability from concentrated MDI production creates structural risk for non-integrated formulators. Distribution runs through direct long-term contracts with automotive OEMs and regional distributor networks serving industrial job shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid PUR-epoxy systems threaten to fragment structural bonding specifications in electric vehicle battery assemblies, forcing incumbent PUR specialists to defend reactive-grade qualification status against epoxy-class thermal resistance benchmarks.
For Market Incumbents: Fortify captive polyol supply positions through Texas Gulf Coast capacity reservations or tolling arrangements with Dow and BASF SE. Deepen application engineering teams with cross-functional polymer chemistry and automation expertise to defend against hybrid system displacement in battery tray assemblies. Prioritize early CARB 2027 certification to lock in West Coast OEM preferential supplier status before compliance deadlines harden procurement criteria. For New Entrants and Emerging Players: Lead with battery pack thermal management bonding as the most penetrable white-space segment, where ceramic-filled PUR formulations address unmet flame-retardant and thermally conductive specifications. Target Querétaro's aerospace cluster for structural bonding applications with lower qualification barriers than automotive tier-one supply chains. Pursue licensing agreements with proprietary curing catalyst holders rather than independent IP development to accelerate supplier qualification cycles. For Investors and Strategic Acquirers: Specialized reactive-grade formulators with dedicated Minnesota and Illinois R&D facilities and existing tier-one automotive seating relationships represent the highest-conviction acquisition archetype. Long-term viability hinges on substitution defense against hybrid epoxy-PUR systems and inorganic thermal interface materials across the electric vehicle platform transition. Watch battery OEM thermal management specification shifts as the critical inflection signal; migration toward phase-change materials or silicone-based solutions would compress reactive PUR addressable market expansion. Revision becomes warranted when hybrid system qualification rates at Michigan and Ontario assembly plants cross threshold penetration levels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Supply | Captive MDI/TDI access insulates margin compression from merchant market volatility. |
| CARB Pre-emptive Certification Investment | Early compliance with California Air Resources Board amendments secures West Coast OEM supplier status. |
| Hybrid System R&D Partnership | Collaboration with epoxy formulators addresses battery tray assembly thermal resistance specifications. |
| Application Engineering Team Expansion | Technical service scarcity in moisture-cure system deployment commands premium contract pricing. |
| Cross-border Formulation Harmonization | Unified EPA-PMRA testing protocols reduce duplicate documentation costs for US-Canada supply chains. |
Research Methodology
A spread of perspectives from tier-one automotive procurement directors, adhesive formulator R&D leads, polyurethane plant managers, and regional distribution channel partners converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with downstream OEM specification committees and upstream polyol supply planners. Secondary validation drew from EPA enforcement action records, Health Canada PMRA hazard classification databases, SEC 10-K disclosures from integrated chemical majors, and automotive production data from Michigan and Ontario assembly corridors. Bottom-up volume estimates from individual adhesive grade consumption were triangulated against top-down market sizing from petrochemical feedstock flow analysis.
Segmentation dimensions modeled include product type tier, end-use application intensity, formulation chemistry class, and customer procurement structure across the projection horizon. CAGRs were derived from regression analysis of historical automotive adhesive content-per-vehicle trends and electric vehicle platform penetration assumptions. Industry-specific forecast inputs incorporated OEM-directed weight reduction program timelines and EPA Clean Air Act compliance deadline phasing.
Forecasts assume regulatory continuity in EPA National Emission Standards for Hazardous Air Pollutants enforcement and Health Canada PMRA hazard classification protocols; material policy shifts would require re-modeling. Specific risks that could force revision include accelerated hybrid PUR-epoxy system adoption in battery assemblies, SEMARNAT VOC regulation tightening in Mexican manufacturing zones, and isocyanate feedstock supply disruptions from Gulf Coast petrochemical facility outages. Revision becomes warranted when hybrid system qualification rates at tier-one automotive suppliers cross threshold penetration levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Industrial Adhesives Market
Adhesives & Sealants
Marine Sealants Market
Adhesives & Sealants
Epoxy Glue Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
South America Acrylic Adhesives Market
Adhesives & Sealants
Global Emulsion Adhesives Market
Adhesives & Sealants
Saudi Arabia Sealants Market
Adhesives & Sealants
Germany Adhesives Market
Adhesives & Sealants
Chlorinated Polyolefin Adhesion Promoter Market
Adhesives & Sealants
Thailand Adhesives and Sealants Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
Mexico Sealants Market
Adhesives & Sealants
Temporary Bonding Adhesives Market
Adhesives & Sealants
Flock Binder Market
Adhesives & Sealants
Middle-East and Africa Electronics Adhesives Market